
 Europe Residential Construction Market | 2026-2036
Europe Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Construction Market Analysis
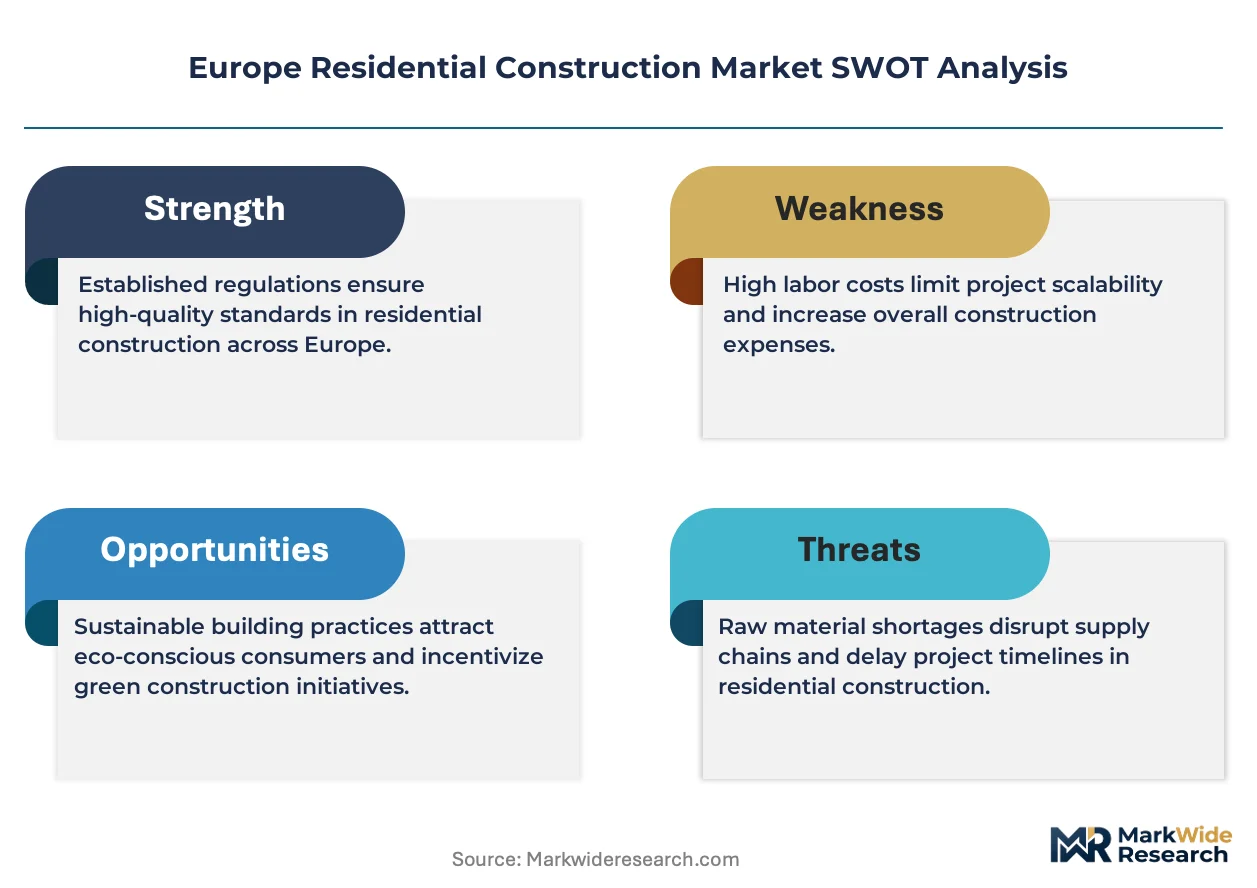
The near-zero-energy building specification is collapsing the gap between premium and standard residential offerings across Europe. Bouygues SA leverages its integrated design-build model to deliver certified low-carbon housing at scale. Barratt Developments plc anchors its competitive position through controlled land pipelines in high-constraint UK planning zones. Skanska AB differentiates via industrialized construction methods that compress programme timelines for multi-family schemes.
Europe residential construction encompasses the design, permitting, and assembly of detached, attached, and collective dwellings using structural systems that must achieve U-values below 0.20 W/m²K under prevailing energy codes. The sector serves household shelter needs while functioning as the primary deployment channel for building decarbonization policy. Single-family homes retain the largest share of completed floor area but carry thinner margins due to fragmented subcontractor dependencies. Multi-family units represent the fastest-expanding value pool as institutional investors channel capital into build-to-rent platforms. Sustainable building technology commands premium pricing power where green mortgage incentives from the European Investment Bank reduce borrower costs.
CE marking under the Construction Products Regulation governs material compliance across EU member states, while national transpositions of the Energy Performance of Buildings Directive mandate progressive renovation rates. France's RE2020 environmental regulation and Germany's Building Energy Act impose lifecycle carbon thresholds that reshape material procurement toward bio-based and recycled inputs. Stakeholders must track how the EU AI Act and emerging smart-home interoperability standards will alter product liability and data governance obligations for connected residential developments.
Market Dynamics
The EU Green Deal's building decarbonization mandates are compressing thermal performance standards across all member states, forcing developers to abandon conventional masonry systems for prefabricated envelope assemblies that achieve sub-0.20 W/m²K U-values.
Growth Catalysts
- RE2020 environmental regulation:France's lifecycle carbon thresholds for new residential construction are redirecting procurement toward bio-based insulation and low-carbon concrete alternatives.
- Build-to-rent institutional capital:Pension funds and REITs are channeling capital into multi-family platforms, accelerating construction velocity for certified energy-efficient rental stock.
- Green mortgage incentives:The European Investment Bank's reduced-rate financing for near-zero-energy homes is compressing payback periods for efficiency upgrades.
Market Restraints
- Timber supply concentration:Nordic and Baltic sawmill capacity constraints are creating input cost volatility for mass timber structural systems mandated by national building codes.
- Skilled labor scarcity:Certified passive house trades and building envelope specialists remain concentrated in Germany and Austria, limiting deployment speed elsewhere.
- Planning permission timelines:UK local authority capacity constraints under the National Planning Policy Framework are extending development approval cycles to 18-24 months.
Strategic Opportunities
- Renovation wave under EPBD:The Energy Performance of Buildings Directive's progressive renovation rate mandates are opening retrofit service markets in Southern and Eastern Europe.
- Industrialized construction convergence:Robotics-enabled panelization combined with BIM-to-fabrication workflows is enabling factory-based assembly for mid-rise residential schemes.
- Smart-home interoperability standards:Emerging EU harmonization for connected device protocols is creating white space for integrated energy management platforms in new developments.
Industry Challenges
- Cross-border certification complexity:Mutual recognition gaps between national passive house institutes and CE marking under the Construction Products Regulation are creating compliance friction for modular suppliers.
- Digital skills integration:Field crews require retraining on augmented reality assembly guidance and IoT commissioning protocols that accompany prefabricated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Construction Market |
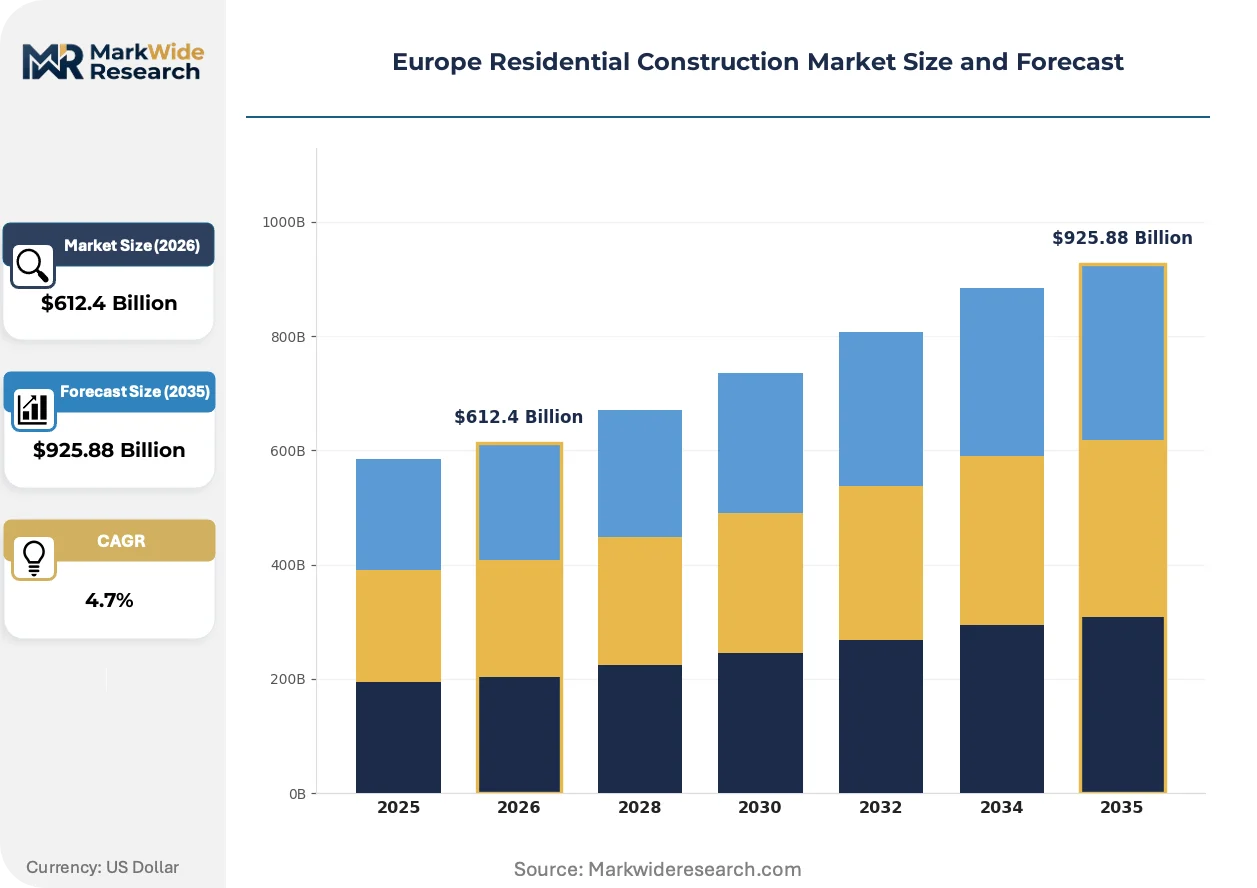
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $925.88 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-family Homes, Multi-family Units, Condominiums, Townhouses Construction Material: Wood, Concrete, Steel, Brick End User: Homeowners, Real Estate Developers, Investment Firms, Contractors Building Technology: Prefabricated, Modular, Sustainable, Smart Homes |
| Companies Covered | Bellway plc, Bouygues SA, Barratt Developments plc, STRABAG SE, Vinci SA, Taylor Wimpey plc, Skanska AB, Eiffage SA, Persimmon Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Construction Market Emerging Trajectories
Prefabrication and digital fabrication methods are displacing site-based construction across European residential markets, compressing programme timelines while enabling the precision required for energy code compliance.
Cross-laminated timber and mass timber hybrid systems are bifurcating the structural market between high-performance engineered wood for mid-rise multi-family schemes and conventional steel-concrete for high-rise towers. German and Austrian developers are specifying CLT for 6-12 storey residential blocks at accelerating volumes. This technology is bifurcating contractor capabilities between industrialized specialists and traditional masonry subcontractors.
France's RE2020 regulation and Germany's Building Energy Act are imposing lifecycle carbon thresholds that reshape material procurement toward bio-based and recycled inputs. The industrial consequence is a forced substitution of Portland cement with geopolymer and calcined clay alternatives in foundation and structural elements. Multi-family residential in France's Île-de-France and Germany's Baden-Württemberg regions are most affected, with developers pre-purchasing certified low-carbon concrete volumes two years ahead of construction.
Institutional build-to-rent platforms are consolidating demand for standardized, certifiable residential product. This buyer concentration is displacing bespoke single-family development in urban cores across the United Kingdom, Netherlands, and Nordic capitals. The shift is most visible in London and Amsterdam, where pension fund joint ventures are acquiring land pipelines specifically for operational efficiency at portfolio scale.
Europe Residential Construction Market Segmentation
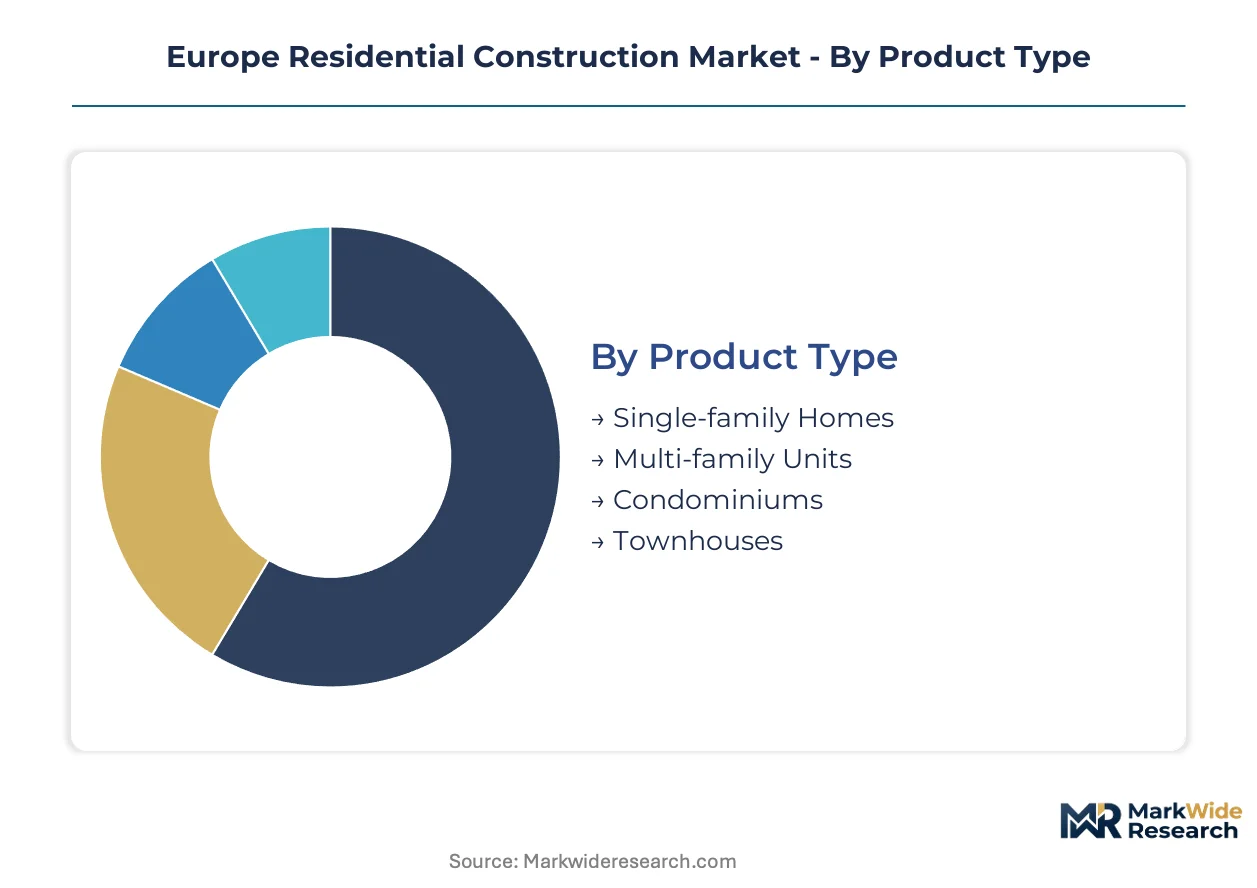
Segmentation reveals how EU Green Deal compliance costs distribute unevenly across product types and construction methods. Material procurement patterns and end-user financing capabilities determine which segments absorb regulatory premiums fastest.
Product Type:
German and French domestic demand dominates single-family and multi-family construction, while UK institutional capital drives build-to-rent platforms across townhouses and multi-family schemes.
- Single-family Homes:Detached dwellings using conventional masonry or timber frame systems. French and German homeowners in suburban zones absorb RE2020 lifecycle carbon costs through green mortgage incentives from the European Investment Bank.
- Multi-family Units:Collective residential structures from 3 to 12 storeys. UK pension funds and Dutch REITs concentrate acquisition in Amsterdam and London corridors where operational efficiency at portfolio scale justifies premium construction.
- Condominiums:Individually owned units within multi-dwelling structures. Italian and Spanish urban cores see constrained supply due to fragmented land ownership and extended planning timelines.
- Townhouses:Attached dwellings sharing party walls. Belgian and Dutch municipalities favor this typology for brownfield density targets in Antwerp and Rotterdam regeneration zones.
Single-family homes command the established base. The steepest expansion runs through multi-family units.
Construction Material:
Cost tiers separate mass timber systems from conventional materials, with Nordic supply constraints pushing steel-concrete hybrids into mid-rise applications.
- Wood:Cross-laminated timber and glulam systems for 6-12 storey structures. German and Austrian developers specify CLT in Baden-Württemberg and Bavaria where certified passive house trades concentrate.
- Concrete:Geopolymer and calcined clay alternatives displace Portland cement in foundations. French Île-de-France developers pre-purchase low-carbon concrete volumes two years ahead to meet RE2020 thresholds.
- Steel:Structural frames for high-rise towers and hybrid systems. Polish and Czech fabrication yards supply continental multi-family schemes where fire regulations permit steel-composite floors.
- Brick:Traditional masonry for renovation and heritage-adjacent projects. UK conservation areas and Dutch historic districts sustain demand despite thinner margins from subcontractor fragmentation.
Concrete retains volume leadership. Wood is climbing the fastest as national building codes mandate bio-based structural alternatives.
End User:
Customer type determines procurement sophistication, with investment firms standardizing specifications while homeowners negotiate bespoke designs.
- Homeowners:Individual purchasers of single-family dwellings or condominium units. German first-time buyers leverage KfW bank efficiency loans to access near-zero-energy specifications at compressed payback periods.
- Real Estate Developers:Firms controlling land pipelines and construction delivery. UK developers navigate 18-24 month National Planning Policy Framework approval cycles by front-loading community consultation.
- Investment Firms:Institutional capital deploying into build-to-rent platforms. Swedish and Danish pension funds acquire operational residential portfolios in Copenhagen and Stockholm for yield stability.
- Contractors:Construction firms executing design-build or traditional contracts. French integrated design-build specialists capture RE2020 compliance risk through lifecycle carbon guarantees.
Real estate developers command the established base. Investment firms show the steepest expansion trajectory as institutional capital reallocates toward operational residential assets.
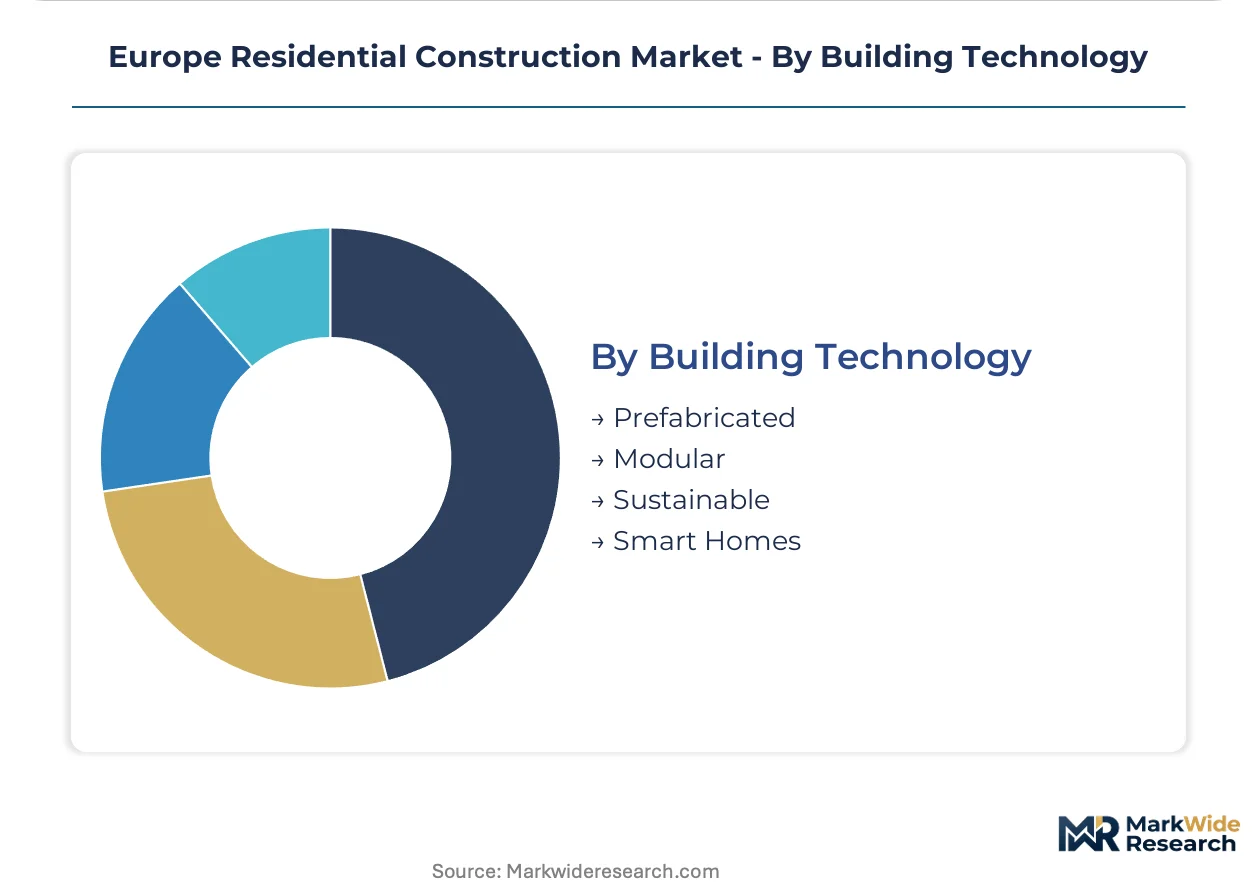
Building Technology:
Maturity gradients separate established prefabrication from emerging smart-home platforms requiring new commissioning protocols.
- Prefabricated:Factory-produced envelope and structural assemblies. German and Austrian industrialized construction specialists compress programme timelines for multi-family schemes through robotics-enabled panelization.
- Modular:Volumetric units assembled off-site and craned into position. UK modular suppliers face cross-border certification friction between national passive house institutes and CE marking requirements.
- Sustainable:Systems achieving near-zero-energy or passive house certification. EU Green Deal thermal performance mandates force abandonment of conventional masonry for prefabricated envelope assemblies.
- Smart Homes:Connected device ecosystems for energy management and occupancy optimization. Emerging EU interoperability standards create compliance uncertainty under the EU AI Act for data governance obligations.
Prefabricated systems command the established base. Smart homes are expanding most quickly as green mortgage incentives tie financing to integrated energy management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's residential construction sector exhibits pronounced trade asymmetries in building materials and prefabricated systems. Germany and France maintain structural surpluses in engineered timber and low-carbon concrete components, while the United Kingdom and Southern Europe rely on cross-border procurement to meet Green Deal thermal performance mandates.
Germany
First-time buyers in suburban zones drive demand for near-zero-energy single-family homes. The Building Energy Act imposes lifecycle carbon thresholds that redirect procurement toward bio-based insulation and mass timber systems. Bavaria and Baden-Württemberg host the densest concentrations of certified passive house trades and industrialized construction specialists.
France
Urban renewal in Île-de-France and Auvergne-Rhône-Alpes accelerates multi-family construction velocity. RE2020 environmental regulation mandates lifecycle carbon accounting that forces developers to pre-purchase low-carbon concrete volumes two years ahead of groundbreaking. Bouygues SA leverages integrated design-build capabilities to deliver certified low-carbon housing at scale.
United Kingdom
Institutional pension funds channel capital into build-to-rent platforms across London and Southeast corridors. National Planning Policy Framework approval cycles extend to 18-24 months due to local authority capacity constraints. Barratt Developments plc anchors competitive positioning through controlled land pipelines in high-constraint planning zones.
Netherlands
Belgian and Dutch municipalities favor townhouse typologies for brownfield density targets in Antwerp and Rotterdam regeneration zones. Randstad municipalities enforce progressive renovation rate mandates under transposed EPBD directives. Amsterdam sees concentrated pension fund joint ventures acquiring land pipelines specifically for operational efficiency at portfolio scale.
Sweden
Swedish and Danish pension funds acquire operational residential portfolios in Stockholm for yield stability. Skanska AB differentiates through industrialized construction methods that compress programme timelines for multi-family schemes. Nordic sawmill capacity constraints create input cost volatility for mass timber structural systems specified in national building codes.
Europe Residential Construction Market Vendor Landscape
Concentration sits with integrated design-build conglomerates and specialized industrialized construction firms that control vertical coordination across energy-code compliance workflows. The competitive terrain stratifies between pan-European infrastructure groups with captive residential divisions and national housebuilders with protected land pipelines. Three archetypes dominate: French engineering-led conglomerates, UK volume housebuilders, and Nordic industrialized construction specialists. Dominant competitive moves include strategic land banking in high-constraint planning zones and backward integration into prefabricated envelope manufacturing.
Within the engineering-conglomerate tier, Bouygues SA and Vinci SA exemplify integrated delivery models that internalize lifecycle carbon risk through design-build contracting. Among UK-listed volume housebuilders, Barratt Developments plc and Taylor Wimpey plc occupy positions anchored by land option agreements and controlled pipeline development. At the industrialized-construction vector, Skanska AB represents factory-based assembly capabilities that compress multi-family programme timelines through robotics-enabled panelization and BIM-to-fabrication workflows.
| Leading Market Players |
|---|
| Bellway plc |
| Bouygues SA |
| Barratt Developments plc |
| STRABAG SE |
| Vinci SA |
| Taylor Wimpey plc |
| Skanska AB |
| Eiffage SA |
| Persimmon Plc |
| Others |
Supply Flow & Price Mechanics
Sawmill capacity utilization in the Nordic-Baltic corridor determines price floors for mass timber structural systems across German and Austrian multi-family schemes. Scale concentration among engineered timber producers grants pricing power to CLT specialists serving Baden-Württemberg developers, while fragmented masonry subcontractors in Southern Europe absorb thinner margins on conventional envelope assemblies.
Pricing Analysis
Investment firm buyers anchor pricing structures across European build-to-rent platforms, with institutional capital compressing procurement costs through standardized specifications at portfolio scale. Three-tier pricing separates passive house-certified dwellings from near-zero-energy standard units and conventional code-minimum stock, with green mortgage incentives from the European Investment Bank reducing borrower price sensitivity for certified tiers. Cost compression in mid-rise multi-family construction is intensifying as Nordic timber supply constraints force substitution toward steel-concrete hybrids. Homeowner segments in France and Germany exhibit lowest price sensitivity where KfW bank efficiency loans offset RE2020 compliance premiums.
Supply Chain Analysis
Baltic Sea port congestion and Nordic rail capacity constraints create chokepoints for cross-laminated timber deliveries to continental construction sites. Geographic supply concentration centers on Sweden, Finland, and Austria for engineered wood systems, with Poland and Czech Republic anchoring steel fabrication for hybrid structural frames. Raw material dependencies include Nordic spruce logs, low-carbon cement alternatives, and bio-based insulation feedstocks. Single-source vulnerability runs through certified passive house trades concentrated in Germany and Austria. Distribution runs through design-build conglomerates with captive prefabrication facilities rather than fragmented subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's building decarbonization mandates constitute a regulatory inflection forcing wholesale technology substitution across structural systems and envelope assemblies. Market disruption accelerates as industrialized construction methods displace site-based masonry across multi-family schemes.
For Market Incumbents: Secure controlled land pipelines in high-constraint UK planning zones and Baden-Württemberg corridors where approval timelines extend 18-24 months. Backward integration into prefabricated envelope manufacturing mitigates substitute-technology risk from modular suppliers. Certification investment in passive house trades defends margin position against emerging industrialized construction specialists. For New Entrants and Emerging Players: Passive house institute fast-track certification in underpenetrated Southern and Eastern European retrofit markets opens immediate service revenue. White-space targets include EPBD-mandated renovation wave execution in Italian and Spanish urban cores where fragmented land ownership constrains incumbent supply. Go-to-market positioning as lifecycle carbon guarantee providers captures RE2020 compliance risk from French integrated design-build incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors industrialized construction specialists with robotics-enabled panelization capabilities and BIM-to-fabrication workflows. Long-term viability over a 5-10 year window rests on acquisition of factory-based assembly platforms serving institutional build-to-rent capital. Signal to watch: mutual recognition agreements between national passive house institutes and CE marking harmonization under the Construction Products Regulation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabrication | Captive envelope production secures RE2020 compliance margins for French design-build conglomerates. |
| Land Pipeline Acquisition in High-Constraint Zones | Controlled development rights in UK National Planning Policy Framework corridors compress competitor access. |
| Passive House Trade Certification Programs | Certified specialist labor pools accelerate deployment velocity for German multi-family schemes. |
| Green Mortgage Platform Partnerships | European Investment Bank incentive alignment reduces borrower acquisition costs for near-zero-energy stock. |
| Cross-Border Modular Certification Harmonization | CE marking convergence with national passive house institutes reduces compliance friction for UK suppliers. |
Methodological Framework
Operator-level perspectives from project development directors, passive house certifiers, municipal planning officers, and institutional asset managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EU building permit databases, national energy performance certificates, and European Investment Bank green mortgage disbursement records. Bottom-up project pipeline enumeration triangulated with top-down construction value-added estimates from Eurostat and national statistical institutes.
Sensitivity analysis tested demand elasticity to interest rate shifts and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled include construction material, building technology tier, end-user archetype, and regional regulatory cluster. CAGRs derived from historical completion volume trends adjusted for EPBD renovation rate mandates and RE2020 lifecycle carbon threshold implementation schedules. Forecast inputs incorporated Nordic sawmill capacity expansion plans and industrialized construction facility commissioning timelines.
Decision-makers should treat outputs as directional under prevailing EU Green Deal implementation schedules and national building code transposition timelines; material deviation in regulatory enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as Energy Performance of Buildings Directive renovation obligations and EU AI Act smart-home data governance requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Prefabricated Homes Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
US Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Japan Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
US Residential Remodeling Market