
 UK Manufactured Homes Market | 2026-2036
UK Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
UK Manufactured Homes Market Analytics
Asset-light leasing and project finance structures is reconfiguring competitive entry barriers for mid-scale developers. Premier Modular leverages its manufacturing scale to dominate volumetric production for public sector contracts. TopHat anchors its position through technology leadership in precision-engineered timber frames. Laing O'Rourke sustains competitive differentiation via in-house digital design-to-manufacture integration.
UK manufactured homes comprise factory-built residential units assembled from prefabricated volumetric modules or panelized systems, typically meeting BS 3632 thermal performance standards and permanent dwelling codes. These structures serve primarily to compress construction timelines and standardize quality for housing providers facing land scarcity and labor shortages. Multi-section modular units capture expanding margin pools as local authorities prioritize scalable social housing delivery. Steel-framed products lead in urban infill applications where fire safety and structural longevity command premium positioning. Workforce housing applications show structural growth tied to employer-sponsored accommodation schemes near logistics and distribution clusters.
The Ministry of Housing, Communities and Local Government sets planning frameworks that determine site allocation speed for manufactured housing developments. Building Regulations Part L and Future Homes Standards mandate escalating thermal efficiency thresholds that filter out non-compliant producers. The Building Safety Regulator enforces gateway compliance requirements that extend approval timelines but elevate quality barriers. Stakeholders must monitor how permitted development rights expansion interacts with local plan resistance in Conservative-controlled shire authorities.
Market Dynamics
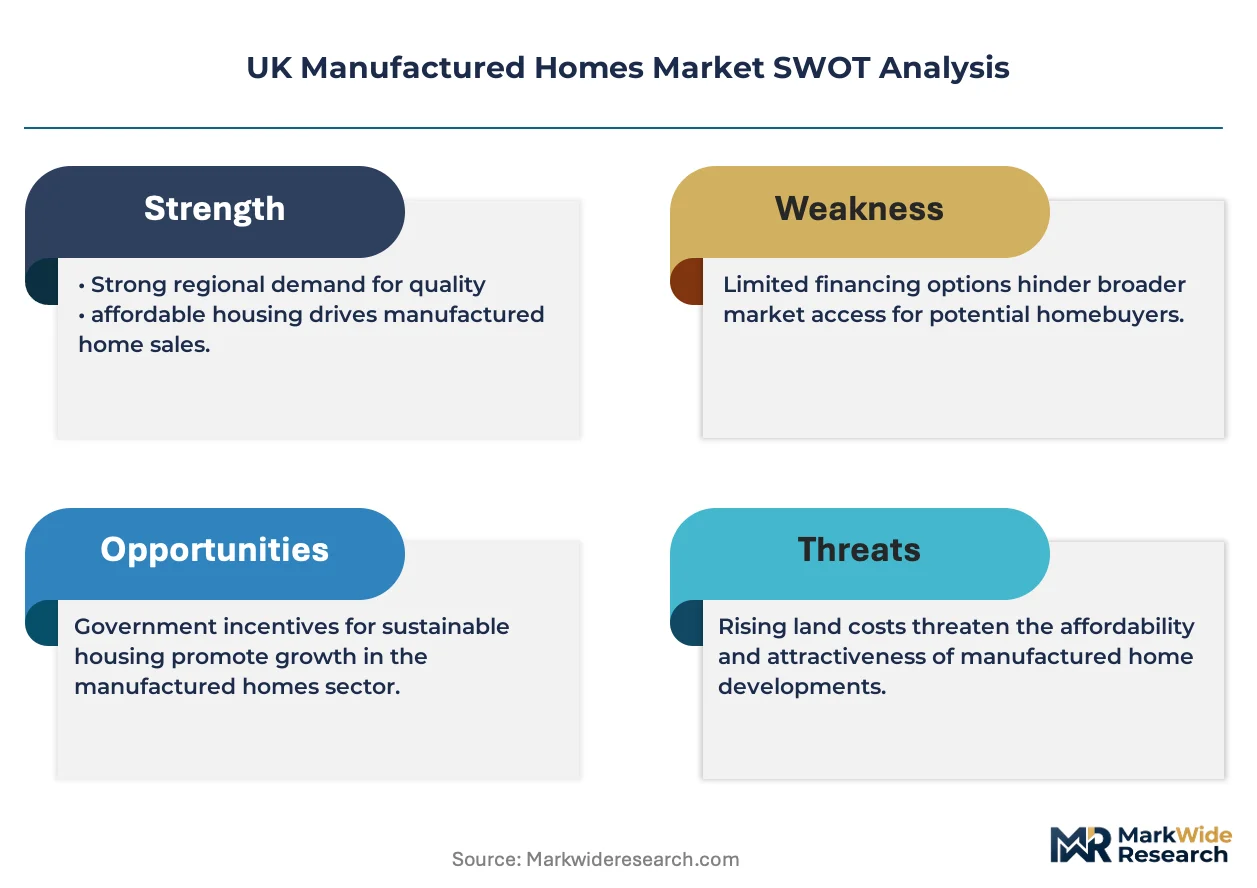
The Building Safety Act 2022 is compressing approval timelines while elevating quality barriers, forcing manufacturers to absorb gateway compliance costs or exit tender processes for social housing contracts.
Growth Catalysts
- Future Homes Standards:Escalating thermal efficiency thresholds under Building Regulations Part L are filtering out non-compliant producers, concentrating contract awards among certified manufacturers.
- Local authority procurement:England's urban corridors, particularly Greater London and the West Midlands, are expanding volumetric module orders for scalable social housing delivery.
- Employer-sponsored schemes:Workforce housing applications tied to logistics and distribution clusters near the Midlands Engine are generating structural demand for rapid-deployment units.
Market Restraints
- Steel input volatility:Structural steel framing costs fluctuate with global commodity markets, squeezing margins on urban infill products where fire safety specifications mandate steel over timber.
- Gateway compliance friction:The Building Safety Regulator's extended approval timelines delay project cash conversion, particularly for mid-scale developers lacking balance sheet depth.
- Site allocation bottlenecks:Permitted development rights expansion confronts local plan resistance in Conservative-controlled shire authorities, constraining greenfield deployment.
Strategic Opportunities
- Net-zero retrofit integration:Panelized systems incorporating photovoltaic-thermal hybrid assemblies can capture premium positioning as local authorities embed operational carbon targets into procurement scoring.
- Asset-light leasing structures:Project finance vehicles separating manufacturing from site ownership are lowering capital barriers for regional entrants targeting housing association frameworks.
- Precision timber engineering:Cross-laminated timber and glulam systems are penetrating mid-rise residential segments previously reserved for concrete, enabled by updated structural design codes.
Industry Challenges
- Digital design-to-manufacture talent scarcity:BIM coordination and parametric modeling skills command wage premiums that smaller fabricators struggle to match against vertically integrated competitors.
- Multi-party liability fragmentation:Insurance placement complexity across design, manufacture, transport, and installation phases extends contract negotiation cycles and elevates legal spend.
- Legacy utility integration:Grid connection protocols for manufactured housing estates lag factory production speeds, creating commissioning delays that erode timeline advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Manufactured Homes Market |
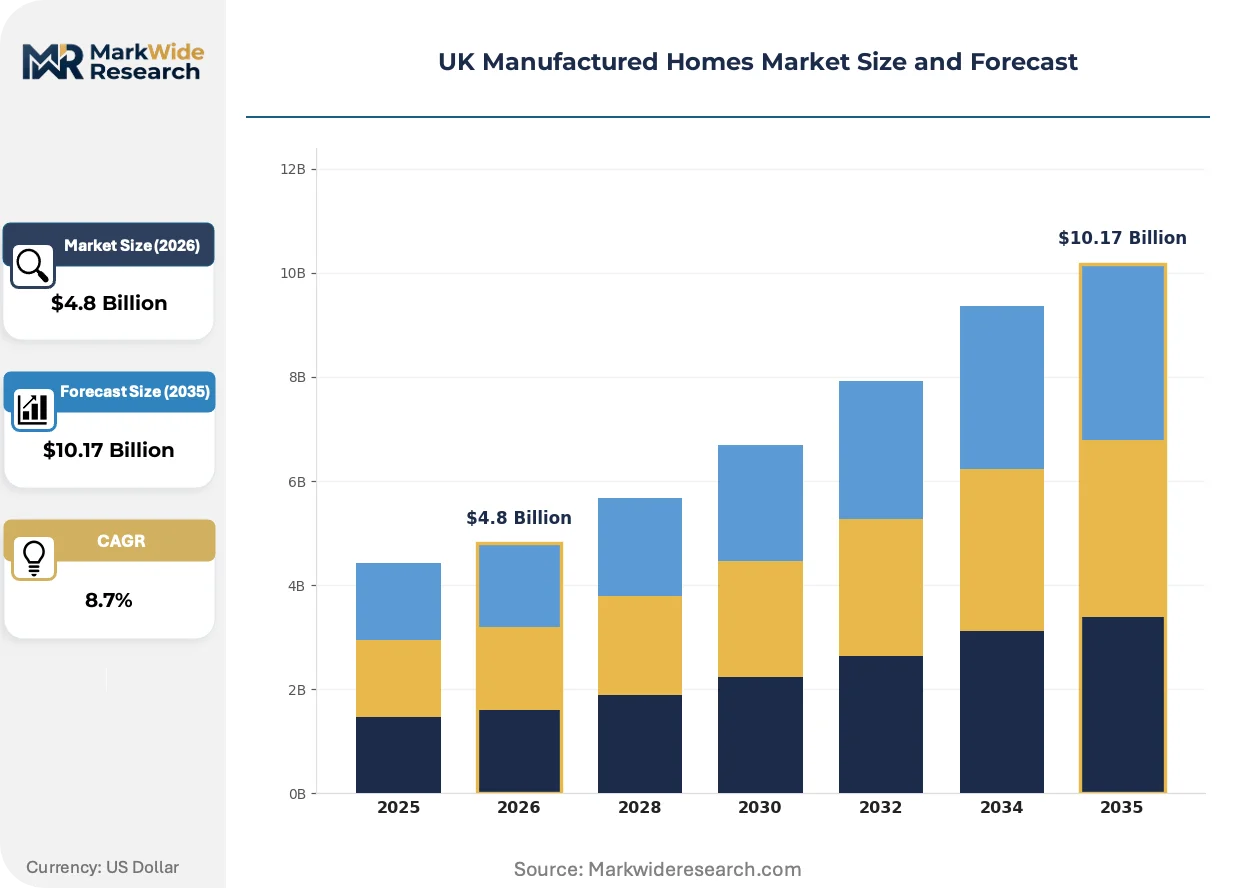
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-section, Multi-section, Modular, Prefabricated Material: Wood, Steel, Concrete, Composite Application: Residential, Vacation Housing, Workforce Housing, Retail Space End User: Households, Investors, Developers, Local Authorities |
| Companies Covered | Premier Modular, Timberlogbuild, Bouygues Construction, Karmod, TopHat, Lendlease Corporation Limited, Campion Homes, Modulous Limited, Laing O'Rourke, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Manufactured Homes Market Evolving Landscape
Digital fabrication workflows are compressing design-to-delivery cycles while regulatory pressure on embodied carbon is reshaping material specifications across the supplier base.
Digital twin platforms are virtualizing quality assurance protocols by embedding sensor feedback loops into volumetric module production lines. Housing associations and local authority procurement teams are mandating these platforms for contract eligibility. The technology is virtualizing defect detection, reducing site rectification costs and compressing final handover timelines.
The Building Safety Act's gateway regime is hardening liability distribution between manufacturers and installers. Dutyholder obligations now extend through the construction phase, forcing contractual renegotiation across supply chains. Steel-framed volumetric products face the steepest compliance cost escalation given fire safety documentation requirements.
Outcome-based procurement frameworks are displacing unit-price contracting among registered providers seeking operational performance guarantees. Housing associations in Greater Manchester and the West Midlands are piloting rental yield-linked payment structures. This shift concentrates contract awards with manufacturers offering whole-life cost modeling and maintenance bundling.
UK Manufactured Homes Market Segmentation
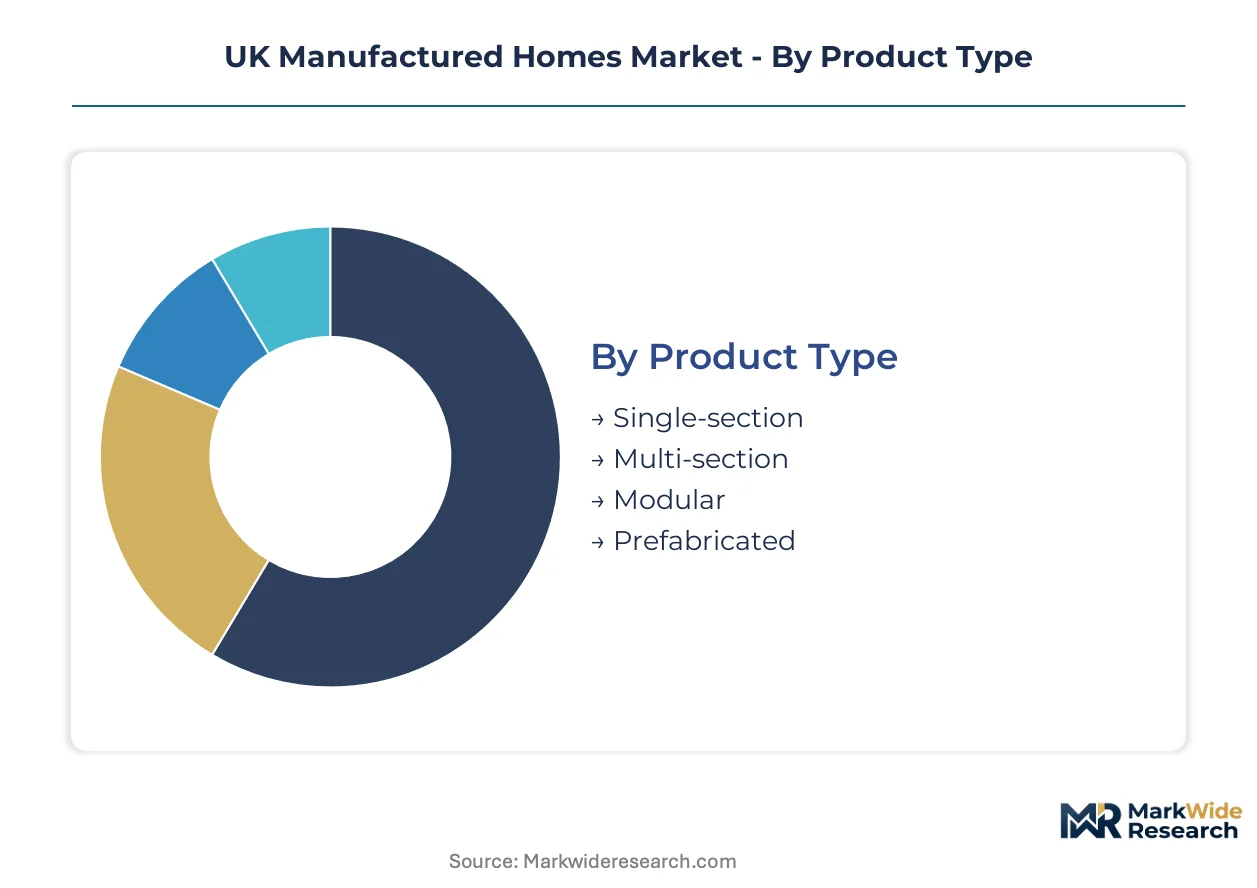
Segmentation in the UK manufactured homes market reveals how procurement priorities, material specifications, and end-user economics fragment contract opportunities across distinct production and financing models. Understanding these fault lines enables manufacturers to align factory configurations with the specific compliance and delivery requirements of each buyer category.
Product Type:
Mature volumetric systems dominate public sector frameworks, while emerging panelized formats penetrate private development where design flexibility commands premium positioning.
- Multi-section:Factory-built units comprising two or more transportable modules that lock together on-site to form larger dwellings. Demand concentrates in Greater London social housing tenders where site density requirements and crane-access constraints favor segmented delivery over single-unit placement. The Building Safety Act's gateway compliance costs hit multi-section producers hardest due to multi-party assembly liability.
- Modular:Fully volumetric three-dimensional units complete with MEP services and interior finishes, manufactured to BS 3632 thermal standards. Procurement is accelerating across West Midlands local authority frameworks seeking scalable deployment for temporary accommodation-to-permanent housing transitions. Steel-framed modular products face margin pressure from fire safety documentation requirements.
- Single-section:Self-contained transportable units typically deployed for rapid-response temporary housing or rural infill sites with access limitations.
- Prefabricated:Panelized wall, floor, and roof components assembled on-site, offering greater architectural customization at the cost of longer construction timelines.
Multi-section retains volume leadership; modular holds the steepest expansion curve.
Material:
Cost tier stratification separates premium structural specifications from economy framing choices, with regulatory pressure on embodied carbon reshaping mid-tier procurement.
- Steel:Cold-formed or hot-rolled structural framing meeting extended fire resistance ratings for urban infill and mid-rise applications. Specification concentrates in West Midlands logistics corridor workforce housing where structural longevity and insurance placement ease offset commodity price volatility. Building Safety Regulator documentation requirements escalate fabrication costs relative to timber alternatives.
- Wood:Precision-engineered timber frames including cross-laminated timber and glulam systems penetrating mid-rise segments previously reserved for concrete. Demand is climbing fastest among housing associations in Greater Manchester piloting net-zero procurement frameworks that weight operational and embodied carbon in scoring algorithms.
- Concrete:Precast or tilt-up concrete systems deployed primarily for permanent foundation applications requiring maximum acoustic separation and thermal mass.
- Composite:Hybrid material assemblies combining timber cores with steel or fiber-reinforced polymer facing layers for specialized performance requirements.
Steel retains volume leadership; wood holds the steepest expansion curve.
Application:
Customer type differentiation separates institutional procurement with long-term asset management horizons from consumer-directed purchases prioritizing immediate occupancy.
- Workforce Housing:Employer-sponsored accommodation schemes tied to logistics, distribution, and manufacturing clusters near the Midlands Engine. Procurement is accelerating through rental yield-linked payment structures that transfer operational risk to manufacturers offering whole-life cost modeling.
- Residential:Permanent dwellings for owner-occupiers or private rental investors, spanning single-family to small multi-family configurations. Demand concentrates in England's urban corridors where land scarcity and labor shortages compress construction timelines for housing providers.
- Vacation Housing:Seasonal or second-home units deployed in coastal and rural tourism destinations, subject to distinct planning permission frameworks for temporary occupancy.
- Retail Space:Commercial modular structures repurposed for pop-up retail, hospitality, or community facility applications with shorter depreciation schedules.
Residential retains volume leadership; workforce housing holds the steepest expansion curve.
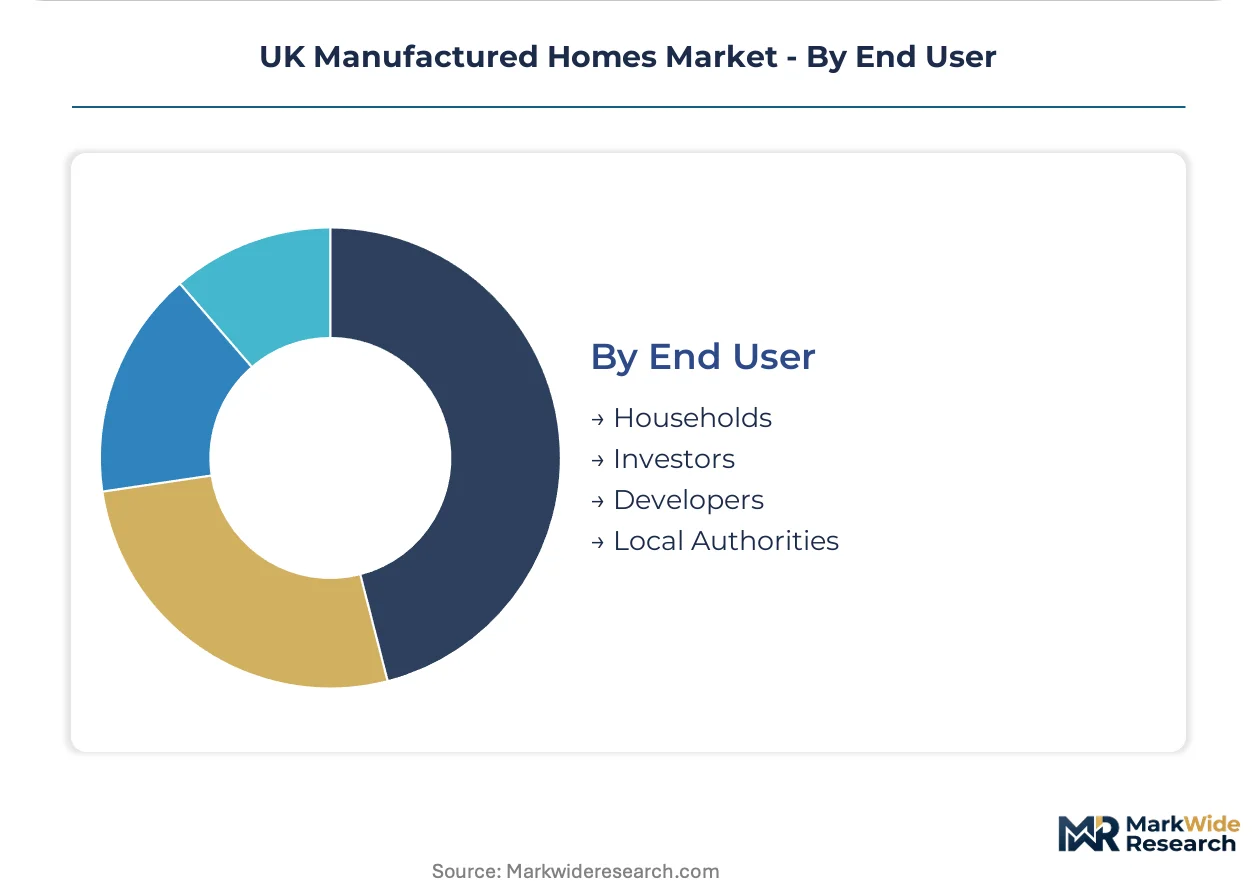
End User:
Geography-driven procurement patterns concentrate contract awards in England's metropolitan authorities while shire resistance constrains greenfield deployment.
- Local Authorities:Municipal housing departments and combined authorities procuring volumetric modules through framework agreements for social housing delivery. Specification concentrates in Greater London and West Midlands where permitted development rights expansion intersects with acute affordability pressures.
- Developers:Private residential developers integrating manufactured units into mixed-tenure schemes or build-to-rent portfolios. Procurement is shifting toward outcome-based frameworks requiring operational performance guarantees and maintenance bundling.
- Housing Associations:Registered providers seeking scalable delivery for affordable and intermediate rent programs, increasingly mandating digital twin platforms for contract eligibility.
- Households:Individual purchasers of manufactured homes for self-build or park home applications, typically financing through specialist lenders with distinct collateral valuation methodologies.
Local authorities retain volume leadership; developers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Local authorities and housing associations concentrate procurement in England's metropolitan corridors, with planning frameworks and permitted development rights expansion determining deployment velocity across sub-regional markets.
London and the Southeast
Greater London's acute land scarcity drives volumetric module procurement for high-density social housing schemes. The Greater London Authority's affordable housing program mandates modular delivery for rapid deployment on brownfield sites. Tower Hamlets and Newham councils lead framework agreements for temporary-to-permanent accommodation transitions.
West Midlands
The Midlands Engine logistics corridor generates structural demand for workforce housing near distribution clusters. Birmingham City Council's modular procurement framework prioritizes steel-framed units for urban infill durability. Coventry and Solihull industrial zones anchor employer-sponsored accommodation schemes.
North England
Combined authorities in Greater Manchester and Liverpool City Region pilot net-zero procurement weighting embodied carbon in scoring algorithms. Homes England's brownfield regeneration fund accelerates panelized system deployment on former industrial land. Leeds and Sheffield housing associations mandate digital twin platforms for contract eligibility.
Scotland
Scottish Government affordable housing supply program targets modular delivery for rural and island communities with construction access constraints. Transport Scotland's infrastructure investment enables factory-built unit deployment in Highland and Island local authorities. Edinburgh and Glasgow city regions concentrate precision-engineered timber frame specifications.
Wales
Welsh Government innovative housing program supports factory-built unit procurement for social rent and intermediate tenure schemes. Cardiff and Newport urban areas drive steel-framed volumetric orders for brownfield density targets. Rural local authorities in North Wales prioritize single-section units for rapid-response temporary housing.
UK Manufactured Homes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement frameworks. The market structure consolidates around vertically integrated manufacturers with in-house design-to-manufacture capability and mid-scale fabricators serving regional housing association networks. Three archetypes dominate: volumetric scale leaders, precision timber specialists, and digital-integrated constructors. Competitive moves center on framework contract capture and technology licensing partnerships rather than price-based rivalry.
Among UK-based fabricators, Premier Modular, TopHat, and Laing O'Rourke occupy distinct positioning within the supplier base. Premier Modular exemplifies the volumetric scale archetype through manufacturing footprint concentration. TopHat anchors the precision-engineered timber tier with cross-laminated timber system specialization. Laing O'Rourke represents digital-integrated construction through in-house design-to-manufacture workflow control. Each sits within separate procurement channel access tiers.
| Leading Market Players |
|---|
| Premier Modular |
| Timberlogbuild |
| Bouygues Construction |
| Karmod |
| TopHat |
| Lendlease Corporation Limited |
| Campion Homes |
| Modulous Limited |
| Laing O'Rourke |
| Others |
Value Network & Pricing Analysis
Steel input volatility determines both tier spreads and supply chain configuration across UK manufactured homes production. The Building Safety Act's fire safety documentation requirements escalate fabrication costs for steel-framed volumetric products, compressing margins at the standard tier while premium positioning absorbs gateway compliance through bundled whole-life service contracts.
Pricing Analysis
Cost-plus contracts with steel indexation dominate public sector framework agreements, transferring commodity risk to housing associations and local authorities. Price differentiation separates BS 3632-certified volumetric modules from non-compliant alternatives, with digital twin platform mandates adding service-layer premiums. Pricing pressure stems from employer-sponsored workforce housing schemes demanding rental yield-linked structures that compress upfront margins. Small fabricators exhibit highest price sensitivity due to wage premiums for BIM coordination talent.
Supply Chain Analysis
Upstream structural steel feedstock draws from UK mills, EU rolling facilities, and Turkish export capacity, with cold-formed sections concentrated in West Midlands fabrication clusters. Cross-laminated timber and glulam systems source from Austrian and Nordic engineered timber suppliers. Single-source vulnerability concentrates in fire-resistant coating chemistries governed by REACH compliance timelines. Distribution runs through housing association framework agreements and local authority procurement portals rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK manufactured homes market sits in early-cycle expansion as local authority procurement accelerates volumetric module adoption for social housing delivery. Net-zero building standards and permitted development rights expansion create structural tailwinds for factory-built unit penetration.
For Market Incumbents: Insulate framework contract positions by deepening backward integration into precision timber engineering and steel framing fabrication. Capture digital twin platform mandates through sensor-embedded production line investments. Defend against mid-scale regional entrants by locking multi-year local authority agreements before asset-light leasing structures proliferate. For New Entrants and Emerging Players: Build out panelized system capabilities targeting North England housing associations piloting embodied carbon-weighted procurement. The Greater Manchester and Liverpool City Region net-zero frameworks represent the most penetrable entry point. Lead with photovoltaic-thermal hybrid assemblies to differentiate on operational carbon scoring. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with in-house design-to-manufacture workflows. Long-term viability hinges on gateway compliance capability and digital fabrication infrastructure. Target acquisition archetypes include precision timber specialists lacking scale and mid-scale fabricators with regional housing association relationships. Monitor Building Safety Regulator approval timeline trends as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Housing associations in Greater Manchester mandate sensor-embedded modules for contract eligibility. |
| Backward Integration into Timber Engineering | Cross-laminated timber specialization captures net-zero procurement scoring premiums. |
| Framework Agreement Lock-In | West Midlands local authority volumetric contracts secure multi-year revenue visibility. |
| Photovoltaic-Thermal Hybrid Assembly | Panelized systems with integrated renewables capture operational carbon-targeted tenders. |
| Asset-Light Leasing Structure Launch | Project finance vehicles separate manufacturing from site ownership for regional expansion. |
Research Methodology
Desk research of Building Regulations Part L documentation, Homes England procurement databases, and local authority framework agreements preceded structured interviews with housing association procurement directors, modular manufacturing plant managers, and Building Safety Regulator compliance officers. Secondary validation drew from Ministry of Housing policy circulars, steel commodity trade data, and engineered timber supplier disclosures. Bottom-up volumetric module shipment estimates triangulated against top-down social housing delivery targets.
Assumption sets held planning permission velocity and steel price banding fixed while varying local authority procurement acceleration rates and net-zero compliance timeline scenarios. Segmentation modeling spanned product type, material specification, application, and end-user archetype dimensions. CAGRs derived from housing delivery gap analysis cross-referenced with factory capacity expansion announcements across the projection horizon. Future Homes Standards thermal efficiency thresholds and gateway compliance cost curves informed trajectory boundaries.
Stress conditions across steel input pricing, Building Safety Regulator approval delays, and permitted development rights political reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding local authority procurement continuity and employer-sponsored scheme uptake. Cross-checking against Homes England annual delivery statistics and housing association development pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Canada Manufactured Homes Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
US Residential Construction Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
North America Prefabricated Housing Market