
 Europe Manufactured Homes Market | 2026-2036
Europe Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Manufactured Homes Market Foresight
Direct-to-developer distribution is reshaping how manufactured homes reach end buyers across Europe, bypassing traditional dealer networks that dominated legacy markets. Derome AB leverages its vertically integrated timber supply chain to control material costs and delivery timelines. Skanska AB competes through off-site manufacturing scale, operating multiple production facilities that serve Northern European markets. Bouygues Batiment International anchors its position in France through permanent modular construction for social housing programs.
Europe manufactured homes are prefabricated dwelling units built in controlled factory environments, typically assembled from one or more transportable sections with permanent chassis or foundation-ready frames, designed to meet national building codes for structural, thermal, and fire performance. Their primary purpose is delivering cost-controlled, code-compliant housing faster than conventional stick-built construction. Modular product types lead value generation due to higher customization margins and multi-story capability, while steel material segments expand fastest as fire-rated frames satisfy stringent EU building safety directives. Residential end users dominate volume, though government procurement channels represent the most concentrated margin pool across the forecast horizon.
CE marking under the EU Construction Products Regulation mandates structural and energy performance declarations for all manufactured homes sold across member states, while national regulators like Germany's KBA-equivalent building authorities enforce supplementary state-level fire and seismic standards. The EU Green Deal's embodied carbon thresholds for building materials are forcing manufacturers to document lifecycle emissions or risk exclusion from publicly funded housing tenders. Stakeholders must monitor how the EU AI Act's emerging requirements for automated quality inspection systems could reshape factory certification protocols and compliance costs.
Market Dynamics
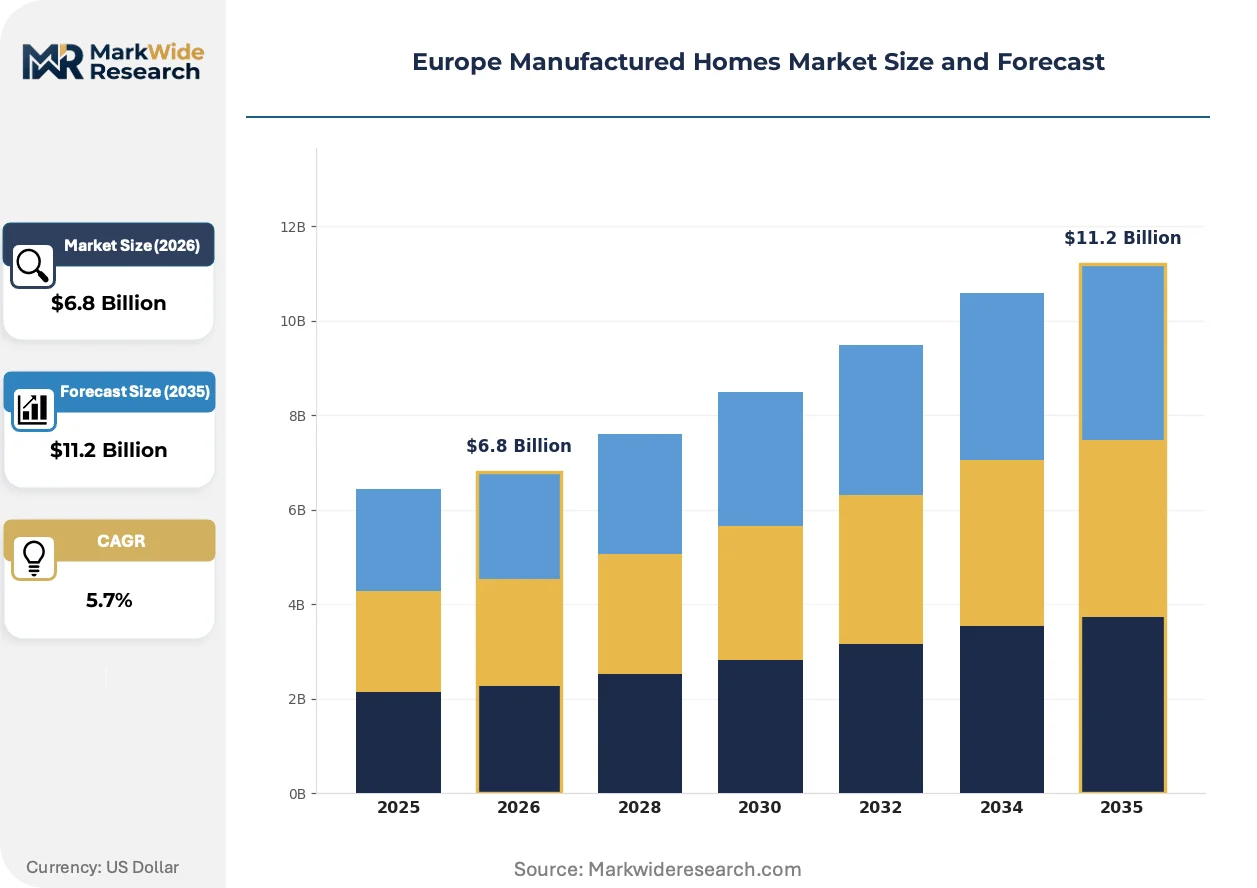
The EU Green Deal's embodied carbon thresholds are compressing factory certification timelines and forcing manufacturers to document lifecycle emissions across every material input. Municipal housing authorities in France and Germany now exclude suppliers who cannot demonstrate compliance, restructuring competitive access to publicly funded tenders.
Growth Catalysts
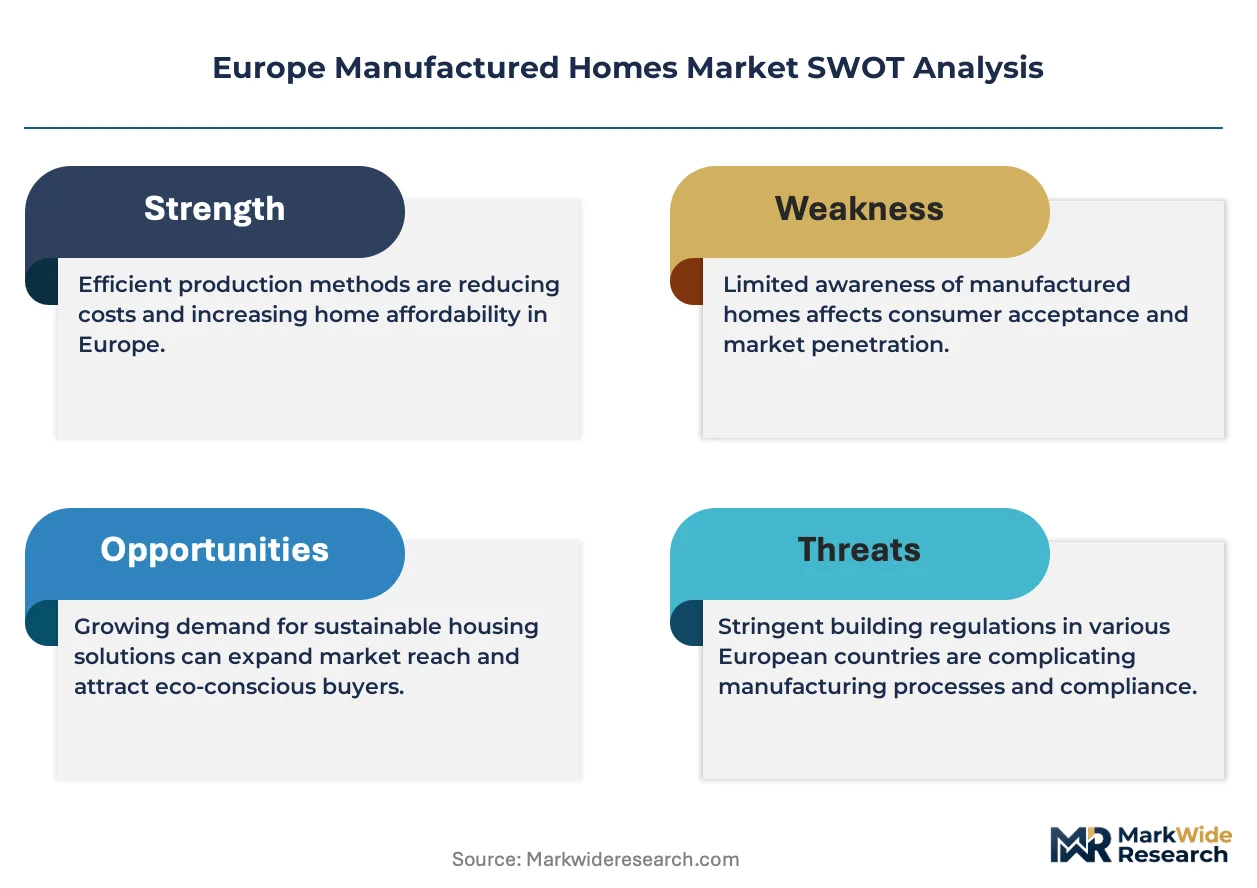
- EU Green Deal building performance standards:Embodied carbon mandates accelerate factory-built construction methods that reduce on-site waste and energy consumption compared to conventional stick-built alternatives.
- German federal zoning relaxation:Multiple federal states now permit manufactured home developments on previously restricted agricultural and peri-urban land, unlocking new site availability.
- Timber-frame thermal performance advances:Cross-laminated timber panels achieve Passivhaus certification thresholds, expanding addressable market into high-efficiency social housing segments.
Market Restraints
- Steel input cost volatility:Fire-rated steel frames face price swings tied to EU carbon border adjustment mechanisms and energy-intensive production curtailments.
- Eastern European manufacturing concentration:Final assembly capacity clusters in Poland and Romania, creating logistics vulnerability for Western European delivery commitments.
- CE marking compliance friction:Divergent national interpretations of the EU Construction Products Regulation create redundant testing burdens across member state borders.
Strategic Opportunities
- Spanish affordable housing deficit:Regional governments in Catalonia and Andalusia issue tenders for rapid-deployment modular units to address chronic rental shortages.
- EU AI Act automated inspection:Machine-vision quality systems reduce factory labor intensity while generating compliance documentation for public procurement.
- Direct-to-developer channel expansion:Bypassing traditional dealer networks captures margin and accelerates project timelines for multi-unit residential developers.
Industry Challenges
- Digital building information modeling talent:Factory design teams lack sufficient expertise in BIM-to-fabrication workflows, delaying production ramp-ups.
- Multi-jurisdiction certification timelines:Parallel national building code approvals for cross-border projects extend time-to-revenue by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Manufactured Homes Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Double-Section, Triple-Section, Modular Material: Wood, Steel, Concrete, Composite End User: Residential, Commercial, Government, Institutional Installation: On-Site, Off-Site, Permanent, Temporary |
| Companies Covered | Laing O'Rourke, Derome AB, Skanska AB, DFH Group, Portakabin Ltd, Peab AB, Bouygues Batiment International, Wolf Holding GmbH, Swietelsky AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Manufactured Homes Market Shifts & Advancements
Factory construction methods are converging with digital design tools and sustainability mandates to redefine how residential units reach European markets. Three developments dominate this transition.
Cross-laminated timber panel systems deliver structural rigidity and thermal performance in a single factory-fabricated component. Social housing developers in Germany and France specify these panels to meet Passivhaus standards without on-site complexity. The technology is migrating from single-story rural applications to multi-story urban infill projects, compressing the performance gap between manufactured and conventional construction.
The EU AI Act's emerging requirements for automated quality inspection systems reshape factory certification protocols. Manufacturers must demonstrate algorithmic traceability in defect detection or risk exclusion from publicly funded tenders. German building authorities enforce supplementary state-level documentation standards, forcing production facilities to upgrade sensor networks and data retention infrastructure.
Direct-to-developer distribution displaces legacy dealer networks that dominated twentieth-century manufactured home markets. Municipal housing authorities in France consolidate procurement through framework agreements with factory operators, eliminating intermediaries. This channel compression concentrates volume with vertically integrated producers who control timber supply chains and final mile logistics.
Europe Manufactured Homes Market Segmentation
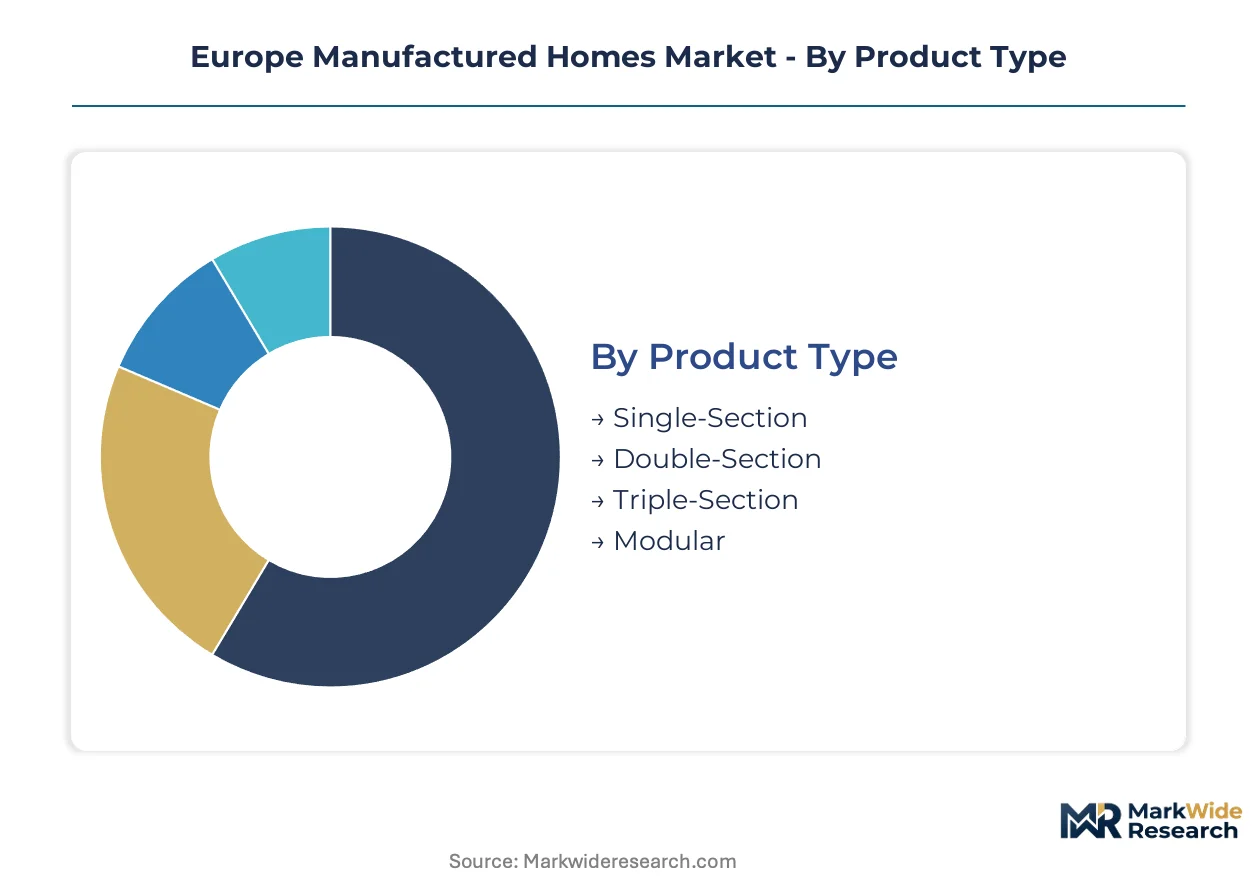
Segmentation reveals how manufacturing complexity, material specifications, and procurement channels create divergent margin profiles across the Europe manufactured homes landscape. Understanding these distinctions allows stakeholders to align production capacity with the fastest-turning demand pockets.
Product Type:
Cycle times vary dramatically: single-section units turn from order to delivery in weeks, while modular multi-story configurations require months of design-to-fabrication coordination.
- Single-Section:Compact transportable units fabricated as one rigid chassis-mounted module, typically deployed for emergency housing or rural infill. French municipal authorities procure these for rapid-deployment social housing programs where speed outweighs customization requirements.
- Modular:Factory-built volumetric units engineered for multi-story stacking and permanent foundation anchoring, capable of achieving Passivhaus thermal performance. German federal states specify these for urban densification projects where zoning relaxation permits manufactured construction on previously restricted sites.
- Double-Section:Two transportable modules joined on-site to create expanded floor plans without the engineering complexity of full modular systems.
- Triple-Section:Three-module configurations maximizing transport efficiency for large-family residential layouts.
Single-Section anchors the volume base while Modular gains share at the steepest rate.
Material:
Cost tiers separate naturally: timber dominates mid-market efficiency housing, steel commands premium fire-rated specifications, and concrete anchors permanent foundation applications.
- Steel:Fire-rated structural frames fabricated to EU building safety directives, with embodied carbon documentation now mandatory for public tender eligibility. German KBA-equivalent building authorities enforce supplementary state-level seismic performance standards that drive specification upgrades.
- Wood:Cross-laminated timber panels delivering structural and thermal performance in single factory-fabricated components, achieving Passivhaus certification without on-site complexity. Derome AB's vertically integrated supply chain controls material costs and delivery timelines for Scandinavian social housing developers.
- Concrete:Precast foundation-ready systems specified for permanent modular construction in France's social housing programs.
- Composite:Hybrid material systems combining thermal efficiency with structural rigidity for specialized climate applications.
Wood commands the largest installed base while Steel expands most quickly under tightening EU fire safety mandates.
End User:
Customer type determines procurement velocity: government framework agreements consolidate volume with longest lead times, while residential direct sales move fastest with highest customization.
- Government:Municipal housing authorities in France and Germany operating framework agreements that exclude suppliers lacking CE marking compliance and embodied carbon documentation. These channels represent the most concentrated margin pool but require quarters-long certification timelines.
- Residential:Individual end buyers seeking cost-controlled, code-compliant housing faster than conventional stick-built alternatives. Direct-to-developer distribution is reshaping how these units reach buyers, bypassing traditional dealer networks.
- Commercial:Private developers specifying manufactured units for workforce housing and rental portfolios.
- Institutional:Universities and healthcare operators procuring rapid-deployment accommodation.
Government procurement concentrates margin value while Residential delivers the highest unit velocity.
Installation:
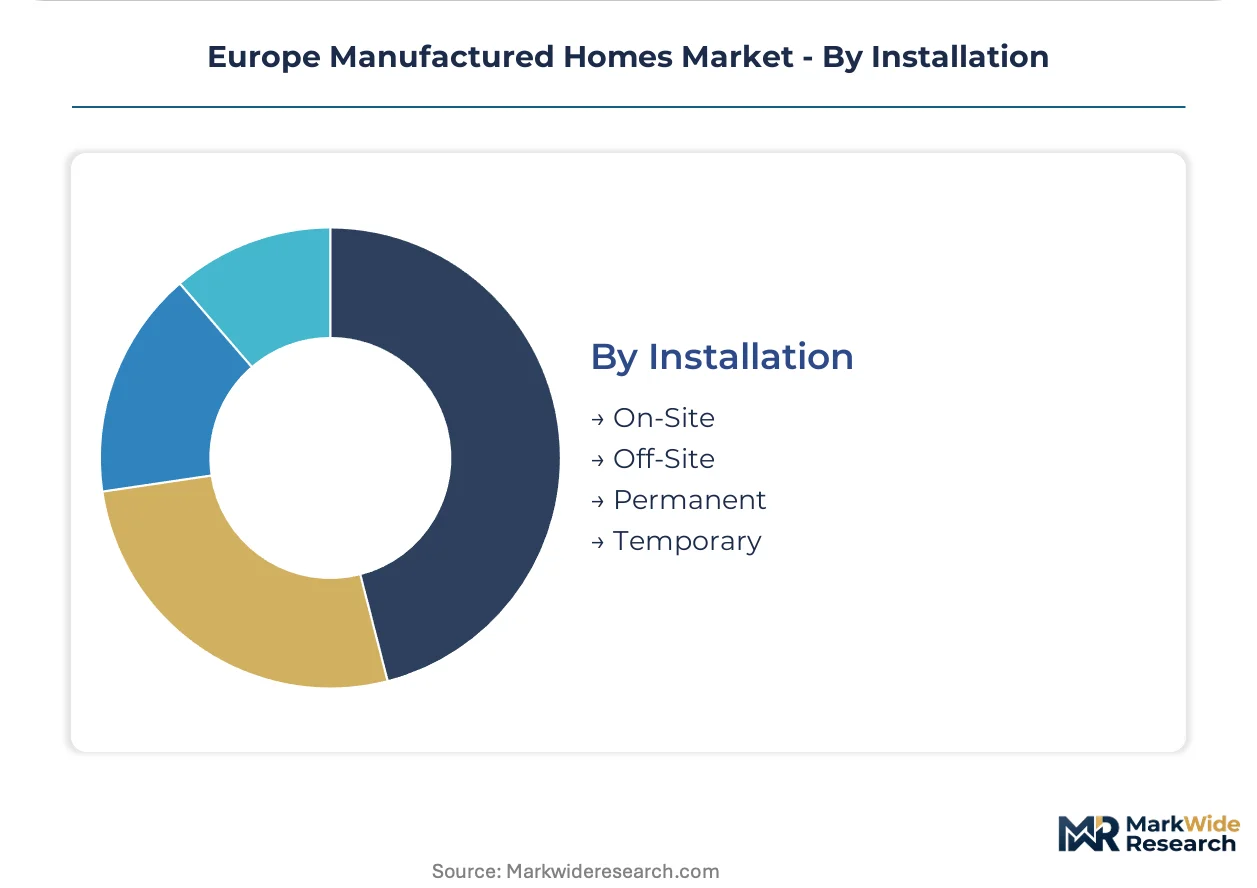
Site preparation requirements create a maturity gradient: temporary deployments turn fastest, permanent foundations slowest, with off-site fabrication compressing total project duration regardless of final anchoring method.
- Off-Site:Complete factory fabrication of volumetric units with transport to prepared foundations, minimizing weather delays and on-site waste. Skanska AB operates multiple production facilities serving Northern European markets through this model.
- Permanent:Foundation-anchored installations meeting national building codes for structural, thermal, and fire performance equivalent to conventional construction. Bouygues Batiment International anchors its France position through permanent modular construction for social housing programs.
- On-Site:Panelized or component-based assembly requiring extended construction duration.
- Temporary:Chassis-mounted deployments for emergency or transitional housing with minimal site preparation.
Permanent installation dominates value generation while Off-Site fabrication climbs the fastest as factory methods displace conventional construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Northern European markets where timber-frame thermal performance commands premium positioning, while Southern European procurement operates on compressed municipal budgets that prioritize unit velocity over margin capture.
Germany
Federal states including Bavaria and Baden-Württemberg relax zoning restrictions to permit manufactured home developments on previously restricted agricultural land. KBA-equivalent building authorities enforce supplementary state-level fire and seismic standards that drive specification upgrades for steel-frame systems. Factory clusters in North Rhine-Westphalia and Lower Saxony serve densification projects across the Rhine-Ruhr metropolitan corridor.
France
Municipal housing authorities in Île-de-France and Auvergne-Rhône-Alpes expand procurement of modular residential units to address chronic urban housing shortages. CE marking under the EU Construction Products Regulation mandates structural and energy performance declarations, while national regulators enforce embodied carbon documentation for public tender eligibility. Bouygues Batiment International anchors permanent modular construction capacity serving social housing programs in Greater Paris.
Sweden
Timber-frame thermal performance advances enable Passivhaus certification thresholds, expanding addressable market into high-efficiency social housing segments. Derome AB leverages vertically integrated timber supply chains to control material costs and delivery timelines for Scandinavian developers. Production facilities concentrate in Västra Götaland and Stockholm regions serving Nordic climate specifications.
United Kingdom
Laing O'Rourke and Portakabin Ltd operate off-site fabrication capacity addressing London's affordable housing deficit through rapid-deployment modular programs. National building regulations diverge from EU Construction Products Regulation frameworks post-Brexit, creating parallel certification requirements for cross-border suppliers. Manufacturing clusters in Midlands and Northern England serve Southeast England demand through established logistics corridors.
Spain
Regional governments in Catalonia and Andalusia issue tenders for rapid-deployment modular units to address chronic rental shortages in Barcelona and Seville metropolitan areas. Municipal procurement operates on compressed timelines that favor single-section configurations over multi-story modular systems. Eastern European assembly capacity in Poland and Romania creates logistics vulnerability for Western Spanish delivery commitments.
Europe Manufactured Homes Market Competitive Landscape
Vertically integrated timber specialists and off-site manufacturing scale operators split the market between supply-chain control and production throughput strategies. The vendor base concentrates among Northern European fabricators with captive access to cross-laminated timber feedstocks and established relationships with municipal housing authorities. Three archetypes dominate: timber-integrated producers controlling upstream material flows, multi-facility scale operators serving cross-border project pipelines, and permanent modular specialists anchoring social housing framework agreements. Competitive dynamics center on backward integration into timber supply and direct-to-developer channel compression that eliminates legacy dealer networks.
Among Sweden-based timber-integrated fabricators, Derome AB exemplifies supply-chain control archetypes through captive forestry and panel production assets. Skanska AB occupies the scale-driven position with multiple production facilities serving Northern European markets. Bouygues Batiment International anchors the permanent modular tier in France through social housing framework agreements with municipal authorities. These three represent divergent strategic postures: upstream integration, geographic scale, and procurement channel concentration.
| Leading Market Players |
|---|
| Laing O'Rourke |
| Derome AB |
| Skanska AB |
| DFH Group |
| Portakabin Ltd |
| Peab AB |
| Bouygues Batiment International |
| Wolf Holding GmbH |
| Swietelsky AG |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr freight corridors carry cross-laminated timber panels from Scandinavian mills to German factory clusters, with transport cost differentials separating captive-supply producers from spot-market buyers and compressing margin structures at each pricing tier.
Pricing Analysis
Configured-to-order premiums for Passivhaus-certified modular units run 25-40% above standard single-section baselines, with price differentiation driven by CE marking compliance tier and timber-frame thermal performance grade. Pricing pressure stems from steel input volatility under EU carbon border adjustment mechanisms, squeezing fire-rated frame margins. Government procurement channels exhibit lowest price sensitivity due to framework agreement structures, while residential direct buyers negotiate hardest on per-unit economics.
Supply Chain Analysis
Export-control friction on automated inspection technologies under the EU AI Act limits machine-vision system flows to non-EU suppliers, constraining quality documentation capabilities. Manufacturing gravity centers on Poland, Romania, and the Czech Republic for final assembly, with cross-laminated timber feedstocks drawing from Swedish and Finnish forestry operations. Single-source vulnerability concentrates in Eastern European production clusters serving Western European delivery commitments. Distribution runs through direct-to-developer channels that displace legacy dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's embodied carbon mandates constitute a regulatory inflection accelerating factory-built construction methods past conventional stick-built alternatives, positioning manufactured homes as the default compliance pathway for social housing procurement.
For Market Incumbents: Build certification moats around CE marking and lifecycle emissions documentation to exclude non-compliant rivals from French and German municipal tenders. Invest in backward integration into cross-laminated timber supply to offset steel price volatility. Anchor production capacity in North Rhine-Westphalia and Lower Saxony to capture Rhine-Ruhr densification demand. For New Entrants and Emerging Players: Spanish regional underpenetration in Catalonia and Andalusia offers rapid-deployment entry points where municipal budgets favor single-section velocity over multi-story complexity. Target government framework agreements with machine-vision quality systems that satisfy EU AI Act documentation requirements. Lead with direct-to-developer distribution to bypass entrenched dealer networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors timber-integrated producers with captive forestry assets and established municipal relationships over capital-heavy steel-frame operators exposed to carbon border costs. Acquisition targets should demonstrate Passivhaus certification capability and framework agreement penetration with French or German housing authorities. Watch for EU AI Act enforcement timelines as the signal indicating which quality-system investments will separate compliant from excluded suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive cross-laminated timber production insulates Derome AB from Nordic pulp price swings. |
| Machine-Vision Quality System Deployment | Automated inspection infrastructure satisfies EU AI Act traceability mandates for German public tenders. |
| Direct-to-Developer Channel Expansion | Bypassing dealer networks captures margin and accelerates project timelines for multi-unit residential developers. |
| Passivhaus Certification Investment | Thermal performance credentials unlock German federal zoning relaxation for urban densification sites. |
| Eastern European Assembly Capacity Addition | Polish and Romanian production facilities reduce delivery lead times to Western European markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Construction Products Regulation filings, municipal procurement databases, and timber trade flow records. Interviews with factory operations directors, social housing procurement officers, cross-laminated timber suppliers, and building authority regulators combined with customs data and industry association reports. Bottom-up unit shipment estimates triangulated against top-down construction spend allocations across member states.
Forecast inputs span product type complexity cycles, material cost trajectories, and zoning policy relaxation timelines across the projection horizon. Segmentation dimensions modeled include factory fabrication method, thermal performance tier, procurement channel structure, and national regulatory cluster. CAGRs derive from regression analysis of historical shipment data against policy implementation schedules and embodied carbon threshold phase-ins.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, energy input costs, or cross-border freight tariffs would shift the trajectory. Material shifts in EU AI Act enforcement intensity or Green Deal carbon threshold acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Japan Residential Construction Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
US Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Residential Roofing Market