
 Epoxy Powder Coatings Market | 2026-2036
Epoxy Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Powder Coatings Market Foresight
The gap between premium thermosetting grades and commodity hybrid formulations is consolidating as automotive and aerospace buyers enforce tighter specification windows while construction and furniture segments prioritize cost. PPG Industries leverages its North American automotive OEM relationships to sustain high-margin specification positions. Akzo Nobel anchors European demand through marine and protective coating channels. Axalta Coating Systems competes aggressively in the industrial coatings segment with fluidized bed and electrostatic spray system integration.
Epoxy powder coatings are thermosetting polymer systems based on bisphenol-A or bisphenol-F epoxy resins cross-linked with carboxyl or hydroxyl functionalized polyesters, applied as dry powders at film builds of 40-120 microns and cured at 160-200°C to form chemically resistant, electrically insulating surface barriers. Thermosetting variants dominate specification-driven end uses where chemical resistance and dielectric strength are non-negotiable, while hybrid formulations capture volume in construction and domestic appliance applications where moderate performance at lower applied cost drives procurement decisions. Electrostatic spray technology leads application method adoption due to transfer efficiency and complex geometry coverage, with fluidized bed retaining share in thick-film industrial and marine coating contexts.
EPA NESHAP standards and REACH Annex XVII restrictions on hexavalent chromium and solvent emissions compel coating line conversions toward zero-VOC powder systems, while ISO 12944 corrosion protection classifications shape product qualification protocols for marine and infrastructure applications. China's MEE enforcement of dual carbon goals accelerates domestic appliance manufacturer shifts from liquid to powder coating lines. Stakeholders must monitor regulatory divergence between jurisdictions where carbon border adjustments and chemical hazard reclassifications threaten to fragment compliance requirements and reshape sourcing geography.
Market Dynamics
Automotive OEMs are forcing specification consolidation across epoxy powder coating tiers as under-hood thermal management requirements harden and chassis corrosion warranties extend to 15-year terms.
Growth Catalysts
- EPA NESHAP compliance deadlines:Liquid solvent-borne coating lines face mandated conversion timelines across US manufacturing facilities, accelerating powder system retrofit investments.
- China's appliance sector:Domestic refrigerator and washing machine manufacturers are converting entire coating operations to zero-VOC powder lines under MEE enforcement of dual carbon goals.
- Fluidized bed application technology:Thick-film marine and industrial pipe coating specifications now specify fluidized bed methods for 250-500 micron builds, expanding addressable substrate categories.
Market Restraints
- Bisphenol-A feedstock concentration:Epoxy resin precursor supply clusters in China's Shandong and Jiangsu provinces, creating single-source vulnerability for Western formulators.
- Cure temperature floor:Thermosetting epoxy systems require minimum 160°C substrate temperatures, excluding heat-sensitive plastics and pre-assembled components from specification.
- Hexavalent chromium substitution lag:REACH Annex XVII restrictions on Cr(VI) corrosion inhibitors force reformulation cycles that extend qualification timelines by 18-24 months.
Strategic Opportunities
- India's industrial corridor expansion:Gujarat and Maharashtra infrastructure projects lack established powder coating supplier relationships, creating first-mover specification capture potential.
- UV-curable epoxy hybrids:Convergence of traditional thermal cure chemistry with UV-initiated crosslinking enables line speed doubling at reduced energy intensity.
- EU Green Deal carbon border adjustments:Import tariffs on embodied carbon favor regional European powder coating production over Asian liquid coating imports.
Industry Challenges
- Electrostatic spray technician scarcity:Complex Faraday cage penetration and wrap-around deposition control require 2,000+ hour certification programs that outpace vocational training pipeline output.
- ISO 12944-6 cyclic testing duration:Marine coating qualification protocols demand 6,000-hour salt spray and cyclic humidity sequences that compress product development calendars.
- Legacy liquid line stranded assets:Automotive tier suppliers face write-down pressure on solvent-borne capital equipment with remaining depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Powder Coatings Market |
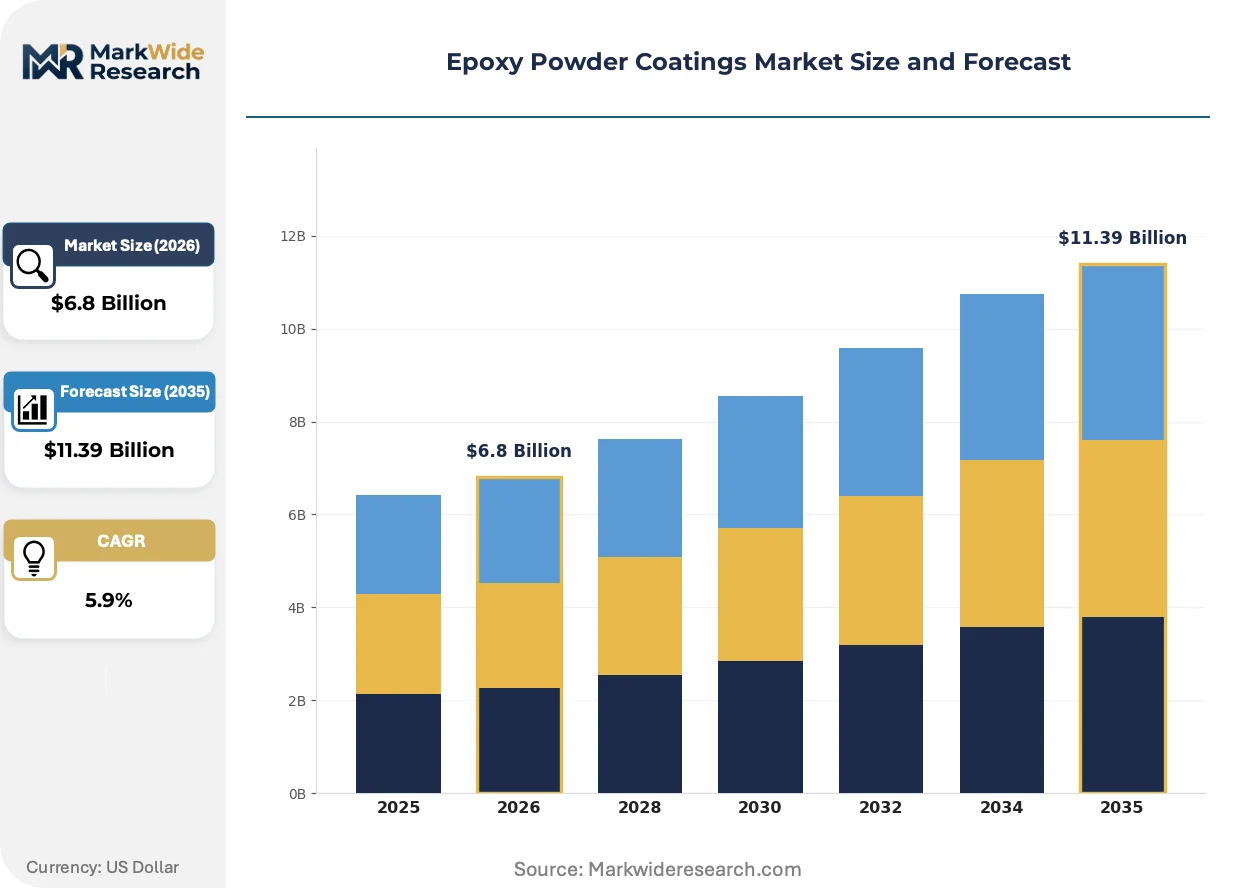
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Thermoplastic, Hybrid, Conductive End Use Industry: Automotive, Construction, Aerospace, Furniture Application: Industrial Coatings, Architectural Coatings, Domestic Appliance Coatings, Marine Coatings Technology: Electrostatic Spray, Fluidized Bed, Hybrid Coating, Thermal Spray |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems, 3M, BASF SE, Jotun A/S, Evonik Industries AG, Diamond Vogel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Powder Coatings Market Shifts & Advancements
Epoxy powder coating technology is fragmenting along thermal performance lines as automotive electrification and renewable energy infrastructure impose divergent specification demands on resin formulators.
Low-temperature cure epoxy formulations incorporating latent catalysts and modified anhydride hardeners are decentralizing application infrastructure from centralized automotive OEM plants toward tiered supplier networks and job-shop operations. Appliance manufacturers in Mexico and Eastern Europe are adopting 140°C cure systems to coat pre-assembled refrigerator liners and dishwasher tubs without component warping. This thermal window compression is enabling powder coating penetration into substrate categories previously reserved for liquid UV or waterborne systems.
REACH Annex XVII amendments restricting per- and polyfluoroalkyl substances are forcing reformulation of epoxy powder coatings containing PTFE-based texture modifiers and slip agents. European protective coating specifiers are shifting qualification protocols toward silicone resin hybrids and ceramic microsphere alternatives. Marine and offshore infrastructure projects in the North Sea and Baltic regions are experiencing 12-18 month coating approval delays as ECHA substance evaluations proceed.
Automotive OEMs are unbundling coating procurement from tiered component supply, establishing direct qualification relationships with epoxy powder formulators for under-hood thermal management components. Tier-one suppliers in Germany and the US Midwest are losing specification control as powertrain electrification eliminates traditional engine block coating volumes and creates new battery tray and inverter housing categories. This disintermediation is most visible in Volkswagen Group's direct sourcing agreements with PPG and Axalta for MEB platform thermal barrier coatings.
Epoxy Powder Coatings Market Segmentation
Epoxy powder coating procurement patterns diverge sharply between specification-driven sectors demanding certified thermal and chemical performance and cost-sensitive segments prioritizing throughput and film build economy. Formulators must maintain parallel product architectures to serve these incompatible requirement sets without cross-contamination of margin structures.
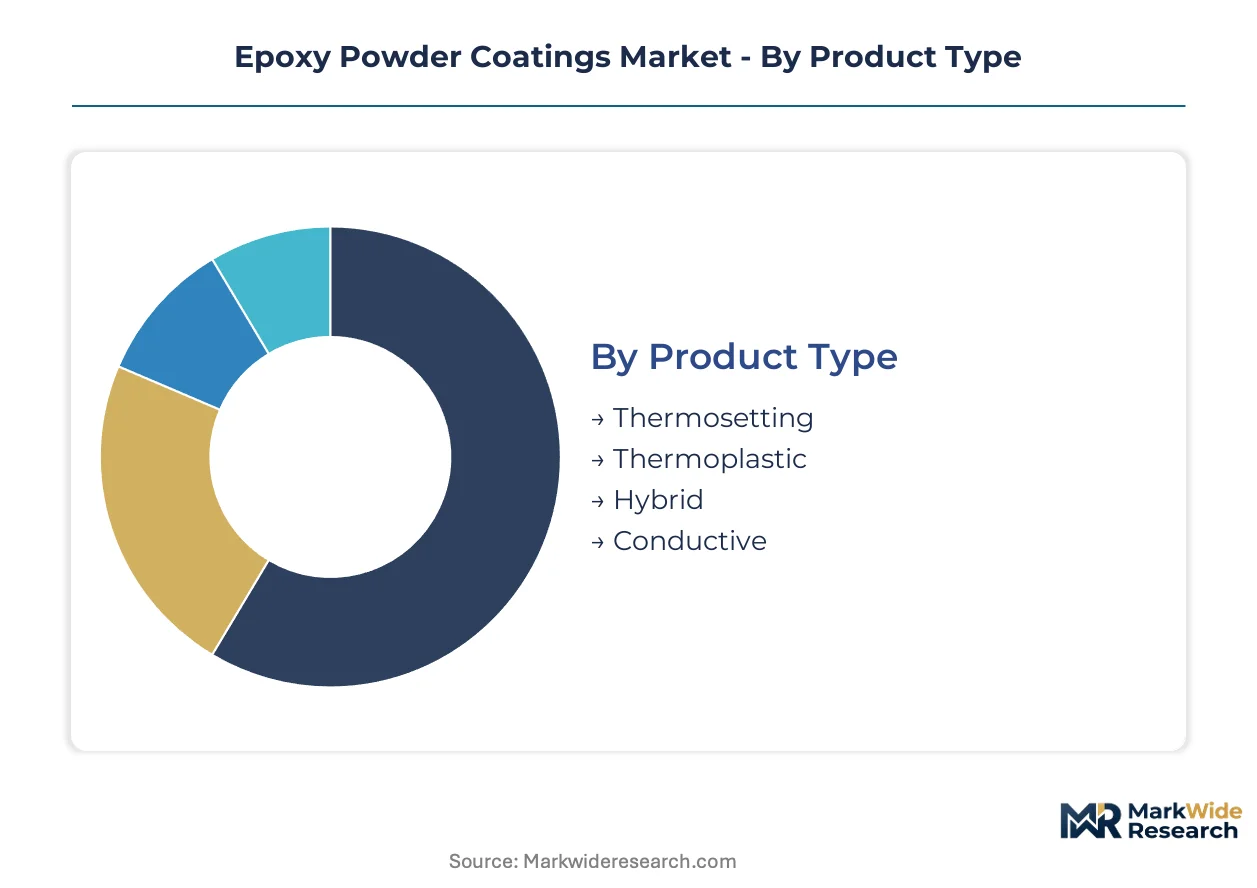
Product Type:
Thermosetting grades command specification premiums in corrosion-critical applications while hybrid formulations capture volume through raw material cost arbitrage and lower cure energy requirements.
- Thermosetting:Bisphenol-A and bisphenol-F epoxy resins cross-linked with carboxyl-functionalized polyesters deliver chemical resistance and dielectric strength for under-hood automotive and electrical enclosure specifications. Demand concentrates in German automotive OEM supply chains where 15-year corrosion warranties mandate certified coating systems.
- Hybrid:Blended epoxy-polyester chemistries reduce raw material costs while maintaining adequate outdoor durability for construction and appliance applications. Chinese refrigerator and washing machine manufacturers are converting liquid lines to hybrid powder systems under MEE enforcement of dual carbon goals.
- Thermoplastic:Linear polymer structures enable remelt and repair characteristics for specialized electrical insulation and pipe coating applications.
- Conductive:Carbon black or metallic filler loadings provide static dissipation for electronics manufacturing environments and hazardous material handling equipment.
Most installed capacity flows through Thermosetting. Expansion is steepest in Hybrid.
End Use Industry:
Automotive qualification protocols enforce the tightest specification windows while furniture and construction procurement prioritizes coverage efficiency and color consistency at scale.
- Automotive:Under-hood thermal management components, chassis systems, and battery tray enclosures require 160-200°C cure systems with salt spray resistance exceeding 3,000 hours. Volkswagen Group's direct sourcing agreements for MEB platform thermal barrier coatings are disintermediating traditional tier-one suppliers.
- Construction:Rebar, structural steel, and aluminum facade systems drive volume demand for 80-120 micron protective films. Infrastructure projects in India's Gujarat and Maharashtra corridors lack established supplier relationships, creating first-mover specification capture potential.
- Aerospace:Fuel tank coatings and interior component finishes must satisfy FAA flammability and outgassing standards with extended qualification timelines.
- Furniture:Metal office systems and outdoor leisure equipment prioritize scratch resistance and UV stability at lowest applied cost per square meter.
Automotive consumes the highest premium-grade tonnage. Construction is climbing the fastest.
Application:
Film thickness requirements separate industrial specifications demanding 250-500 micron builds from architectural and appliance segments optimizing material efficiency at 40-80 microns.
- Industrial Coatings:Fluidized bed application of thick-film systems protects pipelines, valves, and chemical processing equipment from aggressive media. Marine and offshore specifications in the North Sea now mandate fluidized bed methods for subsea hardware.
- Domestic Appliance Coatings:Refrigerator liners, dishwasher tubs, and washing machine drums require 140-160°C cure systems to prevent warping of pre-assembled components. Mexican and Eastern European appliance plants are adopting low-temperature epoxy formulations to enable powder conversion.
- Architectural Coatings:Aluminum window frames, curtain wall systems, and metal roofing demand color consistency and chalk resistance across batch variations.
- Marine Coatings:Ballast tanks, deck hardware, and offshore platforms require ISO 12944-6 cyclic testing certification with 6,000-hour salt spray sequences.
Industrial Coatings commands the highest per-kilogram pricing. Domestic Appliance Coatings is gaining share fastest.
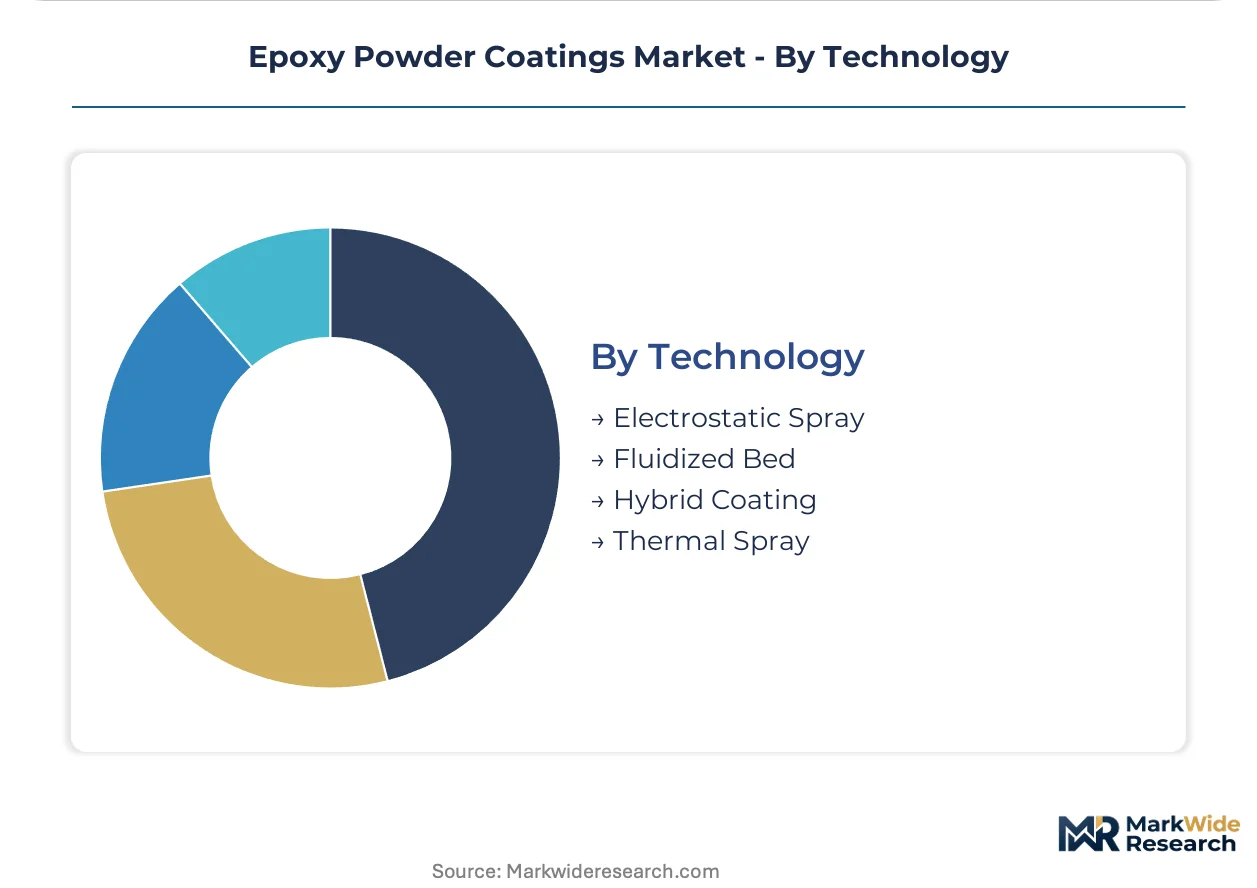
Technology:
Transfer efficiency and substrate geometry complexity determine application method selection between electrostatic spray dominance and fluidized bed retention in thick-film contexts.
- Electrostatic Spray:Corona or tribo-charging deposition achieves 95%+ transfer efficiency on complex geometries including automotive under-hood components and electrical enclosures. Faraday cage penetration challenges require 2,000+ hour technician certification programs.
- Fluidized Bed:Preheated substrate immersion builds 250-500 micron films in single dips for pipe fittings and valve bodies. Marine specifications in Baltic region infrastructure projects are expanding addressable substrate categories.
- Hybrid Coating:Combined electrostatic and fluidized bed methods optimize coverage on mixed-geometry production lines.
- Thermal Spray:Flame and arc deposition of powder feedstock repairs worn industrial components and applies corrosion barriers to oversized substrates.
Electrostatic Spray holds the largest installed base. Fluidized Bed is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor conversion pace outstrips Germany's automotive specification tightening, while India's infrastructure build-out creates vacuum conditions for supplier establishment. Regulatory divergence between EPA NESHAP deadlines and REACH Annex XVII amendments is fragmenting qualification protocols across manufacturing geographies.
China
Domestic refrigerator and washing machine manufacturers are converting entire coating operations to zero-VOC powder lines under MEE enforcement of dual carbon goals. GB standards for volatile organic compound emissions in industrial coatings now mandate powder system adoption for new facility permits. Shandong and Jiangsu provinces concentrate epoxy resin precursor supply, creating single-source vulnerability for Western formulators seeking feedstock security.
Germany
Automotive OEMs enforce 15-year corrosion warranties that mandate certified thermosetting coating systems for under-hood and chassis applications. KBA type-approval protocols for vehicle component coatings now incorporate REACH Annex XVII restrictions on hexavalent chromium corrosion inhibitors. Bavaria's automotive supplier belt around Munich and Ingolstadt experiences direct disintermediation as Volkswagen Group establishes direct sourcing agreements with powder formulators.
United States
EPA NESHAP compliance deadlines for liquid solvent-borne coating lines accelerate powder system retrofit investments across Midwest manufacturing facilities. Automotive tier suppliers in Michigan and Ohio face write-down pressure on stranded solvent-borne capital equipment with remaining depreciation schedules. The Southeast industrial corridor from Georgia to Tennessee attracts appliance manufacturer relocations seeking lower energy costs for cure operations.
India
Gujarat and Maharashtra infrastructure projects lack established powder coating supplier relationships, creating first-mover specification capture potential for formulators with ISO 12944-6 certification capabilities. BIS standards for protective coatings on structural steel are converging toward international corrosion protection classifications. The Delhi-Mumbai Industrial Corridor's special economic zones offer tariff advantages for imported application equipment and resin feedstocks.
Mexico
Appliance manufacturers in Nuevo León and the Bajío Region adopt low-temperature cure systems to coat pre-assembled refrigerator liners without component warping. Nearshoring momentum from US automotive OEMs transfers specification requirements for under-hood thermal management coatings across the border. Mexican environmental enforcement under SEMARNAT is tightening VOC limits in industrial coatings faster than regional supply chain readiness.
Epoxy Powder Coatings Market Competitive Landscape
Top-tier vendors anchor specification-driven automotive and marine segments, while mid-scale formulators compete on hybrid formulation cost and regional logistics. The market structure consolidates around three to four integrated resin-to-coating suppliers with captive feedstock positions, surrounded by numerous regional job-shop formulators serving construction and appliance accounts. Two strategic archetypes dominate: vertically integrated chemical conglomerates controlling bisphenol-A supply chains, and application-technology specialists bundling coating systems with electrostatic or fluidized bed equipment. Capacity expansion and direct OEM qualification relationships represent the dominant competitive moves, displacing traditional tier-one supplier intermediation.
Within the integrated chemical conglomerate tier, PPG Industries, Akzo Nobel N.V., and Axalta Coating Systems exemplify contrasting geographic anchoring strategies. PPG occupies a position calibrated toward North American automotive OEM relationships, while Akzo Nobel represents European marine and protective coating channel concentration. Axalta sits within industrial coatings specialization with fluidized bed and electrostatic spray system integration capabilities. These three entities collectively represent the specification premium tier where corrosion warranty certification and thermal performance documentation determine procurement decisions.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| 3M |
| BASF SE |
| Jotun A/S |
| Evonik Industries AG |
| Diamond Vogel |
| Others |
Supply & Pricing Matrix
Automotive OEM direct sourcing agreements concentrate procurement leverage among specification-grade buyers, forcing three-tier pricing stratification across premium thermosetting, standard hybrid, and economy commodity formulations. This buyer concentration rewards certified suppliers with long-term contract stability while squeezing margins on uncertified volume production.
Pricing Analysis
Bundled coating-application system packages command premiums over unbundled powder-only supply, with electrostatic spray equipment integration adding fifteen to twenty percent to contract values. Price differentiation hinges on ISO 12944-6 certification tier and automotive OEM direct qualification status, with certified suppliers capturing premium positions. Cost compression in hybrid formulations is intensifying as Chinese appliance manufacturers scale zero-VOC conversions. Construction procurement teams exhibit highest price sensitivity, while marine and aerospace specifiers prioritize performance documentation over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and North American infrastructure contractors require formulators to qualify secondary resin suppliers beyond dominant Chinese feedstock channels. Epoxy powder coating supply draws from bisphenol-A precursors concentrated in China's Shandong and Jiangsu provinces, with secondary aromatic amine hardener production in Germany and the United States. Single-source vulnerability in Chinese resin precursor supply creates tariff exposure and logistics chokepoint risk. Distribution runs through regional coating job-shops for construction and appliance accounts, with direct OEM supply chains serving automotive and marine specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy powder coatings function as a regulatory compounder where REACH Annex XVII restrictions on hexavalent chromium and EPA NESHAP compliance deadlines structurally expand addressable market size by mandating line conversions.
For Market Incumbents: Lock in captive bisphenol-A supply positions through backward integration or long-term offtake agreements with Shandong and Jiangsu resin producers. Accelerate ISO 12944-6 certification investments to defend specification premium positions against emerging Asian formulators targeting European marine procurement.
For New Entrants and Emerging Players: India's Gujarat and Maharashtra infrastructure contractors represent the most penetrable buyer archetype, with first-mover specification capture potential in protective coatings for structural steel. Target fluidized bed application capability as the go-to-market angle, as established suppliers underinvest in thick-film marine and industrial pipe coating segments.
For Investors and Strategic Acquirers: Chemical conglomerates with captive resin positions are the most active acquirer in this space, consolidating regional formulators to secure OEM qualification relationships. Acquisition targets should display dual certification in automotive and marine specifications. Watch MEB platform thermal barrier coating procurement volumes as the inflection signal for electrification-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A Resin Supply | Captive feedstock secures margin protection against Shandong supply volatility. |
| Low-Temperature Cure Formulation Development | 140°C systems unlock Mexican and Eastern European appliance manufacturer conversions. |
| Fluidized Bed Application Technology Bundling | Thick-film capability captures North Sea marine infrastructure specifications. |
| Direct OEM Qualification Relationship Building | Volkswagen Group MEB platform agreements demonstrate disintermediation value. |
| REACH Annex XVII Compliant Reformulation | PTFE-free texture modifiers prevent Baltic region coating approval delays. |
Research Methodology
Multiple input streams — primary interviews with coating formulators, automotive OEM procurement directors, and marine specification engineers; secondary validation through customs trade data, SEC 10-K filings, and Cefic chemical industry reports; and technical literature from ISO standards committees — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision criteria across German automotive supply chains, Chinese appliance manufacturing clusters, and Indian infrastructure project offices. Secondary sources included EPA NESHAP regulatory filings, REACH Annex XVII amendment documentation, and MEE enforcement bulletins on dual carbon goals.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include thermosetting-hybrid-thermoplastic grade tier, automotive-construction-appliance end-use industry, electrostatic spray-fluidized bed application technology, and regional production hub clustering. CAGRs were derived from installed base conversion rates and new facility permitting data. Industry-specific forecast inputs incorporated automotive electrification platform rollouts and marine infrastructure project pipelines.
Underlying measurement precision varies by segment; automotive OEM direct qualification data carries tighter precision than construction job-shop volume estimates. Forecasts reflect assumptions on regulatory enforcement consistency, resin precursor supply stability, and cure temperature technology adoption curves. Deviation in EPA NESHAP compliance deadline extensions or ECHA substance evaluation acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Rail Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
China Protective Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Batters and Coatings Market
Coatings
Global Waterborne Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Coating Binders Market
Coatings
Liquid-Applied Roof Coating Market