
 Graphene Coatings Market | 2026-2036
Graphene Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Coatings Market Analysis
The premium-commodity split in graphene coatings is shifting as aerospace-grade formulations with validated thermal cycling data command five-fold pricing multiples over undifferentiated powder additives. NanoXplore Inc. leverages captive flake production to secure supply certainty for tier-one automotive contracts. Haydale Graphene Industries PLC anchors its position through plasma functionalization expertise that reduces batch-to-batch variability. Directa Plus S.p.A. competes on mining-linked feedstock costs from its Colombian graphite supply chain.
Graphene coatings are atomically thin carbon lattices, typically one to ten layers thick, deposited via chemical vapor deposition or liquid-phase exfoliation to impart electrical conductivity, thermal dissipation, or barrier protection against oxidation and corrosion. The protective and anti-corrosive coating types dominate current revenue as marine and infrastructure operators validate multi-year field performance against zinc-rich primers. Aerospace and electronics applications are outpacing automotive in growth velocity, driven by satellite thermal management needs and printed circuit board shielding requirements where film-form graphene achieves sub-ohm sheet resistance targets.
REACH registration requirements in the European Union and EPA New Chemicals Program scrutiny in the United States are lengthening commercialization timelines but simultaneously advantaging pre-registered producers with existing dossiers. China's GB standards for industrial coatings and South Korea's MFDS material safety protocols are converging toward nano-specific hazard classifications that favor suppliers with toxicology data packages. Stakeholders must weigh regulatory compliance investment against the window for first-mover positioning in battery thermal interface coatings before standardized supply agreements crystallize.
Market Dynamics
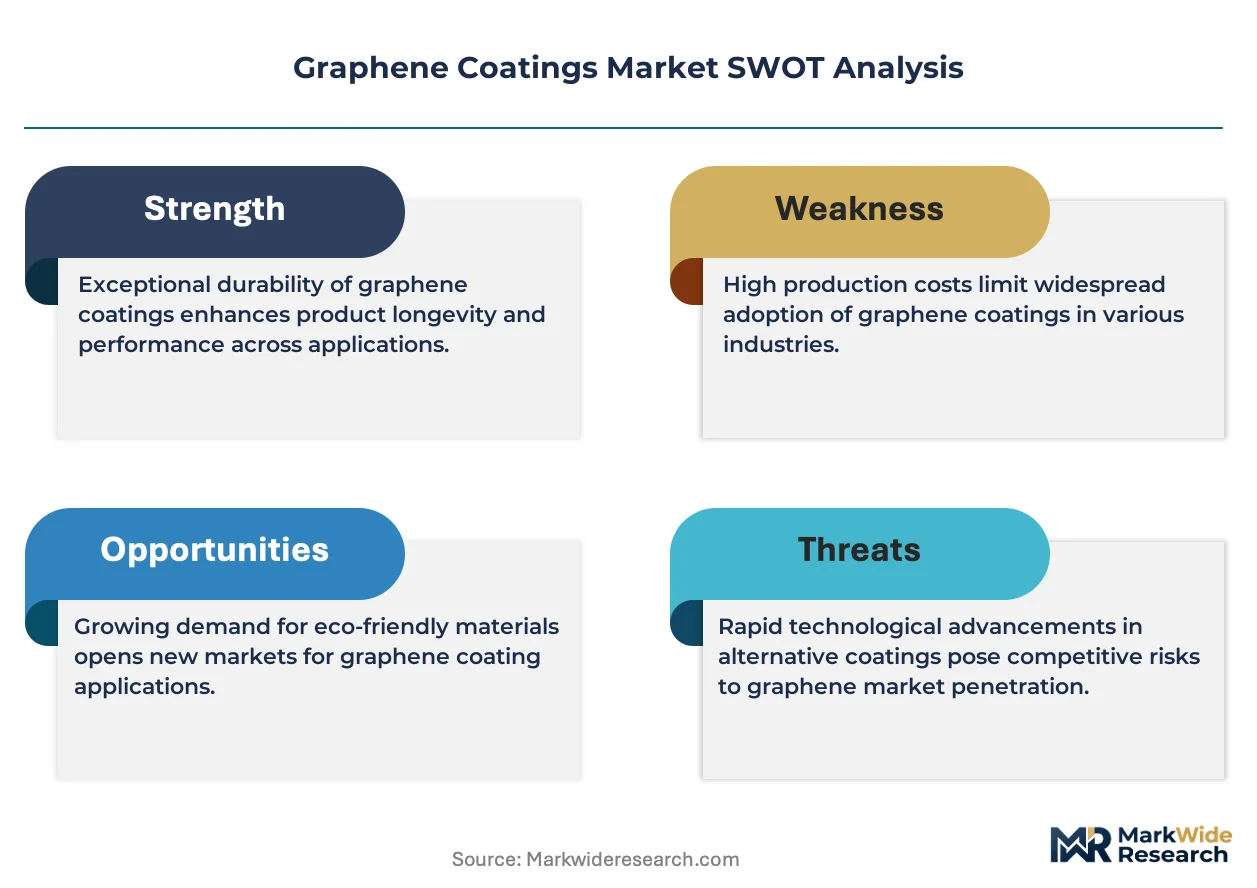
Aerospace OEMs are consolidating procurement around validated graphene thermal barrier systems, compressing qualification timelines and forcing coating suppliers to front-load toxicology dossiers ahead of regulatory deadlines.
Growth Catalysts
- REACH registration momentum:Pre-registered producers in the European Union with existing dossiers are capturing accelerated qualification pathways for battery thermal interface materials.
- Marine infrastructure validation:Multi-year field data from offshore platforms and port facilities is displacing zinc-rich primers in corrosion protection specifications.
- Plasma functionalization:Reduced batch-to-batch variability in conductivity metrics is unlocking tier-one automotive electronics contracts.
Market Restraints
- High-purity graphite feedstock volatility:Colombian and Chinese mining-linked supply chains face extraction permit delays and export quota tightening.
- EPA New Chemicals Program scrutiny:Lengthened commercialization timelines in the United States favor incumbents with existing PMN approvals.
- Silicon carbide thermal interface competition:Mature supply chains and lower per-watt pricing in power electronics cooling applications constrain graphene penetration.
Strategic Opportunities
- South Korean battery foundry cluster expansion:MFDS material safety protocols favor suppliers with nano-specific hazard classifications already on file.
- Satellite thermal management:Film-form graphene achieving sub-ohm sheet resistance targets is opening low-earth orbit constellation supply chains.
- China GB standards convergence:Industrial coating reformulation mandates away from solvent-based systems create first-mover windows for waterborne graphene dispersions.
Industry Challenges
- ISO/TS 80004-13 nano-terminology compliance:Inconsistent layer-count definitions across testing laboratories delay customer qualification cycles.
- CVD reactor capex intensity:Chemical vapor deposition capacity expansion requires $15-25 million per production line, constraining mid-cap scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Coatings Market |
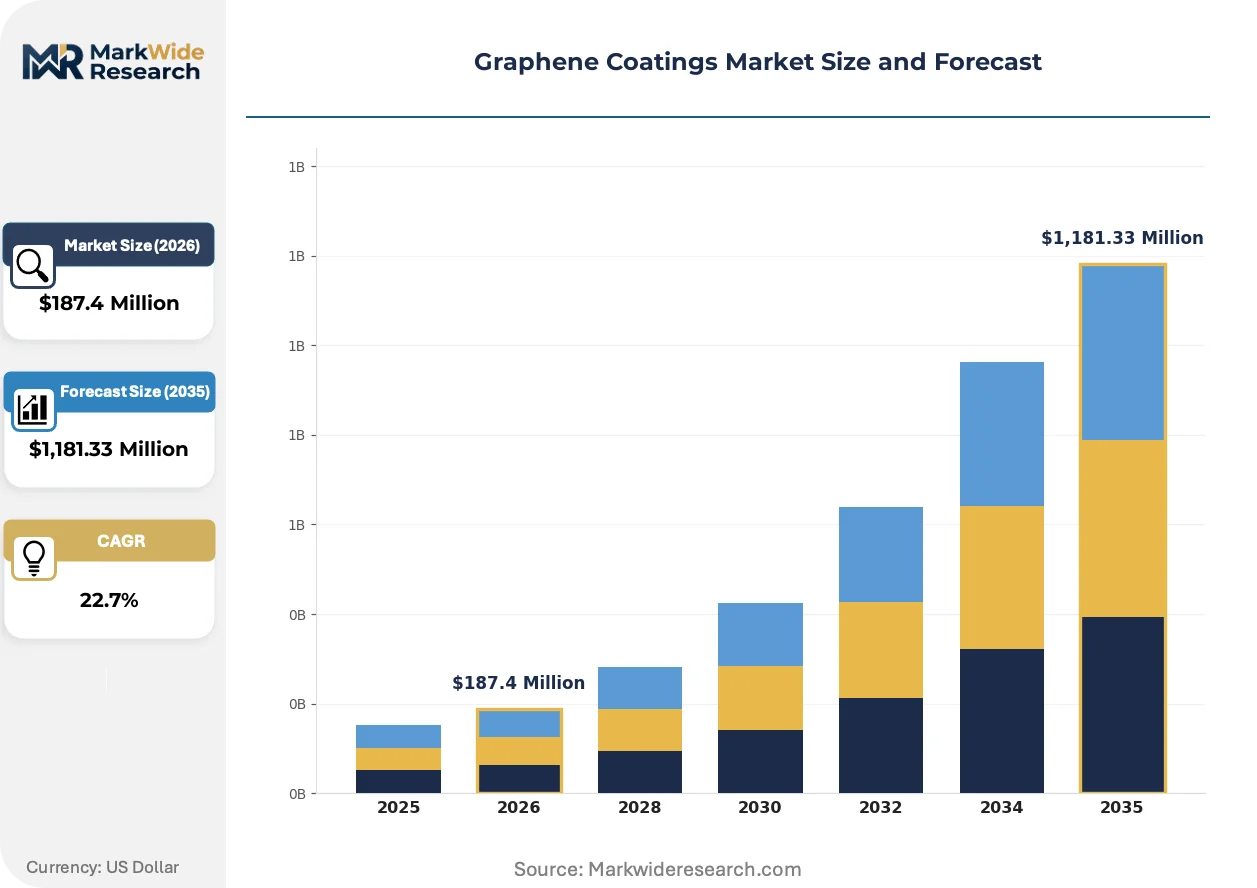
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Thermal, Electrical, Protective, Anti-corrosive Application: Aerospace, Automotive, Electronics, Marine End User: Manufacturing, Construction, Energy, Defense Form: Liquid, Powder, Spray, Film |
| Companies Covered | NanoXplore Inc., Directa Plus S.p.A., Haydale Graphene Industries PLC, Vorbeck Materials Corp, Universal Matter, Grafoid Inc., Graphenea Inc., Global Graphene Group, Xiamen Knano Graphene Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Coatings Market Emerging Trajectories
Liquid-phase exfoliation routes are compressing capital barriers to entry while plasma and electrochemical functionalization methods are fragmenting the patent landscape around surface chemistry control.
Electrochemical exfoliation is decentralizing graphene flake production away from centralized chemical vapor deposition facilities. Battery manufacturers in South Korea and China are installing modular 10-ton-per-year units adjacent to cell assembly lines. This distributed model is collapsing the traditional three-tier supply chain into direct producer-OEM relationships.
REACH Annex XV dossier requirements for nanoforms are forcing reformulation roadmaps across the European Union. Coating suppliers must submit granular characterization data including lateral dimension distributions and surface oxygen content. Marine and infrastructure segments are absorbing these compliance costs fastest due to longer contract durations that amortize testing investments.
Specification-driven procurement is consolidating buyer power among tier-one aerospace and automotive OEMs. These customers now require thermal cycling validation data across 1,000+ cycles before contract award, displacing spot-market spot purchases. South Korean electronics assemblers and German automotive suppliers are most advanced in mandating these performance guarantees upfront.
Graphene Coatings Market Segmentation
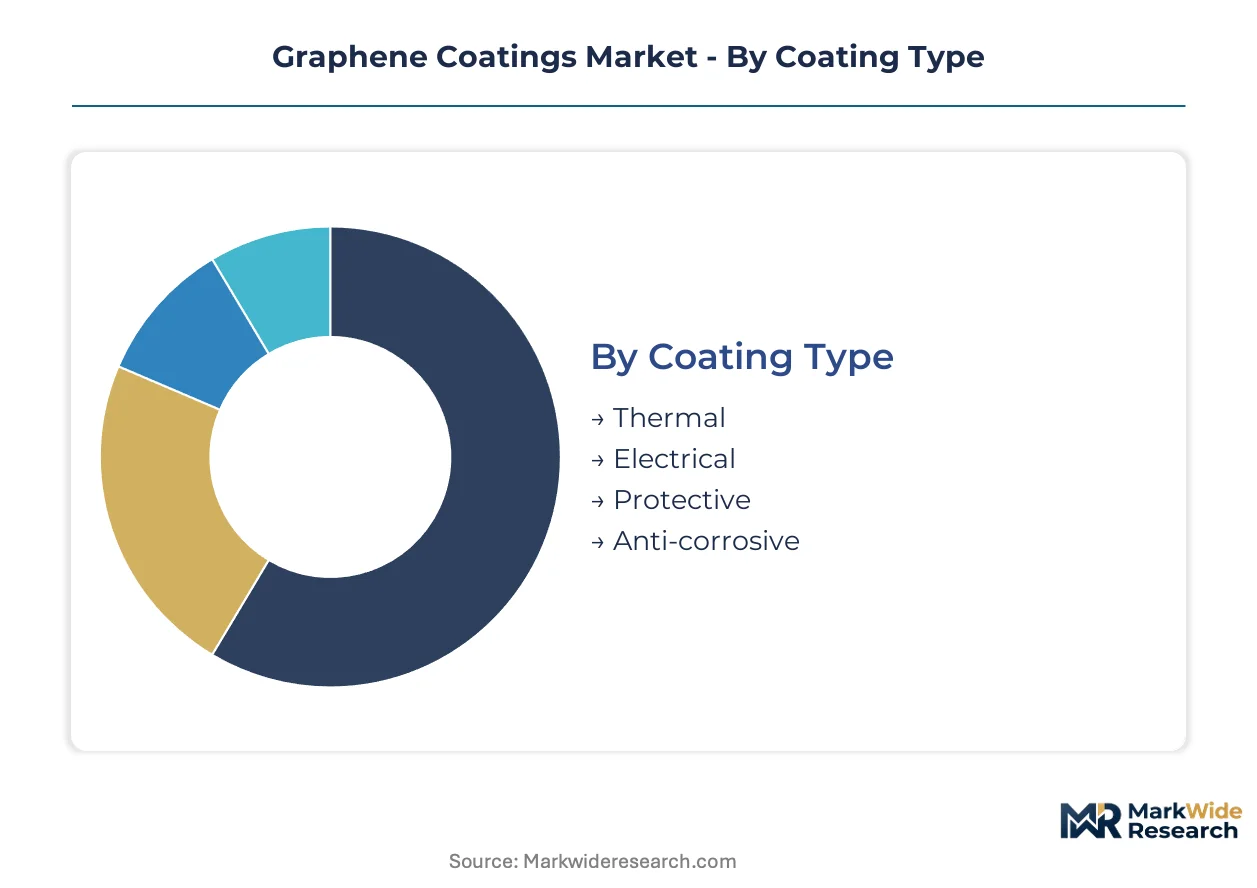
Segmentation in graphene coatings tracks divergent technical specifications across end-use verticals. Aerospace buyers prioritize validated thermal cycling data while marine operators weigh field-proven corrosion resistance against zinc-rich alternatives.
Coating Type:
Buyers select coating type based on functional performance requirements and qualification burden.
- Protective:Barrier formulations prevent oxidation and moisture ingress through atomically dense carbon lattices. Marine infrastructure operators in European port facilities are absorbing REACH Annex XV compliance costs fastest due to amortization across long contract durations.
- Anti-corrosive:These coatings displace zinc-rich primers in offshore platform specifications after multi-year field validation. Demand concentrates in Chinese industrial coating reformulation mandates moving away from solvent-based systems under GB standards.
- Thermal:Heat dissipation coatings for battery thermal interface materials.
- Electrical:Conductive formulations achieving sub-ohm sheet resistance for printed circuit board shielding.
Volume sits with protective formulations; growth tilts toward anti-corrosive as marine specifications harden.
Application:
Application selection follows OEM qualification timelines and performance guarantee requirements.
- Aerospace:Thermal barrier systems for airframe components and satellite thermal management. South Korean and German OEMs mandate 1,000+ cycle validation data before contract award, compressing supplier qualification windows.
- Electronics:Film-form graphene for printed circuit board shielding and thermal interface materials. Battery foundries in South Korea are installing modular production units adjacent to cell assembly lines, collapsing traditional supply chains.
- Automotive:Tier-one electronics contracts requiring plasma-functionalized flake with reduced batch-to-batch conductivity variability.
- Marine:Corrosion protection for offshore platforms and port infrastructure.
Aerospace commands premium pricing multiples; electronics expands most quickly on distributed manufacturing adoption.
End User:
End-user procurement patterns reflect contract duration and regulatory exposure.
- Manufacturing:Electronics assemblers and battery producers drive specification-driven procurement with upfront performance guarantees.
- Energy:Battery thermal interface coatings for power electronics cooling applications competing against silicon carbide alternatives.
- Construction:Infrastructure operators validating multi-year field performance against established coating systems.
- Defense:Satellite constellation suppliers requiring sub-ohm sheet resistance for low-earth orbit thermal management.
Manufacturing absorbs fastest qualification cycles; energy faces margin pressure from mature thermal interface alternatives.
Form:
Form factor determines capital intensity and supply chain configuration.
- Liquid:Waterborne dispersions gaining share under China's GB industrial coating reformulation mandates away from solvent-based systems.
- Film:Chemical vapor deposition films achieving precise layer control for aerospace thermal barrier specifications.
- Powder:Undifferentiated flake additives competing on mining-linked feedstock costs from Colombian graphite supply chains.
- Spray:Applied formulations for field deployment in marine and infrastructure maintenance.
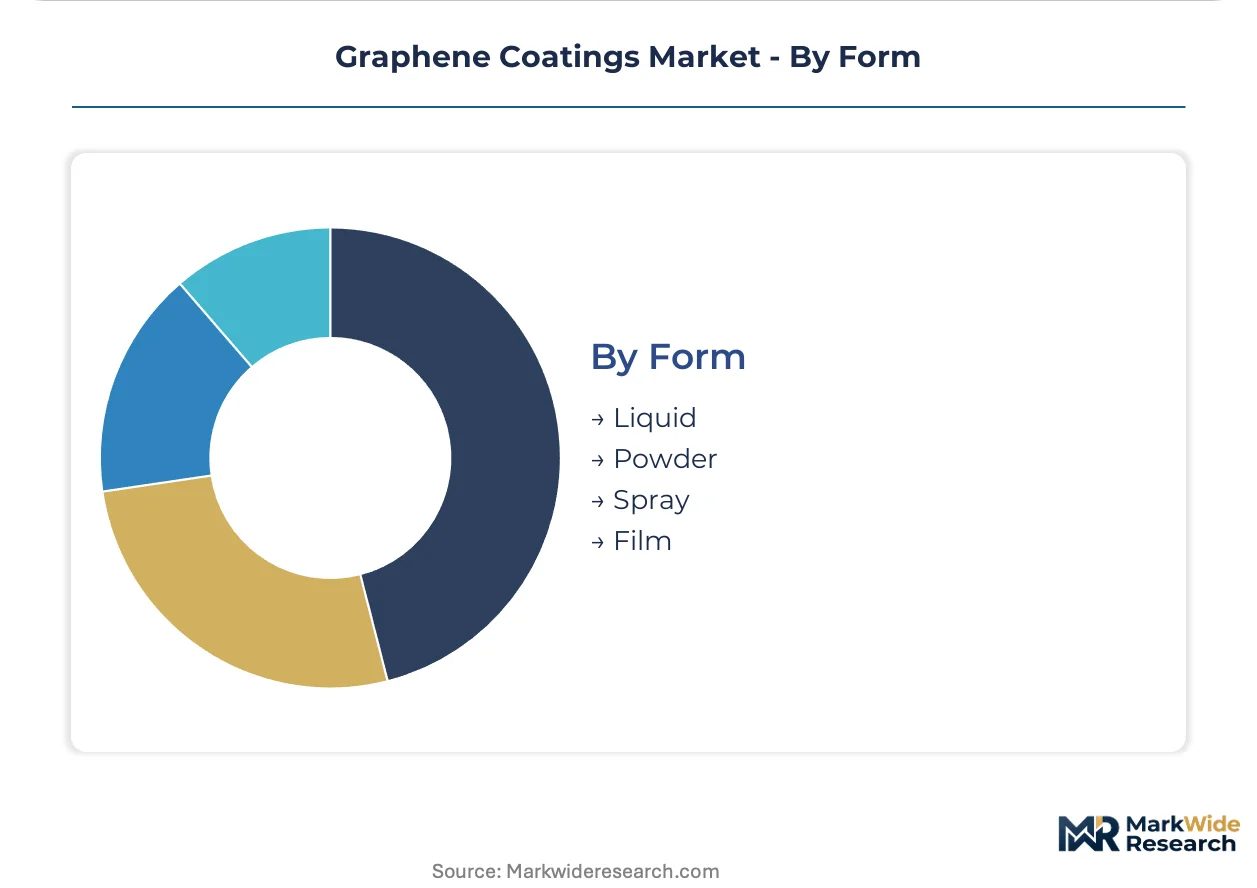
Liquid forms dominate current volume; film commands steepest expansion trajectory on satellite thermal management demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean battery foundries around Ulsan and Gwangju anchor thermal interface coating demand. Chinese electronics assembly hubs in Shenzhen and Suzhou drive conductive formulation procurement. German automotive suppliers in Baden-Württemberg mandate plasma-functionalized flake specifications.
United States
Satellite constellation operators in California and Colorado purchase sub-ohm sheet resistance films for low-earth orbit thermal management. EPA New Chemicals Program scrutiny under TSCA lengthens commercialization timelines for new graphene nanoforms. Houston-area marine infrastructure contractors validate multi-year field performance against zinc-rich primers for offshore platform specifications.
China
Electronics assemblers in the Pearl River Delta consume film-form graphene for printed circuit board shielding applications. GB standards for industrial coatings mandate reformulation away from solvent-based systems under MEE enforcement. Battery manufacturers in the Yangtze River Delta install modular 10-ton-per-year production units adjacent to cell assembly lines.
Germany
Automotive tier-one suppliers in Stuttgart and Munich require 1,000+ cycle thermal validation data before contract award. REACH Annex XV dossier requirements for nanoforms force granular characterization submissions including lateral dimension distributions. Hamburg port facilities absorb compliance costs fastest due to amortization across long marine infrastructure contract durations.
South Korea
Battery foundries in the Seoul Capital Area scale procurement of thermal interface materials for power electronics cooling. MFDS material safety protocols favor suppliers with nano-specific hazard classifications already filed. Busan-Ulsan industrial corridors concentrate distributed manufacturing adoption with direct producer-OEM relationships replacing traditional supply chains.
United Kingdom
Aerospace OEMs in the Midlands and Southwest England consolidate procurement around validated thermal barrier systems. ECHA registration requirements compress qualification timelines for coating suppliers. Haydale Graphene Industries PLC anchors plasma functionalization expertise that reduces batch-to-batch conductivity variability for tier-one contracts.
Graphene Coatings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent scale thresholds. Chemical vapor deposition reactor lines demand $15-25 million per installation, constraining mid-cap scaling. Three archetypes dominate: captive flake producers securing supply certainty, plasma functionalization specialists reducing batch variability, and mining-linked feedstock competitors on Colombian graphite costs. Dominant competitive moves include qualification timeline compression through pre-submitted toxicology dossiers and distributed manufacturing partnerships adjacent to battery assembly lines.
Among North American material developers, Vorbeck Materials Corp exemplifies the functionalization-specialist archetype. NanoXplore Inc. and Haydale Graphene Industries PLC occupy positions on opposite sides of the Atlantic representing captive production and plasma expertise vectors respectively. Directa Plus S.p.A. anchors the mining-linked feedstock tier through its Colombian graphite supply chain positioning.
| Leading Market Players |
|---|
| NanoXplore Inc. |
| Directa Plus S.p.A. |
| Haydale Graphene Industries PLC |
| Vorbeck Materials Corp |
| Universal Matter |
| Grafoid Inc. |
| Graphenea Inc. |
| Global Graphene Group |
| Xiamen Knano Graphene Technology Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Captive flake production by NanoXplore and Haydale anchors supply certainty for tier-one automotive and aerospace contracts, translating directly into pricing power over spot-market dependent competitors. This backward integration into Colombian and Canadian graphite feedstock insulates qualified producers from mining-linked volatility while commanding five-fold multiples over undifferentiated powder additives.
Pricing Analysis
Value-based pricing tied to thermal cycling validation outcomes dominates aerospace procurement, where 1,000+ cycle performance guarantees command premium positioning over commodity flake. Certification tier under REACH Annex XV and MFDS nano-hazard classifications drives price differentiation between pre-registered dossier holders and reformulation laggards. Pricing pressure stems from silicon carbide thermal interface alternatives in power electronics cooling, compressing graphene margins in battery applications. Tier-one automotive electronics buyers exhibit lowest price sensitivity due to plasma functionalization requirements, while marine infrastructure operators amortize compliance costs across long contract durations.
Supply Chain Analysis
Reverse-logistics flows for CVD reactor refurbishment and electrochemical exfoliation unit redeployment concentrate service revenue with equipment OEMs in Germany and the United States. Raw material supply draws from Colombian graphite mining corridors, Chinese spherical graphite processing hubs, and South Korean battery-grade carbon precursor facilities. Single-source vulnerability in high-purity graphite feedstock tightens when Colombian extraction permits face renewal delays. Distribution runs through direct producer-OEM relationships adjacent to Ulsan and Shenzhen battery assembly clusters, bypassing traditional three-tier chemical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graphene coatings represent a materials-transition phase where atomically thin carbon lattices displace zinc-rich primers and silicon carbide thermal interfaces in validated applications.
For Market Incumbents: To counter silicon carbide penetration in power electronics cooling, prioritize REACH Annex XV dossier completion ahead of competitor submissions and secure captive flake supply through upstream graphite mining partnerships in Colombia or Canada. Plasma functionalization R&D investment reduces batch-to-batch conductivity variability, locking tier-one automotive electronics contracts against modular electrochemical exfoliation entrants. For New Entrants and Emerging Players: The mid-tier price gap between CVD aerospace films and undifferentiated powder additives opens white-space in waterborne thermal interface dispersions for Chinese battery manufacturers under GB standards reformulation mandates. Target South Korean foundry clusters with modular 10-ton-per-year production units installed adjacent to cell assembly lines, collapsing qualification timelines through direct MFDS nano-hazard filing partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in plasma functionalization specialists with validated tier-one automotive contracts and pre-submitted REACH dossiers. Long-term viability hinges on regulatory moat durability across the next decade as nano-specific hazard classifications crystallize. Monitor ECHA registration completion rates for graphene nanoforms as inflection indicator for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Feedstock | Captive Colombian or Canadian mining supply insulates against export quota tightening and extraction permit delays. |
| REACH Annex XV Dossier Pre-Submission | Pre-registered producers capture accelerated qualification pathways for battery thermal interface materials in the European Union. |
| Modular Electrochemical Exfoliation Deployment | Distributed 10-ton-per-year units adjacent to South Korean and Chinese battery lines collapse three-tier supply chains. |
| Plasma Functionalization R&D Expansion | Reduced batch-to-batch conductivity variability unlocks tier-one automotive electronics contracts with upfront performance guarantees. |
| Satellite Thermal Management Qualification | Sub-ohm sheet resistance validation opens low-earth orbit constellation supply chains for film-form graphene producers. |
Methodological Framework
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving coating R&D directors at aerospace OEMs, procurement leads at South Korean battery foundries, regulatory affairs managers navigating REACH compliance, and plant engineers at marine infrastructure contractors. Bottom-up volume estimates from modular production unit installations triangulated against top-down market sizing from customs data and industry association reports.
Historical trendline analysis tracked validated thermal cycling data submissions and qualification timeline compression across the projection horizon. Segmentation modeling incorporated coating type, application vertical, form factor, and regional regulatory cluster dimensions. CAGRs derived from slope analysis of adoption curves in battery thermal interface materials and satellite thermal management applications, with cross-validation against graphite feedstock price elasticity and CVD reactor capacity expansion announcements.
Inputs from ECHA dossier databases and MFDS nano-hazard classifications were available through the study window; gaps in proprietary thermal cycling validation datasets from defense satellite programs introduce uncertainty bands around low-earth orbit constellation demand forecasts. Practitioners should monitor Colombian mining permit renewal schedules and EPA New Chemicals Program PMN approval velocities for early signals of supply constraint or regulatory acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Hard Coating Market
Coatings
Antifouling Coatings Market
Coatings
Batters and Coatings Market
Coatings
Topcoat Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Clear Coatings Market
Coatings
Trim Coatings Market