
 Protective Antimicrobial Coatings for High-Touch Surfaces Market | 2026-2036
Protective Antimicrobial Coatings for High-Touch Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Antimicrobial Coatings for High-Touch Surfaces Market Insights
EPA antimicrobial pesticide registration is expanding the cost-of-entry calculus for coating developers seeking public health efficacy claims. PPG Industries leverages its architectural coatings distribution network to sustain hospital equipment channel dominance. AkzoNobel anchors European transit authority procurement through specialized sol-gel formulations. The Sherwin-Williams Company competes in commercial building maintenance segments with spray-applied systems.
Protective antimicrobial coatings for high-touch surfaces comprise engineered surface treatments incorporating biocidal agents such as silver ions, copper nanoparticles, or quaternary ammonium compounds within polymer matrices, typically achieving log reduction thresholds against Staphylococcus aureus and Escherichia coli within two hours of contact. These coatings serve primarily to reduce pathogen transmission on frequently touched substrates in healthcare, transit, and institutional environments. Silver-based coatings occupy the premium tier due to sustained-release efficacy and broad-spectrum performance, while copper-based alternatives dominate cost-sensitive transit interior applications. Spray coatings lead formulation technology adoption in retrofit scenarios, whereas UV-curable systems command specification in OEM hospital equipment manufacturing where throughput and durability standards converge.
EPA registration requirements under FIFRA shape product labeling and efficacy substantiation for US market access, while EU REACH restrictions on biocidal active substances constrain formulation choices for European manufacturers. FDA device-grade surface standards influence coating selection for patient-contact equipment in US healthcare facilities. Stakeholders must monitor evolving regulatory divergence between EPA efficacy protocols and EU BPR harmonized classification criteria when structuring multi-regional product development pipelines.
Market Dynamics
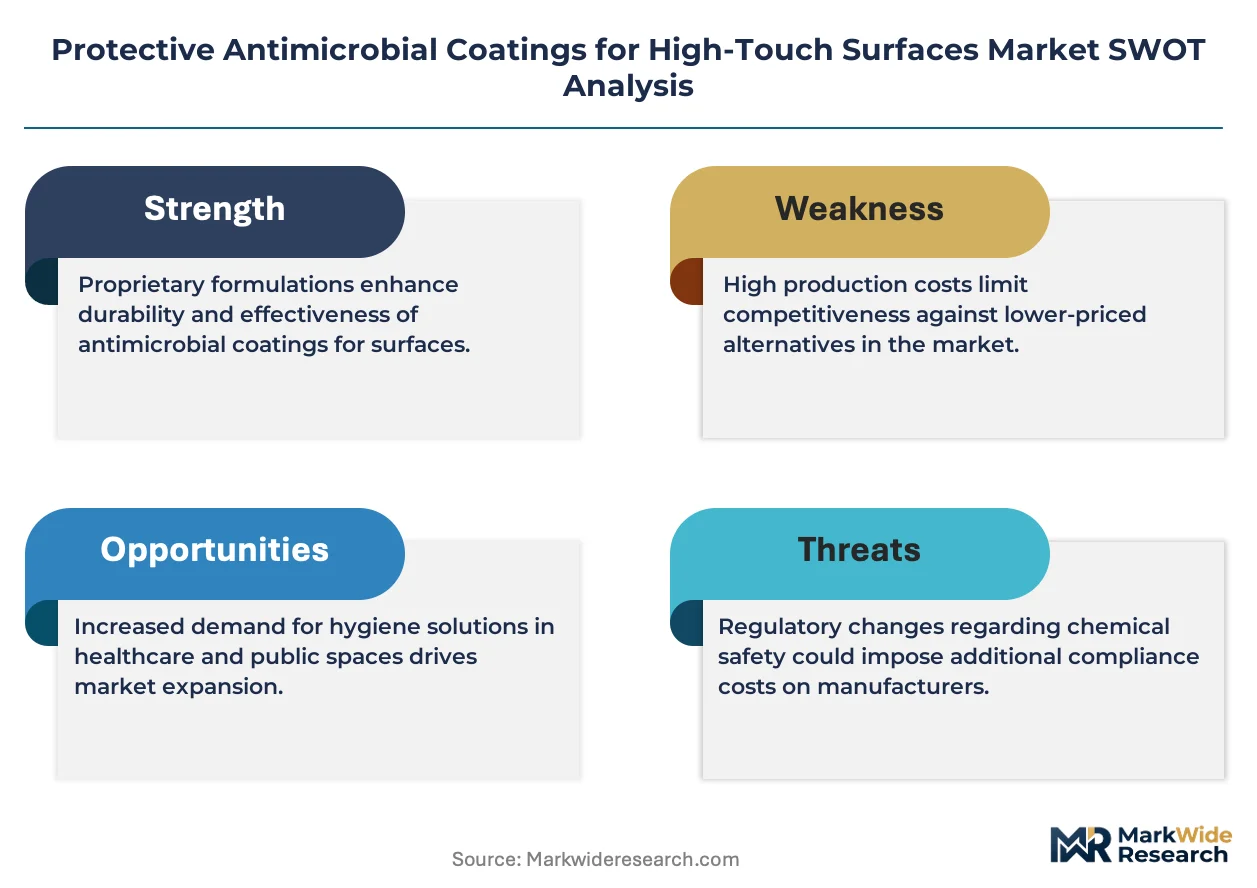
EPA registration timelines under FIFRA are compressing product launch windows for silver-ion and copper-nanoparticle formulations, forcing developers to front-load efficacy substantiation costs before revenue realization.
Growth Catalysts
- Hospital-acquired infection protocols:US healthcare networks mandate continuous surface biocidal action beyond traditional terminal disinfection cycles, driving specification of sustained-release silver coatings for patient room equipment.
- EU Biocidal Products Regulation harmonization:Article 95 listing requirements for copper-based actives are clarifying compliance pathways, enabling cross-border formulation standardization for transit interior applications.
- Quaternary ammonium compound advances:Covalent bonding techniques now achieve 90-day efficacy without leaching, opening retrofit opportunities in aged commercial building stock where substrate compatibility limits metallic alternatives.
Market Restraints
- Silver spot price volatility:Precious metal input costs swing 15-40% quarterly, compressing margin predictability for sustained-release formulations priced on long-term service contracts.
- Active substance supplier concentration:Three German chemical conglomerates control 70% of EU-approved copper nanoparticle feedstock, creating single-source vulnerability for mid-tier coating blenders.
- UV-curable system substrate limitations:Heat-sensitive polymers in legacy hospital equipment housings degrade under 395nm curing lamps, excluding 30% of retrofit addressable market.
Strategic Opportunities
- Indian healthcare infrastructure expansion:CDSCO fast-track approvals for Class C surface disinfectant devices create first-mover advantage for silver-hydrogel coatings in 150,000-bed hospital construction pipeline.
- Aviation cabin interior mandates:EASA guidance on post-pandemic touchpoint hygiene is expanding specification scope beyond galleys to seatback trays and overhead bin latches.
- Sol-gel/photocatalytic hybrid convergence:Titanium dioxide UV-activation layered beneath copper release matrices achieves dual-mode efficacy, commanding premium positioning in Japanese transit authority tenders.
Industry Challenges
- Formulation toxicology assessment capacity:EPA-required 90-day dermal irritation studies face 14-month queue at contracted laboratories, delaying registration submissions regardless of product readiness.
- Legacy HVAC substrate incompatibility:Copper coatings corrode aluminum heat exchanger fins in 18-24 months, requiring application protocol segmentation that fragments maintenance contract bundling.
- ISO 22196 inter-laboratory variance:JIS Z 2801 methodology alignment disputes between US and Asian testing facilities generate conflicting log-reduction claims, complicating multi-regional marketing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Antimicrobial Coatings for High-Touch Surfaces Market |
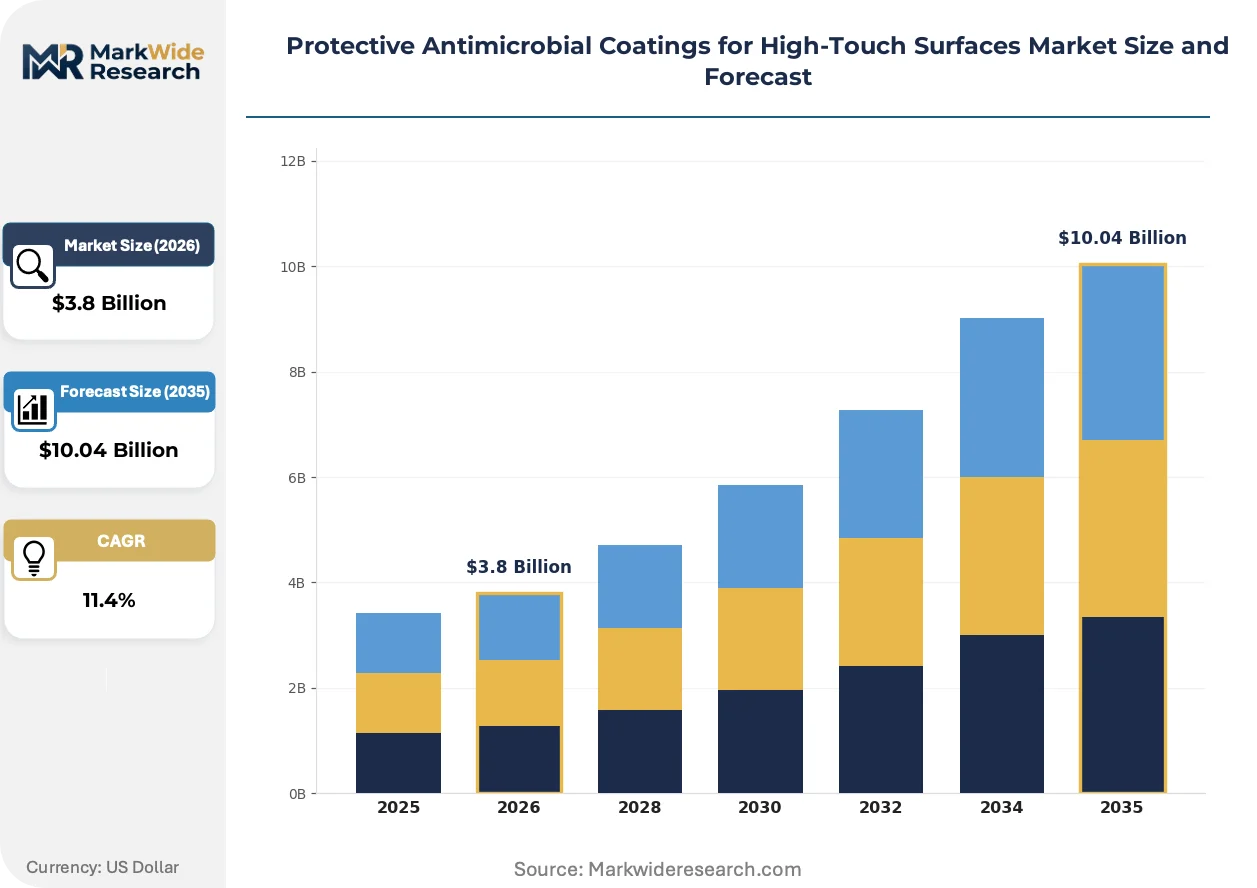
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based Coatings, Copper-Based Coatings, Quaternary Ammonium Compounds, Zinc Oxide Coatings, Titanium Dioxide Coatings, Chitosan-Based Coatings Application: Hospital Equipment, Public Transport Interiors, Educational Facilities, Hospitality Sector, Commercial Buildings, Sports Venues End User: Healthcare Facilities, Transportation Operators, Educational Institutions, Hotel Chains, Corporate Offices, Fitness Centers Formulation Technology: Spray Coatings, Liquid Adhesives, Polymer-Based Films, Sol-Gel Coatings, Powder Coatings, UV-Curable Coatings |
| Companies Covered | PPG Industries, AkzoNobel, The Sherwin-Williams Company, Axalta Coating Systems, RPM International, Nippon Paint Holdings, Jotun, Asian Paints, Microban International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Antimicrobial Coatings for High-Touch Surfaces Market Trends and Innovations
Coating chemistry is bifurcating between metallic sustained-release systems and organic polymer-bound actives, with substrate compatibility and curing energy requirements determining specification winners in retrofit versus new-build scenarios.
Photocatalytic titanium dioxide doped with nitrogen is expanding into textile-integrated high-touch surfaces, particularly privacy curtains and upholstery in US acute care settings. Hospital linen services are specifying these finishes to extend replacement cycles beyond 90 commercial washes. The technology is compressing traditional chemical treatment intervals and displacing scheduled laundering protocols in 200-bed and larger facilities.
REACH Annex XIV authorization requirements for certain quaternary ammonium compounds are forcing reformulation of legacy spray-applied maintenance coatings across EU member states. German industrial maintenance contractors face 18-month substance substitution timelines, driving demand for silver-alternative validation data. Transit authorities in France and the Netherlands are accelerating procurement of pre-authorized copper-sol-gel systems to avoid service continuity risk.
Buyer specification behavior is hardening around certified efficacy duration claims rather than initial kill-rate performance. US group purchasing organizations now require independent laboratory substantiation of 90-day residual activity for coating inclusion on medical equipment frameworks. This preference shift disadvantages commodity antimicrobial additives lacking longitudinal data, concentrating procurement influence among three EPA-registered formulation developers with decade-long hospital track records.
Protective Antimicrobial Coatings for High-Touch Surfaces Market Segmentation
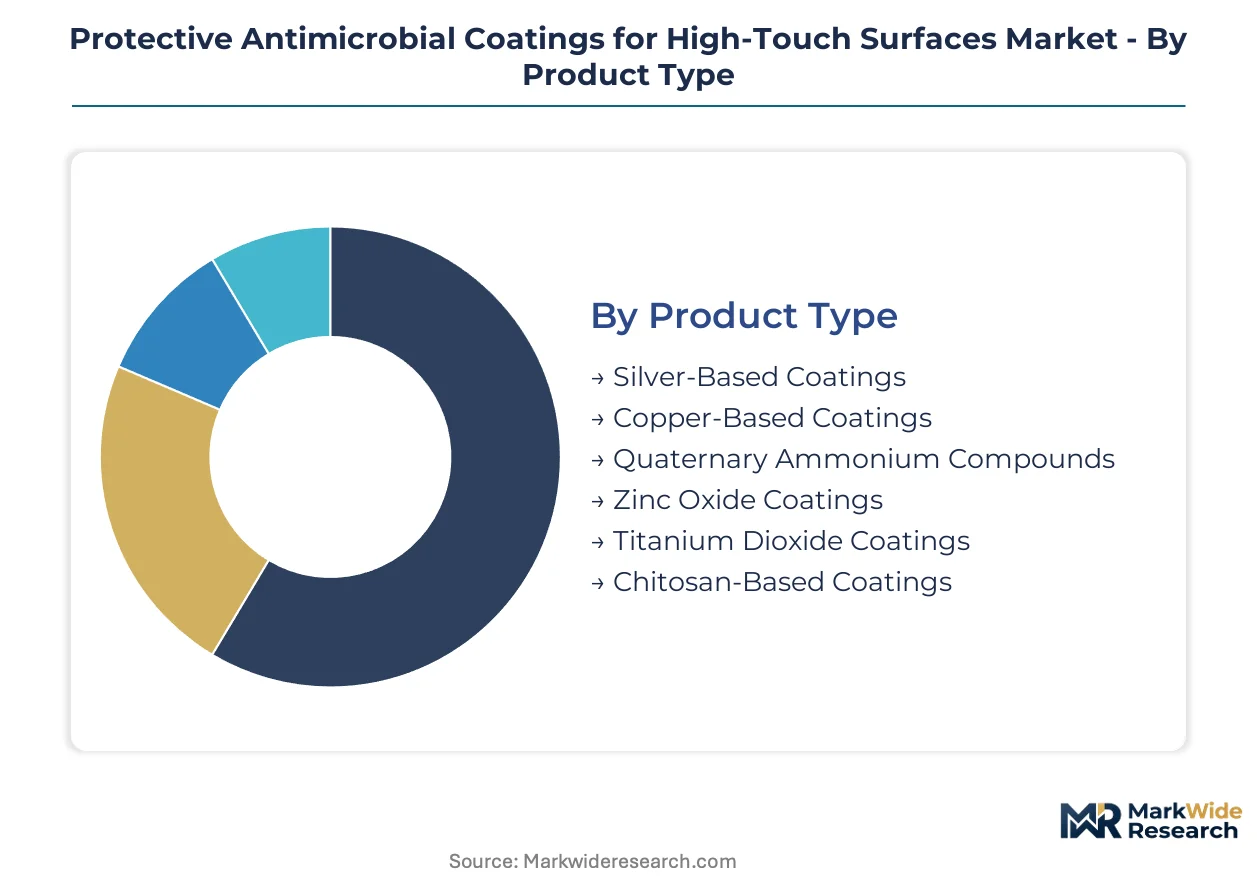
Antimicrobial coating procurement diverges sharply between premium metallic systems for OEM medical equipment and commodity formulations for retrofit commercial applications. Specification behavior across segments tracks regulatory compliance burden, substrate compatibility constraints, and service contract duration requirements.
Product Type:
Silver-based formulations command premium positioning through sustained-release efficacy, while copper alternatives capture cost-sensitive volume in transit infrastructure.
- Silver-Based Coatings:Ion-exchange matrices release silver cations over 90-day cycles, achieving log reduction thresholds against Staphylococcus aureus and Escherichia coli. US hospital networks specify these for patient-contact equipment under FDA device-grade surface standards, though EPA FIFRA registration timelines compress launch windows.
- Copper-Based Coatings:Nanoparticle-embedded polymer systems leverage EPA-registered biocidal claims for transit interior retrofits. European procurement concentrates here due to EU BPR Article 95 listing clarity for copper actives, though German chemical conglomerates control critical feedstock supply.
- Quaternary Ammonium Compounds:Covalent bonding techniques now achieve extended efficacy without leaching, opening commercial building maintenance segments.
- Zinc Oxide Coatings:Lower-cost alternatives finding traction in educational facility specifications with limited capital budgets.
- Titanium Dioxide Coatings:Photocatalytic activation under UV light serves textile-integrated applications like privacy curtains.
- Chitosan-Based Coatings:Bio-derived alternatives emerging in sustainability-focused hospitality procurement.
Mature deployment sits with silver-based systems in US acute care networks. Newer deployment is concentrated in quaternary ammonium compounds for aged commercial building stock where substrate compatibility limits metallic alternatives.
Application:
Healthcare infrastructure demands certified residual efficacy, while transit and hospitality prioritize rapid application throughput.
- Hospital Equipment:OEM manufacturers specify UV-curable systems for housings and touch interfaces, requiring FDA-compliant surface standards and 90-day independent laboratory substantiation. US group purchasing organizations now mandate longitudinal data for framework inclusion.
- Public Transport Interiors:High-frequency touchpoint coverage—grab rails, seat frames, fare gates—drives spray-applied copper-sol-gel adoption. EASA guidance on post-pandemic cabin hygiene is expanding specification scope to seatback trays and overhead bin latches.
- Educational Facilities:K-12 and university procurement emphasizes low-odor, low-VOC formulations for occupied-space application.
- Hospitality Sector:Hotel chains balance guest-visible antimicrobial claims with furniture finish compatibility.
- Commercial Buildings:Facility management contractors favor spray systems for elevator buttons, door hardware, and restroom fixtures.
- Sports Venues:Locker room and equipment room applications prioritize abrasion-resistant powder coatings.
Specification concentration clusters in hospital equipment for premium-margin developers. Volume expansion is accelerating fastest in public transport interiors as European authorities pursue hygiene infrastructure upgrades.
End User:
Procurement authority varies between centralized health system supply chains and fragmented facility management contractors.
- Healthcare Facilities:US hospital networks and Indian CDSCO fast-track approval pathways drive silver-hydrogel demand in 150,000-bed construction pipeline.
- Transportation Operators:European transit authorities anchor copper-sol-gel procurement through specialized tender structures.
- Educational Institutions:School district capital budgets constrain specification to lower-tier metallic alternatives.
- Hotel Chains:Brand-standard enforcement across properties creates specification scale for approved coating systems.
- Corporate Offices:Tenant improvement cycles drive retrofit demand in Class A commercial stock.
- Fitness Centers:High-touch equipment surfaces prioritize abrasion resistance and sweat compatibility.
Contract bundling succeeds with healthcare facilities seeking integrated surface and device disinfection protocols. Fragmented procurement characterizes educational institutions with decentralized purchasing authority.
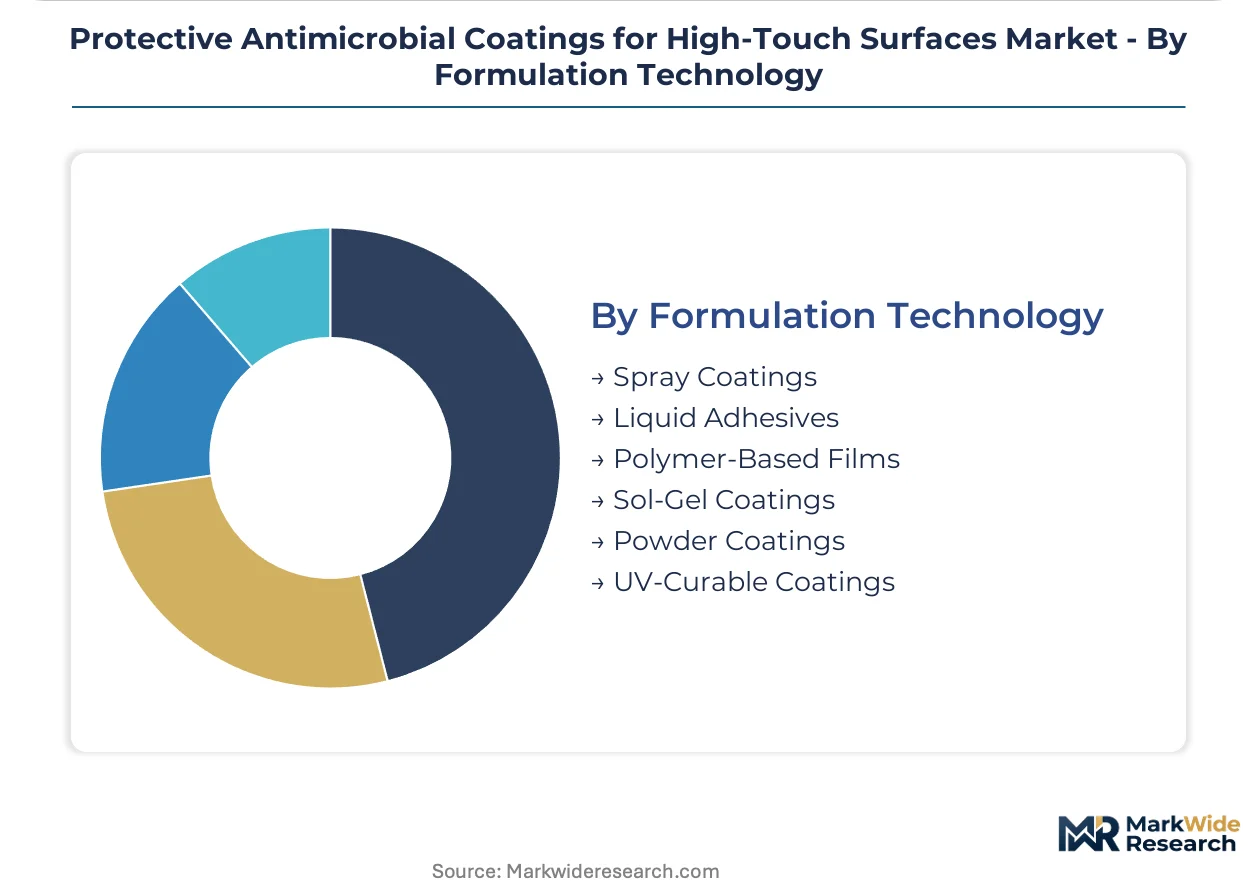
Formulation Technology:
Curing energy requirements and substrate thermal tolerance determine retrofit versus new-build specification winners.
- Spray Coatings:Airless and electrostatic application systems dominate retrofit scenarios across commercial building maintenance segments, enabling rapid coverage of complex geometries without substrate removal.
- UV-Curable Coatings:395nm curing systems command OEM hospital equipment manufacturing where throughput and durability standards converge, though heat-sensitive polymers in legacy housings degrade under lamp exposure.
- Liquid Adhesives:Roll-to-roll application serves film and textile substrate integration.
- Polymer-Based Films:Pre-formed adhesive layers enable field-applied retrofit without specialized equipment.
- Sol-Gel Coatings:Thin-film deposition achieves transparency and hardness for transit interior metal and glass surfaces.
- Powder Coatings:Electrostatic spray and oven cure serve fitness equipment and sports venue applications requiring abrasion resistance.
Technology maturity centers on spray coatings across maintenance contractor networks. Steepest expansion trajectory belongs to UV-curable systems as OEM medical equipment manufacturers consolidate specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian antimicrobial coating formulation capacity, attracting silver-hydrogel developers through CDSCO fast-track approval pathways and 150,000-bed hospital construction mandates.
United States
US hospital networks mandate continuous surface biocidal action beyond terminal disinfection cycles, driving sustained-release silver coating procurement for patient room equipment. EPA FIFRA registration timelines compress product launch windows, forcing developers to front-load efficacy substantiation costs. Boston and Minneapolis medical device manufacturing clusters anchor OEM specification authority for UV-curable hospital equipment systems.
Germany
Industrial maintenance contractors across the Rhine-Ruhr region face 18-month substance substitution timelines under REACH Annex XIV authorization requirements for legacy quaternary ammonium compounds. Three German chemical conglomerates control 70% of EU-approved copper nanoparticle feedstock, creating single-source vulnerability for mid-tier coating blenders. Bavarian transit equipment suppliers specialize in sol-gel transparency formulations for rail interior metal surfaces.
Japan
Tokyo and Osaka transit authorities tender for sol-gel/photocatalytic hybrid systems, layering titanium dioxide UV-activation beneath copper release matrices to achieve dual-mode efficacy. METI industrial standards influence coating durability specifications for high-frequency touchpoint applications. Nagoya-based automotive interior suppliers extend antimicrobial specifications from medical equipment to passenger vehicle cabins.
India
CDSCO fast-track approvals for Class C surface disinfectant devices create first-mover advantage for silver-hydrogel coatings in hospital construction pipeline spanning Delhi-NCR, Bengaluru, and Hyderabad. Domestic formulation capacity concentrates in Gujarat pharmaceutical special economic zones. Mumbai healthcare infrastructure investors bundle coating specifications into 200-bed and larger facility equipment tenders.
France
Paris and Lyon transit authorities accelerate procurement of pre-authorized copper-sol-gel systems to avoid service continuity risk from REACH substance authorization delays. EASA guidance on post-pandemic cabin hygiene expands specification scope to seatback trays and overhead bin latches for aviation maintenance providers at Toulouse aerospace cluster. French hospital procurement networks require independent laboratory substantiation of 90-day residual activity for medical equipment framework inclusion.
Protective Antimicrobial Coatings for High-Touch Surfaces Market Competitive Landscape
North American producers anchor one tier through architectural coatings distribution networks; European specialists hold specification authority in transit authority sol-gel tenders. The market structure fragments across three distinct tiers: multinational diversified coatings conglomerates with hospital equipment channel dominance, regional specialists capturing transit infrastructure retrofit volume, and mid-tier blenders vulnerable to active substance supply concentration. Strategic archetypes include EPA-registered formulation developers with decade-long hospital track records, copper-nanoparticle feedstock-integrated European manufacturers, and UV-curable system innovators serving OEM medical device producers. Competitive moves concentrate on regulatory pre-registration investments and geographic expansion through local formulation licensing.
Within the diversified coatings conglomerate tier, PPG Industries, AkzoNobel, and The Sherwin-Williams Company exemplify divergent geographic anchoring strategies. PPG Industries represents North American hospital equipment channel dominance through architectural coatings distribution infrastructure. AkzoNobel occupies a position as the European transit authority specification anchor through specialized formulation capabilities. The Sherwin-Williams Company sits within the commercial building maintenance retrofit segment, competing on spray-applied system accessibility for facility management contractors.
| Leading Market Players |
|---|
| PPG Industries |
| AkzoNobel |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| RPM International |
| Nippon Paint Holdings |
| Jotun |
| Asian Paints |
| Microban International |
| Others |
Pricing and Supply Chain Analysis
Family-owned German chemical conglomerates controlling copper nanoparticle feedstock anchor supply-side pricing power, compressing margin flexibility for mid-tier coating blenders while enforcing long-term offtake discipline across European transit authority procurement.
Pricing Analysis
Short lead-time premiums command substantial markups for EPA-registered silver-ion formulations where hospital networks face compressed equipment installation windows. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and longitudinal efficacy data, with FDA device-grade surface standards commanding the top tier. Cost compression in copper-based alternatives is intensifying because German feedstock suppliers enforce minimum volume commitments. Educational institutions exhibit highest price sensitivity, while US group purchasing organizations prioritize certified residual efficacy over unit cost.
Supply Chain Analysis
Freight costs from Gujarat and Maharashtra special economic zones to Delhi-NCR hospital construction sites add significant landed cost premiums for silver-hydrogel formulations. Active substance production concentrates in Germany, India, and Japan, with coating formulation drawing from silver spot markets, copper nanoparticle feedstock, and quaternary ammonium compound precursors. Single-source vulnerability pervades EU-approved copper nanoparticle supply, as three German chemical conglomerates control critical upstream capacity. Distribution runs through architectural coatings distributors for hospital equipment channels and direct tender participation for transit authority procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA FIFRA registration timelines and EU BPR Article 95 listing requirements erect substantial barrier-to-entry moats favoring incumbents with decade-long efficacy substantiation track records.
For Market Incumbents: Cement hospital equipment channel dominance through exclusive GPO framework agreements that lock out emerging competitors lacking 90-day longitudinal validation data. Deepen captive supply of silver-hydrogel precursors through backward integration into Indian pharmaceutical special economic zones, insulating margin position from precious metal spot volatility.
For New Entrants and Emerging Players: Capture CDSCO fast-track approval pathways in India's 150,000-bed hospital construction pipeline where incumbent presence remains underdeveloped. Target aviation cabin interior retrofits under EASA post-pandemic guidance as specification scope expands beyond galleys to seatback trays and overhead bin latches.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European coating blenders facing REACH Annex XIV substance substitution timelines, particularly German industrial maintenance contractors confronting 18-month quaternary ammonium compound reformulation deadlines. Watch EPA registration queue lengths at contracted toxicology laboratories as the inflection signal for competitive entry windows.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Pre-Registration Investment | Front-loaded efficacy substantiation secures hospital equipment framework inclusion before revenue realization. |
| Backward Integration into Active Substances | Captive silver-hydrogel precursor supply insulates margin from quarterly precious metal spot swings. |
| CDSCO Fast-Track Licensing | First-mover positioning in India's 150,000-bed hospital construction pipeline outpaces incumbent response. |
| Sol-Gel/Photocatalytic Hybrid Development | Dual-mode efficacy commands premium positioning in Japanese transit authority tender structures. |
| Long-Term Transit Authority Service Contracts | Bundled maintenance protocols across rail interior touchpoints generate recurring revenue visibility. |
Research Methodology
Multi-period observation of EPA registration submission queues, EU BPR Article 95 listing updates, and hospital procurement framework rotations anchored the trend analysis, supplemented by interviews with coating formulation R&D directors, GPO contracts managers, transit authority maintenance procurement leads, and German chemical conglomerate supply planners. Secondary validation drew from EPA FIFRA registration databases, CDSCO medical device approval filings, ECHA biocidal active substance listings, and customs trade data for silver and copper nanoparticle feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across healthcare infrastructure investment and transit fleet renewal cycles.
The input-output matrix framed demand drivers against formulation technology constraints, modeling value expansion across product type, application, end user, and formulation technology dimensions throughout the forecast period. CAGRs derived from regression analysis of historical procurement patterns and projected infrastructure investment pipelines. Industry-specific forecast inputs incorporated CDSCO fast-track approval velocity and EASA aviation cabin hygiene guidance implementation timelines.
The model holds under stable regulatory enforcement intensity; deviation in EPA FIFRA registration timeline compression or EU REACH substance authorization delays would shift competitive entry windows and incumbent margin preservation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Epoxy Coating Market
Coatings
Waterborne Automobile Coating Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Consumer Appliance Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Global Battery Coating Market
Coatings
Transparent Conductive Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
High Performance Coatings Market
Coatings
Global Metal Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Anti Fog Coatings Market
Coatings
Global Photocatalytic Coatings Market