
 Mexico General Surgical Devices Market | 2026-2036
Mexico General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico General Surgical Devices Market Foresight
After-sales maintenance and calibration services for electrosurgical generators is realigning how device vendors capture lifetime value beyond the initial instrument sale. Medtronic leverages its field service network to sustain recurring revenue from hospital clients across central Mexico. Johnson & Johnson anchors its position through specialized training programs for laparoscopic techniques that bind surgeons to its instrument ecosystems.
General surgical devices encompass hand-held instruments, powered equipment, and consumables manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, designed for tissue manipulation, dissection, and wound closure during operative procedures. Minimally invasive technology leads procedure volume growth as surgeons transition from open techniques, while robotic surgery commands premium positioning despite limited installed base expansion. Electrosurgery occupies the largest margin pool through disposable electrode tips and generator leasing arrangements that lock in recurring procurement cycles.
COFEPRIS maintains mandatory registration for all imported medical devices, with updated Good Manufacturing Practice audits now required for foreign manufacturers seeking market authorization. NOM standards for electrical safety and biocompatibility testing shape product design requirements for devices entering Mexican territory. Stakeholders must monitor pending alignment between COFEPRIS procedures and FDA recognition agreements that could streamline dual-market certification pathways.
Market Dynamics
COFEPRIS registration complexity is fragmenting import pathways while ambulatory surgical centers absorb procedure volume previously reserved for inpatient facilities, compressing capital equipment replacement cycles across Mexico's hospital networks.
Growth Catalysts
- NOM Electrical Safety Standards:Updated biocompatibility testing protocols under Mexican mandatory standards are accelerating domestic manufacturing investments as foreign suppliers seek local production partnerships to bypass extended import timelines.
- Monterrey Private Hospital Expansion:Surgical service line diversification in Nuevo León's metropolitan cluster is generating concentrated demand for laparoscopic instrument suites and powered dissection systems.
- Same-Day Procedure Capacity:Ambulatory surgical centers in Mexico City are retrofitting operating suites for minimally invasive techniques, pulling disposable electrode consumption into outpatient settings.
Market Restraints
- Titanium Alloy Input Volatility:Medical-grade titanium sourcing concentrates through a limited supplier base, exposing instrument manufacturers to raw material price swings that compress margin pools on reusable forceps and retractors.
- COFEPRIS-FDA Recognition Gap:Pending alignment delays between Mexican and US regulatory pathways force dual-track certification investments, extending time-to-market for electrosurgical generators and advanced energy platforms.
- Open Surgery Technique Persistence:Training pipeline limitations in public hospital systems sustain dependence on conventional instrumentation, slowing minimally invasive adoption curves in secondary cities.
Strategic Opportunities
- Guadalajara Medical Device Cluster:Jalisco's emerging manufacturing corridor offers tariff-advantaged production bases for serving domestic demand and re-export to Central American markets.
- Leasing-Based Generator Deployment:Capital-constrained regional hospitals are receptive to equipment-as-a-service models for electrosurgical platforms, converting upfront capex into predictable operational expenditure streams.
- COFEPRIS-ANVISA Harmonization:Prospective regulatory convergence with Brazil's ANVISA framework could unlock streamlined dual-market access for sterilized disposable instrument kits.
Industry Challenges
- Laparoscopic Specialist Shortage:Mexico's surgical residency programs produce insufficient minimally invasive-trained practitioners to match ambulatory center expansion timelines, constraining procedure throughput.
- Legacy Electrosurgical Integration:Hospital IT infrastructure fragmentation complicates connectivity between new generator platforms and existing patient monitoring systems, delaying operating room commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico General Surgical Devices Market |
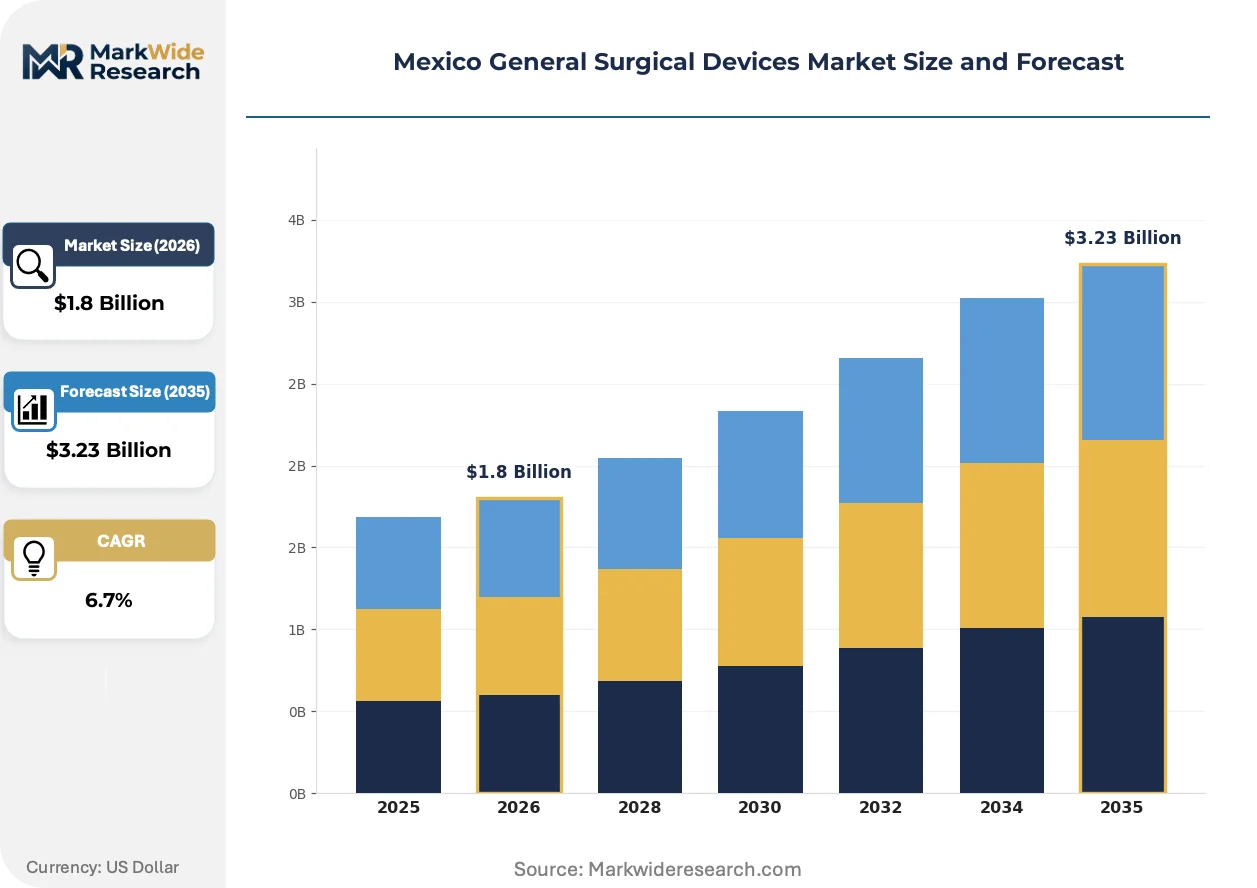
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sutures, Forceps, Scissors, Clamps End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Labs Technology: Minimally Invasive, Robotic Surgery, Electrosurgery, Open Surgery Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Gastrointestinal Surgery |
| Companies Covered | Boston Scientific, Conmed, Johnson & Johnson, Teleflex, Olympus Corp., Medtronic, B. Braun, Intuitive Surgical, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico General Surgical Devices Market Shifts & Advancements
Disposable instrument kits are compressing sterilization infrastructure requirements while software-enabled energy platforms rewrite service revenue models. Three forces are actively restructuring competitive positioning.
Single-use polymer-composite trocars are replacing reusable stainless steel access ports in high-volume laparoscopic procedures. Ambulatory surgical centers in Mexico City and Monterrey are standardizing on these platforms to eliminate reprocessing bottlenecks. The technology is modularizing procurement decisions, allowing facilities to unbundle capital equipment from consumable supply chains.
COFEPRIS updated its Good Manufacturing Practice audit protocols for foreign manufacturers, mandating on-site inspections prior to market authorization. This regulatory tightening is diverting import volume toward established multinationals with compliant quality systems. Domestic distributors serving regional hospital networks face margin compression as direct manufacturer relationships become prerequisites for registration maintenance.
After-sales service contracts are unbundling from equipment sales as independent technical service providers enter the electrosurgical generator maintenance market. Third-party calibration laboratories in Querétaro and Puebla are capturing recurring revenue previously retained by original equipment manufacturers. This channel fragmentation is most visible among mid-tier private hospital groups seeking cost containment on multi-vendor instrument fleets.
Mexico General Surgical Devices Market Segmentation
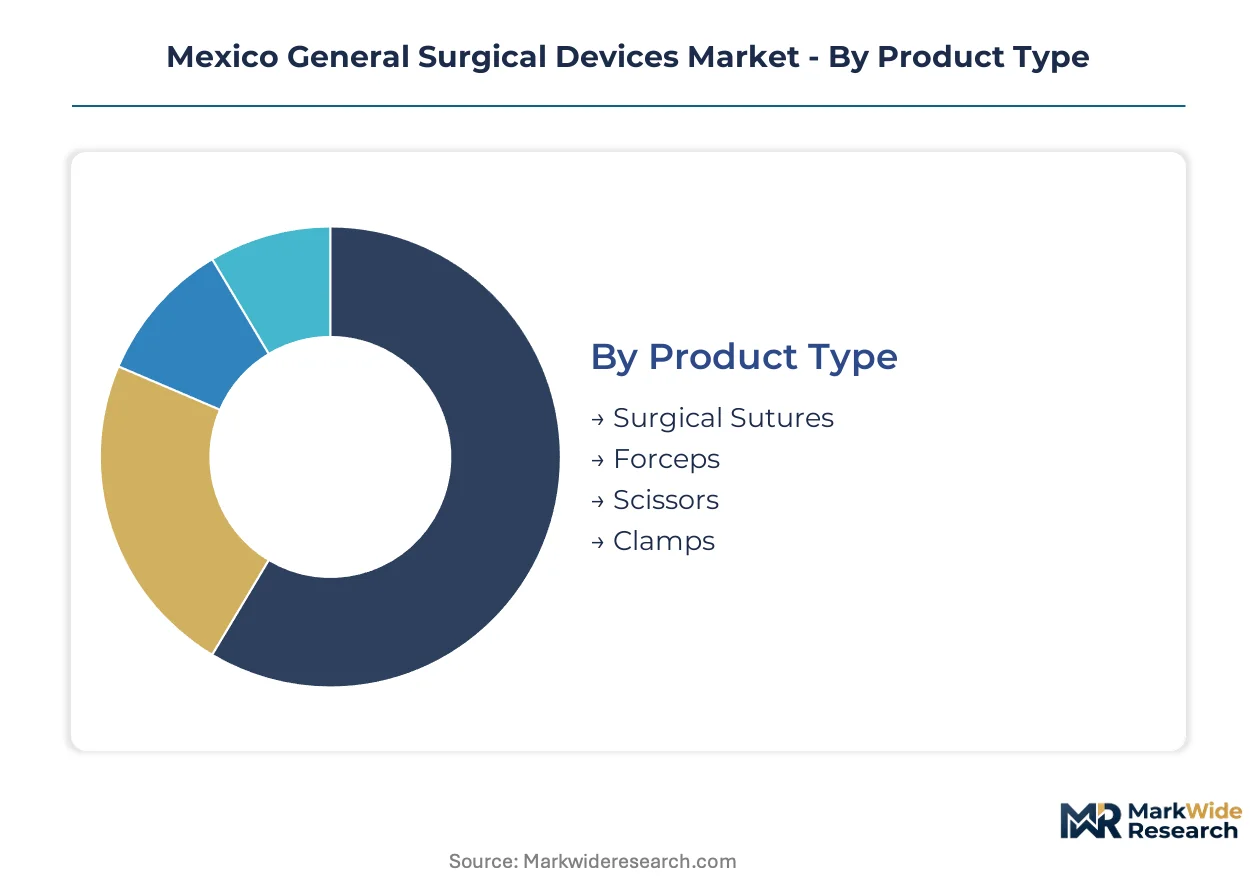
Segmentation reveals how procurement priorities diverge between high-volume consumable purchasers and capital-intensive technology adopters across Mexico's surgical landscape. Understanding these splits enables vendors to align pricing architectures with facility reimbursement models and procedure throughput requirements.
Product Type:
Volume tiers separate commodity consumables from precision instruments with extended depreciation cycles and service attachment potential.
- Surgical Sutures:Absorbable and non-absorbable polymer and natural fiber wound closure products dominate procurement spend through high procedure attachment rates. Demand concentrates in Mexico City tertiary hospitals where cardiac and orthopedic caseloads drive premium braided synthetic uptake. Suture procurement locks facilities into vendor ecosystems through surgeon preference card standardization.
- Forceps:Reusable stainless steel and titanium alloy tissue grasping instruments span dissecting, hemostatic, and specialized configurations. Monterrey private hospital networks are upgrading to ergonomic polymer-grip designs that reduce surgeon fatigue during lengthy laparoscopic procedures. Forceps replacement cycles compress as ambulatory centers shift toward single-use alternatives.
- Scissors:Cutting instruments with tungsten carbide edges or supercut micro-serrated blades serve dissection and suture cutting functions.
- Clamps:Hemostatic and atraumatic occlusion devices span bulldog, Kelly, and Satinsky configurations for vascular and tissue control.
Today's leader: Surgical Sutures. Tomorrow's challenger: Forceps.
End User:
Customer archetypes range from integrated health systems with centralized procurement to independent facilities with decentralized decision authority.
- Hospitals:Tertiary and secondary acute care facilities with dedicated surgical departments and sterilization infrastructure. Mexico City and Monterrey hospital networks are consolidating vendor contracts to leverage volume discounts on electrosurgical generator leases. Hospital procurement committees prioritize total cost-of-ownership metrics over upfront instrument pricing.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited sterilization capacity driving disposable instrument adoption. Guadalajara and Puebla ASCs are retrofitting suites for laparoscopic techniques, pulling single-use trocar and electrode consumption into outpatient settings. These facilities favor procurement flexibility over long-term capital commitments.
- Clinics:Primary and specialty care facilities with limited operative capacity performing minor procedures.
- Research Labs:Academic and preclinical testing facilities sourcing instruments for experimental surgery and device validation.
Procurement gravity centers on Hospitals. ASCs are climbing the fastest.
Technology:
Maturity stages separate established open techniques from platforms requiring specialized training infrastructure and capital deployment.
- Electrosurgery:Radiofrequency energy platforms with disposable electrode tips and grounding pads serving cutting and coagulation functions. The technology commands the largest margin pool through generator leasing arrangements that lock in recurring electrode procurement cycles. Monterrey private hospitals are standardizing on vessel-sealing advanced energy platforms for general surgery service lines.
- Minimally Invasive:Laparoscopic and endoscopic instrumentation enabling reduced-incision procedures with faster recovery profiles. Mexico City ASCs are absorbing volume previously routed to inpatient facilities, compressing capital equipment replacement cycles across hospital networks. Technique adoption depends on specialist surgeon availability and training pipeline capacity.
- Robotic Surgery:Computer-assisted platforms with articulated instrument arms and 3D visualization systems.
- Open Surgery:Conventional incision-based techniques relying on manual instrumentation without energy platform integration.
Margin concentration sits with Electrosurgery. Minimally Invasive holds the steepest expansion trajectory.
Application:
Procedure complexity drives instrument specification requirements from basic tissue manipulation to specialized anatomical access systems.
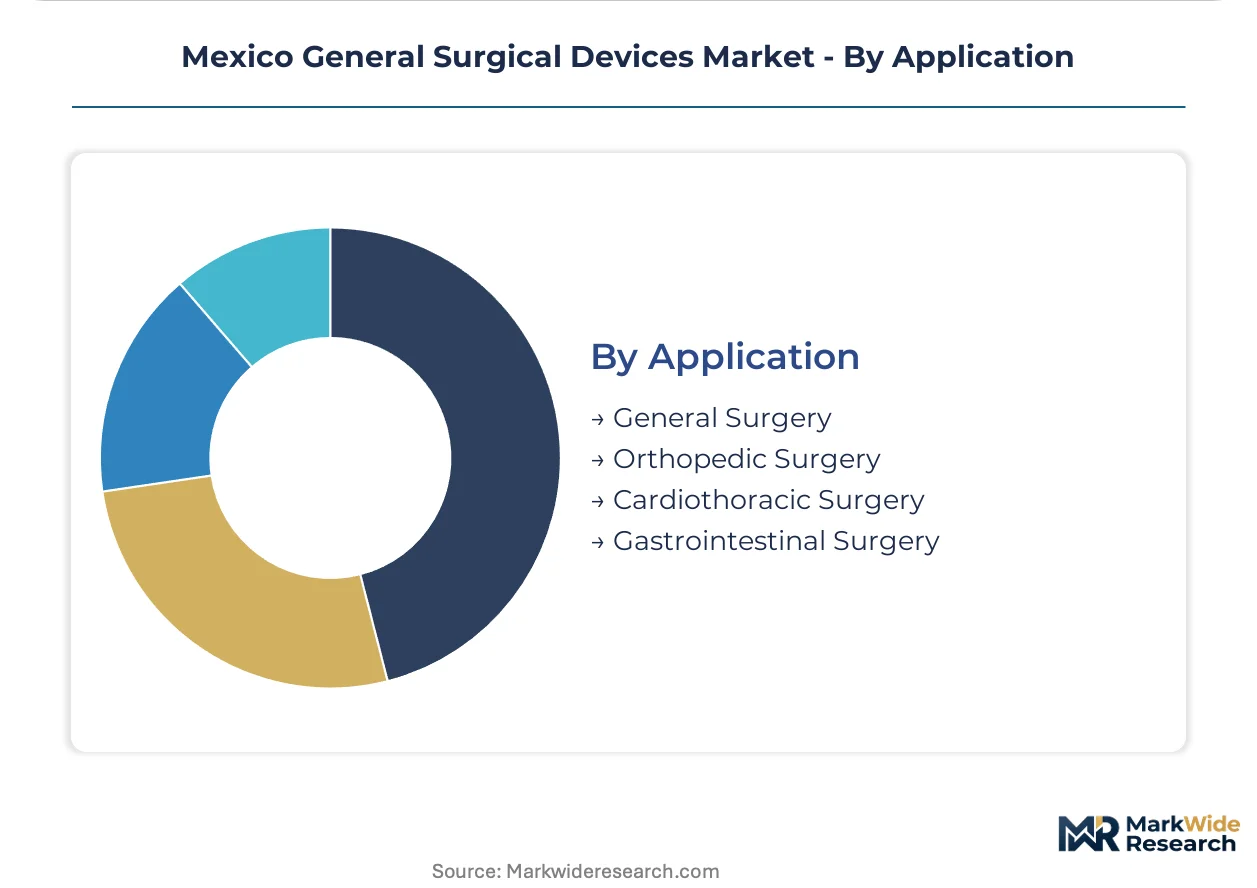
- General Surgery:Abdominal wall, hernia, and soft tissue procedures spanning open and laparoscopic approaches. Demand concentrates in high-volume cholecystectomy and appendectomy cases where disposable trocar standardization is accelerating across Mexico City ambulatory networks. Procedure volume sustains consumable procurement at scale.
- Orthopedic Surgery:Bone and joint procedures requiring specialized retractors, saws, and fixation instrumentation. Nuevo León private hospitals are expanding joint replacement service lines, driving demand for powered dissection systems and bone cement delivery devices. Surgeon training programs in this specialty are expanding faster than minimally invasive pipelines.
- Cardiothoracic Surgery:Cardiac and pulmonary procedures requiring precision vascular clamps and sternal fixation systems.
- Gastrointestinal Surgery:Colorectal and upper GI procedures with stapling and anastomosis device requirements.
Volume leadership belongs to General Surgery. Orthopedic Surgery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Mexico City concentrates surgical device procurement through tertiary hospital networks, Monterrey's private healthcare expansion generates comparable demand density with faster ambulatory center deployment timelines.
Mexico City Metro
Hospital networks in the capital absorb the highest volume of electrosurgical generators and laparoscopic instrument suites. COFEPRIS maintains its headquarters here, streamlining registration pathways for importers with established local subsidiaries. The Santa Fe and Interlomas medical corridors host concentrated private hospital construction driving capital equipment procurement.
Nuevo León
Monterrey's private hospital groups are diversifying into orthopedic and cardiovascular service lines requiring specialized powered dissection systems. State-level health infrastructure bonds are financing surgical suite modernization across metropolitan facilities. The Monterrey Medical Cluster anchors distribution networks serving northern Mexico and cross-border re-export to Texas markets.
Jalisco
Guadalajara's emerging medical device manufacturing corridor attracts foreign suppliers seeking tariff-advantaged production bases. The state's pharmaceutical and device manufacturing heritage provides technical workforce pools for sterile instrument assembly operations. Zapopan and El Salto industrial parks host contract manufacturers serving domestic demand and Central American export markets.
Bajío Region
Querétaro and León are developing independent technical service capabilities for electrosurgical generator calibration and maintenance. Regional hospital groups here favor leasing-based equipment deployment to convert capital expenditure into operational budgets. The automotive manufacturing skills base transfers precision into medical instrument metalworking subcontracting.
Northern Border States
Tijuana and Ciudad Juárez maquiladora infrastructure supports sterilized disposable kit assembly for US market re-export under harmonized tariff schedules. Cross-border supply chain integration allows rapid replenishment of consumable inventories for Chihuahua and Sonora hospital networks. Baja California's medical device manufacturing incentives compete with Jalisco for foreign direct investment in surgical instrument production.
Mexico General Surgical Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational instrument vendors commanding premium positioning in capital equipment while domestic distributors capture consumable volume through price-competitive positioning. The market structure tiers into three archetypes: integrated health system suppliers with full portfolio coverage, specialized energy platform vendors with recurring revenue service models, and regional distributors with fragmented multi-brand representation. Consolidation pressure is accelerating through hospital network procurement centralization and COFEPRIS registration barriers favoring established quality systems.
Among the integrated multinational tier, Johnson & Johnson and Medtronic exemplify archetypes built on surgeon training ecosystems and field service networks that embed long-term procurement relationships. Boston Scientific occupies a position representing specialized interventional and minimally invasive platform vendors with concentrated therapeutic area focus. These entities anchor competitive dynamics through scale advantages in registration maintenance, after-sales service density, and clinical education infrastructure that binds facility procurement committees to their instrument ecosystems.
| Leading Market Players |
|---|
| Boston Scientific |
| Conmed |
| Johnson & Johnson |
| Teleflex |
| Olympus Corp. |
| Medtronic |
| B. Braun |
| Intuitive Surgical |
| Stryker |
| Others |
Supply & Pricing Matrix
Captive sourcing of medical-grade titanium from US and Japanese suppliers anchors both the supply position and pricing power of premium instrument manufacturers serving Mexico's hospital networks. This upstream control insulates established vendors from raw material volatility while compressing margin pools for distributors lacking direct mill relationships.
Pricing Analysis
Capacity additions in Jalisco's manufacturing corridor are reshaping price floors for standard-grade disposable instruments as domestic assembly operations undercut import landed costs. Three-tier pricing structure across premium, standard, and economy levels separates COFEPRIS-registered multinationals from regional distributors and unbranded alternatives. Price differentiation hinges on certification tier and after-sales service bundling. Margins are tightening due to ambulatory surgical center procurement centralization. Public hospital systems exhibit highest price sensitivity; Monterrey private hospital groups prioritize total cost-of-ownership over upfront unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Mexico's hospital procurement committees mandate multi-supplier qualification for electrosurgical generators and laparoscopic suites, fragmenting vendor concentration. Manufacturing concentrates in the United States, Germany, and China for capital equipment, while sterile disposable assembly draws from Jalisco, Baja California, and Costa Rica maquiladora operations. Raw material dependencies center on medical-grade stainless steel, titanium alloys, and polymer composites. Single-source vulnerability persists for advanced energy platform components. Distribution runs through Monterrey Medical Cluster hubs serving northern territories and Mexico City-based GPO contracts dominating central regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the demand-shift toward disposable instrument kits with validated sterilization documentation. Premium specifications now dominate procurement scoring at ambulatory surgical centers.
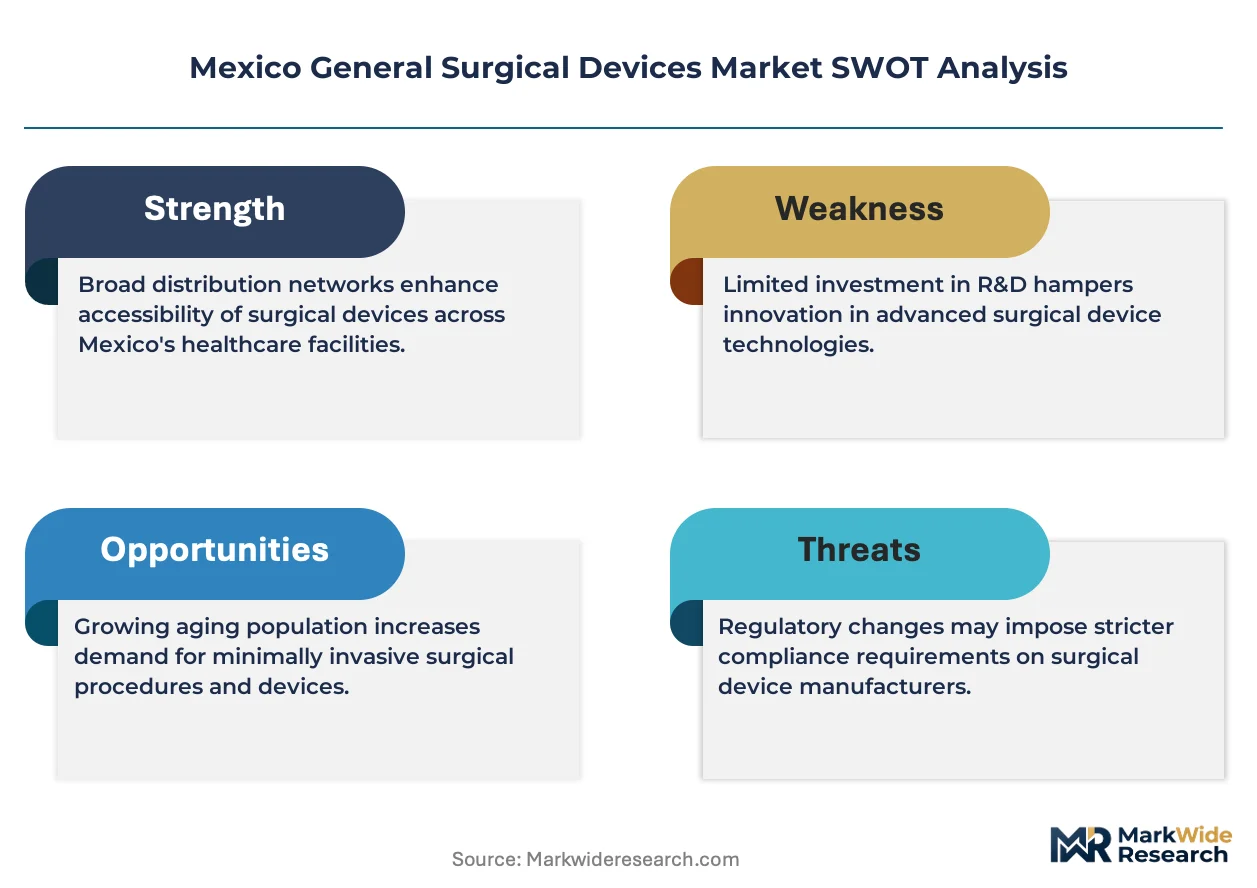
For Market Incumbents: Lock in surgeon training ecosystems as defensive moats against emerging platform competitors. Deepen backward integration into titanium alloy sourcing to defend margin position from raw material volatility. Prioritize COFEPRIS registration maintenance investments to sustain import pathway control against regional distributor encroachment. For New Entrants and Emerging Players: Enter via Guadalajara contract manufacturing partnerships to exploit tariff-advantaged production bases for Central American re-export. Target Bajío region hospital groups with leasing-based generator deployment models that convert capital expenditure into operational budgets. Pursue independent technical service certification in Querétaro to capture aftermarket revenue from multi-vendor instrument fleets. For Investors and Strategic Acquirers: Roll-up economics work for specialized electrosurgical service providers because hospital IT infrastructure fragmentation creates persistent calibration and maintenance demand. Five-to-ten year viability rests on consolidation of third-party technical service networks into platform-scale operations. Watch COFEPRIS-FDA recognition agreement progression as inflection indicator for dual-market certification pathway value.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pathway | Streamlined market authorization unlocks procurement access at Mexico City tertiary networks. |
| Hospital System Partnership | Surgeon training programs bind preference cards to specific instrument ecosystems. |
| Leasing-Based Deployment Model | Equipment-as-a-service converts upfront capex into predictable operational expenditure streams. |
| Software Companion Development | Generator-platform connectivity addresses IT infrastructure fragmentation delaying OR commissioning. |
| Reimbursement Strategy | Same-day procedure coding alignment accelerates ambulatory surgical center capital investment cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned biomedical engineers at Mexico City hospital networks, GPO contracts managers, COFEPRIS regulatory consultants, and ambulatory surgical center operations directors. Secondary validation drew from COFEPRIS registration databases, hospital procurement records, NOM standards documentation, and customs import manifests. Bottom-up facility-level demand estimation triangulated against top-down manufacturer shipment data.
Historical reference periods anchored the projection framework to procedure volume trends and capital replacement cycles observed across the analysis window. Segmentation modeling incorporated product type, end user facility tier, technology maturity stage, and application-specific procedure complexity. CAGRs were derived from least-squares fitting of normalized growth trajectories. Forecast inputs included laparoscopic specialist pipeline capacity and ambulatory center construction permits.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around quarterly demand estimates. Deviation in COFEPRIS-FDA recognition timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Osmotic Pumps Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Heart Closure Devices Market