
 Urology EMR Software Market | 2026-2036
Urology EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Urology EMR Software Market Insights
Modular platform bundling is realigning how urology practices evaluate EMR procurement, shifting from standalone systems toward integrated suites that combine scheduling, billing, and clinical documentation. NextGen Healthcare leverages its ambulatory care specialization to anchor multi-site urology deployments across the United States. ModMed Urology differentiates through specialty-specific templates for cystoscopy and prostate procedures. AdvancedMD competes on pricing flexibility for independent practices seeking subscription-based alternatives.
Urology EMR software constitutes digital health record systems engineered for genitourinary care workflows, incorporating ICD-10 coding for nephrology-specific procedures, image annotation for cystoscopic findings, and discrete data capture for prostate-specific antigen tracking. Cloud-based deployment leads product type adoption as practices prioritize remote accessibility and reduced IT overhead, while on-premise installations retain share among hospital systems with legacy infrastructure investments. Single-tenant and multi-tenant SaaS models dominate deployment architecture, with API integration emerging as the fastest-growing connectivity method for linking diagnostic imaging and laboratory systems.
FDA 21 CFR Part 820 quality system regulations govern software-as-medical-device classifications for diagnostic modules, while HIPAA security rules mandate encryption standards for protected health information transmission. ONC certification requirements under the 21st Century Cures Act shape interoperability capabilities that vendors must embed for federal reimbursement eligibility. Stakeholders should monitor evolving state-level privacy laws and CMS quality reporting mandates that will determine which platform architectures sustain competitive viability.
Market Dynamics
Cloud migration is compressing deployment cycles for urology practices while HIPAA security rule updates and ONC certification mandates force simultaneous compliance investments, creating a dual-pressure environment where platform consolidation accelerates.
Growth Catalysts
- ONC Certification Requirements:Federal reimbursement eligibility under the 21st Century Cures Act compels practices to upgrade interoperability capabilities, expanding addressable market for certified vendors.
- Independent Practice Consolidation:Physician practice management companies are acquiring urology groups and mandating standardized EMR platforms across portfolios, creating bulk procurement opportunities.
- API Integration Architecture:Discrete data capture for prostate-specific antigen tracking and cystoscopic image annotation now flows through open APIs, reducing custom integration costs.
Market Restraints
- Legacy Infrastructure Lock-In:Hospital systems with sunk capital in on-premise server farms face high switching costs that delay SaaS adoption despite superior cloud economics.
- Specialty-Specific Customization Costs:Urology workflows require procedure templates for transurethral resection and nephrostomy placement that generic EMR platforms cannot replicate without expensive configuration.
- Interstate Privacy Law Fragmentation:California's CCPA and emerging state-level health data statutes create compliance complexity that national platform deployments must navigate.
Strategic Opportunities
- Remote Patient Monitoring Integration:Post-operative urology care for prostatectomy and nephrolithiasis patients is shifting to home-based monitoring, creating demand for EMR modules that ingest wearable and home device data.
- Artificial Intelligence-Assisted Diagnostics:Machine learning algorithms for cystoscopic image classification are converging with core EMR platforms, enabling point-of-care decision support.
- Texas and Florida Practice Expansion:Population migration to Sun Belt states is concentrating urology practice formation in these markets, favoring vendors with regional implementation capabilities.
Industry Challenges
- Urology Informatics Specialist Shortage:Practices lack personnel trained in both clinical workflows and health IT system administration, forcing reliance on vendor professional services.
- Data Migration Complexity:Historical patient records spanning decades of heterogeneous formats require expensive cleansing and mapping before cloud platform activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology EMR Software Market |
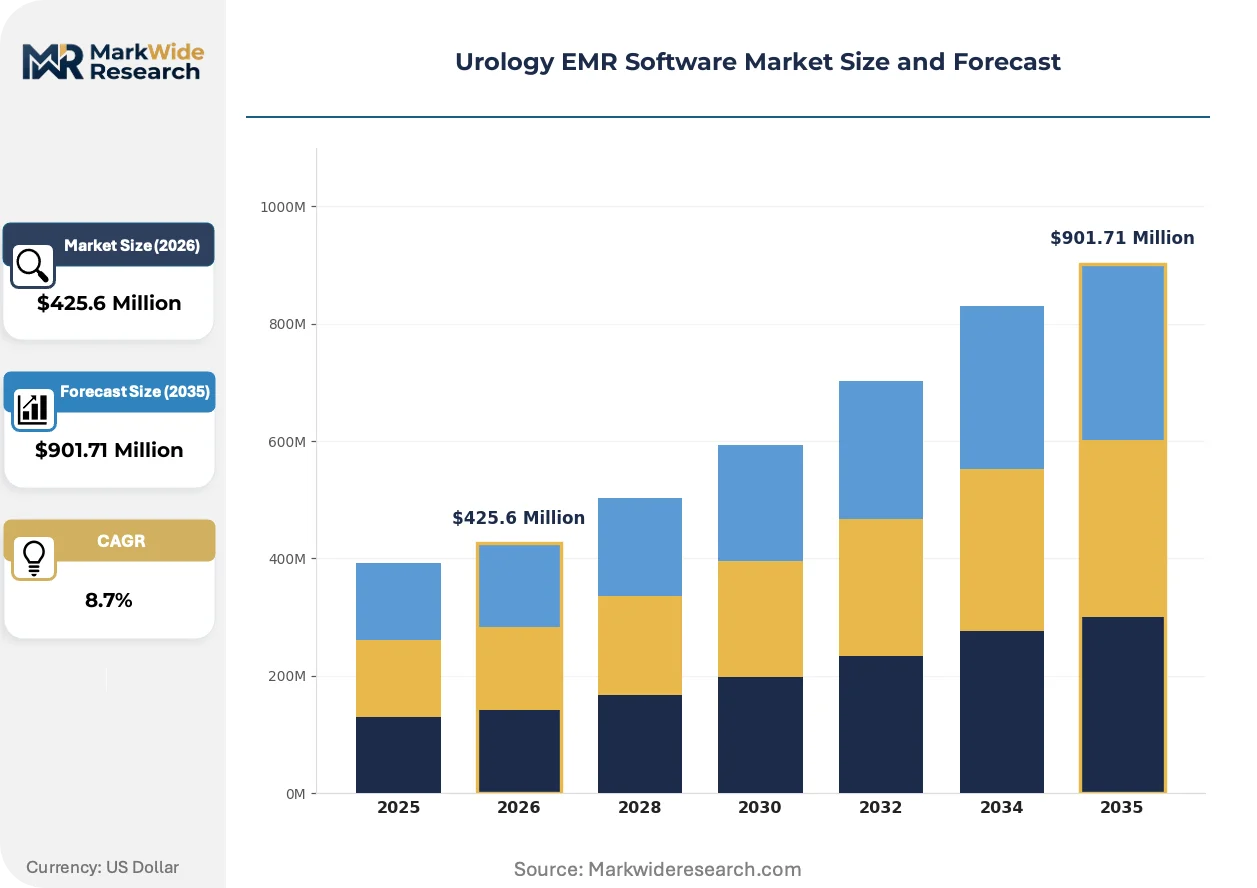
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $901.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Web-Based User Type: Hospitals, Clinics, Private Practices, Urology Centers Deployment Model: Single-Tenant, Multi-Tenant, SaaS, On-Premises Integration Method: API Integration, Direct Integration, Middleware, Custom Solutions |
| Companies Covered | ChartLogic, NextGen Healthcare, ModMed Urology, AdvancedMD, eClinicalWorks, Advanced Data Systems (ADS), Azalea Health, UroChart, Praxis EMR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology EMR Software Market Trends and Innovations
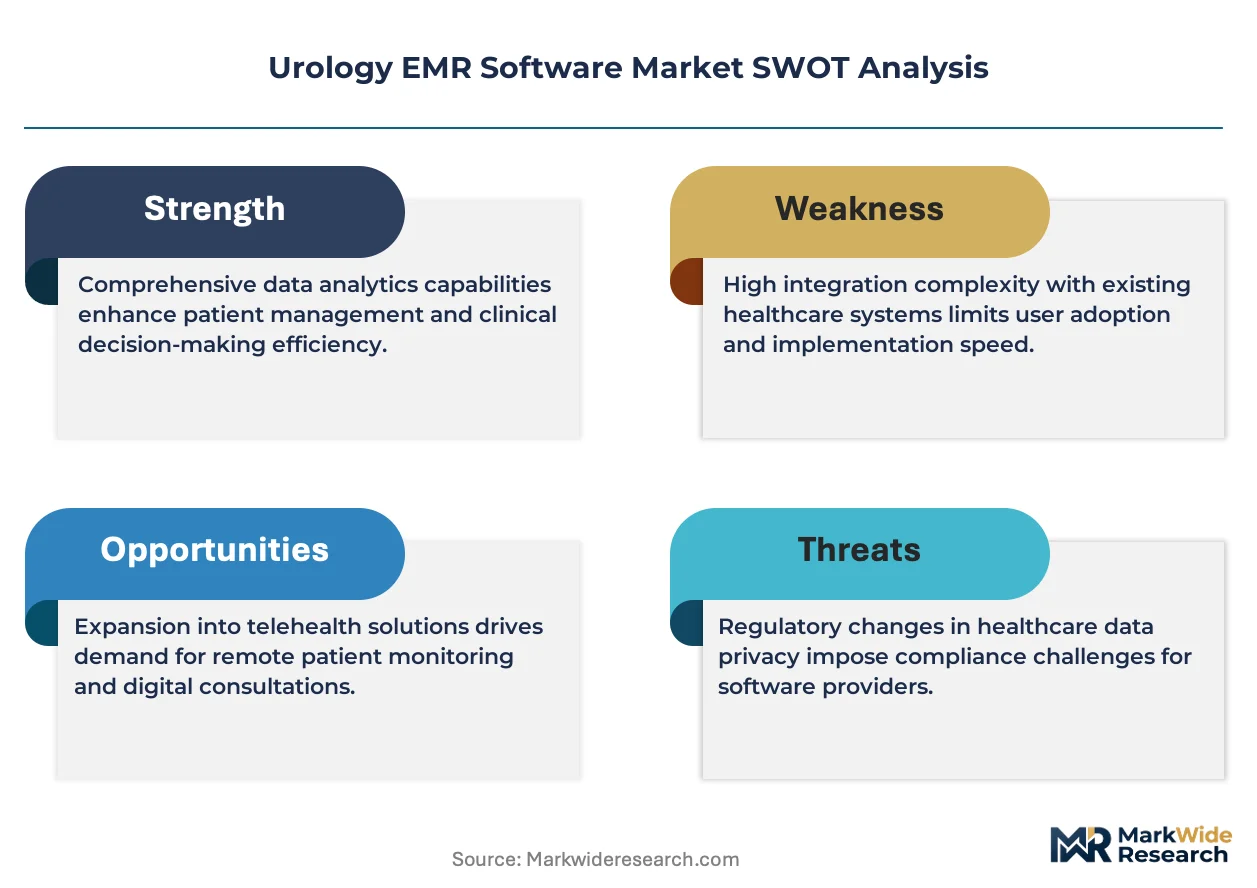
Platform architecture is pivoting from modular add-ons toward unified clinical-financial workflows, while regulatory pressure on data portability accelerates vendor consolidation around interoperable standards.
Natural language processing for clinical documentation is unifying voice capture with structured data entry in urology encounters. Large hospital systems in the Midwest and Southeast are deploying ambient clinical intelligence tools at scale, compressing documentation time from fifteen minutes to under three minutes per cystoscopy case. This compression is unifying billing capture with real-time clinical note generation, eliminating retrospective coding workflows.
FDA 21 CFR Part 820 quality system regulations are tightening software-as-medical-device classifications for diagnostic modules embedded within EMR platforms. Vendors must now submit design control documentation and risk management files for algorithms that interpret prostate imaging or suggest biopsy targets. Urology-specific EMR developers with diagnostic ambitions face capital-intensive regulatory pathways that favor established players with quality management infrastructure.
Subscription pricing models are displacing perpetual license structures as the dominant procurement mechanism. Independent practices in metropolitan markets now expect month-to-month contracts with implementation fee amortization, while hospital procurement departments negotiate enterprise-wide urology module pricing as part of broader health system EMR renewals. This shift is most visible in Texas, where private equity-backed urology groups are standardizing on single-vendor cloud platforms across fifty-plus location networks.
Urology EMR Software Market Segmentation
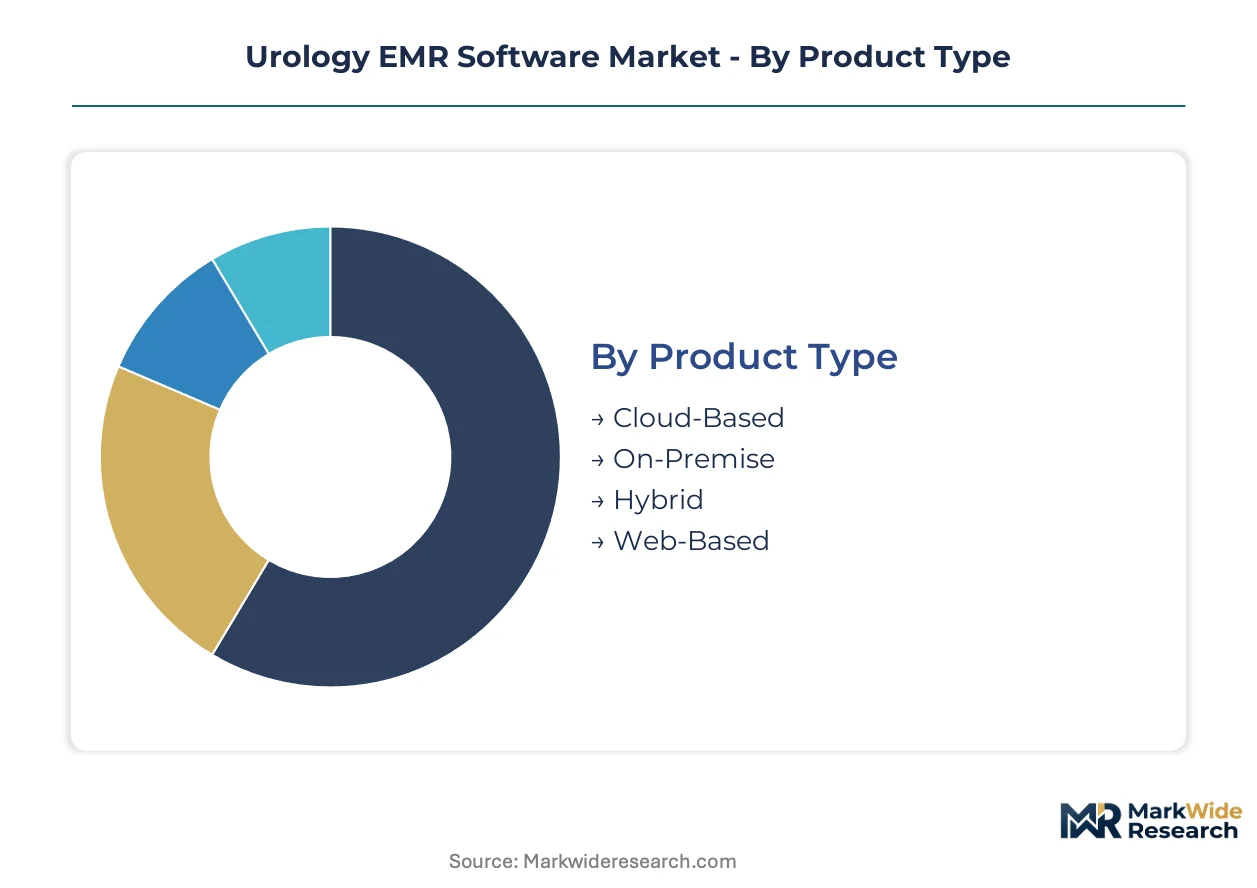
Urology EMR procurement cycles now compress to 18-24 months as cloud platforms obsolete legacy infrastructure. Practices segment their evaluations across deployment architecture, clinical setting, and integration complexity to match vendor capabilities against workflow requirements.
Product Type:
Upgrade cycles favor platforms that eliminate on-site server maintenance while preserving specialty-specific workflow configurations.
- Cloud-Based:Multi-tenant SaaS architecture delivers remote accessibility for multi-site urology groups with centralized IT governance. Demand concentrates among private equity-backed practice networks in Texas and Florida seeking rapid deployment across fifty-plus locations without capital expenditure.
- On-Premise:Hospital systems with sunk infrastructure investments retain these deployments for data sovereignty and customized security postures. Large integrated delivery networks in the Midwest defer cloud migration to align with broader health system EMR consolidation timelines.
- Hybrid:Split architectures isolate protected health information on local servers while pushing analytics workloads to cloud environments.
- Web-Based:Browser-native platforms reduce client-side software maintenance for independent practices with limited IT staffing.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Hybrid configurations bridging legacy and modern infrastructure.
User Type:
Procurement authority varies sharply across clinical settings, with hospital IT departments imposing enterprise-wide standards while independent practices retain vendor selection autonomy.
- Hospitals:Enterprise EMR mandates from Epic or Cerner dominate inpatient urology services, forcing specialty modules to integrate within monolithic architectures. Academic medical centers in Boston and Philadelphia drive demand for research data extraction capabilities alongside clinical workflows.
- Clinics:Ambulatory surgery centers prioritize scheduling-billing-clinical unification to compress revenue cycle timelines.
- Private Practices:Solo and small-group urologists select cloud-native platforms with subscription pricing to preserve cash flow flexibility.
- Urology Centers:Dedicated prostate biopsy and stone disease facilities require procedure-specific documentation templates and image management.
Hospital procurement generates the largest individual contract values; private practices deliver the highest platform activation velocity.
Deployment Model:
Data residency requirements and customization depth determine tenant architecture selection across compliance-sensitive workflows.
- Single-Tenant:Isolated instance deployments satisfy HIPAA security rule interpretations requiring dedicated infrastructure for high-volume prostate cancer centers. Major hospital systems in California specify single-tenant cloud to align with CCPA data localization mandates.
- Multi-Tenant:Shared infrastructure economics enable aggressive pricing for independent practice segments without compromising core functionality.
- SaaS:Subscription delivery with automatic updates eliminates version fragmentation that complicates interoperability certification.
- On-Premises:Perpetual license structures with annual maintenance persist where capital budgets preclude operational expenditure conversion.
Multi-Tenant SaaS captures the majority of new activations; single-tenant deployments command premium pricing in regulated environments.
Integration Method:
Connectivity architecture determines whether diagnostic imaging, laboratory, and wearable data flow automatically into clinical decision workflows or require manual reconciliation.
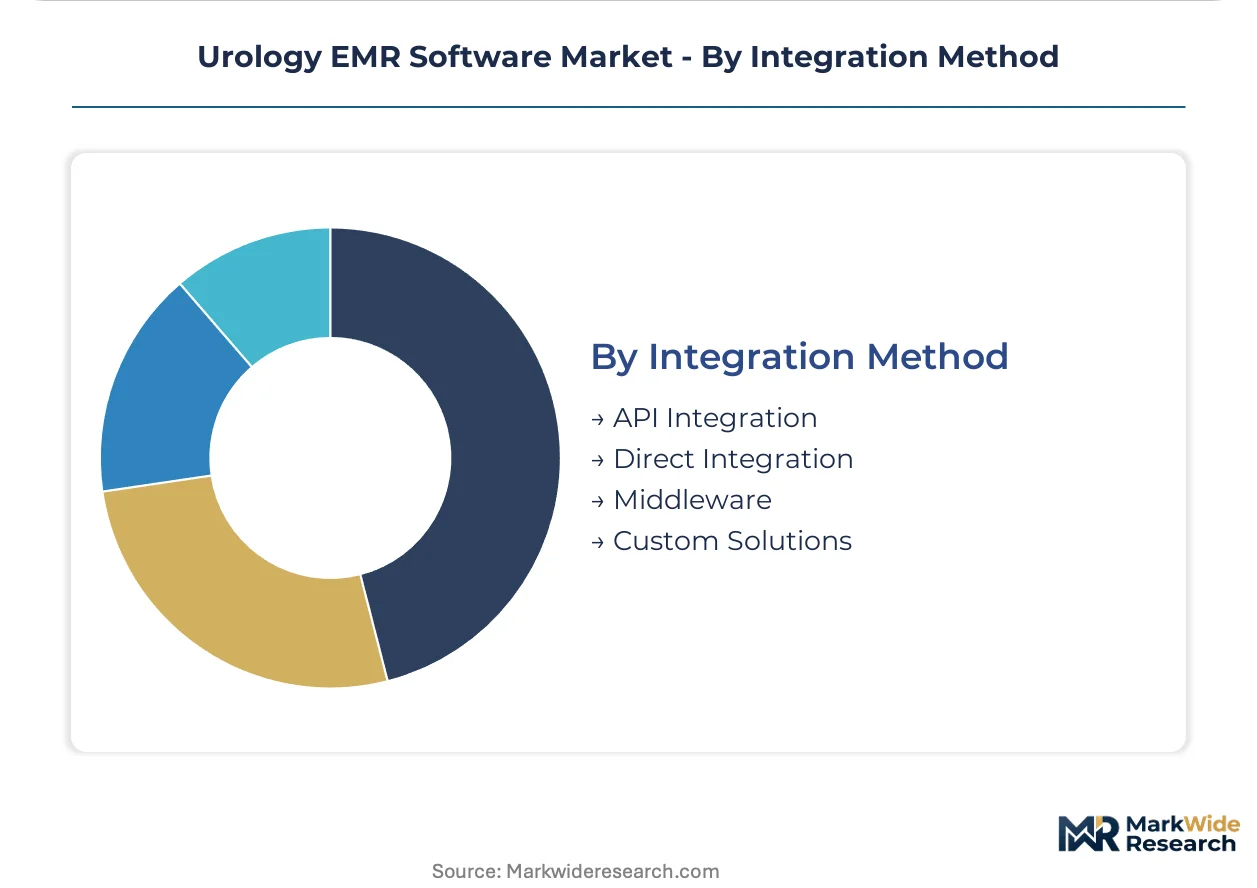
- API Integration:RESTful and FHIR-compliant interfaces enable real-time ingestion of cystoscopic video and PSA trend data from disparate systems. ONC certification requirements under the 21st Century Cures Act mandate API accessibility, making this the default specification for new procurements.
- Direct Integration:Point-to-point connections between specific vendor platforms reduce latency for high-frequency data exchange.
- Middleware:Integration engines translate between legacy HL7 v2 messaging and modern FHIR resources during transition periods.
- Custom Solutions:Bespoke development bridges proprietary systems in hospital environments with entrenched vendor relationships.
API Integration dominates greenfield deployments; middleware solutions sustain share during prolonged migration timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Israel while consumption spreads across hospital systems and private practices in North America, Western Europe, and select Asia-Pacific markets. Cloud infrastructure investments by major technology providers have shifted development gravity toward Seattle, San Francisco, and Tel Aviv. Regulatory fragmentation across jurisdictions shapes deployment architecture choices for multi-national vendors.
United States
Medicare reimbursement incentives and HIPAA security rule updates drive hospital system upgrades. The 21st Century Cures Act mandates ONC-certified interoperability, compelling practices to replace legacy systems. Texas and Florida host the fastest-growing private equity-backed urology networks, with fifty-plus location deployments standardizing on single-vendor cloud platforms.
Germany
Hospital digitization programs under the Hospital Future Act accelerate EMR procurement for academic medical centers. The EU Medical Device Regulation and GDPR data localization requirements favor single-tenant cloud deployments. The Rhine-Ruhr metropolitan region concentrates vendor implementation teams serving cross-border practices in the Netherlands and Belgium.
United Kingdom
NHS England's digital transformation targets push integrated care systems toward unified clinical platforms. The UK GDPR and NHS data security standards mandate encryption levels that exceed baseline HIPAA requirements. London's Harley Street medical district drives demand for private-practice solutions with premium billing integration.
Israel
Health IT export specialization leverages military-acquired cybersecurity expertise for medical software development. The Israeli Ministry of Health's digital health strategy funds R&D partnerships between startups and hospital networks. Tel Aviv's medical technology cluster produces diagnostic modules and AI-assisted imaging tools that integrate with core EMR platforms.
Japan
Aging demographics expand urology service demand while labor shortages accelerate automation investment. The Pharmaceuticals and Medical Devices Agency tightens software-as-medical-device classifications for diagnostic algorithms. Tokyo and Osaka metropolitan areas pilot ambient clinical intelligence tools for cystoscopy documentation in university hospitals.
Urology EMR Software Market Competitive Landscape
The competitive structure tilts toward specialty-focused ambulatory platforms rather than monolithic hospital systems. Vendor tiers separate cloud-native specialists from legacy enterprise suites with urology modules. Three archetypes dominate: multi-site deployment specialists, procedure-template differentiators, and subscription-priced alternatives for independent practices. Consolidation accelerates through private equity portfolio standardization and hospital system enterprise renewals that bundle specialty modules.
Among specialty-focused developers, NextGen Healthcare, ModMed Urology, and AdvancedMD represent distinct competitive positions. NextGen Healthcare anchors the multi-site deployment archetype through ambulatory care infrastructure scaled across United States metropolitan markets. ModMed Urology exemplifies procedure-specific differentiation with specialty templates for genitourinary workflows. AdvancedMD occupies the pricing-flexibility position for cash-flow-sensitive independent practices seeking subscription alternatives to capital-intensive perpetual licenses.
| Leading Market Players |
|---|
| ChartLogic |
| NextGen Healthcare |
| ModMed Urology |
| AdvancedMD |
| eClinicalWorks |
| Advanced Data Systems (ADS) |
| Azalea Health |
| UroChart |
| Praxis EMR |
| Others |
Pricing and Supply Chain Analysis
ONC certification mandates under the 21st Century Cures Act gate qualified vendor participation and premium-tier pricing access, as federal reimbursement eligibility requires interoperability investments that smaller developers cannot fund. This regulatory filter concentrates supply among certified platforms while segmenting pricing power between enterprise hospital systems and independent practice buyers.
Pricing Analysis
Margin tightening in the independent practice segment reflects subscription pricing displacement of perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels segments by deployment architecture and integration complexity. Cost compression accelerates in multi-tenant SaaS tiers as private equity-backed urology networks in Texas and Florida negotiate volume discounts. Hospital systems exhibit lowest price sensitivity due to bundled enterprise renewals; solo practitioners remain most sensitive to implementation fee structures.
Supply Chain Analysis
Domestic-content requirements for HIPAA-compliant data residency reshape cloud infrastructure sourcing toward US-based server farms. Software development concentrates in the United States, Israel, and India, with cloud compute resources drawing from hyperscaler investments in Virginia, Oregon, and Tel Aviv. Supply chain risk centers on single-source vulnerability for FHIR-compliant API middleware. Distribution runs through direct vendor sales teams for hospital systems and value-added resellers for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native platform architecture is displacing on-premise legacy installations across urology workflows, creating transition-phase winners among vendors with specialty-specific templates and API-first integration capabilities.
For Market Incumbents: Cement multi-site deployment dominance by deepening ambulatory care infrastructure in Sun Belt metropolitan markets. Acquire specialty-specific template libraries for cystoscopy and prostate procedures to neutralize ModMed Urology's differentiation. Defend against API-native challengers by accelerating FHIR certification timelines ahead of CMS quality reporting mandates. For New Entrants and Emerging Players: Private equity-backed urology groups in Texas and Florida represent the most penetrable channel partner type for rapid scale. Target fifty-plus location networks seeking standardized cloud platforms without Epic or Cerner enterprise lock-in. Pursue white-label partnerships with revenue cycle management vendors to bypass direct sales cost structures. For Investors and Strategic Acquirers: FDA 21 CFR Part 820 quality system documentation submissions are the leading indicator that diagnostic module developers possess regulatory infrastructure worth premium multiples. Position acquisition targets around specialty EMR vendors with AI-assisted imaging pipelines and established ONC certification. Long-term viability favors platforms bridging clinical documentation with remote patient monitoring data ingestion.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Acceleration | Federal reimbursement eligibility under the 21st Century Cures Act compels interoperability investment. |
| Specialty Template Acquisition | Procedure-specific workflows for cystoscopy and prostate biopsy differentiate ambulatory platforms. |
| API-First Integration Partnership | FHIR-compliant connectivity reduces custom development costs for diagnostic imaging linkage. |
| Remote Monitoring Module Launch | Post-operative urology care shifts to home-based data ingestion from wearables and devices. |
| Geographic Expansion to Sun Belt | Population migration to Texas and Florida concentrates practice formation and procurement authority. |
Research Methodology
FDA 510(k) filings, CMS Medicare reimbursement databases, and ONC certification records formed the secondary backbone for regulatory pathway validation. Primary interviews with urology practice administrators, hospital IT procurement officers, health system GPO contracts managers, and EHR integration specialists triangulated deployment timeline and pricing sensitivity inputs. Bottom-up and top-down approaches cross-validated vendor-reported activation data against hospital system EMR consolidation announcements.
Bottom-up modeling aggregated individual practice and hospital system procurement patterns across deployment architecture, organization size, integration complexity, and regional adoption clusters. Top-down analysis calibrated aggregate market expansion against cloud infrastructure investment disclosures from major technology providers. CAGRs derived from segment-level activation trajectories and replacement cycle compression for legacy on-premise installations.
Caveats apply where HIPAA security rule enforcement intensity or state-level privacy law fragmentation could materially shift platform architecture preferences and vendor competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Critical Care Information Systems Market