
 OBGYN EHR Market | 2026-2036
OBGYN EHR Market Size, Share, and Industry Trends Forecast 2026-2036
OBGYN EHR Market Analytics
Modular subscription packaging is repositioning how OBGYN practices evaluate EHR investments, replacing all-in-one enterprise contracts with component-based purchasing that lets buyers select only obstetrics-specific modules. Epic Systems Corporation leverages its dominant hospital network presence to extend into affiliated outpatient women's health clinics. athenahealth competes through cloud-native architecture that reduces IT overhead for smaller practices. CureMD Healthcare specializes in specialty-specific templates that address prenatal visit documentation and fetal monitoring workflows.
An OBGYN EHR is a clinical information system designed for obstetrics and gynecology workflows, incorporating structured data fields for gestational age tracking, cervical dilation progression, and fetal heart rate pattern interpretation to support prenatal, intrapartum, and postpartum care coordination. Cloud-based deployment now leads product type preference as practices prioritize remote accessibility and automatic security patching over capital-intensive server ownership. Among end users, private practices represent the fastest-expanding segment due to physician-owned groups seeking autonomy from hospital system technology mandates. Research institutions occupy a narrower but higher-margin niche where longitudinal reproductive health datasets command premium pricing for grant-funded studies.
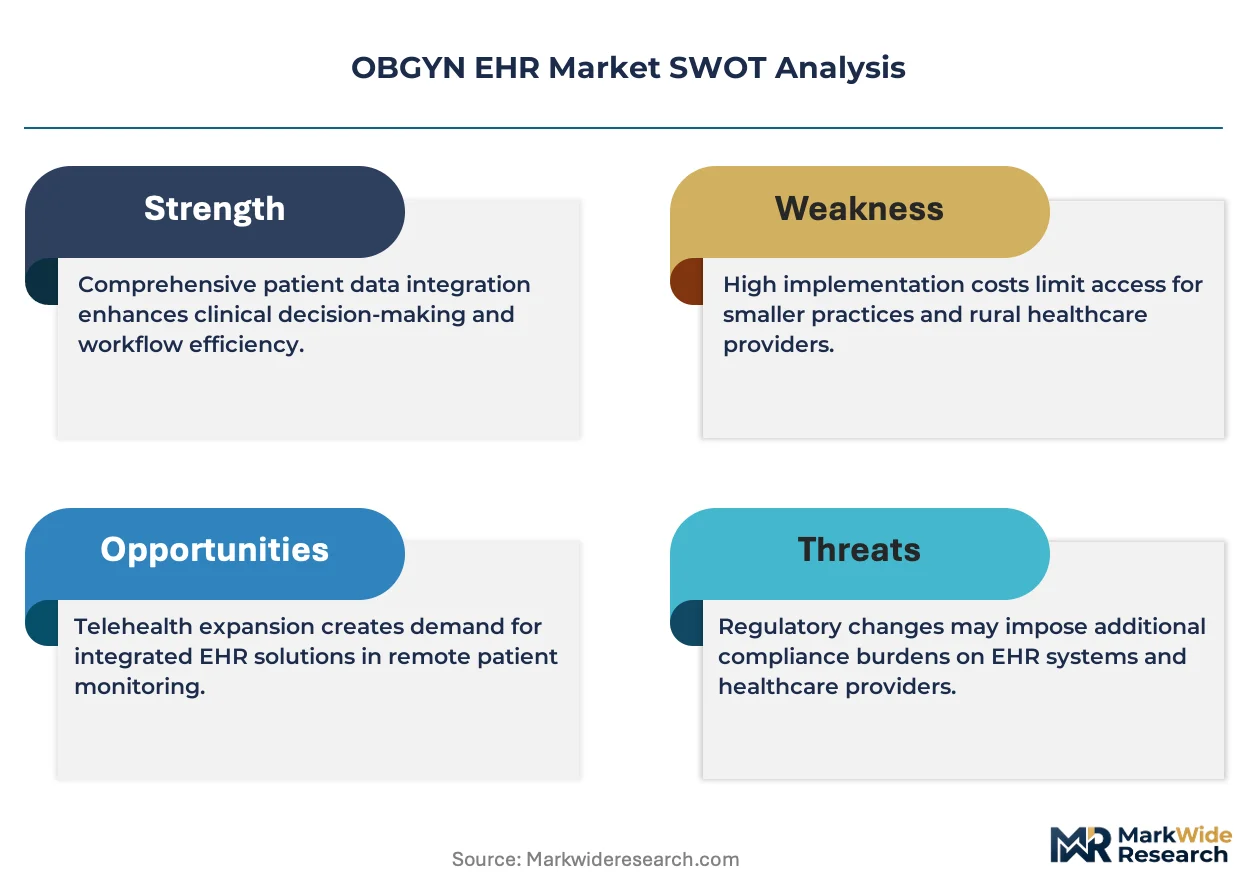
FDA oversight of software as a medical device intersects with ONC certification requirements to create a dual compliance burden for vendors building decision-support features into maternal care platforms. HIPAA security rule enforcement continues shaping demand through mandatory risk assessments that push smaller practices toward vendor-managed infrastructure rather than self-hosted alternatives. Stakeholders must monitor how state-level scope-of-practice expansions for nurse-midwives reshape user licensing requirements and workflow customization needs across delivery settings.
Market Dynamics
Modular subscription packaging is fragmenting purchasing authority across OBGYN practices, replacing centralized IT procurement with specialty-specific module selection driven by maternal-fetal medicine workflow requirements.
Growth Catalysts
- ONC 21st Century Cures Act:Certification mandates in the United States are accelerating ambulatory provider migration toward interoperable platforms that support care coordination across delivery settings.
- Cloud-native architecture:Automatic security patching and remote accessibility are reducing IT overhead burdens for physician-owned groups operating outside hospital system technology mandates.
- Value-based care pilots:Alternative payment models tied to maternal health outcomes are incentivizing EHR investments that capture longitudinal prenatal and postpartum data for quality measurement.
Market Restraints
- Dual compliance burden:FDA oversight of software as a medical device intersects with ONC certification requirements, extending development timelines for decision-support features in maternal care platforms.
- HIPAA security rule enforcement:Mandatory risk assessments are pushing smaller practices toward vendor-managed infrastructure, limiting self-hosted alternatives and concentrating supplier power.
- Specialized workflow complexity:Fetal heart rate pattern interpretation and cervical dilation progression tracking require obstetrics-specific templates that generic EHR platforms cannot replicate without costly customization.
Strategic Opportunities
- Nurse-midwife scope expansion:State-level licensing changes are creating demand for workflow customization across birth centers and home delivery settings outside traditional hospital EHR networks.
- Research institution datasets:Longitudinal reproductive health data commands premium pricing for grant-funded studies, opening a higher-margin niche for platforms with robust data export capabilities.
- API-first interoperability:Standardized data exchange protocols are enabling third-party fetal monitoring device integration, creating new revenue streams for middleware vendors.
Industry Challenges
- Legacy system migration:Practices with decade-old on-premise installations face data mapping complexity when transitioning to cloud-native platforms, risking patient record fragmentation.
- Specialty clinician training:Documentation templates optimized for maternal-fetal medicine require retraining for generalist staff rotating through women's health departments, slowing implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OBGYN EHR Market |
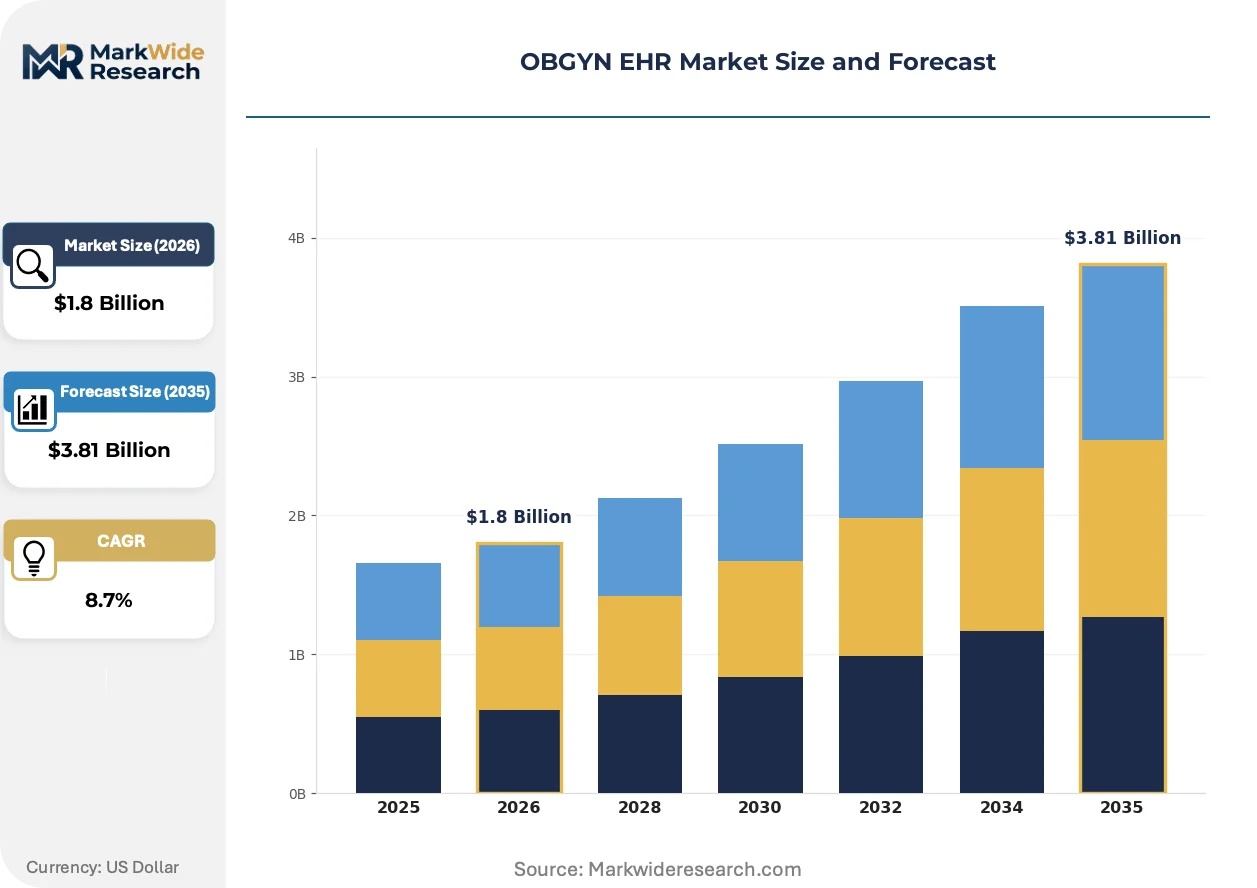
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile End User: Clinics, Hospitals, Private Practices, Research Institutions Deployment: Public Cloud, Private Cloud, Client-server, SaaS Feature: Patient Portal, Telehealth, Reporting Tools, Customization |
| Companies Covered | Epic Systems Corporation, Oracle Health, athenahealth, Greenway Health, CureMD Healthcare, NextGen Healthcare, InSync Healthcare Solutions, Practice Fusion, Inc., WRS Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OBGYN EHR Market Evolving Landscape
Artificial intelligence integration is reshaping clinical documentation in prenatal care, compressing the gap between raw monitoring data and structured diagnostic interpretation.
Machine learning algorithms trained on fetal heart rate variability patterns are electrifying intrapartum surveillance by automating early warning detection for obstetric emergencies. Large hospital systems are deploying these tools across labor and delivery units to reduce cognitive load on nursing staff during high-acuity events. The technology is compressing response times for uterine rupture and fetal distress cases while generating structured data for quality improvement registries.
The FDA's evolving framework for software as a medical device is tightening validation requirements for AI-enabled decision support in maternal care platforms. Vendors must now submit clinical evidence demonstrating algorithm performance across diverse patient populations before commercial deployment. This regulatory friction is favoring established players with dedicated regulatory affairs teams over emerging competitors.
Physician-owned groups are consolidating purchasing decisions through specialty-focused group purchasing organizations rather than accepting hospital system technology mandates. These alliances negotiate module-specific pricing for obstetrics workflows independent of enterprise-wide EHR contracts. The shift is most visible in suburban markets where independent practices retain sufficient patient volume to sustain autonomy.
OBGYN EHR Market Segmentation
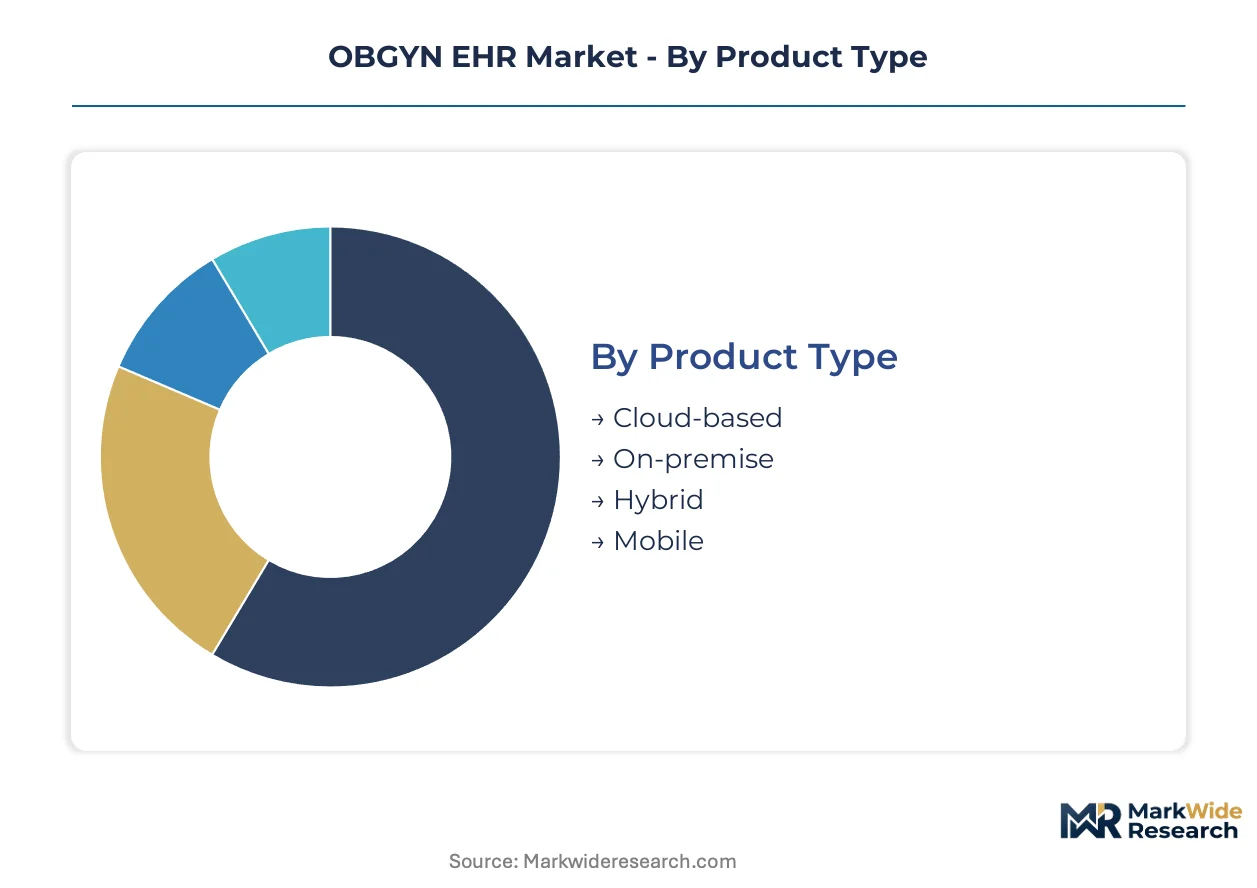
Segmentation in the OBGYN EHR market reveals how deployment architecture and user workflow requirements fragment purchasing decisions across ambulatory and acute care settings. Understanding these divisions exposes where vendor specialization creates pricing power versus where standardization erodes margins.
Product Type:
Integration depth varies sharply across product architectures, with cloud-native platforms embedding directly into hospital system networks while mobile solutions operate as standalone point solutions for field-based clinicians.
- Cloud-based:Multi-tenant architectures with automatic security patching eliminate capital expenditure for server hardware. Demand concentrates among private practices in the United States seeking autonomy from hospital IT mandates, driven by ONC 21st Century Cures Act interoperability requirements.
- On-premise:Self-hosted installations on local servers retain full data custody for practices with specialized compliance needs. Research institutions in the United States favor this architecture for grant-funded longitudinal studies requiring direct database access.
- Hybrid:Split architectures keep sensitive fetal monitoring data on local servers while pushing administrative workflows to cloud tiers.
- Mobile:Native iOS and Android applications enable bedside documentation and remote prenatal visit access.
Cloud-based deployments lead volumes today; mobile solutions are gaining share fastest among nurse-midwife practices.
End User:
Customer type determines module complexity, with acute care settings demanding full maternal-fetal medicine suites while ambulatory sites prioritize prenatal documentation efficiency.
- Private Practices:Physician-owned groups purchase component-based subscriptions selecting only obstetrics-specific modules. These buyers in the United States drive fastest expansion as they resist hospital system technology mandates.
- Hospitals:Enterprise contracts require full integration with labor and delivery units, neonatal intensive care, and anesthesia services. United States hospital networks leverage existing Epic installations to extend into affiliated outpatient women's health clinics.
- Clinics:Federally qualified health centers and community clinics need streamlined prenatal workflows without intrapartum complexity.
- Research Institutions:Academic medical centers command premium pricing for platforms with robust data export capabilities supporting grant-funded reproductive health studies.
Hospitals anchor revenue concentration today; private practices are expanding most quickly.
Deployment:
Infrastructure control preferences split along IT staff availability, with SaaS models eliminating overhead for resource-constrained sites.
- SaaS:Subscription-based software delivery with vendor-managed infrastructure. Small practices across the United States select this model to avoid HIPAA security rule compliance burdens.
- Private Cloud:Dedicated cloud instances for single-tenant data isolation. Hospital systems in the United States deploy this architecture for labor and delivery units requiring guaranteed uptime SLAs.
- Public Cloud:Shared infrastructure with utility pricing for non-sensitive administrative workloads.
- Client-server:Legacy two-tier architectures persisting in rural practices with unreliable broadband connectivity.
SaaS dominates new installations today; private cloud is climbing the fastest among multi-site health systems.
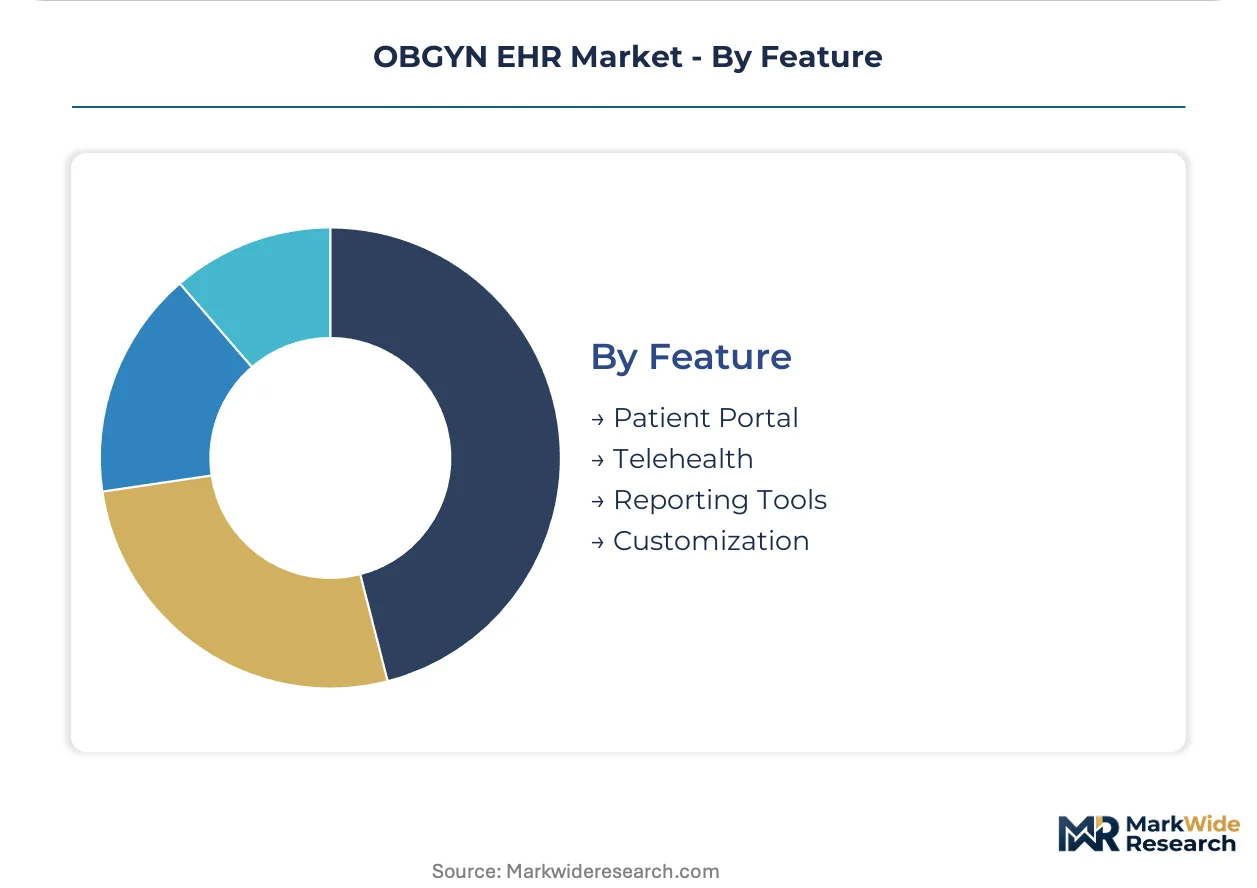
Feature:
Capability modularization lets practices match functionality to reimbursement model, with value-based care pilots demanding reporting tools that fee-for-service sites omit.
- Telehealth:HIPAA-compliant video consultation with integrated fetal monitoring data display. Rural practices in the United States adopted this capability rapidly post-pandemic to extend prenatal care access.
- Reporting Tools:Automated quality measure extraction for maternal health outcome registries. United States practices participating in CMS value-based care pilots require these tools for alternative payment model qualification.
- Patient Portal:Secure messaging and appointment scheduling with gestational age-specific educational content delivery.
- Customization:Template editors for cervical dilation progression tracking and fetal heart rate pattern interpretation workflows.
Reporting tools lead feature adoption today; telehealth shows steepest expansion trajectory among rural and suburban practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The OBGYN EHR industry traces its commercial roots to the United States, where early electronic health record pioneers developed specialty-specific obstetrics modules for academic medical centers in the 1990s. This foundation established the regulatory and technical frameworks that now shape adoption patterns across multiple continents.
United States
Private physician-owned groups and hospital-affiliated women's health clinics drive the bulk of procurement activity. ONC 21st Century Cures Act certification mandates accelerate ambulatory provider migration toward interoperable platforms. Texas and Florida host dense concentrations of independent OBGYN practices resisting hospital system technology consolidation.
Germany
Academic medical centers and university hospitals anchor demand for maternal-fetal medicine workflow integration. The EU Medical Device Regulation (MDR) imposes clinical validation requirements on AI-enabled decision support features. Bavaria's healthcare clusters around Munich and Erlangen concentrate reproductive medicine research institutions seeking longitudinal data export capabilities.
United Kingdom
NHS trusts and private maternity hospitals pursue cloud-native deployments to reduce IT infrastructure overhead. GDPR compliance frameworks shape vendor selection criteria for patient data handling across prenatal and intrapartum workflows. London's academic health science centers command premium pricing for platforms supporting grant-funded reproductive health studies.
India
Corporate hospital chains and fertility clinic networks expand EHR investments to standardize care documentation across multi-site operations. The Central Drugs Standard Control Organization (CDSCO) oversees software as a medical device classifications for maternal monitoring applications. Maharashtra's Mumbai-Pune corridor concentrates the country's largest private maternity hospital chains driving specialty-specific procurement.
Australia
State health departments and private obstetrics practices adopt cloud-based platforms to support regional prenatal care access. The Therapeutic Goods Administration (TGA) regulates software-based clinical decision support in maternal care settings. New South Wales and Victoria host the densest concentrations of maternal-fetal medicine specialists requiring integrated fetal monitoring workflows.
OBGYN EHR Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and specialty workflow customization capabilities. Hospital system dominance by entrenched enterprise vendors creates consolidation pressure at the top tier, while fragmented specialty-specific vendors compete for ambulatory practice contracts below. Two strategic archetypes define competitive positioning: hospital network extenders leveraging existing inpatient installations, and cloud-native specialists targeting independent practice autonomy. M&A activity concentrates among mid-tier vendors seeking certification portfolios, while strategic partnerships with fetal monitoring device manufacturers emerge as a secondary competitive vector.
Among United States-based enterprise vendors, Epic Systems Corporation and Oracle Health occupy positions anchoring hospital network EHR ecosystems that extend into affiliated outpatient women's health settings. Cloud-native specialists athenahealth and CureMD Healthcare exemplify the independent-practice-focused archetype, with athenahealth representing vendor-managed infrastructure approaches and CureMD Healthcare occupying a position within specialty-specific template development for obstetrics workflows.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| athenahealth |
| Greenway Health |
| CureMD Healthcare |
| NextGen Healthcare |
| InSync Healthcare Solutions |
| Practice Fusion, Inc. |
| WRS Health |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs cascade through subscription tiers as multi-tenant architectures eliminate server hardware capital expenditure for private practices while private cloud instances command premium pricing from hospital systems seeking guaranteed uptime SLAs.
Pricing Analysis
Component-based subscription models stratify across certification depth, with ONC 21st Century Cures Act-certified platforms commanding premium positioning over uncertified alternatives. Price differentiation rests on interoperability grade and maternal-fetal medicine template sophistication. Cost compression in the mid-market intensifies as Epic Systems Corporation and Oracle Health leverage hospital network dominance to bundle outpatient modules at volume discounts. Physician-owned groups exhibit highest price sensitivity, while research institutions prioritize data export capabilities over subscription cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers Amazon Web Services, Microsoft Azure, and Google Cloud Platform hosting the majority of SaaS deployments. Software development draws from domestic engineering talent pools in the United States and India, with AI/ML expertise concentrated in academic medical center partnerships. Supply chain risk centers on regulatory restriction as FDA software-as-medical-device classifications extend validation timelines for decision-support features. Distribution runs through direct vendor sales teams for enterprise hospital contracts and specialty-focused group purchasing organizations for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-enabled decision support modules where clinical validation investments create defendable pricing premiums against commodity EHR alternatives.
For Market Incumbents: Anchor market position through deepening integration with labor and delivery unit workflows, extending from inpatient installations into affiliated outpatient clinics. Defend against cloud-native specialists by accelerating AI/ML feature deployment for fetal heart rate pattern interpretation. Prioritize regulatory affairs capacity to navigate FDA software-as-medical-device validation requirements faster than emerging competitors. For New Entrants and Emerging Players: Direct-to-specialist digital channels offer lowest customer acquisition cost entry into nurse-midwife practices operating outside hospital system mandates. Target birth centers and home delivery settings in states with expanded scope-of-practice licensing as the most penetrable segment. Pursue API-first interoperability positioning to capture middleware revenue from fetal monitoring device integration rather than competing head-on for core EHR subscriptions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier vendors lack dedicated regulatory affairs teams to manage dual FDA-ONC compliance burdens. Long-term viability favors platforms with proven hospital system integration capabilities and longitudinal data export architectures serving research institution demand. Watch state-level nurse-midwife licensing expansion as inflection indicator for ambulatory-focused acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clinical validation evidence accelerates commercial deployment of AI-enabled maternal monitoring algorithms. |
| Hospital System Partnership | Epic Systems Corporation leverages inpatient dominance to extend EHR contracts into affiliated outpatient women's health clinics. |
| Strategic Partnership with Device Manufacturers | API integration with fetal monitoring hardware creates proprietary data streams and switching costs. |
| Geographic Expansion via Group Purchasing Organizations | Specialty-focused GPOs consolidate independent practice procurement decisions outside hospital system control. |
| Platform Integration with Telehealth Modules | HIPAA-compliant video consultation with fetal monitoring display addresses rural prenatal care access gaps. |
Research Methodology
Bottom-up private practice and hospital procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core. Primary interviews with OBGYN practice administrators, hospital IT procurement officers, EHR implementation specialists, and group purchasing organization contract managers combined with secondary validation from ONC certification databases, CMS Medicare reimbursement filings, and hospital procurement records. Triangulation across deployment model segmentation and end-user category sizing ensures cross-verification of volume estimates.
Historical trendline analysis of cloud migration patterns and modular subscription adoption informs projection frameworks across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user type, and feature module selection, with CAGRs derived from regression analysis of certification mandate compliance timelines and value-based care pilot expansion rates. AI/ML feature penetration and nurse-midwife licensing expansion serve as industry-specific demand drivers.
Regulatory enforcement intensity, reimbursement model shifts, and AI validation timeline delays are the dominant revision risks. Forecasts reflect assumptions about interoperability mandate compliance rates and cloud infrastructure cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Medical Terminology Software Market