
 US Healthcare ERP Market | 2026-2036
US Healthcare ERP Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare ERP Market Insights
Multi-source vendor consolidation is pivoting toward hybrid deployment architectures that blend legacy on-premises infrastructure with cloud-native modules. Epic Systems Corporation leverages deep clinical workflow integration to sustain dominance in academic medical centers. Cerner Corporation anchors its position through extensive federal health IT contracts, while Oracle Corporation competes aggressively via cloud infrastructure bundling with ERP applications.
US Healthcare ERP denotes enterprise software platforms that integrate financial accounting, supply chain logistics, human capital management, and patient administration through HL7 FHIR-compliant data exchange protocols and role-based access controls. These systems serve primarily to eliminate departmental silos, reduce administrative overhead, and enforce audit trails across multi-site health delivery networks. Financial Management modules capture the largest installed base due to reimbursement complexity under value-based care contracts, though Cloud-Based deployment represents the fastest expansion vector as rural hospitals abandon capital-intensive server refresh cycles. Supply Chain Management functionality has matured into a distinct margin battleground, with pharmacy procurement and implantable device tracking commanding premium configuration pricing.
FDA 21 CFR Part 11 electronic records requirements, HIPAA Security Rule mandates, and CMS Promoting Interoperability standards collectively shape product roadmaps and procurement checklists for every major vendor. The Office of the National Coordinator for Health IT certification criteria further constrain market access, disqualifying uncertified platforms from federal incentive participation. Stakeholders must weigh interoperability obligations against vendor lock-in risks when evaluating SaaS migration timelines and contract renewal positions.
Market Dynamics
Hospital consolidation across the Midwest and Southeast is forcing rapid ERP standardization as multi-facility IDNs replace fragmented legacy billing and supply chain systems with unified platforms. The HITECH Act's enhanced HIPAA enforcement has transformed compliance monitoring from peripheral feature to mandatory procurement checkpoint.
Growth Catalysts
- Regulatory Compliance Mandates:The HIPAA Security Rule and CMS Promoting Interoperability standards compel hospitals to deploy audit-capable ERP modules or forfeit federal incentive payments.
- Cloud Migration Economics:Rural hospitals in Texas and Ohio are abandoning on-premises server refreshes for SaaS ERP contracts that convert capital expenditure to operational spending.
- Value-Based Care Complexity:Reimbursement contracts tied to quality metrics require integrated financial and clinical data workflows that legacy siloed systems cannot support.
Market Restraints
- Implementation Cost Structure:Multi-year deployment timelines and specialized health IT consulting fees strain capital budgets at independent community hospitals.
- Vendor Concentration Risk:Dominance by three platform vendors creates lock-in exposure and limits negotiation leverage during contract renewals.
- Interoperability Friction:HL7 FHIR compliance gaps between acquired facilities with disparate legacy systems delay consolidation benefits.
Strategic Opportunities
- Pharmacy Supply Chain Integration:Track-and-trace mandates for controlled substances create demand for ERP modules with real-time inventory visibility and automated diversion detection.
- AI-Enabled Predictive Analytics:Machine learning modules forecasting patient volume and supply consumption are penetrating academic medical centers in Florida and Ohio.
- Rural Hospital Consolidation:Critical access hospitals in Texas seeking affiliation with larger systems require rapid ERP harmonization to achieve operational integration.
Industry Challenges
- Health IT Talent Scarcity:Shortages of certified Epic and Cerner implementation specialists extend deployment timelines and inflate contractor rates.
- Legacy System Integration Complexity:Decades-old patient billing platforms in acquired facilities resist seamless data migration without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare ERP Market |
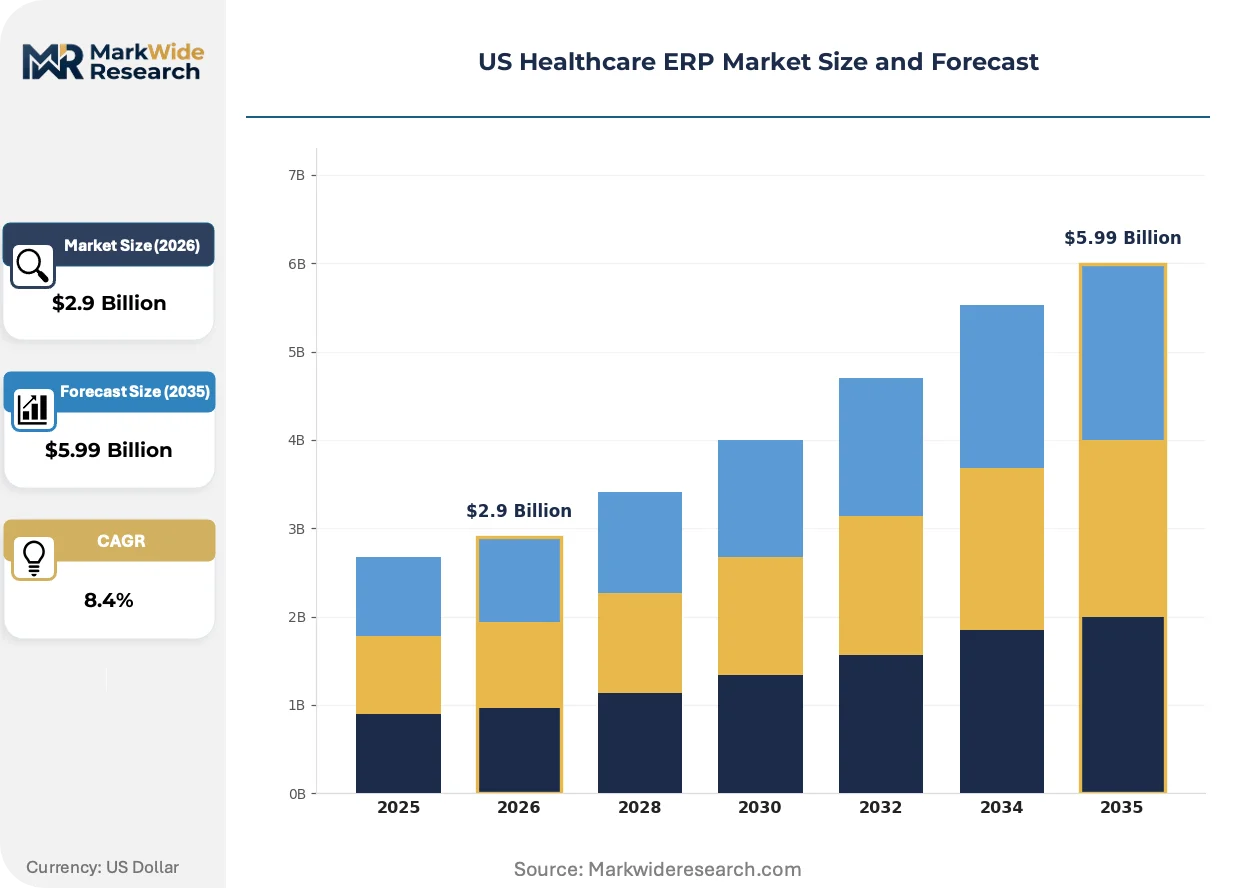
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core ERP, Financial Management, Supply Chain Management, Human Capital Management End User: Hospitals, Clinics, Pharmacies, Health Insurance Providers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Patient Management, Billing, Compliance Monitoring, Resource Allocation |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Oracle Corporation, Microsoft Corporation, SAP SE, McKesson Corporation, Medical Information Technology, Inc., Infor, NextGen Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare ERP Market Trends and Innovations
Cloud-native ERP architectures are overtaking on-premises deployments as hospital CFOs prioritize operational flexibility over capital ownership. Three convergent forces are compressing vendor switching cycles and reshaping procurement criteria.
Containerized microservices architectures is overtaking monolithic ERP codebases in new hospital deployments. Epic and Oracle are restructuring platforms around Kubernetes-orchestrated modules that allow independent scaling of financial, supply chain, and human capital functions. This decomposition enables faster patch cycles and reduces downtime risk during system updates.
The FDA's 21 CFR Part 11 electronic records requirements are tightening validation protocols for ERP modules handling clinical trial billing and device procurement. Vendors must now submit formal documentation of audit trail integrity and user access controls to hospital compliance officers before contract execution. Academic medical centers with active research portfolios are requiring pre-validated FDA-compliant configurations as standard procurement terms.
Subscription-based pricing models are displacing perpetual license structures in mid-market hospital negotiations. CFOs in multi-hospital systems across Florida and Ohio are demanding consumption-based contracts that scale fees with bed count or transaction volume rather than fixed upfront payments. This shift transfers implementation risk to vendors and accelerates SaaS migration timelines among capital-constrained facilities.
US Healthcare ERP Market Segmentation
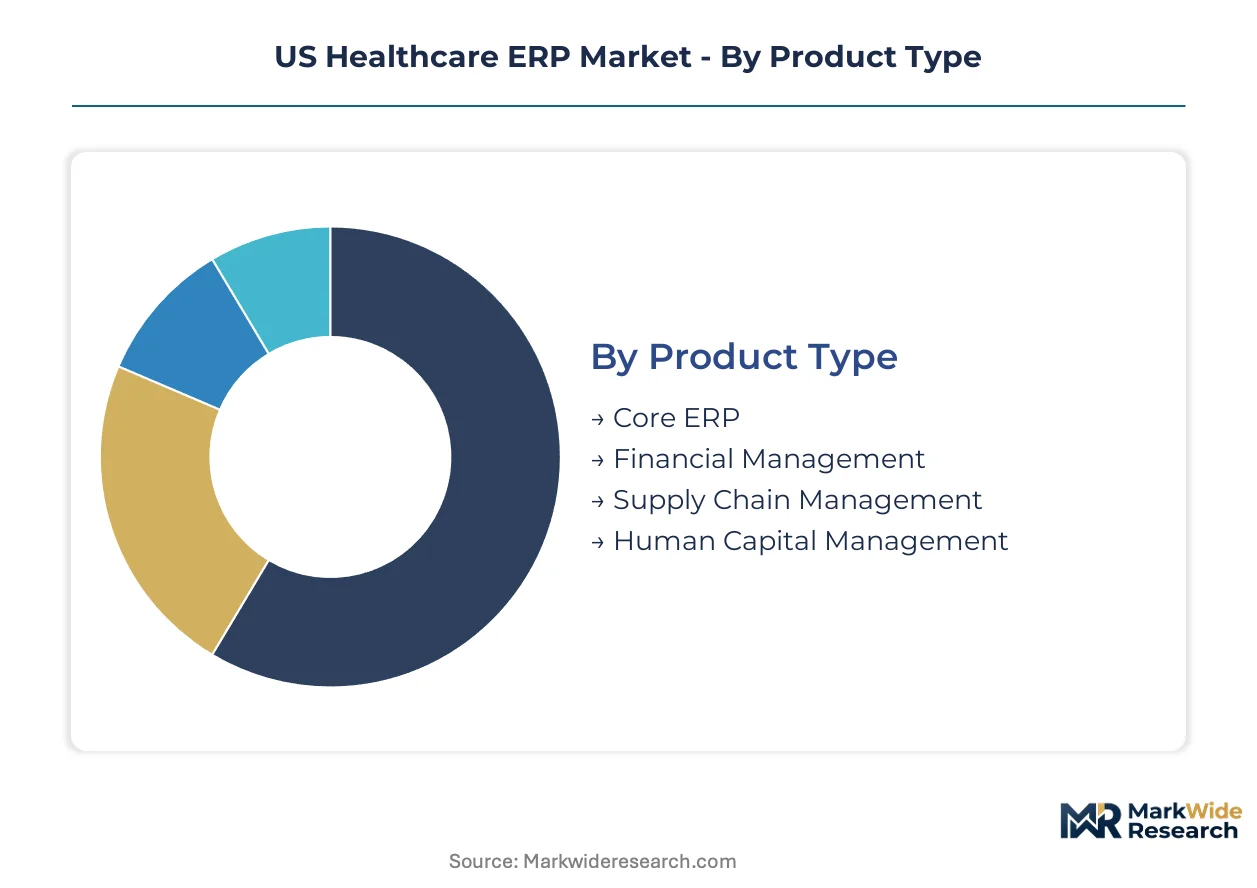
Healthcare ERP segmentation reveals how procurement priorities diverge across facility types and regulatory exposure. Vendors calibrate module bundling and pricing tiers to match the operational complexity and compliance maturity of each buyer segment.
Product Type:
Standardization pressures from HIPAA and CMS certification criteria compress differentiation at the core platform layer, while specialized modules command premium configuration fees based on workflow depth.
- Core ERP:Unified platforms integrating financial, supply chain, and human capital functions through HL7 FHIR-compliant data exchange. Demand concentrates among multi-hospital IDNs in Texas and Ohio where acquired facilities require rapid harmonization of disparate legacy systems.
- Financial Management:Modules capturing reimbursement complexity under value-based care contracts, including automated claims processing and audit trail generation. Hospital CFOs in Florida prioritize these systems to manage risk-adjusted payment models and federal incentive reporting.
- Supply Chain Management:Pharmacy procurement and implantable device tracking with real-time inventory visibility.
- Human Capital Management:Workforce scheduling and credentialing aligned with Joint Commission staffing requirements.
Leading the category by volume: Financial Management. Growing fastest: Supply Chain Management.
End User:
Scale of operations and regulatory scrutiny intensity create distinct procurement profiles across buyer types, with consolidation dynamics reshaping vendor targeting strategies.
- Hospitals:Academic medical centers and multi-facility systems deploy comprehensive ERP suites with mandatory compliance monitoring modules. IDN consolidation across the Midwest and Southeast drives replacement of fragmented billing systems with standardized enterprise platforms.
- Clinics:Ambulatory settings favor modular cloud deployments with lower implementation overhead.
- Pharmacies:Track-and-trace mandates for controlled substances require specialized inventory modules with automated diversion detection.
- Health Insurance Providers:Payers integrate ERP with claims adjudication systems to streamline provider network management.
Dominant procurement volume flows to hospitals. Clinics represent the steepest expansion trajectory as rural affiliations accelerate.
Deployment:
Capital constraint severity and IT staffing depth determine migration pace from legacy infrastructure to consumption-based service models.
- On-Premises:Legacy server installations retained by large systems with sunk infrastructure investments and specialized security teams.
- Cloud-Based:Scalable architectures eliminating capital-intensive refresh cycles. Rural hospitals in Texas and Ohio are abandoning on-premises deployments for operational expenditure models that transfer implementation risk to vendors.
- Hybrid:Blended configurations preserving sensitive financial data on-site while pushing administrative functions to cloud.
- SaaS:Subscription pricing with consumption-based scaling tied to bed count or transaction volume.
On-Premises retains the largest installed base. Cloud-Based deployment is gaining share fastest among capital-constrained facilities.
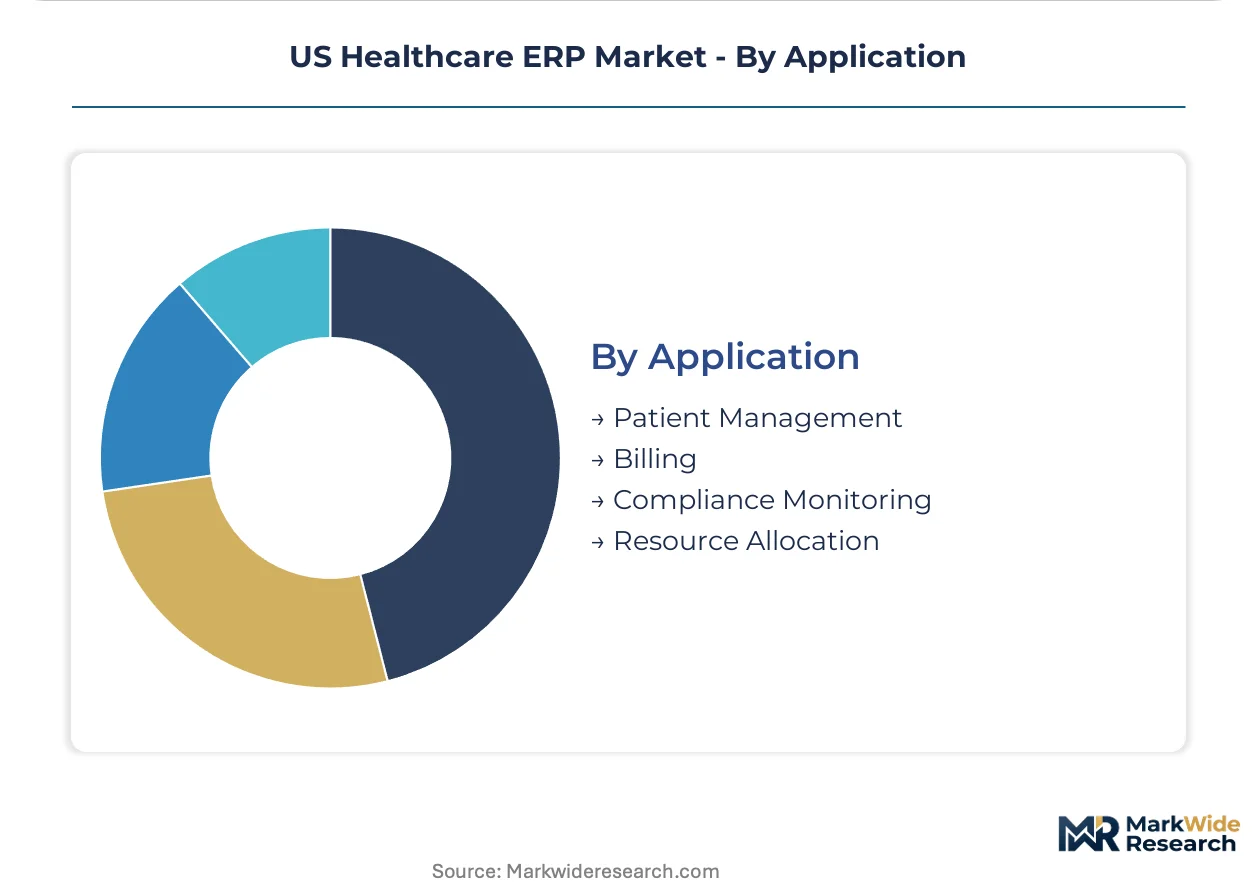
Application:
Regulatory enforcement intensity and reimbursement model complexity elevate certain functional modules from operational convenience to procurement necessity.
- Patient Management:Admission, discharge, and transfer workflows integrated with clinical documentation systems.
- Billing:Revenue cycle management addressing multi-payer complexity and prior authorization automation.
- Compliance Monitoring:Audit trail generation and access control enforcement mandated by HIPAA Security Rule and HITECH Act. Hospital compliance officers now require pre-validated FDA 21 CFR Part 11 configurations before contract execution.
- Resource Allocation:Predictive analytics for staffing optimization and supply consumption forecasting.
Billing modules command the broadest deployment. Compliance Monitoring is climbing the fastest as enforcement penalties escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors healthcare ERP procurement intensity through its concentration of multi-hospital IDNs and rural hospital consolidation waves. The state's blend of academic medical centers and critical access facilities creates layered demand for both enterprise suites and modular cloud deployments.
Texas
Hospital consolidation across Dallas-Fort Worth and Houston drives urgent standardization of billing and supply chain systems under newly formed IDN umbrellas. CMS Promoting Interoperability standards compel rural facilities in the Panhandle and West Texas to abandon legacy platforms. The Texas Medical Center in Houston anchors cloud migration adoption among academic institutions.
Florida
Value-based care contracts with risk-adjusted payment models elevate financial management modules to procurement priority for hospital CFOs in Miami and Tampa. HIPAA Security Rule enforcement through HITECH compels compliance monitoring investment. The Orlando health corridor concentrates AI-enabled predictive analytics deployment for patient volume forecasting.
Ohio
Rural hospital abandonment of capital-intensive server refreshes accelerates SaaS ERP adoption across the Appalachian and Midwestern regions of the state. The Cleveland Clinic and Ohio State University medical networks drive hybrid architecture standardization. Cincinnati's health corridor anchors pharmacy supply chain integration for controlled substance track-and-trace compliance.
Southeast Cluster
Georgia and North Carolina hospital systems expand procurement of integrated suites to unify patient billing with supply chain operations across acquired facilities. Joint Commission staffing requirements elevate human capital management module demand in Atlanta and Charlotte. Research Triangle Park anchors FDA 21 CFR Part 11 validation requirements for clinical trial billing configurations.
Midwest Consolidation Belt
Illinois and Michigan multi-facility systems replace fragmented legacy billing platforms with standardized enterprise resource planning. ONC certification criteria constrain vendor selection for Chicago and Detroit health networks. The Great Lakes industrial corridor concentrates supply chain management investment for implantable device tracking and real-time inventory visibility.
US Healthcare ERP Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle cloud infrastructure with specialized healthcare modules to capture IDN consolidation contracts. The vendor base concentrates around three platform providers with deep clinical workflow integration, creating tiered procurement dynamics between enterprise suites and modular alternatives. Two strategic archetypes prevail: integrated clinical-financial platform specialists and cloud-native infrastructure bundlers. M&A activity and subscription pricing model expansion represent the dominant competitive vectors reshaping contract structures.
Within the integrated platform tier, Epic Systems Corporation and Cerner Corporation exemplify archetypes anchored in academic medical center dominance and federal health IT contracting respectively. Oracle Corporation occupies a position representing cloud infrastructure bundling strategies competing for multi-hospital standardization contracts. These three entities collectively anchor vendor concentration risk dynamics that limit negotiation leverage during renewal cycles for hospital procurement officers.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| McKesson Corporation |
| Medical Information Technology, Inc. |
| Infor |
| NextGen Healthcare |
| Others |
Pricing and Supply Chain Analysis
CMS Promoting Interoperability standards gate qualified supply access and premium-tier pricing eligibility for ERP vendors serving US hospital systems. Vendors lacking ONC certification face exclusion from federal incentive programs, compressing their addressable market to cash-constrained independent facilities willing to absorb compliance risk.
Pricing Analysis
Warranty and implementation service bundling separates full-service contracts from stripped-down SaaS subscriptions in hospital procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and customization depth. Price differentiation hinges on FDA 21 CFR Part 11 pre-validation and Epic/Cerner specialist availability. Pricing pressure stems from rural hospital capital constraints forcing vendors toward consumption-based models. Independent community hospitals exhibit highest price sensitivity; academic medical centers prioritize workflow integration over cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel ERP vendors to maintain qualified relationships with multiple hyperscale providers. Software development concentrates in the United States, India, and Ireland. Raw material dependencies include semiconductor components for on-premises servers, specialized health IT labor, and HIPAA-compliant data center capacity. Supply chain risk centers on single-source vulnerability for certified implementation specialists. Distribution runs through direct enterprise sales teams and health IT consulting partners serving IDN procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into cloud infrastructure and clinical workflow data layers defines competitive positioning in this market. Players are racing to control upstream data pipelines and downstream implementation service capacity.
For Market Incumbents: Anticipate margin compression from subscription pricing by locking multi-year IDN contracts before renewal cycles open. Acquire boutique health IT consultancies to capture implementation revenue streams. Defend against Oracle's infrastructure bundling through deeper Epic clinical integration.
For New Entrants and Emerging Players: Enter via modular SaaS offerings targeting rural hospital consolidation in Texas and Ohio. Critical access facilities seeking IDN affiliation present the most penetrable segment. Position around rapid deployment timelines and consumption-based pricing without legacy migration complexity.
For Investors and Strategic Acquirers: FDA 21 CFR Part 11 validation completion is the leading indicator that a vendor can capture academic medical center contracts. Long-term viability rests on clinical workflow integration depth rather than infrastructure scale. Target acquisition candidates with pre-validated compliance configurations and existing GPO relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Investment | Federal incentive program eligibility determines addressable market scope for hospital ERP vendors. |
| Cloud Infrastructure Partnership | Hyperscaler alliances transfer capital risk and accelerate SaaS deployment timelines for rural facilities. |
| Health IT Consultancy Acquisition | Implementation capacity scarcity creates captive revenue streams and deepens IDN relationships. |
| AI-Enabled Predictive Module Launch | Machine learning differentiation targets academic medical centers in Florida and Ohio expansion corridors. |
| Pharmacy Supply Chain Integration | Controlled substance track-and-trace mandates open premium pricing for specialized inventory modules. |
Research Methodology
Independent corroboration across hospital CIO interviews, GPO contract databases, and CMS certification records underwrites the qualitative findings. Primary fieldwork engaged health system procurement officers, Epic implementation specialists, biomedical informatics directors, and IDN finance executives. Secondary validation drew from hospital procurement databases, ONC certification listings, CMS Medicare cost reports, and SEC filings of publicly traded health IT vendors. Bottom-up facility-level demand estimates triangulated against top-down market sizing from vendor revenue disclosures.
Rate-of-change decomposition across the analysis window segments growth by deployment model, facility scale, application module, and regional consolidation intensity. Modeled dimensions include cloud-native versus hybrid architecture, multi-hospital IDN versus independent facility, financial management versus supply chain versus human capital modules, and Texas-Florida-Ohio versus other state clusters. CAGRs derive from regression against hospital bed count projections, IDN merger announcements, and federal incentive program participation trends. Forecast inputs incorporate rural hospital closure rates and HITECH enforcement penalty escalation trajectories.
Revisions become necessary when HIPAA Security Rule enforcement intensity shifts, IDN consolidation pace deviates from announced merger timelines, or cloud migration economics reverse due to data sovereignty requirements. Deviation in federal health IT incentive funding would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Global Clinical Information System Market