
 Healthcare ERP Market | 2026-2036
Healthcare ERP Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare ERP Market Intelligence
Subscription-based licensing is decoupling software ownership from infrastructure control in healthcare ERP procurement. Oracle leverages its Cerner acquisition to anchor clinical-financial integration across large hospital networks. SAP competes through deep supply chain management specialization that extends into pharmaceutical track-and-trace compliance. Epic dominates the ambulatory and acute care segment where its captive interoperability framework controls physician workflow lock-in.
Healthcare ERP denotes enterprise resource planning software architected for medical environments, typically integrating HL7 FHIR data exchange protocols, role-based access controls, and modular architectures spanning finance, HR, and patient administration. Its primary commercial purpose centers on unifying operational silos to reduce administrative cost burdens and enforce clinical governance standards. Cloud-based ERP leads new deployments as hospitals exit capital-intensive on-premise maintenance cycles, while hybrid ERP configurations capture margin pools among mid-tier laboratories navigating phased digital transitions. Patient relationship management solutions represent the fastest-attached module as consumer-directed care models reshape revenue cycle priorities.
FDA 21 CFR Part 11, HIPAA security rules, and the EU AI Act collectively shape product certification requirements and cross-border data residency obligations for healthcare ERP vendors. The FDA mandates audit trails and electronic signature integrity for systems touching clinical trial management, while HIPAA encryption standards dictate infrastructure architecture choices for US deployments. Stakeholders must monitor how emerging FDA software-as-medical-device guidance intersects with ERP modules that embed clinical decision support algorithms.
Market Dynamics
Cloud migration mandates under HIPAA and the EU AI Act are forcing hospital systems to restructure procurement around data residency controls and audit-ready infrastructure, decoupling software ownership from physical data center management.
Growth Catalysts
- FHIR R4 interoperability mandates:The 21st Century Cures Act requires healthcare providers to enable patient data exchange through standardized APIs, driving replacement of legacy systems that cannot support real-time clinical data flows.
- Germany's Hospital Future Act funding:Federal investment pools are accelerating digital infrastructure modernization across state hospital networks, with ERP systems qualifying as core eligible expenditures.
- Track-and-trace serialization requirements:Pharmaceutical supply chains must maintain end-to-end visibility from manufacturer to patient, embedding ERP modules with GS1 standards compliance as a non-negotiable procurement criterion.
Market Restraints
- Specialized implementation talent scarcity:Healthcare ERP deployments require certified consultants fluent in both HL7 standards and hospital revenue cycle operations, with training pipelines failing to match deployment timelines.
- Concentrated cloud infrastructure dependency:Three hyperscale providers dominate healthcare-compliant hosting, creating single-point-of-failure risks for multi-hospital networks migrating core patient administration systems.
- FDA software-as-medical-device ambiguity:Uncertainty around which ERP-embedded clinical decision support algorithms trigger premarket review is freezing procurement cycles for advanced analytics modules.
Strategic Opportunities
- Japan's regional medical association consolidation:Merger waves among prefecture-level hospital groups are creating demand for unified ERP platforms that can absorb disparate legacy systems without workflow disruption.
- Consumer-directed care revenue cycle modules:High-deductible health plan proliferation is forcing hospitals to deploy patient financial engagement tools that integrate price transparency and payment plan management.
- EU AI Act conformity assessment pathways:Early certification as a "high-risk AI system" vendor creates competitive moats for ERP platforms that embed clinical algorithms with embedded bias detection and explainability features.
Industry Challenges
- Interoperability testing backlog:ONC certification requirements for certified health IT products are creating 6-12 month delays for ERP vendors attempting to release FHIR-enabled modules.
- Legacy mainframe data migration complexity:Hospital systems running 1980s-era patient accounting systems face exponential cost overruns when extracting historical claims data for cloud ERP ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare ERP Market |
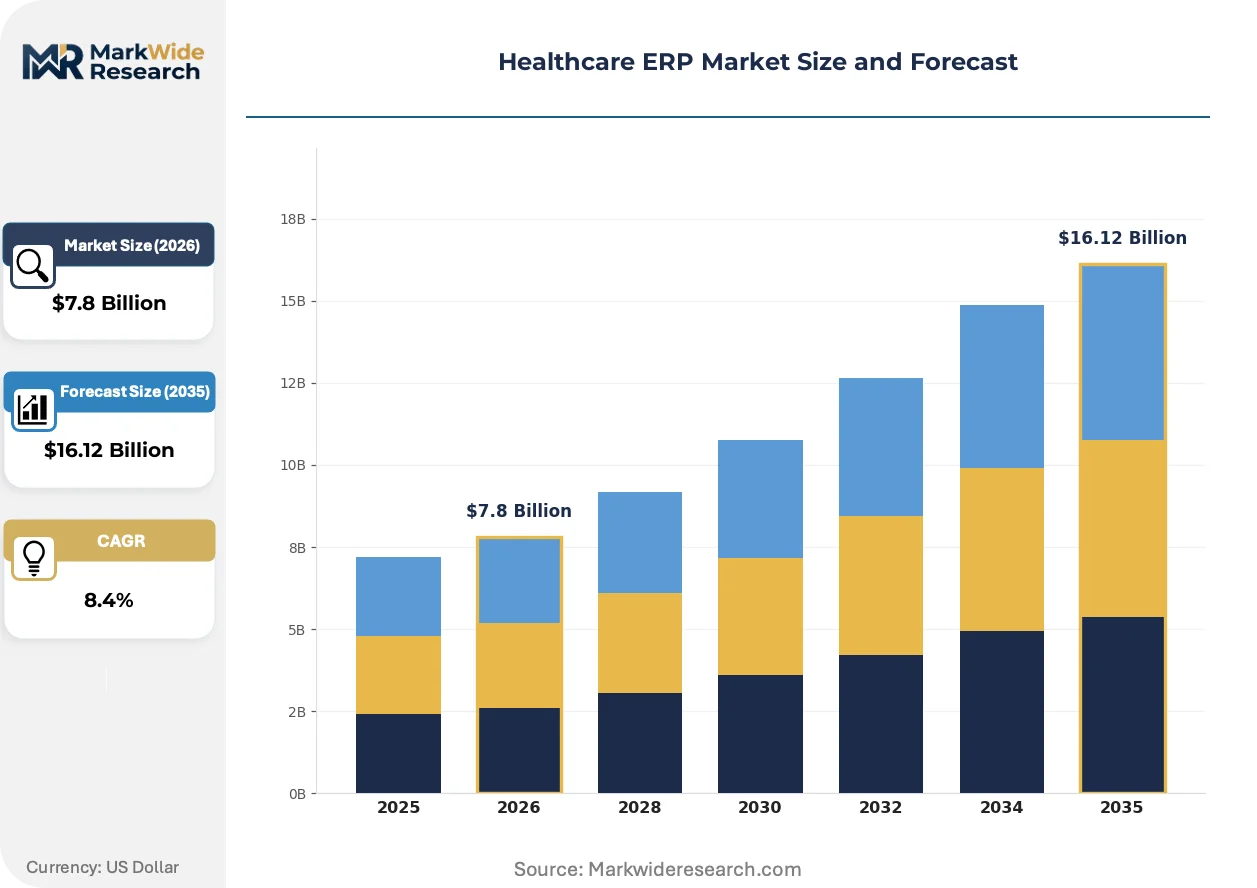
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based ERP, On-premise ERP, Hybrid ERP, Custom ERP End User: Hospitals, Clinics, Laboratories, Rehabilitation Centers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premise Solution: Financial Management, Supply Chain Management, Human Resource Management, Patient Relationship Management |
| Companies Covered | Oracle, Infor, SAP, Epic, Cerner, Meditech, eClinicalWorks, Microsoft Dynamics 365, NetSuite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare ERP Market Strategic Shifts & Innovations
Healthcare ERP architecture is absorbing AI-driven clinical decision support and ambient documentation capabilities that were previously standalone point solutions, compressing the vendor landscape around platforms with native interoperability.
Generative AI is absorbing routine administrative workflows including prior authorization submission, clinical documentation completion, and revenue cycle denial management. Large hospital networks in the United States are piloting these capabilities through limited deployments in outpatient settings, with full inpatient rollout contingent on liability framework clarification. The technology is absorbing tasks previously handled by specialized business process outsourcing vendors, compressing margins in the healthcare administrative services sector.
The EU AI Act's risk classification system is mandating conformity assessments for ERP modules that embed diagnostic or treatment recommendation algorithms. Vendors must now maintain technical documentation, human oversight protocols, and post-market monitoring systems that mirror medical device quality management requirements. German university hospitals are responding by segregating high-risk AI functions into standalone modules with isolated validation pipelines, while lower-risk administrative automation proceeds through standard procurement channels.
Subscription pricing is displacing perpetual license models across mid-tier health systems that lack capital reserves for upfront software acquisition. Community hospitals in the United States are negotiating five-year operational expenditure contracts that bundle implementation, training, and continuous compliance updates. This shift is most visible among independent rural facilities seeking to avoid technical debt accumulation from on-premise infrastructure refresh cycles.
Healthcare ERP Market Segmentation
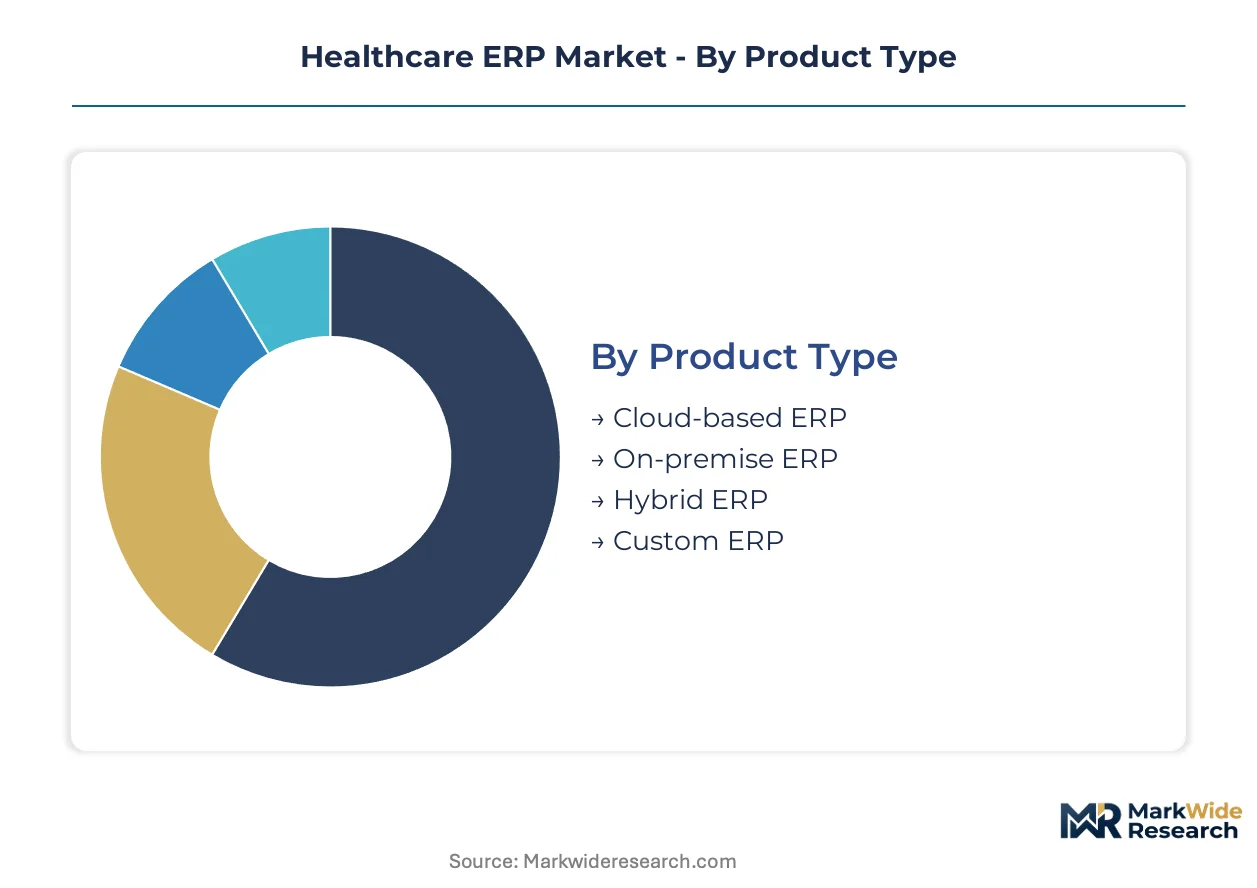
Healthcare ERP procurement decisions pivot on compliance architecture, integration depth, and total cost of ownership across facility types. Segmentation reveals how cloud migration mandates and clinical workflow requirements reshape vendor selection criteria and module prioritization.
Product Type:
Cloud migration mandates under HIPAA and the EU AI Act are decoupling software ownership from infrastructure control, making deployment model the primary cost-tier differentiator.
- Cloud-based ERP:Architected for multi-tenant hosting with embedded FHIR R4 APIs and automated HIPAA compliance patching. Demand concentrates in United States hospital networks exiting capital-intensive data center maintenance cycles, driven by subscription pricing that converts capital expenditure to operational expenditure.
- On-premise ERP:Retained by facilities with specialized air-gapped security requirements or legacy mainframe dependencies that resist cloud data migration. German university hospitals maintain these configurations for clinical trial management systems requiring FDA 21 CFR Part 11 audit trail isolation.
- Hybrid ERP:Captures mid-tier laboratories navigating phased digital transitions, with financial modules cloud-hosted while patient administration remains on-premise.
- Custom ERP:Built for national health systems with unique reimbursement coding requirements or multi-language regulatory reporting obligations.
Cloud-based ERP leads on scale; Hybrid ERP leads on momentum among facilities with technical debt constraints.
End User:
Facility scale determines module integration complexity and regulatory exposure, with acute care settings requiring the most extensive clinical-financial data unification.
- Hospitals:Integrated platforms spanning finance, HR, supply chain, and patient administration with real-time HL7 FHIR exchange. United States health systems prioritize revenue cycle modules that automate prior authorization and denial management under high-deductible plan proliferation.
- Clinics:Ambulatory-focused deployments emphasizing scheduling, billing, and referral management with lighter regulatory overhead than inpatient settings.
- Laboratories:Specialized inventory tracking for reagents and specimens, with GS1 serialization compliance for pharmaceutical supply chain integration.
- Rehabilitation Centers:Longitudinal care planning tools with outcome measurement reporting for bundled payment models.
Hospitals dominate absolute spend; Clinics show steepest expansion trajectory as independent practices consolidate into network structures.
Deployment:
Data residency controls and audit-ready infrastructure requirements are restructuring hosting decisions around jurisdictional compliance rather than pure cost optimization.
- Public Cloud:Hyperscale-hosted environments with shared tenancy and automated scaling, preferred by United States community hospitals seeking to avoid infrastructure technical debt.
- Private Cloud:Dedicated single-tenant hosting meeting stringent EU AI Act conformity assessment requirements for high-risk clinical algorithm modules.
- Hybrid Cloud:Segregated architecture with administrative workloads public-hosted and patient data private-hosted, capturing German Hospital Future Act funding eligibility.
- On-premise:Physical data center control retained for facilities in jurisdictions with strict cross-border data transfer prohibitions.
Public Cloud captures volume concentration; Private Cloud gains share fastest as EU AI Act enforcement tightens.
Solution:
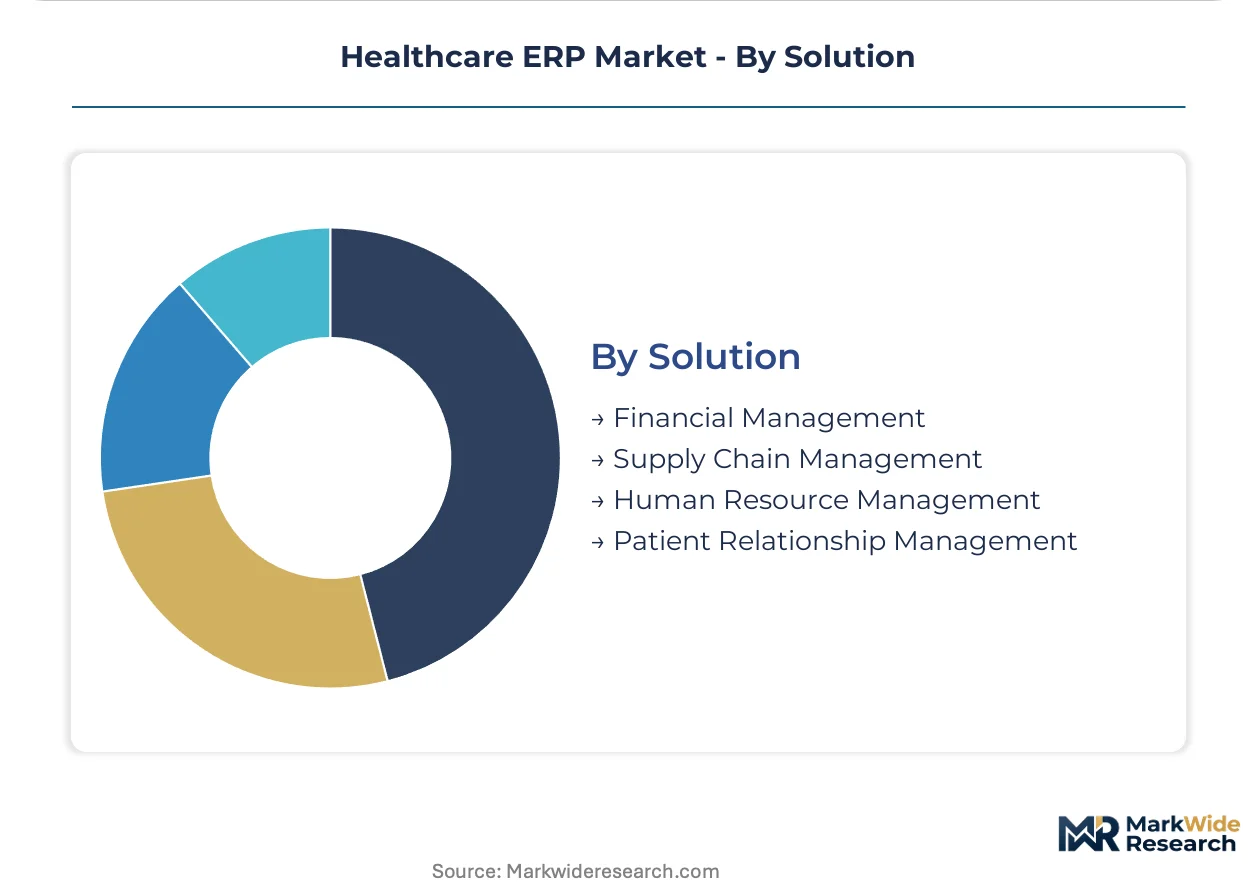
Revenue cycle pressures and consumer-directed care models are elevating patient-facing modules from administrative afterthoughts to competitive differentiators.
- Financial Management:General ledger, accounts payable, and cost accounting with healthcare-specific reimbursement rule engines. United States hospitals deploy these modules to automate Medicare Advantage risk adjustment coding.
- Supply Chain Management:Pharmaceutical track-and-trace with GS1 standards compliance, end-to-end visibility from manufacturer to patient administration, and automated procurement against formulary restrictions.
- Human Resource Management:Credentialing, scheduling, and competency tracking for clinical staff with role-based access integration.
- Patient Relationship Management:Price transparency tools, payment plan management, and automated outreach for high-deductible health plan engagement.
Financial Management leads on scale; Patient Relationship Management climbs the fastest as hospitals absorb consumer-directed care responsibilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Hospital Future Act funding accelerates ERP replacement cycles faster than Japan's regional consolidation timeline, though both markets face parallel clinical data migration constraints.
United States
Hospital networks prioritize revenue cycle automation as high-deductible health plans shift financial burden onto patients. HIPAA security rules and FDA 21 CFR Part 11 mandates dictate cloud architecture choices for clinical trial management modules. The Texas Medical Center cluster in Houston drives demand for integrated supply chain platforms that track pharmaceuticals from manufacturer to bedside.
Germany
Federal investment pools under the Hospital Future Act qualify ERP systems as core eligible expenditures for state hospital network modernization. EU AI Act conformity assessments for high-risk clinical algorithms reshape procurement criteria for university hospitals. The Berlin-Brandenburg metropolitan region concentrates deployment activity as Charité and Vivantes systems pursue phased cloud migrations.
Japan
Prefecture-level hospital group mergers create demand for unified platforms absorbing disparate legacy systems without workflow disruption. METI guidelines on healthcare data interoperability accelerate FHIR R4 adoption timelines. The Kansai region around Osaka exhibits fastest procurement velocity as regional medical associations consolidate administrative functions.
United Kingdom
NHS England's digital transformation mandates push acute trusts toward cloud-hosted patient administration systems with embedded financial management. GDPR cross-border data transfer rules complicate hosting decisions for trusts with research partnerships. The Greater Manchester health system serves as deployment testbed for integrated ERP platforms spanning multiple hospital sites.
India
Corporate hospital chains expand ERP footprints as they acquire independent nursing homes and diagnostic chains. CDSCO medical device regulations intersect with software procurement for systems embedding clinical decision support. The Delhi-NCR corridor concentrates vendor implementation activity as Max Healthcare and Apollo Hospitals standardize platforms across facilities.
Healthcare ERP Market Key Industry Players
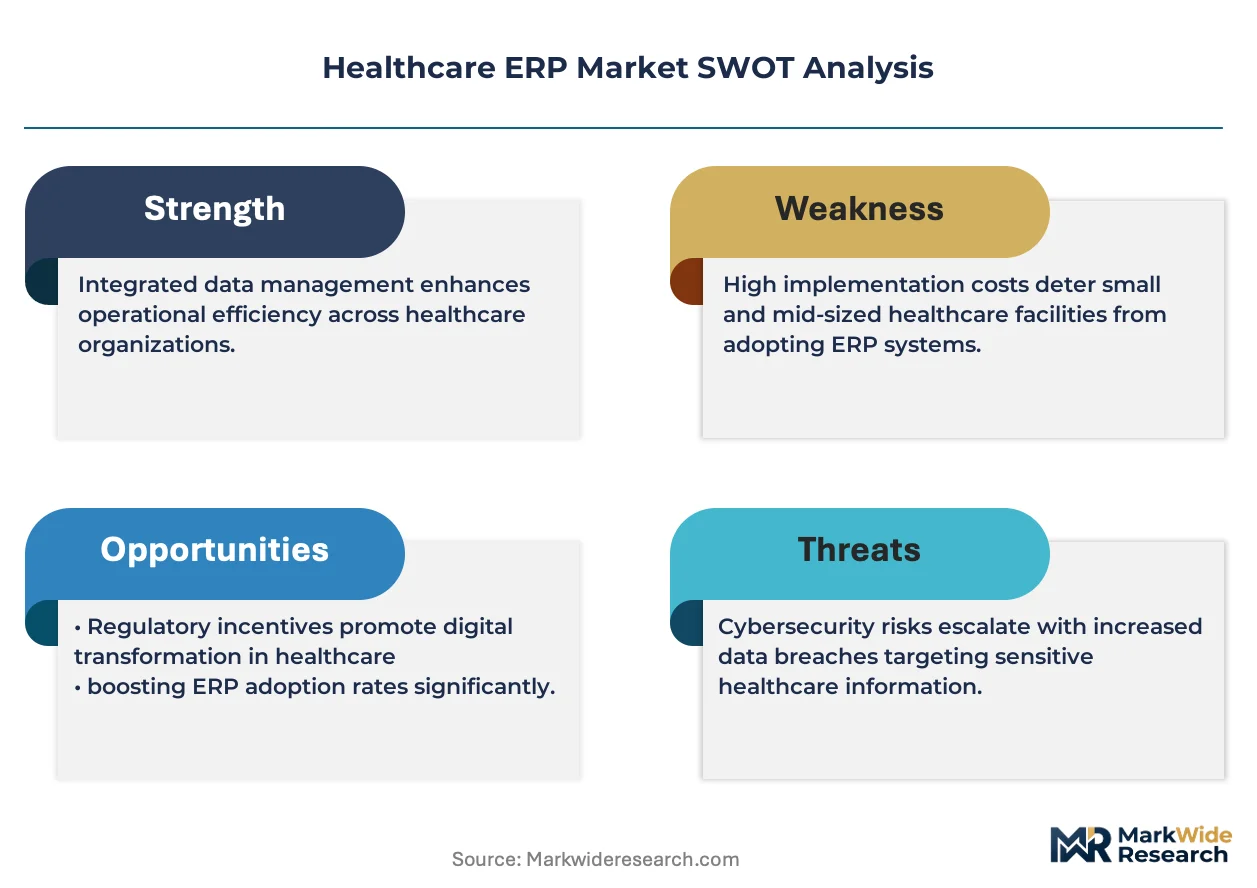
Top-tier vendors anchor large hospital network deployments, while mid-tier specialists capture clinic and laboratory segments through modular pricing. The market structure tilts toward consolidation as clinical-financial integration requirements raise barriers for point-solution providers. Three archetypes dominate: enterprise software conglomerates with healthcare verticals, dedicated healthcare IT specialists with captive interoperability frameworks, and cloud-native platforms attacking mid-market price points. Competitive moves center on M&A for clinical data assets and strategic partnerships with hyperscale cloud providers for compliant hosting infrastructure.
Among enterprise software conglomerates, Oracle and SAP occupy positions at opposite ends of the integration spectrum. Oracle exemplifies the clinical-financial consolidation archetype through its Cerner acquisition, while SAP represents supply chain management specialization extending into pharmaceutical compliance. Epic sits within the dedicated healthcare IT tier, its captive interoperability framework controlling physician workflow patterns across ambulatory and acute care settings.
| Leading Market Players |
|---|
| Oracle |
| Infor |
| SAP |
| Epic |
| Cerner |
| Meditech |
| eClinicalWorks |
| Microsoft Dynamics 365 |
| NetSuite |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up implementation specialists now control the mid-tier consulting layer that sits between ERP vendors and hospital buyers, concentrating pricing power among three hyperscale cloud providers while compressing margins for systems integrators competing on deployment speed.
Pricing Analysis
Capacity additions in Germany under the Hospital Future Act are reshaping price floors for cloud-hosted ERP modules as federal funding eligibility creates tiered procurement thresholds. Subscription-based SaaS pricing dominates new hospital deployments, with price differentiation resting on FHIR R4 certification grade and embedded EU AI Act compliance documentation. Cost compression in the mid-tier laboratory segment is intensifying because technical debt constraints force phased migration strategies. Community hospitals exhibit highest price sensitivity due to capital reserve limitations, while academic medical centers prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscale cloud infrastructure providers that dominate HIPAA-compliant hosting certifications for hospital networks. Component dependencies draw from semiconductor fabrication in Taiwan, enterprise storage systems in South Korea, and specialized healthcare compliance auditing services in the United States. Tariff exposure on cross-border data transfer infrastructure creates procurement friction for multi-national hospital systems operating across jurisdictions. Distribution runs through value-added resellers with certified HL7 implementation expertise, channel partners that bundle training and continuous compliance updates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare ERP procurement has shifted toward late-cycle quality specifications as EU AI Act conformity assessments and FDA software-as-medical-device guidance elevate compliance documentation above feature velocity in vendor selection.
For Market Incumbents: Extend clinical-financial data integration capabilities through embedded FHIR R4 APIs that lock in physician workflow patterns, while accelerating EU AI Act certification pipelines for high-risk algorithm modules. Consolidate position by acquiring specialized track-and-trace compliance vendors that serve pharmaceutical supply chain requirements. Defensive priority centers on preempting cloud-native entrants from capturing mid-tier laboratory price points through modular subscription offerings. For New Entrants and Emerging Players: Enter via Japan's prefecture-level hospital consolidation wave, where merger-driven administrative unification creates demand for legacy system absorption without workflow disruption. Target independent rural clinics in the United States seeking patient relationship management modules that automate high-deductible plan engagement. White-space opportunity concentrates on ambient documentation capabilities that compress administrative outsourcing margins. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier implementation specialists with certified HL7 consulting benches and established hospital network relationships. Long-term viability favors platforms with captive interoperability frameworks that resist point-solution disintermediation. Acquisition target archetype: cloud-native ERP vendors with embedded AI governance tooling that satisfies emerging FDA software-as-medical-device requirements. Signal to watch: FDA premarket review determinations for clinical decision support algorithms embedded in administrative modules.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Certification Investment | ONC certification requirements create 6-12 month release delays for non-compliant vendors. |
| EU AI Act Conformity Pathway | Early high-risk system classification builds competitive moats for clinical algorithm modules. |
| Hospital System Partnership | Charité and Vivantes migrations in Berlin-Brandenburg establish reference architectures. |
| Software Companion Development | Ambient documentation capabilities absorb prior authorization and denial management workflows. |
| Reimbursement Strategy Alignment | Medicare Advantage risk adjustment coding automation drives financial module prioritization. |
Research Approach
Coverage spans the United States, Germany, Japan, the United Kingdom, and India, with primary inputs from each market combining interviews with hospital CIOs, GPO contracts managers, HL7 implementation specialists, and biomedical engineers alongside secondary validation. Sources draw from CMS Medicare cost reports, NHS England procurement databases, Germany's Hospital Future Act funding disclosures, and METI healthcare interoperability guidelines. Bottom-up facility-level deployment tracking triangulates against top-down vendor revenue segmentation.
Granularity-level modeling captures deployment mode by cloud architecture type, end-user facility scale from community hospitals to academic medical centers, solution module prioritization across financial and clinical domains, and regional regulatory cluster variations. CAGRs derive from facility replacement cycle analysis, cloud migration mandate compliance timelines, and interoperability standard adoption curves across the projection horizon. Industry-specific inputs include HL7 FHIR R4 implementation velocity and EU AI Act enforcement phase-in assumptions.
Inputs from hospital procurement databases and vendor implementation pipelines were available through the study window; gaps in private-cloud infrastructure cost disclosures and legacy mainframe data extraction pricing introduce uncertainty bands around hybrid deployment forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Healthcare Information Governance Solution Market