
 Medical Information Market | 2026-2036
Medical Information Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Information Market Intelligence
Medical inquiry management revenue is fragmenting across traditional call center operations and AI-enabled self-service platforms. IQVIA leverages its real-world evidence infrastructure to capture higher-margin analytics contracts. Parexel International Corporation anchors its position through specialized medical information services tied to clinical development programs. McKesson Corporation competes via distribution-linked data access that pharmaceutical clients find difficult to replicate internally.
Medical information encompasses the collection, processing, and dissemination of scientifically accurate data about pharmaceutical products to healthcare professionals and patients, typically operating through structured databases with audit trails and response documentation protocols. Pharmacovigilance software commands the largest share of product type spending due to mandatory adverse event reporting requirements across jurisdictions. Cloud-based delivery is expanding fastest among deployment modes as biotech firms prioritize scalable infrastructure without capital-intensive on-premises investments. Contract research organizations represent a concentrated demand pocket within end users, driven by sponsor companies outsourcing medical information responsibilities to control operational costs.
FDA, EMA, and ISO 14155 standards collectively govern medical information accuracy, pharmacovigilance timelines, and clinical trial disclosure obligations. FDA mandates 24-hour adverse event intake capabilities, while EMA's Good Pharmacovigilance Practices specify medical query response documentation standards that shape platform design requirements. Stakeholders must evaluate whether to build compliant infrastructure internally or partner with vendors whose systems already satisfy multi-jurisdictional regulatory audits.
Market Dynamics
Pharmaceutical data governance mandates are compressing technology refresh cycles, forcing vendors to rebuild platforms around real-time compliance verification rather than retrospective audit readiness. This structural pressure is redistributing competitive advantage toward infrastructure providers with pre-certified multi-jurisdictional deployments.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail requirements are mandating platform upgrades across sponsor organizations, creating replacement demand for legacy document management systems.
- Biotech outsourcing surge:Venture-funded biotech firms without internal pharmacovigilance infrastructure are contracting specialized medical information services to preserve capital for clinical development.
- Cloud-native architecture:API-first platforms with serverless adverse event processing are capturing market share from monolithic on-premises installations.
Market Restraints
- Validation cost inflation:Computerized system validation for FDA-compliant platforms consumes 18-24 months of implementation timelines, extending sales cycles.
- Talent scarcity in Japan:Bilingual medical information specialists with PMDA submission experience command premium compensation, constraining service expansion.
- Data residency fragmentation:China's NMPA data localization requirements and GDPR cross-border transfer rules are forcing redundant infrastructure investments.
Strategic Opportunities
- Real-world evidence integration:Linking medical inquiry databases with IQVIA or Flatiron health record repositories creates differentiated analytics offerings.
- Germany's E-Health Act:Electronic prescription mandates and digital health application reimbursement pathways are expanding addressable market for patient-facing information platforms.
- Generative AI documentation:Large language models trained on EMA Q&A repositories are compressing medical query response drafting from hours to minutes.
Industry Challenges
- ISO 14155 clinical trial disclosure:Synchronizing medical information systems with trial registry updates requires complex EDC-CTMS-MI platform integration.
- Adverse event source proliferation:Social media monitoring, wearable device streams, and patient support program calls are overwhelming traditional intake workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Information Market |
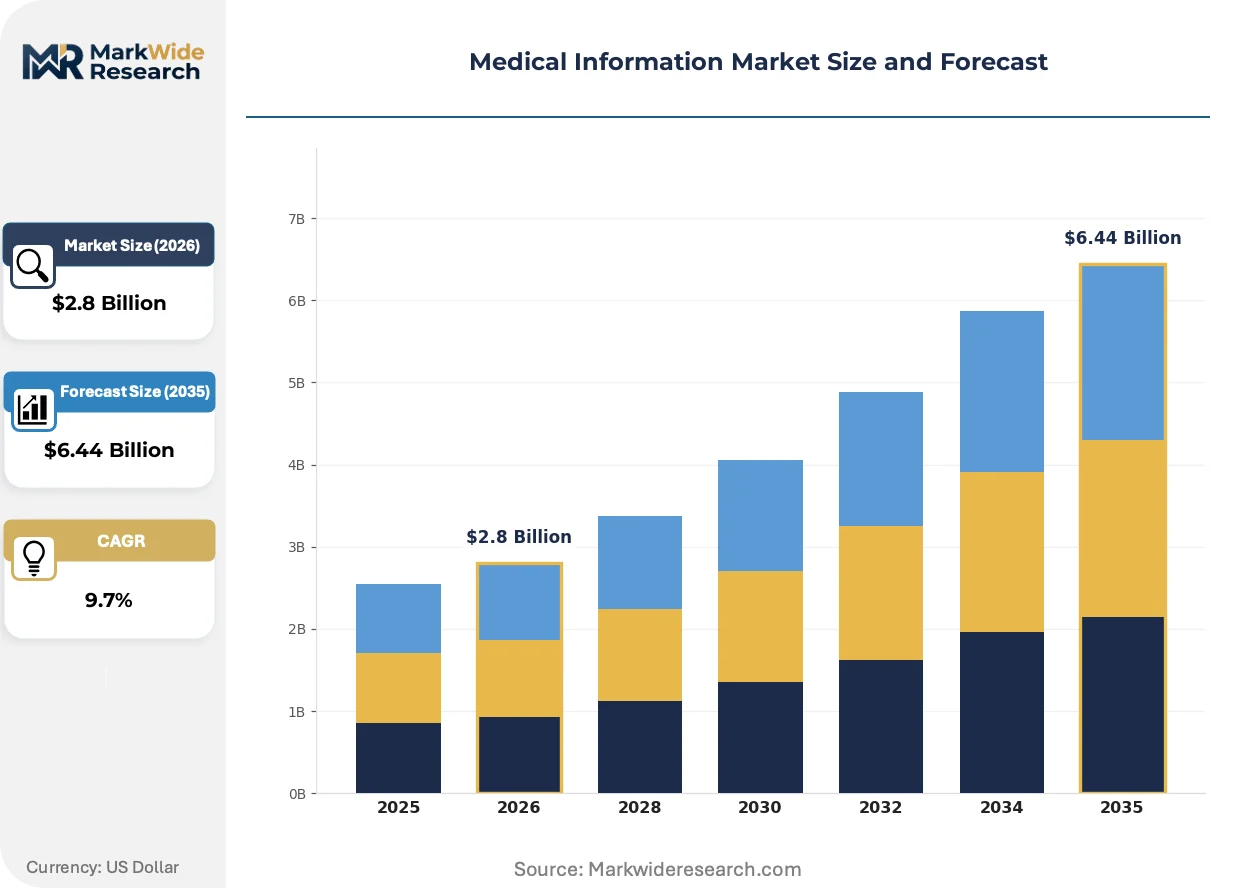
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management Tools, Pharmacovigilance Software, Content Management Systems, Knowledge Management Solutions End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Delivery Mode: Web-Based, Cloud-Based, On-Premises, Mobile Applications Application: Clinical Trials, Regulatory Compliance, Market Access, Medical Affairs |
| Companies Covered | IQVIA, Parexel International Corporation, McKesson Corporation, Accenture plc, C3i Solutions, ProPharma Group, Cognizant, Infosys Limited, PrimeVigilance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Information Market Strategic Shifts & Innovations
Automation is penetrating the traditionally labor-intensive medical inquiry response workflow, with natural language processing and generative systems compressing documentation timelines while regulators simultaneously tighten accountability standards for AI-assisted outputs.
Large language models trained on proprietary pharmacovigilance case databases are rendering obsolete the manual drafting of standard response letters for frequently asked medical queries. Mid-tier contract research organizations with limited medical writing staff are deploying these systems most aggressively. The technology is rendering obsolete the historical tradeoff between response speed and scientific accuracy, collapsing both into simultaneous delivery.
EMA's evolving Good Pharmacovigilance Practices documentation standards are mandating structured data capture for every healthcare professional interaction, not merely adverse events. This regulatory expansion is forcing platform vendors to rebuild query management modules around HL7 FHIR interoperability frameworks. Specialized medical information service providers serving European markets are absorbing disproportionate compliance engineering costs.
Healthcare professionals are demanding multimodal response formats beyond traditional telephone and email channels, with secure messaging platforms and embedded video explanations gaining preference. Pharmaceutical medical information departments are unbundling response delivery from content creation, contracting specialized digital communication vendors. This behavioral shift is most pronounced in United States academic medical centers where physician time constraints are most severe.
Medical Information Market Segmentation
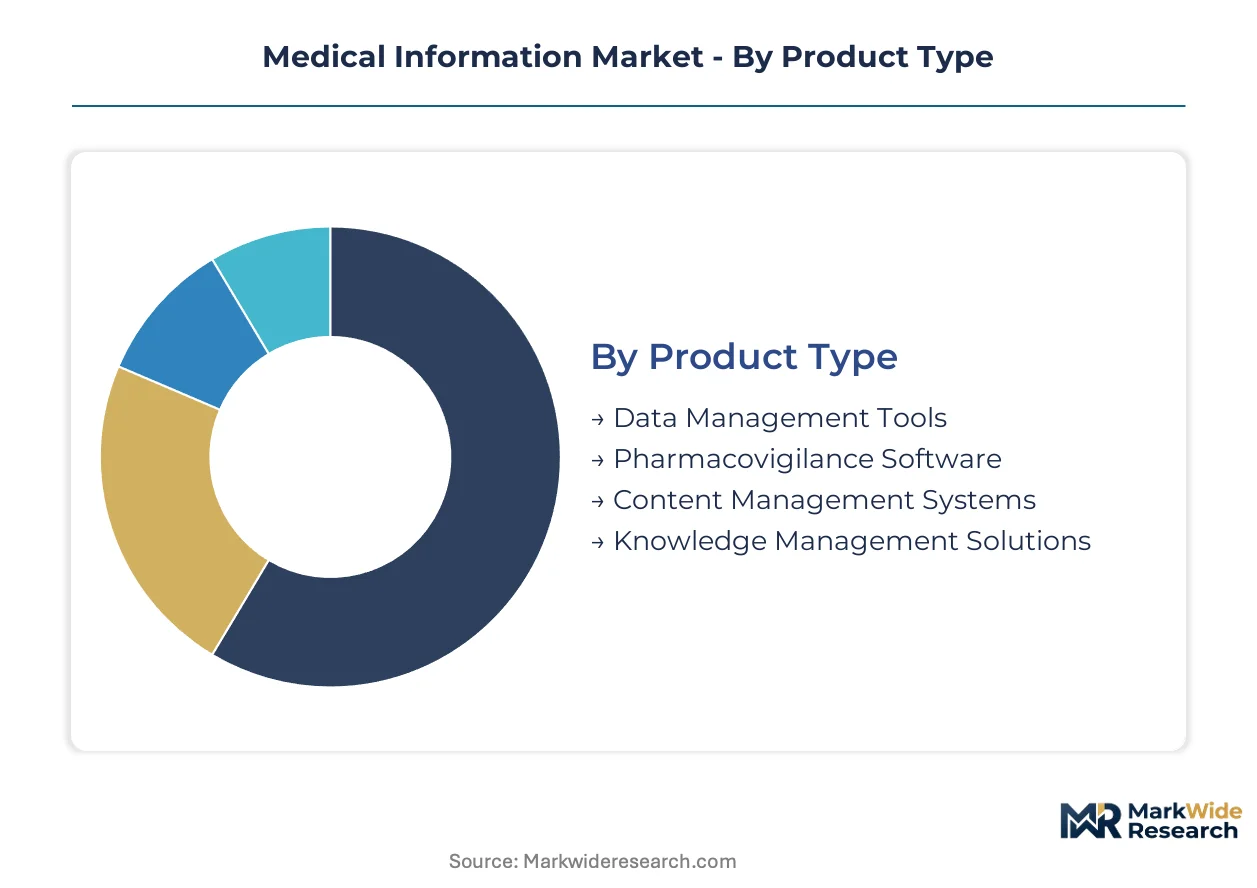
Medical information platforms serve divergent operational requirements across pharmacovigilance, clinical disclosure, and healthcare professional engagement. Segment boundaries reflect regulatory workflow specialization rather than generic software categorization.
Product Type:
Deployment complexity spans from adverse event processing engines to document repositories, with each product category addressing distinct compliance verification chains.
- Pharmacovigilance Software:Adverse event intake, case processing, and regulatory reporting modules form the technical backbone of mandatory pharmacovigilance obligations. FDA 24-hour intake mandates and EMA Good Pharmacovigilance Practices documentation standards concentrate procurement among sponsor organizations with multi-jurisdictional portfolios. Validation timelines of 18-24 months lock in vendor relationships once established.
- Knowledge Management Solutions:Structured response libraries with HL7 FHIR interoperability enable healthcare professional query resolution with full audit trails. Germany's E-Health Act electronic prescription pathways and academic medical center demand in the United States are accelerating platform refresh cycles toward API-first architectures.
- Data Management Tools:Clinical trial disclosure synchronization with EDC and CTMS systems addresses ISO 14155 obligations.
- Content Management Systems:Document versioning with electronic signature capabilities satisfies FDA 21 CFR Part 11 requirements.
Established volume favors pharmacovigilance software; emerging adoption favors knowledge management solutions.
End User:
Organizational scale and capital availability determine whether medical information infrastructure is built internally or contracted to specialized service providers.
- Contract Research Organizations:Outsourced medical information responsibilities allow sponsor companies to convert fixed costs into variable spend while accessing pre-validated platforms. IQVIA and Parexel capture concentrated demand from venture-funded biotech firms preserving capital for clinical development. Talent scarcity in Japan constrains service expansion despite PMDA submission experience premiums.
- Pharmaceutical Companies:Large-cap sponsors maintain captive medical information departments with direct regulatory accountability, though cloud migration is unbundling infrastructure ownership from operational execution. McKesson's distribution-linked data access creates replication barriers for internal builds.
- Biotechnology Firms:Venture-funded entities without pharmacovigilance infrastructure represent the fastest-expanding contract service demand pool.
- Research Institutions:Academic medical centers in the United States drive multimodal response format requirements beyond traditional telephone and email channels.
Pharmaceutical companies anchor current procurement volume; biotechnology firms represent the steepest expansion trajectory.
Delivery Mode:
Capital intensity and scalability requirements shape deployment architecture preferences across the user base.
- Cloud-Based:Serverless adverse event processing and API-first platforms eliminate capital-intensive on-premises investments while enabling real-time compliance verification. Biotech prioritization of scalable infrastructure without fixed asset commitment is redistributing competitive advantage toward pre-certified multi-jurisdictional deployments. China's NMPA data localization and GDPR cross-border transfer rules force redundant infrastructure investments that partially offset cloud economics.
- Web-Based:Browser-accessible platforms with lower implementation friction serve mid-tier CROs with limited IT engineering resources.
- On-Premises:Monolithic installations persist among sponsors with legacy validation investments and restrictive data residency policies.
- Mobile Applications:Secure messaging platforms address physician time constraints in United States academic medical centers.
Cloud-based delivery is gaining share fastest; on-premises retention reflects regulatory inertia rather than preference.
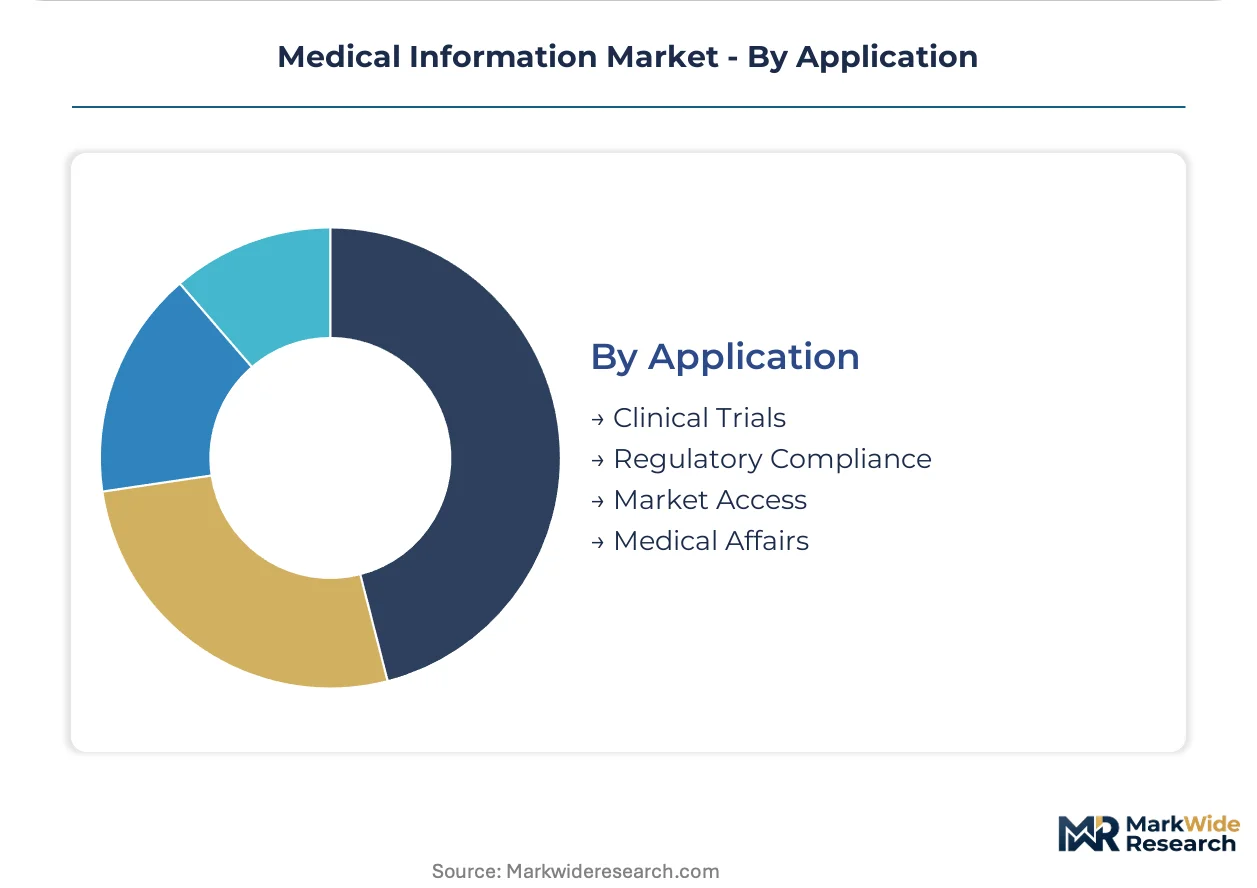
Application:
Functional modules align with distinct stakeholder workflows across the product lifecycle.
- Regulatory Compliance:FDA 21 CFR Part 11 electronic signature requirements and EMA evolving data integrity guidelines mandate platform capabilities spanning audit trails, version control, and access logging. Technology refresh cycles compress as governance mandates shift from retrospective audit readiness to real-time verification.
- Medical Affairs:Healthcare professional query management with structured response documentation addresses EMA expansion of capture requirements beyond adverse events to all interactions. Generative AI documentation trained on EMA Q&A repositories is compressing response drafting timelines.
- Clinical Trials:ISO 14155 disclosure synchronization requires complex EDC-CTMS-MI platform integration.
- Market Access:Real-world evidence integration with health record repositories creates differentiated analytics offerings.
Regulatory compliance commands current platform investment; medical affairs is climbing the fastest as interaction capture obligations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical information platform consumption diverges sharply across geographies: United States sponsors prioritize real-time compliance verification, while German and Japanese markets emphasize structured documentation protocols and bilingual specialist networks respectively.
United States
FDA 21 CFR Part 11 mandates drive replacement demand for legacy document management systems across sponsor organizations. Academic medical centers in Boston and New York Metro are unbundling response delivery from content creation, contracting specialized digital communication vendors to address physician time constraints.
Germany
The E-Health Act electronic prescription pathways expand addressable market for patient-facing information platforms. EMA Good Pharmacovigilance Practices documentation standards shape platform design requirements, with Frankfurt and Munich clusters absorbing disproportionate compliance engineering costs for HL7 FHIR interoperability frameworks.
Japan
PMDA submission experience premiums constrain service expansion despite concentrated demand from multinational sponsors. Bilingual medical information specialists command compensation premiums in Tokyo and Osaka, creating talent scarcity that limits platform vendor market penetration.
China
NMPA data localization requirements force redundant infrastructure investments that partially offset cloud economics. Domestic biotech firms in Shanghai and Beijing prioritize scalable infrastructure without capital-intensive on-premises commitments, redistributing procurement toward pre-certified multi-jurisdictional deployments.
United Kingdom
EMA regulatory alignment post-Brexit creates dual compliance obligations for sponsors maintaining European market access. London and Cambridge life sciences clusters are outsourcing medical information responsibilities to preserve capital for clinical development, accelerating contract research organization platform adoption.
Medical Information Market Key Industry Players
Capability concentration sits with specialized pharmacovigilance service providers; scale advantage sits with diversified healthcare technology conglomerates. The market structures around three tiers: integrated contract research organizations with pre-validated platforms, distribution-linked data access providers, and IT services firms with healthcare verticals. Dominant competitive moves include strategic partnerships with real-world evidence data repositories and geographic expansion through regulatory pre-certification in multiple jurisdictions.
Within the integrated CRO tier, IQVIA and Parexel International Corporation exemplify archetypes combining clinical development infrastructure with medical information service delivery. McKesson Corporation anchors the distribution-linked data access segment, occupying a position where pharmaceutical clients face replication barriers for internal builds. These three entities represent distinct competitive vectors: real-world evidence integration, specialized medical information services, and supply chain data monetization respectively.
| Leading Market Players |
|---|
| IQVIA |
| Parexel International Corporation |
| McKesson Corporation |
| Accenture plc |
| C3i Solutions |
| ProPharma Group |
| Cognizant |
| Infosys Limited |
| PrimeVigilance |
| Others |
Cost & Logistics Intelligence
Regulatory validation chokepoints in FDA 21 CFR Part 11 and EMA Good Pharmacovigilance Practices determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic distribution of pre-certified platform providers. Single-source dependencies on bilingual medical information specialists in Japan and HL7 FHIR engineering talent in Germany compress margins while inflating implementation timelines.
Pricing Analysis
Long-term subscription contracts dominate procurement, with SaaS-tiered pricing stratifying across validation depth, jurisdictional coverage, and real-time compliance verification capabilities. Price differentiation rests on FDA pre-certification status, EMA audit readiness, and specialist staffing ratios in Tokyo and Frankfurt. Cost compression in mid-tier knowledge management solutions is intensifying because venture-funded biotech firms prioritize capital preservation over feature depth. Biotechnology firms exhibit highest price sensitivity; large-cap pharmaceutical sponsors accept premium tiers for multi-jurisdictional coverage.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers in the United States, Germany, and Japan, with serverless adverse event processing modules drawing from specialized compliance engineering clusters. Raw material dependencies include HL7 FHIR interoperability frameworks, proprietary pharmacovigilance case databases, and generative AI training corpora. Single-source vulnerability concentrates in bilingual PMDA submission specialists and EMA Q&A repository access. Distribution runs through contract research organization platforms, direct pharmaceutical procurement channels, and biotech venture capital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-certified multi-jurisdictional deployment capability sits as the scarcest asset, with 18-24 month validation timelines locking out challengers and concentrating margin capture among established vendors.
For Market Incumbents: Entrench platform positions by acquiring HL7 FHIR engineering capacity in Frankfurt and Munich clusters before compliance engineering costs escalate further. Anchor defensive moats through exclusive real-world evidence data partnerships with health record repositories, neutralizing the substitute threat from AI-native documentation startups.
For New Entrants and Emerging Players: China's domestic biotech corridor offers the most penetrable geography, where NMPA data localization requirements have forced redundant infrastructure investments that incumbent cloud providers struggle to optimize. Target mid-tier contract research organizations in Shanghai and Beijing with API-first platforms priced below validated Western alternatives. Capture initial referenceability through project-based pharmacovigilance module deployments.
For Investors and Strategic Acquirers: The market sits at a compliance-engineering investment phase that favors vertically integrated service providers with captive validation expertise. Long-term viability hinges on regulatory pre-certification breadth rather than feature innovation velocity. Watch EMA documentation standard expansion as the inflection signal for knowledge management solution demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Expansion | FDA 21 CFR Part 11 and EMA GVP compliance creates non-replicable platform differentiation. |
| Real-World Evidence Data Partnership | IQVIA and Flatiron health record access enables differentiated analytics offerings for medical affairs. |
| Generative AI Documentation Deployment | Large language models trained on EMA Q&A repositories compress medical query response timelines. |
| Bilingual Specialist Network Buildout | PMDA submission experience in Tokyo and Osaka commands premium compensation and constrains competitor expansion. |
| Cloud-Native Architecture Migration | Serverless adverse event processing eliminates capital-intensive on-premises investments for biotech clients. |
Research Approach
The analysis maps pharmacovigilance software, knowledge management solutions, data management tools, and content management systems, each validated through medical information directors, regulatory affairs leads, pharmacovigilance officers, and biotech C-suite executives. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA GVP inspection reports, ClinicalTrials.gov disclosure records, and ISO 14155 audit documentation. Bottom-up platform deployment counts triangulated against top-down pharmaceutical R&D spend allocations.
Assumptions held fixed include FDA 24-hour adverse event intake mandates, EMA expanding interaction capture requirements, and cloud infrastructure cost curves across the analysis window. Segmentation dimensions modeled span product type, end user organizational scale, delivery mode architecture, and application workflow. CAGRs derived from regression against historical platform procurement cycles and regulatory refresh timelines. Forecast inputs incorporated biotech venture funding velocity and CRO outsourcing penetration rates.
Macroeconomic conditions sit as an overlay; deviation in biotech capital availability, hyperscaler pricing, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against IQVIA and Parexel public disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Medical Software Market