
 Global Medical Writing Market | 2026-2036
Global Medical Writing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Writing Market Foresight
The shift from in-house medical writing teams toward outsourced and hybrid delivery models is hardening across the biopharmaceutical sector. IQVIA leverages its integrated data and writing capabilities to anchor large-scale regulatory submission projects for multinational sponsors. Parexel International Corporation sustains competitive positioning through deep therapeutic specialization in oncology and rare disease documentation. Cactus Communications differentiates by operating a scalable freelance network that addresses mid-tier biotech demand for cost-efficient publication support.
Medical writing encompasses the specialized creation of clinical, regulatory, and scientific documents governed by strict formatting standards such as ICH E3 guidelines for clinical study reports and CDISC-compliant data presentation. Its primary commercial purpose is enabling pharmaceutical and device developers to secure regulatory approvals, publish peer-reviewed evidence, and communicate product value to healthcare stakeholders. Regulatory writing commands the largest service-type revenue pool due to the non-discretionary nature of FDA, EMA, and NMPA submission requirements. Publication writing represents the fastest-expanding segment as open-access mandates and real-world evidence programs multiply journal submission volumes. The oncology therapy area dominates segment demand, driven by the complexity of immuno-oncology trial designs and the proliferation of breakthrough therapy designations requiring accelerated documentation cycles.
FDA's Project Optimus and EMA's updated clinical trial regulation are reshaping protocol documentation standards, directly expanding scope for dose-optimization and adaptive trial writers. The EU AI Act and FDA guidance on machine learning in drug development are creating new compliance categories for algorithm transparency documentation that medical writing teams must address. Stakeholders should monitor how decentralized trial frameworks and synthetic control arm methodologies alter the evidentiary formats that regulators will accept for marketing authorization.
Market Dynamics
The medical writing market is undergoing structural compression as regulatory documentation requirements expand faster than sponsor headcount, forcing pharmaceutical companies to externalize specialized writing functions or automate routine outputs.
Growth Catalysts
- FDA Project Optimus:The dose-optimization mandate expands protocol documentation scope for oncology and rare disease trials, creating sustained demand for adaptive trial writers.
- Immuno-oncology complexity:Breakthrough therapy designations compress submission timelines while multiplying the volume of safety narratives and integrated summaries required per application.
- EU AI Act transparency requirements:Algorithm documentation for machine learning-enabled drug development creates new compliance categories that medical writing teams must address.
Market Restraints
- Talent scarcity in rare disease specialization:The shallow pool of writers with gene therapy and orphan drug expertise concentrates supply in Boston and Basel, inflating project rates.
- CDISC implementation costs:Smaller biotech sponsors face capital barriers to building compliant data presentation capabilities, delaying outsourcing decisions.
- Regulatory divergence:Misalignment between FDA guidance on decentralized trials and EMA's clinical trial regulation fragments document templates, raising compliance overhead.
Strategic Opportunities
- Synthetic control arm documentation:External comparator methodologies accepted by FDA and EMA require novel evidentiary formats that established writers can productize.
- Real-world evidence programs:Post-approval study mandates in the US and EU multiply publication planning and health economics writing volumes.
- Japan's PMDA globalization:The regulator's expanded English-language submission pathway opens access for Western medical writing providers.
Industry Challenges
- Legacy system integration:Medical writing platforms must interface with sponsor document management systems that span decades of technical debt, extending deployment timelines.
- Certification bottlenecks:ISO 27001 and SOC 2 Type II audits for handling patient-level data delay vendor onboarding by quarters, compressing project windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Writing Market |
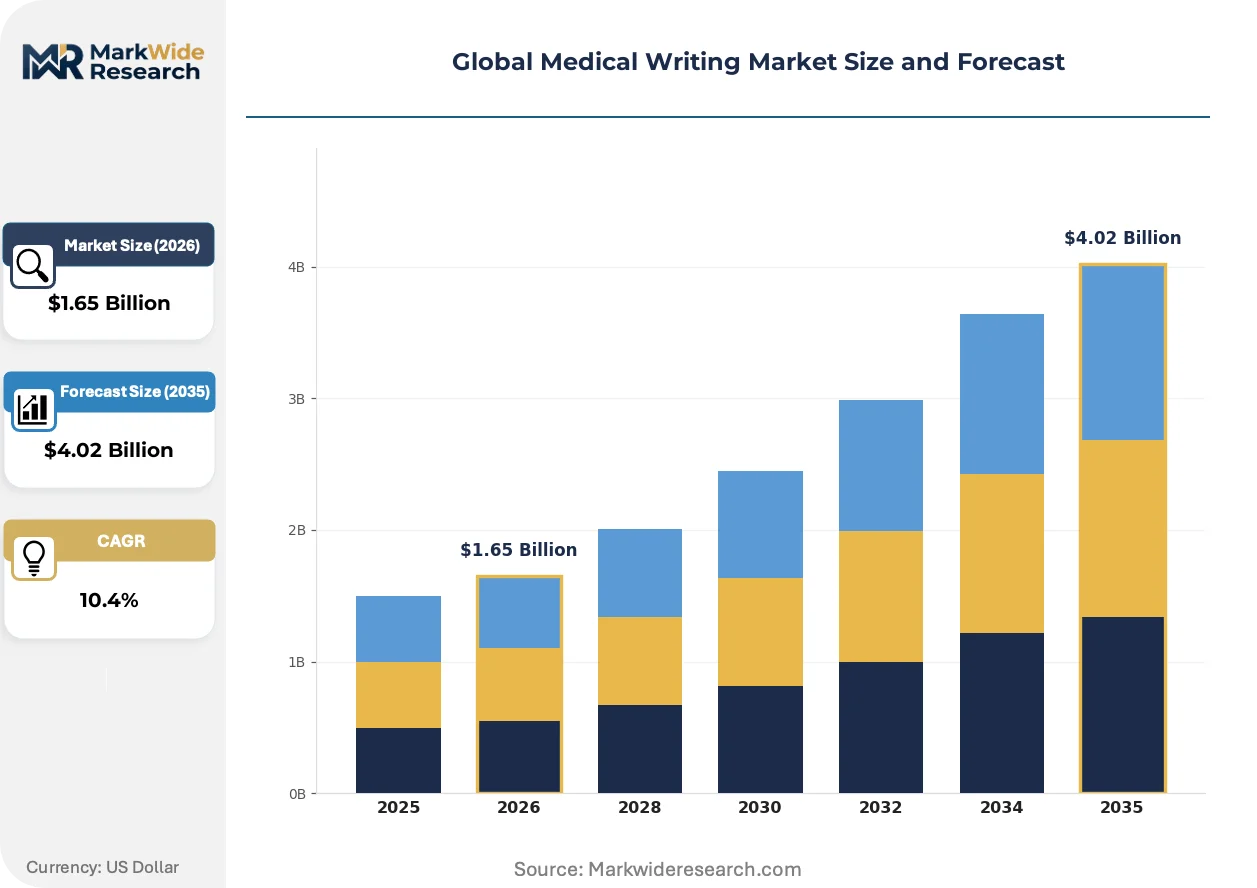
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $4.02 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regulatory Writing, Publication Writing, Medical Communications, Promotional Writing, Clinical Research Writing Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases, Endocrinology, Dermatology End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Medical Device Manufacturers, Academic Institutions Delivery Mode: In-house, Outsourced, Hybrid Model, Freelance Services |
| Companies Covered | Syneos Health, Freyr Solutions, IQVIA, Cactus Communications, Trilogy Writing & Consulting, Parexel International Corporation, MMS Holdings, Labcorp Drug Development, ICON plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Writing Market Shifts & Advancements
Generative AI is penetrating medical writing workflows at the sentence and section level, automating first drafts of routine documents while human writers concentrate on strategic narrative construction and regulatory negotiation.
Natural language generation tools trained on ICH E3-compliant clinical study reports is consolidating the market structure around hybrid delivery models. Large CROs deploy these systems for standard safety narratives, reducing cycle times for routine outputs. The technology is consolidating competitive advantage among vendors with proprietary training data and validation frameworks that satisfy FDA software-as-medical-device scrutiny.
EMA's updated clinical trial regulation and the EU AI Act are converging to mandate algorithmic transparency in submissions involving machine learning. Sponsors must now produce interpretability documentation alongside traditional efficacy data. Oncology and rare disease applications face the steepest compliance ramps as these modalities increasingly incorporate AI-driven biomarker discovery.
Biotech procurement patterns are fragmenting as mid-tier sponsors unbundle writing services from full-service CRO relationships. Direct contracts with specialized medical writing boutiques are displacing bundled regulatory packages. This pattern is most visible in the San Francisco and Cambridge clusters where venture-backed sponsors prioritize cost transparency and therapeutic expertise over institutional scale.
Global Medical Writing Market Segmentation
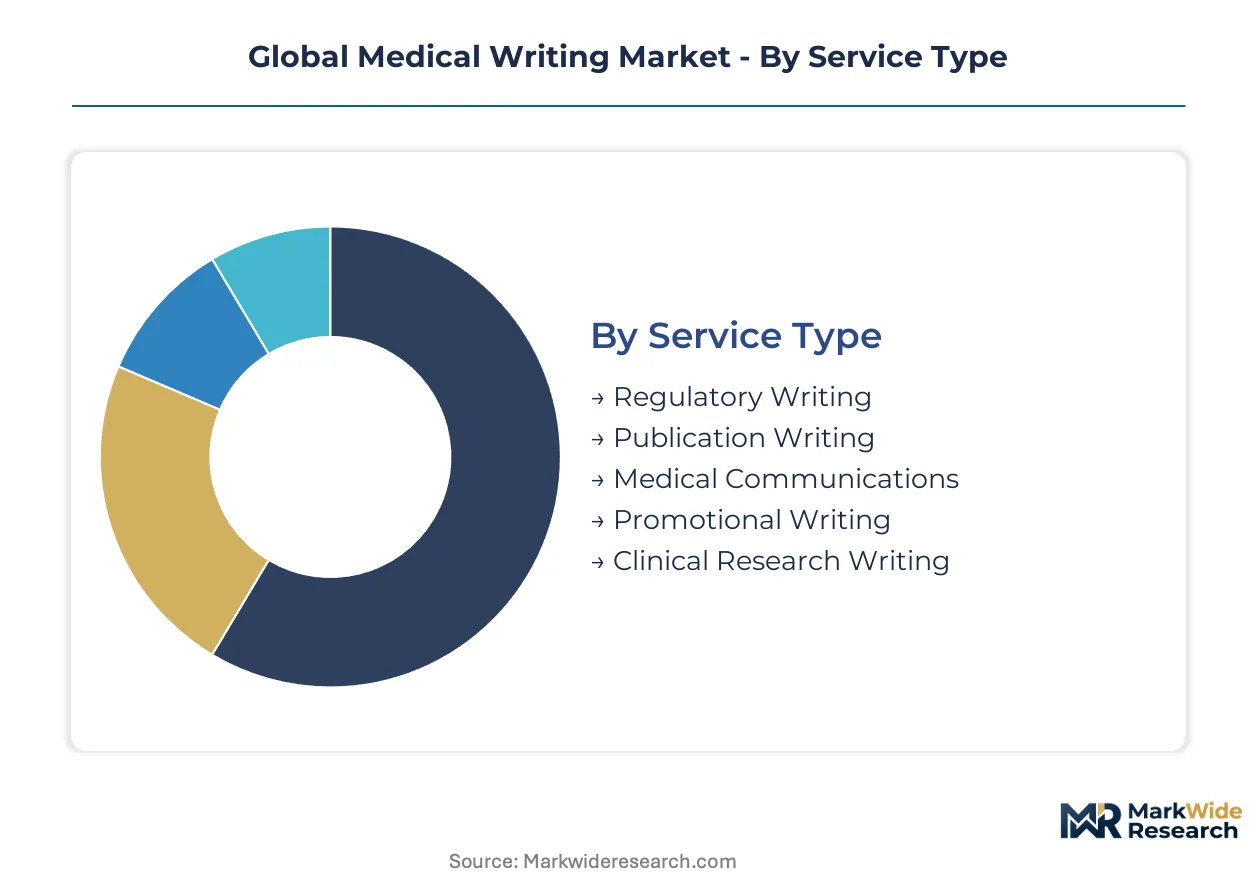
Medical writing segmentation reveals how compliance burdens concentrate revenue across service types while therapeutic complexity reshapes capability requirements. Understanding these divisions exposes where certification investments and talent scarcity create sustainable competitive moats.
Service Type:
FDA submission requirements and EMA clinical trial regulations impose distinct certification burdens across service categories, with regulatory documentation demanding ISO 27001 validation while publication services face less stringent data handling protocols.
- Regulatory Writing:Clinical study reports, investigational new drug applications, and marketing authorization submissions formatted to ICH E3 and CDISC standards. Pharmaceutical sponsors in the United States and Germany concentrate procurement here due to non-negotiable FDA and EMA compliance deadlines that internal teams cannot scale to meet.
- Publication Writing:Manuscripts, abstracts, and poster presentations for peer-reviewed journals. Mid-tier biotechnology firms in Cambridge and San Francisco drive outsourcing volume as open-access mandates from NIH and Wellcome Trust multiply submission targets without expanding headcount.
- Medical Communications:Educational materials for healthcare professionals and patient advocacy groups.
- Promotional Writing:Regulatory-compliant marketing copy for approved therapeutics.
- Clinical Research Writing:Protocol documents, informed consent forms, and investigator brochures.
Regulatory Writing sits at the top of the volume ranking, with Publication Writing climbing the fastest.
Therapy Area:
Oncology documentation commands premium pricing due to breakthrough therapy designation timelines and immuno-oncology protocol complexity, while cardiovascular and endocrinology segments operate on standardized templates with compressed margins.
- Oncology:Adaptive trial protocols, dose-escalation narratives, and integrated safety summaries for checkpoint inhibitors and CAR-T therapies. Sponsors in Boston and Basel concentrate demand as FDA Project Optimus mandates expand documentation scope for dose-optimization studies.
- Neurology:Complex endpoint documentation for Alzheimer's and Parkinson's trials with subjective outcome measures. The shallow pool of writers familiar with FDA guidance on novel surrogate endpoints in neurodegenerative disease inflates project rates in New Jersey and Basel.
- Cardiovascular:Large outcomes trial documentation with established statistical analysis plans.
- Infectious Diseases:Antiviral and antibiotic trial protocols with standardized regulatory pathways.
- Endocrinology:Diabetes and obesity trial documentation following well-established FDA guidance.
- Dermatology:Topical and systemic therapy protocols with moderate regulatory complexity.
Oncology captures the largest revenue share, with Neurology expanding most quickly due to gene therapy submissions.
End User:
Procurement sophistication varies sharply across end users, with multinational pharmaceutical companies demanding SOC 2 Type II validation while academic institutions prioritize cost efficiency over certification depth.
- Pharmaceutical Companies:Full-spectrum regulatory and publication services for blockbuster drug portfolios. Headquarters clusters in New Jersey, Basel, and Tokyo generate concentrated demand for integrated submission packages spanning FDA, EMA, and PMDA requirements.
- Biotechnology Firms:Specialized rare disease and gene therapy documentation with compressed timelines. Venture-backed sponsors in Cambridge and South San Francisco unbundle writing from full-service CRO relationships to secure therapeutic expertise.
- Contract Research Organizations:White-label medical writing capacity for sponsor clients.
- Medical Device Manufacturers:EU MDR technical documentation and FDA 510(k) submissions.
- Academic Institutions:Grant applications and investigator-initiated trial protocols.
Pharmaceutical Companies anchor procurement volume, with Biotechnology Firms gaining share fastest through direct boutique contracts.
Delivery Mode:
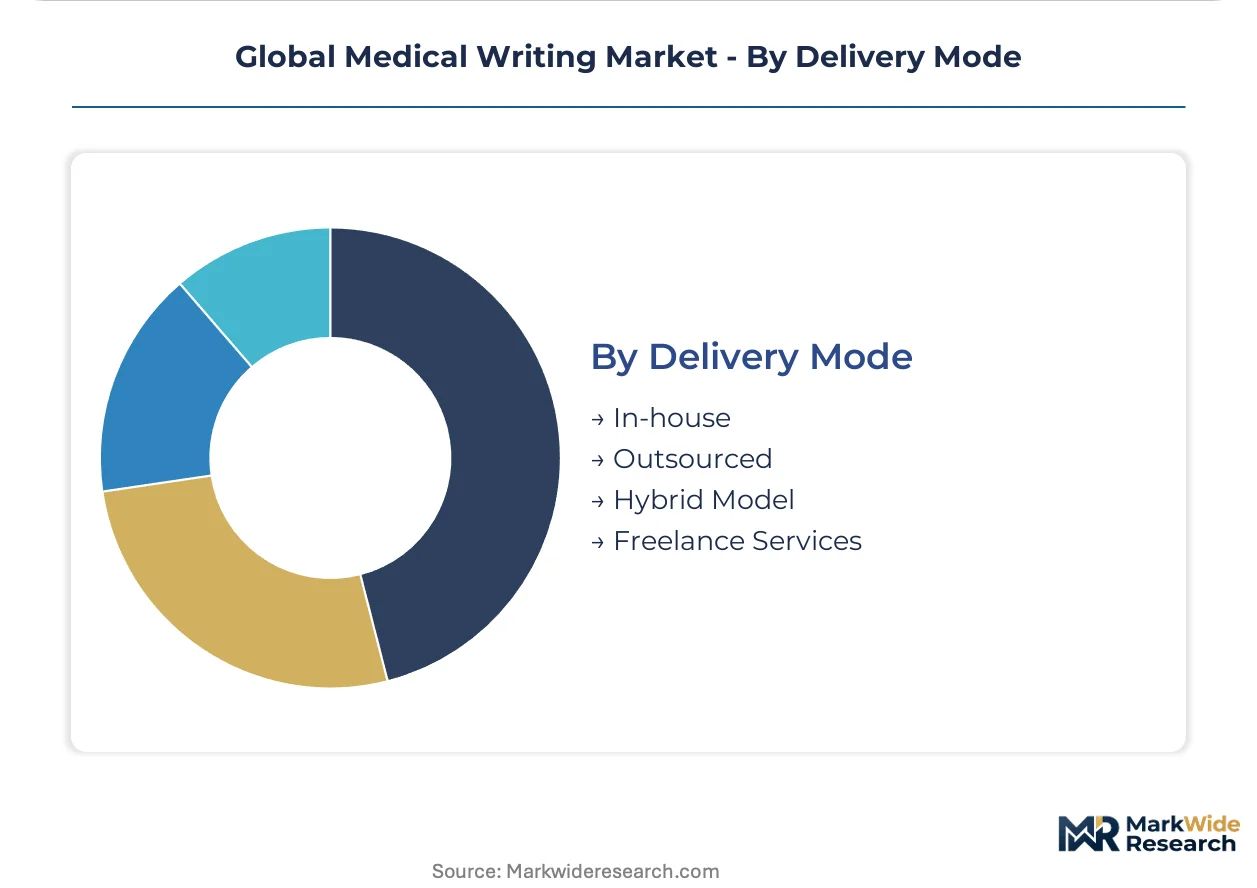
Data security requirements fragment delivery options, with in-house models requiring HIPAA-compliant infrastructure investments that smaller sponsors cannot justify.
- In-house:Captive medical writing teams integrated with clinical and regulatory functions. Large pharmaceutical companies in Switzerland and the United States maintain these structures for core oncology and rare disease assets where narrative control outweighs cost efficiency.
- Outsourced:Dedicated contracts with specialized medical writing agencies or CRO writing divisions. This model dominates mid-market biotechnology procurement in the United Kingdom and Germany as sponsors prioritize flexibility over fixed costs.
- Hybrid Model:Strategic writers retained in-house with surge capacity outsourced.
- Freelance Services:Direct contracts with individual medical writers through platforms.
Outsourced delivery holds the volume lead, with Hybrid Models ascending fastest as sponsors rebalance after pandemic-era overextension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement geography as sponsors migrate documentation work toward jurisdictions with streamlined compliance pathways and specialized talent pools. Cost-of-compliance gaps between the United States and emerging hubs are accelerating vendor diversification strategies.
United States
FDA submission volumes and breakthrough therapy designation timelines drive concentrated demand for regulatory writers in the Boston-Cambridge and San Francisco corridors. The agency's Project Optimus dose-optimization mandates expand documentation scope for oncology trials. New Jersey and Maryland host dense clusters of pharmaceutical headquarters outsourcing integrated submission packages.
Germany
EMA centralized procedures and the EU AI Act's algorithmic transparency requirements sustain demand for specialized medical writing services in Frankfurt and Munich. The country's medical device manufacturers face expanded EU MDR technical documentation burdens. Heidelberg and Berlin emerge as hubs for rare disease documentation expertise serving European sponsors.
Switzerland
Swissmedic's alignment with EMA procedures and Basel's pharmaceutical headquarters concentration create premium demand for regulatory writers. The country's gene therapy and orphan drug specialists command elevated project rates. Zurich and Geneva host boutique agencies serving mid-tier biotechnology firms with compressed timelines.
United Kingdom
MHRA's post-Brexit regulatory independence and London's CRO concentration sustain outsourcing volume for publication and medical communications services. The country's academic medical centers drive investigator-initiated trial documentation demand. Cambridge and Oxford clusters specialize in early-phase protocol writing for biotechnology sponsors.
Japan
PMDA's expanded English-language submission pathway opens procurement opportunities for Western medical writing providers in Tokyo and Osaka. The regulator's globalization initiative reduces language barriers for multinational sponsors. Yokohama's pharmaceutical manufacturing base generates demand for localized regulatory documentation support.
Global Medical Writing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented delivery models and rare disease specialization. The market structure consolidates around three maturity tiers: integrated CRO divisions with captive pharmaceutical relationships, specialized medical writing boutiques with therapeutic depth, and platform-based freelance networks addressing cost-sensitive mid-market demand. Dominant competitive moves include strategic partnerships with data analytics providers and vertical integration into protocol design services.
Within the integrated CRO tier, IQVIA and Parexel International Corporation exemplify scale-driven positioning through regulatory submission anchoring and therapeutic specialization. Cactus Communications occupies a distinct archetype as a platform-based operator leveraging scalable freelance networks. These three entities collectively represent the structural segmentation between institutional scale, therapeutic depth, and cost-efficient flexibility that defines procurement alternatives for biotechnology and pharmaceutical sponsors.
| Leading Market Players |
|---|
| Syneos Health |
| Freyr Solutions |
| IQVIA |
| Cactus Communications |
| Trilogy Writing & Consulting |
| Parexel International Corporation |
| MMS Holdings |
| Labcorp Drug Development |
| ICON plc |
| Others |
Supply & Pricing Matrix
Biotechnology sponsors unbundling writing services from full-service CRO contracts are compressing procurement budgets across the mid-market segment, forcing suppliers to restructure delivery models and absorb certification overhead without rate recovery.
Pricing Analysis
Writer certification costs and ISO 27001 audit expenses pass through to sponsor invoices, elevating project rates for regulatory documentation relative to publication services. Pricing stratifies across premium, standard, and economy tiers based on therapeutic specialization depth and data security certification level. Cost compression in the standard tier is intensifying because freelance platform competition erodes hourly rates for routine safety narratives. Mid-tier biotechnology firms exhibit the highest price sensitivity, while large pharmaceutical companies prioritize narrative control over cost efficiency.
Supply Chain Analysis
EU AI Act local-content mandates for algorithmic transparency documentation are reshaping sourcing patterns toward European-based writers with machine learning interpretability expertise. Medical writing talent concentrates in the United States, Switzerland, and the United Kingdom, with Basel and Boston anchoring rare disease specialization. The supply chain draws from freelance platforms, boutique agencies, and captive CRO divisions as primary inputs. Single-source vulnerability in gene therapy documentation expertise concentrates project risk in Boston and Basel clusters. Distribution runs through direct sponsor contracts, platform-mediated freelance engagements, and white-label CRO arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
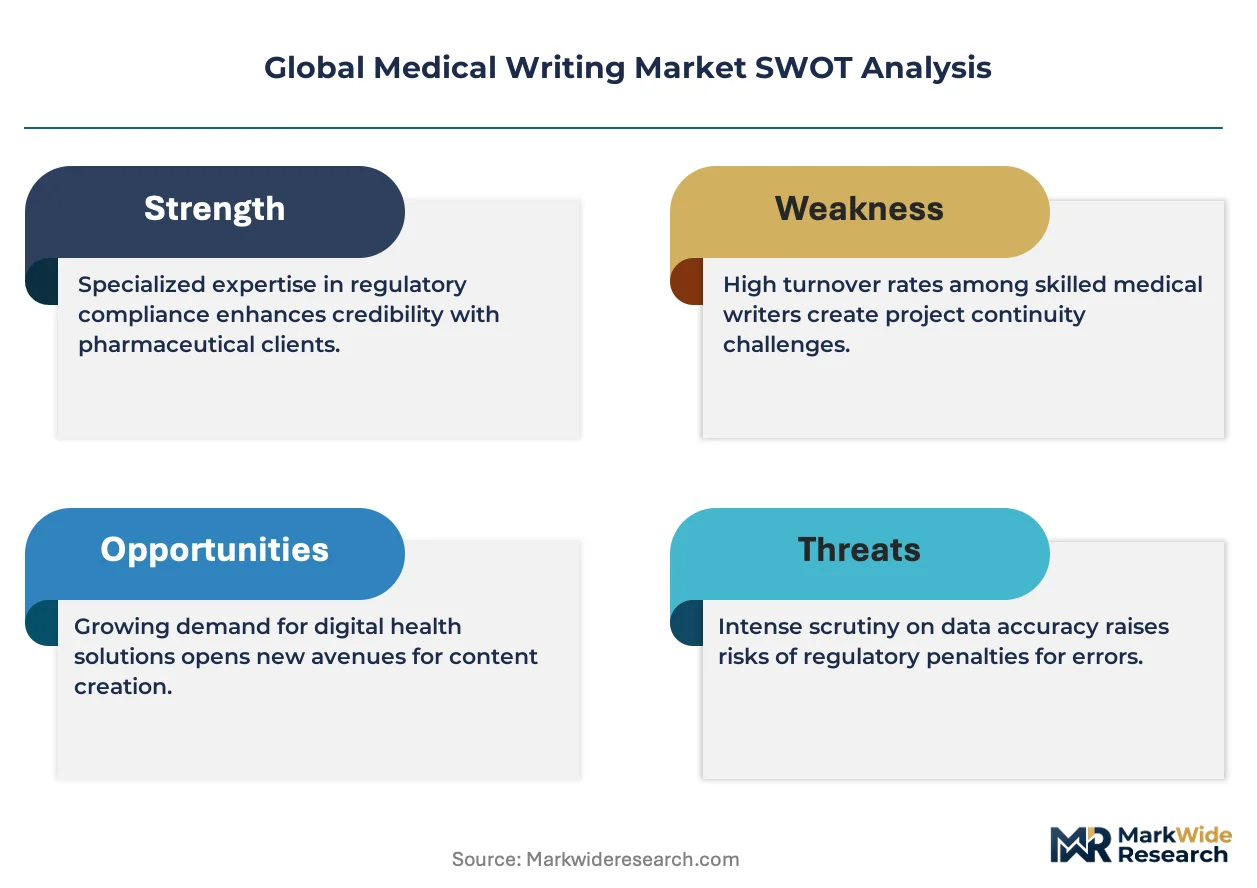
The medical writing market has entered a late-cycle quality phase where sponsor procurement prioritizes ISO 27001-validated delivery and therapeutic depth over cost minimization.
For Market Incumbents: Hedge against freelance platform commoditization by building proprietary training datasets for generative AI tools validated under FDA software-as-medical-device guidance. Consolidate position through backward integration into protocol design services, capturing upstream narrative control before competitors establish therapeutic expertise moats in oncology and rare disease segments.
For New Entrants and Emerging Players: AI-augmented regulatory writing tools offer the most penetrable entry vector, targeting mid-tier biotechnology sponsors in Cambridge and San Francisco with compressed timeline requirements. Focus initial commercial traction on dose-optimization documentation for FDA Project Optimus submissions, where established CROs lack specialized capacity.
For Investors and Strategic Acquirers: Asymmetric upside sits with boutique agencies possessing gene therapy documentation expertise and existing Swissmedic or PMDA relationships. Long-term viability favors targets with validated AI tooling and rare disease writer networks rather than scale-driven CRO divisions. Watch for inflection when synthetic control arm methodologies achieve broad FDA acceptance, expanding addressable documentation scope.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Validation Framework Development | FDA software-as-medical-device scrutiny creates competitive moat for validated natural language generation tools. |
| Rare Disease Writer Network Expansion | Gene therapy submission volumes in Boston and Basel justify premium pricing for specialized expertise. |
| Protocol Design Service Integration | Upstream narrative control captures sponsor relationships before documentation requirements crystallize. |
| EU AI Act Compliance Capability | Algorithmic transparency documentation opens new revenue category for machine learning-enabled drug development. |
| PMDA English-Language Pathway Access | Japan's regulatory globalization enables Western providers to serve Tokyo-based pharmaceutical sponsors. |
Research Methodology
Multiple input streams — regulatory affairs directors at biotechnology sponsors, medical writing agency executives, CRO procurement leads, and FDA submission specialists — were reconciled against FDA guidance documents, EMA clinical trial regulation updates, and ClinicalTrials.gov protocol records. Secondary validation incorporated ICH E3 guideline revisions, CDISC implementation timelines, and ISO 27001 certification databases. Bottom-up project volume estimates from sponsor RFP data were cross-referenced with top-down market sizing from service provider revenue disclosures.
Historical regulatory submission volumes were cross-referenced against panel input from medical writing operations heads to establish baseline demand patterns across the analysis window. Segmentation modeling incorporated service type, therapy area complexity, end-user procurement sophistication, and delivery mode security requirements. CAGRs were derived from sponsor headcount constraints relative to documentation burden expansion. Forecast inputs included breakthrough therapy designation timelines and decentralized trial framework adoption curves.
The model holds under stable regulatory divergence between FDA and EMA; deviation in harmonized algorithmic transparency standards or accelerated AI guidance issuance would shift service-type demand composition. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Healthcare Information Software Market