
 Medical Simulation Software Market | 2026-2036
Medical Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Simulation Software Market Insights
Subscription-based leasing of simulation platforms is reconfiguring capital deployment across the vendor landscape. CAE Healthcare leverages long-term service contracts to anchor recurring revenue in military and civilian training networks. Mentice specializes in endovascular simulation, occupying a defensible niche in catheter-based procedure training. 3D Systems sustains technology leadership through in-house production of haptic hardware paired with proprietary software stacks.
Medical simulation software encompasses programmable digital environments that replicate anatomical systems, physiological responses, and procedural workflows for risk-free clinical training. These systems integrate real-time physics engines, patient-specific imaging data, and force-feedback peripherals to enable repeatable skill acquisition before live patient contact. Surgical simulators command the largest installed base among product types, though virtual reality simulators are recording the fastest expansion as headset costs decline and fidelity improves. Medical schools represent the most consolidated end-user segment by procurement volume, while military training facilities offer higher per-seat pricing due to classified scenario customization requirements.
FDA guidance on medical device training validation, EMA expectations for simulated evidence in surgical device submissions, and ISO 13485 quality management standards collectively shape product development roadmaps and customer compliance obligations. The EU AI Act introduces additional scrutiny for adaptive learning algorithms that personalize training difficulty in real time. Stakeholders must monitor whether regulators will mandate simulation-based proficiency benchmarks as prerequisites for device approval or clinician credentialing renewal.
Market Dynamics
Cloud-native deployment architectures are systematically displacing perpetual licensing models across hospital IT procurement cycles, forcing vendors to restructure revenue recognition and customer retention strategies around recurring service delivery.
Growth Catalysts
- FDA device training validation guidance:The agency's emphasis on simulation-based proficiency evidence accelerates institutional procurement of validated platforms for surgical credentialing programs.
- VR headset cost compression:Consumer electronics manufacturing scale is driving hardware acquisition costs below institutional budget thresholds, expanding addressable training seat capacity.
- Defense-civilian budget merger:United States military healthcare training networks are channeling procurement through consolidated acquisition vehicles accessible to civilian academic medical centers.
Market Restraints
- Haptic peripheral supply concentration:Precision force-feedback hardware fabrication depends on a limited supplier base concentrated in East Asian precision manufacturing clusters.
- EU AI Act algorithmic scrutiny:Real-time adaptive difficulty personalization in training modules triggers additional conformity assessment obligations and documentation burdens.
- Legacy system integration friction:Hospital IT environments running on-premise electronic health record architectures face substantial middleware costs for simulator data exchange.
Strategic Opportunities
- Japan's aging surgeon workforce:Extended career training requirements and procedural volume maintenance needs create sustained demand for skill reinforcement platforms.
- 5G-enabled remote proctoring:Low-latency cellular networks are enabling distributed expert supervision of simulation sessions across rural training sites.
- India medical education expansion:National accreditation body mandates for simulation-based undergraduate training are creating institutional procurement windows.
Industry Challenges
- Bioengineer-software developer talent gap:Cross-functional teams require personnel fluent in both physiological modeling and real-time graphics programming.
- ISO 13485 quality system implementation:Medical device classification of certain simulator hardware triggers full quality management system certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Simulation Software Market |
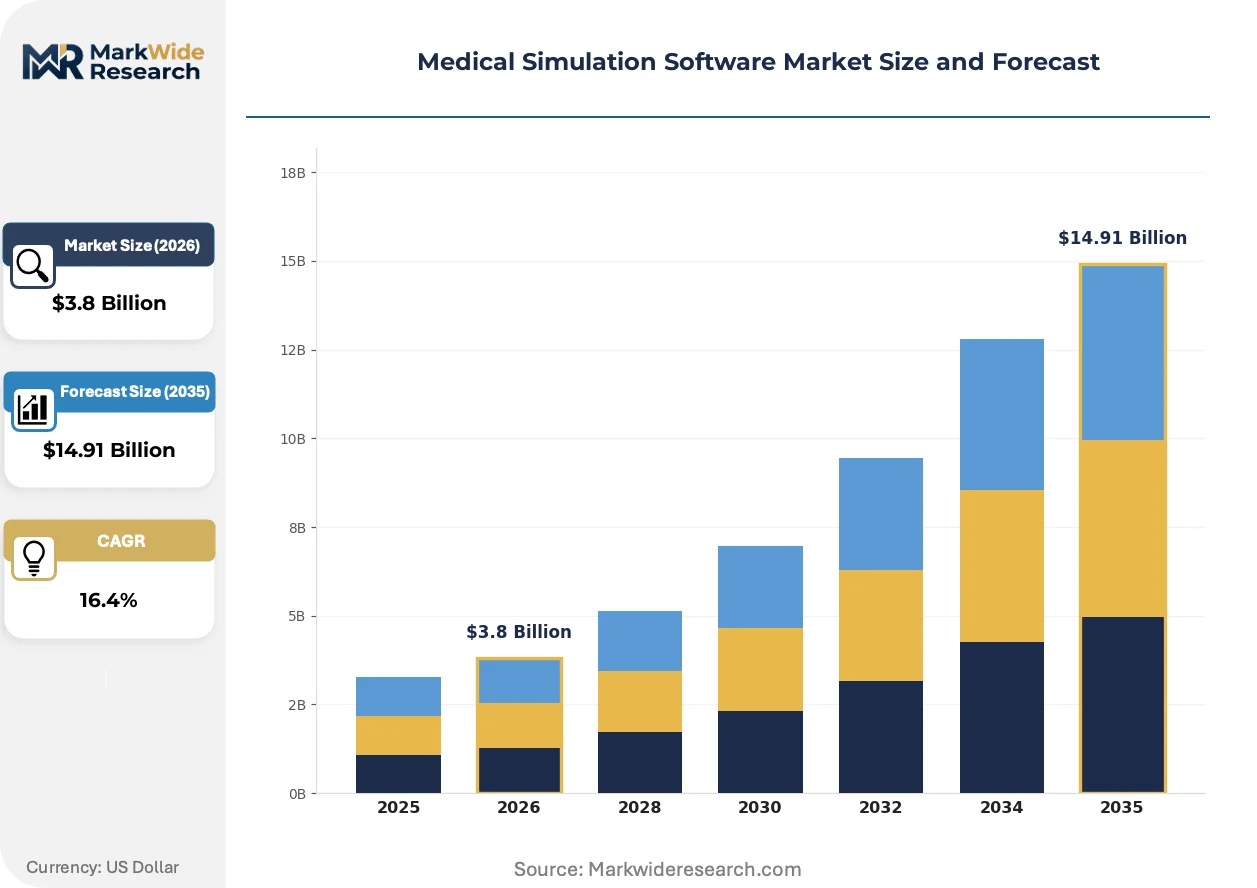
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Simulators, Patient Simulators, Virtual Reality Simulators, Software Platforms End User: Medical Schools, Hospitals, Clinics, Military Training Facilities Technology: Immersive Virtual Reality, Augmented Reality, Web-based Solutions, PC-based Simulations Application: Clinical Training, Surgical Planning, Medical Education, Emergency Response Training |
| Companies Covered | Surgical Science, 3D Systems, Laerdal Medical, MedVisionSim, Mentice, CAE Healthcare, Simulab, HealthStream, Gaumard Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Simulation Software Market Trends and Innovations
Physics engines capable of patient-specific anatomical deformation are compressing the fidelity gap between digital rehearsal and live tissue response, redefining minimum viable performance for training platform procurement.
Photorealistic volumetric rendering is digitizing preoperative surgical planning workflows, enabling trainees to rehearse procedures on reconstructions derived from actual patient imaging datasets. Academic medical centers in Germany are deploying these systems for complex oncologic resection preparation. The technology is digitizing traditional cadaver-based anatomical familiarization, reducing specimen procurement costs and enabling repeatable exposure to rare pathological presentations.
The EU AI Act's risk classification framework for adaptive learning systems is compelling vendors to rearchitect personalization algorithms around explainable decision boundaries. Training platforms must now document how difficulty adjustment logic responds to learner performance metrics. European medical device manufacturers integrating simulation into their clinical evidence packages face heightened scrutiny of algorithmic validation protocols.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide simulation platform subscriptions, displacing departmental point solutions. United States health systems are negotiating system-level contracts covering medical school, residency, and continuing medical education deployments. This concentration is visible in multi-hospital networks standardizing on single-vendor architectures to simplify IT support and content licensing administration.
Medical Simulation Software Market Segmentation
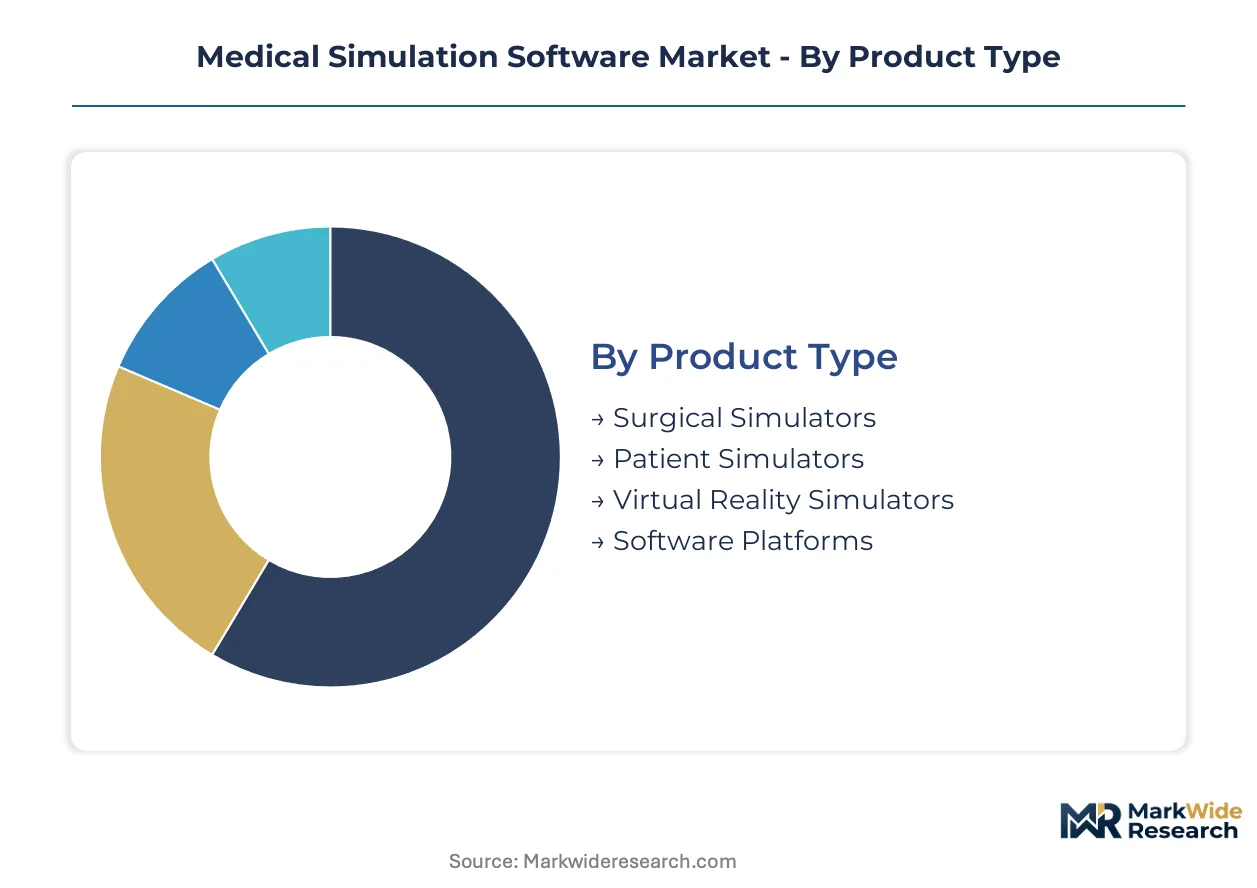
Procurement patterns in medical simulation software diverge sharply across institutional settings and technical architectures. Understanding these fault lines reveals where pricing power concentrates and which deployment models are displacing legacy systems.
Product Type:
Cost tier differentiation separates capital-intensive hardware bundles from lightweight software licensing arrangements.
- Surgical Simulators:Integrated hardware-software systems replicate operative environments with haptic feedback and tissue deformation physics. Medical schools in the United States anchor procurement volume for these platforms as accreditation standards tighten around hands-on credentialing requirements.
- Virtual Reality Simulators:Headset-dependent immersive environments deliver procedural training at substantially lower per-seat hardware costs. Germany's academic medical centers are expanding VR simulator deployment for oncologic resection rehearsal as photorealistic volumetric rendering fidelity improves.
- Patient Simulators:Full-body mannequin systems with programmable physiological responses support team-based emergency scenarios.
- Software Platforms:Modular licensing of physics engines and anatomical libraries enables custom curriculum development.
Surgical Simulators holds installed capacity. Virtual Reality Simulators is rotating up the share rankings.
End User:
Customer type determines contract structure, with subscription terms varying by institutional procurement authority and classified content requirements.
- Medical Schools:Consolidated procurement committees negotiate enterprise-wide platform licenses covering undergraduate through residency training. These institutions represent the most concentrated demand segment by seat volume, though pricing discipline remains intense due to shared state funding pools.
- Military Training Facilities:Classified scenario customization and dual-use civilian-military curriculum requirements command premium per-seat pricing. United States defense healthcare training networks channel procurement through consolidated acquisition vehicles accessible to civilian academic partners.
- Hospitals:Continuing medical education departments and residency programs drive replacement cycles for aging simulation suites.
- Clinics:Smaller procedural volumes limit dedicated simulator investment to high-margin specialty practices.
Medical Schools holds installed capacity. Military Training Facilities is rotating up the share rankings.
Technology:
Maturity curves separate proven deployment modes from emerging architectures still navigating validation requirements.
- Immersive Virtual Reality:Headset-delivered stereoscopic environments with six-degrees-of-freedom controller tracking enable psychomotor skill acquisition. Japan's aging surgeon workforce is driving demand for VR skill reinforcement platforms as extended career training requirements expand.
- PC-based Simulations:Monitor-based interfaces with mouse or joystick input dominate low-cost training seat provision. India's medical education expansion under national accreditation mandates is accelerating procurement of these accessible entry-level systems.
- Augmented Reality:Overlay displays blending digital anatomy with physical mannequins or cadaveric specimens remain in pilot deployment phases.
- Web-based Solutions:Browser-delivered modules support asynchronous cognitive training and assessment with minimal IT infrastructure.
PC-based Simulations holds installed capacity. Immersive Virtual Reality is climbing the fastest.
Application:
Volume concentration follows regulatory pressure points where simulation evidence carries formal weight in credentialing or device approval.
- Clinical Training:Procedural skill acquisition and maintenance for practicing clinicians facing recertification requirements. FDA guidance on device training validation is accelerating institutional procurement of validated platforms for surgical credentialing programs.
- Surgical Planning:Patient-specific rehearsal on reconstructed imaging datasets prior to complex operations. German academic medical centers are deploying these systems for oncologic resection preparation, digitizing traditional cadaver-based familiarization.
- Medical Education:Undergraduate anatomy and physiology instruction using repeatable digital exposure to rare pathological presentations.
- Emergency Response Training:Team coordination scenarios for mass casualty events and critical incident response protocols.
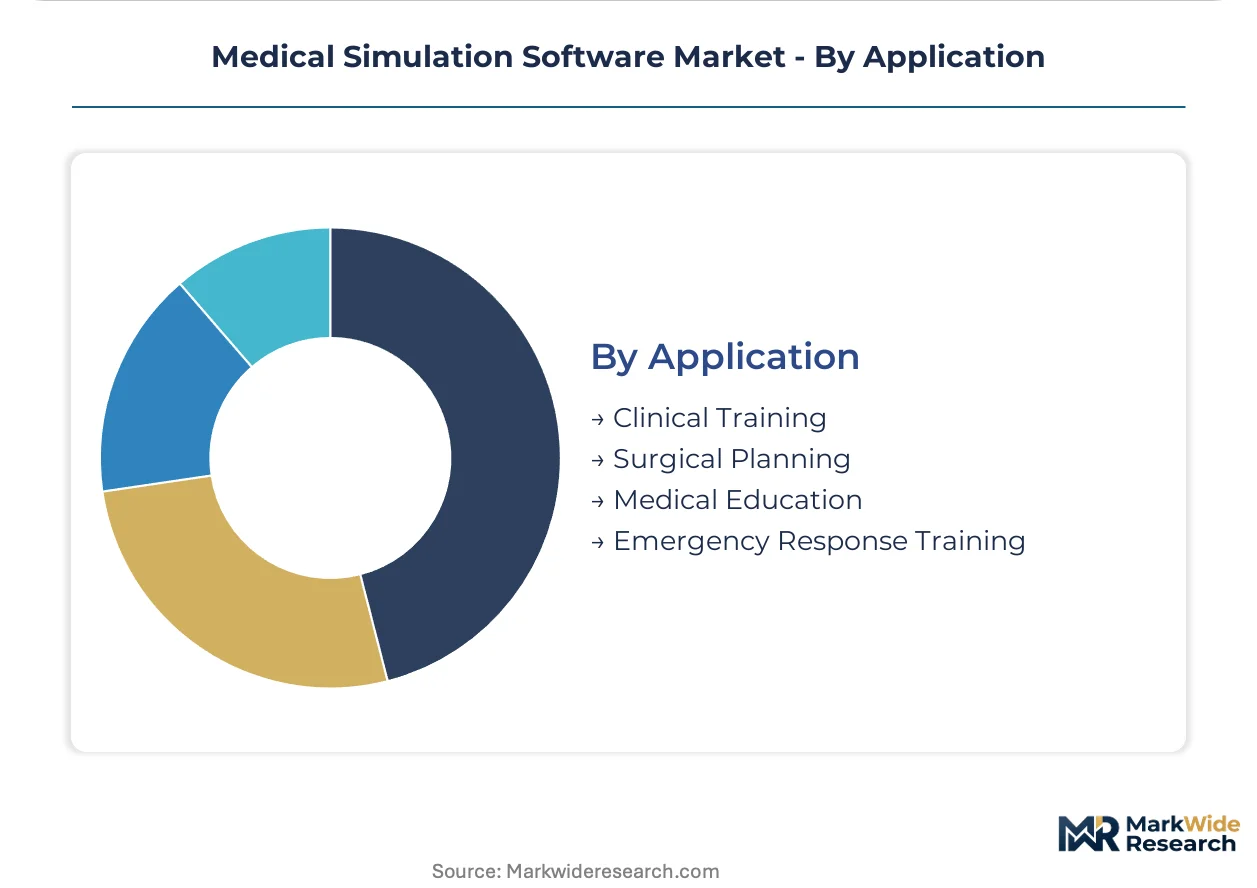
Clinical Training holds installed capacity. Surgical Planning is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on device training validation is accelerating institutional procurement across the United States, while EMA expectations for simulated evidence reshape European surgical device submissions. Japan's aging surgeon workforce and India's medical education expansion create divergent demand profiles across Asia-Pacific.
United States
Defense and civilian healthcare training budgets have merged procurement channels, enabling academic medical centers to access military acquisition vehicles. FDA guidance on medical device training validation mandates simulation-based proficiency evidence for surgical credentialing programs. The Greater Boston cluster anchors enterprise-wide platform deployments across multi-hospital networks standardizing on single-vendor architectures.
Germany
Academic medical centers are deploying photorealistic volumetric rendering systems for complex oncologic resection preparation. EMA expectations for simulated evidence in surgical device submissions compel manufacturers to integrate validated training platforms into clinical evidence packages. The Baden-Württemberg region concentrates vendor development activity for physics engines capable of patient-specific anatomical deformation.
Japan
Extended career training requirements for an aging surgeon workforce sustain demand for skill reinforcement platforms. METI standards for medical device software quality management shape procurement specifications for institutional buyers. The Kanto region around Tokyo hosts concentrated deployments of immersive virtual reality systems for procedural volume maintenance.
India
National accreditation body mandates for simulation-based undergraduate training are creating institutional procurement windows across medical colleges. The country's national pharmaceutical regulator is developing conformity assessment frameworks for adaptive learning algorithms. Maharashtra and Karnataka anchor the highest concentration of PC-based simulation deployments for accessible entry-level training seats.
United Kingdom
NHS continuing medical education budgets are consolidating around subscription-based platform licensing to reduce per-seat hardware costs. The EU AI Act's risk classification framework triggers additional documentation burdens for vendors deploying real-time difficulty personalization. The London-Southeast corridor leads procurement of web-based asynchronous training modules with minimal IT infrastructure requirements.
Medical Simulation Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around enterprise-wide subscription contracts. Hospital procurement committees are displacing departmental point solutions with standardized platform architectures. Three archetypes dominate: integrated hardware-software vendors with captive haptic production, pure-play software specialists licensing modular physics engines, and diversified simulation conglomerates spanning civilian and military training networks. M&A activity targets haptic peripheral capabilities and cloud-native deployment expertise.
Within the diversified training network tier, CAE Healthcare and Laerdal Medical exemplify channel-controlling players leveraging long-term service contracts across merged defense-civilian procurement channels. Mentice occupies a specialist position in catheter-based procedure training modules. These three companies anchor distinct competitive vectors: CAE Healthcare represents the military-civilian convergence archetype, Laerdal Medical exemplifies the full-body mannequin systems legacy, and Mentice illustrates defensible niche specialization in endovascular simulation.
| Leading Market Players |
|---|
| Surgical Science |
| 3D Systems |
| Laerdal Medical |
| MedVisionSim |
| Mentice |
| CAE Healthcare |
| Simulab |
| HealthStream |
| Gaumard Scientific |
| Others |
Pricing and Supply Chain Analysis
The Yokohama-Long Beach maritime corridor's freight cost volatility amplifies procurement spreads between ISO 13485-certified haptic hardware and uncertified alternatives, concentrating margin pressure on vendors lacking backward integration into East Asian precision manufacturing clusters while rewarding buyers with consolidated defense-civilian acquisition vehicles.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between premium surgical simulators and accessible PC-based training modules. Three-tier pricing structure across premium, standard, and economy levels reflects haptic fidelity grades and cloud-native deployment readiness. Cost compression in VR headset bundles is intensifying because consumer electronics manufacturing scale collapses hardware acquisition thresholds. Medical schools with shared state funding pools exhibit highest price sensitivity; military training facilities with classified scenario requirements show lowest.
Supply Chain Analysis
Export-control restrictions on force-feedback actuator technology limit component flows from Japan and Germany to Chinese assembly operations. Precision machining capacity concentrates in Taiwan, South Korea, and Japan for haptic peripheral fabrication. Supply chains draw from rare earth magnet suppliers in China's Jiangxi province and specialized semiconductor foundries in Hsinchu. Single-source vulnerability runs through East Asian precision manufacturing clusters. Distribution runs through consolidated defense procurement vehicles and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA validation protocols and ISO 13485 certification timelines create structural barriers that extend incumbent replacement cycles and inflate new entrant compliance costs.
For Market Incumbents: Harden cloud-native deployment architectures against emerging pure-play software specialists by anchoring recurring revenue in long-term service contracts. Deepen backward integration into haptic hardware production to escape East Asian supplier concentration. Prioritize certification maintenance as cloud-native entrants without ISO 13485 compliance face 18-24 month quality system implementation delays.
For New Entrants and Emerging Players: Establish a beachhead in India's PC-based simulation segment where national accreditation mandates create procurement windows without incumbent lock-in. Target medical colleges in Maharashtra and Karnataka with accessible entry-level systems. Pursue white-label partnerships with established GPOs to bypass direct hospital sales cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming healthcare simulation divisions lacking cloud-native expertise. Long-term viability favors vendors with captive haptic production and military-civilian channel control. Watch for EU AI Act enforcement actions against adaptive learning algorithms as an inflection indicator for regulatory-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables subscription revenue recognition and displaces perpetual licensing in hospital IT environments. |
| Haptic Hardware Backward Integration | Secures supply continuity against East Asian precision manufacturing concentration risks. |
| ISO 13485 Quality System Certification | Triggers medical device classification compliance and extends competitive moats through validation timelines. |
| Defense-Civilian Channel Convergence | Unlocks military acquisition vehicles for academic medical center procurement consolidation. |
| Patient-Specific Imaging Integration | Compresses fidelity gaps between digital rehearsal and live tissue response for surgical planning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA device submissions, hospital GPO contract databases, and ISO certification registries. Primary interviews engaged simulation platform product managers, hospital biomedical engineering directors, military training procurement officers, and medical school curriculum committee chairs. Secondary validation drew from SEC filings of publicly traded simulation vendors, customs trade data for haptic peripheral imports, and academic medical center capital expenditure disclosures. Bottom-up installed base estimates triangulated against top-down healthcare training budget allocations.
Forecast inputs span deployment model transitions, headset cost compression curves, and regulatory validation timeline shifts across the analysis window. Segmentation dimensions modeled include product type, end-user institution category, technology architecture, and application workflow. CAGRs derived from logistic adoption curves fitted to historical procurement patterns and projected training seat expansion. Industry-specific inputs incorporate FDA guidance implementation timelines and defense budget authorization trajectories.
Stress conditions across VR hardware cost decline rates, EU AI Act enforcement intensity, and haptic component tariff exposure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding accreditation mandate adoption and cloud procurement preference shifts. Material shifts in FDA simulation-based proficiency requirements or defense-civilian budget separation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Medical Software Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Medical Information Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Global Medical Transcription Software Market