
 Asia Pacific Healthcare IT Market | 2026-2036
Asia Pacific Healthcare IT Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Healthcare IT Market Analysis
Hospital procurement channels across Southeast Asia are rewriting how health IT vendors reach end buyers, with group purchasing organizations and ministry-level tenders displacing single-site sales. Philips leverages deep imaging informatics integration to sustain its position in radiology-workflow software across Indian tertiary hospitals. GE Healthcare anchors its regional footprint through localized R&D centers in Bangalore and Shanghai that compete on cost-adapted product lines. Siemens Healthineers differentiates via AI-enabled diagnostic platforms that dominate high-end hospital networks in Japan and South Korea.
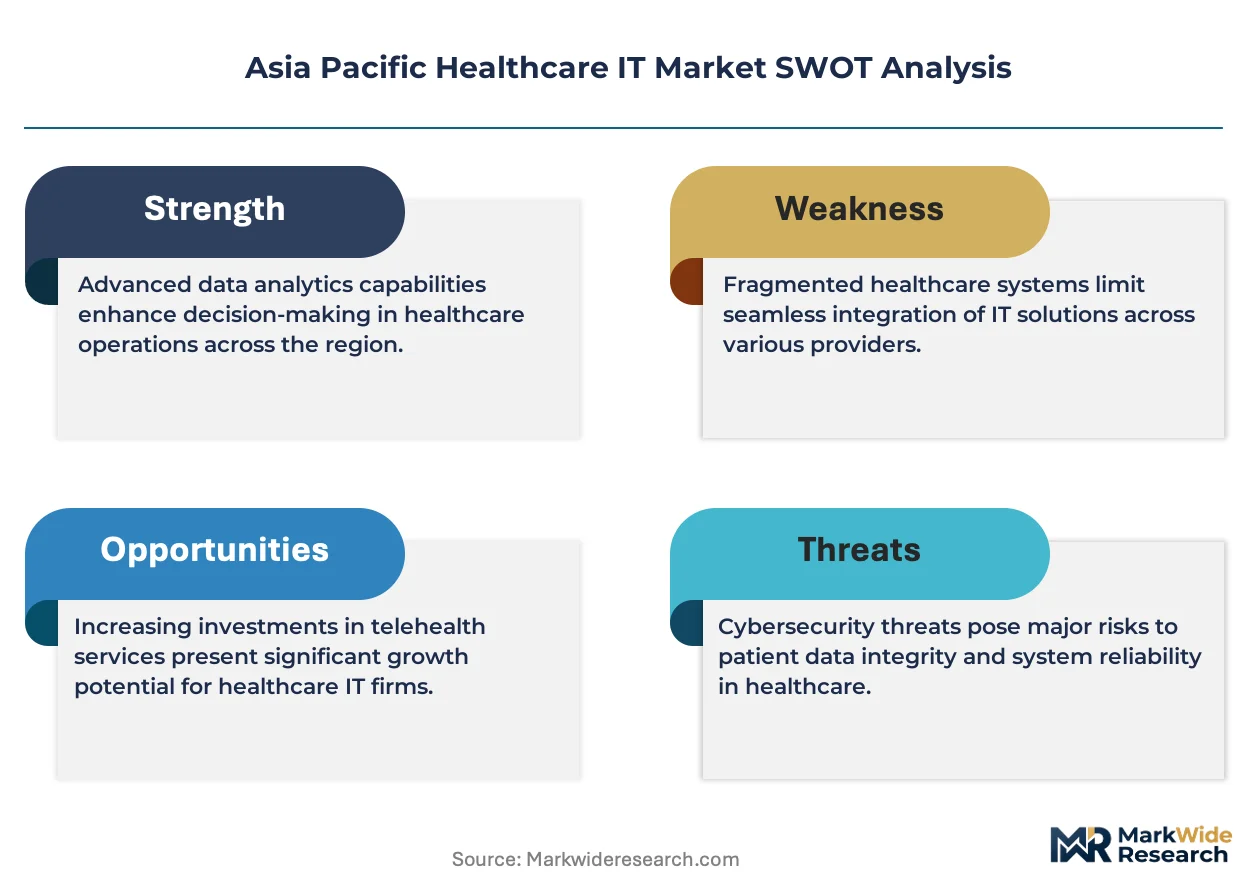
Healthcare IT encompasses the hardware, software, and network infrastructure enabling electronic capture, storage, exchange, and analysis of clinical and administrative health data, typically operating through interoperable standards such as HL7 FHIR for data exchange between disparate systems. Its primary commercial purpose is reducing clinical error rates, optimizing resource utilization, and enabling real-time decision support across care continuums. Telemedicine platforms are capturing the fastest expansion as post-pandemic reimbursement frameworks normalize virtual consultations across the region's archipelago geographies. Cloud-based deployment is displacing on-premise installations where capital constraints and distributed care networks make SaaS models structurally preferable. Population health management applications are emerging as the highest-margin segment due to payer and government contracts for chronic disease surveillance.
Japan's PMDA governs software-as-medical-device classifications that shape product registration pathways for AI diagnostic tools entering that market. India's CDSCO and the Digital Information Security in Healthcare Act framework, alongside China's NMPA cybersecurity requirements for networked medical devices, collectively raise compliance barriers that favor vendors with established regulatory affairs capacity. Australia's TGA and South Korea's MFDS add further heterogeneity to approval timelines across the region. Stakeholders must monitor convergence between national electronic health record mandates and data localization requirements that could fragment cloud architecture strategies.
Market Dynamics
Cloud-native architecture is compressing deployment cycles across Asia Pacific hospital networks, collapsing traditional on-premise installation timelines from years to months while forcing vendors to restructure service revenue models around subscription economics.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic production incentives are accelerating local assembly of health IT hardware, reducing import dependency for hospital server infrastructure and edge computing devices.
- Telemedicine reimbursement normalization:Post-pandemic payment frameworks across Southeast Asian archipelago states are institutionalizing virtual consultation billing codes that sustain platform investment.
- HL7 FHIR interoperability mandates:China's tier-one hospital grading standards now require EMR-to-EHR data exchange compliance, creating forced upgrade cycles for legacy systems.
Market Restraints
- Data localization requirements:China's NMPA cybersecurity rules and India's DISHA framework fragment cloud architecture strategies, forcing redundant infrastructure investment across national borders.
- Specialized health informatics talent scarcity:Clinical data scientists and FHIR integration engineers command premium compensation that stretches vendor operating margins.
- Proprietary legacy system entrenchment:Decades-old hospital information systems in Japan and South Korea resist API-based interoperability, extending sales cycles for replacement platforms.
Strategic Opportunities
- Population health management software:Government chronic disease surveillance contracts in Australia and Singapore represent high-margin recurring revenue streams underserved by current vendor portfolios.
- AI diagnostic platform commercialization:Japan's PMDA software-as-medical-device pathway, though rigorous, creates first-mover advantage for cleared algorithms in radiology and pathology workflows.
- Group purchasing organization channel development:Ministry-level tenders across Indonesia, Thailand, and Vietnam consolidate procurement authority, rewarding vendors with centralized contract negotiation capabilities.
Industry Challenges
- Multi-jurisdiction regulatory navigation:Australia's TGA, South Korea's MFDS, and China's NMPA maintain divergent cybersecurity and clinical validation requirements that extend product registration timelines and inflate compliance headcount.
- Interoperability standard fragmentation:Coexistence of HL7 FHIR, IHE profiles, and national health information exchange protocols forces vendors to maintain multiple integration codebases.
- Hospital IT budget cyclicality:Public sector fiscal calendars and election-driven health spending freezes in emerging Southeast Asian markets create unpredictable procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Healthcare IT Market |
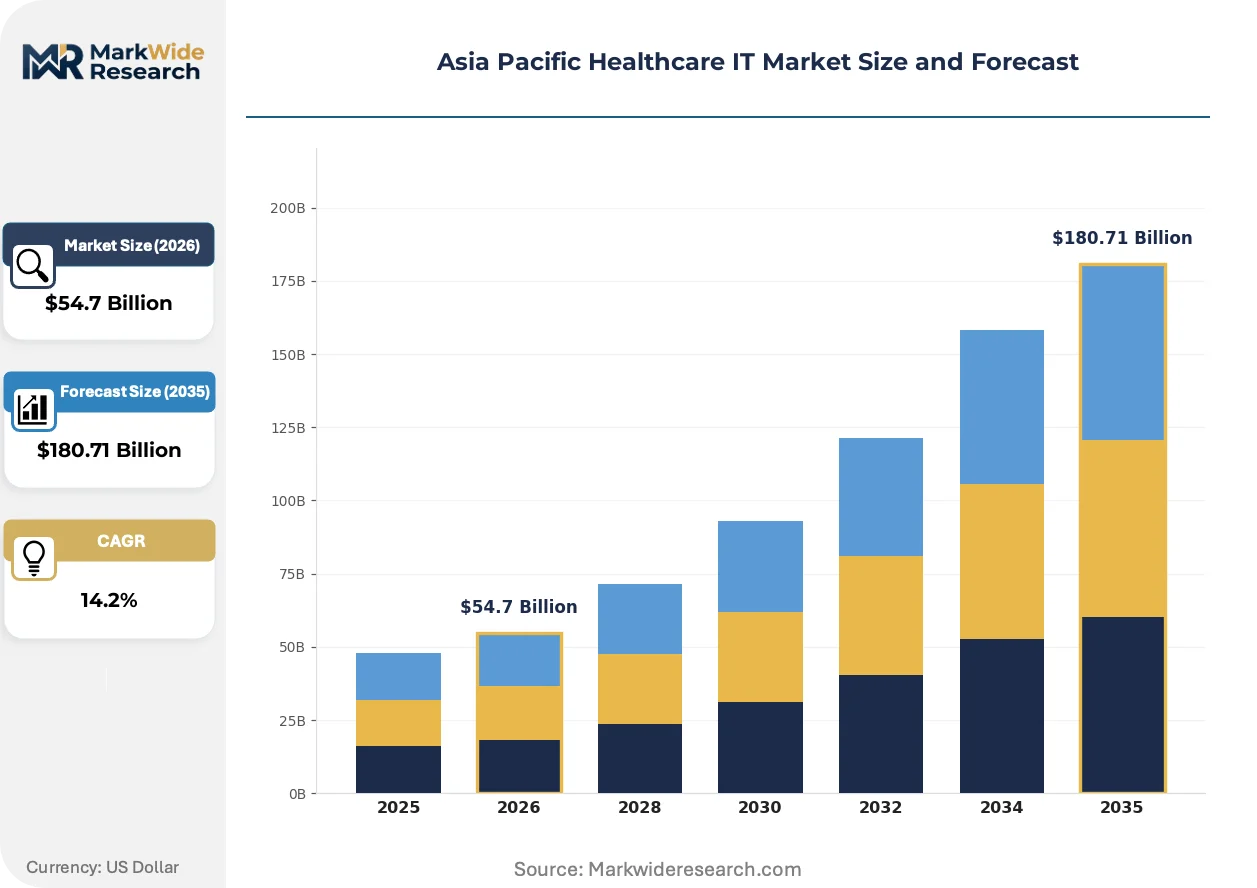
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $180.71 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, EMR, Telemedicine, Health Information Exchange End User: Hospitals, Clinics, Diagnostic Centers, Outpatient Facilities Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Application: Patient Management, Revenue Cycle Management, Data Analytics, Population Health Management |
| Companies Covered | Philips, GE Healthcare, IBM Corporation, Siemens Healthineers AG, Oracle, Optum, Tata Consultancy Services, Fujitsu, Cognizant, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Healthcare IT Market Emerging Trajectories
Artificial intelligence inference at the network edge is restructuring how diagnostic data flows through hospital workflows, compressing latency-sensitive decision points while generating new regulatory classification debates.
Federated learning architectures for medical imaging are migrating from experimental pilot programs to production deployment across Japanese and South Korean hospital networks. Radiology departments at tertiary institutions in Tokyo and Seoul are adopting these distributed training methods to pool diagnostic algorithm development without centralizing sensitive patient data. This migration from centralized cloud training to edge-coordinated model updates is enabling competitive AI diagnostic capabilities among hospitals previously excluded from big-data research consortiums.
Japan's PMDA has tightened software-as-medical-device classification criteria for AI diagnostic tools, requiring prospective clinical validation studies that mirror pharmaceutical trial structures. This regulatory evolution has extended product registration timelines by twelve to eighteen months for algorithm developers. High-end hospital networks are responding by prioritizing vendor partnerships with established regulatory affairs capacity over pure technical performance metrics.
Hospital procurement authority is consolidating upward from individual facilities to ministry-level tender boards and multi-hospital group purchasing organizations across Southeast Asia. Single-site IT directors in Indonesia, Thailand, and Vietnam are losing autonomous budget control to centralized procurement committees that negotiate enterprise-wide platform licenses. This concentration is most visible in Malaysia's public hospital network, where the Ministry of Health now mandates standardized EMR platforms across all government facilities, collapsing vendor diversity in favor of approved-system lists.
Asia Pacific Healthcare IT Market Segmentation
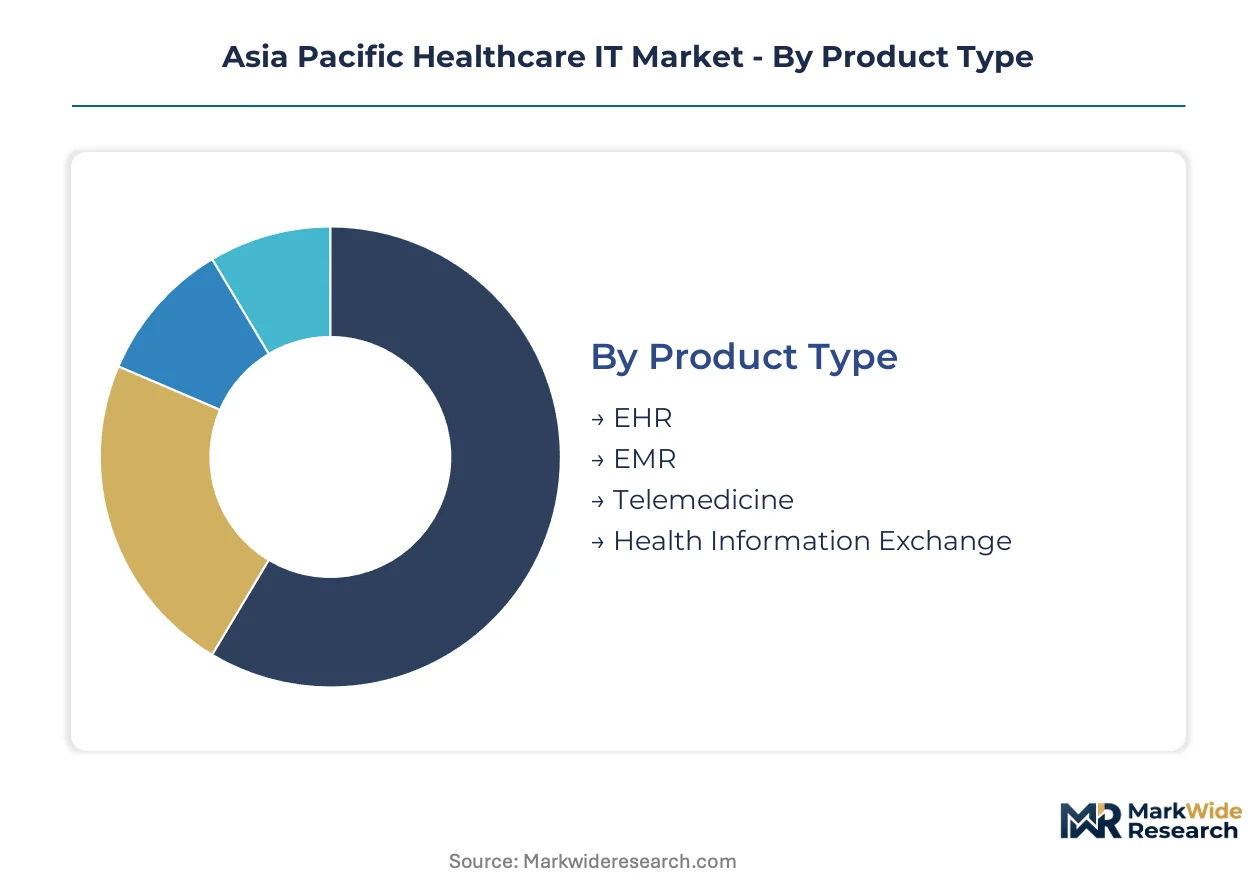
Healthcare IT procurement across Asia Pacific follows distinct technology maturity curves and capital availability profiles. Understanding how product architectures, user settings, deployment models, and clinical applications segment reveals where vendor resources generate highest returns.
Product Type:
Clinical workflow integration spans from legacy record digitization through real-time virtual care platforms, with adoption depth varying by hospital IT budget cycles and regulatory compliance deadlines.
- EHR:Comprehensive electronic health record systems consolidate longitudinal patient data across departments and facilities. China's tier-one hospital clusters drive replacement demand as NMPA grading standards mandate interoperability compliance.
- EMR:Department-level electronic medical record systems manage episode-specific clinical documentation. Southeast Asian public hospital networks concentrate procurement through ministry tenders, compressing vendor margins but securing multi-year contract volumes.
- Telemedicine:Virtual consultation platforms with integrated billing and prescription workflows. Post-pandemic reimbursement normalization across Indonesian and Philippine archipelago geographies sustains platform investment.
- Health Information Exchange:Interoperable data sharing infrastructure connecting disparate provider networks. India's DISHA framework and data localization requirements fragment cross-border architecture strategies.
Established volume favors EHR; emerging adoption favors Telemedicine.
End User:
Facility scale determines IT sophistication thresholds, from enterprise-grade analytics at tertiary institutions to lightweight SaaS tools for distributed primary care.
- Hospitals:Acute care institutions with 100+ beds requiring integrated clinical, administrative, and diagnostic systems. Japan's PMDA software-as-medical-device classifications reshape procurement criteria for AI-enabled platforms.
- Clinics:Primary and specialty outpatient settings with limited IT staff and capital constraints. Cloud-based subscription models displace on-premise installations where maintenance expertise is scarce.
- Diagnostic Centers:Standalone imaging and laboratory facilities requiring PACS integration and HL7 FHIR connectivity. South Korea's MFDS cybersecurity requirements extend product registration timelines for networked devices.
- Outpatient Facilities:Ambulatory surgery centers and day-care units needing scheduling and billing optimization. Australia's chronic disease surveillance contracts create recurring revenue opportunities for population health tools.
Procurement authority concentrates at Hospitals; margin expansion concentrates at Diagnostic Centers.
Deployment:
Capital structure and data sovereignty concerns shape infrastructure choices across national borders.
- On-Premise:Hospital-owned server infrastructure with dedicated maintenance staff. Japanese and South Korean legacy system entrenchment resists API-based interoperability, extending replacement cycles.
- Cloud-Based:Third-party hosted platforms with elastic compute scaling. China's NMPA cybersecurity rules and India's DISHA framework force redundant infrastructure investment across jurisdictions.
- Hybrid:Mixed architecture with sensitive data on-premise and analytics workloads in cloud. Australia's TGA data residency requirements for clinical trial systems favor this configuration.
- SaaS:Subscription-licensed software with vendor-managed updates and security. Southeast Asian archipelago geographies with distributed care networks find this model structurally preferable.
Revenue stability favors SaaS; customization depth favors Hybrid.
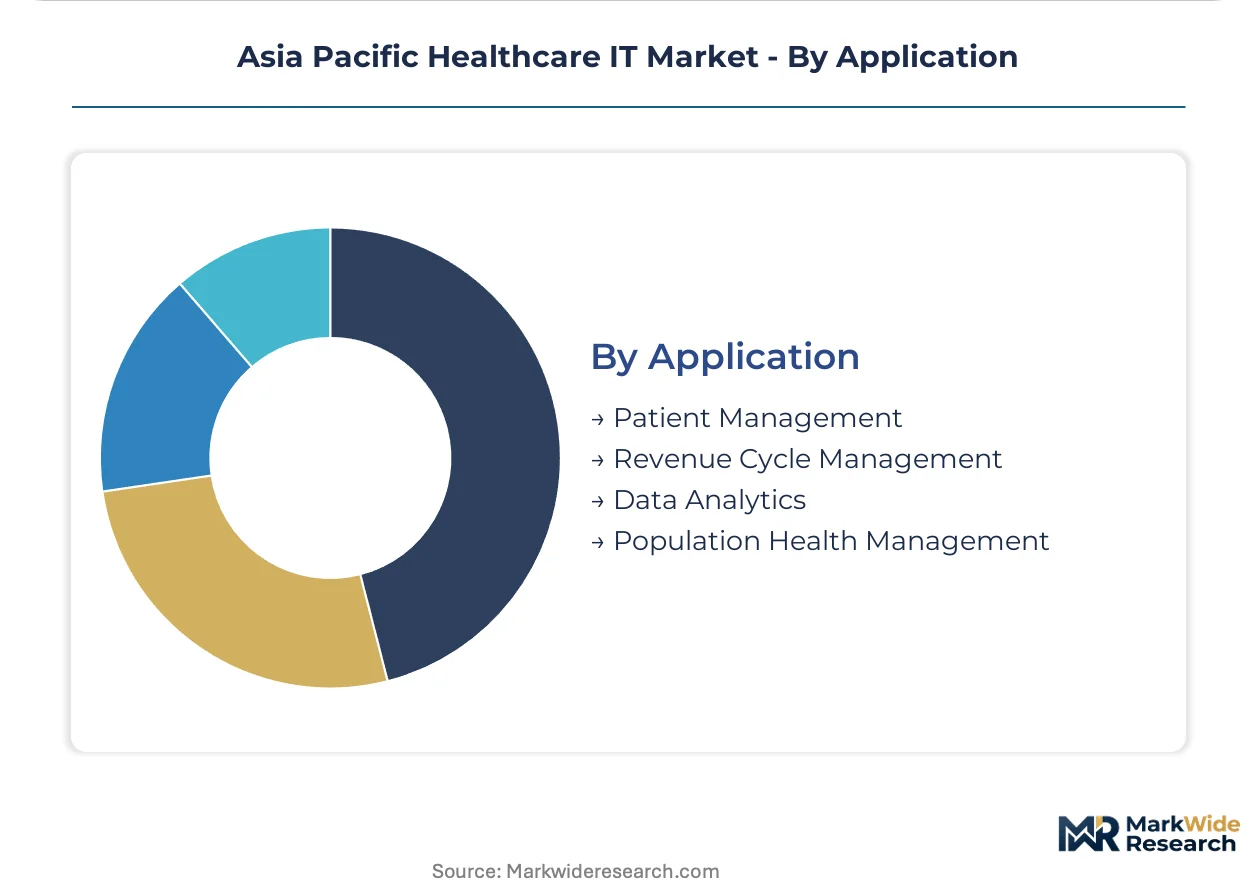
Application:
Functional modules align with specific operational pain points from front-desk throughput to population-level disease surveillance.
- Patient Management:Scheduling, registration, and care coordination workflows. Singapore's integrated public hospital clusters demand real-time bed management and referral tracking.
- Revenue Cycle Management:Billing, claims processing, and payment reconciliation systems. India's expanding health insurance penetration creates demand for automated prior authorization platforms.
- Data Analytics:Clinical and operational intelligence dashboards with predictive capabilities. Federated learning architectures enable Japanese tertiary hospitals to pool algorithm development without centralizing sensitive records.
- Population Health Management:Chronic disease surveillance and risk stratification tools. Government contracts in Australia and Singapore represent high-margin recurring revenue streams.
Contract volume favors Patient Management; margin concentration favors Population Health Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is accelerating domestic health IT infrastructure buildout across the region. China's NMPA cybersecurity requirements and tier-one hospital grading standards are forcing EMR-to-EHR upgrade cycles. Japan's PMDA software-as-medical-device classifications are reshaping procurement criteria for AI diagnostic platforms.
China
Tier-one hospital clusters in Beijing, Shanghai, and Guangzhou drive replacement demand as NMPA grading standards mandate interoperability compliance. The NMPA cybersecurity rules for networked medical devices force redundant infrastructure investment. Yangtze River Delta hospital networks are consolidating procurement authority through ministry-level tender boards.
Japan
Tertiary institutions in Tokyo and Osaka are adopting federated learning architectures for medical imaging without centralizing sensitive patient data. The PMDA has tightened software-as-medical-device classification criteria for AI diagnostic tools. Kanto region radiology departments are prioritizing vendor partnerships with established regulatory affairs capacity.
India
Domestic production incentives under the PLI scheme are accelerating local assembly of health IT hardware and reducing import dependency. The CDSCO and Digital Information Security in Healthcare Act framework raise compliance barriers. Bangalore and Hyderabad clusters are anchoring localized R&D centers that compete on cost-adapted product lines.
South Korea
High-end hospital networks are driving AI-enabled diagnostic platform adoption under MFDS cybersecurity requirements. The MFDS extends product registration timelines for networked devices. Seoul Capital Area tertiary institutions dominate radiology-workflow software procurement.
Australia
Government chronic disease surveillance contracts are creating recurring revenue opportunities for population health management tools. The TGA maintains data residency requirements for clinical trial systems. New South Wales and Victoria public hospital clusters are consolidating procurement through standardized platform mandates.
Asia Pacific Healthcare IT Market Vendor Landscape
On the supply side, the industry is structured around three distinct tiers with divergent resource allocation strategies. Imaging informatics specialists, enterprise software conglomerates, and IT services integrators each occupy differentiated positions in the value chain. Consolidation pressure is intensifying as ministry-level tenders favor vendors with centralized contract negotiation capabilities. Dominant competitive moves include strategic partnerships with local system integrators and portfolio diversification into population health management applications.
Among diversified technology conglomerates, Philips, GE Healthcare, and Siemens Healthineers exemplify the imaging-centric archetype that dominates radiology-workflow software procurement. These companies occupy positions anchored by deep clinical informatics integration rather than pure infrastructure plays. Tata Consultancy Services represents the IT services integrator model that competes on deployment velocity and localized implementation capacity. Oracle and IBM Corporation sit within the enterprise software tier, leveraging existing database and cloud infrastructure relationships to penetrate hospital procurement channels. The competitive dynamic favors vendors that combine regulatory affairs expertise with subscription-based revenue models aligned to Southeast Asian capital constraints.
| Leading Market Players |
|---|
| Philips |
| GE Healthcare |
| IBM Corporation |
| Siemens Healthineers AG |
| Oracle |
| Optum |
| Tata Consultancy Services |
| Fujitsu |
| Cognizant |
| Others |
Supply Flow & Price Mechanics
Server infrastructure concentration in China's Yangtze River Delta and India's Bangalore-Hyderabad corridor determines where margin pools accumulate downstream, with cloud-native platform vendors capturing recurring revenue while hardware assemblers compete on cost-adapted product lines.
Pricing Analysis
Volume-discount tiering structures dominate ministry-level tenders across Indonesia, Thailand, and Vietnam, where group purchasing organizations negotiate enterprise-wide platform licenses. Pricing stratifies across premium AI-enabled diagnostic tiers, standard EMR-to-EHR compliance packages, and economy SaaS subscriptions for distributed primary care networks. Cost compression in the economy tier is intensifying because Southeast Asian public hospital networks face capital constraints and election-driven spending freezes. Diagnostic centers exhibit the lowest price sensitivity due to PACS integration requirements and MFDS cybersecurity compliance premiums.
Supply Chain Analysis
Foxconn, Wistron, and Dixon Technologies hold contract-manufacturing capacity for hospital server infrastructure and edge computing devices across China, India, and Taiwan. Semiconductor components for AI inference accelerators and medical-grade displays draw from South Korean and Japanese suppliers. Single-source vulnerability in advanced GPU allocations for federated learning architectures creates procurement bottlenecks at Japanese tertiary institutions. Distribution runs through ministry-level tender boards in emerging Southeast Asian markets and direct enterprise sales to tier-one hospital clusters in China and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as procurement authority consolidates upward from individual facilities to centralized committees, creating niches for vendors with regulatory affairs capacity and subscription-based revenue models aligned to capital-constrained buyers.
For Market Incumbents: Build regulatory moats through PMDA software-as-medical-device clearance pathways and NMPA cybersecurity certification capacity. Defensive consolidation moves center on acquiring FHIR integration engineering talent and establishing localized R&D centers in Bangalore and Shanghai. Cloud-native platform substitution by IT services integrators threatens imaging informatics specialists who delay subscription economics transition.
For New Entrants and Emerging Players: Vietnam's public hospital network and Philippine archipelago geographies show underpenetration in population health management software. White-space targets include government chronic disease surveillance contracts in Australia and Singapore, plus telemedicine platforms for Indonesian island-distributed care networks. SaaS-first go-to-market with ministry-level tender board pre-qualification accelerates procurement access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as subscription economics displace on-premise installation revenue. Long-term viability favors vendors combining AI diagnostic platform pipelines with established regulatory affairs headcount. Acquisition target archetype: mid-cap specialists with cleared algorithms in radiology or pathology workflows. Watch for HL7 FHIR interoperability mandate acceleration as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Ministry-level tender board pre-qualification secures multi-year EMR platform contracts across Malaysia's public network. |
| Software Companion Development | AI-enabled diagnostic modules for PACS integration differentiate radiology-workflow vendors under Japan's PMDA pathways. |
| Reimbursement Strategy | Virtual consultation billing code normalization sustains telemedicine platform investment across Indonesian archipelago states. |
| CE Marking Pathway | European regulatory capacity enables Southeast Asian vendors to access premium hospital networks in Singapore and Australia. |
| Regulatory Approval Pathway | CDSCO and DISHA framework compliance raises barriers that favor established health IT infrastructure players in India. |
Methodological Framework
Desk research of hospital procurement databases, GPO contracts, and CMS Medicare data preceded structured interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads across China, Japan, India, and Southeast Asia. Primary fieldwork combined with secondary validation from SEC filings, NMPA cybersecurity disclosures, and PMDA software-as-medical-device registration records. Bottom-up facility-level demand modeling and top-down national health IT budget allocation analysis provided triangulation across the projection horizon.
Assumption sets held regulatory timeline structures and reimbursement framework evolution within observed patterns while varying cloud adoption velocity and AI diagnostic platform commercialization rates. Segmentation dimensions modeled include deployment model, facility scale tier, clinical application module, and regional regulatory cluster. CAGRs derived from facility penetration curves and per-bed IT spending trajectories. Forecast inputs incorporated HL7 FHIR interoperability mandate implementation schedules and PLI scheme domestic production incentive utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler cloud providers into hospital SaaS platforms would shift outcomes. Regulatory acceleration in China's NMPA cybersecurity rules or India's DISHA framework enforcement could compress vendor margins. Quarterly review of ministry tender board award patterns and AI diagnostic tool PMDA clearance timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Healthcare Enterprise Software Market