
 Medical Coding Market | 2026-2036
Medical Coding Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Coding Market Intelligence
Claims denial management revenue is reconfiguring how vendors allocate engineering resources across the medical coding value chain. Optum Inc. leverages its payer-provider data integration to preempt coding errors before submission. Epic Systems anchors hospital workflows through embedded computer-assisted coding modules within its EHR architecture. 3M Health Information Systems competes on natural language processing depth for inpatient documentation capture.
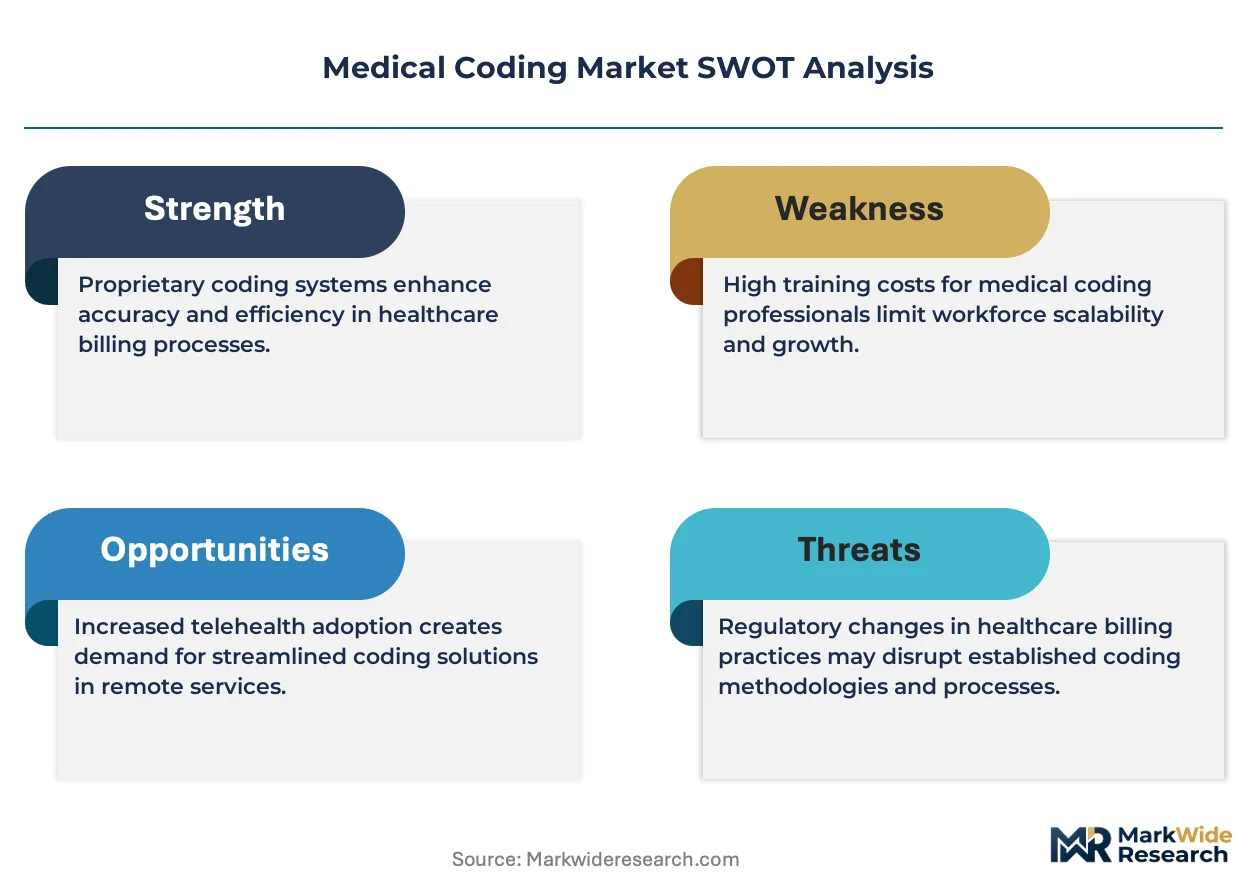
Medical coding comprises the translation of clinical documentation into standardized alphanumeric codes per ICD, CPT, and HCPCS classification systems, with AI-powered coding solutions now processing unstructured physician notes through natural language processing engines to suggest billable codes in real time. The primary commercial purpose centers on ensuring accurate reimbursement, regulatory compliance, and population health analytics for healthcare providers and payers. Computer-assisted coding holds established penetration in hospital inpatient settings where documentation volume and complexity justify automation investment, while AI-powered coding represents the fastest-expanding product type as large language models improve specialty-specific accuracy. Cloud-based deployment is displacing on-premises installations among mid-size physician practices seeking reduced IT overhead and faster implementation cycles.
FDA oversight of clinical decision support software intersects with CMS coding accuracy requirements and HIPAA privacy mandates to shape product development priorities and go-to-market constraints for platform vendors. The EU AI Act's risk classification framework for healthcare algorithms will affect European market entry strategies for NLP coding engines trained on U.S. clinical corpora. Stakeholders must monitor evolving payer audit protocols and AI liability standards to align R&D roadmaps with enforcement trajectories.
Market Dynamics
AI-assisted coding platforms are compressing reimbursement cycles by automating ICD-10-CM/PCS translation, forcing vendors to reallocate engineering resources toward real-time denial prevention rather than retrospective audit tools.
Growth Catalysts
- CMS Value-Based Care Mandates:Hospital systems face financial penalties for documentation gaps, accelerating procurement of clinical documentation integrity platforms that close coding accuracy gaps before claim submission.
- Natural Language Processing Engines:Large language models trained on specialty-specific clinical corpora now process unstructured physician notes into billable codes with accuracy thresholds that justify enterprise deployment.
- United States Federal EHR Requirements:Sustained enforcement of electronic health record interoperability rules creates procurement pressure for integrated coding modules within hospital IT architectures.
Market Restraints
- HIPAA Compliance Architecture:Cloud-based NLP coding engines face structural friction from state-level privacy variations that complicate multi-tenant deployment models.
- Physician Documentation Variability:Unstructured clinical notes retain idiosyncratic shorthand and specialty-specific nomenclature that resists standardized code mapping.
- Legacy On-Premises Installations:Hospital capital cycles and IT security protocols delay migration to cloud-native coding platforms despite operational advantages.
Strategic Opportunities
- Ambulatory Surgery Centers:These facilities operate with thinner administrative staffing than hospitals, creating white space for lightweight, specialty-tuned coding automation.
- EU AI Act Risk Classification:Healthcare algorithm certification requirements will favor vendors who pre-validate NLP coding engines for high-risk medical device equivalence.
- Telehealth Documentation Streams:Virtual care encounters generate distinct documentation patterns that incumbent inpatient-focused platforms have not optimized.
Industry Challenges
- Certified Professional Coder Shortage:The credentialing pipeline for AAPC and AHIMA certifications lags demand, constraining quality assurance staffing for AI-suggested codes.
- EHR Integration Complexity:Computer-assisted coding modules must map to proprietary data architectures from Epic, Cerner, and MEDITECH, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Coding Market |
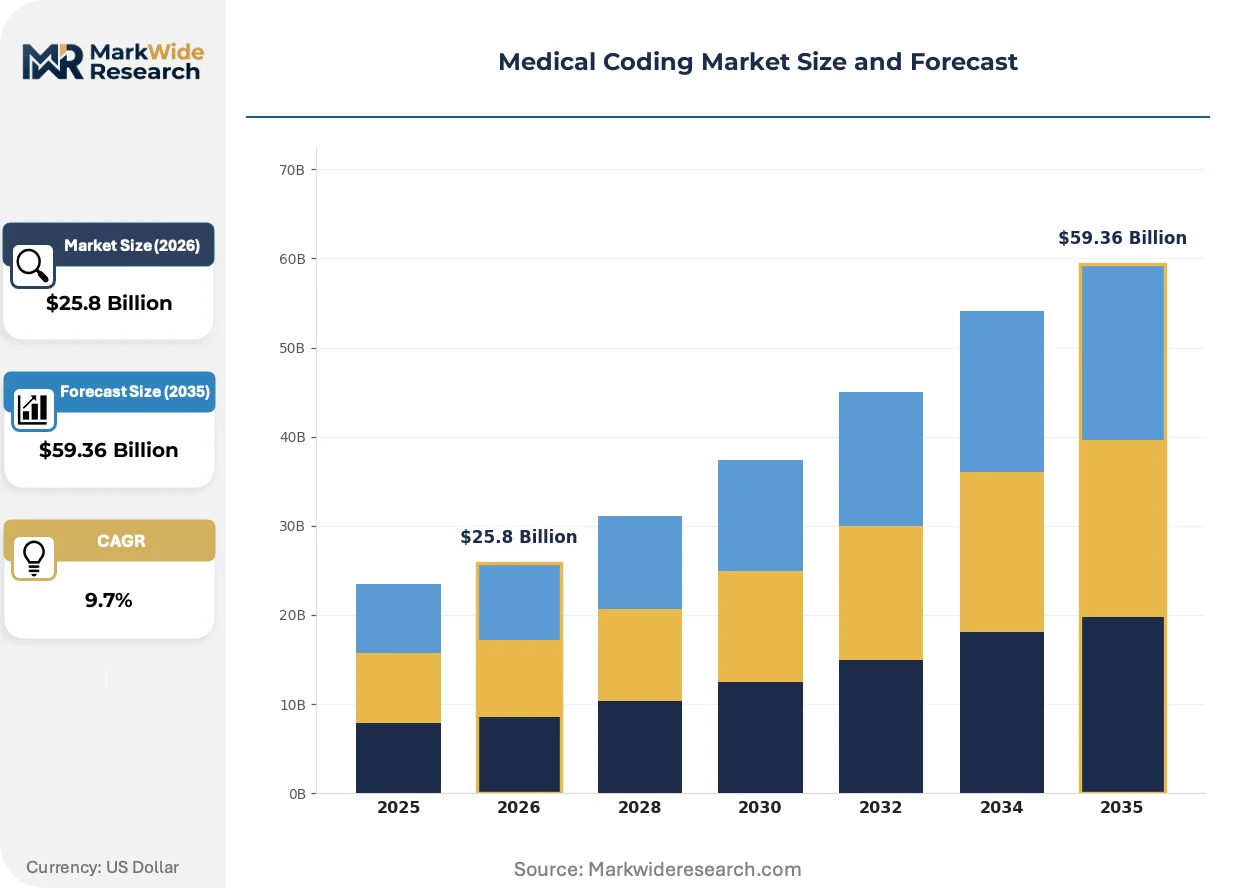
| Market Size in 2026 | $25.8 Billion |
| Market Size in 2035 | $59.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computer-Assisted Coding, Manual Coding, AI-Powered Coding, Natural Language Processing, Speech Recognition Application: Inpatient Coding, Outpatient Coding, Emergency Care Documentation, Physician Documentation, Clinical Trials Coding End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Physician Practices, Rehabilitation Centers Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Hosted Services, Web-Based Platforms |
| Companies Covered | AGS Health, CureMD, Optum Inc., Epic Systems, Ciox Health, 3M Health Information Systems, Aviacode Incorporated, Athenahealth, GeBBS Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Coding Market Strategic Shifts & Innovations
Automation is penetrating deeper into clinical workflows, with coding platforms evolving from retrospective audit tools to real-time decision support embedded at the point of documentation.
Large language model architectures are hybridizing rule-based coding logic with probabilistic code suggestion, enabling platforms to weight ICD-10-CM specificity guidelines against payer-specific denial patterns. Hospital revenue cycle departments are piloting these hybrid systems in high-complexity surgical specialties where documentation nuance drives reimbursement variance. The structural consequence is compression of coding backlogs from days to hours, reducing accounts-receivable aging.
The EU AI Act's risk-based classification framework is redefining product development roadmaps for vendors seeking European market entry. NLP coding engines trained on United States clinical corpora must now demonstrate algorithmic transparency and bias mitigation documentation to qualify for high-risk healthcare algorithm status. European hospital procurement committees are beginning to require CE-marking equivalence for clinical decision support functions, forcing architectural redesigns.
Mid-size physician practices are consolidating vendor relationships around EHR-embedded coding modules rather than standalone platforms. These buyers prioritize single-contract simplicity over best-of-breed functionality, compressing the addressable market for independent coding software vendors. The shift is most visible in United States multi-specialty group practices where IT staffing constraints favor integrated workflow tools over point solutions requiring separate implementation.
Medical Coding Market Segmentation
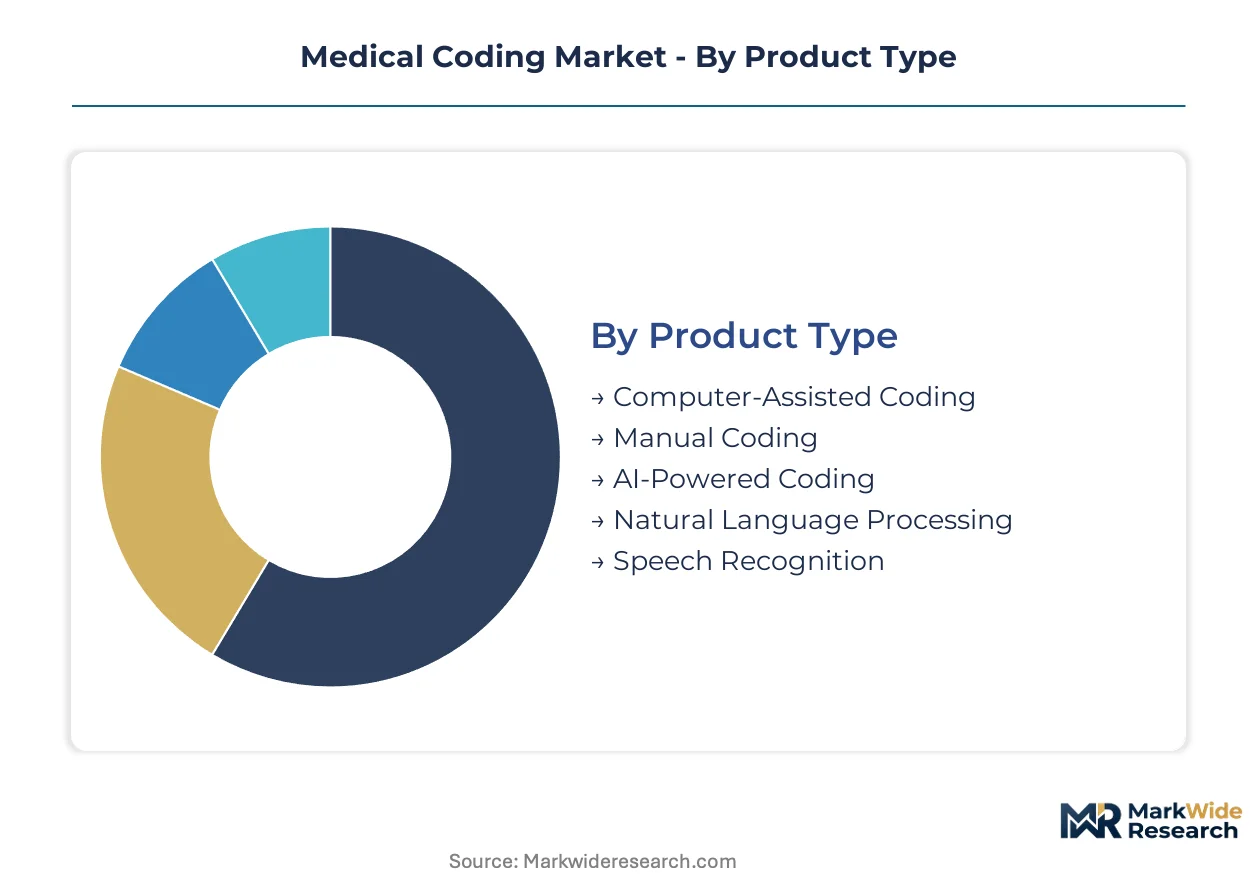
Medical coding segmentation reflects divergent technology maturities and procurement cycles across healthcare delivery settings. Product type and deployment mode decisions directly determine implementation timelines, while application and end-user categories shape pricing structures and integration complexity.
Product Type:
Cycle times vary sharply: manual coding processes turn over quarterly as staffing contracts renew, while AI-powered platforms operate on multi-year enterprise licenses with annual model retraining cycles.
- Computer-Assisted Coding:Rule-based engines flag documentation gaps and suggest ICD-10-CM/PCS codes through embedded EHR workflows. United States hospital systems concentrate procurement here for inpatient surgical documentation where coder productivity gains justify licensing costs.
- AI-Powered Coding:Large language models process unstructured clinical notes into billable codes with specialty-specific accuracy thresholds. Ambulatory surgical centers in the United States are expanding fastest here, driven by thin administrative staffing and real-time denial prevention requirements.
- Manual Coding:Certified professional coders review clinical documentation without algorithmic assistance, remaining prevalent in small physician practices with low claim volumes and limited IT infrastructure.
- Natural Language Processing:Text-mining engines extract clinical entities from physician narratives to populate structured code fields, deployed primarily as embedded modules within broader computer-assisted coding platforms.
- Speech Recognition:Voice-to-text systems capture clinician dictation for downstream coding extraction, gaining traction in emergency care settings where documentation speed constrains revenue cycle performance.
Computer-assisted coding dominates installed base. AI-powered coding is where expansion concentrates.
Application:
Cost tiers stratify by documentation complexity: inpatient coding commands premium platform pricing due to ICD-10-PCS procedural intricacy, while physician documentation operates at lower per-encounter license rates.
- Inpatient Coding:ICD-10-CM diagnosis and ICD-10-PCS procedure code assignment for hospital admissions requires navigating multi-day stays with hundreds of billable elements. United States health systems anchor procurement here, pressured by CMS hospital-acquired condition penalties and DRG optimization requirements.
- Outpatient Coding:CPT and HCPCS Level II coding for same-day services including surgeries, diagnostics, and clinic visits. Diagnostic laboratories in the United States are automating here fastest, facing high test volumes with thin margin structures that demand throughput efficiency.
- Emergency Care Documentation:Time-pressured coding for unscheduled acute encounters with incomplete clinical information at point of service.
- Physician Documentation:Point-of-care code capture during patient encounters, increasingly embedded within EHR note templates to reduce retrospective coder review.
- Clinical Trials Coding:MedDRA and WHO-Drug standardization for pharmaceutical research, requiring specialized dictionaries and regulatory submission protocols distinct from reimbursement coding.
Inpatient coding captures highest platform pricing. Outpatient coding is climbing the fastest.
End User:
Customer types span capital intensity spectrum: hospitals deploy enterprise-wide platforms with dedicated implementation teams, while physician practices purchase per-provider SaaS subscriptions.
- Hospitals:Multi-departmental deployments spanning inpatient, outpatient, and emergency settings with integration into Epic, Cerner, or MEDITECH architectures. United States hospital systems are consolidating vendor relationships around EHR-embedded modules to reduce IT complexity.
- Physician Practices:Small to mid-size group practices prioritizing cloud-native solutions with minimal on-site infrastructure. These buyers favor single-contract EHR integration over standalone coding platforms due to staffing constraints.
- Ambulatory Surgical Centers:Freestanding facilities performing same-day procedures with compressed revenue cycles and limited coding staff.
- Diagnostic Laboratories:High-volume test processors requiring automated code assignment for molecular pathology and genomic sequencing panels.
- Rehabilitation Centers:Long-term acute care and skilled nursing facilities with distinct documentation patterns and payer mix complexities.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest.
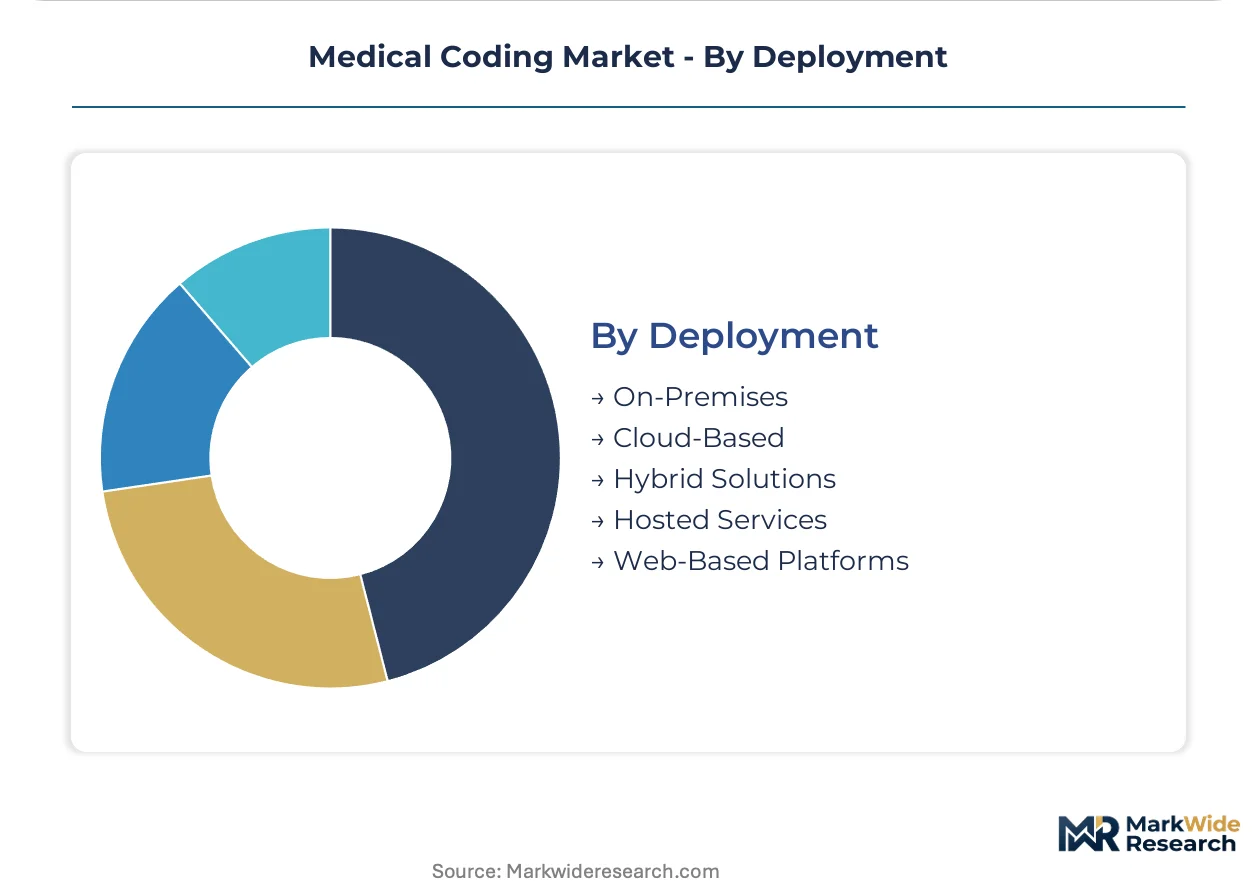
Deployment:
Volume concentration tilts toward cloud migration: mid-size practices are displacing on-premises installations fastest, while health systems retain hybrid architectures for security-sensitive workloads.
- Cloud-Based:Multi-tenant SaaS platforms with automatic updates and reduced IT overhead. United States physician practices are migrating here fastest, driven by HIPAA-compliant vendor architectures and subscription pricing that preserves working capital.
- On-Premises:Locally installed software behind hospital firewalls with direct EHR database integration. Large United States health systems retain this model for inpatient environments where data residency policies and legacy security protocols constrain external hosting.
- Hybrid Solutions:Split architectures with sensitive workloads on-premises and analytics engines cloud-hosted, adopted by hospitals navigating phased migration timelines.
- Hosted Services:Single-tenant private cloud deployments managed by vendor or third-party data centers, bridging control requirements with outsourced infrastructure.
- Web-Based Platforms:Browser-accessible coding tools with lighter integration requirements, targeting small practices and temporary staffing scenarios.
On-premises dominates installed base. Cloud-based deployment is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems deploy AI-assisted coding platforms for real-time denial prevention, while European hospitals prioritize EU AI Act compliance certification for clinical decision support algorithms. Emerging markets in Asia-Pacific rely on outsourced manual coding services due to lower labor costs and limited NLP infrastructure investment.
United States
Federal EHR interoperability mandates and CMS value-based care penalties drive hospital procurement of integrated coding modules. HIPAA compliance requirements shape cloud deployment architectures for multi-tenant NLP platforms. The Dallas-Fort Worth metroplex anchors revenue cycle management outsourcing clusters serving national health systems.
Germany
Hospital digitization funding under the Hospital Future Act accelerates computer-assisted coding adoption for inpatient DRG optimization. CE marking requirements for clinical decision support software filter vendor market entry. The Rhine-Ruhr metropolitan region concentrates health IT implementation services for university hospital networks.
United Kingdom
NHS England's electronic patient record standardization creates procurement windows for embedded coding automation. The UK Medicines and Healthcare products Regulatory Agency oversees software-as-medical-device classifications affecting NLP deployment. London's digital health cluster incubates specialty-specific documentation tools for private hospital groups.
India
Medical coding outsourcing hubs in Bengaluru and Hyderabad process United States health system documentation through offshore delivery centers. CDSCO guidelines for clinical decision support software remain under development, creating regulatory uncertainty for domestic AI platform vendors. Chennai's healthcare BPO corridor expands training pipelines for certified professional coders.
Japan
PMDA software certification requirements extend implementation timelines for foreign NLP coding platforms. METI's healthcare productivity initiatives subsidize hospital IT modernization including documentation automation. The Osaka-Kobe medical device cluster develops specialty-tuned coding engines for domestic hospital information systems.
Medical Coding Market Key Industry Players
Capability concentration sits with specialized health IT vendors possessing deep NLP clinical corpora; scale advantage sits with diversified technology conglomerates integrating coding modules across payer-provider workflows. The market structures around three archetypes: EHR-embedded platform vendors, standalone coding automation specialists, and revenue cycle management conglomerates with data integration assets. Dominant competitive moves include EHR partnership exclusivity arrangements and specialty-specific model training acquisitions.
Within the EHR-embedded tier, Epic Systems and athenahealth anchor hospital workflow integration strategies. Optum Inc. exemplifies the data-integrated conglomerate archetype, leveraging payer-provider connectivity across the reimbursement cycle. 3M Health Information Systems occupies a position bridging clinical documentation capture with enterprise NLP depth for inpatient environments.
| Leading Market Players |
|---|
| AGS Health |
| CureMD |
| Optum Inc. |
| Epic Systems |
| Ciox Health |
| 3M Health Information Systems |
| Aviacode Incorporated |
| Athenahealth |
| GeBBS Healthcare Solutions |
| Others |
Cost & Logistics Intelligence
The Dallas-Fort Worth logistics corridor anchors medical coding platform distribution, with freight cost dynamics compressing margins for cloud-native vendors while amplifying pricing power for EHR-embedded incumbents who bypass standalone infrastructure provisioning.
Pricing Analysis
Long-term enterprise subscription contracts dominate hospital procurement, locking multi-year SaaS commitments with annual retraining cycles built into pricing escalators. Price differentiation hinges on NLP accuracy thresholds and specialty-specific model certification against CMS audit protocols. Pricing pressure stems from mid-size physician practices consolidating vendor relationships around EHR-embedded modules. Ambulatory surgical centers exhibit highest price sensitivity due to thin administrative staffing budgets, while academic medical centers prioritize accuracy premiums over cost minimization.
Supply Chain Analysis
Extended payment terms from United States health systems strain vendor working capital, forcing supply-chain finance facilities to bridge receivables gaps for NLP engine providers. Software development concentrates in the United States, India, and Germany, with clinical corpus training data sourced from hospital partnerships, academic medical centers, and pharmaceutical research institutions. Single-source vulnerability runs through hyperscaler cloud infrastructure dependencies. Distribution runs through direct enterprise sales teams and EHR partnership channels, with implementation services subcontracted to regional health IT consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical coding is approaching a platform-economics inflection where EHR ecosystem dominance will determine vendor survival, driven by Epic's embedded workflow architecture consolidating procurement decisions around single-contract simplicity.
For Market Incumbents: Build data network effects moats by deepening payer-provider data integration across denial pattern repositories. Anchor hospital workflows through exclusive EHR partnership arrangements that preempt standalone coding platform insertion. Invest in specialty-specific NLP model training for surgical documentation complexity where reimbursement variance justifies premium positioning. Counter cloud-native entrants by emphasizing on-premises deployment options for security-sensitive health systems. For New Entrants and Emerging Players: Pursue ambulatory surgical center white space where thin staffing creates urgent demand for lightweight, real-time denial prevention tools. Target diagnostic laboratory automation where high test volumes and thin margins prioritize throughput efficiency over comprehensive platform functionality. Lead with telehealth documentation optimization, as virtual care encounter patterns remain underdeveloped by incumbent inpatient-focused architectures. For Investors and Strategic Acquirers: Niche NLP specialists with specialty-tuned clinical corpora represent the highest-conviction acquisition archetype for platform consolidation plays. Monitor EU AI Act high-risk algorithm certification timelines as inflection indicators for European market entry viability. Frame long-term positioning around clinical documentation integrity convergence with revenue cycle management, where vertical data integration creates durable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EHR Partnership Exclusivity | Epic-embedded modules capture hospital procurement decisions through workflow integration depth. |
| Specialty-Specific NLP Acquisition | Trained clinical corpora for surgical documentation differentiate accuracy thresholds against generic engines. |
| EU AI Act Pre-Certification | High-risk algorithm documentation enables European hospital procurement committee access. |
| Cloud-Native SaaS Migration | Multi-tenant architectures reduce IT overhead for mid-size physician practices seeking faster implementation. |
| Revenue Cycle Data Integration | Payer denial pattern repositories train predictive models for real-time coding accuracy improvement. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with hospital revenue cycle directors, certified professional coders, health IT procurement officers, and EHR integration specialists informed platform adoption drivers. Secondary sources include CMS reimbursement rule documentation, FDA clinical decision support guidance, EU AI Act implementation texts, and hospital GPO contract databases. Bottom-up deployment estimates and top-down market sizing triangulate volume figures.
Calibration against historical adoption curves for computer-assisted coding platforms shapes the projection framework across the analysis window. Segmentation dimensions modeled include product type, deployment mode, application complexity, and end-user capital intensity. CAGRs derive from weighted average of technology diffusion rates and procurement cycle timing. Forecast inputs incorporate certified coder shortage trajectories and NLP accuracy improvement curves.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or CMS penalty enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding EHR interoperability mandate timelines and cloud migration adoption patterns. Regulatory acceleration in AI liability standards or payer audit protocol changes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market