
 Medical Imaging Outsourcing Market | 2026-2036
Medical Imaging Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Outsourcing Market Intelligence
Diagnostic centers are reorganizing procurement patterns around teleradiology partnerships as hospital systems face radiologist staffing gaps. RadNet, Inc. leverages its national imaging center network to capture recurring outpatient volume. Radiology Partners anchors its position through exclusive contracts with large health systems across multiple states. vRad competes on turnaround time, sustaining sub-thirty-minute STAT read capabilities for emergency departments.
Medical imaging outsourcing encompasses the remote interpretation of diagnostic scans by specialized radiologists operating outside the patient's physical care location, utilizing DICOM-standard image transmission and PACS infrastructure to deliver diagnostic reports within clinically mandated timeframes. CT scan services command premium pricing due to the subspecialty expertise required for complex trauma and oncology staging interpretations. MRI services represent the fastest-growing service type as health systems defer capital expenditure on high-field magnet installations. Artificial Intelligence integration within cloud imaging platforms is concentrating margin pools among vendors that combine algorithmic triage with human over-read workflows.
FDA regulates AI-enabled diagnostic software as Software as a Medical Device, requiring clinical validation studies that shape vendor development roadmaps and customer procurement criteria. HIPAA mandates govern image transmission security and patient data handling across all outsourced arrangements, creating compliance infrastructure costs that favor scaled providers. Cloud imaging deployments face state-level telemedicine licensing requirements that fragment operational architecture. Stakeholders must monitor regulatory convergence between FDA algorithmic transparency standards and state radiologist credentialing reciprocity agreements.
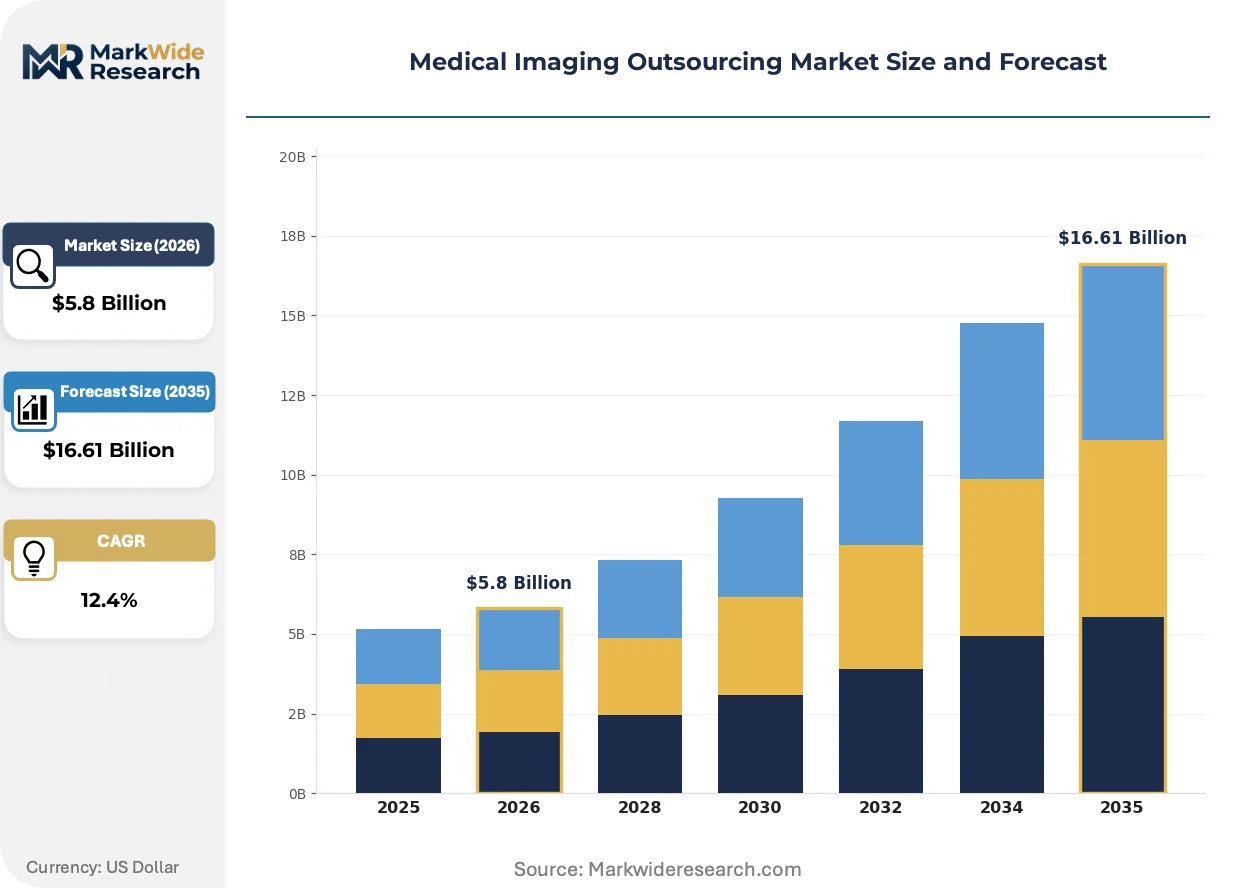
Market Dynamics
Radiologist workforce attrition is compressing interpretation capacity faster than training pipelines can replenish, forcing health systems to externalize diagnostic reads through teleradiology networks and cloud-native PACS infrastructure.
Growth Catalysts
- AI-Assisted Triage:FDA's 510(k) clearance pathway for computer-aided detection software accelerates algorithmic integration into outsourced workflows, reducing radiologist time-per-study.
- United States:Hospital system consolidation creates centralized imaging procurement offices that favor national outsourcing contracts over fragmented local arrangements.
- DICOM-Standard Interoperability:Universal image transmission protocols eliminate proprietary lock-in, lowering switching costs between teleradiology vendors.
Market Restraints
- State Licensing Fragmentation:Telemedicine credentialing reciprocity gaps force vendors to maintain redundant radiologist pools across jurisdictions, inflating operational overhead.
- Cloud Infrastructure Concentration:Reliance on hyperscale cloud providers for HIPAA-compliant storage creates single-point-of-failure risk in outsourced architectures.
- Subspecialty Radiologist Scarcity:Neuroradiology and pediatric radiology fellowship graduates remain insufficient to match demand from trauma centers and children's hospitals.
Strategic Opportunities
- India:English-speaking radiologist workforce and favorable time-zone differentials position the country as an overnight read hub for US emergency departments.
- Portable MRI Integration:Low-field magnet deployments at point-of-care sites create demand for remote interpretation of scans acquired outside traditional hospital radiology departments.
- EU AI Act:Conformity assessment requirements for high-risk medical AI establish compliance moats for vendors with established quality management systems.
Industry Challenges
- Legacy PACS Integration:Health systems running decade-old on-premise archives face costly middleware development to connect cloud teleradiology platforms.
- Quality Assurance Standardization:Discrepancy tracking between in-house and outsourced reads lacks industry-wide metrics, complicating liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Outsourcing Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $16.61 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: X-ray Services, MRI Services, Ultrasound Services, CT Scan Services End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: DICOM, PACS, Artificial Intelligence, Cloud Imaging Distribution Channel: Direct Sales, Partner Network, Online Services, Others |
| Companies Covered | vRad, ONRAD, RadNet, Inc., Radiology Partners, Vesta Teleradiology, Akumin Inc., ALM Teleradiology, NDI, National Diagnostic Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Outsourcing Market Strategic Shifts & Innovations
Algorithmic diagnostic assistance is migrating from experimental pilot programs to contractual requirements in health system RFPs, reshaping vendor selection criteria and service-level agreements.
Edge computing hardware is miniaturizing CT reconstruction algorithms for deployment directly on scanner consoles, enabling preliminary image quality validation before transmission to remote radiologists. Emergency departments in rural United States hospitals are adopting these embedded systems to reduce rescan rates. The technology is compressing turnaround time commitments that teleradiology vendors must guarantee to win contracts.
FDA's evolving Software as a Medical Device guidance requires clinical validation studies for AI-assisted diagnostic tools, extending development timelines for algorithm vendors seeking 510(k) clearance. Radiologist over-read requirements remain mandatory for all cleared algorithms, preserving human-in-the-loop workflows. Vendors with existing quality management system infrastructure capture disproportionate share of new clearances.
Subscription-based per-study pricing is displacing traditional full-time-equivalent radiologist contracts in health system procurement negotiations. Large integrated delivery networks in the United States are unbundling after-hours emergency reads from daytime subspecialty interpretations, sourcing each from specialized vendors. This fragmentation concentrates volume with vendors offering narrow service depth rather than comprehensive coverage.
Medical Imaging Outsourcing Market Segmentation
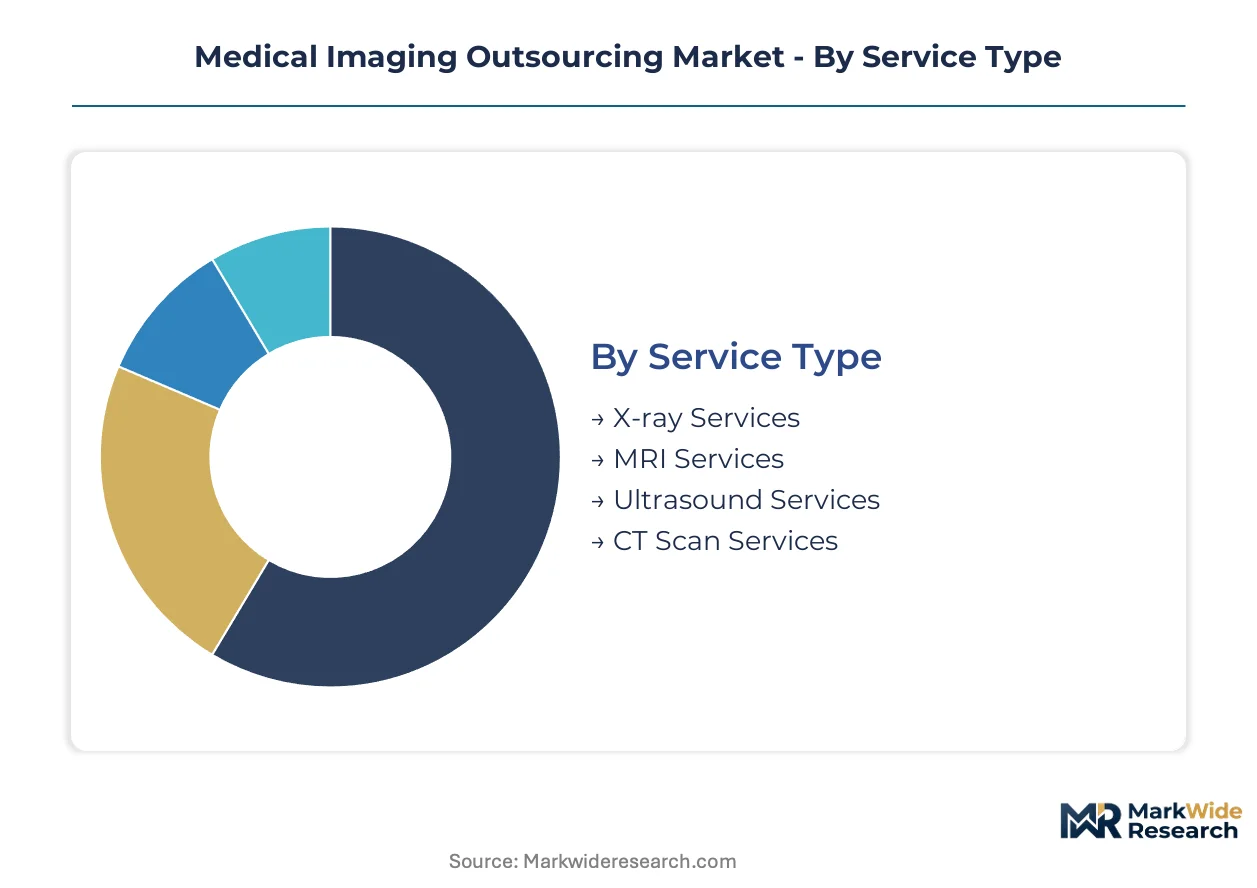
Segmentation reveals how teleradiology vendors align service configurations with buyer procurement structures. Channel selection, technology stack, and end-user scale determine pricing architecture and contract terms across the outsourcing landscape.
Service Type:
X-ray Services flow through high-volume partner networks serving diagnostic center chains, while MRI and CT services concentrate in direct sales channels targeting hospital system procurement offices.
- CT Scan Services:Complex trauma and oncology staging interpretations demand subspecialty neuroradiology expertise. Academic medical centers in the United States drive demand for 24/7 coverage of emergency stroke protocols and multiphase liver imaging.
- MRI Services:Health systems defer capital expenditure on 3T magnet installations, outsourcing musculoskeletal and cardiac interpretations instead. Community hospitals in suburban United States markets are expanding remote MRI read contracts to avoid radiologist recruitment.
- X-ray Services:High-volume screening programs and urgent care chest interpretations dominate this segment, with teleradiology vendors achieving economies through automated workflow triage.
- Ultrasound Services:Obstetric and vascular applications require real-time collaboration capabilities, limiting pure asynchronous outsourcing adoption.
By volume, X-ray Services leads. By growth pace, MRI Services is ahead.
End User:
Cost tier stratification separates enterprise health system contracts from pay-per-study arrangements with independent diagnostic operators.
- Diagnostic Centers:Independent imaging chains outsource overnight and weekend coverage to maintain accreditation without full-time radiologist payroll. RadNet's national network captures recurring outpatient volume through multi-year service agreements.
- Hospitals:Emergency departments require STAT read capabilities under thirty minutes, driving premium pricing for teleradiology vendors with subspecialty neuroradiology benches. Rural critical access hospitals in the United States represent the fastest-expanding customer tier.
- Clinics:Primary care and specialty physician groups purchase bundled interpretation packages for point-of-care ultrasound and limited X-ray services.
- Research Institutions:Clinical trial imaging cores demand FDA 21 CFR Part 11 compliant workflows with audit trails for regulatory submissions.
By contract value, Hospitals dominate. By expansion trajectory, Diagnostic Centers are climbing the fastest.
Technology:
Application maturity separates legacy infrastructure deployments from AI-native platform architectures reshaping vendor competitive position.
- Artificial Intelligence:FDA 510(k) cleared algorithms for pulmonary nodule detection and intracranial hemorrhage triage reduce radiologist time-per-study. Vendors combining algorithmic screening with mandatory human over-read capture disproportionate share of health system RFPs.
- Cloud Imaging:Hyperscale storage and compute architectures enable geographic load balancing across radiologist pools. HIPAA-compliant deployments face state-level telemedicine licensing fragmentation that inflates operational overhead.
- PACS:Picture archiving and communication systems remain the workflow backbone, with cloud-native replacements displacing decade-old on-premise installations.
- DICOM:Universal image transmission protocols eliminate proprietary vendor lock-in, lowering switching costs between teleradiology providers.
By installed base, PACS leads. By investment flow, Artificial Intelligence is gaining share fastest.
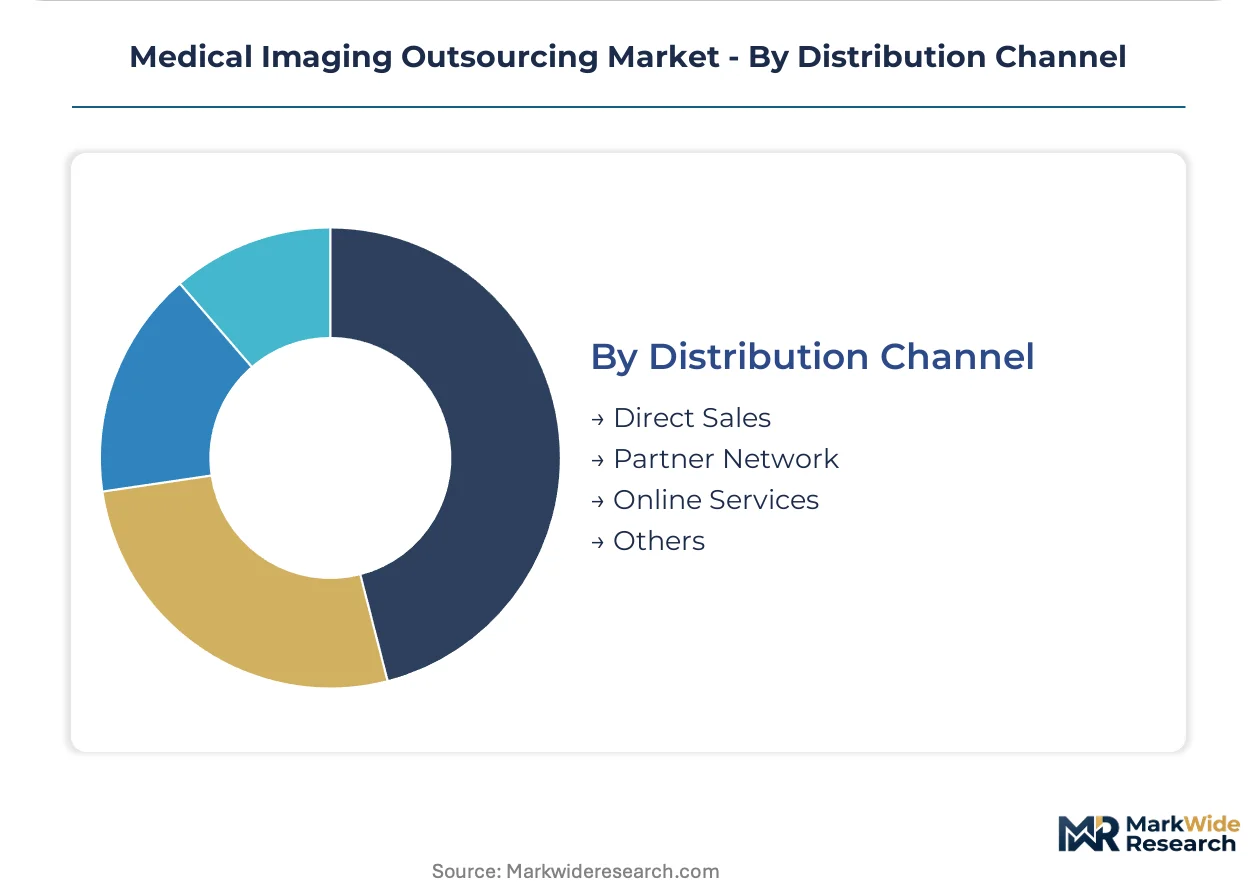
Distribution Channel:
Customer type and transaction scale determine whether vendors pursue direct enterprise relationships or layered partner intermediation.
- Direct Sales:National teleradiology vendors maintain dedicated health system account teams for integrated delivery network procurement offices. Radiology Partners anchors market position through exclusive multi-state contracts negotiated through direct channels.
- Partner Network:Regional diagnostic center chains and hospital alliances aggregate demand through group purchasing organizations. vRad competes on turnaround time commitments secured through partner-mediated emergency department placements.
- Online Services:Self-service platforms enable small clinics and individual practitioners to upload studies and receive interpretations without contractual negotiation.
- Others:Academic consortia and government health systems employ specialized procurement vehicles including cooperative agreements and sole-source justifications.
By revenue concentration, Direct Sales leads. By coverage expansion, Partner Network shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital system procurement offices in the United States concentrate contract value, while diagnostic center chains in Germany and India drive volume expansion through overnight read partnerships.
United States
Health system consolidation creates centralized imaging procurement offices favoring national outsourcing contracts. FDA's 510(k) clearance pathway for AI-assisted diagnostic tools accelerates vendor selection criteria. Emergency departments in rural Texas and Arizona hospitals expand teleradiology partnerships to address radiologist staffing gaps.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia demand 24/7 neuroradiology coverage for stroke protocols. EU AI Act conformity assessment requirements shape vendor compliance roadmaps for algorithmic transparency. Berlin-based diagnostic chains outsource overnight CT interpretations to maintain accreditation without expanding payroll.
India
English-speaking radiologist workforce and favorable time-zone differentials position the country as an overnight read hub for US emergency departments. CDSCO regulation of imported diagnostic software creates compliance infrastructure for cloud imaging platforms. Bangalore and Hyderabad imaging centers serve as remote interpretation backbones for North American health systems.
United Kingdom
NHS imaging backlogs drive demand for external radiology reads through teleradiology procurement frameworks. MHRA guidance on Software as a Medical Device extends development timelines for AI algorithm vendors. London and Manchester hospital trusts consolidate diagnostic contracts with national outsourcing providers.
Canada
Rural critical access hospitals in Alberta and Saskatchewan outsource emergency imaging to address subspecialty radiologist scarcity. Health Canada regulation of cloud-based diagnostic tools mandates HIPAA-equivalent data handling standards. Toronto-based academic centers pilot AI-assisted triage for pulmonary nodule detection workflows.
Medical Imaging Outsourcing Market Key Industry Players
Player mix skews toward national teleradiology networks with dedicated health system account teams. Market structure concentrates around three strategic tiers: scale-driven vendors with multi-state exclusive contracts, turnaround-time specialists competing on STAT read capabilities, and regional diagnostic chains with captive radiologist pools. Dominant competitive moves include exclusive contracting with integrated delivery networks and geographic load-balancing across radiologist benches.
Among US-based teleradiology networks, vRad, RadNet, Inc., and Radiology Partners exemplify distinct competitive archetypes. vRad occupies the rapid-turnaround position with sub-thirty-minute emergency read capabilities. RadNet, Inc. anchors the outpatient volume capture model through its national imaging center network. Radiology Partners sits within the exclusive contracting tier, securing multi-state arrangements with large health system procurement offices.
| Leading Market Players |
|---|
| vRad |
| ONRAD |
| RadNet, Inc. |
| Radiology Partners |
| Vesta Teleradiology |
| Akumin Inc. |
| ALM Teleradiology |
| NDI |
| National Diagnostic Imaging |
| Others |
Cost & Logistics Intelligence
FDA's 510(k) clearance pathway for AI-assisted diagnostic software gates both vendor qualification and price differentiation simultaneously, separating algorithm-enabled platforms from legacy interpretation services through mandatory clinical validation investments that concentrate margin pools among scaled providers.
Pricing Analysis
Next-generation AI-native platforms command premium positioning against prior-generation cloud-PACS offerings and legacy on-premise installations still common in rural hospital systems. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance status and subspecialty neuroradiology bench depth. Cost compression in the standard tier intensifies as subscription-based per-study models displace full-time-equivalent contracts. Rural critical access hospitals exhibit highest price sensitivity, while academic medical centers prioritize turnaround time guarantees over per-unit economics.
Supply Chain Analysis
Just-in-time radiologist deployment dominates overnight read operations, though strategic stockpiling of credentialed subspecialty benches across state jurisdictions addresses licensing reciprocity fragmentation. Supply concentrates in the United States for daytime subspecialty interpretation, India for overnight emergency coverage, and Germany for EU-compliant algorithm development. Raw material dependencies include cloud compute infrastructure from hyperscale providers, DICOM-standard transmission protocols, and fellowship-trained neuroradiologist labor pools. Single-source vulnerability in hyperscale cloud storage creates operational concentration risk. Distribution runs through direct enterprise sales for health system procurement offices and partner-mediated channels for diagnostic center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DICOM-standard interoperability has triggered platform-economics inflection, collapsing proprietary lock-in advantages and redistributing competitive power toward vendors with modular AI integration capabilities.
For Market Incumbents: Fortify market position through exclusive multi-state contracting with consolidated health system procurement offices and backward integration into cloud-native PACS infrastructure. Radiologist workforce attrition threatens service-level agreement compliance, making captive fellowship pipeline investments essential. Vertical integration into algorithm development preserves margin capture as FDA 510(k) clearance requirements escalate. For New Entrants and Emerging Players: Lead with portable MRI interpretation services for point-of-care deployments at rural critical access hospitals and urgent care networks, the most penetrable segment given capital expenditure constraints on magnet installations. Target subscription-based per-study pricing to bypass incumbent full-time-equivalent contract dominance. Partner with low-field MRI hardware manufacturers for bundled go-to-market positioning. For Investors and Strategic Acquirers: EU AI Act conformity assessment requirements reshape the acquisition landscape toward vendors with established quality management systems and algorithmic transparency documentation. Long-term viability centers on platforms combining human over-read workflows with cleared diagnostic algorithms. Monitor FDA 510(k) clearance velocity as inflection indicator for vendor scalability.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm 510(k) Clearance | FDA validation studies accelerate vendor selection criteria in health system RFPs. |
| Cloud-Native PACS Migration | Hyperscale deployments enable geographic load balancing across radiologist pools. |
| Exclusive Health System Contracting | Multi-state arrangements anchor recurring revenue through centralized procurement offices. |
| Overnight Read Hub Development | India-based English-speaking benches capture US emergency department volume through time-zone arbitrage. |
| Subspecialty Fellowship Pipeline | Neuroradiology and pediatric radiology training investments address scarcity-driven service gaps. |
Research Approach
Desk research of FDA 510(k) clearance databases, hospital procurement contract filings, and radiologist workforce surveys preceded structured interviews with teleradiology vendor executives, health system imaging directors, and GPO contracts managers. Primary fieldwork with diagnostic center chain operators and cloud infrastructure providers combined with secondary validation against DICOM standard documentation and state telemedicine licensing records. Bottom-up service volume estimates triangulated against top-down health system expenditure analysis.
Variance decomposition across service type, end-user scale, technology deployment model, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented adoption curves incorporating AI integration velocity, radiologist supply constraints, and hospital consolidation patterns. Forecast inputs included fellowship graduation rates by subspecialty and cloud infrastructure capex disclosures from hyperscale providers.
Forecasts assume regulatory continuity in FDA Software as a Medical Device guidance and state-level telemedicine reciprocity frameworks; material policy shifts would require re-modeling. Algorithmic transparency mandates, radiologist licensing compact expansion, or cloud infrastructure compliance breaches represent specific risk factors. Revision becomes warranted when AI-assisted read penetration crosses thresholds that alter human-in-the-loop workflow economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Systems Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market