
 Dentistry EMR Software Market | 2026-2036
Dentistry EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dentistry EMR Software Market Insights
Cloud-native architecture certification is redrawing competitive boundaries in dentistry EMR software. Epic Systems leverages hospital system integration to anchor enterprise dental deployments. Henry Schein One sustains channel dominance through its distributor relationships with private practices. Dentrix Ascend specializes in SaaS transitions for mid-sized dental groups seeking minimal IT overhead.
Dentistry EMR software digitizes patient records, treatment planning, billing, and imaging workflows through structured data architectures that support interoperability standards such as HL7 FHIR. Cloud-based deployment leads segment growth due to lower capital expenditure and automatic regulatory updates, while on-premise systems retain share among security-sensitive hospital dental departments. Artificial Intelligence integration represents the fastest-expanding technology segment, with algorithms now automating radiographic analysis and predictive scheduling to reduce chair-time waste.
FDA oversight of software-as-medical-device classifications, HIPAA privacy rule enforcement by the Office for Civil Rights, and ONC certification requirements collectively elevate barriers for uncredentialed entrants. Stakeholders must monitor evolving interoperability mandates and cybersecurity breach notification thresholds that reshape vendor liability and procurement criteria.
Market Dynamics
Cloud-native architecture certification is decomposing legacy on-premise installations across dental group practices, forcing vendors to rebuild interoperability stacks around HL7 FHIR standards rather than retrofit aging codebases.
Growth Catalysts
- ONC Certification Mandates:United States dental software procurement now requires 21st Century Cures Act compliance, accelerating replacement cycles for uncertified legacy systems.
- AI-Enabled Radiographic Analysis:Machine learning algorithms automating caries detection and periodontal assessment are compressing diagnostic timeframes in high-volume practices.
- Multi-Location Consolidation:Dental service organizations spanning 10+ locations are standardizing on single-platform EMR deployments to centralize revenue cycle management.
Market Restraints
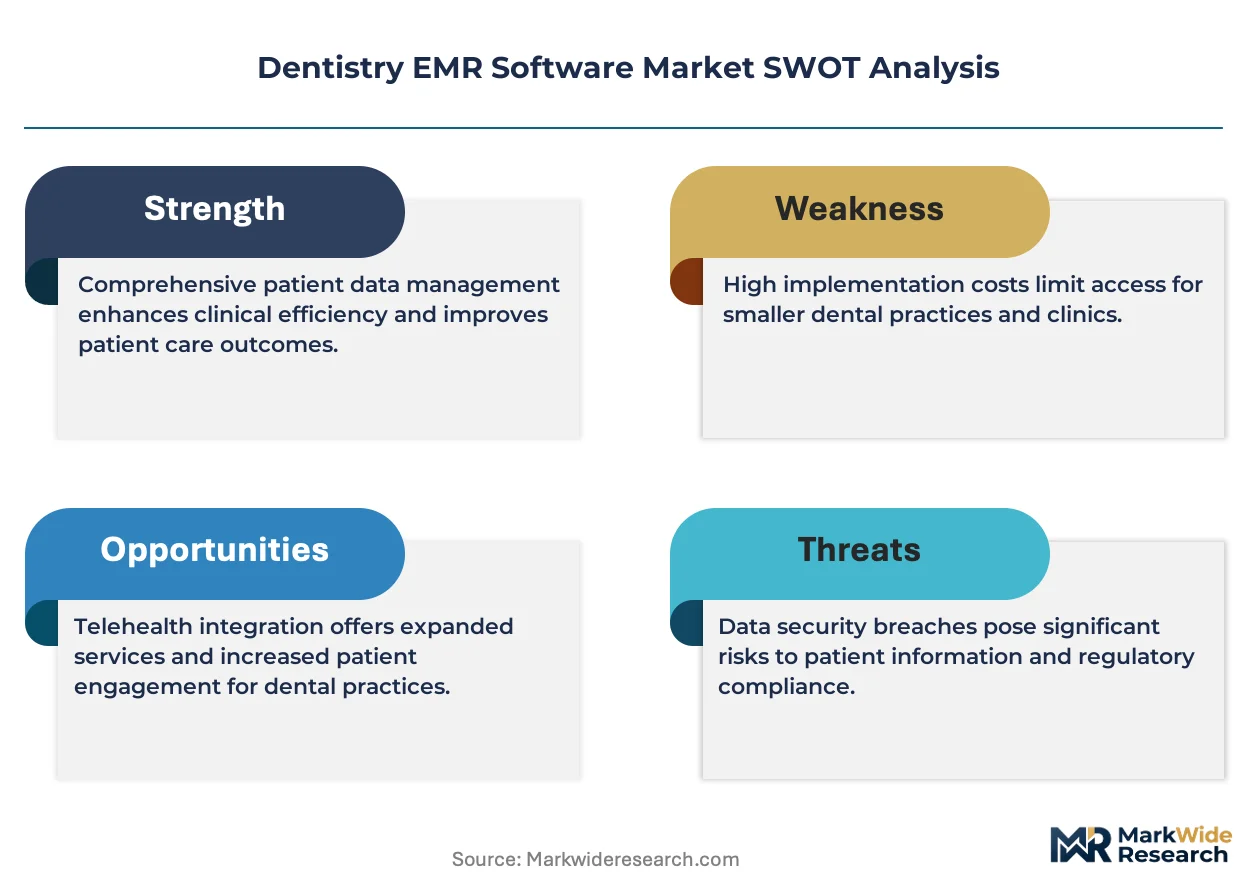
- HIPAA Breach Liability Exposure:Office for Civil Rights enforcement actions impose per-record penalties that disproportionately burden small practice operators without dedicated security staff.
- Data Migration Complexity:Legacy Dentrix and Eaglesoft installations contain decades of unstructured imaging archives that resist automated porting to cloud schemas.
- Subscription Cost Compression:Per-provider SaaS fees accumulating across hygiene, associate, and specialist licenses erode margins for practices with high staff turnover.
Strategic Opportunities
- Teledentistry Integration:Asynchronous consultation workflows and remote monitoring modules open revenue streams in rural United States counties lacking specialist density.
- DSO-Native Platform Design:Enterprise-grade analytics dashboards and centralized credentialing tools address the procurement criteria of dental service organizations scaling past 50 locations.
- FDA Software-as-Medical-Device Pathway:Diagnostic algorithms securing 510(k) clearance for radiographic interpretation command premium positioning in academic hospital dental departments.
Industry Challenges
- Interoperability Engineering Talent Scarcity:Vendors compete for developers proficient in both HL7 FHIR implementation and dental-specific workflow logic, inflating compensation benchmarks.
- Legacy Hardware Amortization Cycles:Practices with recently purchased panoramic imaging units resist cloud transitions requiring parallel infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dentistry EMR Software Market |
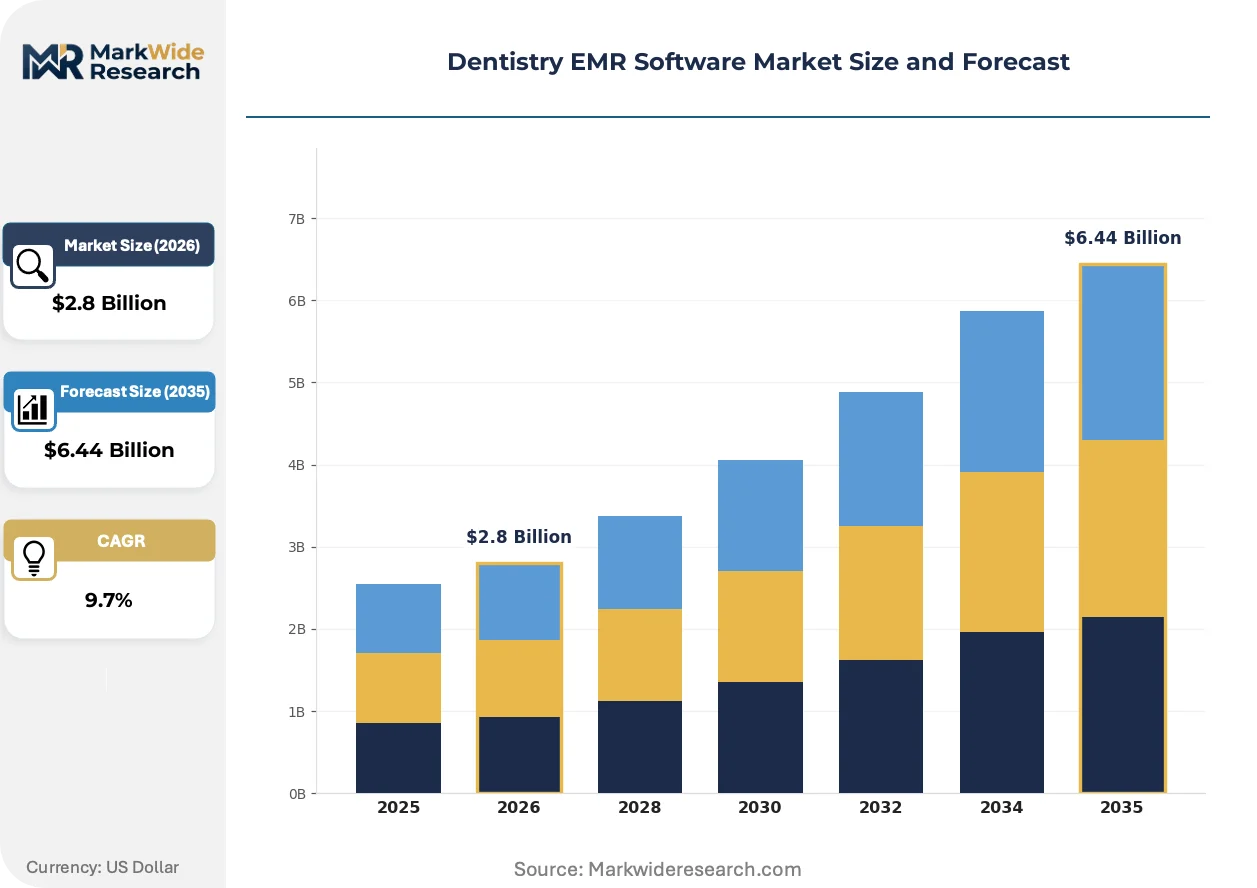
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Mobile Applications, Hybrid Solutions End User: Dentists, Dental Clinics, Hospitals, Orthodontists Technology: Artificial Intelligence, Telehealth, Big Data, Blockchain Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hybrid Cloud |
| Companies Covered | eClinicalWorks, Eaglesoft, Dentrix Ascend, Carestack, Open Dental, Curve Dental, AdvancedMD, Henry Schein One, Epic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dentistry EMR Software Market Trends and Innovations
Artificial intelligence integration is decomposing traditional diagnostic workflows, with algorithmic analysis now standardizing interpretation quality across operator skill levels and reducing variability in treatment planning.
Natural language processing is decomposing manual charting conventions. Voice-activated perio charting and automated clinical note generation are penetrating multi-provider practices in the United States and Germany. Mid-sized dental groups adopting these tools report 15-20% compression in documentation overhead per appointment.
EU MDR and FDA software-as-medical-device classifications are tightening validation requirements for diagnostic algorithms. Vendors must now maintain quality management systems and post-market surveillance infrastructure previously unnecessary for practice management modules. European dental technology distributors are filtering procurement lists to exclude uncertified AI diagnostic tools.
Subscription fatigue among independent practitioners is fragmenting purchasing authority. Practice owners are unbundling EMR decisions from equipment financing packages and negotiating module-specific contracts rather than accepting all-in-one suites. This pattern concentrates in the United States Pacific Northwest and German private practice clusters where dentist labor mobility remains elevated.
Dentistry EMR Software Market Segmentation
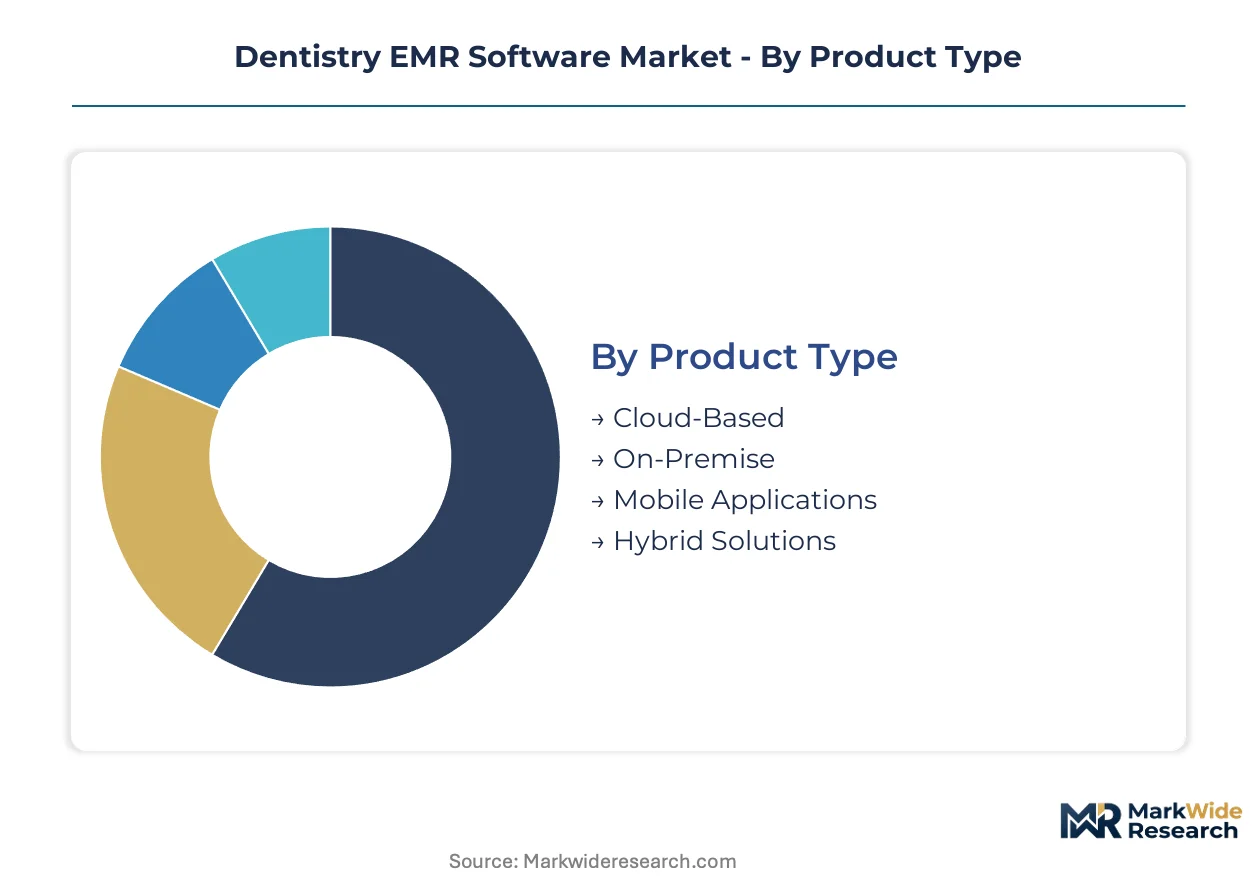
Segmentation in dentistry EMR software reveals how procurement authority fragments across practice scales and IT maturity levels. Cloud-native platforms command premium pricing while legacy on-premise installations persist in security-sensitive hospital dental departments. Understanding these divides illuminates where vendors must rebuild interoperability stacks versus defend installed base.
Product Type:
Margin pools concentrate in subscription-based cloud platforms where automatic regulatory updates reduce compliance labor for multi-location dental groups.
- Cloud-Based:SaaS architectures with HL7 FHIR-native interoperability eliminate capital expenditure burdens. Dental service organizations across the United States and Germany prioritize these platforms for centralized revenue cycle management across 10-plus locations. Automatic ONC certification updates reduce dedicated IT staffing requirements.
- On-Premise:Local server installations with direct hardware control retain preference among hospital dental departments bound by institutional cybersecurity protocols. Academic medical centers in Japan and Germany maintain these systems to satisfy internal audit committees and legacy imaging hardware integration.
- Mobile Applications:Smartphone-native charting and image capture tools extend chairside workflows for roaming specialists. Orthodontists in high-mobility United States markets adopt these for satellite clinic coverage.
- Hybrid Solutions:Split architectures keeping imaging data local while routing scheduling and billing through cloud layers. German private practices with recent panoramic unit investments favor this transitional path.
Cloud-Based holds installed capacity. Hybrid Solutions is rotating up the share rankings.
End User:
Procurement scale and decision velocity diverge sharply between fragmented independent practices and consolidated dental service organizations.
- Dentists:Solo and small-group general practitioners with high price sensitivity and limited IT staff. Subscription fatigue in the United States Pacific Northwest drives unbundling of EMR decisions from equipment financing.
- Dental Clinics:Multi-provider group practices with standardized workflows and centralized administration. These entities in Germany and Japan drive demand for AI-enabled radiographic analysis modules.
- Hospitals:Academic and community hospital dental departments with institutional procurement committees. HIPAA breach liability exposure shapes vendor selection criteria in United States hospital systems.
- Orthodontists:Specialty practices with imaging-intensive workflows and extended treatment timelines. Remote monitoring modules open revenue streams for these operators in rural United States counties.
Dental Clinics anchor volume concentration. Orthodontists are climbing the fastest as teledentistry integration expands addressable case loads.
Technology:
Regulatory certification requirements now separate premium-positioned diagnostic tools from commodity practice management modules.
- Artificial Intelligence:Machine learning algorithms automating caries detection and periodontal assessment. FDA 510(k) clearance for radiographic interpretation commands premium positioning in United States academic hospital dental departments. EU MDR compliance filters procurement lists at European dental technology distributors.
- Telehealth:Asynchronous consultation workflows and remote patient monitoring infrastructure. Rural United States counties lacking specialist density generate concentrated demand for these modules.
- Big Data:Population-level analytics platforms for dental service organizations scaling past 50 locations. Enterprise-grade dashboards address centralized credentialing and cross-practice benchmarking.
- Blockchain:Distributed ledger architectures for immutable consent records and supply chain verification. Early pilots in German private practice clusters test credential portability.
Artificial Intelligence holds installed capacity. Telehealth is rotating up the share rankings.
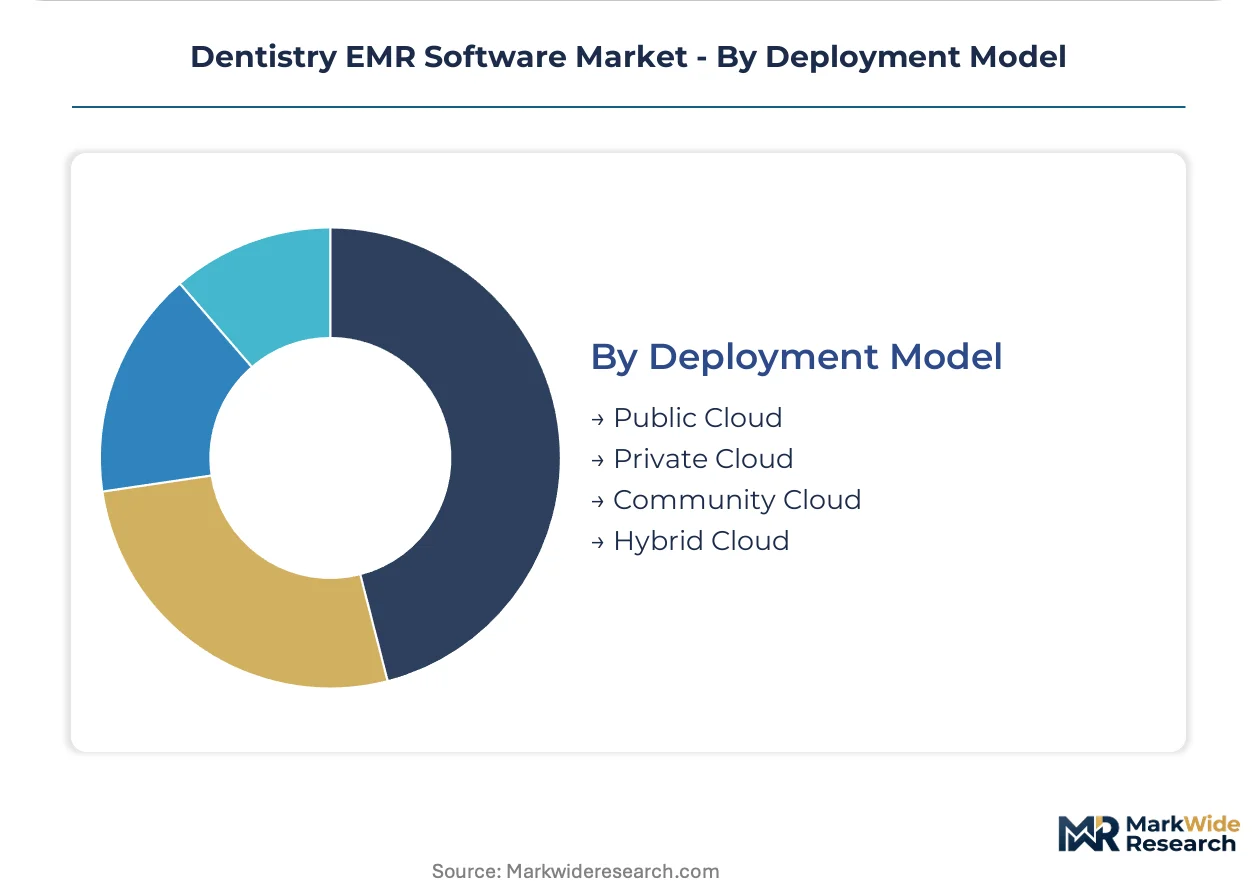
Deployment Model:
Data residency requirements and latency sensitivity determine cloud architecture selection across national regulatory boundaries.
- Public Cloud:Shared infrastructure with automatic scaling and geographic redundancy. Cost compression in per-provider SaaS fees erodes margins for United States practices with high staff turnover.
- Private Cloud:Dedicated single-tenant environments with customized security controls. Japanese dental groups with strict data localization mandates favor these deployments.
- Community Cloud:Collaborative infrastructure shared among affiliated practices or regional dental associations. German private practice clusters leverage these for collective bargaining on vendor terms.
- Hybrid Cloud:Dynamic workload placement between private and public tiers based on sensitivity classification. United States dental service organizations use these for patient-facing versus administrative data separation.
Public Cloud dominates transaction volume. Private Cloud is gaining share fastest as data sovereignty enforcement tightens across European and Asia-Pacific jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in dentistry EMR software favor net-importing jurisdictions with stringent regulatory certification requirements. The United States generates surplus platform development capacity while Germany and Japan rely on cross-border licensing for specialized diagnostic modules.
United States
HIPAA enforcement by the Office for Civil Rights accelerates platform replacement cycles among small practices. ONC certification mandates under the 21st Century Cures Act filter procurement lists to compliant vendors. Dental service organizations in Texas and Florida drive concentrated demand for multi-location cloud deployments.
Germany
EU MDR compliance requirements elevate barriers for diagnostic algorithm vendors serving academic hospital dental departments. The country's national data protection regulator enforces strict data localization for patient records. Private practice clusters in Bavaria and North Rhine-Westphalia pilot hybrid cloud architectures to preserve recent imaging hardware investments.
Japan
METI interoperability standards push dental clinics toward HL7 FHIR-native platforms. PMDA oversight of software-as-medical-device classifications extends validation timelines for AI diagnostic tools. Tokyo and Osaka dental groups favor private cloud deployments to satisfy institutional audit committees.
United Kingdom
NHS Digital procurement frameworks standardize EMR requirements across community dental services. GDPR compliance costs disproportionately burden independent practitioners without dedicated compliance staff. London and Southeast England dental groups concentrate demand for teledentistry modules addressing rural specialist access gaps.
India
CDSCO medical device regulations increasingly capture software diagnostic tools in scope. The country's national health authority promotes EMR adoption through public health insurance expansion. Bangalore and Hyderabad dental chains drive cloud-native platform demand among mid-sized group practices.
Dentistry EMR Software Market Competitive Landscape
Concentration sits with integrated health system vendors and dental-specific software specialists. Market structure divides between hospital-anchored enterprise platforms and practice-focused SaaS providers. Three archetypes dominate: health system integrators leveraging existing infrastructure, dental channel specialists with distributor relationships, and cloud-native challengers targeting mid-market consolidation. Competitive moves center on interoperability certification races and AI diagnostic module development.
Within the health system integrator tier, Epic Systems occupies a position bridging hospital IT infrastructure with dental department workflows. Henry Schein One anchors the dental channel specialist archetype through its distributor network reach. Dentrix Ascend exemplifies the cloud-native transition specialist targeting multi-location group practices.
| Leading Market Players |
|---|
| eClinicalWorks |
| Eaglesoft |
| Dentrix Ascend |
| Carestack |
| Open Dental |
| Curve Dental |
| AdvancedMD |
| Henry Schein One |
| Epic Systems |
| Others |
Pricing and Supply Chain Analysis
Cloud-native architecture certification displacing legacy on-premise installations simultaneously concentrates procurement authority among dental service organizations and compresses per-provider SaaS fees across multi-location deployments. This substitution dynamic redraws vendor pricing power while reshaping supply geography toward HL7 FHIR-native development centers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS-tiered pricing across cloud-native platforms, with automatic ONC certification updates commanding premium positioning over uncertified alternatives. Price differentiation separates HIPAA-compliant enterprise tiers from basic practice management modules, while cost compression in per-provider licensing erodes margins for United States practices with high hygiene staff turnover. Solo practitioners in the Pacific Northwest exhibit highest price sensitivity, whereas dental service organizations scaling past 50 locations demonstrate lowest sensitivity due to centralized procurement leverage.
Supply Chain Analysis
HL7 FHIR interoperability engineering talent scarcity in the San Francisco Bay Area and Boston metropolitan clusters underwrites vendor compensation inflation and extends development timelines for dental-specific workflow modules. Software development draws from India and Poland for back-end engineering, with United States and Germany hosting front-end clinical workflow specialists. Single-source vulnerability concentrates in cloud infrastructure dependencies on hyperscale providers. Distribution runs through dental technology distributors and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of developers proficient in both HL7 FHIR implementation and dental-specific clinical logic defines competitive boundaries, forcing vendors into bidding wars for scarce interoperability engineering talent that inflates platform development costs.
For Market Incumbents: Secure ONC certification maintenance as a defensive moat against cloud-native challengers, while deepening backward integration into AI diagnostic algorithm development to offset margin compression from subscription fatigue. Channel control through dental distributor relationships remains critical for defending installed base against SaaS transitions targeting mid-sized group practices. For New Entrants and Emerging Players: Anchor in teledentistry modules for rural United States counties lacking specialist density, where asynchronous consultation workflows face minimal incumbent saturation. White-space concentration exists in DSO-native analytics dashboards for dental service organizations between 10-50 locations. Go-to-market execution should leverage direct inside sales bypassing traditional equipment financing bundles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental software specialists holding legacy on-premise installed bases ripe for cloud transition. Five-to-ten year viability hinges on successful SaaS migration execution and AI diagnostic module FDA clearance attainment. Monitor 510(k) submission volume for radiographic interpretation algorithms as inflection indicator for premium positioning potential.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR-native interoperability stacks reduce compliance labor for multi-location dental groups. |
| Acquisition of Specialist Firm | AI diagnostic algorithm developers with FDA 510(k) clearance command premium enterprise positioning. |
| Geographic Expansion | Teledentistry modules penetrate rural United States counties lacking endodontist and periodontist density. |
| Strategic Partnership | Hospital system IT integration agreements anchor Epic Systems in academic dental departments. |
| Product Launch | Voice-activated perio charting tools compress documentation overhead for multi-provider practices. |
Research Methodology
Desk research of FDA 510(k) clearance databases, ONC certification registries, and dental technology distributor procurement frameworks preceded structured interviews with dental service organization IT directors, practice management software product managers, hospital dental department procurement committees, and HL7 FHIR implementation specialists. Secondary validation drew from HIPAA breach notification archives, CMS Medicare reimbursement data, and dental industry trade association technology adoption surveys. Bottom-up deployment estimates across cloud and on-premise installations triangulated against top-down market sizing from vendor revenue disclosures.
Variance decomposition across deployment model, practice scale, technology integration level, and regional regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included dental service organization consolidation velocity, AI diagnostic algorithm regulatory submission timelines, and interoperability mandate enforcement intensity across United States, German, and Japanese jurisdictions.
Decision-makers should treat outputs as directional under sustained HIPAA enforcement and ONC certification mandate assumptions; material deviation in regulatory timeline acceleration or cloud security incident frequency would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR software-as-medical-device classification enforcement and data sovereignty localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Healthcare Mobile Computers Market