
 Asia-Pacific Viral Clearance Market | 2026-2036
Asia-Pacific Viral Clearance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Viral Clearance Market Insights
Subscription-based validation service contracts is realigning how viral clearance vendors monetize recurring client relationships. WuXi AppTec leverages its integrated CDMO footprint to bundle clearance studies with ongoing manufacturing campaigns. Sartorius AG anchors its regional position through captive consumables supply tied to filtration system placements. Merck KGaA differentiates via chromatography resin portfolios that lock in downstream process loyalty across multi-year agreements.
Viral clearance encompasses validated removal or inactivation of adventitious agents from biopharmaceutical feedstreams, typically achieving log reduction values exceeding four orders of magnitude through size-exclusion filtration, solvent-detergent treatment, or low-pH incubation. Chromatography and filtration technologies command the deepest margin pools due to resin and membrane replacement cycles, while inactivation methods grow fastest as gene therapy developers adopt parvovirus-resistant processes. Application demand skews heavily toward biologics and vaccines, with blood products representing a mature, price-sensitive segment where contract manufacturing organizations concentrate procurement leverage.
Japan's PMDA enforces ICH Q5A-derived viral safety expectations that obligate sponsors to demonstrate clearance across multiple orthogonal methods. Australia's TGA and South Korea's MFDS have harmonized with PIC/S guidelines, creating a unified compliance baseline that shapes vendor qualification requirements across the region. Stakeholders must monitor how China's NMPA interprets viral clearance data packages for locally manufactured biosimilars targeting export markets.
Market Dynamics
Japan's PMDA enforcement of ICH Q5A-derived viral safety expectations is compressing validation timelines and forcing biologics manufacturers to pre-qualify multiple orthogonal clearance methods before Phase III submission. This regulatory pressure cascades through South Korea's MFDS and Australia's TGA, reshaping vendor qualification requirements across the entire region.
Growth Catalysts
- Chromatography resin replacement cycles:Biologics manufacturers in Japan's Kanto pharmaceutical corridor require quarterly resin refresh schedules to maintain viral log reduction validation, creating recurring consumables demand that anchors vendor revenue streams.
- China's NMPA biosimilar guidelines:Tightened viral safety mandates for locally manufactured biosimilars targeting export markets are pushing domestic CDMOs to adopt validated clearance platforms previously used only for innovator biologics.
- Gene therapy parvovirus resistance:Developers of recombinant protein therapies across South Korea and Australia are mandating parvovirus-resistant process designs, expanding the addressable market for specialized inactivation equipment beyond traditional plasma-derived products.
Market Restraints
- Captive consumables lock-in:Vendors bundling filtration membranes with system placements create switching costs that limit price competition and compress margin flexibility for mid-tier biologics manufacturers.
- Validation study duration:PMDA-mandated clearance demonstrations across multiple orthogonal methods extend development timelines by 8-14 months, delaying revenue recognition for contract research organizations.
- Specialized operator scarcity:The shallow talent pool for downstream process validation engineers in Australia's TGA-regulated facilities forces wage premiums that inflate per-study costs.
Strategic Opportunities
- Subscription validation contracts:WuXi AppTec's bundled clearance study model demonstrates how integrated CDMOs can capture recurring revenue by embedding validation services within multi-year manufacturing agreements.
- India's emerging biologics corridor:CDSCO's alignment with ICH viral safety standards creates entry pathways for clearance vendors to serve biosimilar developers in Hyderabad and Bangalore before domestic supply chains mature.
- Continuous processing convergence:Integration of perfusion bioreactors with inline viral filtration systems enables real-time clearance validation, reducing batch failure risk for high-value gene therapy vectors.
Industry Challenges
- Legacy facility retrofit complexity:Blood product manufacturers in mature markets face structural constraints installing low-pH inactivation suites within existing cleanroom footprints, forcing greenfield investments or contract manufacturing reliance.
- Cross-regional data package harmonization:China's NMPA interprets viral clearance documentation differently than Japan's PMDA for the same manufacturing process, requiring sponsors to maintain parallel validation studies for multi-territory filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Viral Clearance Market |
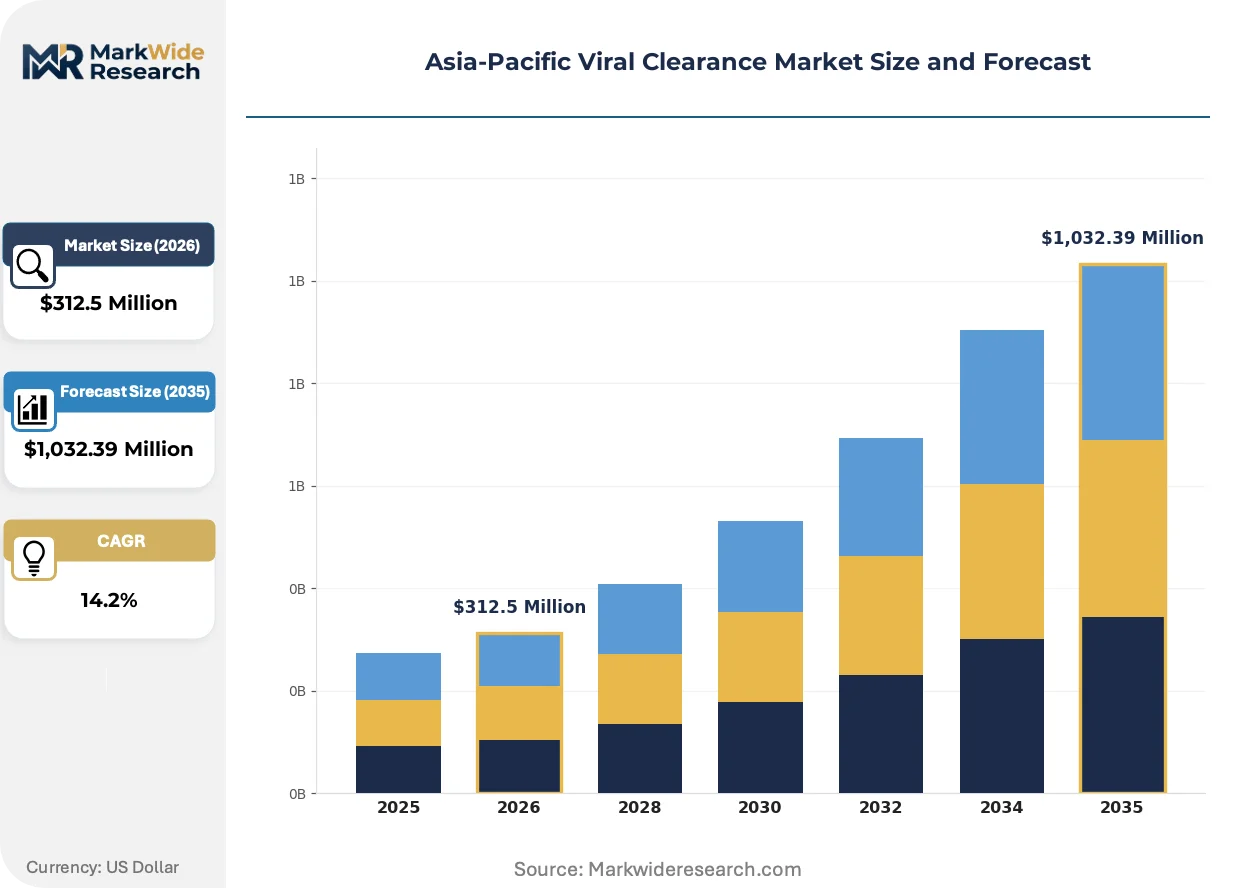
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,032.39 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Filtration, Chromatography, Inactivation, Precipitation Application: Biologics, Vaccines, Gene Therapy, Blood Products End User: Pharmaceutical Companies, Biotech Firms, Research Laboratories, Contract Manufacturing Organizations Process Stage: Upstream Processing, Downstream Processing, Quality Control, Validation |
| Companies Covered | WuXi AppTec, Syngene International, WuXi Biologics, Charles River Laboratories, Sartorius AG, Merck KGaA, Texcell, Eurofins Scientific, Lonza Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Viral Clearance Market Trends and Innovations
Single-use viral clearance systems are compressing capital deployment timelines and enabling modular facility designs that biologics manufacturers can reconfigure between product campaigns. This shift is redrawing competitive boundaries between traditional stainless-steel equipment vendors and disposable platform specialists.
Membrane adsorbers is overtaking resin-packed columns for intermediate-scale biologics manufacturing. These devices combine anion exchange functionality with flow-through processing, eliminating packing validation and cleaning verification steps. Gene therapy developers in Japan's Kanto corridor are adopting membrane adsorbers for Phase II campaigns, collapsing downstream process development timelines from months to weeks and forcing chromatography resin suppliers to defend position through performance guarantees rather than installed base alone.
PMDA's 2023 clarification on viral clearance bracketing studies is tightening documentation requirements for platform technologies previously accepted across multiple product classes. Sponsors must now demonstrate clearance robustness across wider parameter ranges, increasing validation study costs. Biologics manufacturers are responding by consolidating vendor relationships with filtration system suppliers capable of generating comprehensive bracketing data packages.
Buyer concentration among top-tier CDMOs is compressing pricing power for standalone clearance service providers. WuXi AppTec, Samsung Biologics, and Boehringer Ingelheim's Shanghai facility now internalize validation capabilities that independent contract research organizations previously captured. This procurement consolidation is visible most acutely in South Korea's Songdo biocluster, where MFDS-registered facilities prefer integrated service contracts over discrete study procurement.
Asia-Pacific Viral Clearance Market Segmentation
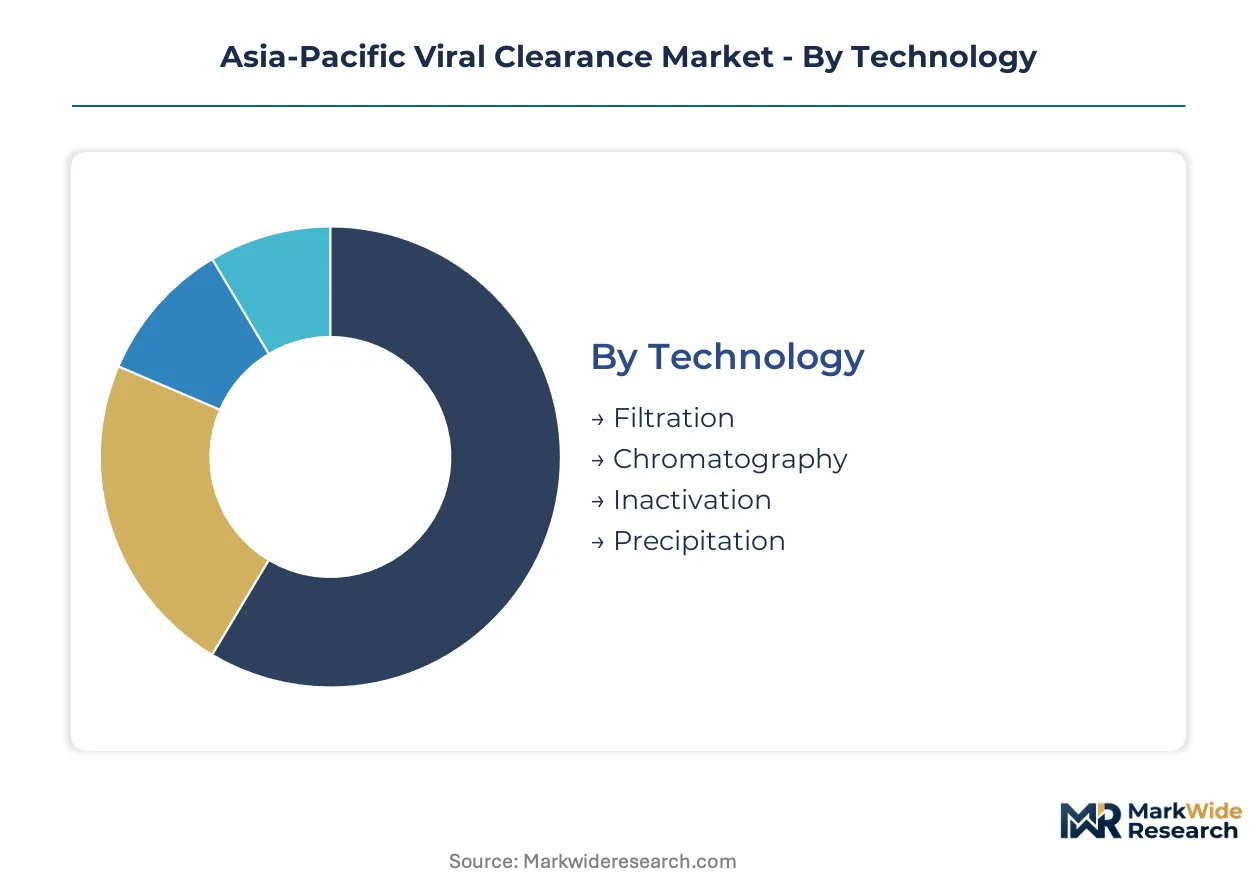
Viral clearance market segmentation reveals how technology choices, application requirements, and end-user procurement patterns create distinct competitive arenas across the Asia-Pacific region. Understanding these divisions helps vendors align R&D investments with where purchasing power and regulatory pressure concentrate.
Technology:
Technology selection in viral clearance hinges on log reduction targets, feedstream characteristics, and compatibility with the broader downstream train.
- Filtration:Size-exclusion membranes achieve parvovirus retention through nominal pore ratings below 20 nanometers. Japan's PMDA-mandated bracketing studies for nanofiltration systems drive quarterly membrane replacement cycles among Kanto corridor biologics manufacturers.
- Chromatography:Anion exchange and mixed-mode resins bind viral particles through electrostatic interactions, enabling log reduction validation orthogonal to filtration. South Korean CDMOs under MFDS oversight favor protein A affinity capture combined with viral clearance chromatography steps for monoclonal antibody processes.
- Inactivation:Low-pH incubation and solvent-detergent treatments disrupt viral envelopes without denaturing target proteins.
- Precipitation:Caprylic acid and ammonium sulfate fractionation removes enveloped viruses through differential solubility manipulation.
Chromatography leads on scale through resin replacement economics; inactivation leads on momentum as gene therapy developers demand parvovirus-resistant process designs.
Application:
Application segments diverge sharply in validation burden, pricing tolerance, and vendor relationship structures.
- Biologics:Recombinant protein therapies require multi-modal clearance demonstrations across orthogonal technologies to satisfy PMDA and TGA filing requirements. Australia's biologics manufacturers concentrate procurement with vendors offering integrated filtration-chromatography platforms.
- Vaccines:Viral and subunit vaccines present unique clearance challenges due to antigen similarity to adventitious agents. China's NMPA tightened biosimilar viral safety guidelines are pushing domestic vaccine producers toward validated clearance platforms previously reserved for innovator products.
- Gene Therapy:Adeno-associated virus and lentiviral vector manufacturing demands specialized inactivation protocols resistant to parvovirus contamination.
- Blood Products:Plasma-derived therapies represent a mature segment where contract manufacturing organizations wield concentrated procurement leverage.
Biologics commands the deepest margin pools; gene therapy is climbing the fastest as vector manufacturing scales across the region.
End User:
End-user type determines whether viral clearance capabilities are built in-house, outsourced, or procured through integrated service bundles.
- Pharmaceutical Companies:Large innovators maintain captive downstream process development groups and multi-year resin supply agreements with Merck KGaA and Sartorius AG.
- Biotech Firms:Venture-backed developers in Australia's Melbourne and Sydney clusters prefer disposable filtration systems to avoid capital deployment before Phase IIb data.
- Research Laboratories:Academic and government facilities conduct clearance studies for early-stage proof-of-concept work.
- Contract Manufacturing Organizations:CDMOs represent the most sophisticated procurement segment, with WuXi AppTec and Samsung Biologics internalizing validation capabilities that independent service providers once captured.
CDMOs lead on scale through consolidated purchasing power; biotech firms are gaining share fastest as venture funding flows into Australia's emerging biologics corridor.
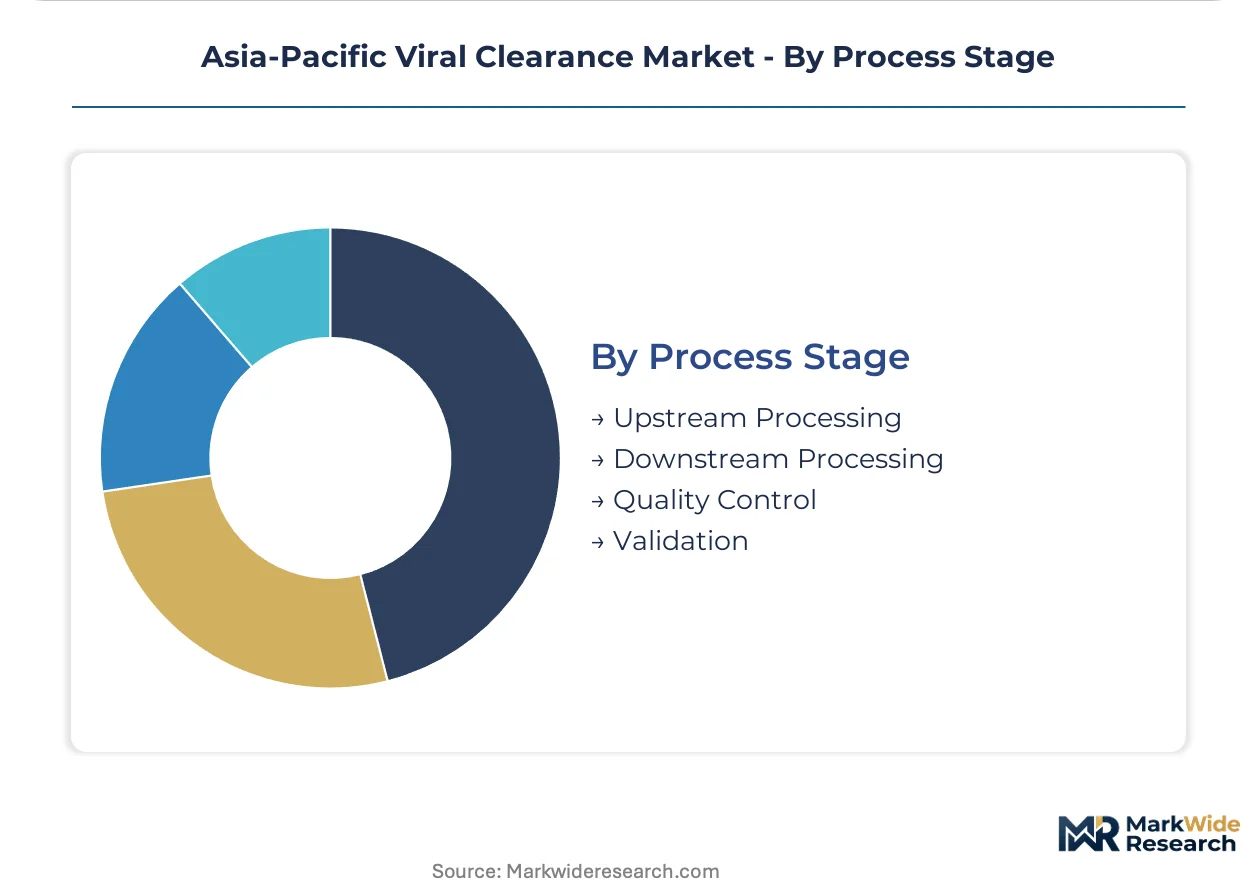
Process Stage:
Process stage segmentation tracks where viral clearance validation occurs within the manufacturing workflow.
- Upstream Processing:Cell culture media and raw material testing for adventitious agents occurs before bioreactor inoculation.
- Downstream Processing:Capture, intermediate purification, and polishing steps incorporate dedicated viral clearance unit operations. Japan's PMDA enforcement of ICH Q5A-derived expectations compresses validation timelines for downstream process transfers.
- Quality Control:Release testing and in-process monitoring verify clearance performance against validated parameters.
- Validation:Bracketing studies, robustness testing, and regulatory documentation preparation represent discrete service revenue pools.
Downstream processing leads on scale through consumables attachment; validation is expanding most quickly as PMDA documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's viral clearance validation burden exceeds China's by a factor of three in documentation requirements, yet Chinese CDMOs now match Japanese facilities in chromatography resin consumption per manufacturing campaign. This divergence shapes how vendors allocate technical support resources across the region.
Japan
Gene therapy developers in the Kanto pharmaceutical corridor drive demand for dedicated downstream validation services. PMDA's enforcement of ICH Q5A-derived expectations compresses timelines and forces pre-qualification of multiple orthogonal clearance methods before Phase III submission. Osaka-based biologics manufacturers concentrate procurement with vendors offering integrated filtration-chromatography platforms.
China
Domestic CDMOs adopt validated clearance platforms previously reserved for innovator biologics as NMPA tightens biosimilar viral safety guidelines. The Yangtze River Delta biotech cluster sees the fastest capacity expansion for viral clearance services targeting export markets. Shanghai facilities now internalize validation capabilities that independent contract research organizations once captured.
South Korea
MFDS-registered facilities in the Songdo biocluster prefer integrated service contracts over discrete study procurement. Recombinant protein therapy developers mandate parvovirus-resistant process designs, expanding demand for specialized inactivation equipment. Samsung Biologics anchors regional capacity through captive downstream process development groups.
Australia
TGA harmonization with PIC/S guidelines creates unified compliance baselines that reshape vendor qualification requirements. Melbourne and Sydney venture-backed developers favor disposable filtration systems to defer capital deployment before Phase IIb data. Specialized operator scarcity for downstream process validation engineers forces wage premiums that inflate per-study costs.
India
CDSCO alignment with ICH viral safety standards creates entry pathways for clearance vendors before domestic supply chains mature. Hyderabad and Bangalore biosimilar developers represent emerging demand as contract manufacturing procurement consolidates. The country's national pharmaceutical regulator is tightening documentation requirements for platform technologies previously accepted across multiple product classes.
Asia-Pacific Viral Clearance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated CDMOs capturing recurring validation revenue while standalone equipment vendors defend position through consumables attachment. The market structure tilts toward consolidation among top-tier service providers, though mid-tier filtration specialists retain footholds in discrete technology niches. Three archetypes dominate: integrated CDMOs bundling clearance with manufacturing campaigns, captive consumables suppliers locking in downstream process loyalty, and independent contract research organizations offering discrete study procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves, with vendors racing to pre-qualify multiple orthogonal methods ahead of regulatory submission deadlines.
Within the integrated CDMO tier, WuXi AppTec and WuXi Biologics exemplify the bundled service model that embeds validation within multi-year manufacturing agreements. Among European-headquartered specialists, Sartorius AG and Merck KGaA anchor regional positioning through consumables supply tied to system placements. Charles River Laboratories occupies a position representing the independent contract research archetype, though buyer concentration among top-tier manufacturers compresses pricing power for standalone service providers.
| Leading Market Players |
|---|
| WuXi AppTec |
| Syngene International |
| WuXi Biologics |
| Charles River Laboratories |
| Sartorius AG |
| Merck KGaA |
| Texcell |
| Eurofins Scientific |
| Lonza Group |
| Others |
Pricing and Supply Chain Analysis
Top-tier CDMO procurement consolidation across South Korea's Songdo biocluster and China's Yangtze River Delta biotech corridor enforces subscription-based validation contracts as the dominant pricing model. This buyer concentration compresses standalone service provider margins while rewarding integrated vendors with multi-year consumables attachment.
Pricing Analysis
Capacity additions in China's Yangtze River Delta biotech cluster are reshaping price floors for chromatography resin supply. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated Japanese facilities from MFDS-registered Korean sites and emerging Indian CDMOs. Cost compression in the economy tier stems from domestic Chinese resin manufacturing scaling. Blood product manufacturers in mature markets exhibit highest price sensitivity due to concentrated procurement leverage, while gene therapy developers in Japan's Kanto corridor show lowest sensitivity for parvovirus-resistant process designs.
Supply Chain Analysis
Regional distribution centers in Singapore and Shanghai anchor hub-and-spoke patterns for filtration membrane logistics across the Asia-Pacific. Manufacturing concentration rests on Germany, Japan, and the United States for chromatography resin production, with China expanding domestic capacity for anion exchange media. Raw material dependencies include specialty polymers for nanofiltration membranes, protein A ligands for affinity capture, and solvent-detergent formulations for viral inactivation. Single-source vulnerability from European resin suppliers creates structural risk for Japanese biologics manufacturers facing PMDA-mandated validation timelines. Distribution runs through captive consumables programs tied to system placements by Sartorius AG and Merck KGaA.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in viral clearance services hinges on resin replacement cycle acceleration and the shift toward bundled validation-manufacturing contracts that capture recurring revenue streams.
For Market Incumbents: Hedge against buyer consolidation by deepening consumables attachment through performance guarantees rather than installed base defense alone. Samsung Biologics and WuXi AppTec internalizing validation capabilities threatens standalone service providers with demand displacement. Anchor leverage in chromatography resin portfolios that lock in downstream process loyalty across multi-year agreements, while expanding technical support presence in Japan's Kanto corridor to compress PMDA validation timelines. For New Entrants and Emerging Players: The price-point gap between premium Japanese PMDA-validated services and economy-tier Indian CDSCO-aligned offerings creates entry pathways for membrane adsorber specialists. Australia's Melbourne and Sydney biotech clusters represent the most penetrable geography, with venture-backed developers favoring disposable filtration systems before Phase IIb data. Target gene therapy vector manufacturers with modular single-use clearance platforms that collapse downstream process development timelines from months to weeks. For Investors and Strategic Acquirers: Integrated CDMOs with captive downstream validation capabilities are the most active acquirer in this space, seeking to bundle clearance studies within multi-year manufacturing agreements. Long-term viability favors vendors with consumables-recurring revenue models over discrete project-based service providers. Monitor NMPA documentation requirement tightening for biosimilar export markets as the inflection indicator for Chinese domestic CDMO consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA bracketing study pre-qualification accelerates Phase III submission timelines for Kanto corridor sponsors. |
| Manufacturing Scale-Up | Perfusion bioreactor integration with inline viral filtration reduces batch failure risk for high-value gene therapy vectors. |
| Backward Integration | CDMO captive downstream process development groups displace independent contract research organization revenue capture. |
| Long-term Supply Agreement | Quarterly resin refresh schedules with Japanese biologics manufacturers anchor recurring consumables revenue streams. |
| Geographic Expansion | India's CDSCO alignment with ICH viral safety standards creates entry pathways before domestic supply chain maturation. |
Research Methodology
Multiple input streams — primary interviews with biologics manufacturing executives, regulatory affairs leads at PMDA-registered facilities, and CDMO procurement directors; secondary validation through FDA filings, EMA submissions, MFDS inspection reports, and chromatography resin trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations captured validation study pricing, resin replacement cycle frequency, and bracketing documentation requirements across Japan, China, South Korea, Australia, and India.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application category, end-user procurement pattern, and regional regulatory cluster. CAGRs were derived from installed base growth, consumables attachment rates, and capacity expansion timelines. Forecast inputs incorporated PMDA documentation requirement evolution and NMPA biosimilar guideline tightening for export markets.
The model assumes a particular technology adoption path; alternative pathways for continuous processing convergence with inline viral filtration would alter the outlook. Forecasts reflect assumptions regarding regulatory harmonization pace and CDMO consolidation trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Rapid Sterility Testing Market
Testing Services
Biomarker Testing Services Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Radiographic Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Point of Care Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market