
 Warfarin Sensitivity Test Market | 2026-2036
Warfarin Sensitivity Test Market Size, Share, and Industry Trends Forecast 2026-2036
Warfarin Sensitivity Test Market Analytics
Hospital-based anticoagulation clinics is collapsing toward home health care monitoring as the dominant buyer archetype for warfarin sensitivity testing. Roche Diagnostics leverages its diagnostic platform breadth to sustain laboratory test dominance across integrated health networks. Abbott competes through point-of-care test portability, while Siemens Healthineers anchors its position in high-throughput hospital settings with automated workflow integration.
Warfarin sensitivity testing encompasses pharmacogenomic assays that detect CYP2C9, VKORC1, and CYP4F2 polymorphisms to predict individual anticoagulant response, typically requiring blood samples processed through PCR amplification or microarray hybridization within 24-48 hour turnaround windows. The primary commercial purpose centers on reducing bleeding and thromboembolic events by personalizing warfarin dosing protocols. Genetic test products command premium positioning due to their predictive value in cardiology applications, while point-of-care technology segments expand fastest through decentralized clinic deployment. Polymerase chain reaction methods retain volume leadership in diagnostic laboratories, though mass spectrometry approaches gain traction in research institutions seeking multi-analyte profiling capabilities.
FDA oversight of pharmacogenomic test validation and CLIA laboratory certification requirements shape product development timelines and market access conditions in the United States. The country's national pharmaceutical regulator maintains stringent analytical performance standards that differentiate approved assays from laboratory-developed alternatives. Stakeholders must monitor evolving reimbursement coding for pharmacogenomic services and the pace of clinical guideline integration across cardiovascular specialty societies.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing vendor access points and privileging diagnostic platforms with enterprise-scale contracting capabilities. This structural concentration forces test manufacturers to secure sole-source agreements with health system purchasing coalitions rather than competing clinic-by-clinic.
Growth Catalysts
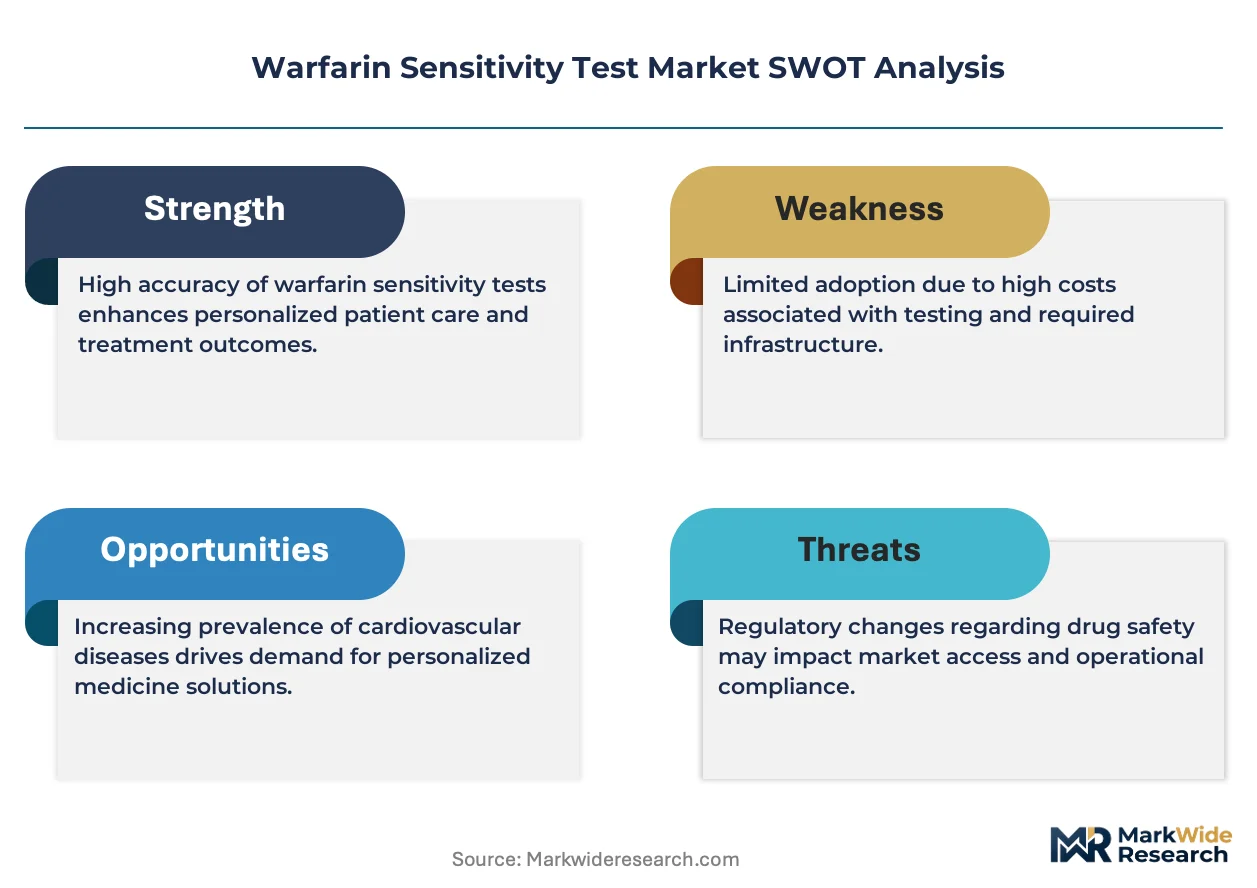
- CLIA Laboratory Certification:The United States' CLIA program mandates quality standards for clinical laboratories performing pharmacogenomic testing, creating a barrier that protects established assay providers from unvalidated competitors.
- Cardiovascular Specialty Society Guidelines:Integration of CYP2C9 and VKORC1 genotyping into anticoagulation management protocols by professional medical associations drives protocol adoption across hospital-based anticoagulation clinics.
- PCR Platform Installed Base:Existing polymerase chain reaction infrastructure in diagnostic laboratories reduces capital friction for adding warfarin sensitivity assays to routine test menus.
Market Restraints
- Reimbursement Coding Fragmentation:Inconsistent Current Procedural Terminology coverage for pharmacogenomic services across US commercial payers creates revenue uncertainty for testing laboratories.
- Sample Collection Logistics:Blood specimen stability requirements and 24-48 hour processing windows limit test accessibility in rural and remote clinical settings without courier networks.
- Direct Oral Anticoagulant Substitution:Prescription growth of apixaban and rivaroxaban as first-line alternatives to warfarin in non-valvular atrial fibrillation compresses the addressable patient population for sensitivity testing.
Strategic Opportunities
- Home Health Care Channel:Expansion of remote patient monitoring programs creates demand for point-of-care warfarin sensitivity testing outside traditional hospital laboratories.
- Pharmacist-Led Anticoagulation Services:State-level scope-of-practice expansions enabling pharmacist prescribing authority open new test-ordering channels in community pharmacy settings.
- Multi-Analyte Cardiovascular Panels:Convergence of pharmacogenomic testing with lipid metabolism and clotting factor genotyping enables comprehensive cardiovascular risk profiling from single specimens.
Industry Challenges
- Bioinformatics Specialist Shortage:Interpretation of complex CYP2C9 haplotype combinations requires trained personnel, constraining laboratory scaling in competitive hiring markets.
- Electronic Health Record Integration:Embedding pharmacogenomic results into computerized physician order entry systems demands custom interface development with diverse hospital IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warfarin Sensitivity Test Market |
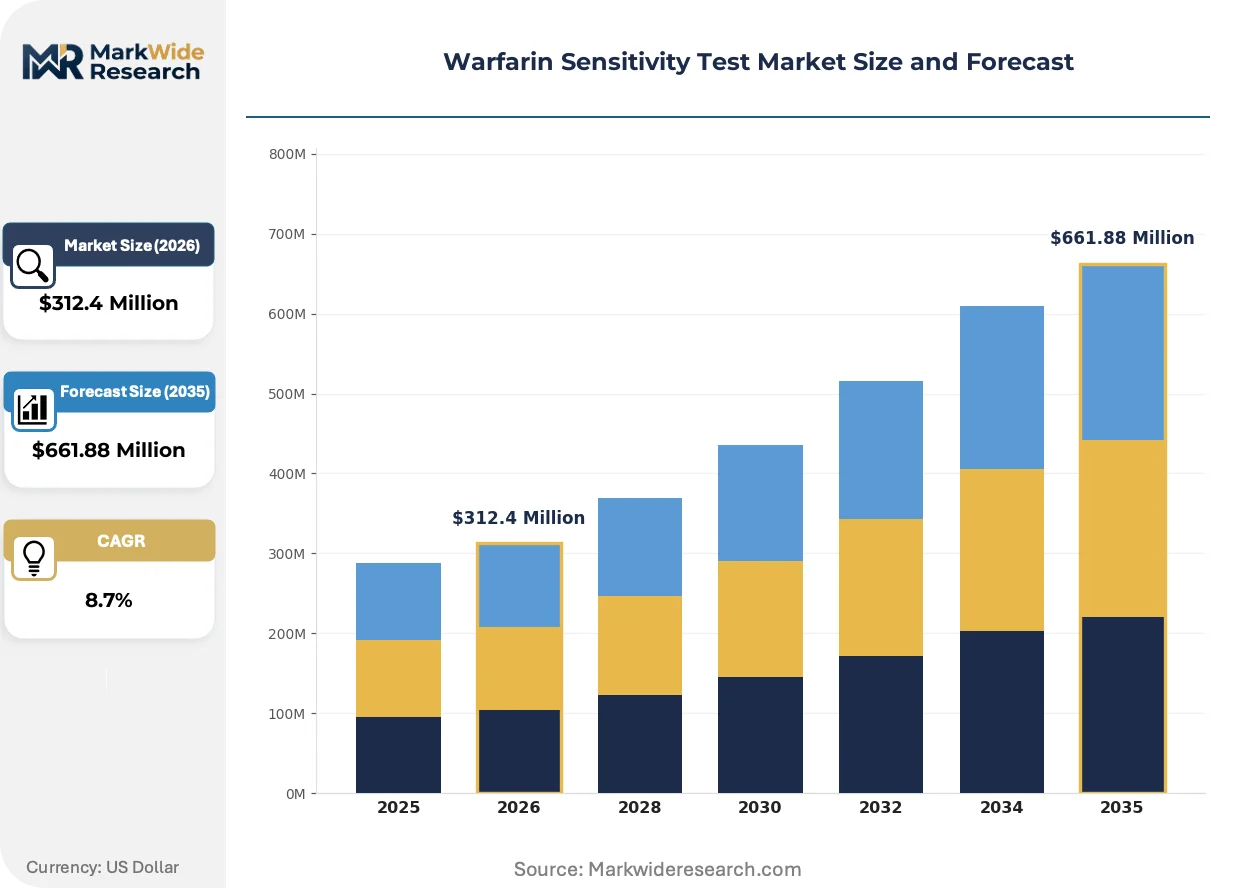
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Test, Clinician Test, Point-of-Care Test, Laboratory Test Technology: Polymerase Chain Reaction, Sequencing, Microarray, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Home Health Care, Research Institutions Application: Cardiology, Oncology, Vascular Medicine, Hematology |
| Companies Covered | Abbott, Roche Diagnostics, Eurolyser Diagnostica GmbH, CoaguSense, ACON Laboratories, TrimGen Corporation, Siemens Healthineers, Micropoint Biosciences, AutoGenomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warfarin Sensitivity Test Market Evolving Landscape
Digital pathology and artificial intelligence-assisted result interpretation are reshaping how pharmacogenomic laboratories process and report complex genotype-phenotype correlations. These capabilities compress turnaround times while reducing manual review burdens.
Mass spectrometry-based multi-analyte detection is displacing single-gene polymerase chain reaction methods in research-oriented cardiovascular centers. Academic medical centers with established proteomics cores are adopting liquid chromatography-tandem mass spectrometry platforms for simultaneous warfarin metabolite and genotype analysis. This convergence is compressing per-test costs while expanding the analytical window beyond CYP2C9 and VKORC1 to include CYP4F2 and CYP2C19 polymorphisms.
The FDA's 2023 guidance on pharmacogenomic test validation establishes analytical performance benchmarks that differentiate approved in vitro diagnostic devices from laboratory-developed tests. This regulatory clarification is accelerating health system procurement preferences for FDA-cleared assays over homebrew alternatives. Integrated delivery networks in the United States are consolidating vendor lists to favor manufacturers with complete regulatory dossiers.
Anticoagulation clinic directors are consolidating test ordering around bundled per-patient episode payments rather than fee-for-service reimbursement. This payment model compression favors diagnostic manufacturers capable of delivering integrated platforms spanning genotyping, INR monitoring, and clinical decision support software. The shift is most visible in Medicare Advantage-contracted cardiovascular centers seeking capitated cost control.
Warfarin Sensitivity Test Market Segmentation
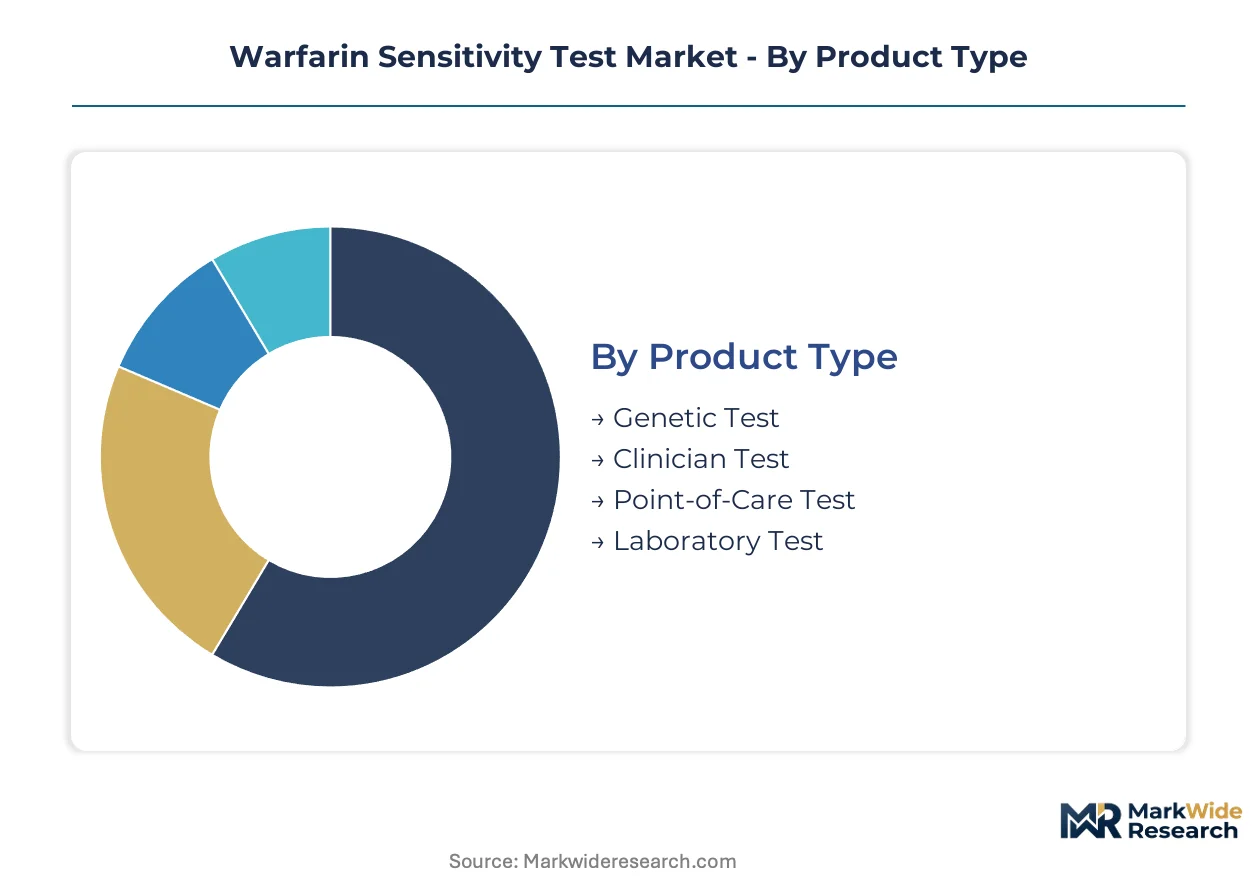
Warfarin sensitivity testing fragments across four intersecting dimensions that determine competitive positioning. Product type and technology choices dictate capital requirements and reimbursement pathways, while end-user concentration shapes distribution economics.
Product Type:
Genetic tests face the most acute substitution pressure from direct oral anticoagulants, forcing vendors to emphasize predictive value in complex polypharmacy patients.
- Genetic Test:Pharmacogenomic assays detecting CYP2C9, VKORC1, and CYP4F2 polymorphisms through PCR amplification or microarray hybridization. Demand concentrates in cardiovascular centers with established precision medicine programs, driven by FDA guidance on pharmacogenomic test validation.
- Clinician Test:Physician-interpreted assays with embedded clinical decision support for anticoagulation dosing protocols. Adoption accelerates in hospital-based anticoagulation clinics seeking to reduce bleeding event liability.
- Point-of-Care Test:Portable devices enabling rapid genotype determination outside central laboratories. Home health care monitoring programs in rural settings drive procurement where courier networks prove unreliable.
- Laboratory Test:High-throughput batch processing through automated workflow integration. Integrated delivery networks favor this segment for enterprise-scale contracting efficiency.
Laboratory tests anchor the volume base while point-of-care tests gain share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive platforms from reagent-light alternatives, with installed base inertia protecting incumbent methods.
- Polymerase Chain Reaction:Thermal cycling amplification of target gene regions with established protocol libraries. Diagnostic laboratories in the United States leverage existing PCR infrastructure to minimize capital friction for test menu expansion.
- Sequencing:Next-generation and Sanger methods for comprehensive haplotype resolution. Research institutions adopt this technology for multi-analyte cardiovascular risk profiling beyond standard warfarin pharmacogenes.
- Microarray:Solid-phase hybridization of labeled nucleic acids to immobilized probes. Mid-scale laboratories select this approach for parallel genotyping of multiple pharmacogenes from single specimens.
- Mass Spectrometry:Liquid chromatography-tandem MS for simultaneous metabolite and genotype analysis. Academic medical centers with proteomics cores drive adoption for expanded analytical windows including CYP2C19 polymorphisms.
PCR methods retain volume leadership while mass spectrometry climbs the fastest among advanced platforms.
End User:
Customer type concentration privileges vendors with multi-channel deployment capabilities as procurement consolidates around bundled episode payments.
- Hospitals:Inpatient and outpatient anticoagulation clinics with integrated pharmacy services. Medicare Advantage-contracted cardiovascular centers seek capitated cost control through bundled genotyping and INR monitoring.
- Diagnostic Laboratories:Independent and hospital-affiliated CLIA-certified facilities processing referral specimens. The United States' CLIA program quality standards protect established assay providers from unvalidated competitors.
- Home Health Care:Remote patient monitoring programs and decentralized clinic deployment. State-level pharmacist prescribing authority expansions open new test-ordering channels in community pharmacy settings.
- Research Institutions:Academic medical centers conducting genotype-phenotype correlation studies. Bioinformatics specialist shortages constrain laboratory scaling in competitive hiring markets.
Hospitals anchor the volume base while home health care gains share at the steepest rate.
Application:
Maturity differentiation separates cardiology's established guidelines from oncology's emerging off-label protocols.
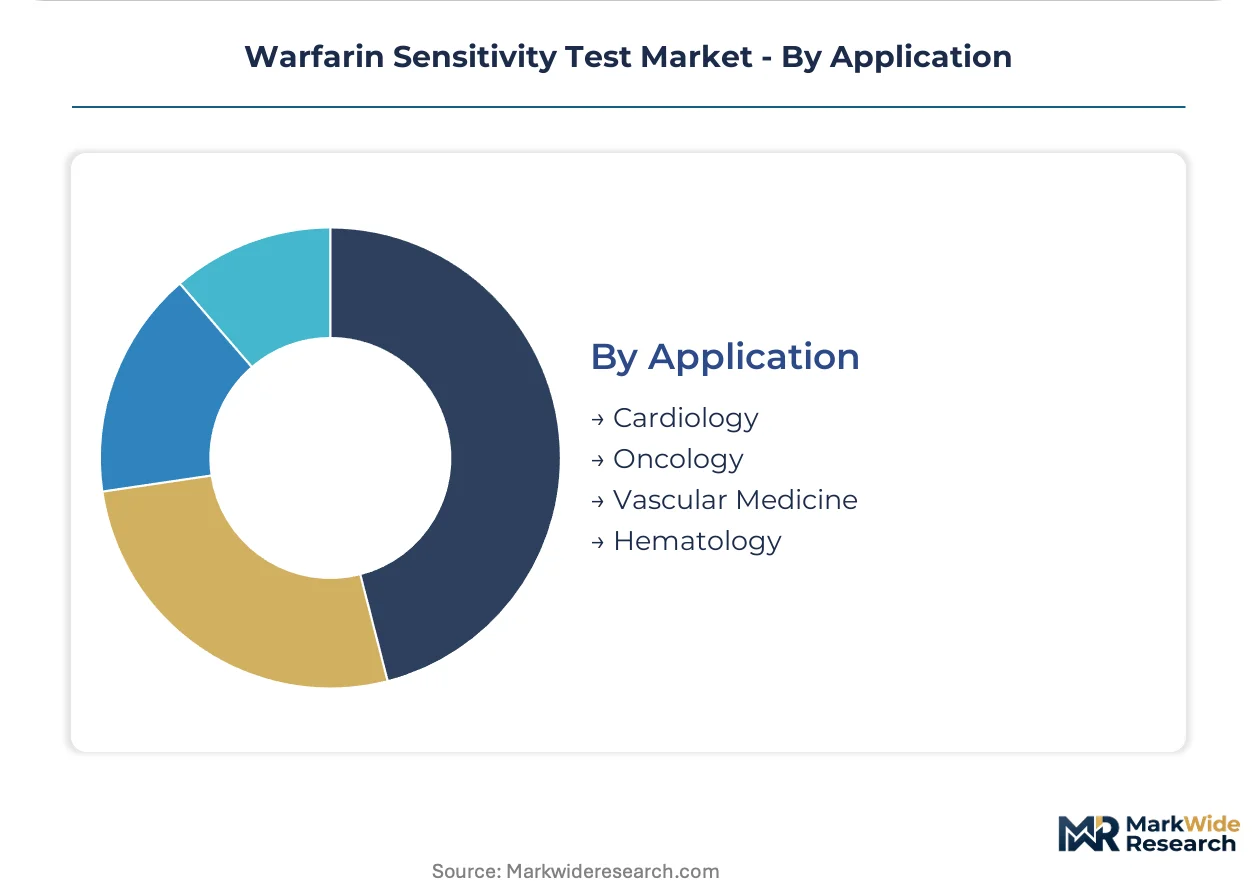
- Cardiology:Atrial fibrillation and mechanical valve anticoagulation management with guideline-supported genotyping. Cardiovascular specialty society protocols drive adoption across hospital-based anticoagulation clinics.
- Oncology:Thromboprophylaxis in cancer patients with chemotherapy-induced coagulopathy. Academic medical centers explore pharmacogenomic-guided dosing where drug-drug interactions complicate direct oral anticoagulant selection.
- Vascular Medicine:Peripheral artery disease and venous thromboembolism management. Diagnostic laboratories process specimens for specialist practices without in-house genotyping capacity.
- Hematology:Inherited thrombophilia and complex coagulation disorder evaluation. Research institutions investigate multi-gene panels combining warfarin sensitivity with clotting factor genotyping.
Cardiology anchors the volume base while oncology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 pharmaceutical corridor linking Boston to Philadelphia underwrites the United States' concentration of precision medicine infrastructure for pharmacogenomic testing. This logistics spine enables 24-48 hour specimen processing windows that anchor hospital-based anticoagulation clinic operations.
United States
FDA guidance on CYP2C9 and VKORC1 genotyping validation shapes procurement preferences across Medicare Advantage-contracted cardiovascular centers. The CLIA laboratory certification program protects established assay providers from unvalidated competitors. The Boston-Cambridge biotech cluster drives protocol adoption through academic medical center influence on clinical guidelines.
Germany
EMA harmonization of pharmacogenomic test standards accelerates hospital laboratory integration of warfarin sensitivity assays. The country's statutory health insurance system maintains structured reimbursement pathways for genetic diagnostics. The Rhine-Ruhr metropolitan region concentrates diagnostic laboratory capacity serving Western European referral networks.
Japan
PMDA regulatory frameworks for in vitro diagnostics shape product registration timelines for multinational assay manufacturers. METI industrial policy supports domestic biotechnology infrastructure development. The Kansai region's Osaka-Kobe medical device cluster anchors point-of-care technology distribution across East Asian markets.
United Kingdom
NHS England's specialized commissioning frameworks determine access to pharmacogenomic testing in anticoagulation services. MHRA post-Brexit regulatory autonomy influences divergence from EU diagnostic device standards. The Cambridge-London life sciences corridor concentrates research institutions investigating multi-analyte cardiovascular panels.
Canada
Health Canada oversight of pharmacogenomic device licensing aligns with FDA validation benchmarks for cross-border test manufacturers. Provincial health authority procurement consolidates around enterprise-scale diagnostic platform contracts. The Toronto-Waterloo biomedical corridor anchors CLIA-equivalent laboratory certification capacity serving North American referral specimens.
Warfarin Sensitivity Test Market Competitive Landscape
Concentration sits with diversified diagnostic conglomerates and point-of-care specialists competing across distinct channel archetypes. The vendor base organizes around three strategic positions: laboratory platform providers with automated workflow integration, portable device manufacturers serving decentralized care settings, and molecular diagnostics specialists with pharmacogenomic assay portfolios. Competitive moves center on sole-source contracting with integrated delivery networks and FDA clearance dossier completion for health system procurement qualification.
Within the diversified diagnostic tier, Roche Diagnostics and Siemens Healthineers exemplify platform breadth strategies, while Abbott represents point-of-care portability positioning. Among specialized pharmacogenomic assay developers, AutoGenomics and TrimGen Corporation occupy positions in molecular diagnostics segments. These five entities collectively span the technology spectrum from high-throughput laboratory automation to rapid-turnaround clinic-based testing.
| Leading Market Players |
|---|
| Abbott |
| Roche Diagnostics |
| Eurolyser Diagnostica GmbH |
| CoaguSense |
| ACON Laboratories |
| TrimGen Corporation |
| Siemens Healthineers |
| Micropoint Biosciences |
| AutoGenomics |
| Others |
Value Network & Pricing Analysis
CLIA laboratory certification in the United States gates both supplier qualification and price differentiation simultaneously, as FDA-cleared assays command premium positioning over laboratory-developed alternatives while uncertified competitors face exclusion from integrated delivery network procurement lists. This regulatory threshold compresses margins for mid-tier reagent suppliers unable to absorb validation costs, while entrenched platform manufacturers leverage sole-source contracting to sustain pricing power across hospital-based anticoagulation clinics.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with integrated delivery networks extracting per-test reductions for multi-year sole-source commitments spanning genotyping, INR monitoring, and clinical decision support software. Price differentiation rests on FDA clearance tier and automation integration depth, as high-throughput hospital laboratories pay premiums for automated workflow compatibility while rural clinics prioritize portable device affordability. Cost compression in point-of-care segments is intensifying because Abbott and CoaguSense compete for home health care channel share with stripped-down reagent kits. Diagnostic laboratories within Medicare Advantage-contracted cardiovascular centers exhibit lowest price sensitivity due to bundled episode payment insulation, whereas independent reference labs face acute margin pressure from commercial payer reimbursement coding fragmentation.
Supply Chain Analysis
Thermocycler manufacturing concentration in Germany, Japan, and the United States creates equipment procurement chokepoints for diagnostic laboratories expanding PCR-based warfarin sensitivity test menus. Reagent supply draws from synthetic oligonucleotide producers in South Korea and Singapore, with Taq polymerase enzymes sourced from recombinant protein facilities in Switzerland and the United States. Single-source vulnerability in fluorescence-labeled probe supply exposes assay manufacturers to semiconductor fabrication bottlenecks affecting optical detection components. Distribution runs through cold-chain logistics networks anchored by the I-95 pharmaceutical corridor, where 24-48 hour specimen stability requirements privilege regional laboratory clusters over decentralized processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in pharmacist-led anticoagulation services, as state-level scope-of-practice expansions create ordering-channel niches outside hospital-based clinic consolidation. Direct oral anticoagulant substitution pressure splits demand between complex polypharmacy patients requiring precision dosing and straightforward cases abandoning warfarin entirely.
For Market Incumbents: Consolidate around FDA-cleared assay portfolios to defend against laboratory-developed test erosion, while securing sole-source agreements with Medicare Advantage-contracted cardiovascular centers seeking bundled genotyping and monitoring platforms. Backward integration into thermocycler manufacturing reduces equipment procurement vulnerability from German and Japanese suppliers. Channel control through clinical decision support software embedding deepens switching costs for hospital anticoagulation clinics. For New Entrants and Emerging Players: Bioinformatics interpretation services represent a service-layer gap where incumbents under-serve mid-scale laboratories lacking CYP2C9 haplotype analysis expertise. Home health care monitoring programs in rural settings without courier networks offer the most penetrable geography, as point-of-care device portability trumps high-throughput automation for decentralized deployment. Pharmacist prescribing authority expansions in community pharmacy settings provide a direct go-to-market angle bypassing hospital procurement consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostic conglomerates seeking to divest non-core pharmacogenomic assay portfolios amid direct oral anticoagulant demand compression. Long-term viability hinges on multi-analyte cardiovascular panel convergence, where warfarin sensitivity testing integrates with lipid metabolism and clotting factor genotyping for comprehensive risk profiling. Watch FDA guidance evolution on pharmacogenomic test validation as the inflection signal determining health system procurement preferences between cleared devices and laboratory-developed alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coding alignment for pharmacogenomic services secures commercial payer coverage across cardiovascular centers. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks compress competitor access points through enterprise-scale contracting. |
| Software Companion Development | Clinical decision support embedding within Epic and Cerner EHR architectures reduces manual interpretation burdens. |
| CE Marking Pathway | EMA harmonization accelerates Western European laboratory integration of warfarin sensitivity assays. |
| Platform Integration | Mass spectrometry convergence with metabolite analysis expands analytical windows beyond standard pharmacogenes. |
Research Methodology
A spread of perspectives from anticoagulation clinic directors, CLIA laboratory certification officers, hospital procurement managers, and cardiovascular specialty society guideline committee members converged on the working assumptions driving test adoption forecasts. Primary interviews with diagnostic platform engineers and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and cardiovascular society clinical guideline documents. Bottom-up test volume estimates from hospital-affiliated and independent laboratories triangulated against top-down spending projections from integrated delivery network annual reports.
Segmentation dimensions modeled span product type, technology platform, end-user channel, and application area across the projection horizon. Analytical framework approach incorporates PCR platform installed base dynamics, CLIA laboratory certification pipeline velocity, and direct oral anticoagulant prescription substitution rates as industry-specific forecast inputs. CAGRs derive from weighted scenario analysis of reimbursement coding expansion, cardiovascular guideline integration pace, and point-of-care technology adoption curves.
Forecasts assume regulatory continuity in FDA pharmacogenomic test validation and CLIA laboratory certification regimes; material policy shifts would require re-modeling of health system procurement preferences and assay provider competitive positioning. Practitioners should keep alternative scenarios live as direct oral anticoagulant substitution rates and pharmacist scope-of-practice expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Radiographic Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Urine Testing Cups Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Global Legionella Testing Market
Testing Services
Drug Tester Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Rapid Coagulation Testing Market