
 North America Endotoxin and Pyrogen Testing Market | 2026-2036
North America Endotoxin and Pyrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Endotoxin and Pyrogen Testing Market Analytics
Buyer concentration among large pharmaceutical and biotechnology sponsors is hardening as mergers reduce the number of in-house testing programs. Charles River Laboratories leverages its integrated discovery-to-manufacturing footprint to capture multi-year service contracts. Lonza Group anchors its position through specialized biosafety testing capacity near key client sites. Associates of Cape Cod differentiates with deep expertise in Limulus Amebocyte Lysate reagent production.
Endotoxin and pyrogen testing encompasses analytical methods that detect lipopolysaccharide contaminants from Gram-negative bacteria and fever-inducing substances in pharmaceuticals, medical devices, and biological products. The Limulus Amebocyte Lysate assay remains the primary pharmacopeial method, detecting endotoxin at thresholds as low as 0.03 endotoxin units per milliliter. Reagents and kits command the largest product segment share due to recurring consumable demand across high-throughput screening operations. The recombinant Factor C testing method represents the fastest-expanding approach as manufacturers seek animal-origin-free alternatives aligned with sustainability mandates. Pharmaceutical applications absorb the majority of testing volume, driven by sterile injectable and vaccine release requirements.
FDA enforces endotoxin limits through the Bacterial Endotoxins Test in United States Pharmacopeia Chapter 85, while Health Canada applies parallel standards through the Canadian Pharmacopeia. The United States Pharmacopeia's pending adoption of recombinant Factor C as a compendial method is reshaping supplier qualification protocols. Stakeholders must monitor regulatory divergence between FDA and Health Canada on alternative test validation timelines.
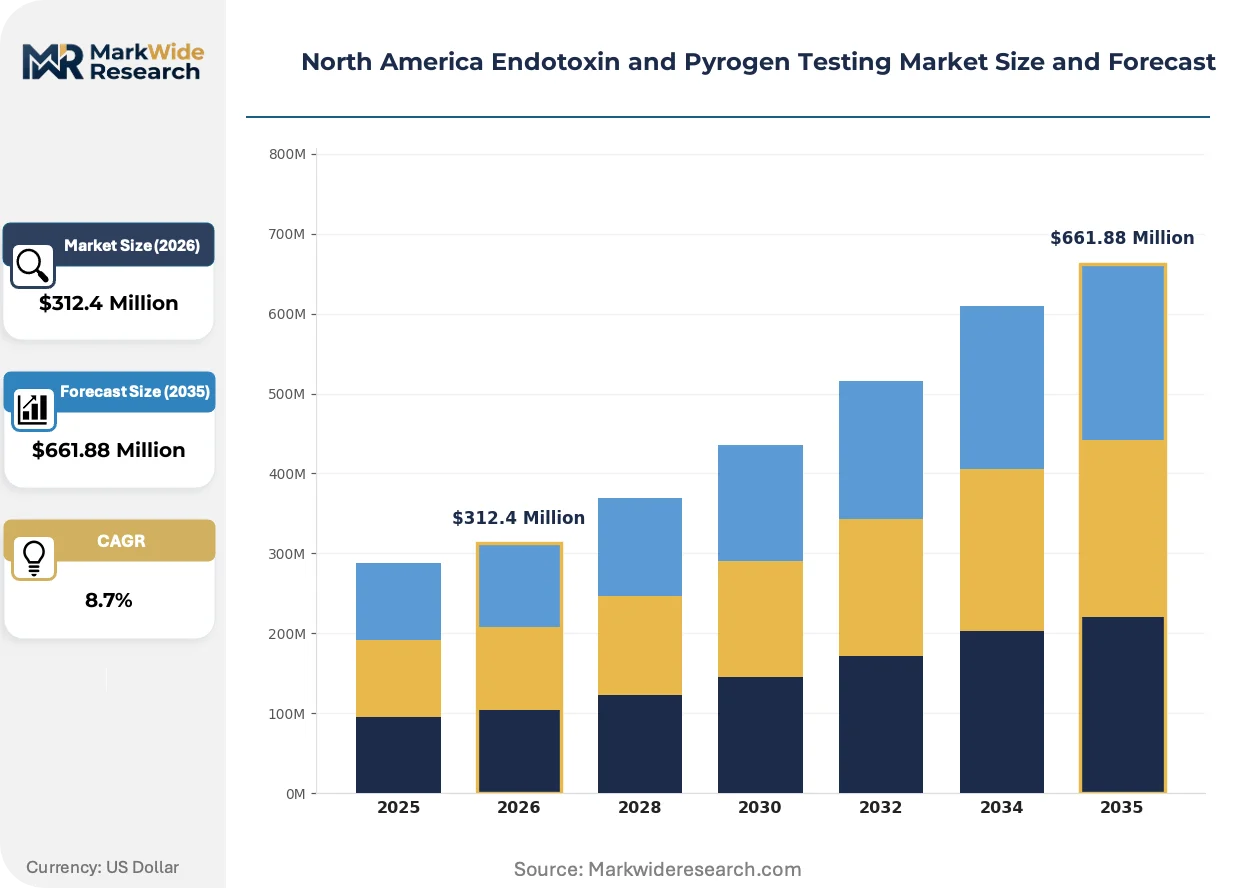
Market Dynamics
The transition from horseshoe crab-derived Limulus Amebocyte Lysate to recombinant Factor C assays is compressing supplier qualification timelines while opening capacity bottlenecks for high-volume sterile injectable manufacturers. This technology migration is redistributing testing workflows from centralized quality control labs toward integrated manufacturing suites.
Growth Catalysts
- FDA Bacterial Endotoxins Test enforcement:The United States Pharmacopeia Chapter 85 mandate for parenteral product release is expanding screening volumes across vaccine and biologic fill-finish operations.
- Biologics manufacturing expansion:Massachusetts and New Jersey drug development hubs are driving demand for high-throughput endotoxin screening capacity near contract manufacturing sites.
- Recombinant Factor C validation:The pending compendial status for animal-origin-free testing methods is accelerating qualification programs among sustainability-focused sponsors.
Market Restraints
- Reagent supply concentration:Atlantic horseshoe crab harvesting limitations constrain raw material availability for traditional LAL production, creating batch-to-batch variability risks.
- Validation cost barriers:Alternative method equivalence studies required under FDA guidance impose six-figure qualification expenses that exclude smaller contract testing laboratories.
- Health Canada timeline divergence:Slower adoption of recombinant Factor C standards relative to FDA protocols forces dual-validation strategies for cross-border product submissions.
Strategic Opportunities
- Point-of-use testing integration:In-line endotoxin detection systems for continuous manufacturing lines offer workflow compression opportunities in Puerto Rico's pharmaceutical manufacturing zone.
- United States Pharmacopeia method expansion:The pending recombinant Factor C chapter creates first-mover advantages for assay kit suppliers with validated platform offerings.
- Cell and gene therapy applications:Autologous therapy release testing represents an underpenetrated segment with specialized pyrogen detection requirements distinct from traditional biologics.
Industry Challenges
- Specialized technician scarcity:LAL chromogenic and turbidimetric assay expertise resides in a limited workforce pool concentrated in legacy pharmaceutical corridors.
- Legacy system integration:Electronic batch record systems require custom middleware development to accommodate recombinant Factor C data formats, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Endotoxin and Pyrogen Testing Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Services Testing Method: LAL Test, rFC Test, Pyrogen Test, GC/MS Application: Pharmaceuticals, Biotechnology, Medical Devices, Laboratory Research End User: Hospitals, Research Labs, Diagnostic Centers, Pharmaceutical Companies |
| Companies Covered | Charles River Laboratories, Thermo Fisher Scientific, Lonza Group, Merck KGaA, Eurofins Scientific, Associates of Cape Cod, SGS SA, bioMérieux SA, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Endotoxin and Pyrogen Testing Market Evolving Landscape
Automation architectures and sustainable reagent platforms are converging to reshape endotoxin detection economics. The market is witnessing a structural pivot from batch-oriented quality control toward real-time release paradigms.
Microfluidic cartridge-based endotoxin detection is decentralizing testing workflows from centralized quality control laboratories to manufacturing floor stations. Biologics sponsors in Massachusetts and New Jersey are deploying these platforms for at-line release decisions. The technology is decentralizing equipment procurement patterns, compressing capital deployment from six-figure central lab systems toward distributed, lower-unit-cost instrumentation.
The United States Pharmacopeia's pending recombinant Factor C adoption is mandating equivalency demonstration protocols for alternative endotoxin detection methods. This compendial expansion is forcing reagent manufacturers to maintain dual production lines during transition periods. Contract testing organizations serving FDA-regulated sponsors are accelerating validation timelines to secure preferred supplier status ahead of method chapter finalization.
Consolidated pharmaceutical sponsors are unbundling after-sales service contracts from equipment procurement, instead negotiating multi-site service level agreements with independent calibration providers. This behavior is displacing manufacturer-captive service revenue streams with third-party maintenance networks. The pattern is most visible among large biotechnology sponsors in the Northeast corridor seeking operational expenditure flexibility.
North America Endotoxin and Pyrogen Testing Market Segmentation
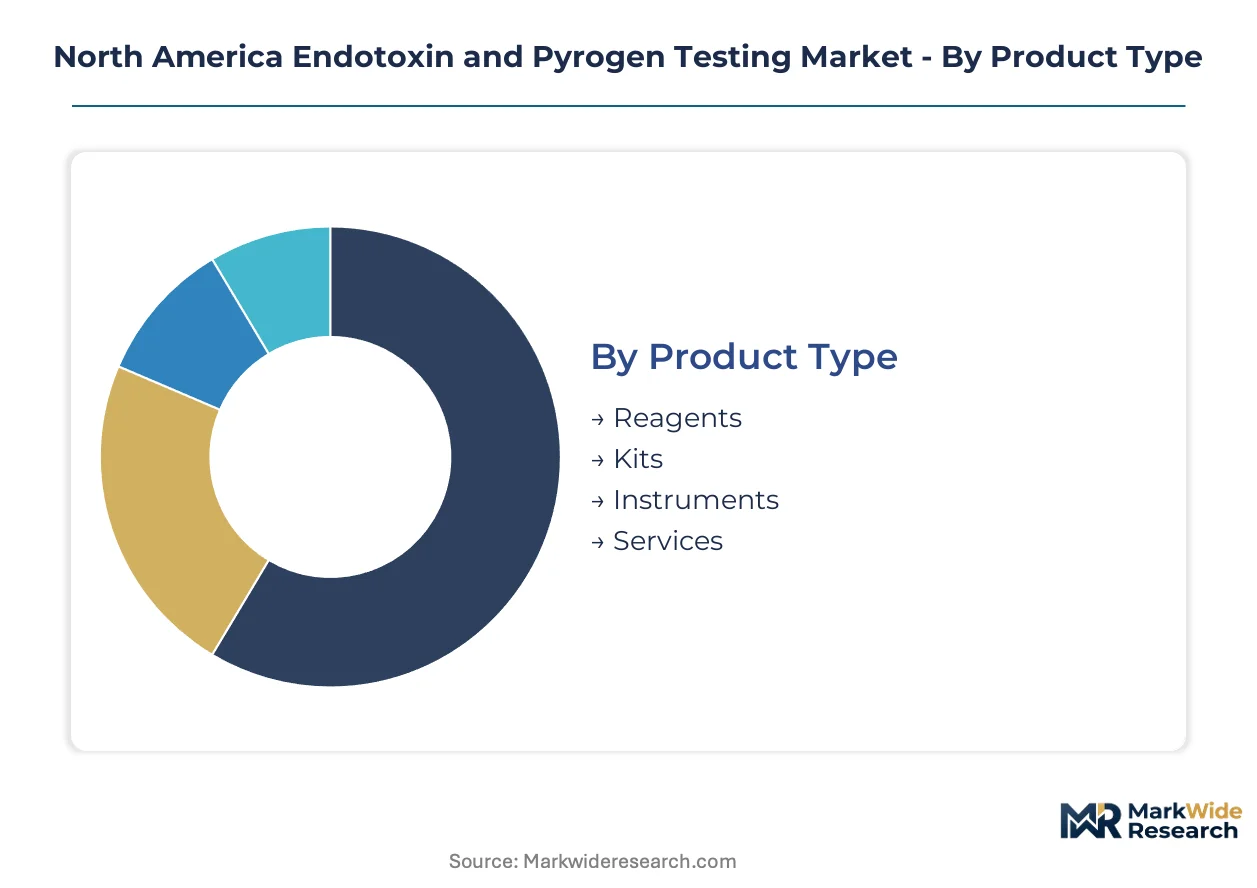
Endotoxin and pyrogen testing demand fragments across product formats, analytical methods, and end-use settings. Each segment carries distinct regulatory certification burdens and procurement cycles that reshape supplier economics. Understanding these fault lines reveals where margin concentration and growth velocity diverge.
Product Type:
FDA 21 CFR Part 820 quality system regulations impose device-level validation requirements on instruments, while reagents face USP chapter-specific lot release protocols. The certification burden intensifies with product complexity, compressing supplier qualification timelines for integrated systems.
- Reagents:Limulus Amebocyte Lysate and recombinant Factor C formulations constitute the recurring consumable base. Massachusetts biologics manufacturers absorb the highest regional volumes as fill-finish operations expand near Boston's contract manufacturing cluster. FDA's pending rFC compendial adoption is forcing dual-source qualification strategies.
- Kits:Pre-configured assay platforms bundle reagents, standards, and consumables for validated workflows. New Jersey pharmaceutical sponsors favor these for technology transfer standardization across multiple contract testing sites. Kit format demand concentrates where sponsor quality groups seek to minimize inter-lab variability.
- Instruments:Chromogenic and turbidimetric detection systems with automated sample handling.
- Services:Contract testing and validation support outsourced by sponsors lacking in-house LAL expertise.
Leading the category by volume: Reagents. Growing fastest: Services.
Testing Method:
Method selection hinges on USP chapter alignment and Health Canada pharmacopeial convergence timelines. Sponsors serving both markets face dual-validation overhead when regulatory adoption diverges.
- LAL Test:The horseshoe crab-derived assay remains the pharmacopeial standard with established FDA enforcement precedent. Atlantic coast harvesting constraints are elevating batch-to-batch variability risks for traditional lysate supply. Method dominance persists where legacy validation investments create switching costs.
- rFC Test:Recombinant Factor C assays eliminate animal origin while matching LAL sensitivity thresholds. Massachusetts sustainability-mandated sponsors are accelerating qualification ahead of USP chapter finalization. The method is gaining share fastest where European parent companies impose animal-welfare procurement policies.
- Pyrogen Test:Rabbit-based fever response assays for products incompatible with LAL/rFC detection.
- GC/MS:Gas chromatography-mass spectrometry for non-endotoxin pyrogen identification in complex matrices.
Volume leadership: LAL Test. Steepest expansion trajectory: rFC Test.
Application:
Application segments separate by release-test criticality and contamination consequence severity. Parenteral product categories face the most stringent endotoxin limit enforcement.
- Pharmaceuticals:Sterile injectable and vaccine release testing absorbs the dominant share of analytical capacity. New Jersey's parenteral manufacturing corridor generates concentrated demand for high-throughput screening near fill-finish operations. FDA Bacterial Endotoxins Test enforcement is expanding screening volumes across biologic drug substance programs.
- Biotechnology:Cell culture harvest and protein purification stage testing for monoclonal antibodies and recombinant proteins. Massachusetts gene therapy developers are driving specialized pyrogen detection requirements distinct from traditional biologics. The segment demands method flexibility for complex matrix interference challenges.
- Medical Devices:Implantable and contact-fluid device sterilization validation testing.
- Laboratory Research:Preclinical and discovery-stage screening with less stringent documentation requirements.
Dominant by volume: Pharmaceuticals. Climbing the fastest: Biotechnology.
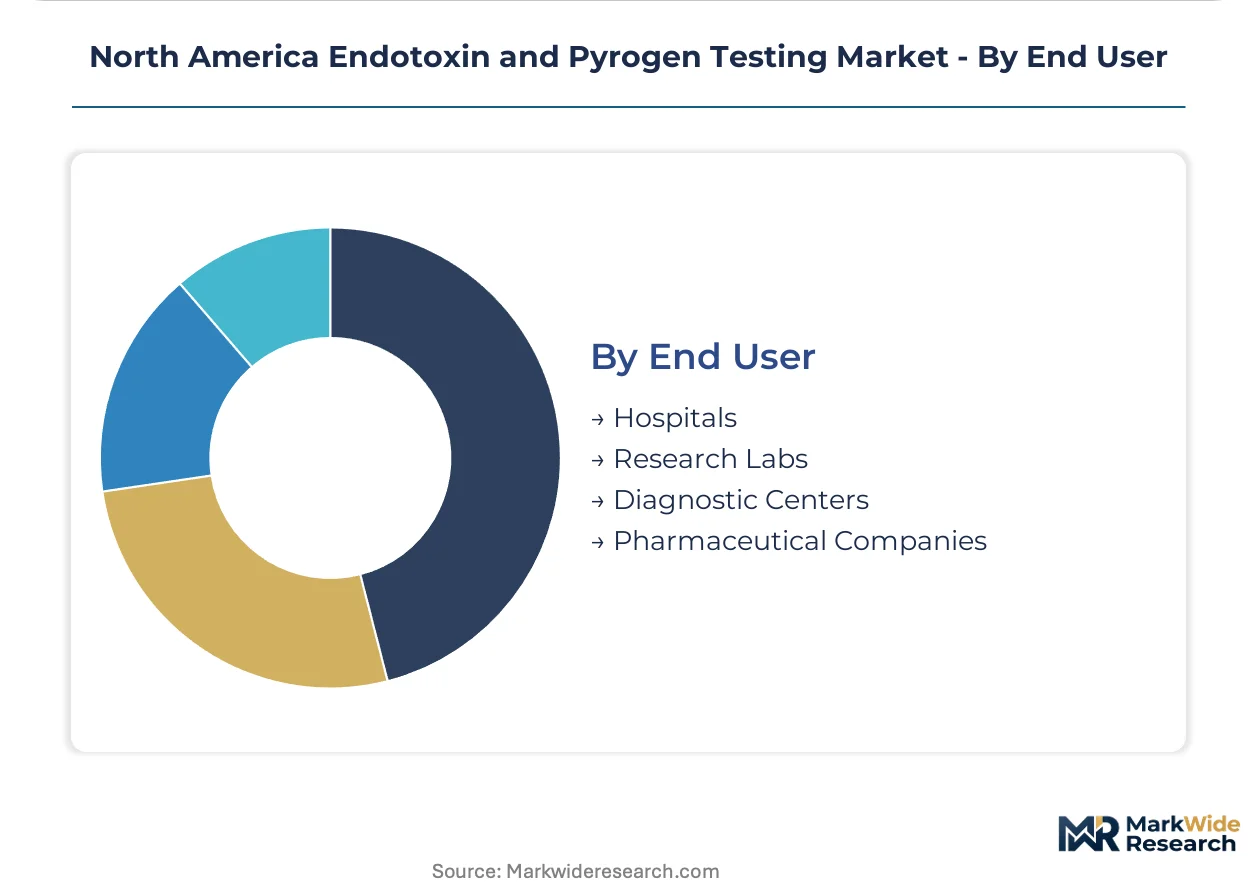
End User:
End user categories fragment by in-house testing capability depth and outsourcing propensity. Large sponsors retain centralized quality control while mid-tier organizations unbundle to contract laboratories.
- Pharmaceutical Companies:Integrated quality control operations with dedicated LAL laboratories and trained technician pools. Northeast corridor sponsors are consolidating testing programs as merger activity reduces redundant capacity. The category drives instrument procurement for at-line release integration.
- Research Labs:Academic and government facilities with intermittent testing volumes and limited validation infrastructure. Boston's university research cluster generates steady kit demand for preclinical screening. Budget constraints favor lower-unit-cost consumable formats over capital equipment.
- Hospitals:Compounding pharmacy and investigational drug testing for patient-specific preparations.
- Diagnostic Centers:Clinical laboratory testing for blood product and infusion safety screening.
Volume concentration: Pharmaceutical Companies. Fastest expansion: Research Labs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endotoxin and pyrogen testing concentrates in the United States pharmaceutical corridor, with secondary nodes emerging in Canadian biologics manufacturing and Mexican medical device export zones. FDA enforcement of United States Pharmacopeia Chapter 85 standards drives screening volume expansion, while Health Canada maintains parallel pharmacopeial requirements with divergent alternative method adoption timelines.
United States
Massachusetts and New Jersey biologics manufacturers absorb the dominant share of regional testing capacity as sterile injectable production expands. FDA's pending recombinant Factor C compendial adoption is accelerating qualification programs among sustainability-mandated sponsors. The Greater Boston contract manufacturing cluster is deploying microfluidic cartridge-based detection for at-line release decisions.
Canada
Ontario's vaccine manufacturing facilities and Quebec's pharmaceutical production sites generate concentrated demand for high-throughput screening. Health Canada's slower recombinant Factor C adoption timeline relative to FDA protocols forces dual-validation strategies for cross-border product submissions. Toronto's contract testing laboratories are expanding capacity to serve US-Canada integrated supply chains.
Mexico
Medical device sterilization validation testing dominates demand as export-oriented manufacturers supply US parenteral product markets. COFEPRIS alignment with FDA quality system regulations elevates endotoxin screening requirements for implantable device production. The Tijuana-Mexicali manufacturing corridor is consolidating testing programs as multinational sponsors integrate Mexican facilities into North American supply networks.
North America Endotoxin and Pyrogen Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue recombinant reagent specialization and point-of-use automation. The market exhibits tiered concentration with integrated life sciences conglomerates controlling instrument platforms and specialized reagent manufacturers defending consumable positions. Three archetypes dominate: discovery-to-manufacturing service integrators, biosafety testing specialists, and Limulus Amebocyte Lysate reagent purists. Competitive dynamics center on multi-year service contract capture and alternative method validation acceleration ahead of compendial adoption.
Among North American-based service providers, Charles River Laboratories exemplifies the integrated discovery-to-manufacturing archetype through its footprint across Massachusetts contract research sites. Lonza Group anchors the biosafety testing specialist tier with proximity-based capacity near New Jersey pharmaceutical sponsors. Associates of Cape Cod occupies the reagent purity position, representing deep specialization in Limulus Amebocyte Lysate production heritage.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Thermo Fisher Scientific |
| Lonza Group |
| Merck KGaA |
| Eurofins Scientific |
| Associates of Cape Cod |
| SGS SA |
| bioMérieux SA |
| Sartorius AG |
| Others |
Value Network & Pricing Analysis
Large pharmaceutical sponsors concentrated in Massachusetts and New Jersey pharmaceutical corridors negotiate multi-year service level agreements that compress reagent pricing into volume-tiered contract structures. This buyer concentration shifts pricing power toward consolidated sponsors while forcing smaller contract testing laboratories into spot-market procurement for Limulus Amebocyte Lysate and recombinant Factor C reagents.
Pricing Analysis
High-volume kit procurement by integrated biologics manufacturers captures standard-tier pricing, while specialized pyrogen testing services for cell and gene therapy applications command premium rates. Price differentiation rests on USP chapter certification status and after-sales validation support bundling. Cost compression in traditional LAL reagents is intensifying because Atlantic horseshoe crab harvesting constraints elevate batch-to-batch variability risks. Small contract testing laboratories exhibit highest price sensitivity; large pharmaceutical sponsors with captive quality control operations demonstrate lowest sensitivity due to switching cost amortization across multi-site networks.
Supply Chain Analysis
Specialized technician scarcity in Massachusetts and New Jersey pharmaceutical corridors constrains quality control laboratory expansion timelines. Geographic supply concentration centers on United States reagent manufacturing, Canadian biosafety testing capacity, and Mexican medical device sterilization validation services. Raw material dependencies include Atlantic horseshoe crab hemolymph for traditional LAL production, recombinant protein expression systems for Factor C assays, and chromogenic substrate chemicals for detection chemistry. Single-source vulnerability characterizes recombinant Factor C reagent supply during USP chapter transition periods. Distribution runs through direct manufacturer-sponsor contracts for high-volume reagents and third-party laboratory service networks for outsourced testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
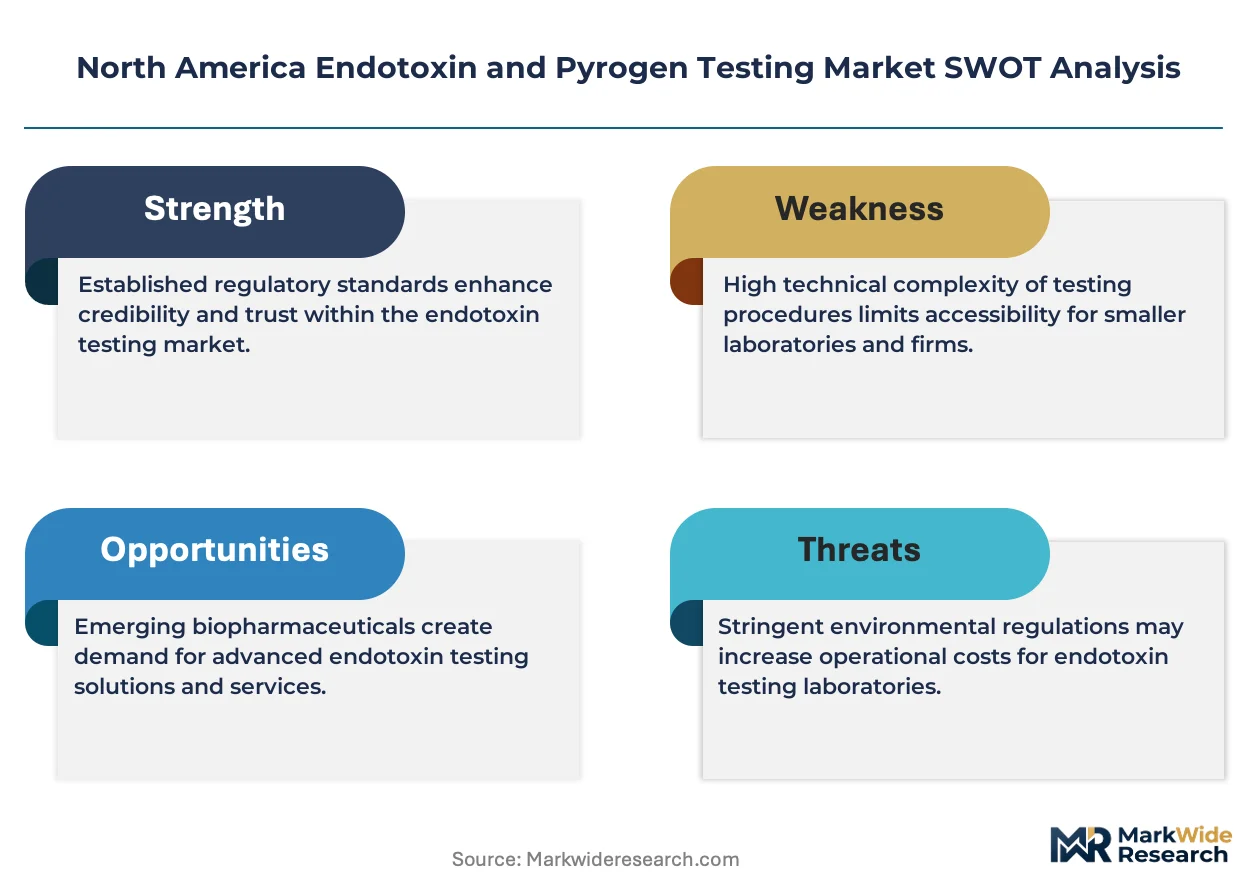
This market is consolidating around multi-year service contract capture as FDA recombinant Factor C compendial adoption raises validation cost barriers that exclude smaller contract testing laboratories.
For Market Incumbents: To counter emerging recombinant reagent specialists, incumbents should accelerate dual-source qualification programs for recombinant Factor C ahead of USP chapter finalization and secure backward integration into Limulus Amebocyte Lysate harvesting operations through Atlantic coast supplier partnerships. For New Entrants and Emerging Players: Enter via point-of-use microfluidic detection systems for Puerto Rico pharmaceutical manufacturing zones, where continuous manufacturing line integration remains underpenetrated. Target autologous cell and gene therapy release testing in Massachusetts, where specialized pyrogen detection requirements diverge from traditional biologics workflows. Pursue go-to-market partnerships with independent calibration providers unbundling from manufacturer-captive service networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor recombinant reagent manufacturers with validated platform offerings in United States pharmaceutical corridors, where sustainability-mandated sponsor procurement policies accelerate animal-origin-free method transitions. Long-term viability hinges on USP chapter adoption completion and Health Canada convergence timelines. Monitor recombinant Factor C equivalency study completion rates as inflection indicator for supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Factor C Platform Validation | Accelerates qualification ahead of USP chapter finalization for preferred supplier status. |
| Microfluidic Cartridge Manufacturing Scale-Up | Enables at-line release decisions in Puerto Rico pharmaceutical manufacturing zones. |
| Dual-Source LAL Reagent Qualification | Mitigates Atlantic horseshoe crab harvesting variability risks for high-volume sponsors. |
| Cell and Gene Therapy Testing Capacity Expansion | Captures specialized pyrogen detection demand from Massachusetts autologous therapy developers. |
| Independent Calibration Service Network Buildout | Displaces manufacturer-captive revenue streams among unbundling large biotechnology sponsors. |
Research Methodology
Multi-period observation of FDA enforcement patterns, USP chapter revision timelines, and Health Canada pharmacopeial adoption trajectories anchored the trend analysis, supplemented by interviews with quality control directors at biologics manufacturers, regulatory affairs specialists, contract testing laboratory operations managers, and reagent procurement leads. Secondary validation drew from FDA guidance documents, USP chapter drafts, Health Canada pharmacopeial bulletins, and SEC filings of publicly traded life sciences service providers. Bottom-up testing volume estimates triangulated against top-down market value reconstructions.
Input-output matrices mapped reagent consumption rates to pharmaceutical manufacturing expansion data, biologics pipeline advancement, and sterile injectable production capacity across the projection horizon. Segmentation dimensions included product format, testing method, application category, and end-user type. CAGRs were derived from regression analysis of historical testing volume expansion against regulatory enforcement intensity and manufacturing capacity buildout. Industry-specific forecast inputs incorporated recombinant Factor C equivalency study completion rates and horseshoe crab harvesting permit allocations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between FDA and Health Canada or accelerated Atlantic horseshoe crab population decline. Forecasts reflect assumptions regarding USP chapter finalization timing and sponsor qualification program acceleration. Material deviation in recombinant Factor C compendial adoption schedules or cross-border regulatory harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Global Endocrine Testing Market
Testing Services
Creatinine Testing Market
Testing Services
Calprotectin Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Dengue Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Solid Tumor Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
United States Esoteric Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Instrument Calibration Services Market
Testing Services
Cholesterol Test Market