
 US Respiratory Assist Devices EUA Market | 2026-2036
US Respiratory Assist Devices EUA Market Size, Share, and Industry Trends Forecast 2026-2036
US Respiratory Assist Devices EUA Market Intelligence
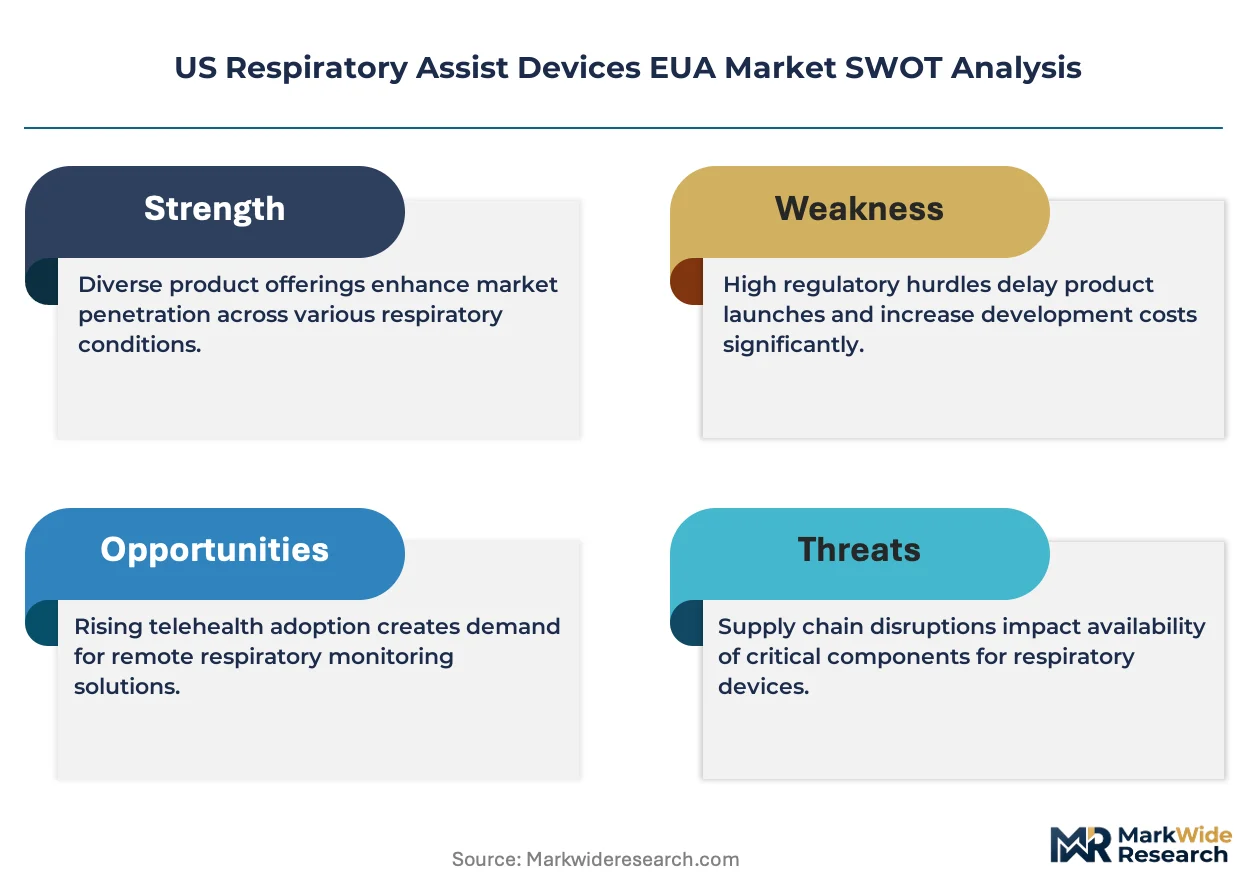
FDA 510(k) clearance and EUA qualification cycles are rotating the competitive landscape, favoring manufacturers with established quality management systems and prior FDA engagement. ResMed leverages its cloud-connected platform architecture to sustain recurring revenue streams across homecare channels. Medtronic anchors hospital-centric distribution through its critical care portfolio and direct sales infrastructure. Philips competes on manufacturing scale, though its recent device recalls have opened channel space for Fisher & Paykel Healthcare, which specializes in humidification-integrated interfaces.
US Respiratory Assist Devices EUA refers to mechanical and pneumatic systems engineered to augment or substitute spontaneous breathing, typically operating at pressure ranges of 4–30 cm H₂O and flow rates exceeding 60 L/min for high-flow modalities, deployed primarily in acute, sub-acute, and domiciliary care to manage ventilatory insufficiency or upper airway obstruction. Continuous Positive Airway Pressure dominates sleep apnea management with mature margin pools, while High-Flow Nasal Cannula represents the fastest-growing product category as clinicians expand its use beyond intensive care into emergency departments and step-down units. Non-Invasive delivery mode captures the majority of volume, though Invasive applications retain premium pricing in perioperative and neurocritical settings.
FDA maintains primary jurisdiction through EUA authority under Section 564 of the FD&C Act, while CMS reimbursement codes shape commercial viability and access decisions for home-based therapies. OSHA respiratory protection standards and state-level licensure requirements for durable medical equipment suppliers create layered compliance obligations that filter market participation. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications and CMS competitive bidding reforms that could restructure payment for home respiratory equipment.
Market Dynamics
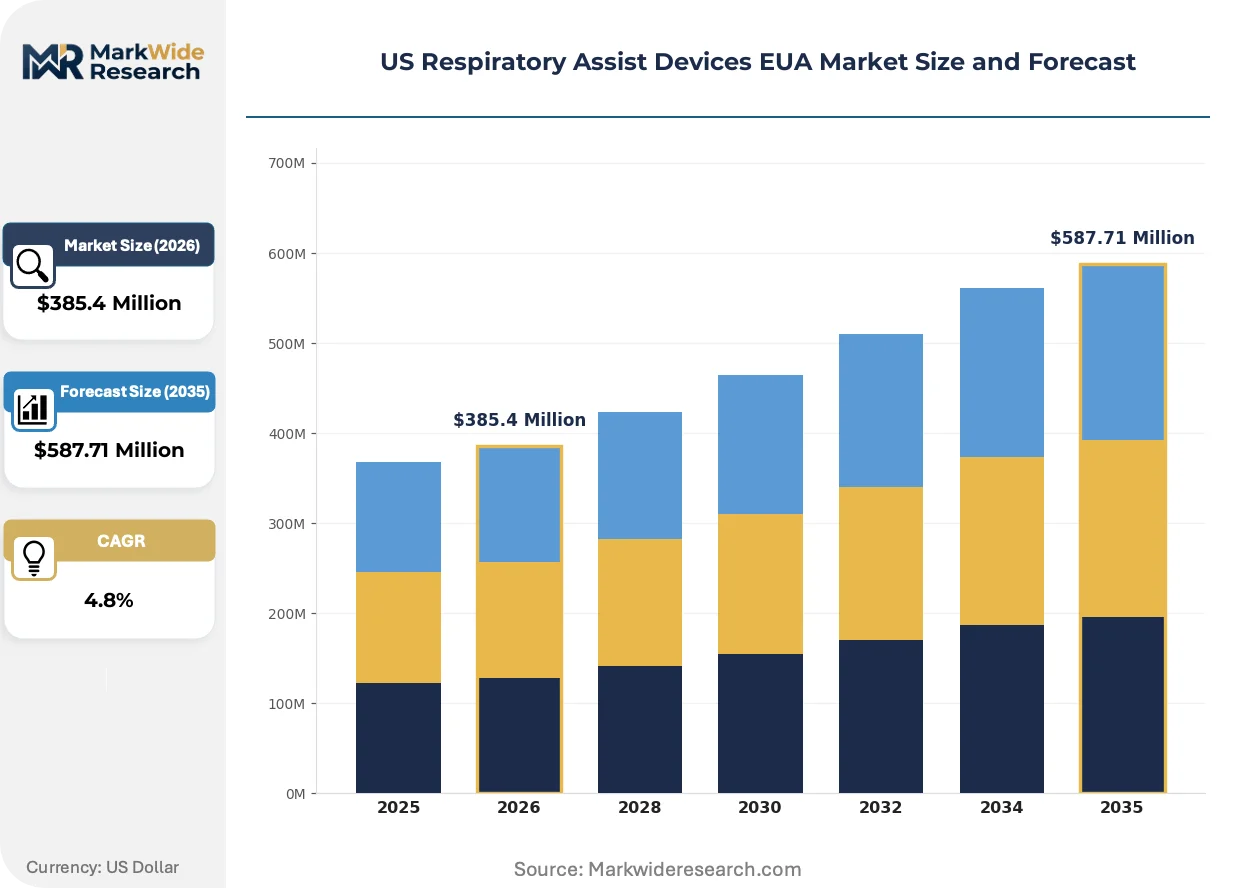
FDA EUA pathway compression and CMS reimbursement recalibration are restructuring competitive entry barriers, privileging manufacturers with pre-established quality management infrastructure and direct payer relationships over emerging hardware innovators.
Growth Catalysts
- Post-Acute Care Migration:Hospital-at-home programs and skilled nursing facility discharge protocols are expanding reimbursable domiciliary respiratory support, creating device demand outside traditional acute settings.
- EUA Regulatory Velocity:FDA's emergency authorization framework under Section 564 of the FD&C Act accelerates market access for novel platforms addressing ventilatory insufficiency during public health emergencies.
- High-Flow Nasal Cannula Protocol Expansion:Emergency departments and step-down units are adopting HFNC systems for hypoxemic respiratory failure, extending use beyond intensive care boundaries.
Market Restraints
- Silicone and Polymer Input Volatility:Medical-grade elastomer pricing fluctuations compress margin pools for interface manufacturers dependent on specialized biocompatible materials.
- Southeast Distribution Concentration:Aging demographic clusters in Florida, Georgia, and North Carolina create geographic demand spikes that strain regional durable medical equipment supplier capacity.
- 510(k) Predicate Device Limitations:FDA's substantial equivalence requirements for non-EUA pathways constrain innovation in software-integrated respiratory platforms lacking clear regulatory predicates.
Strategic Opportunities
- Remote Patient Monitoring Integration:Cloud-connected pressure and flow sensors enable predictive intervention models that reduce hospital readmission exposure for COPD and heart failure cohorts.
- Texas and Arizona Homecare Penetration:Sun Belt migration patterns and Medicare Advantage expansion in these states create underpenetrated addressable markets for domiciliary ventilatory support.
- IRA Medicare Negotiation Exclusions:Durable medical equipment categories outside pharmaceutical price controls retain pricing autonomy that supports service bundling and outcomes-based contracting.
Industry Challenges
- Respiratory Therapist Credentialing Bottlenecks:State licensure requirements and specialized training pipelines constrain field deployment capacity for complex non-invasive ventilation setup and monitoring.
- Legacy Electronic Health Record Integration:Proprietary data formats from incumbent device manufacturers create interoperability friction with hospital information systems and remote monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Respiratory Assist Devices EUA Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Positive Airway Pressure, Bi-Level Positive Airway Pressure, High-Flow Nasal Cannula, Portable Ventilators End User: Hospitals, Homecare Settings, Emergency Medical Services, Rehabilitation Centers Delivery Mode: Invasive, Non-Invasive, Mixed Mode, Oxygen-Assisted Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Respiratory Distress Syndrome, Postoperative Care |
| Companies Covered | Koninklijke Philips N.V., Medtronic, ResMed, Fisher & Paykel Healthcare Limited, GE HealthCare, Drägerwerk AG & Co. KGaA, Masimo, Teleflex Incorporated, Getinge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Respiratory Assist Devices EUA Market Strategic Shifts & Innovations
Software-defined respiratory platforms and algorithm-driven pressure modulation are compressing the traditional hardware-upgrade cycle, while regulatory clarity on artificial intelligence classifications remains unresolved.
Adaptive servo-ventilation algorithms with real-time breath-by-breath pressure adjustment are displacing fixed-pressure CPAP systems in central sleep apnea and complex respiratory failure presentations. Sleep medicine practices and pulmonary specialty clinics are prioritizing these platforms for high-comorbidity patients. The shift is displacing legacy device inventory and shortening replacement cycles across homecare supplier networks.
FDA's evolving guidance on software-as-a-medical-device classifications under 21 CFR 820 quality system regulations is creating compliance complexity for cloud-connected respiratory platforms. Manufacturers must demonstrate cybersecurity controls and algorithm validation protocols that exceed traditional hardware submissions. Homecare settings face the steepest adaptation curve as software update cycles compress hardware certification timelines.
Hospital procurement committees are unbundling device acquisition from service contracts, separating capital expenditure decisions from ongoing clinical support obligations. Integrated delivery networks and group purchasing organizations are driving this disaggregation, pressuring manufacturers to demonstrate standalone device value. The pattern is most visible in the Southeast, where health system consolidation has concentrated purchasing leverage among regional mega-systems.
US Respiratory Assist Devices EUA Market Segmentation
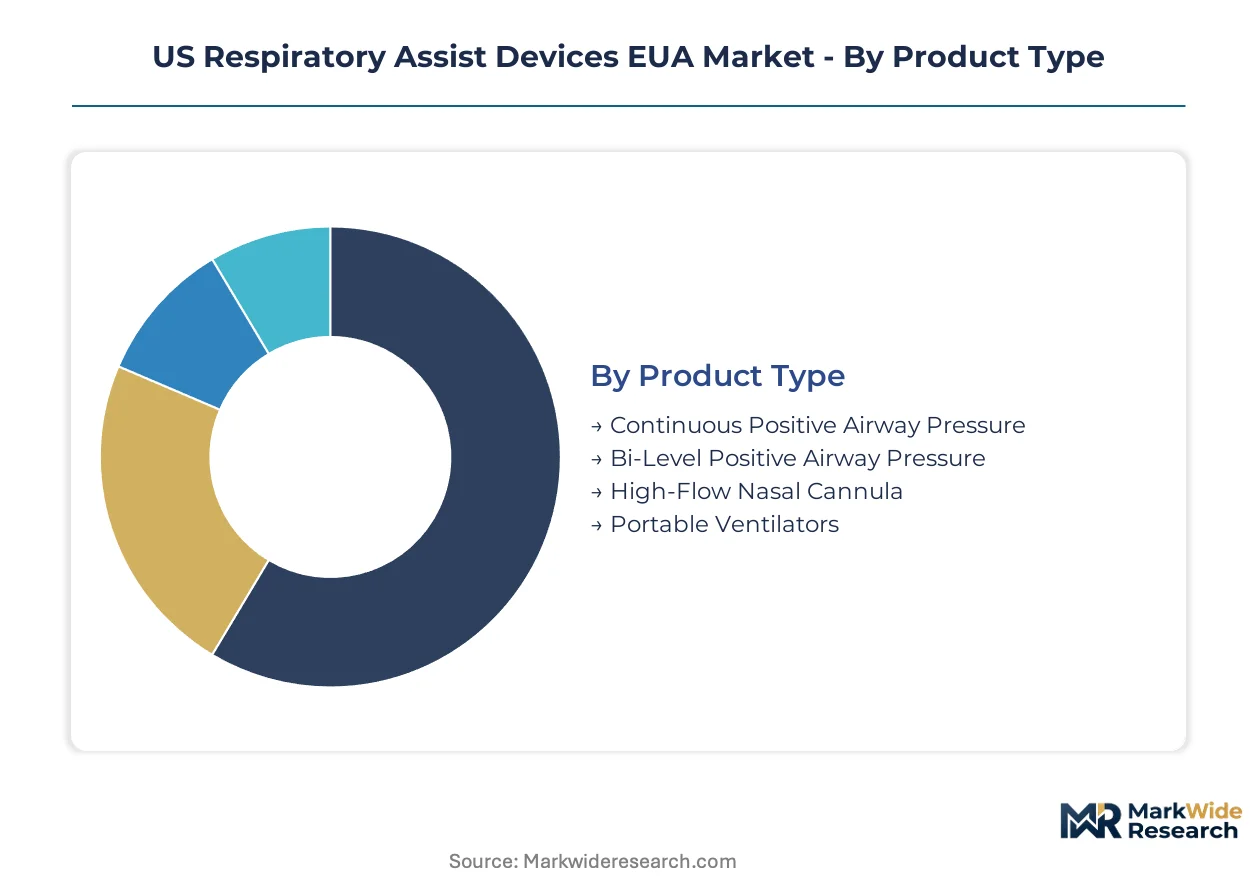
Device classification under FDA EUA pathways creates divergent compliance burdens across product architectures, while reimbursement coding under CMS durable medical equipment schedules shapes channel economics. Segmentation reveals where regulatory velocity intersects with clinical utility to determine commercial viability.
Product Type:
FDA predicates and software validation requirements split this category between mature 510(k) pathways and compressed EUA timelines.
- Continuous Positive Airway Pressure:Fixed-pressure pneumatic systems operating at 4–20 cm H₂O dominate sleep apnea management with established predicate devices and streamlined FDA clearance. CMS E0601 reimbursement codes support homecare deployment across Medicare Advantage networks in Florida and Georgia, though silicone cushion supply constraints periodically interrupt manufacturer fulfillment.
- High-Flow Nasal Cannula:Heated humidified oxygen delivery at 60+ L/min is climbing the fastest as emergency departments in Texas and Arizona adopt the modality for hypoxemic respiratory failure outside traditional intensive care boundaries. FDA EUA authorization during respiratory public health emergencies accelerated hospital procurement cycles for these systems.
- Bi-Level Positive Airway Pressure:Dual-pressure systems with separate inspiratory and expiratory settings serve complex respiratory failure and central sleep apnea presentations requiring algorithm-driven pressure modulation.
- Portable Ventilators:Battery-powered turbine-based systems enable inter-facility transport and emergency medical service deployment with invasive and non-invasive capability.
Established volume favors Continuous Positive Airway Pressure; emerging adoption favors High-Flow Nasal Cannula.
End User:
Care setting determines reimbursement pathway, clinical support requirements, and device complexity specifications.
- Hospitals:Acute care facilities deploy the full spectrum of invasive and non-invasive modalities with 24-hour respiratory therapy coverage and centralized biomedical engineering support. Southeastern health system consolidation in North Carolina and Georgia has concentrated purchasing leverage among integrated delivery networks negotiating enterprise-wide device contracts.
- Homecare Settings:Domiciliary deployment of CPAP and BiPAP systems is expanding most quickly as hospital-at-home programs and skilled nursing discharge protocols shift reimbursable respiratory support outside institutional boundaries. Medicare competitive bidding reforms and Medicare Advantage expansion in Texas and Arizona are reshaping supplier economics.
- Emergency Medical Services:Pre-hospital transport ventilators and portable suction equipment serve critical care transport with durability and battery-life specifications distinct from stationary platforms.
- Rehabilitation Centers:Sub-acute facilities bridge acute hospitalization and home discharge with weaning protocols for ventilator-dependent patients requiring progressive respiratory muscle training.
Institutional procurement anchors revenue concentration; domiciliary channels are gaining share fastest.
Delivery Mode:
Interface invasiveness determines pricing tier, clinical training requirements, and infection control protocols.
- Non-Invasive:Mask-based interfaces capture majority volume across CPAP, BiPAP, and HFNC modalities with lower complication profiles and reduced nursing intensity. Homecare adoption concentrates in Southeast Medicare Advantage markets where aging demographics and COPD prevalence coincide.
- Invasive:Endotracheal and tracheostomy interfaces command premium pricing in perioperative anesthesia, neurocritical care, and prolonged mechanical ventilation with specialized respiratory therapist credentialing requirements.
- Mixed Mode:Dual-capability devices transition patients between non-invasive and invasive support without equipment exchange, reducing inventory burden in step-down units.
- Oxygen-Assisted:Low-flow and high-flow oxygen integration with pressure support addresses hypoxemic respiratory failure with blended delivery protocols.
Non-Invasive systems dominate unit economics; Invasive applications sustain margin premiums.
Application:
Disease-specific reimbursement coding and clinical guideline adoption shape device selection within each indication.
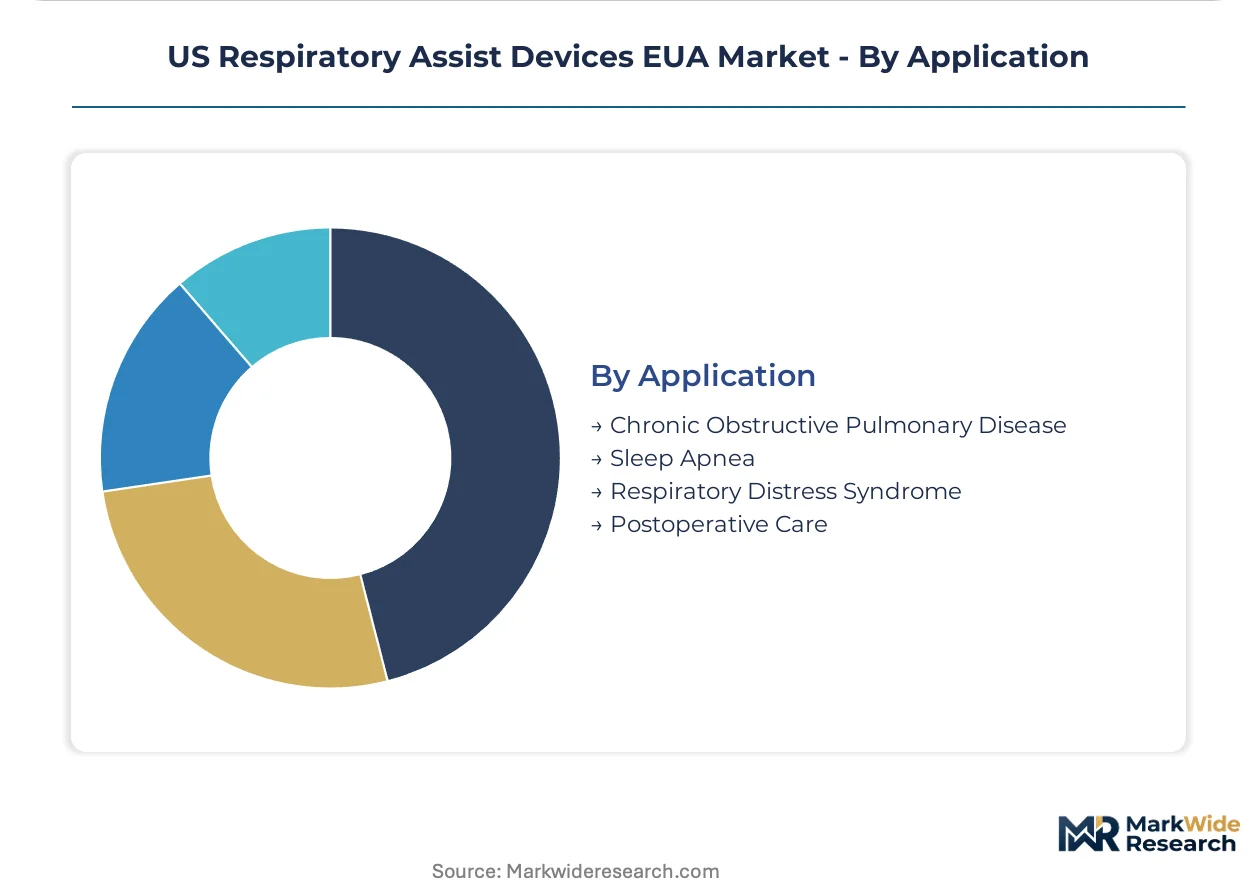
- Sleep Apnea:Obstructive and central sleep disordered breathing drives CPAP and adaptive servo-ventilation demand with mature Medicare coverage determination and home sleep testing expansion. Diagnostic growth in Sun Belt retirement migration corridors sustains device replacement cycles.
- Chronic Obstructive Pulmonary Disease:Hypercapnic respiratory failure and nocturnal hypoventilation indications support non-invasive ventilation reimbursement with remote patient monitoring integration reducing hospital readmission exposure.
- Respiratory Distress Syndrome:Acute hypoxemic failure in emergency and critical care settings drives HFNC and invasive mechanical ventilation with EUA pathway utilization during surge capacity events.
- Postoperative Care:Perioperative respiratory support and extubation failure prevention employs non-invasive ventilation in surgical step-down units with anesthesia-directed protocols.
Sleep Apnea commands established installed base; COPD remote monitoring integration shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and homecare suppliers concentrate device demand across distinct geographic clusters, with Medicare reimbursement policies and state-level durable medical equipment licensure shaping regional access patterns.
Southeast
Florida, Georgia, and North Carolina drive procurement volume through aging demographic concentrations and COPD prevalence corridors. Medicare Advantage expansion across these states accelerates homecare channel penetration for CPAP and BiPAP systems. Atlanta anchors regional distribution infrastructure for durable medical equipment suppliers serving hospital-at-home discharge protocols.
Southwest
Texas and Arizona present underpenetrated addressable markets as Sun Belt migration patterns concentrate respiratory disease burden in metropolitan Phoenix and Dallas-Fort Worth. CMS competitive bidding reforms in these states reshape supplier economics for domiciliary ventilatory support. Houston medical center networks drive hospital-centric procurement for acute respiratory failure platforms.
Northeast
New York and Massachusetts health system consolidation concentrates purchasing leverage among integrated delivery networks negotiating enterprise-wide device contracts. FDA's Boston district office proximity accelerates 510(k) submission cycles for software-integrated respiratory platforms. Philadelphia corridor suppliers manage legacy electronic health record integration friction with hospital information systems.
Midwest
Illinois and Ohio manufacturing bases support component sourcing for medical-grade elastomer interfaces, though silicone input volatility compresses margin pools. Cleveland Clinic and Northwestern Medicine networks anchor institutional procurement for invasive and non-invasive ventilation. Chicago distribution hubs manage regional durable medical equipment supplier capacity constraints.
West Coast
California's Silicon Valley proximity accelerates software-as-a-medical-device development for cloud-connected respiratory platforms under FDA scrutiny. Kaiser Permanente's integrated model drives outcomes-based contracting pilots for remote patient monitoring integration. Los Angeles basin suppliers navigate OSHA respiratory protection standards layered with state licensure requirements.
US Respiratory Assist Devices EUA Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with established FDA quality management systems, creating tiered entry barriers for emerging hardware innovators. Three archetypes dominate: cloud-connected platform specialists, critical care portfolio anchors, and manufacturing-scale diversified industrials. Competitive moves concentrate on strategic partnerships for remote monitoring integration and geographic expansion into underpenetrated Sun Belt homecare markets.
Within the diversified medical technology tier, Koninklijke Philips N.V., Medtronic, and ResMed occupy distinct positioning vectors. Philips exemplifies manufacturing-scale capabilities across respiratory interface categories. Medtronic anchors hospital-centric distribution through critical care infrastructure. ResMed represents cloud-connected platform architecture with recurring revenue potential across homecare channels. Fisher & Paykel Healthcare Limited, GE HealthCare, and Drägerwerk AG & Co. KGaA sit within specialized equipment fabrication segments, with Masimo, Teleflex Incorporated, and Getinge rounding out the specialist tier.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| ResMed |
| Fisher & Paykel Healthcare Limited |
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Masimo |
| Teleflex Incorporated |
| Getinge |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day silicone elastomer lead times tether pricing power to medical-grade polymer availability, concentrating margin negotiation leverage among manufacturers with captive supply arrangements or long-term offtake contracts indexed to petrochemical benchmarks. This inventory dynamic amplifies cost pass-through capacity for established players while squeezing hardware innovators lacking procurement scale.
Pricing Analysis
Cost-plus contracts with silicone indexation dominate hospital procurement, embedding raw material volatility into device pricing. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected platforms with remote monitoring from basic pneumatic systems and refurbished units. Price differentiation hinges on FDA 510(k) clearance tier and bundled clinical support services. Pricing pressure stems from Medicare competitive bidding compression in Sun Belt homecare markets. Durable medical equipment suppliers exhibit highest price sensitivity; integrated delivery networks in the Southeast demonstrate lowest sensitivity due to outcomes-based contracting priorities.
Supply Chain Analysis
Strait of Malacca transit underwrites medical-grade polymer feedstock security for Southeast Asian silicone processors serving US interface manufacturers. Component sourcing concentrates in Malaysia, Singapore, and Germany for precision-molded elastomers, electronic pressure sensors, and turbine assemblies. Supply chain risk centers on single-source dependency for heated humidifier chambers with proprietary geometries. Distribution runs through regional durable medical equipment hubs in Atlanta and Dallas-Fort Worth, with last-mile deployment managed by Medicare-credentialed homecare suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Respiratory Assist Devices EUA Market functions as a regulatory-moat story where FDA quality management system entrenchment and CMS reimbursement code ownership create switching costs that protect incumbent positioning against hardware commoditization.
For Market Incumbents: Shield installed base revenue by deepening backward integration into medical-grade silicone processing and acquiring Medicare-credentialed homecare suppliers in Texas and Arizona. Cloud-connected platform interoperability threats from software-as-a-medical-device entrants demand accelerated API standardization investment. Priority lever rests on predictive algorithm FDA 510(k) clearance velocity. For New Entrants and Emerging Players: Lead with adaptive servo-ventilation software modules that integrate with legacy ResMed and Philips hardware via open-API protocols, avoiding capital-intensive device manufacturing. Hospital-at-home programs in Phoenix and Dallas-Fort Worth represent the most penetrable white-space. Go-to-market angle targets Medicare Advantage plans with readmission reduction guarantees. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because CMS reimbursement code permanence and respiratory therapist credentialing scarcity protect pricing power across replacement cycles. Acquisition target archetype: cloud-connected remote monitoring platforms with FDA software-as-a-medical-device clearance and established hospital system pilot contracts. Signal to watch: Medicare competitive bidding reform announcements affecting durable medical equipment reimbursement tiers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compressed approval timelines under EUA pathways privilege manufacturers with prior FDA engagement and established quality management infrastructure. |
| Cloud Platform Integration | Remote patient monitoring algorithms reduce hospital readmission exposure for COPD cohorts and create recurring SaaS revenue streams. |
| Hospital System Partnership | Integrated delivery networks in North Carolina and Georgia concentrate purchasing leverage and demand enterprise-wide device standardization. |
| Software Companion Development | FDA guidance on software-as-a-medical-device classifications requires cybersecurity validation protocols that exceed traditional hardware submissions. |
| Reimbursement Strategy | CMS competitive bidding reforms and Medicare Advantage expansion reshape supplier economics for domiciliary ventilatory support in Sun Belt states. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across respiratory therapy directors at Southeastern health systems, biomedical engineers at integrated delivery networks, durable medical equipment supplier executives, GPO contracts managers, and FDA regulatory affairs specialists. Secondary validation drew from FDA 510(k) and EUA filing databases, CMS Medicare competitive bidding program disclosures, hospital procurement records, and durable medical equipment licensure registries. Bottom-up device shipment estimates triangulated against top-down reimbursement claims data.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, delivery mode, end-user setting, and disease application. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Industry-specific inputs incorporated respiratory therapist workforce pipeline projections, Medicare Advantage penetration curves in Sun Belt states, and silicone elastomer price index movements.
Forecasts assume regulatory continuity in FDA EUA authority under Section 564 and CMS durable medical equipment reimbursement schedules; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as FDA software-as-a-medical-device guidance and IRA Medicare negotiation scope expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market