
 Friability Tester Market | 2026-2036
Friability Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Friability Tester Market Foresight
Contract testing organizations is hardening their share of friability tester procurement as pharmaceutical outsourcing accelerates. ERWEKA GmbH anchors its position through deep specialization in European pharmacopeial compliance instruments. SOTAX competes on gravimetric and optical testing method integration across its automated platform lines. Agilent Technologies extends its reach through channel control in North American quality control lab networks.
A friability tester measures the mechanical durability of compressed tablets and granules by subjecting samples to controlled abrasion and shock in a rotating drum, with results expressed as percentage weight loss against pharmacopeial thresholds. The apparatus typically operates at 25 rpm for 100 revolutions per USP <1216> and EP 2.9.7 protocols, serving as a mandatory quality control checkpoint before batch release. Automatic product type variants command the dominant margin pool due to integration demands from high-throughput pharmaceutical manufacturers. Gravimetric testing method segments show the steepest trajectory as real-time weight-loss tracking replaces manual endpoint determination. Contract testing organizations within the end user dimension represent the fastest-expanding install base as outsourcing erodes captive QC lab investment.
The US FDA enforces friability specifications through dissolution and mechanical integrity guidance for ANDA submissions, while the EMA's MDR framework elevates validation documentation requirements for equipment qualification. India's CDSCO aligns with ICH Q6A specifications for new drug applications, tightening importer scrutiny on testing apparatus provenance. Stakeholders must monitor pharmacopeial harmonization negotiations between USP, EP, and IP chapters, as divergence in drum geometry specifications could force dual-equipment strategies or trigger replacement cycles.
Market Dynamics
Pharmaceutical outsourcing is compressing captive QC lab investment and redirecting capital toward contract testing organizations, forcing equipment vendors to restructure their sales coverage and service models around multi-site CTO networks rather than single-facility pharmaceutical manufacturers.
Growth Catalysts
- EMA MDR Framework:The EU's Medical Device Regulation elevates validation documentation requirements for equipment qualification, compelling pharmaceutical manufacturers to upgrade to compliant automated friability testers with full IQ/OQ/PQ traceability.
- Contract Testing Organizations:Pharmaceutical outsourcing accelerates as Big Pharma sheds fixed QC costs, expanding the addressable install base for high-throughput automated systems capable of batch-to-batch electronic records.
- Gravimetric Method Integration:Real-time weight-loss tracking replaces manual endpoint determination, reducing operator variability and aligning with USP Chapter 41 weighing accuracy requirements for analytical balances.
Market Restraints
- Stainless Steel Input Volatility:Drum construction relies on pharmaceutical-grade 316L stainless steel, with price swings in nickel and molybdenum feedstock compressing equipment margins and triggering quarterly pricing adjustments.
- German Equipment Concentration:Specialized pharmacopeial compliance instrument manufacturing clusters around Frankfurt and Ludwigshafen, creating geographic supply risk and extended lead times during regional logistics disruptions.
- Laser Diffraction Substitution:Particle size distribution analysis via laser diffraction offers complementary mechanical integrity data, diverting some R&D budgets from dedicated friability capital expenditure.
Strategic Opportunities
- Indian CDSCO Alignment:India's pharmaceutical regulator tightening ICH Q6A specifications for new drug applications creates demand for USP/EP-compliant equipment among domestic generic manufacturers and export-oriented formulation units.
- Optical-Gravimetric Convergence:Integration of machine vision with real-time weighing enables simultaneous surface defect detection and mass loss quantification, opening premium pricing tiers for multi-modal systems.
- Service Contract Unbundling:After-sales revenue streams expand through predictive maintenance packages and remote calibration services, decoupling recurring revenue from new equipment sales cycles.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergence between USP, EP, and IP drum geometry specifications forces manufacturers to maintain multiple equipment configurations or absorb retooling costs for dual-compliance instruments.
- 21 CFR Part 11 Integration Complexity:Electronic records and signatures compliance requires extensive legacy system retrofitting, extending validation timelines and demanding specialized IT-OT convergence expertise scarce among mid-sized pharmaceutical QC departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friability Tester Market |
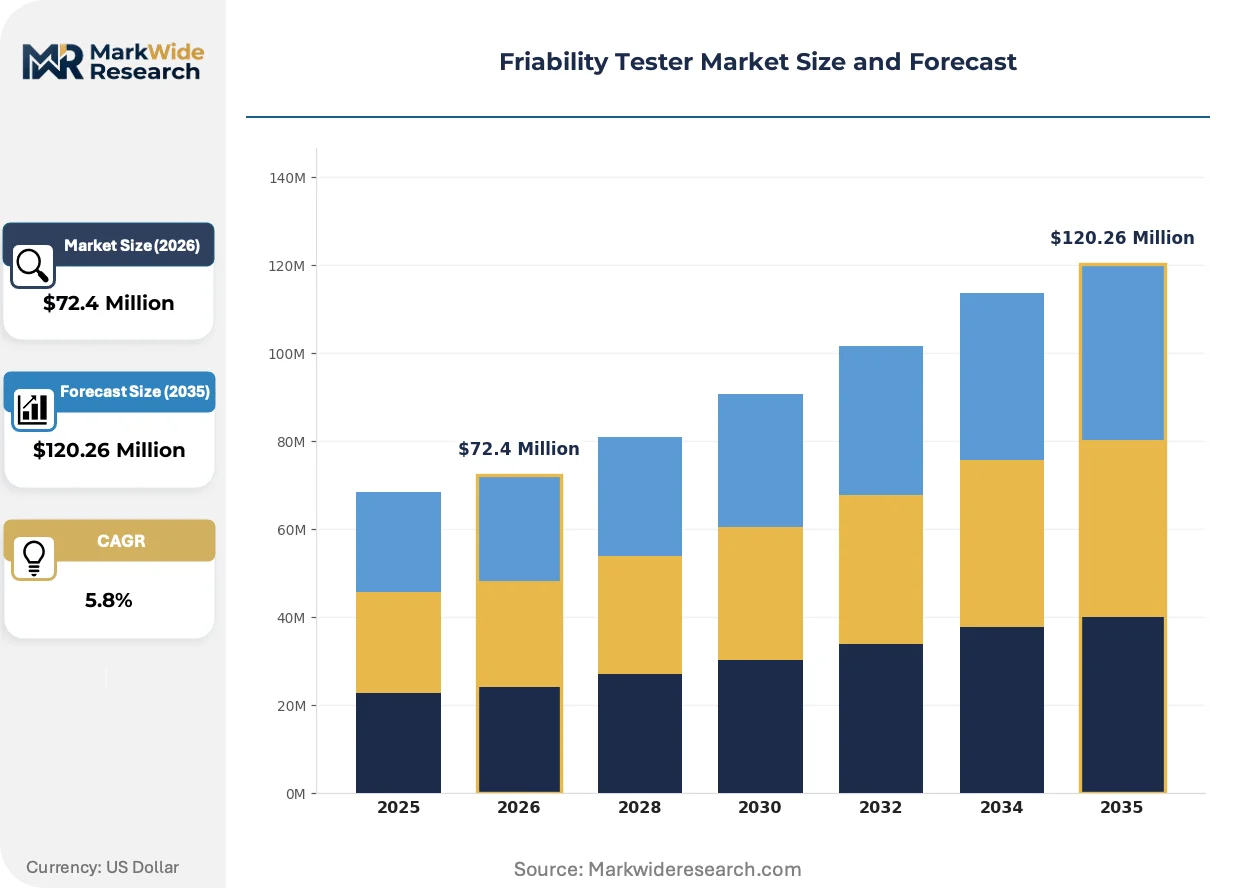
| Market Size in 2026 | $72.4 Million |
| Market Size in 2035 | $120.26 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Digital, Motorized Testing Method: Electromechanical, Gravimetric, Optical, Mechanical Application: Pharmaceutical Tablets, Nutraceuticals, Herbal Formulations, Veterinary Drugs End User: Pharmaceutical Manufacturers, Quality Control Labs, Research Institutes, Contract Testing Organizations |
| Companies Covered | Copley Scientific, ERWEKA GmbH, SOTAX, Agilent Technologies, Pharma Test, Electrolab, Labindia Analytical Instruments, Veego Instrument Corporation, Campbell Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friability Tester Market Shifts & Advancements
Automation and data integrity requirements are transforming friability testing from a manual QC checkpoint into an integrated, audit-ready workflow node within pharmaceutical manufacturing execution systems.
Machine vision systems equipped with high-resolution cameras and edge computing capabilities are rewriting how surface abrasion is quantified. High-volume generic manufacturers in India and China deploy these systems to eliminate operator subjectivity in endpoint determination. The technology is compressing the market for basic manual drum testers by embedding visual defect classification directly into gravimetric workflows.
REACH and RoHS restrictions on hazardous substances in electrical equipment are reshaping instrument design priorities. European manufacturers must eliminate lead solder and specific flame retardants from control electronics, accelerating redesign cycles and favoring vendors with established EU compliance engineering teams. The regulatory burden falls heaviest on mid-tier suppliers lacking dedicated environmental compliance functions.
Buyer concentration among the largest contract testing organizations is altering channel economics. Multi-site CTOs negotiate enterprise pricing and standardized equipment platforms, displacing the fragmented purchasing patterns of independent pharmaceutical QC labs. This concentration is most visible in Germany's Rhine-Main pharmaceutical cluster, where CROs like Eurofins and SGS have consolidated testing capacity across Ludwigshafen, Frankfurt, and Darmstadt facilities.
Friability Tester Market Segmentation
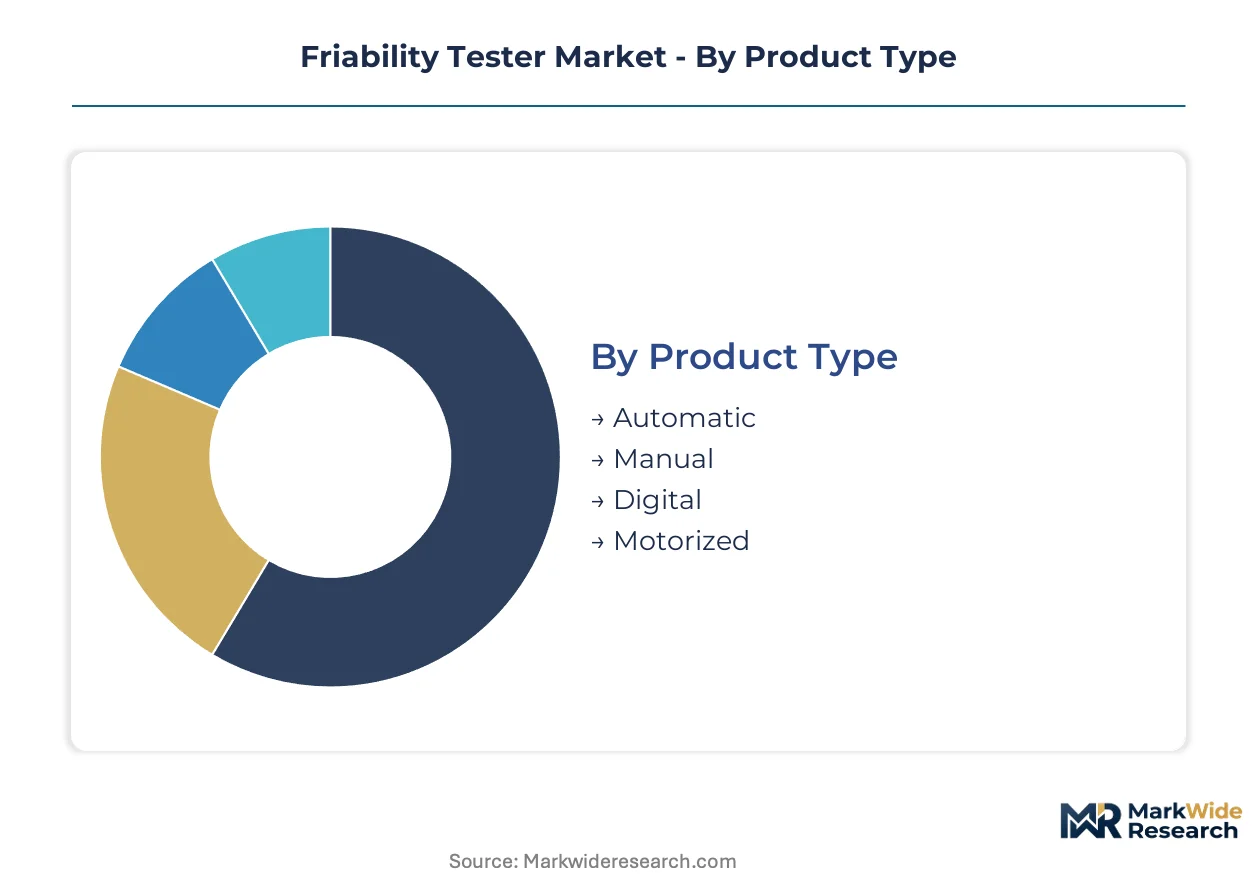
Friability tester procurement patterns diverge sharply across equipment sophistication tiers and testing methodologies. Pharmaceutical manufacturers select instrument configurations based on batch volume, regulatory filing requirements, and integration depth with manufacturing execution systems.
Product Type:
Equipment upgrade cycles accelerate as legacy manual systems face replacement pressure from data integrity mandates and throughput demands.
- Automatic:These systems integrate programmable drum rotation, automated sample loading, and direct LIMS connectivity for electronic batch records. High-volume generic manufacturers in India deploy these units to meet CDSCO's tightened ICH Q6A documentation requirements for export-oriented production.
- Manual:Hand-cranked or basic motorized drums without data capture capabilities serve small-batch compounders and educational institutions. Demand concentrates in emerging market formulation units with limited capital budgets and minimal regulatory filing obligations.
- Digital:Microprocessor-controlled units with touchscreen interfaces and internal data storage bridge the gap between manual and fully automatic systems. These instruments appeal to mid-sized pharmaceutical QC labs seeking 21 CFR Part 11 readiness without full MES integration costs.
- Motorized:Simple electric drive mechanisms replace hand-cranking while omitting advanced control electronics. Regional generic manufacturers in Eastern Europe favor this tier for cost-sensitive capacity expansion.
Volume placements concentrate in Automatic; the faster expansion belongs to Digital.
Testing Method:
Method selection hinges on the trade-off between measurement precision and operational complexity in high-throughput environments.
- Gravimetric:Real-time weight-loss tracking via integrated analytical balances eliminates operator variability in endpoint determination. The steepest adoption curve occurs among contract testing organizations seeking to standardize procedures across multi-site networks.
- Electromechanical:Combined motor control with programmable rotation parameters enables precise adherence to USP and EP revolution counts. German pharmaceutical clusters around Frankfurt specify these systems for pharmacopeial compliance validation.
- Optical:Machine vision systems quantify surface abrasion patterns through high-resolution imaging and edge computing. Indian and Chinese generic manufacturers deploy these for defect classification integration into gravimetric workflows.
- Mechanical:Basic drum rotation without integrated measurement remains confined to R&D screening and teaching laboratories. Limited growth trajectory reflects regulatory pressure for documented, reproducible test protocols.
Gravimetric methods command the dominant revenue share; optical-gravimetric convergence is gaining share fastest.
Application:
Application-driven procurement reflects divergent regulatory scrutiny and batch economics across dosage form categories.
- Pharmaceutical Tablets:Compressed oral solid dosage forms for human use face the most stringent mechanical integrity requirements under FDA dissolution guidance and EMA MDR frameworks. This segment absorbs the majority of high-end automatic system placements.
- Nutraceuticals:Dietary supplement tablets and capsules operate under less prescriptive regulatory regimes but increasingly adopt pharmaceutical-grade QC protocols for export market access. US contract manufacturers drive demand for mid-tier digital systems.
- Herbal Formulations:Traditional medicine products with variable matrix compositions require specialized drum geometries and abrasion parameters. Domestic manufacturers in India and China represent the primary install base.
- Veterinary Drugs:Animal health tablets face species-specific testing protocols with lower throughput requirements. Regional animal health specialists in Brazil and Australia constitute the core demand pool.
Pharmaceutical Tablets anchor volume demand; Nutraceuticals are climbing the fastest.
End User:
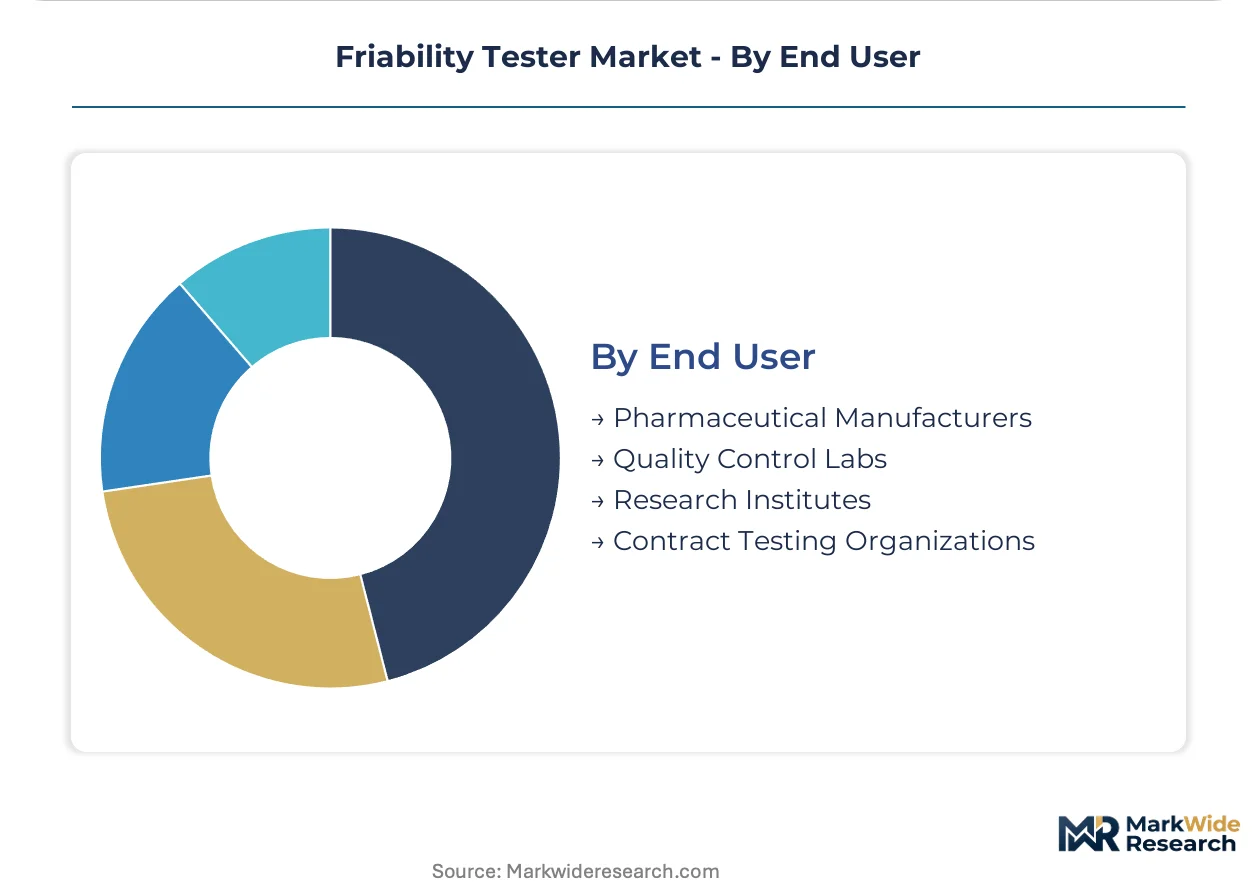
Customer structure is shifting as pharmaceutical outsourcing redirects capital from captive facilities to specialized testing service providers.
- Contract Testing Organizations:Multi-site CROs and CMOs consolidate testing capacity under standardized equipment platforms with enterprise pricing. Germany's Rhine-Main cluster—Eurofins and SGS facilities across Ludwigshafen, Frankfurt, and Darmstadt—exemplifies this concentration.
- Pharmaceutical Manufacturers:Big Pharma captive QC labs face investment compression as outsourcing accelerates, though innovator companies maintain specialized instruments for NDA-supporting stability studies.
- Quality Control Labs:Independent third-party testing facilities serving regional generic manufacturers seek mid-range digital systems with flexible protocol programming.
- Research Institutes:Academic and government laboratories prioritize manual and motorized units for method development and educational purposes, with limited budget for automation.
Contract Testing Organizations are expanding most quickly; Pharmaceutical Manufacturers retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and tax-advantaged research corridors in the United States concentrate friability tester procurement. Equipment vendors structure regional service networks around these zones to capture high-volume generic drug production and innovator stability testing demand.
United States
Generic drug manufacturers near Research Triangle Park and the New Jersey pharmaceutical corridor drive automatic system placements. The FDA's ANDA dissolution guidance mandates mechanical integrity documentation, compelling upgrades to 21 CFR Part 11-compliant instruments. Boston-area contract testing organizations consolidate multi-site capacity under standardized Agilent platforms.
Germany
Frankfurt and Ludwigshafen host Europe's densest cluster of pharmacopeial compliance instrument manufacturing. The EMA MDR framework elevates IQ/OQ/PQ traceability requirements, favoring ERWEKA GmbH's specialized European pharmacopeial systems. Rhine-Main CROs negotiate enterprise pricing across Eurofins and SGS facilities.
India
Hyderabad's Genome Valley and Ahmedabad's formulation belt absorb mid-tier digital and automatic systems. CDSCO's ICH Q6A alignment for export-oriented production tightens importer scrutiny on USP/EP-compliant apparatus provenance. Domestic generic manufacturers replace manual drums ahead of regulatory audits.
China
Yangtze River Delta pharmaceutical parks near Shanghai deploy optical-gravimetric convergent systems for high-throughput defect classification. NMPA's harmonization with ICH quality guidelines accelerates replacement of legacy mechanical testers. Zhejiang and Jiangsu provinces concentrate contract manufacturing capacity requiring validated electronic records.
Switzerland
Basel's innovator pharmaceutical headquarters maintain specialized instruments for NDA-supporting stability studies. Swissmedic's stringent equipment qualification standards favor premium automated platforms with full audit trails. The country's precision engineering tradition supports domestic servicing of high-end gravimetric systems.
Friability Tester Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacopeial compliance instrument makers commanding premium positioning against regional fabricators. The vendor base organizes into three tiers: European specialists with deep regulatory engineering capabilities, diversified analytical platform providers leveraging channel density, and emerging market equipment builders competing on capital cost. Consolidation pressure intensifies as multi-site contract testing organizations demand standardized platforms with unified service contracts. Technology licensing agreements between drum mechanics specialists and balance manufacturers reshape component sourcing economics.
Among European pharmacopeial specialists, ERWEKA GmbH anchors the compliance-focused tier through its Ludwigshafen engineering base. SOTAX occupies a position on the automated platform vector, while Agilent Technologies exemplifies the diversified analytical instrument provider leveraging North American quality control lab networks. These three represent distinct competitive archetypes: the deep specialist, the integrated automation house, and the channel-dominant platform player.
| Leading Market Players |
|---|
| Copley Scientific |
| ERWEKA GmbH |
| SOTAX |
| Agilent Technologies |
| Pharma Test |
| Electrolab |
| Labindia Analytical Instruments |
| Veego Instrument Corporation |
| Campbell Electronics |
| Others |
Supply & Pricing Matrix
Backward integration into analytical balance manufacturing anchors pricing power for premium friability tester vendors, as captive metrology capabilities eliminate third-party component markups while EMA MDR validation documentation requirements lock buyers into qualified supplier relationships.
Pricing Analysis
Premium pricing for sub-8-week lead times separates urgent replacement demand from standard procurement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by 21 CFR Part 11 compliance depth and IQ/OQ/PQ documentation completeness. Price differentiation centers on gravimetric-automation integration density and remote calibration service bundling. Pricing pressure stems from nickel-molybdenum volatility in 316L stainless steel drum fabrication, compressing margins most acutely for mid-tier digital system vendors. Contract testing organizations exhibit lowest price sensitivity due to enterprise standardization mandates; regional generic manufacturers in Eastern Europe show highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements for pharmaceutical-grade 316L stainless steel force vendors to maintain approved mill relationships across Germany and Switzerland alongside backup Japanese suppliers. Component sourcing draws from precision machining clusters in Baden-Württemberg, control electronics from Taiwanese PCB fabricators, and analytical load cells from Swiss metrology specialists. Supply chain risk concentrates in single-source dependency on Ludwigshafen-area drum mechanics engineering for pharmacopeial compliance instruments. Distribution runs through direct field service organizations for automatic systems, regional distributors for digital tiers, and educational supply channels for manual units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMA MDR equipment qualification documentation creates a barrier-to-entry moat that rewards incumbents with validated IQ/OQ/PQ traceability while straining capital-constrained challengers.
For Market Incumbents: Anticipate laser diffraction substitution threats in R&D screening applications by embedding surface defect classification into gravimetric workflows. Defensive consolidation should prioritize acquisition of machine vision software specialists to close optical-gravimetric convergence gaps. Channel control investments in multi-site contract testing organization service contracts provide the strongest retention lever against diversified analytical platform competitors.
For New Entrants and Emerging Players: Launch via refurbished equipment leasing models targeting mid-sized Indian generic manufacturers facing CDSCO audit pressure without capital budgets for new automatic systems. White-space concentration sits in digital tier gravimetric systems with modular 21 CFR Part 11 upgrade paths. The most penetrable segment comprises Eastern European regional manufacturers seeking motorized tier replacements; go-to-market should emphasize remote calibration service bundling to offset lower hardware margins.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified analytical instrument conglomerates seeking pharmacopeial compliance capabilities. Long-term viability favors targets with established EMA MDR validation documentation libraries and captive servicing networks across the Rhine-Main cluster. The signal to watch is pharmacopeial harmonization negotiation momentum between USP, EP, and IP chapters—convergence would compress dual-compliance equipment demand, while sustained divergence extends replacement cycle visibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical-Gravimetric System Integration | Machine vision convergence captures premium positioning against laser diffraction substitution in Indian and Chinese generic manufacturing. |
| Remote Calibration Service Expansion | Predictive maintenance packages decouple recurring revenue from new equipment sales cycles for contract testing organizations. |
| EMA MDR Documentation Investment | IQ/OQ/PQ traceability libraries create switching costs that lock pharmaceutical manufacturers into qualified supplier relationships. |
| Indian CDSCO Compliance Positioning | ICH Q6A-aligned equipment provenance documentation opens export-oriented formulation units in Hyderabad and Ahmedabad. |
| Stainless Steel Input Hedging | Long-term offtake agreements with German and Swiss mills mitigate nickel-molybdenum price volatility compression on drum fabrication margins. |
Research Methodology
Multi-period observation of equipment procurement patterns, regulatory filing timelines, and contract testing organization capacity expansion anchored the trend analysis, supplemented by interviews with pharmaceutical quality control directors, regulatory affairs specialists at generic manufacturers, CRO laboratory managers, and analytical instrument procurement officers. Secondary validation drew from FDA ANDA submission databases, EMA MDR technical documentation requirements, CDSCO import registration records, and USP pharmacopeial chapter revision histories. Bottom-up install base modeling triangulated against top-down pharmaceutical capital expenditure surveys.
Input-output matrices mapped automatic, digital, manual, and motorized product type demand against gravimetric, electromechanical, optical, and mechanical testing method adoption curves across pharmaceutical tablet, nutraceutical, herbal formulation, and veterinary drug applications. Segmentation dimensions included end user structure shifting between contract testing organizations and captive pharmaceutical manufacturers, regional regulatory cluster alignment with USP, EP, or IP pharmacopeial standards, and integration depth with manufacturing execution systems. CAGRs were derived from equipment replacement cycle analysis and outsourcing-driven install base reconfiguration across the projection horizon.
Pharmacopeial harmonization delays, stainless steel commodity volatility, and contract testing organization buyer concentration are the dominant revision risks to modeled equipment demand. Forecasts assume continued divergence in drum geometry specifications between USP, EP, and IP chapters. Deviation in EMA MDR enforcement intensity or CDSCO audit frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Sterility Testing Market
Testing Services
Allergy Tester Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Adenovirus Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Mycological Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Solid Tumor Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
North America Drug Screening Market
Testing Services
Dengue Testing Market