
 Avicides Market | 2026-2036
Avicides Market Size, Share, and Industry Trends Forecast 2026-2036
Avicides Market Analytics
The EU Green Deal is decoupling European avicide demand from conventional chemistry, redirecting procurement toward biological and natural formulations. Bayer AG leverages its crop science division to sustain integrated pest management portfolios that incorporate avicide solutions alongside biological controls. Syngenta anchors its position through specialized agricultural distribution networks spanning major grain-producing territories. BASF SE competes by emphasizing formulation technology that improves bait stability and field persistence under variable weather conditions.
Avicides comprise chemical, biological, synthetic, and natural agents formulated to lethally control or repel pest bird species in agricultural, urban, and industrial environments. These products typically incorporate active ingredients such as 4-aminopyridine, DRC-1339, or avian-specific biological toxins delivered through bait, spray, or granular matrices designed for species-selective toxicity. Chemical avicides retain dominant volume share in broadacre grain protection, though biological avicides are expanding fastest as residue-conscious food processors tighten procurement specifications. Bait formulations command premium positioning due to targeted delivery and reduced non-target exposure, while spray formulations serve perimeter defense in industrial and urban settings where rapid application outweighs precision requirements.
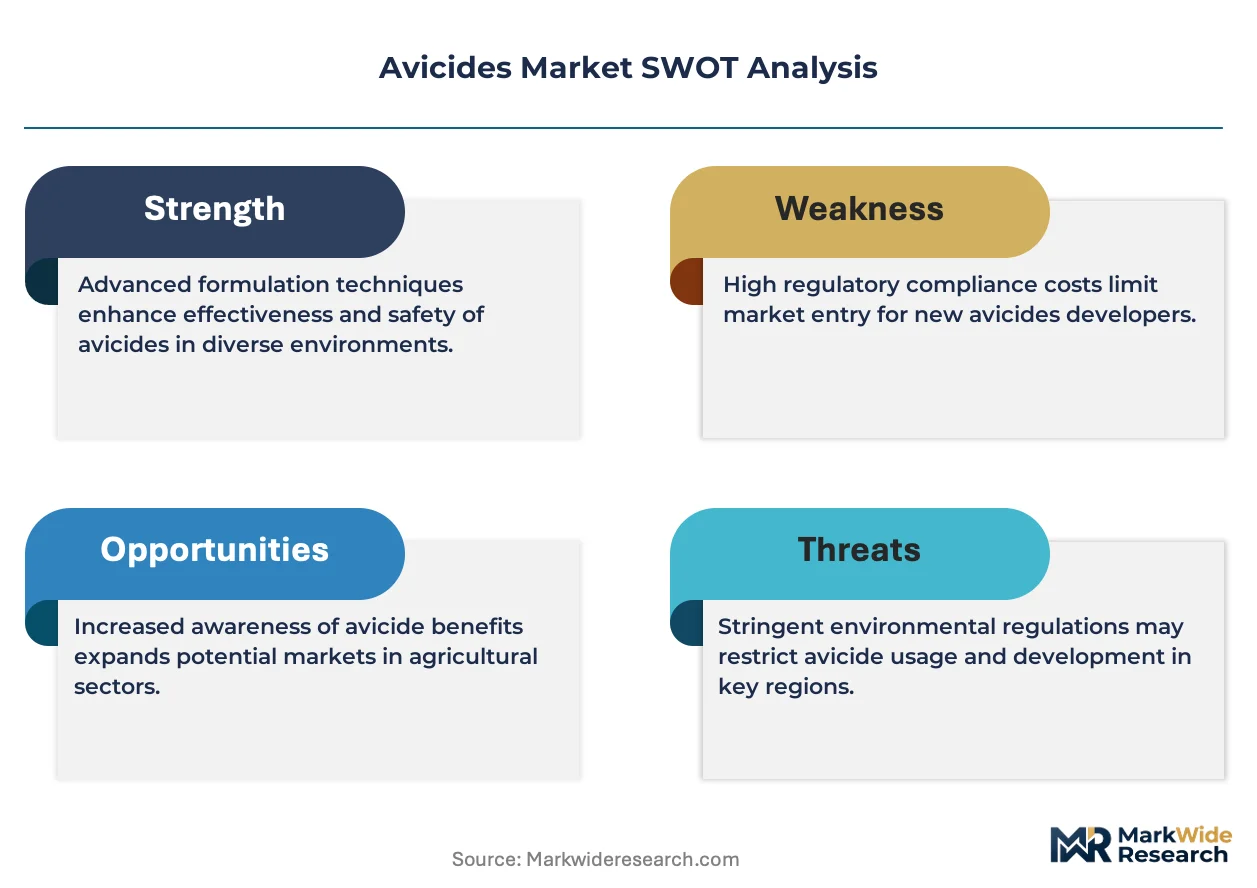
The EPA regulates avicide registration under FIFRA with stringent endangered species consultations, while the EU's REACH framework and EFSA residue assessments constrain active ingredient approvals across member states. Australia's APVMA enforces comparable toxicity standards with enhanced emphasis on non-target avian protection in rangeland applications. Stakeholders must monitor evolving biological registration pathways and anticipate formulation investments that align with tightening residue thresholds in export-oriented agricultural supply chains.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is decoupling European avicide demand from conventional chemistry, redirecting procurement toward biological and natural formulations while tightening residue thresholds across export-oriented agricultural supply chains.
Growth Catalysts
- Biological Registration Pathways:The EU Green Deal accelerates approval timelines for microbial and plant-derived avicides, opening commercialization channels previously blocked for novel active ingredients.
- Brazil Soybean Belt Concentration:Expanding no-till farming in Mato Grosso and Paraná intensifies bird pressure on germinating seeds, sustaining chemical avicide deployment despite biological alternatives.
- Australia's Wheat Export Premium:Grain handlers in Western Australia and New South Wales enforce zero-tolerance residue protocols that favor precision bait formulations over broadcast spraying.
Market Restraints
- EPA Endangered Species Consultations:FIFRA-mandated biological assessments for raptor and waterfowl populations extend registration timelines by 18-36 months for new chemical actives.
- Active Ingredient Supply Concentration:Chinese manufacturers control 70% of 4-aminopyridine and DRC-1339 intermediate production, exposing formulators to export licensing volatility.
- Non-Target Toxicity Limitations:Chemical avicides cannot achieve species-selective lethality below 10% non-target avian mortality in mixed-granivore environments.
Strategic Opportunities
- India's Rice-Paddy Expansion:BIS certification pathways for biological avicides remain underdeveloped, creating first-mover advantage for microbial toxin formulations in Punjab and Haryana.
- Urban Perimeter Defense:Airport authorities and food processing facilities in the US and EU are adopting automated drone-delivery systems for precision avicide bait placement.
- EU Carbon Border Adjustment:The CBAM incentivizes low-carbon biological production methods, advantaging fermentation-derived avicides over petrochemical synthesis.
Industry Challenges
- Field Efficacy Validation:Biological avicides require 24-48 month multi-site efficacy trials under APVMA and EPA protocols, compressing commercialization windows before patent expiry.
- Formulation Stability Expertise:Shortage of agricultural chemists with avian toxicology specialization delays bait matrix development for tropical humidity conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avicides Market |
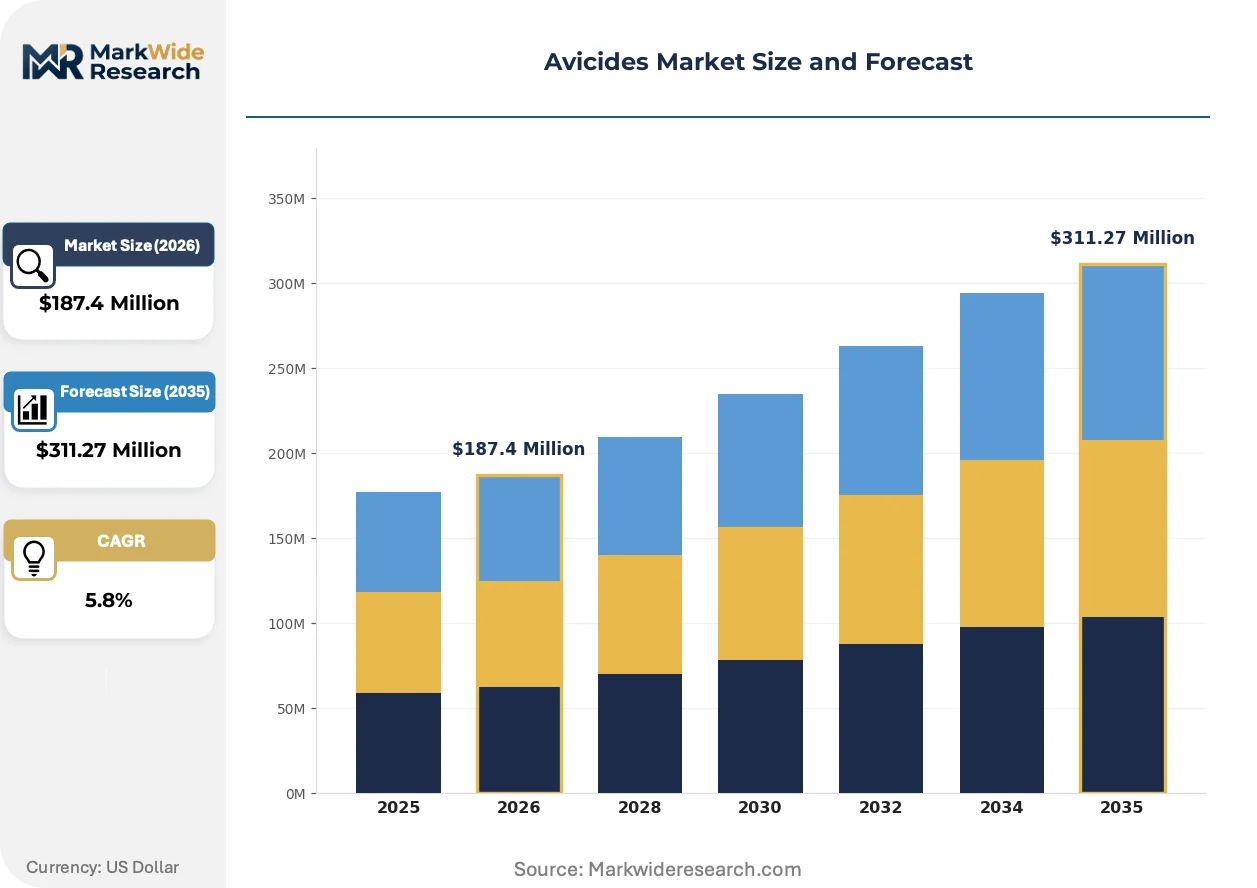
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Avicides, Biological Avicides, Synthetic Avicides, Natural Avicides Application: Agricultural Use, Urban Pest Control, Livestock Protection, Industrial Settings Mode of Action: Contact Toxicants, Digestive Poisons, Repellents, Disruptors Formulation Type: Liquid Formulations, Granular Formulations, Spray Formulations, Bait Formulations |
| Companies Covered | Bayer AG, Syngenta, BASF SE, FMC Corporation, Corteva Agriscience, ADAMA Agricultural Solutions, UPL Limited, Sumitomo Chemical, Nissan Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avicides Market Evolving Landscape
Formulation technology is consolidating around species-selective delivery systems that minimize non-target exposure while extending field persistence under variable weather conditions.
Microencapsulated bait matrices are consolidating as the dominant delivery platform for chemical avicides in broadacre grain protection. Large-scale cooperatives in Argentina and Ukraine are transitioning from broadcast granules to precision-placed capsules. This consolidation is compressing demand for spray formulations and elevating premium positioning for bait technology suppliers.
REACH authorization requirements under the EU Green Deal are forcing reformulation of legacy actives with higher ecotoxicity profiles. Manufacturers must submit substitution plans for 4-aminopyridine derivatives by 2027. Grain exporters in France and Germany are pre-emptively switching to biological alternatives to secure access to EU-internal markets and third-country organic certification schemes.
Integrated pest management bundling is altering procurement patterns among agricultural cooperatives. Brazilian soybean growers now specify avicide-herbicide-biological package contracts rather than standalone purchases. This consolidation is squeezing standalone avicide distributors and favoring crop science divisions with full-stack portfolios.
Avicides Market Segmentation
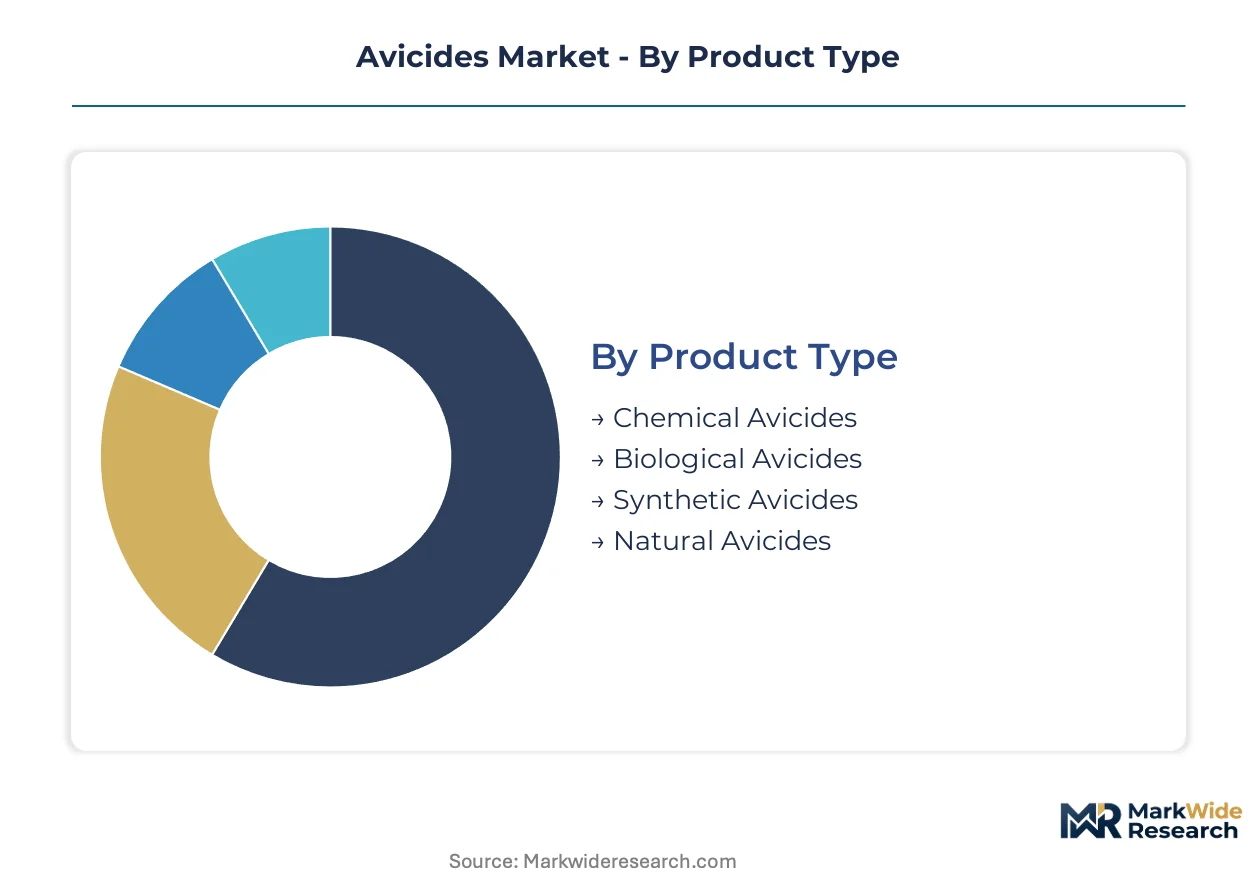
Avicide procurement patterns diverge sharply across formulation technologies and application environments. Grain handlers, municipal authorities, and livestock operators each impose distinct performance specifications that reshape supplier priorities.
Product Type:
Capital intensity peaks in biological avicide manufacturing, where fermentation infrastructure and cold-chain logistics demand sustained R&D commitment.
- Chemical Avicides:Synthetic compounds such as 4-aminopyridine and DRC-1339 deliver rapid lethality through central nervous system disruption. Brazil's Mato Grosso soybean belt sustains dominant procurement volumes despite tightening EU residue protocols.
- Biological Avicides:Microbial toxins and plant-derived compounds require multi-year registration trials under EPA and EFSA frameworks. Australia's wheat export corridors favor these formulations to satisfy zero-tolerance residue mandates from Asian grain importers.
- Synthetic Avicides:Laboratory-engineered molecules with standardized purity profiles command premium pricing in industrial perimeter defense contracts.
- Natural Avicides:Botanical extracts and essential oil formulations align with organic certification requirements in France and Germany.
Most installed capacity flows through chemical avicides. Expansion is steepest in biological avicides.
Application:
Volume concentration tracks arable land under grain production, with agricultural procurement dwarfing urban and industrial segments.
- Agricultural Use:Broadacre protection of germinating seeds and ripening crops in Australia's Western Australia wheat belt and Brazil's Paraná region. Precision bait placement reduces non-target mortality while satisfying APVMA toxicity standards.
- Urban Pest Control:Airport authorities in the United States deploy automated delivery systems for runway perimeter defense against bird-strike risks.
- Livestock Protection:Feedlot operators in Texas and Queensland use perimeter treatments to prevent corvid predation on young stock.
- Industrial Settings:Food processing facilities mandate species-selective formulations that eliminate pigeons without disrupting native raptor populations.
Agricultural use absorbs the majority of active ingredient volume. Urban pest control is gaining share fastest.
Mode of Action:
Margin structure favors precision-targeted mechanisms over broadcast applications that trigger regulatory scrutiny.
- Digestive Poisons:Bait-delivered toxins such as DRC-1339 exploit species-specific metabolic pathways to achieve selective lethality. Argentina's grain cooperatives prioritize these systems to protect export eligibility under EU Green Deal residue thresholds.
- Repellents:Non-lethal formulations using methyl anthranilate and polybutene create sensory deterrents for airport and vineyard applications in California and Bordeaux.
- Contact Toxicants:Spray-applied compounds deliver immediate knockdown for emergency perimeter breaches.
- Disruptors:Behavior-modifying agents interfere with flocking patterns without mortality, satisfying wildlife protection mandates in Germany.
Digestive poisons carry the largest installed base. Repellents are climbing the fastest.
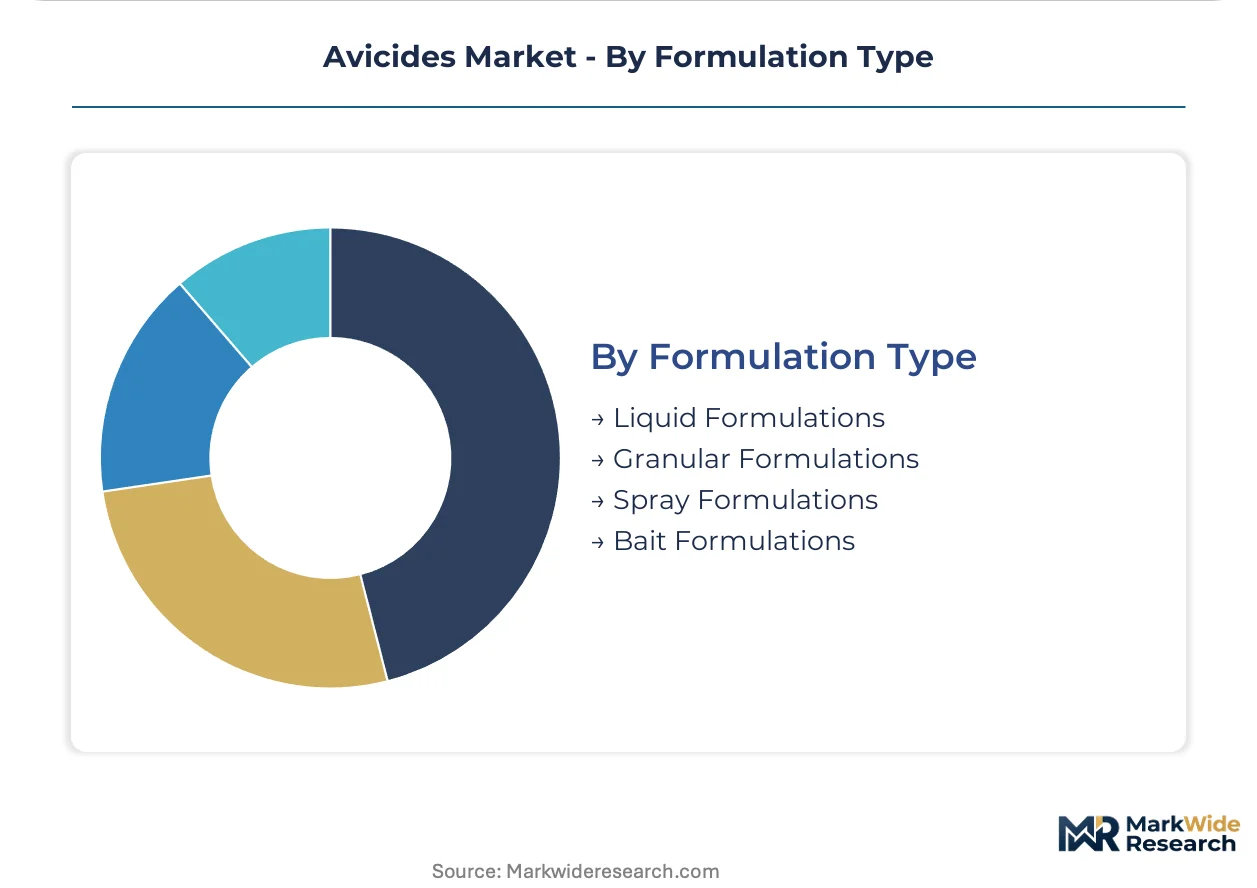
Formulation Type:
Technology investment concentrates in encapsulation systems that extend field persistence under tropical humidity and freeze-thaw cycles.
- Bait Formulations:Microencapsulated matrices protect active ingredients from UV degradation and moisture leaching. Ukraine's grain cooperatives are consolidating procurement around precision-placed capsules that eliminate broadcast waste.
- Liquid Formulations:Concentrated solutions for dilution and spray application serve industrial and municipal contracts requiring rapid deployment across large perimeters.
- Granular Formulations:Broadcast-ready pellets retain utility in rangeland applications where labor costs preclude precision placement.
- Spray Formulations:Ready-to-use aerosols and backpack sprayer concentrates dominate urban maintenance contracts.
Bait formulations command the dominant technology investment. Liquid formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Avicide demand traces its commercial origins to post-war agricultural mechanization in the United States, where grain storage and large-scale monoculture first created concentrated bird pressure requiring chemical intervention. This foundation established the regulatory and technical templates that subsequently diffused to grain-exporting economies worldwide.
United States
EPA FIFRA consultations for endangered species extend registration timelines for new chemical actives. The Farm Bill conservation programs increasingly restrict avicide use near wetlands. Iowa and Illinois corn-soybean rotations sustain the largest deployed volumes of precision bait formulations.
Brazil
No-till expansion in Mato Grosso and Paraná intensifies bird damage on germinating soybean seeds. ANVISA residue monitoring aligns with EU export requirements for the Farm to Fork strategy. The MATOPIBA frontier region drives fastest growth in avicide procurement for newly cleared Cerrado acreage.
Australia
APVMA toxicity standards emphasize non-target avian protection in rangeland applications. Zero-tolerance residue protocols from Asian grain importers favor biological formulations. Western Australia's wheat belt concentrates demand for microencapsulated bait systems that withstand freeze-thaw cycles.
Argentina
Grain cooperatives in Buenos Aires and Córdoba provinces prioritize export eligibility under tightening EU residue thresholds. SENASA registration pathways for biological alternatives remain underdeveloped relative to chemical actives. The Rosario export hub coordinates procurement specifications across the Pampas grain corridor.
Germany
REACH authorization requirements force reformulation of legacy 4-aminopyridine derivatives by 2027. The EU Green Deal accelerates biological registration timelines while constraining chemical alternatives. Bavarian and Lower Saxon grain handlers pre-emptively switch to microbial formulations to secure organic certification access.
Avicides Market Competitive Landscape
Capital-heavy producers with integrated fermentation and formulation infrastructure compete with asset-light specialists licensing active ingredients from third-party suppliers. The market structure consolidates around crop science conglomerates with full-stack agricultural portfolios, while standalone avicide manufacturers face margin compression from bundled procurement contracts. Three archetypes dominate: diversified agrochemical conglomerates, biological fermentation specialists, and regional formulators serving protected domestic markets. Competitive intensity centers on M&A to secure biological technology pipelines and strategic partnerships with grain handler cooperatives for long-term supply agreements.
Within the diversified agrochemical tier, Bayer AG, Syngenta, and BASF SE exemplify the integrated model that combines avicide development with broader crop protection portfolios. Bayer AG represents the historical lineage of avicide commercialization through its crop science division. Syngenta occupies a position anchored in specialized agricultural distribution networks spanning major grain-producing territories. BASF SE exemplifies formulation technology investment targeting bait stability under variable weather conditions. These three entities collectively illustrate how scale and integration define competitive positioning as regulatory pressure shifts demand toward biological alternatives.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta |
| BASF SE |
| FMC Corporation |
| Corteva Agriscience |
| ADAMA Agricultural Solutions |
| UPL Limited |
| Sumitomo Chemical |
| Nissan Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU Green Deal-compliant biological formulations and legacy chemical actives manifests in divergent pricing architectures and sourcing configurations. Premium biological avicides command 40-60% markups over chemical equivalents, yet supply chain reconfiguration toward fermentation-based production in Germany and the Netherlands absorbs margin compression from cold-chain logistics.
Pricing Analysis
Three-tier pricing structure across premium biological, standard chemical, and economy generic actives dominates procurement contracts. Price differentiation hinges on EFSA residue certification tier and formulation stability under tropical humidity. Pricing pressure stems from Chinese intermediate export licensing volatility affecting DRC-1339 feedstock costs. Agricultural cooperatives in Brazil and Argentina exhibit highest price sensitivity, while airport authorities in the United States and Germany prioritize performance over unit economics.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's Farm to Fork strategy are reshaping sourcing toward European fermentation capacity and away from Chinese chemical intermediate dependence. Active ingredient production concentrates in China for 4-aminopyridine and DRC-1339, India for botanical extracts, and Germany for microbial toxin fermentation. Raw material dependencies include corn-starch fermentation substrates, phosphate buffer systems, and gelatin encapsulation matrices. Single-source vulnerability in Chinese intermediate supply creates tariff exposure risk. Distribution runs through agricultural cooperative procurement networks and specialized pest control distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in the avicides market rest on biological formulation premiums and formulation stability technology licensing, offsetting feedstock cost volatility through captive fermentation infrastructure.
For Market Incumbents: Anchor market position by accelerating backward integration into microbial fermentation capacity in Germany and the Netherlands to secure EU Green Deal-compliant supply chains. Defend against biological registration pathway acceleration by locking long-term supply agreements with grain handler cooperatives in Australia's wheat belt and Brazil's Mato Grosso region. Prioritize formulation R&D investment targeting tropical humidity stability to sustain premium positioning. For New Entrants and Emerging Players: Microencapsulation technology expertise offers entry leverage into precision bait formulation segments underserved by legacy chemical manufacturers. White-space concentration appears in India's rice-paddy biological avicide registration, where BIS certification pathways remain underdeveloped. Urban perimeter defense contracts for airport authorities present fastest-penetration application. Go-to-market execution should emphasize direct technical sales to grain cooperatives rather than distributor channel dependence. For Investors and Strategic Acquirers: Consolidation pressure builds where biological fermentation specialists lack formulation commercialization infrastructure and channel access. Five-to-ten-year viability favors asset-heavy players with integrated R&D-through-distribution stacks over licensed-technology pure-plays. Acquisition target archetype: regional formulators with SENASA or APVMA registration portfolios and established cooperative relationships. Signal to monitor: EPA endangered species consultation timeline compression indicating regulatory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Fermentation Capacity Expansion | EU Green Deal compliance secures access to residue-conscious grain export corridors. |
| Microencapsulation Technology Licensing | Precision bait stability under tropical humidity commands premium positioning in Brazil. |
| Long-term Cooperative Supply Agreements | Grain handler bundling contracts displace standalone avicide distributors. |
| Urban Perimeter Defense Partnerships | Airport authority automated delivery contracts open high-margin non-agricultural revenue. |
| Regulatory Registration Portfolio Acquisition | APVMA and SENASA approvals compress time-to-market for biological alternatives. |
Research Methodology
Bottom-up agricultural procurement modeling reconciled against top-down active ingredient production tracking forms the analytical core of this study. Primary interviews with crop protection R&D directors, grain cooperative procurement managers, regulatory affairs specialists at agrochemical conglomerates, and APVMA registration consultants were cross-validated against secondary sources including EPA FIFRA registration databases, EFSA residue assessment publications, ANVISA monitoring reports, and customs trade data for 4-aminopyridine and DRC-1339 intermediate flows. Triangulation between demand-side contract volumes and supply-side manufacturing capacity ensures statistical integrity.
Input-output matrices map formulation type, mode of action, and application environment against geographic regulatory clusters across the projection horizon. Segmentation dimensions include product type tier, agricultural versus urban application, and bait versus spray formulation technology. CAGRs derive from regression analysis of historical procurement volumes correlated with planted acreage, bird damage incidence rates, and regulatory approval timelines. Industry-specific forecast inputs incorporate EU Green Deal implementation pace and biological registration pathway acceleration under EFSA frameworks.
The model holds under stable regulatory transition timelines and intact Chinese intermediate export licensing; deviation in trade policy enforcement or EPA endangered species consultation delays would shift volume trajectories. Forecasts reflect documented assumptions regarding biological efficacy validation completion and cooperative procurement bundling persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Insecticide Market
Crop Protection
Global Acephate Market
Crop Protection
Herbicides Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Tebuconazole Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Soil Fumigant Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Miticides Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Fogger Market
Crop Protection
Nematicides Market