
 Europe Crop Protection Chemicals Market | 2026-2036
Europe Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Crop Protection Chemicals Market Foresight
Buyer concentration among large-scale cooperative farming groups across France and Germany is expanding, reshaping procurement volumes and contract structures for crop protection inputs. Bayer AG leverages its integrated seed-chemistry pipeline to secure multi-year supply agreements with these consolidated purchasers. BASF SE anchors its position through advanced formulation R&D facilities in Ludwigshafen. Syngenta Group competes via digital agriculture platforms that bundle chemical applications with predictive analytics services.
Crop protection chemicals comprise synthetic and biological active ingredients formulated to control weeds, insects, fungi, and pests affecting agricultural yields, typically requiring precise application rates measured in grams per hectare to ensure efficacy while minimizing environmental residue. Herbicides sustain the largest revenue share across Europe due to pervasive weed pressure in cereal monocultures, though biological insecticides represent the fastest-expanding category as residue limits tighten under EU sustainability mandates. Foliar application dominates volume consumption, while seed treatment concentrates margin pools through premium pricing of proprietary coating technologies.
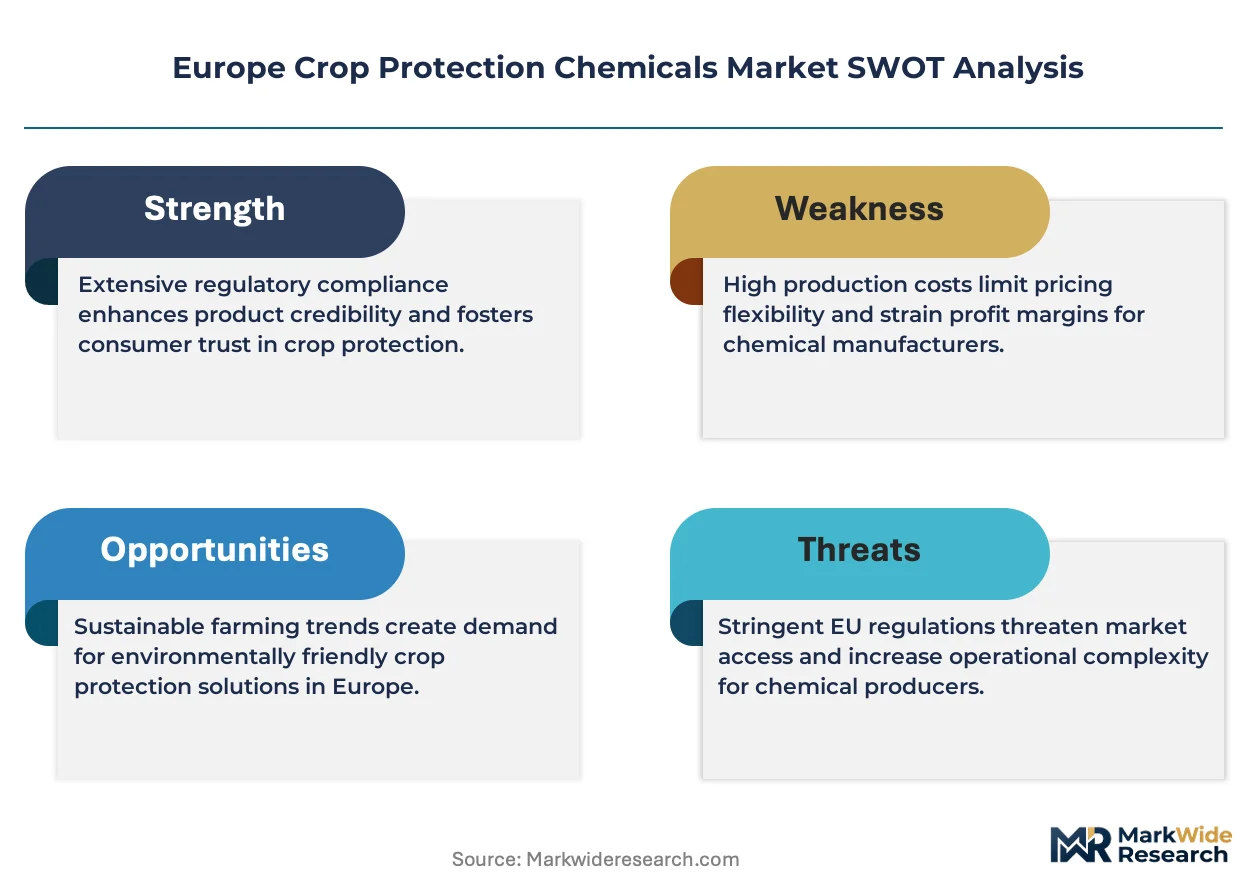
The European Chemicals Agency (ECHA) enforces REACH compliance for active substance registration, while the EU Green Deal's pesticide reduction targets are forcing reformulation investments across the supplier base. Sustainable Use of Pesticides Directive requirements reshape product labels, buffer zones, and operator certification standards. National regulators in France and Germany impose additional groundwater protection restrictions that exceed baseline EU thresholds. Stakeholders must monitor the trajectory of EU-wide hazard-based cut-off criteria and position portfolios for accelerated biological substitution timelines.
Market Dynamics
The EU Green Deal's pesticide reduction targets are compressing the conventional synthetic chemistry pipeline while forcing rapid biological substitution across the supplier base. Farm to Fork mandates are reshaping procurement criteria before 2030 deadlines.
Growth Catalysts
- Biological Formulation Adoption:Specialty growers in Spain and Italy are scaling purchases of bio-based insecticides and fungicides to meet tightening EU residue limits.
- REACH Registration Pathways:Streamlined active substance approvals under ECHA protocols are accelerating market entry for novel microbial biocontrol agents.
- Precision Agriculture Corridors:Variable-rate application technologies in Germany's cereal belt are expanding addressable demand for site-specific crop protection inputs.
Market Restraints
- Active Ingredient Cost Volatility:Petrochemical feedstock fluctuations and energy price spikes in Ludwigshafen and Antwerp manufacturing clusters are squeezing formulation margins.
- Groundwater Protection Restrictions:France's ANSES and Germany's BfR impose buffer zone requirements and application bans that exceed baseline EU thresholds, limiting product utility.
- Biological Efficacy Limitations:Narrow temperature windows and shelf-life constraints for microbial agents restrict their deployment in northern European climatic conditions.
Strategic Opportunities
- Seed Treatment Premiumization:Proprietary coating technologies for cereals and oilseeds command pricing multiples over foliar applications, concentrating margin pools with integrated pipeline owners.
- Digital Agriculture Convergence:Bundling predictive analytics with chemical prescriptions creates recurring revenue streams among France's cooperative farming groups.
- Eastern European Expansion:Poland and Romania's consolidation of smallholder farms into commercial operations is opening underpenetrated volume pools for standardized herbicide formulations.
Industry Challenges
- Operator Certification Complexity:Sustainable Use of Pesticides Directive mandates for spray equipment calibration and drift mitigation training are extending sales cycles and raising compliance costs.
- Reformulation Capex Burden:Hazard-based cut-off criteria under EU Green Deal timelines are forcing multi-year R&D commitments with uncertain registration outcomes.
- Supply Chain Reconfiguration:Biological active ingredient sourcing from fermentation facilities requires cold-chain logistics investments alien to legacy chemical distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Crop Protection Chemicals Market |
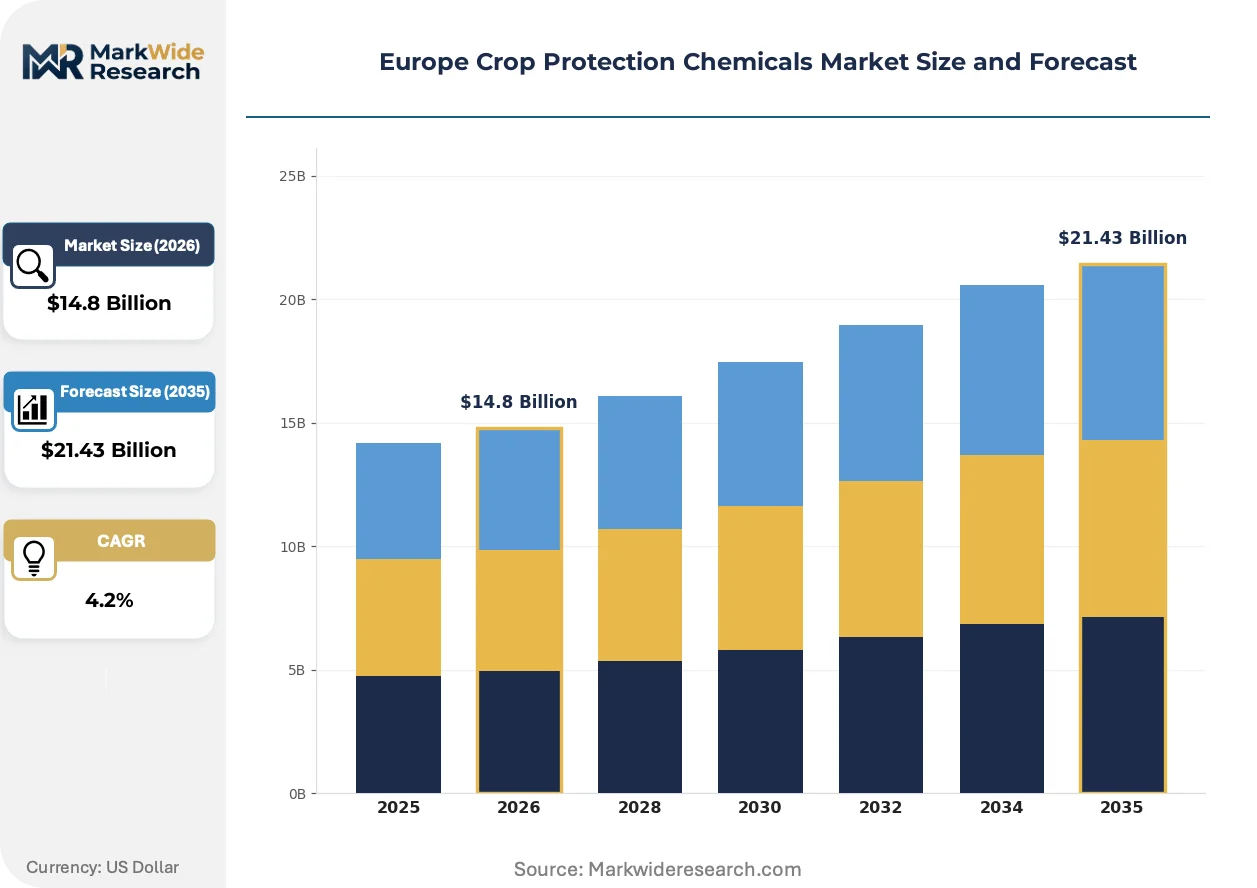
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Formulation Type: Liquid, Granule, Powder, Emulsifiable Concentrate Crop Type: Cereal, Fruits, Vegetables, Oilseeds Application Method: Foliar, Soil Treatment, Seed Treatment, Aerial Application |
| Companies Covered | Bayer AG, BASF SE, Syngenta Group, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm Ltd, ADAMA Agricultural Solutions Ltd., Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Crop Protection Chemicals Market Shifts & Advancements
Biological active ingredients and digital application platforms are displacing conventional chemistries and blanket spraying protocols across European agriculture. The convergence of data-driven agronomy with residue-compliant inputs is redefining competitive advantage.
RNA interference technology is integrating into crop protection portfolios as a targeted pest suppression mechanism. Large-scale cereal operations in France and Germany are piloting RNAi-based biopesticides for lepidopteran control. This molecular approach is integrating with existing integrated pest management frameworks while compressing the market for broad-spectrum neurotoxic insecticides.
ECHA's REACH authorization requirements for endocrine-disrupting substances are forcing active ingredient withdrawals from the European market. The regulatory mechanism is eliminating chemistries with mammalian toxicity profiles from herbicide and fungicide portfolios. Cereal monocultures in northern France are most affected, with growers substituting mechanical weeding and cover cropping for displaced chemical options.
Cooperative farming groups are consolidating procurement decisions across thousands of hectares, displacing individual farm-level purchasing. These aggregators in Germany's precision agriculture corridors are negotiating multi-year supply agreements with volume guarantees and performance clauses. The shift is most visible in Rhineland-Palatinate and Lower Saxony, where machinery rings have evolved into input purchasing consortia with dedicated agronomy staff.
Europe Crop Protection Chemicals Market Segmentation
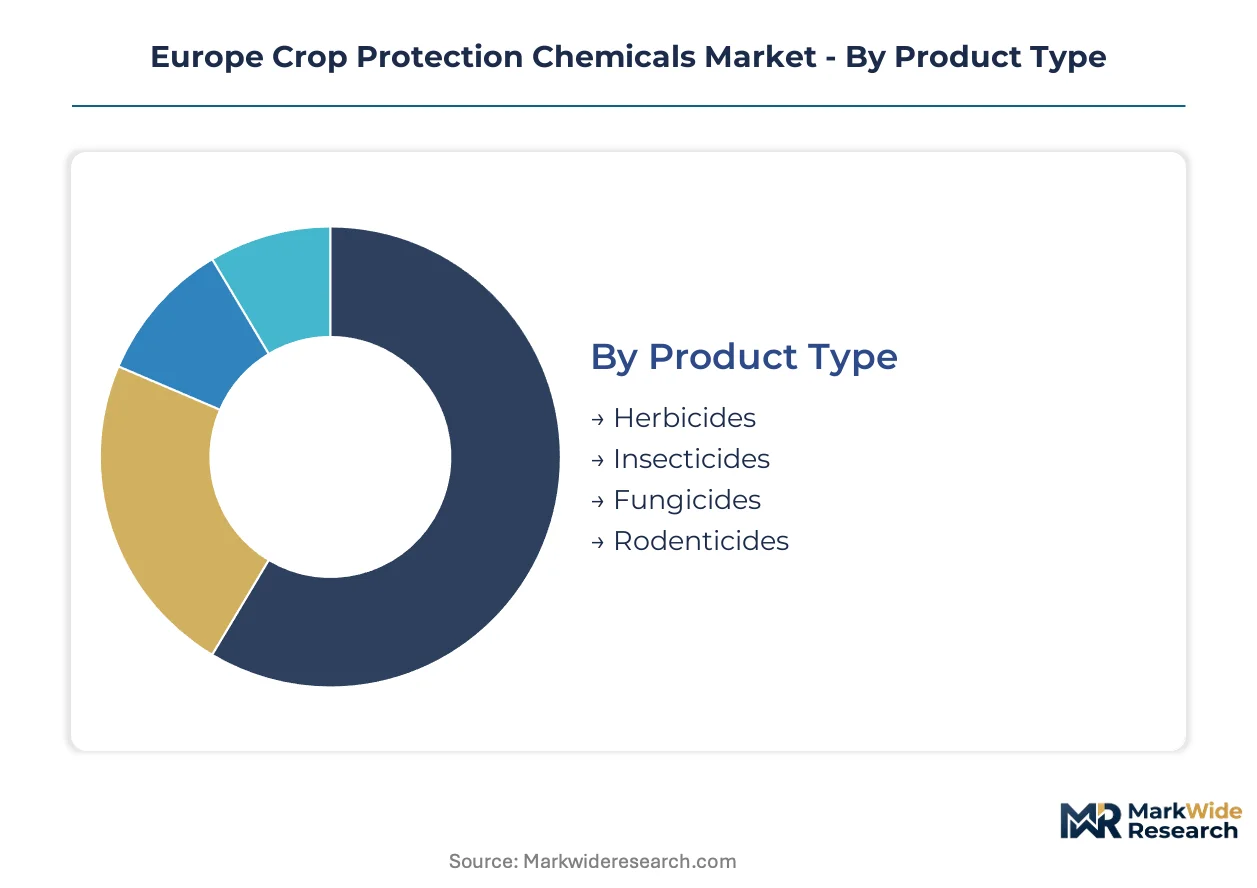
Segmentation in Europe's crop protection chemicals market reveals divergent margin structures across formulation technologies and application methods. Product type splits expose herbicide dominance against biological acceleration, while crop-specific demand tracks the region's agricultural geography from France's cereal belt to Mediterranean specialty production.
Product Type:
Volume concentrates in broad-spectrum chemistries, yet premium pools are migrating toward residue-compliant alternatives under EU Green Deal timelines.
- Herbicides:Synthetic auxins, glyphosate formulations, and ALS inhibitors control weed pressure across northern Europe's cereal monocultures. Demand concentrates in France's wheat-growing regions where blackgrass resistance drives rotation between chemical modes of action.
- Insecticides:Pyrethroids, neonicotinoids, and emerging microbial formulations target lepidopteran and aphid infestations in vegetable production. Spain's Almería greenhouse complexes are scaling biological insecticide purchases to meet supermarket chain residue specifications.
- Fungicides:Azoles, strobilurins, and SDHI combinations protect against Septoria and rust pathogens in humid Atlantic climates.
- Rodenticides:Anticoagulant baits and non-toxic alternatives manage rodent pressure in grain storage and oilseed rape fields.
Today's leader: Herbicides. Tomorrow's challenger: Insecticides.
Formulation Type:
Application efficiency and operator safety are reshaping formulation preferences across European farming operations.
- Liquid:Suspension concentrates and soluble liquids enable precise dosing through modern sprayer equipment. Germany's precision agriculture corridors favor liquid formulations for variable-rate application compatibility.
- Emulsifiable Concentrate:Oil-based carriers improve penetration of systemic actives into waxy leaf surfaces. Mediterranean olive and citrus growers rely on EC formulations for scale insect control under high-temperature conditions.
- Granule:Controlled-release matrices reduce operator exposure and environmental drift in rice paddies and vegetable plots.
- Powder:Wettable powders persist in smallholder markets and seed treatment applications where water access limits liquid alternatives.
Emulsifiable concentrate formulations retain the steepest expansion trajectory in specialty crop segments.
Crop Type:
Commodity scale versus value-per-hectare intensity determines formulation sophistication and pricing power across crop segments.
- Cereal:Wheat, barley, and maize production across France, Germany, and Poland consumes the largest absolute volumes of herbicides and fungicides. Cooperative farming groups in Lower Saxony negotiate multi-year supply agreements for standardized cereal protection programs.
- Vegetables:Protected and open-field vegetable production in Italy's Po Valley and Spain's Murcia region demands residue-compliant biological inputs. Integrated pest management mandates from German retail chains are accelerating substitution of conventional chemistries in tomato and pepper cultivation.
- Fruits:Apple, pear, and stone fruit orchards in northern Italy and southern France require precision-timed fungicide applications against scab and brown rot.
- Oilseeds:Rapeseed and sunflower production in Romania and Hungary depends on herbicide-tolerant varieties and desiccant applications at harvest.
Vegetable crop protection commands the fastest-growing premium tier.
Application Method:
Equipment investment cycles and labor constraints are redistributing volume across application modalities.
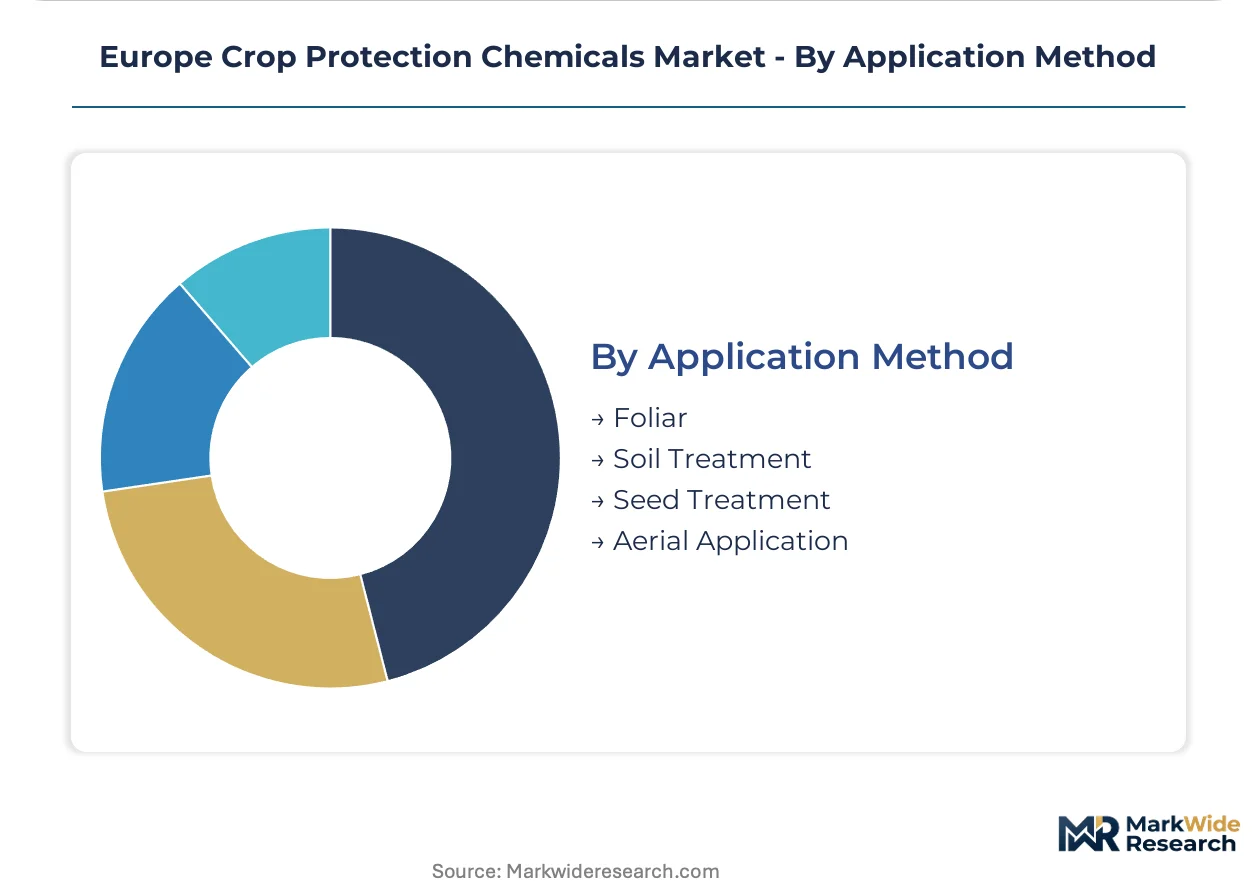
- Foliar:Direct leaf and stem spraying remains the dominant volume channel for herbicide and fungicide delivery. France's cereal belt deploys self-propelled sprayers with GPS section control to minimize overlap and buffer zone violations.
- Seed Treatment:Proprietary coating technologies for cereals and oilseeds concentrate margin pools through premium pricing. Rhineland-Palatinate machinery rings are consolidating procurement of treated seed for member farms.
- Soil Treatment:Pre-plant incorporated and at-planting applications of nematicides and residual herbicides address soil-borne pest pressure.
- Aerial Application:Drone and manned aircraft spraying expands in eastern European large-scale farming and inaccessible terrain.
Seed treatment technology is gaining share fastest in integrated pipeline offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands larger absolute volumes of crop protection chemicals than Italy, yet Mediterranean specialty growers in Spain and Italy are outpacing northern cereal producers in biological formulation adoption rates.
France
France's cereal belt in Hauts-de-France and Grand Est sustains the region's largest herbicide and fungicide consumption volumes. ANSES imposes groundwater protection restrictions that exceed baseline EU thresholds, banning atrazine-class chemistries in vulnerable aquifer zones. Cooperative farming groups in Picardy negotiate multi-year supply agreements with integrated pipeline owners for standardized wheat protection programs.
Germany
Germany's precision agriculture corridors in Lower Saxony and Rhineland-Palatinate deploy variable-rate application technologies that expand demand for site-specific inputs. BfR buffer zone requirements and drift mitigation mandates reshape product labels and operator certification standards. Machinery rings in these regions have evolved into input purchasing consortia with dedicated agronomy staff negotiating volume guarantees.
Spain
Spain's Almería and Murcia greenhouse complexes scale biological insecticide purchases to meet German retail chain residue specifications. The country's national agricultural regulator enforces EU Green Deal pesticide reduction targets ahead of 2030 deadlines through accelerated substitution timelines. Specialty vegetable producers in southeastern coastal provinces pilot RNA interference technologies for lepidopteran control.
Italy
Italy's Po Valley vegetable production and northern orchard regions drive demand for residue-compliant biological inputs. Integrated pest management mandates from supermarket chains accelerate substitution of conventional chemistries in tomato, pepper, and stone fruit cultivation. Precision application equipment manufacturers in Emilia-Romagna collaborate with formulation specialists on site-specific delivery systems.
Poland
Poland's consolidation of smallholder farms into commercial operations opens underpenetrated volume pools for standardized herbicide formulations. The country's national plant protection office aligns with REACH registration pathways while adapting EU Sustainable Use of Pesticides Directive requirements to local farming structures. Large-scale cereal operations in Greater Poland and Silesia deploy self-propelled sprayers with GPS section control.
Europe Crop Protection Chemicals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's crop protection chemicals landscape, creating a tiered market structure where scale advantages clash with agility in regulatory compliance. The supplier base concentrates around integrated seed-chemistry pipelines and advanced formulation capabilities, with digital agriculture platforms emerging as a third competitive vector. Strategic archetypes include conglomerate integrators, biological specialists, and precision application technology bundlers. Multi-year supply agreements with cooperative farming groups and reformulation investments for EU Green Deal compliance represent the dominant competitive moves reshaping market positioning.
Within the conglomerate integrator tier, Bayer AG and BASF SE exemplify European-anchored competitors leveraging captive R&D infrastructure, while Syngenta Group occupies a position bridging chemical and digital agriculture convergence. These three entities represent contrasting geographic origins and structural approaches to the region's tightening regulatory environment.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm Ltd |
| ADAMA Agricultural Solutions Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Cooperative farming group consolidation across France and Germany is forcing suppliers toward multi-year contract structures with volume guarantees and performance clauses, compressing spot-market premiums and redirecting margin capture toward seed treatment technologies and digital service bundling.
Pricing Analysis
Capacity additions in Ludwigshafen and Antwerp manufacturing clusters are reshaping price floors for synthetic formulation tiers. Contract-based long-term offtake dominates procurement between cooperative buyers and integrated pipeline owners, with price differentiation anchored in REACH registration status and precision agriculture compatibility. Cost compression in commodity herbicide segments is intensifying because petrochemical feedstock volatility squeezes formulation margins. Smallholder operations in Poland and Romania exhibit highest price sensitivity, while German machinery ring consortia accept premium positioning for site-specific application bundles.
Supply Chain Analysis
Skilled formulation chemist shortages in Germany's Rhineland-Palatinate and technical operator gaps in Spain's Murcia processing facilities are constraining batch consistency for biological active ingredient production. Manufacturing gravity centers on Germany, Belgium, and France for synthetic chemistries, with Italy and Spain hosting specialty fermentation capacity for microbial biocontrol agents. Raw material sourcing draws from Chinese petrochemical intermediates, Indian technical grade supplies, and regional biofermentation feedstocks. Single-source vulnerability concentrates in cold-chain logistics for temperature-sensitive biologicals. Distribution runs through cooperative purchasing consortia and agricultural merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's crop protection chemicals market functions as a geographic-arbitrage play where regulatory stringency differentials between northern EU member states and eastern European accession countries create divergent compliance cost structures and timing advantages for portfolio repositioning.
For Market Incumbents: Cement multi-year supply agreements with France's cereal belt cooperatives before EU Green Deal hazard-based cut-off criteria eliminate additional synthetic active ingredients. Prioritize backward integration into biological fermentation capacity to secure cold-chain distribution control against emerging pure-play microbial specialists. Channel control through machinery ring partnerships in Lower Saxony defends position against digital agriculture platform bundlers. For New Entrants and Emerging Players: Agricultural merchant networks in Poland and Romania represent the most penetrable channel infrastructure for standardized herbicide formulations targeting consolidated smallholder operations. White-space concentration sits in RNA interference biocontrol pilot programs for Spanish greenhouse vegetable producers seeking residue-compliant alternatives. A licensing partnership with precision application equipment manufacturers accelerates market entry without captive distribution investment. For Investors and Strategic Acquirers: Asymmetric upside sits with biological formulation specialists possessing ECHA-registered microbial portfolios and established cold-chain logistics. Long-term viability over the projection horizon favors acquisition targets with dual synthetic-biological pipeline capabilities and cooperative buyer relationships in Germany's precision agriculture corridors. Monitor EU-wide groundwater protection restriction announcements as the inflection signal for accelerated biological substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Fermentation Capacity Expansion | Captures margin pools as ECHA registrations accelerate microbial biocontrol market entry. |
| Precision Agriculture Platform Integration | Bundles predictive analytics with chemical prescriptions for Germany's machinery ring consortia. |
| REACH Registration Pathway Investment | Secures active substance approvals ahead of EU Green Deal hazard-based cut-off implementation. |
| Cooperative Supply Agreement Negotiation | Locks volume guarantees with France's cereal belt farming groups amid buyer consolidation. |
| Seed Treatment Technology Acquisition | Concentrates margin capture through proprietary coating technologies for cereals and oilseeds. |
Research Methodology
Multiple input streams — formulation R&D directors, cooperative procurement managers, agricultural merchant network heads, and ECHA regulatory affairs specialists — were reconciled with secondary validation from customs trade databases, Cefic sector reports, SEC 10-K filings, and national plant protection office registrations. Bottom-up triangulation across product-level volume estimates and top-down cross-checks against regional agricultural production statistics anchored the analytical framework.
Historical consumption patterns were cross-referenced against expert panel assessments to derive expansion trajectories across the projection horizon. Segmentation dimensions modeled include product type, formulation technology, crop category, application method, and regional regulatory cluster intensity. CAGRs were computed from normalized baseline values through iterative convergence testing. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and cooperative farming group consolidation rates.
Revisions become necessary when EU-wide hazard-based cut-off criteria accelerate, groundwater protection restrictions tighten beyond baseline thresholds, or biological efficacy breakthroughs displace synthetic chemistry demand faster than modeled. Forecasts reflect documented assumptions regarding regulatory implementation pacing and buyer consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Pest Control Products Market
Crop Protection
Larvicides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Fosthiazate Market
Crop Protection
Europe Fungicide Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Crop Bactericides Market
Crop Protection
Iprodione Market
Crop Protection
Pest Control Market
Crop Protection
Soil Fumigant Market
Crop Protection
IPM Pheromones Market