
 Low-Odor, Enclosed-Greenhouse Foliar Protection Market | 2026-2036
Low-Odor, Enclosed-Greenhouse Foliar Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Odor, Enclosed-Greenhouse Foliar Protection Market Insights
Dutch biological input suppliers is rebalancing capacity toward low-volatility formulations after residue limit tightening across Northern European markets. BASF leverages integrated microbial screening platforms to shorten biological active discovery cycles. Bayer anchors its position through captive fermentation assets for Bacillus-based products. Syngenta competes via precision-delivery partnerships with automation integrators.
Low-odor, enclosed-greenhouse foliar protection denotes crop protection inputs engineered for minimal volatile organic compound release within controlled-environment agriculture, typically incorporating aqueous suspension concentrates or microencapsulated actives below 50 ppm odor threshold to prevent phytotoxicity and worker exposure in sealed structures. These formulations serve commercial growers requiring uninterrupted harvest cycles without ventilation downtime. Biopesticides command widening margin pools as residue-sensitive export channels in Northern Europe and North America tighten maximum residue limits. Microencapsulation technology attracts formulation investment due to its compatibility with electrostatic application systems and extended release profiles in high-humidity greenhouse environments. Wettable powders face gradual displacement where automated mixing stations reduce dust exposure concerns.
EPA's Worker Protection Standard and EU REACH registration requirements shape active ingredient eligibility for enclosed-space applications, with both frameworks tightening dermal exposure benchmarks. EFSA's ongoing reassessment of neonicotinoid alternatives accelerates biological product registration queues. OSHA's permissible exposure limits for greenhouse operators reinforce demand for sub-odor-threshold formulations. Stakeholders must weigh biological pipeline maturation against synthetic active re-registration timelines when allocating R&D budgets across formulation platforms.
Market Dynamics
Microencapsulation chemistry is compressing formulation timelines while EU Green Deal residue mandates force active ingredient substitution across Northern European greenhouse clusters.
Growth Catalysts
- EU REACH dermal exposure benchmarks:Tightening permissible limits for enclosed-space operators accelerates sub-odor-threshold formulation registration queues.
- Spain's Almería greenhouse cluster:Concentrated protected-crop acreage generates concentrated demand for aqueous suspension concentrates compatible with electrostatic systems.
- Microencapsulation compatibility:Extended-release profiles in high-humidity environments enable uninterrupted harvest cycles without ventilation downtime.
Market Restraints
- Biological active fermentation capacity:Captive production assets for Bacillus-based inputs concentrate supply risk with limited third-party tolling alternatives.
- EPA Worker Protection Standard re-registration:Synthetic active ingredient eligibility reviews create multi-year pipeline uncertainty for legacy chemistries.
- Wettable powder displacement friction:Automated mixing station capex requirements slow conversion in mid-scale greenhouse operations.
Strategic Opportunities
- Netherlands specialty propagation segment:Ornamental and vegetable transplant producers seek residue-free export certification for North American channels.
- EFSA neonicotinoid alternative acceleration:Expedited biological product review pathways shorten time-to-market for microbial screening platform outputs.
- Precision-delivery automation convergence:Electrostatic application system integration with greenhouse climate controls creates bundled input-hardware value pools.
Industry Challenges
- Formulation chemist talent scarcity:Cross-disciplinary expertise spanning microencapsulation chemistry and greenhouse agronomy concentrates in Dutch and German research clusters.
- OSHA permissible exposure limit compliance documentation:Sub-odor-threshold verification protocols require specialized analytical laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Odor, Enclosed-Greenhouse Foliar Protection Market |
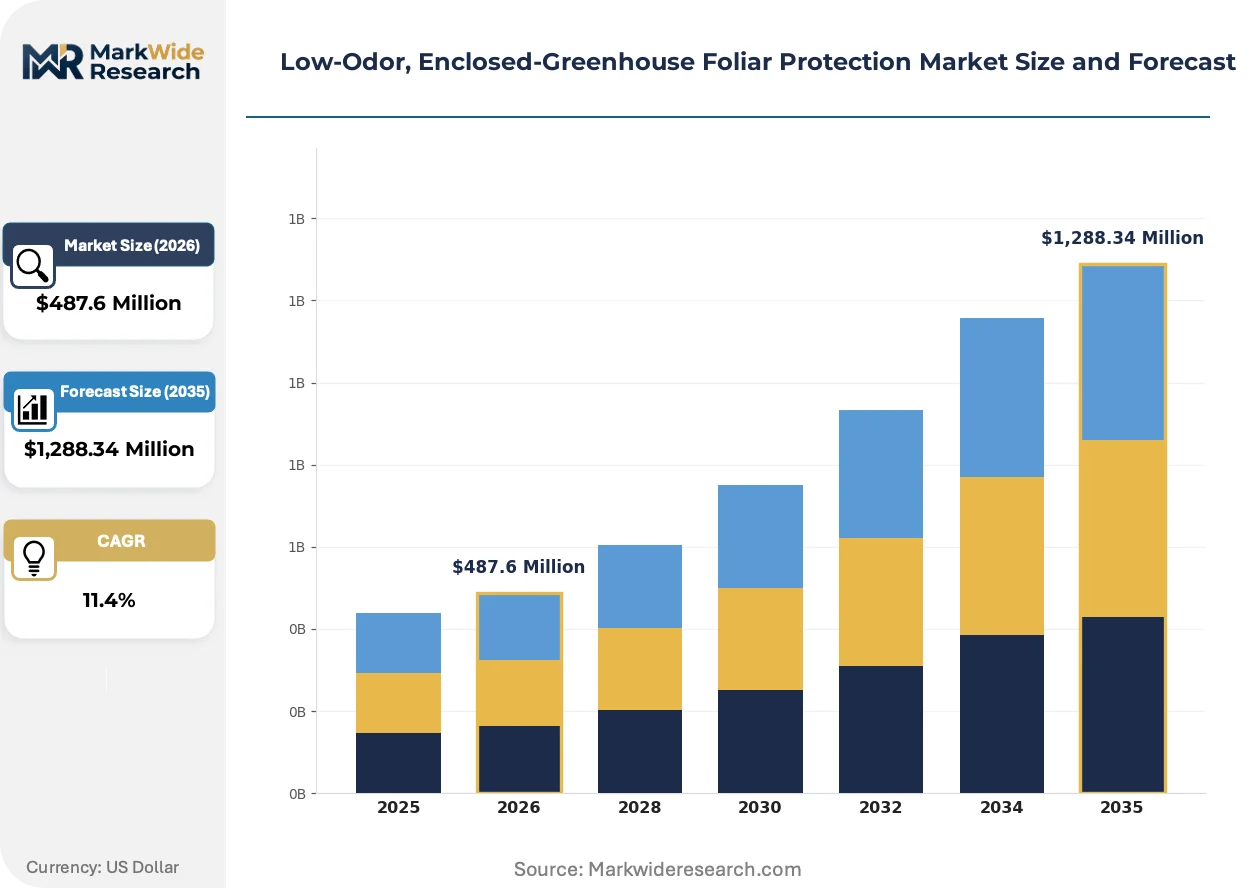
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Miticides, Biopesticides Formulation Technology: Emulsifiable Concentrates, Suspension Concentrates, Wettable Powders, Granules, Microencapsulation Application Method: Spray, Fogging, Drip Irrigation, Misting, Electrostatic Application End User: Commercial Growers, Specialty Plant Producers, Research Facilities, Automation Integrators |
| Companies Covered | BASF, Bayer, Syngenta, Corteva Agriscience, Koppert Biological Systems, Biobest Group, Valent BioSciences, Certis Biologicals, BioWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Odor, Enclosed-Greenhouse Foliar Protection Market Trends and Innovations
Active ingredient delivery mechanisms are compressing application frequencies while regulatory residue thresholds restructure competitive entry barriers across formulation platforms.
Microencapsulated aqueous suspension concentrates enable controlled release of biological actives in saturated humidity conditions. Dutch ornamental propagators and Spanish vegetable growers are adopting these formulations at accelerated registration cycles. This chemistry is rewriting the trade-off between worker exposure compliance and phytotoxicity risk in sealed structures.
EU Green Deal chemical residue reduction mandates tighten maximum allowable levels for export-bound produce. EFSA's parallel neonicotinoid reassessment redirects regulatory review capacity toward biological alternatives. Northern European greenhouse operators face compressed compliance timelines for active ingredient substitutions.
Certification-driven procurement now dominates residue-sensitive export channels. Third-party residue testing documentation is displacing traditional supplier quality assurances in buyer selection criteria. Netherlands-based specialty crop exporters exhibit the strictest certification requirements for North American market access.
Low-Odor, Enclosed-Greenhouse Foliar Protection Market Segmentation
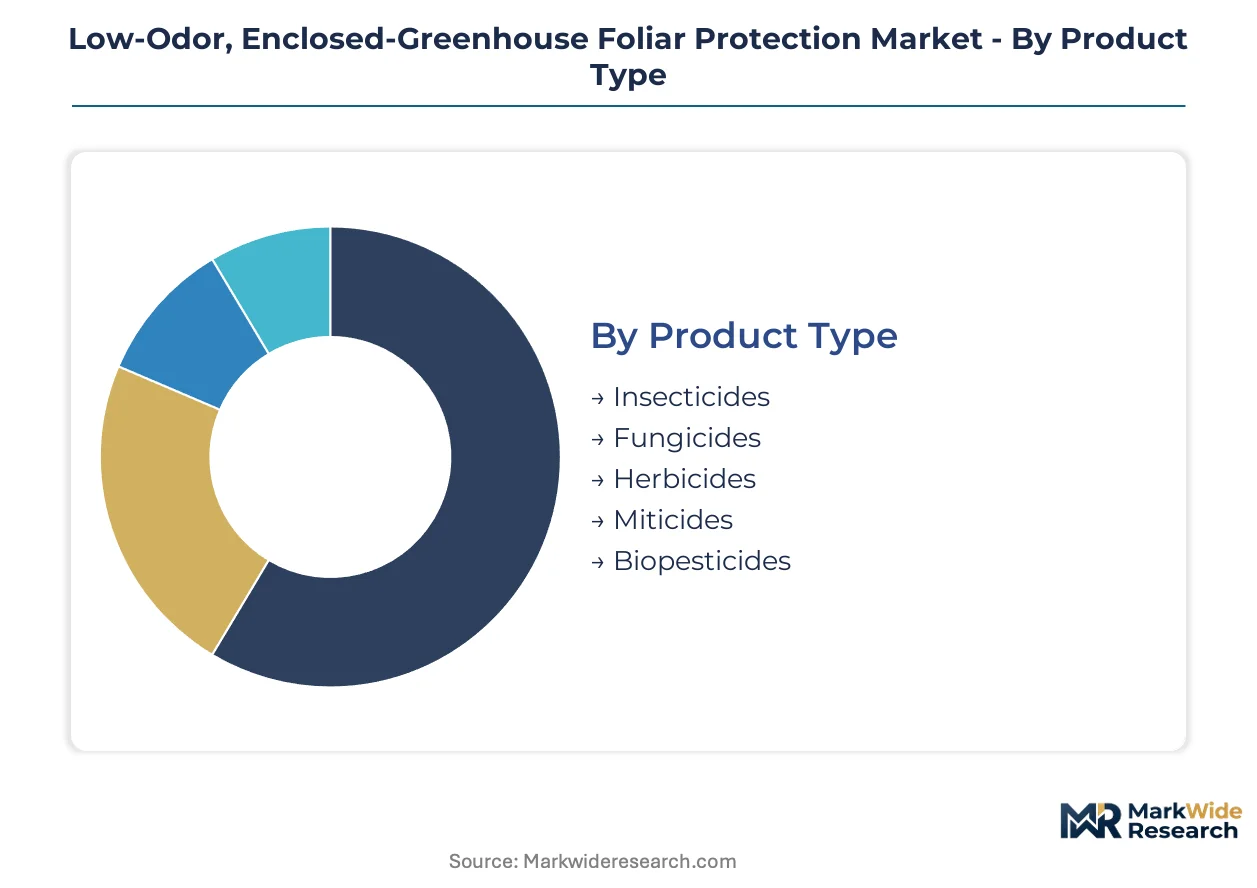
Segmentation in low-odor, enclosed-greenhouse foliar protection reveals distinct capital requirements and margin structures across formulation platforms. Technology choices here determine compliance pathways for residue-sensitive export channels and worker exposure mandates.
Product Type:
Capital intensity varies sharply across product categories, with biological active fermentation requiring dedicated bioreactor infrastructure while synthetic chemistries demand reformulation investment to meet sub-odor thresholds.
- Insecticides:Aqueous suspension concentrates dominate this segment, with microencapsulated pyrethroids and neonicotinoid alternatives capturing demand from Netherlands ornamental exporters facing EU Green Deal residue limits. Almería vegetable growers prioritize these formulations for uninterrupted harvest cycles.
- Fungicides:Biofungicide formulations incorporating Bacillus subtilis and Trichoderma species command premium positioning in specialty propagation segments. Dutch biological input suppliers are rebalancing capacity toward these actives after Northern European residue tightening.
- Herbicides:Selective post-emergent chemistries with reduced volatility profiles serve automated greenhouse operations requiring minimal ventilation downtime.
- Miticides:Oil-based formulations face displacement where electrostatic application systems demand aqueous compatibility.
- Biopesticides:Microbial and biochemical actives attract formulation investment from integrated microbial screening platforms.
Insecticides absorb the bulk of installed capacity; biopesticides are expanding most quickly amid EFSA neonicotinoid alternative acceleration.
Formulation Technology:
Application method compatibility and climate control integration determine technology selection, with automated mixing stations and electrostatic systems favoring specific physical forms.
- Emulsifiable Concentrates:Solvent-heavy legacy formulations face regulatory pressure under EPA Worker Protection Standard dermal exposure benchmarks.
- Suspension Concentrates:Aqueous carrier systems enable sub-50 ppm odor thresholds essential for sealed-structure worker compliance. Spain's Almería cluster concentrates demand for these formulations compatible with electrostatic systems.
- Wettable Powders:Dust exposure concerns drive gradual displacement where automated mixing station capex is justified.
- Granules:Soil-incorporated delivery avoids foliar phytotoxicity in high-value ornamental propagation.
- Microencapsulation:Extended-release profiles in saturated humidity environments compress application frequencies while satisfying OSHA permissible exposure limits. Dutch and German research clusters concentrate formulation chemist expertise for this technology.
Microencapsulation is gaining share fastest as precision-delivery automation converges with climate control systems; emulsifiable concentrates face steepest contraction under residue mandate pressure.
Application Method:
Automation integration and labor exposure reduction shape equipment investment patterns across greenhouse operations of varying scale.
- Spray:Conventional hydraulic systems retain installed base in mid-scale operations with manual labor availability.
- Fogging:Thermal and cold fogging systems penetrate dense crop canopies in high-density tomato and pepper production.
- Drip Irrigation:Root-zone delivery avoids foliar residue concerns entirely for systemic chemistries.
- Misting:High-pressure systems achieve uniform coverage in propagation facilities with delicate seedling stages.
- Electrostatic Application:Charged droplet technology reduces volume rates and drift potential. Integration with greenhouse climate controls creates bundled input-hardware value pools for commercial growers.
Spray retains the largest installed equipment base; electrostatic application is climbing the fastest as automation integrators partner with input suppliers.
End User:
Certification requirements and export market access create tiered demand structures, with residue documentation needs concentrating in specific customer categories.
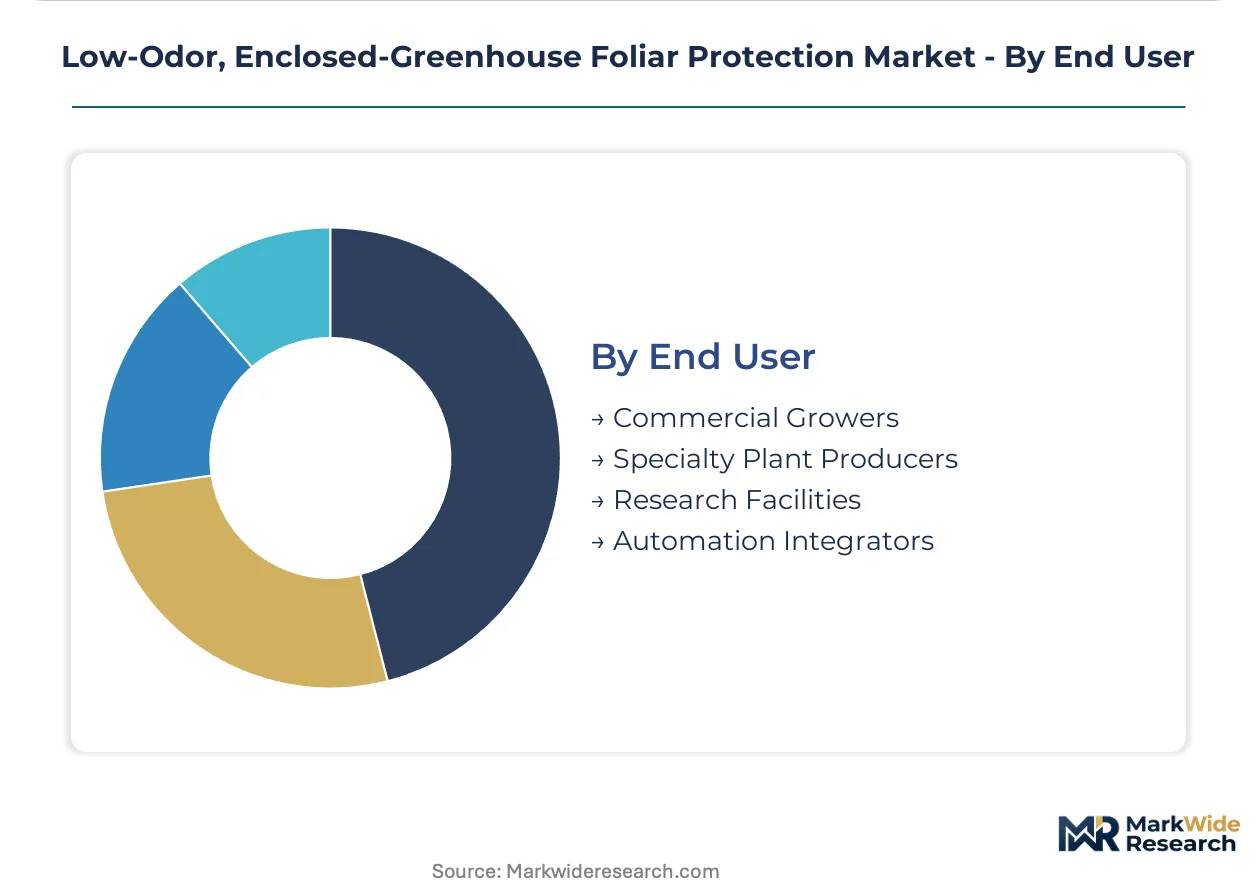
- Commercial Growers:Large-scale vegetable producers in Spain and the Netherlands drive volume demand for aqueous suspension concentrates compatible with uninterrupted harvest schedules.
- Specialty Plant Producers:Ornamental and vegetable transplant propagators in the Netherlands seek residue-free export certification for North American channels. Third-party residue testing documentation dominates their procurement criteria.
- Research Facilities:Controlled-environment agriculture R&D centers pilot novel microbial screening platform outputs.
- Automation Integrators:Precision-delivery system providers bundle foliar protection inputs with climate control hardware.
Commercial growers absorb the bulk of formulation volume; specialty plant producers are expanding most quickly as certification-driven procurement penetrates export-bound segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based specialty propagation operations anchor regional formulation demand as EU Green Deal residue mandates cascade through Northern European export channels.
Netherlands
Ornamental and vegetable transplant producers drive concentrated demand for residue-free certification targeting North American export channels. EFSA's neonicotinoid reassessment redirects regulatory review capacity toward biological alternatives. Westland and Aalsmeer greenhouse clusters accelerate microencapsulated aqueous suspension concentrate adoption to maintain uninterrupted harvest schedules.
Spain
Almería's protected vegetable acreage generates volume demand for electrostatic-compatible formulations serving tomato and pepper export operations. EU REACH dermal exposure benchmarks tighten permissible limits for enclosed-space operators. Andalusian commercial growers prioritize sub-odor-threshold chemistries to eliminate ventilation downtime during harvest cycles.
Germany
Baden-Württemberg and Bavaria research clusters concentrate formulation chemist expertise spanning microencapsulation chemistry and greenhouse agronomy. Germany's Federal Office of Consumer Protection and Food Safety enforces strict residue documentation for export-bound produce. Stuttgart-area automation integrators bundle precision-delivery hardware with climate control systems.
United States
California and Florida greenhouse vegetable producers face EPA Worker Protection Standard re-registration uncertainty for legacy synthetic actives. OSHA permissible exposure limits for greenhouse operators reinforce demand for sub-odor-threshold formulations. Salinas Valley and Immokalee clusters pilot biological active integration amid residue-sensitive retail procurement requirements.
China
Shandong and Jiangsu protected agriculture provinces expand greenhouse acreage for domestic vegetable supply and export-oriented ornamental propagation. The Ministry of Ecology and Environment tightens volatile organic compound discharge standards for enclosed agricultural facilities. Weifang and Shouguang greenhouse technology hubs drive electrostatic application system localization.
Low-Odor, Enclosed-Greenhouse Foliar Protection Market Competitive Landscape
Global majors compete with regional champions across formulation technology and biological active sourcing. Market structure tilts toward consolidated leadership among integrated agrochemical conglomerates with captive fermentation assets, while specialized biological input suppliers occupy niche certification-driven segments. Three archetypes dominate: multinational conglomerates with microbial screening platforms, regional biological specialists with propagation segment focus, and automation-integrated solution providers. Competitive moves concentrate on precision-delivery partnerships and captive capacity expansion for Bacillus-based actives.
Within the multinational conglomerate tier, BASF SE and Bayer AG exemplify integrated microbial screening and fermentation asset strategies. Koppert Biological Systems B.V. occupies a specialist position among Netherlands-based biological input suppliers serving residue-sensitive export channels. These three anchors represent divergent approaches to biological pipeline maturation against synthetic active re-registration timelines.
| Leading Market Players |
|---|
| BASF |
| Bayer |
| Syngenta |
| Corteva Agriscience |
| Koppert Biological Systems |
| Biobest Group |
| Valent BioSciences |
| Certis Biologicals |
| BioWorks |
| Others |
Pricing and Supply Chain Analysis
Propylene glycol price benchmarks cascade through aqueous suspension concentrate production into three-tier pricing structures across premium, standard, and economy levels. Dutch formulation houses pass through feedstock volatility to Almería commercial growers while Netherlands specialty propagators absorb certification premiums for North American export channels.
Pricing Analysis
Service bundling separates residue-testing documentation from base formulation supply, with third-party certification packages commanding premium positioning. Pricing stratifies across premium, standard, and economy tiers based on microencapsulation complexity and EU REACH registration status. Cost compression in standard-tier aqueous concentrates is intensifying due to Spanish volume demand consolidation. Mid-scale greenhouse operators in Almería exhibit highest price sensitivity; Netherlands ornamental exporters show lowest sensitivity amid certification-driven procurement mandates.
Supply Chain Analysis
Qualification gating through EFSA biopesticide registration and EPA Worker Protection Standard compliance concentrates active ingredient supply among Netherlands, Germany, and United States fermentation asset holders. Formulation chemistry draws from petrochemical-derived suspension carriers, Bacillus subtilis culture media, and electrostatic application-compatible adjuvants. Single-source vulnerability concentrates in captive bioreactor capacity for microbial actives. Distribution runs through greenhouse technology integrators bundling inputs with climate control hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where biological active fermentation capacity bottlenecks prop pricing power among incumbent asset holders.
For Market Incumbents: Cement market position through captive fermentation expansion in Baden-Württemberg research clusters and precision-delivery automation partnerships with Spanish greenhouse integrators. EFSA neonicotinoid alternative acceleration threatens legacy synthetic portfolios; vertical integration into Bacillus-based active production is the defensive priority. For New Entrants and Emerging Players: Capture white-space in mid-scale Almería operations underserved by automated mixing station requirements and in Netherlands specialty propagation segments demanding rapid residue-testing turnaround. A certification-fast-track go-to-market angle penetrates export-bound ornamental channels fastest. For Investors and Strategic Acquirers: Distressed-cycle entries favor Netherlands-based biological input specialists with EFSA registration pipelines and German microencapsulation chemistry boutiques during synthetic active re-registration uncertainty. Five-to-ten year viability hinges on biological pipeline maturation velocity; watch EFSA review queue length as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Backward integration into Bacillus-based active production secures supply against third-party tolling scarcity. |
| Precision-Delivery Automation Partnership | Electrostatic system bundling with Spanish greenhouse integrators creates hardware-locked input demand. |
| EFSA Fast-Track Registration Investment | Expedited biological product review pathways compress time-to-market for microbial screening outputs. |
| Third-Party Certification Documentation Service | Residue-testing bundling addresses Netherlands specialty propagator procurement criteria for North American channels. |
| Microencapsulation R&D Cluster Expansion | Dutch and German formulation chemist concentration supports extended-release profile development. |
Research Methodology
Document review covered EPA Worker Protection Standard filings, EFSA biopesticide registration databases, EU REACH substance dossiers, and greenhouse operator trade association publications, complemented by interviews with formulation chemists at Dutch biological input suppliers, procurement leads at Almería commercial growing cooperatives, regulatory affairs directors at multinational agrochemical conglomerates, and automation integrators in Stuttgart-area technology clusters. Secondary validation drew from customs trade data, SEC 10-K agriculture segment disclosures, and controlled-environment agriculture equipment shipment records. Bottom-up volume modeling triangulated against top-down value estimates.
Segment-level outputs across the analysis window reflect discrete modeling of formulation technology, application method, and end-user category dimensions. CAGRs derived from regression against historical adoption curves for microencapsulated chemistries and biological active penetration rates. Industry-specific inputs incorporated EFSA review queue velocity assumptions and electrostatic application system installation forecasts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA neonicotinoid alternative approval timelines and biological active fermentation capacity expansion decisions. Forecasts reflect documented assumptions on regulatory review capacity and greenhouse automation adoption curves. A model refresh is warranted upon material change in EU Green Deal residue mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Fumigation Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Pest Control Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
South America Nematicides Market
Crop Protection
Azoxystrobin Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Fosthiazate Market