
 Herbicides Market | 2026-2036
Herbicides Market Size, Share, and Industry Trends Forecast 2026-2036
Herbicides Market Intelligence
Glyphosate resistance in key weed species is pivoting product economics toward glufosinate-ammonium and dicamba-based alternatives. Bayer AG leverages its seed-trait pipeline to anchor bundled herbicide offerings. Syngenta Group competes through differentiated formulation technologies that extend residual activity. BASF SE specializes in precision application systems that reduce per-hectare chemical load.
Herbicides are chemical agents formulated to inhibit weed growth through interference with photosynthesis, amino-acid synthesis, or cell division, typically applied at rates measured in grams of active ingredient per hectare. Their primary commercial purpose is to protect crop yield potential by eliminating vegetative competition for water, nutrients, and light. Selective herbicides dominate cereal crop applications where crop safety margins determine product choice, while non-selective formulations command premium positioning in pre-plant burndown and industrial vegetation management. Liquid formulations lead volume sales due to ease of tank-mixing and spray application compatibility, though microencapsulated variants are gaining share where extended release reduces leaching risk.
The EPA regulates herbicide tolerance limits through residue chemistry studies and ecological risk assessments, while the EU Green Deal and REACH framework restrict certain active ingredients based on endocrine-disruption and biodiversity criteria. India's Central Insecticides Board mandates registration trials that shape which molecules enter the world's second-largest agrarian economy. Brazil's national health surveillance agency, ANVISA, enforces maximum residue limits that directly determine export eligibility for soybean and corn destined for European processors. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistries retain market access.
Market Dynamics
Glyphosate resistance across Palmer amaranth and waterhemp populations is forcing commercial growers toward alternative chemistries and stacked-trait seed systems, compressing the effective lifecycle of established active ingredients.
Growth Catalysts
- EU Green Deal residue tightening:The European Commission's Farm to Fork strategy accelerates bio-based formulation approvals, creating first-mover advantages for manufacturers with microbial herbicide pipelines.
- Brazilian post-emergent expansion:Commercial soybean operations in Mato Grosso and Goiás are adopting glufosinate-ammonium programs at scale, driving volume demand for non-glyphosate chemistry.
- Drone-based spot-spraying:Computer-vision systems mounted on agricultural UAVs enable sub-hectare application precision, reducing active ingredient load while maintaining weed control efficacy.
Market Restraints
- Chinese intermediate concentration:Synthesis of key AI precursors clusters in Jiangsu and Shandong provinces, exposing formulation supply to single-point disruption risks from environmental compliance crackdowns.
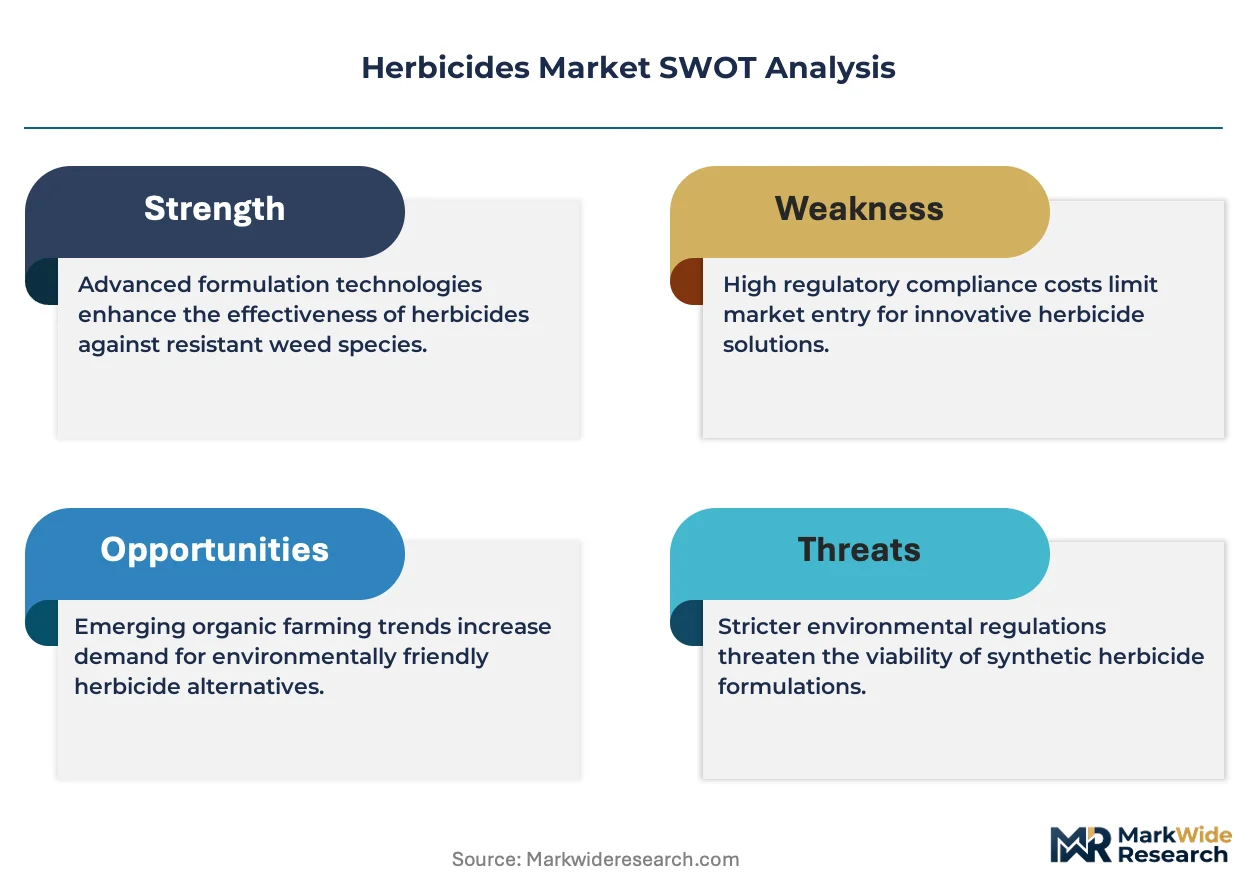
- EU REACH substance evaluation:Endocrine-disruption screening under ECHA's 2023-2025 work program threatens withdrawal authorization for multiple triazine and phenoxy herbicides.
- Biological substitute maturation:Bioherbicides derived from Phoma macrostoma and Sclerotinia minor demonstrate 60-70% efficacy in turf applications, capping premium pricing for chemical alternatives in amenity sectors.
Strategic Opportunities
- India cereal crop penetration:The Central Insecticides Board's streamlined registration pathway for low-toxicity molecules enables faster entry into wheat and rice applications across Punjab and Haryana.
- Precision application bundling:Integration of soil-moisture sensors with variable-rate spray systems creates service-revenue streams beyond product sales for equipment-chemistry combinations.
- Carbon credit alignment:Reduced-tillage programs enabled by effective pre-plant burndown qualify for verified carbon offset protocols in North American grain markets.
Industry Challenges
- Resistance management stewardship:Mandatory herbicide-resistance monitoring protocols require field-staff expansion and grower-education investments that strain mid-tier manufacturer resources.
- Multi-jurisdiction dossier maintenance:Divergent data requirements between EPA 40 CFR Part 158, EU Regulation 1107/2009, and Brazil's Lei 7.802/1989 force redundant toxicology study commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbicides Market |
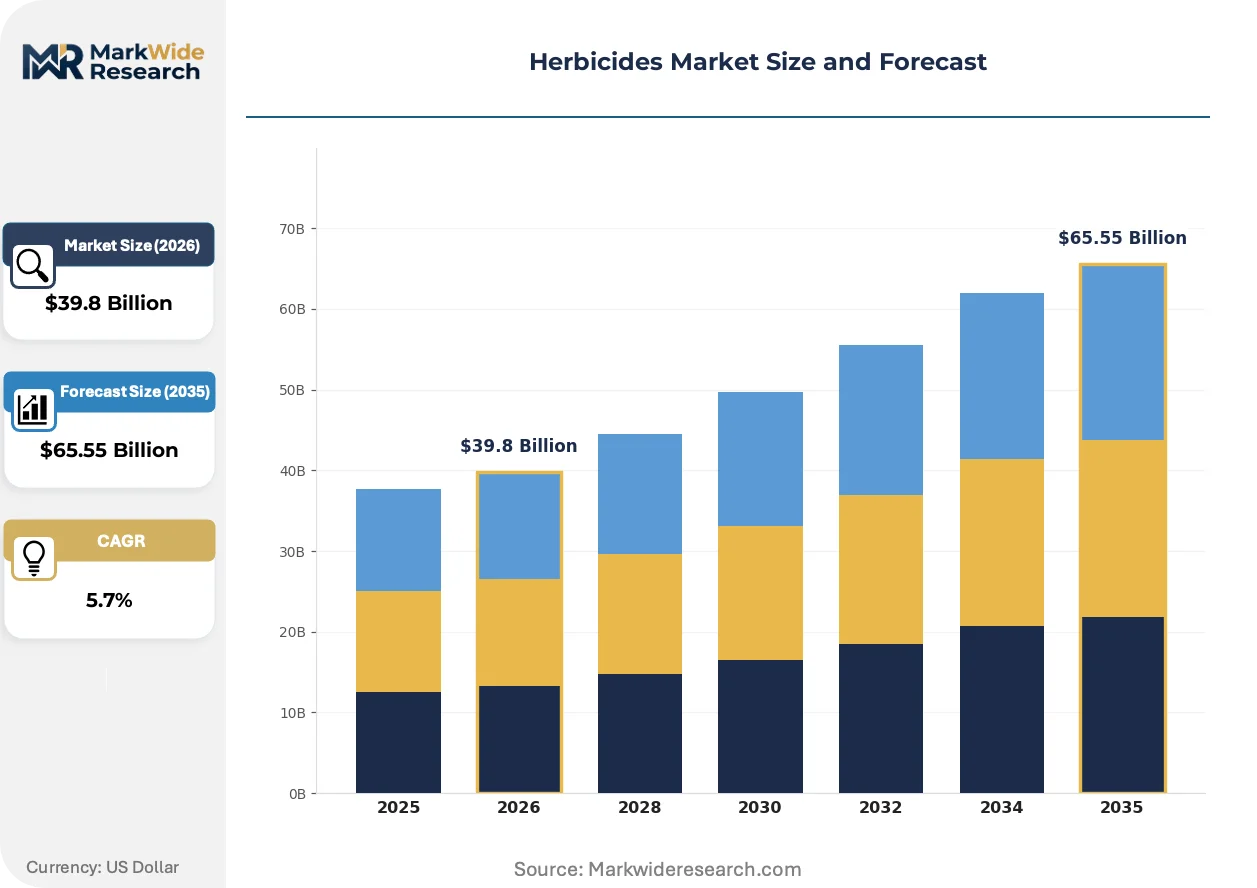
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $65.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-emergent, Post-emergent, Selective, Non-selective, Systemic Form: Liquid, Granular, Powder, Emulsifiable Concentrate, Microencapsulated Application: Cereal Crops, Oilseed Cultivation, Vegetable Farming, Turf Management, Plantation Crops End User: Commercial Growers, Agricultural Cooperatives, Landscape Managers, Government Agencies, Horticulture Experts |
| Companies Covered | Bayer AG, BASF SE, Syngenta Group, Corteva Agriscience, Nufarm Ltd, FMC Corporation, ADAMA Agricultural Solutions, Sumitomo Chemical, UPL Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbicides Market Strategic Shifts & Innovations
Formulation chemistry and application hardware are converging to reduce environmental load while maintaining weed control thresholds, with digital agriculture platforms mediating how growers select and deploy products.
RNA interference herbicides targeting EPSPS and ALS gene expression in weed species are consolidating the discovery pipeline around nucleic-acid delivery systems. Large-scale row-crop operators in the US Corn Belt are piloting these molecules through sponsored trial programs. The technology is consolidating R&D expenditure away from conventional synthetic chemistry toward biological-platform partnerships.
The EU Green Deal's 50% pesticide reduction target by 2030 is accelerating integrated pest management mandates across member states. National action plans in France and Germany now require non-chemical methods as first-line weed control in sensitive areas. Horticulture and viticulture segments are responding with mechanical weeding equipment purchases that reduce herbicide dependency.
Amenity and industrial vegetation managers are unbundling chemical supply from application services, contracting directly with certified spray operators rather than purchasing through distribution. Municipal procurement in Australian states and Canadian provinces now specifies outcome-based contracts with efficacy guarantees rather than product volumes. This reconfiguration compresses distributor margins while rewarding formulation performance.
Herbicides Market Segmentation
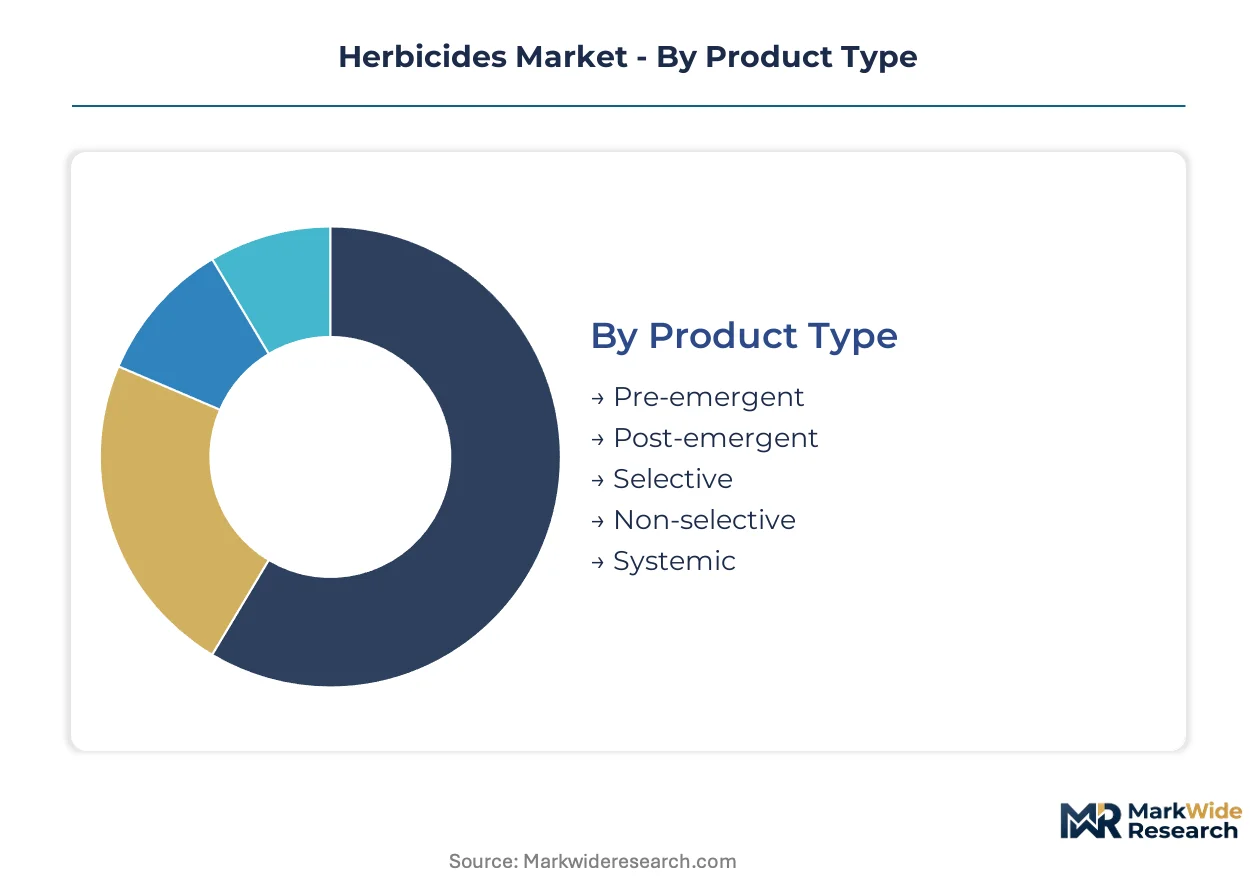
Herbicide purchasing decisions pivot on weed emergence timing, crop safety margins, and application infrastructure compatibility. Segmentation reveals how formulation chemistry and end-use specialization create distinct competitive arenas with divergent margin profiles.
Product Type:
Buyer selection hinges on crop growth stage and weed spectrum specificity, with resistance management protocols increasingly dicting rotation requirements.
- Post-emergent:Applied after weed emergence, these formulations target actively growing vegetation through foliar absorption. Brazilian soybean operations in Mato Grosso are expanding glufosinate-ammonium programs as glyphosate resistance intensifies, though higher per-hectare costs constrain adoption among smaller holdings.
- Selective:Engineered to eliminate target weeds while preserving crop metabolic pathways, these agents dominate cereal applications where narrow safety margins determine product choice. India's Central Insecticides Board prioritizes registration for low-toxicity selective molecules, accelerating entry into Punjab wheat systems.
- Pre-emergent:Soil-applied formulations creating residual barriers against germination.
- Non-selective:Broad-spectrum vegetation control for pre-plant burndown and industrial sites.
- Systemic:Translocated agents moving through plant vascular systems for root-kill efficacy.
Post-emergent leads on scale; selective leads on momentum.
Form:
Application equipment compatibility and environmental persistence requirements shape formulation preferences across end-use segments.
- Liquid:Dominant volume format enabling precise tank-mixing with adjuvants and compatibility with standard spray rigs. Drone-based spot-spraying systems in Australian grain regions favor liquid concentrates for computer-vision guided sub-hectare application, reducing active ingredient load while maintaining efficacy thresholds.
- Microencapsulated:Polymer-shell delivery systems enabling controlled release and reduced leaching risk. EU Green Deal residue tightening is accelerating regulatory preference for these formulations in groundwater-sensitive catchments across France and Germany.
- Granular:Solid carrier formulations for broadcast or banded soil application.
- Powder:Dry concentrates requiring reconstitution prior to field application.
- Emulsifiable Concentrate:Oil-in-water dispersions combining lipophilic active ingredients with aqueous spray compatibility.
Liquid commands installed base penetration; microencapsulated climbs the fastest on regulatory alignment.
Application:
Crop value per hectare and weed pressure severity determine chemistry investment levels across agricultural segments.
- Cereal Crops:Wheat, rice, and maize applications where selective agents protect yield potential against grassy and broadleaf competition. China's volume demand concentrates in Henan and Shandong provinces, with state procurement policies influencing product selection for food security reserves.
- Oilseed Cultivation:Soybean and canola systems requiring specialized programs against competitive broadleaf species. Brazilian commercial operations face ANVISA residue limits that directly determine European export eligibility, forcing chemistry upgrades beyond domestic regulatory minimums.
- Vegetable Farming:High-value produce with strict maximum residue limits and pre-harvest interval constraints.
- Turf Management:Amenity and sports surface applications where aesthetic standards override cost minimization.
- Plantation Crops:Perennial systems including coffee, citrus, and oil palm with multi-year weed control horizons.
Cereal crops anchor volume demand; oilseed cultivation shows steepest expansion trajectory on South American acreage growth.
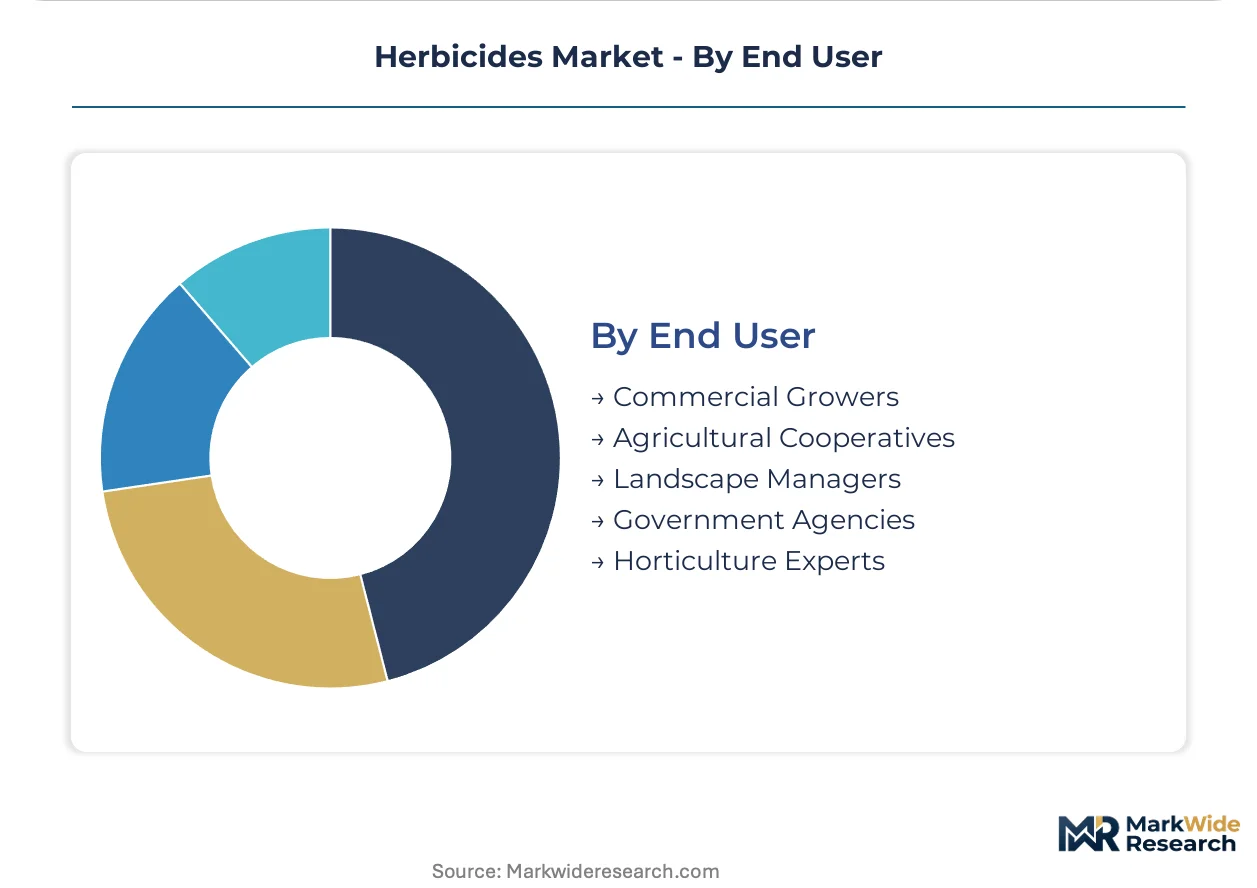
End User:
Scale economies and technical sophistication create divergent purchasing behaviors across customer categories.
- Commercial Growers:Large-scale operations with dedicated agronomy staff and precision application infrastructure. US Corn Belt operators are piloting RNA interference herbicides through sponsored trial programs, consolidating R&D expenditure toward biological-platform partnerships.
- Agricultural Cooperatives:Pooled procurement entities aggregating demand across member farms for volume pricing leverage.
- Landscape Managers:Municipal and private amenity contractors shifting toward outcome-based contracts with efficacy guarantees rather than product volumes.
- Government Agencies:Public vegetation control programs on transportation corridors and conservation lands.
- Horticulture Experts:Specialized producers requiring crop-specific programs with narrow application windows.
Commercial growers dominate absolute spend; landscape managers are gaining share fastest on service unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces concentrate synthesis of key active ingredient precursors, exposing formulation supply chains to environmental compliance volatility. Regulatory divergence between jurisdictions shapes which chemistries retain market access across major agrarian economies.
United States
US Corn Belt operators pilot RNA interference herbicides through sponsored trial programs, consolidating R&D expenditure toward biological-platform partnerships. EPA regulates tolerance limits through residue chemistry studies and ecological risk assessments under 40 CFR Part 158. Precision application systems reduce per-hectare chemical load across Iowa and Illinois soybean operations.
Brazil
Commercial soybean operations in Mato Grosso and Goiás adopt glufosinate-ammonium programs at scale as glyphosate resistance intensifies. ANVISA enforces maximum residue limits that determine European export eligibility for soybean and corn. Post-emergent formulation demand concentrates in the Cerrado agricultural frontier.
China
State procurement policies influence product selection for food security reserves in Henan and Shandong cereal production zones. MEE environmental compliance crackdowns in Jiangsu province disrupt precursor synthesis for global formulation supply. Volume demand for cereal crop applications drives domestic manufacturer capacity expansion.
India
The Central Insecticides Board streamlines registration pathways for low-toxicity molecules, accelerating entry into Punjab wheat and Haryana rice systems. DGFT trade policies shape import dependency for technical-grade active ingredients. Demand concentrates in northern Indo-Gangetic plain cereal applications.
Germany
BASF SE anchors precision application system development from Ludwigshafen headquarters, reducing per-hectare chemical load through variable-rate technologies. EU Green Deal residue tightening and ECHA REACH substance evaluation threaten withdrawal authorization for triazine herbicides. Bio-based formulation approvals accelerate for microbial herbicide pipelines.
Herbicides Market Key Industry Players
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where scale-driven players anchor bundled offerings while specialists occupy niche chemistry positions. The vendor base stratifies between integrated agrochemical conglomerates with seed-trait pipelines, mid-tier manufacturers with regional registration expertise, and precision application equipment-chemistry bundlers. Dominant competitive moves include portfolio diversification into bio-based alternatives and strategic partnerships with drone-based application service providers.
Within the integrated conglomerate tier, Bayer AG, BASF SE, and Syngenta Group exemplify divergent strategic positioning. Bayer AG leverages seed-trait pipelines to anchor bundled herbicide offerings. BASF SE occupies a position as a precision application specialist reducing chemical load per hectare. Syngenta Group exemplifies differentiated formulation technologies that extend residual activity. These three entities represent distinct archetypes: trait-bundled chemistry, precision-enabled reduction, and formulation-performance extension.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| Nufarm Ltd |
| FMC Corporation |
| ADAMA Agricultural Solutions |
| Sumitomo Chemical |
| UPL Ltd |
| Others |
Cost & Logistics Intelligence
EU Green Deal residue tightening and the EU Green Deal's 50% pesticide reduction mandate are forcing formulation suppliers toward bio-based alternatives and microencapsulated delivery systems, compressing margins on conventional synthetic chemistry while rewarding premium positioning for microbial pipelines and precision-enabled reduction technologies.
Pricing Analysis
Active ingredient precursor costs in Jiangsu province directly transmit to finished formulation pricing across export markets. Three-tier pricing structure across premium, standard, and economy levels separates microbial bioherbicides from extended-residue synthetics and commodity generics. Cost compression in the standard tier is intensifying because Chinese environmental compliance crackdowns disrupt intermediate supply. Commercial growers in Brazil and the US Corn Belt show lowest price sensitivity due to yield-protection economics, while smallholder cereal farmers in India exhibit highest sensitivity to per-hectare chemical costs.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Shandong provinces, where environmental compliance actions by China's MEE cascade through global active ingredient availability. Formulation supply draws from concentrated precursor synthesis in these coastal industrial zones, with technical-grade AI production resting on petrochemical feedstocks and specialized catalyst inputs. Regulatory restriction risk emanates from divergent residue limits between EPA, ECHA REACH, and ANVISA jurisdictions. Distribution runs through regional agrochemical distributors with registration expertise, though commercial growers increasingly contract directly with certified spray operators for outcome-based service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory stringency and South American volume expansion, with manufacturers capturing margin premiums in Europe's bio-based transition while scaling cost-optimized synthetics for Brazilian soybean operations.
For Market Incumbents: To counter glyphosate resistance compression and accelerating bioherbicide substitution, Bayer AG and Syngenta Group should deepen backward integration into microbial fermentation capacity for bio-based pipelines while anchoring bundled seed-trait offerings in the Cerrado agricultural frontier. Channel control through direct service contracts with Mato Grosso commercial operators protects margin position against distributor disintermediation. For New Entrants and Emerging Players: The EU Green Deal's accelerated bio-based formulation approval pathway in France and Germany opens a window for microbial herbicide specialists to establish first-mover positioning in viticulture and horticulture segments where mechanical weeding mandates create chemical substitution demand. India's streamlined Central Insecticides Board registration for low-toxicity molecules offers the most penetrable entry point for selective cereal crop applications across Punjab and Haryana, with co-development partnerships with domestic distributors as the optimal go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with precision application equipment-chemistry bundlers possessing drone-based spot-spraying capabilities and variable-rate spray system integration expertise. Long-term viability over the coming decade hinges on carbon credit alignment and reduced-tillage program enablement in North American grain markets. Watch for ANVISA residue limit harmonization with EU standards as the inflection signal for chemistry upgrade cycles in Brazilian export-oriented operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captures margin from bio-based formulation demand surge under EU Green Deal mandates. |
| Precision Application System Bundling | Creates service-revenue streams beyond product sales through soil-moisture sensor integration. |
| Drone-Based Spot-Spraying Partnership | Reduces active ingredient load while maintaining efficacy thresholds in Australian grain regions. |
| Carbon Credit Alignment Certification | Qualifies reduced-tillage programs for verified offset protocols in North American markets. |
| Direct Service Contract Expansion | Compresses distributor margins while locking in commercial grower relationships through outcome-based efficacy guarantees. |
Research Approach
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with agrochemical R&D directors, regulatory affairs specialists at national registration bodies, commercial grower agronomists, and precision application equipment manufacturers. Secondary validation draws from EPA 40 CFR filings, ECHA REACH substance evaluations, ANVISA residue limit publications, and customs trade data on active ingredient precursor flows. Bottom-up volume estimates from crop-acreage application rates triangulate against top-down manufacturer capacity disclosures.
Rate-of-change decomposition separates volume expansion from value mix-shift across the projection horizon. Segmentation dimensions modeled include product type, formulation chemistry, crop application, and grower scale tier. CAGRs derive from regression against historical acreage trends, resistance adoption curves, and regulatory phase-out schedules. Industry-specific forecast inputs incorporate glyphosate resistance monitoring data and EU Farm to Fork implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA substance withdrawal decisions or MEE environmental enforcement surges in Jiangsu province. Forecasts reflect assumptions on resistance evolution rates, bioherbicide efficacy maturation, and regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
China Fungicide Market
Crop Protection
India Herbicide Market
Crop Protection
Metamifop Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
US Pest Control Market
Crop Protection
Propiconazole Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Nematicides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
North America Acaricides Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Global Dicamba Herbicide Market