
 US Greenhouse Horticulture Market | 2026-2036
US Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
US Greenhouse Horticulture Market Insights
USDA Organic certification is rotating the competitive field by requiring soil-based or approved hydroponic inputs, which filters out conventional-only operators. Mastronardi Produce leverages its integrated seed-to-shelf pipeline across multiple states. Windset Farms sustains premium positioning through branded retail packaging and varietal specialization. Gotham Greens anchors urban production with rooftop facilities in Chicago, Denver, and New York metro areas.
Greenhouse horticulture deploys climate-controlled structures with glazing materials, automated environmental systems, and precision irrigation to cultivate plants outside their native growing seasons. Structural spans range from gutter-connected polyethylene houses to fully enclosed glass Venlo designs with integrated heating, cooling, and CO2 enrichment. Vegetables dominate volume flows through commercial grower channels, while herbs command margin premiums in direct-to-restaurant distribution. Hydroponics leads technology adoption among large-scale operations, yet organic soil-based methods capture price premiums at retail garden centers and farmers' markets.
FDA Food Safety Modernization Act rules, EPA pesticide tolerance limits, and state agricultural labor standards shape operational compliance costs and product traceability requirements. California's agricultural water regulations and Arizona's groundwater management directives constrain site selection and irrigation technology choices. Stakeholders must monitor evolving organic hydroponic eligibility rulings and energy cost trajectories to time capital deployment decisions.
Market Dynamics
Supermarket chains and foodservice distributors are consolidating procurement around contracted acreage with domestic greenhouse operators, compressing spot-market participation and elevating long-term supply agreements as the dominant commercial interface. This structural shift is reshaping how growers finance expansion and manage price risk.
Growth Catalysts
- USDA Organic Certification:Soil-based and approved hydroponic input requirements are filtering conventional-only operators from premium retail channels. Certified growers capture price premiums at farmers' markets and garden centers.
- Foodservice Distributors:Restaurant chains and institutional buyers are expanding year-round contracted volumes for tomatoes, cucumbers, and leafy greens, insulating greenhouse operators from commodity price swings.
- LED Supplemental Lighting:Energy-efficient spectral controls are extending viable growing seasons in northern latitudes, enabling Michigan and Ohio operations to compete with traditional Sun Belt production.
Market Restraints
- Natural Gas Price Volatility:Heating costs in glass Venlo structures consume 25-35% of operating budgets, exposing northern operators to fuel price spikes that soil-based field growers avoid.
- Groundwater Access Constraints:Arizona's Active Management Areas and California's Sustainable Groundwater Management Act restrict well drilling permits, limiting site selection to districts with surplus water allocations.
- Imported Hydroponic Produce:Mexican and Canadian greenhouse tomatoes enter US markets duty-free under USMCA, pressuring domestic margin structures on commodity varieties.
Strategic Opportunities
- Controlled-Environment Cannabis:State-legal medical and adult-use markets in Florida, Arizona, and Illinois are repurposing vegetable greenhouse infrastructure for high-margin cultivation.
- Integrated Carbon Capture:Industrial CO2 waste streams from ethanol plants and ammonia facilities are being piped to greenhouse operations, reducing enrichment costs and qualifying for IRA clean energy credits.
- Direct-to-Restaurant Channels:Chef-forward distribution bypassing traditional wholesalers is capturing 40-60% price premiums on heirloom tomatoes and specialty herbs in Chicago and New York metro areas.
Industry Challenges
- Controlled-Environment Agronomy Talent:Shortage of technicians trained in climate system calibration, integrated pest management, and hydroponic nutrient solution balancing limits expansion velocity.
- Organic Hydroponic Eligibility Uncertainty:Pending USDA National Organic Program rulings on container-based production methods are freezing capital deployment for growers weighing soilless infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Greenhouse Horticulture Market |
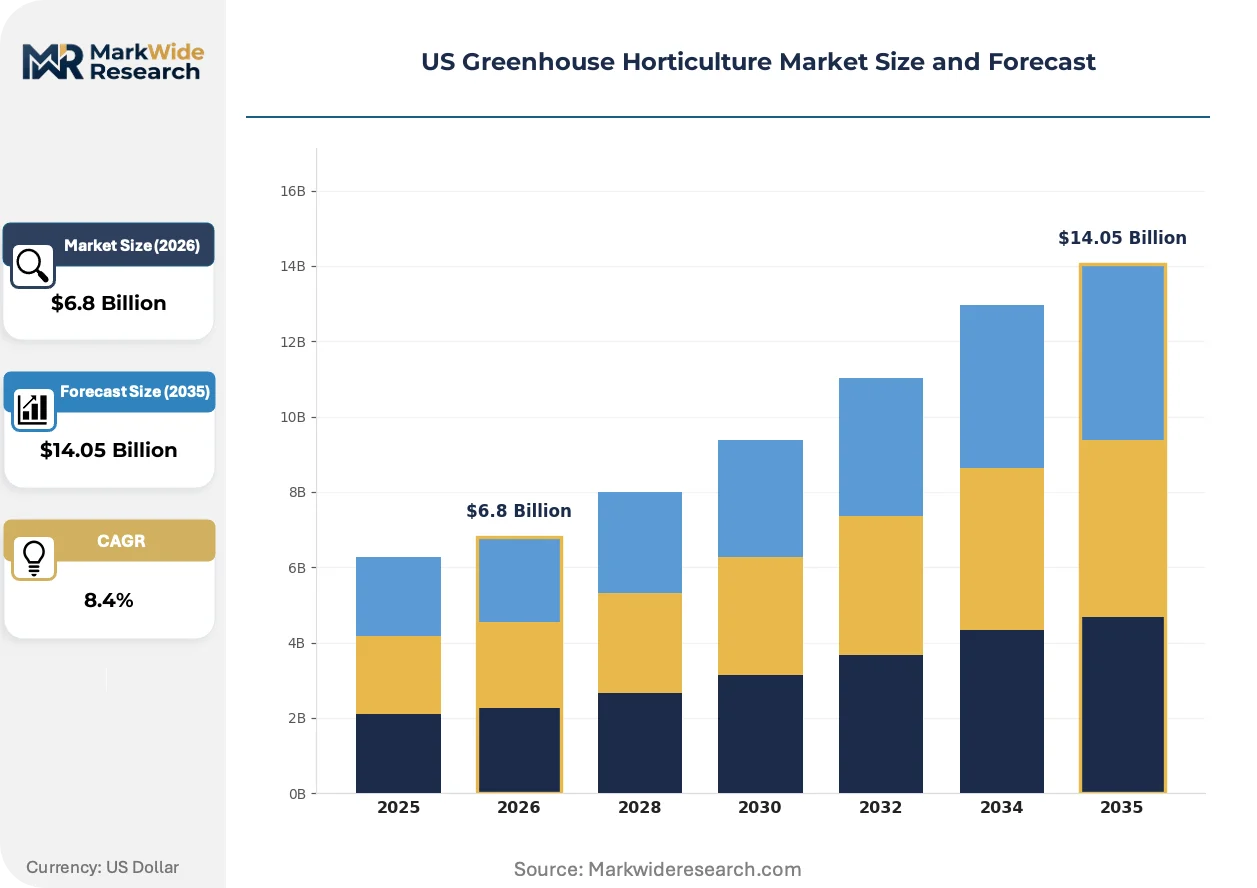
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flowers, Vegetables, Herbs, Foliage Plants Technology: Hydroponics, Aquaponics, Aeroponics, Organic End User: Commercial Growers, Retail Garden Centers, Landscaping Companies, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Farmers' Markets |
| Companies Covered | Mastronardi Produce, Windset Farms, Gotham Greens, Stuppy Greenhouse, Poly-Tex, Rough Brothers, Hort Americas, Ceres Greenhouse Solutions, Agra Tech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Greenhouse Horticulture Market Trends and Innovations
Automation and environmental sensing technologies are compressing labor inputs and enabling sub-acre precision management, while regulatory pressure on water and energy use is accelerating closed-loop system adoption across the Southwest and Southeast production clusters.
Sensor-integrated fertigation systems are miniaturizing nutrient delivery from zone-level to individual-plant granularity, enabling varietal-specific feeding protocols within single greenhouse bays. Large-scale tomato and cucumber operations in Arizona and Florida are deploying these systems to reduce water use intensity by 15-20% while maintaining yield consistency. The technology is compressing the viable scale threshold for precision agriculture, allowing sub-five-acre operations to match the input efficiency of 50-acre facilities.
EPA pesticide tolerance limits under the Federal Insecticide, Fungicide, and Rodenticide Act are tightening residue thresholds for imported produce, elevating domestic greenhouse operators who maintain documented biosecurity protocols. FDA Food Safety Modernization Act traceability rules are mandating lot-level record retention, favoring integrated seed-to-shelf pipelines over fragmented spot-market sourcing. California and Arizona growers are responding by deploying blockchain-enabled supply chain tracking to preempt audit failures.
Buyer consolidation among supermarket chains is compressing supplier counts and extending contract durations from annual to multi-year terms. Kroger, Albertsons, and Publix are reducing their greenhouse tomato supplier bases by 30-40%, concentrating volume with operators who can guarantee 52-week supply across multiple SKUs. This pattern is most visible in the Southeast, where Publix's Florida-centric procurement is anchoring expansion in central Florida greenhouse clusters.
US Greenhouse Horticulture Market Segmentation
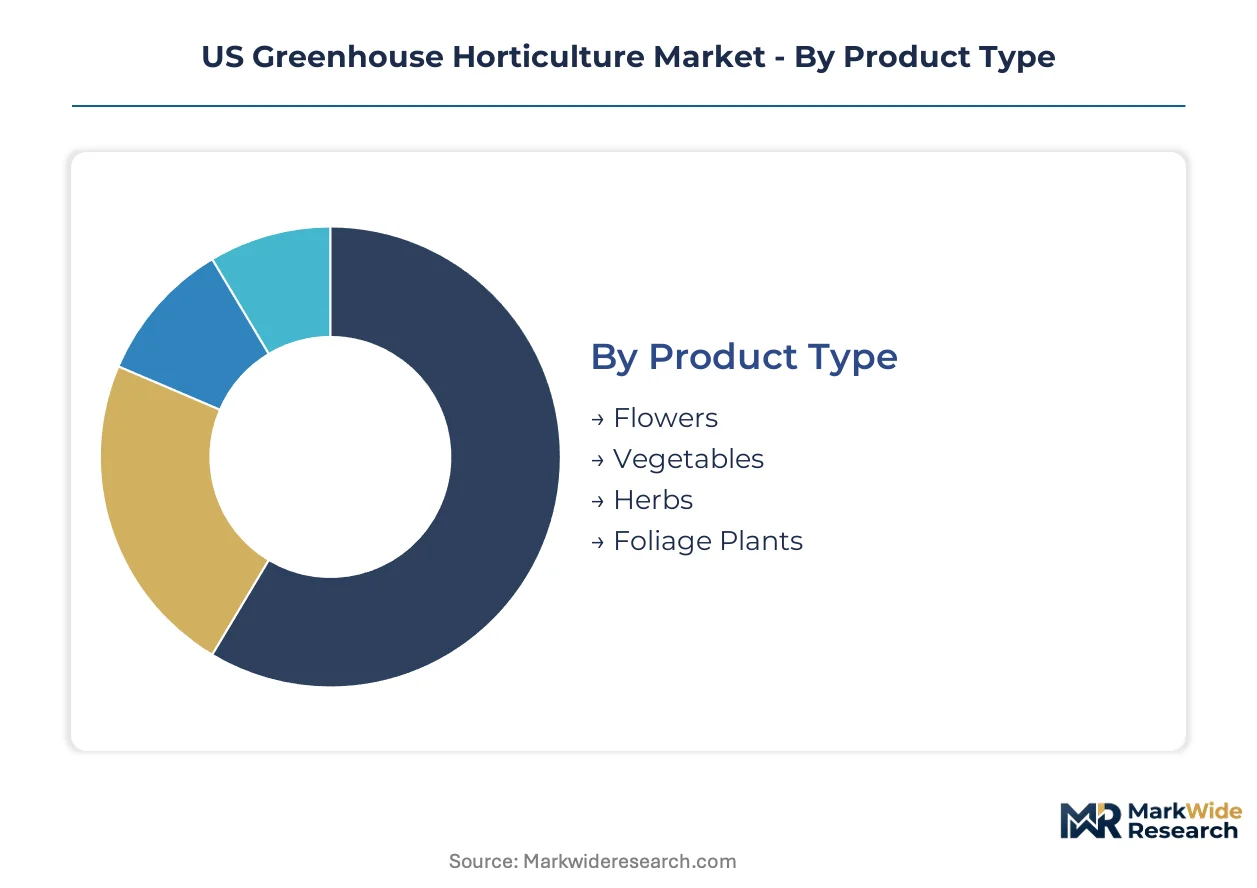
US greenhouse horticulture segments along four axes that determine capital intensity, regulatory exposure, and margin capture. Product type drives volume scale while technology choice locks in compliance pathways and operating cost structures.
Product Type:
Margin pools concentrate in vegetables and herbs where year-round supply contracts command premium pricing from foodservice distributors and supermarket chains.
- Vegetables:Tomatoes, cucumbers, and leafy greens dominate commercial throughput with climate-controlled production extending growing seasons beyond field agriculture limits. Demand clusters in the Southwest and Southeast where Phoenix, Tucson, and central Florida greenhouse clusters supply Publix, Kroger, and Albertsons with 52-week contracted volumes. LED supplemental lighting is enabling Michigan and Ohio operators to compete with traditional Sun Belt production on vine crops.
- Herbs:Basil, cilantro, and specialty varieties capture 40-60% price premiums in direct-to-restaurant channels bypassing traditional wholesalers. Chicago and New York metro area chefs drive demand for heirloom varietals with documented provenance and harvest-to-plate traceability. Smaller bay configurations suit herb production's higher labor intensity and varietal turnover.
- Flowers:Ornamental production serves retail garden centers and landscaping companies with seasonal demand spikes around holidays and spring planting cycles. Florida and California operations dominate poinsettia and bedding plant supply.
- Foliage Plants:Interior landscaping contracts and consumer houseplant demand sustain lower-margin volume production concentrated in Florida and Texas greenhouse clusters.
Vegetables hold installed capacity. Herbs is rotating up the share rankings.
Technology:
Technology choice determines water use intensity, nutrient delivery precision, and eligibility for USDA Organic certification price premiums.
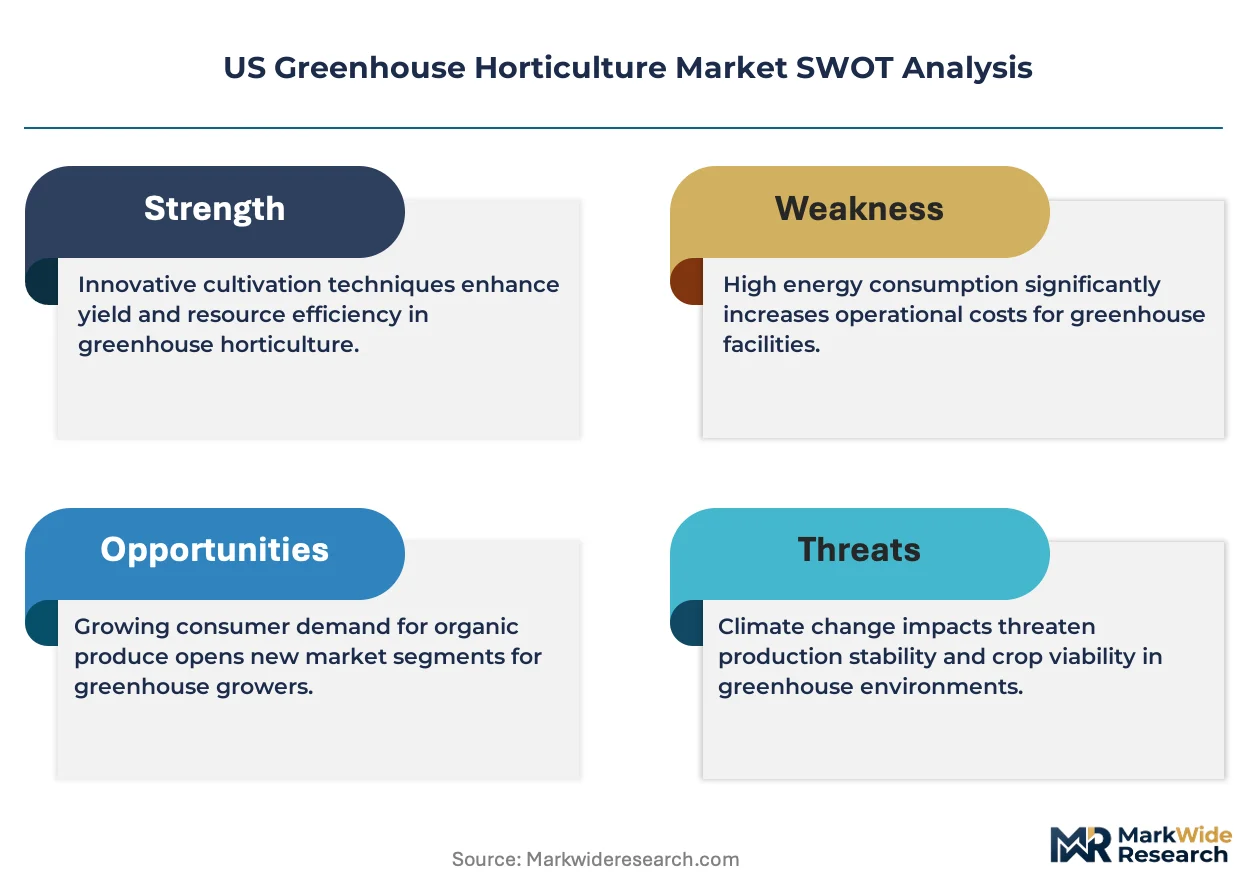
- Hydroponics:Nutrient film technique and deep water culture systems enable 15-20% water use reduction compared to soil-based methods while maintaining yield consistency. Large-scale tomato and cucumber operations in Arizona and Florida deploy sensor-integrated fertigation at individual-plant granularity. Pending USDA National Organic Program rulings on container-based production are freezing capital deployment for growers weighing soilless infrastructure investments.
- Organic:Soil-based or approved hydroponic input requirements filter conventional-only operators from premium retail channels at farmers' markets and garden centers. Certified growers capture price premiums but face higher labor costs and biosecurity protocol documentation burdens under FDA Food Safety Modernization Act traceability rules.
- Aquaponics:Integrated fish cultivation recirculates nutrient-rich water to plant beds, closing waste loops in smaller-scale operations serving local restaurant and farmers' market channels.
- Aeroponics:Mist-based root delivery minimizes water use and enables vertical stacking configurations, though technical complexity limits adoption to research institutions and specialty herb producers.
Hydroponics dominates large-scale commercial acreage. Organic is climbing the fastest as supermarket chains expand certified SKU counts.
End User:
Customer type determines contract structure, payment terms, and traceability documentation intensity.
- Commercial Growers:Volume purchasers of propagation material and climate system components supply supermarket chains and foodservice distributors through multi-year supply agreements. Buyer consolidation among Kroger, Albertsons, and Publix is reducing supplier counts by 30-40% and extending contract durations.
- Retail Garden Centers:Seasonal demand for bedding plants and ornamentals with higher margin capture on certified organic and heirloom varieties. Direct consumer relationships enable price premiums absent in wholesale channels.
- Landscaping Companies:Contract growers for commercial and residential installation projects with specifications for mature plant size and seasonal availability windows.
- Research Institutions:Controlled-environment agriculture trials and cultivar development programs at land-grant universities and private breeding operations.
Commercial growers hold installed capacity. Retail garden centers is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin retention, traceability burden, and exposure to spot-market price volatility.
- Wholesale Distributors:Foodservice and supermarket supply chains dominate volume flows with lot-level record retention mandated by FDA traceability rules. Blockchain-enabled tracking systems are preempting audit failures among California and Arizona operators.
- Direct Sales:Chef-forward distribution in Chicago and New York metro areas captures premium pricing on specialty tomatoes and herbs with harvest-to-plate provenance documentation.
- Farmers' Markets:USDA Organic certified producers command price premiums with direct consumer relationships and minimal intermediary costs.
- Online Retail:Seedling and houseplant shipments to consumers with packaging and logistics costs compressing margins relative to wholesale channels.
Wholesale distributors hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket chains and foodservice distributors concentrate procurement around contracted acreage with domestic greenhouse operators, compressing spot-market participation and elevating long-term supply agreements as the dominant commercial interface across US production regions.
Southwest
Phoenix and Tucson anchor the nation's largest controlled-environment agriculture cluster, with operators leveraging year-round solar radiation to supply vine crops to Publix, Kroger, and Albertsons. Arizona's Active Management Areas restrict well drilling permits under groundwater management directives, forcing site selection toward districts with surplus water allocations. LED supplemental lighting adoption is accelerating in Maricopa County as operators seek to offset summer peak electricity pricing through spectral efficiency gains.
Southeast
Central Florida greenhouse clusters supply Publix's Florida-centric procurement with 52-week contracted volumes of tomatoes, cucumbers, and leafy greens. The state's subtropical climate reduces heating costs relative to northern operations, though hurricane exposure elevates structural insurance premiums. Orlando and Tampa metropolitan areas host expanding propagation facilities serving the ornamental and bedding plant trades for retail garden center distribution.
Midwest
Michigan and Ohio operators deploy energy-efficient spectral controls to extend viable growing seasons for vine crops, enabling competition with traditional Sun Belt production. Natural gas price volatility consumes 25-35% of operating budgets in glass Venlo structures, exposing northern operators to fuel price spikes that soil-based field growers avoid. Chicago metro area chefs drive demand for heirloom tomato and specialty herb direct-to-restaurant channels capturing 40-60% price premiums.
California
Central Coast and Salinas Valley operations face tightening constraints under the Sustainable Groundwater Management Act, limiting site selection to districts with surplus water allocations and accelerating closed-loop irrigation adoption. FDA Food Safety Modernization Act traceability rules mandate lot-level record retention, favoring integrated seed-to-shelf pipelines over fragmented spot-market sourcing. Blockchain-enabled supply chain tracking deployment is preempting audit failures among Monterey and Santa Barbara county growers.
Northeast
New York and Boston metropolitan areas anchor urban rooftop greenhouse production, with facilities leveraging waste heat from adjacent buildings and municipal compost streams for soil-based organic certification. Gotham Greens operates across Chicago, Denver, and New York metro areas with controlled-environment facilities integrated into commercial real estate developments. High land and labor costs compress margins relative to Sun Belt operations, though proximity to chef-forward distribution channels enables premium capture on harvest-to-plate provenance documentation.
US Greenhouse Horticulture Market Competitive Landscape
Player mix skews toward vertically integrated produce distributors and regional greenhouse fabricators serving distinct customer tiers. The vendor base separates into three structural layers: large-scale produce suppliers with multi-state contracted acreage, mid-cap regional operators specializing in varietal differentiation, and equipment fabricators supplying structural components and environmental systems. Consolidation pressure concentrates volume with operators who can guarantee 52-week supply across multiple SKUs, while technology licensing and strategic partnerships dominate competitive moves among component suppliers.
Within the integrated produce supplier tier, Mastronardi Produce and Windset Farms exemplify scale-driven positioning through multi-state seed-to-shelf pipelines and branded retail packaging strategies. Gotham Greens occupies a distinct urban production archetype with rooftop facility networks anchored in major metropolitan markets. Among greenhouse fabricators, Stuppy Greenhouse, Poly-Tex, and Rough Brothers represent equipment specialists serving commercial grower expansion cycles with structural spans ranging from polyethylene houses to glass Venlo designs.
| Leading Market Players |
|---|
| Mastronardi Produce |
| Windset Farms |
| Gotham Greens |
| Stuppy Greenhouse |
| Poly-Tex |
| Rough Brothers |
| Hort Americas |
| Ceres Greenhouse Solutions |
| Agra Tech |
| Others |
Pricing and Supply Chain Analysis
Fourteen-day propagation-to-harvest lead times for vine crops concentrate pricing power with operators who maintain year-round contracted acreage, while spot-market participants absorb volatility from Mexican and Canadian duty-free imports under USMCA. This temporal compression rewards integrated seed-to-shelf pipelines and penalizes fragmented sourcing that cannot guarantee 52-week supply consistency to Kroger, Albertsons, and Publix procurement desks.
Pricing Analysis
Cost-plus contracts indexed to natural gas futures and agricultural labor wage bands dominate multi-year supply agreements between greenhouse operators and supermarket chains. Three-tier pricing structure across premium certified-organic, standard hydroponic, and economy field-grown levels separates USDA Organic price premiums at farmers' markets from commodity tomato margins pressured by Mexican imports. Pricing pressure stems from heating cost volatility consuming 25-35% of northern operators' budgets, rendering Sun Belt producers least price-sensitive while Michigan and Ohio facilities face acute margin compression during winter fuel spikes.
Supply Chain Analysis
Inventory cycles of seven-to-ten days for leafy greens and fourteen-to-twenty-one days for vine crops tether downstream distribution to just-in-time replenishment models. Domestic production draws from Arizona, Florida, and California clusters, with propagation materials and LED lighting systems sourced from China, the Netherlands, and domestic manufacturers. Single-source vulnerability concentrates in semiconductor-dependent climate control systems, while wholesale distributors anchor downstream flows through foodservice and supermarket channels with lot-level FDA traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agronomy expertise—spanning climate system calibration, integrated pest management, and hydroponic nutrient balancing—functions as the binding constraint on expansion velocity, with technician shortages limiting facility commissioning timelines regardless of capital availability.
For Market Incumbents: Secure multi-year supply agreements with Publix, Kroger, and Albertsons before buyer consolidation reduces supplier counts further, while capturing in-house propagation capabilities to insulate against seed supply disruptions. Backward integration into CO2 enrichment sourcing from ethanol plants and ammonia facilities reduces input cost exposure and qualifies for IRA clean energy credits. For New Entrants and Emerging Players: Lead with direct-to-restaurant channels in Chicago and New York metro areas, where chef-forward distribution captures 40-60% price premiums on heirloom tomatoes and specialty herbs with harvest-to-plate provenance documentation. Target urban rooftop production archetypes with waste heat integration and municipal compost streams for organic certification, bypassing capital-intensive ground-up greenhouse construction. For Investors and Strategic Acquirers: Long-term, this sits as a climate-resilience infrastructure play because supermarket chains and foodservice distributors are structurally shifting procurement from field agriculture to controlled-environment supply guarantees. Acquisition targets should display integrated seed-to-shelf pipelines with documented biosecurity protocols. The signal to watch is USDA National Organic Program rulings on container-based production eligibility, which would unlock capital deployment for soilless infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Supply Agreement | Locks in 52-week volume commitments with Kroger, Albertsons, and Publix procurement desks. |
| Backward Integration | Captures CO2 waste streams from ethanol plants to reduce enrichment costs and qualify for IRA credits. |
| Certification Investment | Secures USDA Organic price premiums at farmers' markets and garden centers ahead of eligibility rulings. |
| Direct-to-Restaurant Channel | Bypasses wholesale distributors to capture chef-forward premiums in Chicago and New York metro areas. |
| Urban Rooftop Expansion | Leverages waste heat and municipal compost streams for organic certification in high-land-cost metros. |
Research Methodology
Cross-validation between primary interviews with greenhouse operations managers, produce procurement directors at supermarket chains, climate system engineers, and foodservice distribution executives and secondary sources including USDA National Agricultural Statistics Service data, EPA pesticide tolerance filings, FDA Food Safety Modernization Act guidance documents, and state-level groundwater management directives anchors the qualitative findings. Bottom-up facility capacity assessments and top-down consumption estimates triangulate market sizing.
Sensitivity analysis across natural gas price trajectories, organic hydroponic eligibility scenarios, and LED technology adoption curves shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, technology choice, end-user category, and distribution channel, with CAGRs derived from regression analysis against historical acreage expansion and input cost indices. Forecast inputs incorporate Arizona groundwater allocation constraints and California Sustainable Groundwater Management Act compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained supermarket chain consolidation, stable USMCA trade terms, and resolved USDA organic hydroponic eligibility would require recalibration. Revision becomes warranted when natural gas price volatility or groundwater access restrictions cross thresholds that render northern or Southwestern operations structurally unprofitable.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
North America Eggs Market