
 African Swine Feed Market | 2026-2036
African Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
African Swine Feed Market Outlook
South African feed millers is realigning output toward higher-protein formulations as regional soybean processing expands. Cargill Incorporated leverages its grain origination networks to secure corn supply across the continent. Nutreco NV anchors its position through premix specialization for large-scale integrators. Alltech Inc competes via yeast-based additive portfolios that address gut health challenges in tropical climates.
African swine feed denotes nutritionally complete rations formulated for Sus scrofa domesticus, typically containing 14-18% crude protein, lysine levels of 0.8-1.0%, and energy densities of 3,200-3,400 kcal ME per kilogram, manufactured through pelleting or mash processes to optimize feed conversion efficiency in commercial pork production systems. Corn-based formulations dominate volume due to price accessibility across East and West Africa, while enzyme-supplemented diets represent the fastest-expanding additive category as producers seek digestibility gains from locally sourced coarse grains. Premix distribution channels capture disproportionate margin pools by concentrating technical expertise and trace mineral precision.
Nigeria's National Agency for Food and Drug Administration and Control, South Africa's Department of Agriculture, Land Reform and Rural Development, and the FAO/OIE African swine fever control frameworks collectively shape product registration, import permitting, and biosecurity-aligned feed handling standards across the continent. Producers must monitor evolving mycotoxin regulatory thresholds and veterinary drug residue limits that determine market access for pork exports to the European Union. Stakeholder decisions on backward integration into soybean crushing will determine cost structures as regional oilseed processing capacity expands.
Market Dynamics
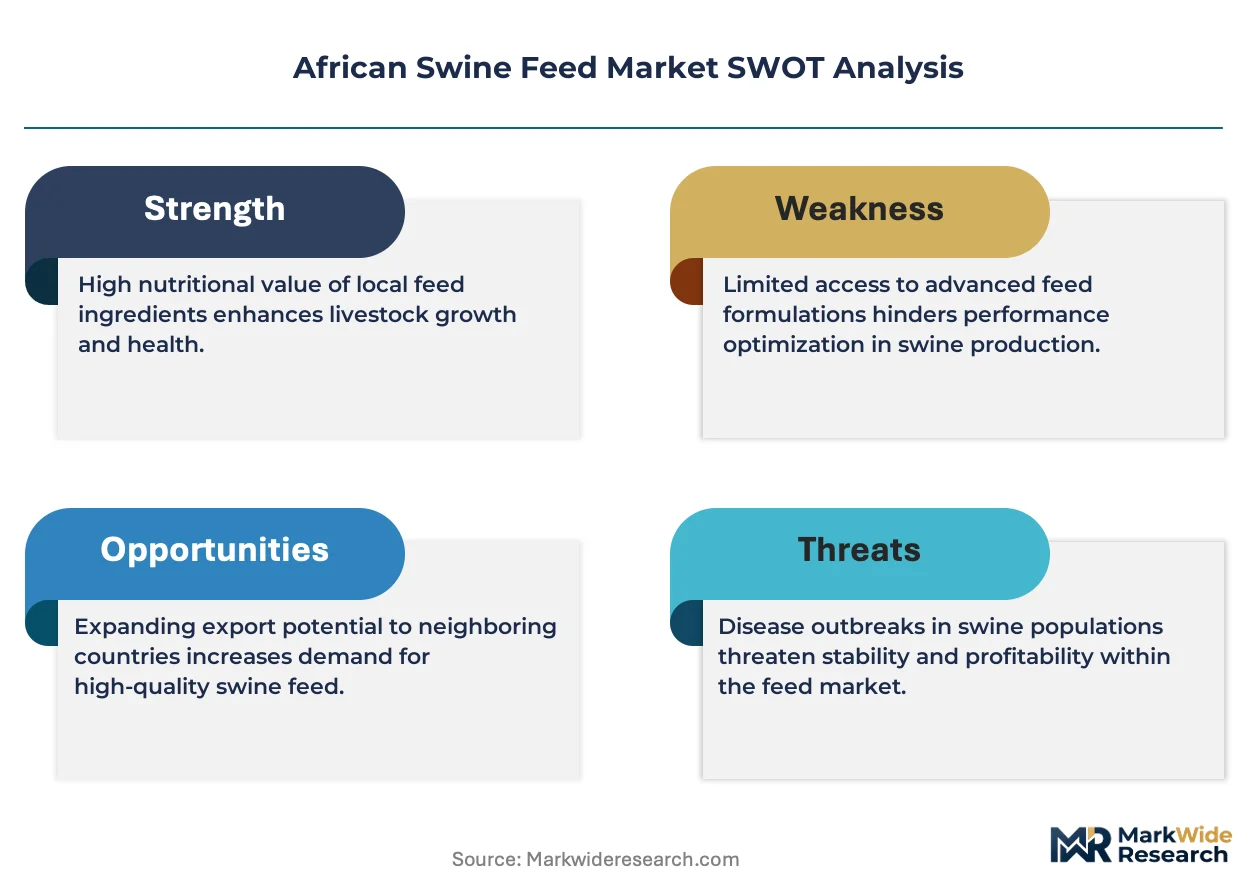
African swine fever containment protocols are forcing commercial pig farms across Sub-Saharan Africa to upgrade biosecurity-aligned feed handling infrastructure, redirecting capital toward traceable supply chains and veterinary-supervised procurement systems.
Growth Catalysts
- FAO/OIE Control Frameworks:Harmonized disease surveillance protocols are standardizing feed mill biosecurity investments across Nigeria, Kenya, and Uganda, accelerating formal sector consolidation.
- Soybean Processing Expansion:Regional oilseed crushing capacity growth in South Africa and Zambia is localizing protein concentrate supply, reducing import dependency for lysine-rich formulations.
- Enzyme Supplementation:Phytase and xylanase additives are unlocking digestibility gains from sorghum and millet, enabling substitution of imported corn in East African rations.
Market Restraints
- Corn Price Volatility:Weather-induced supply shocks in Zambia and Zimbabwe transmit directly to feed formulation costs, compressing integrator margins during drought cycles.
- Import Concentration Risk:Vitamin premix supply remains dominated by European and Asian exporters, exposing African compounders to currency fluctuation and shipping disruptions.
- Aflatoxin Regulatory Thresholds:EU-aligned mycotoxin limits under Nigeria's NAFDAC and South Africa's Department of Agriculture render substantial local grain harvests unfit for export-oriented pork production.
Strategic Opportunities
- Ethiopia's Untapped Commercial Sector:Orthodox dietary restrictions have constrained formal pork production, creating first-mover advantage for feed suppliers as urban consumption patterns diversify.
- Mobile Premix Distribution:Agent networks delivering micro-dosed mineral packs directly to smallholder cooperatives bypass traditional distributor markups in Ghana and Côte d'Ivoire.
- Regional Oilseed Incentives:South African industrial development zones offer tax relief for soybean crushing investments, lowering landed cost of high-protein feed ingredients.
Industry Challenges
- Veterinary Feed Directive Compliance:Antibiotic growth promoter phase-out timelines under national veterinary authorities demand rapid reformulation without compromising feed conversion ratios.
- Specialized Nutritionist Scarcity:Tropical swine diet formulation expertise concentrates in South Africa and Nigeria, leaving secondary markets dependent on remote technical support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | African Swine Feed Market |
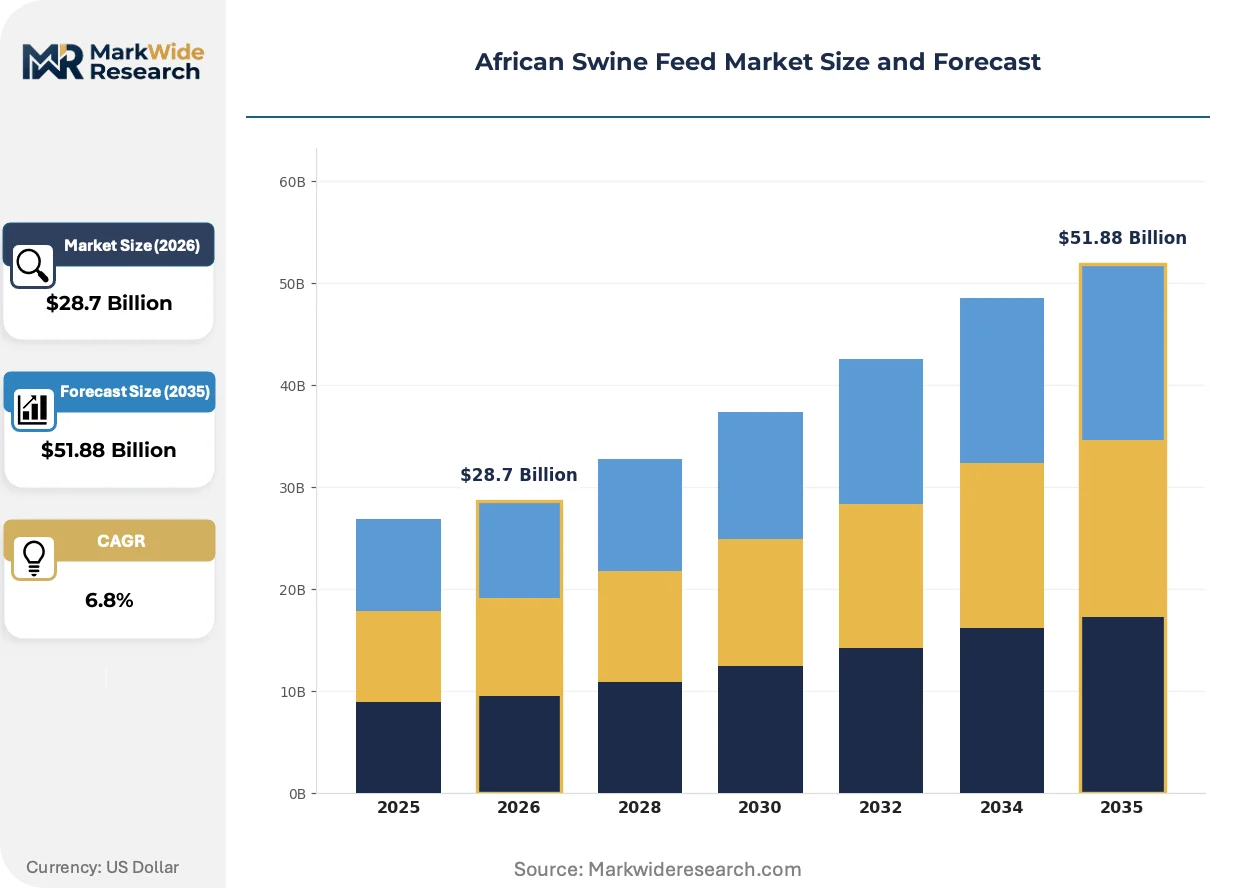
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Corn, Soybean Meal, Wheat, Barley Additive Type: Vitamins, Minerals, Enzymes, Probiotics Formulation Type: Complete Feed, Supplementary Feed, Concentrate, Premix Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | Cargill Incorporated, Nutreco NV, Alltech Inc, Novus International, Kemin Industries Inc, Serfco Feeds, Elanc, Novafeeds, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
African Swine Feed Market Strategic Shifts
Feed manufacturing across Africa is pivoting toward precision nutrition and localized ingredient sourcing as integrators seek to decouple from volatile global commodity flows while meeting tightening export residue standards.
Exogenous enzyme cocktails targeting non-starch polysaccharides in sorghum-based diets are absorbing the technical risk of coarse grain substitution previously considered incompatible with commercial feed conversion targets. Large-scale integrators in Nigeria and Kenya are piloting these formulations at 15-20% inclusion rates, compressing the cost premium against corn-based rations from historical levels.
South Africa's Department of Agriculture, Land Reform and Rural Development has tightened veterinary drug residue monitoring protocols for pork destined for European markets, triggering mandatory feed chain documentation from mill to farm gate. Exporters are responding by segregating production lines and investing in third-party certified premix sourcing, elevating compliance costs for non-integrated operators.
Contracted feed supply arrangements are displacing spot market procurement among commercial farms exceeding 5,000 head capacity, locking in volume commitments with millers in exchange for price hedging. This consolidation of purchasing power concentrates in Nigeria's southwestern intensive production zones, squeezing independent compounders dependent on fragmented smallholder demand.
African Swine Feed Market Segmentation
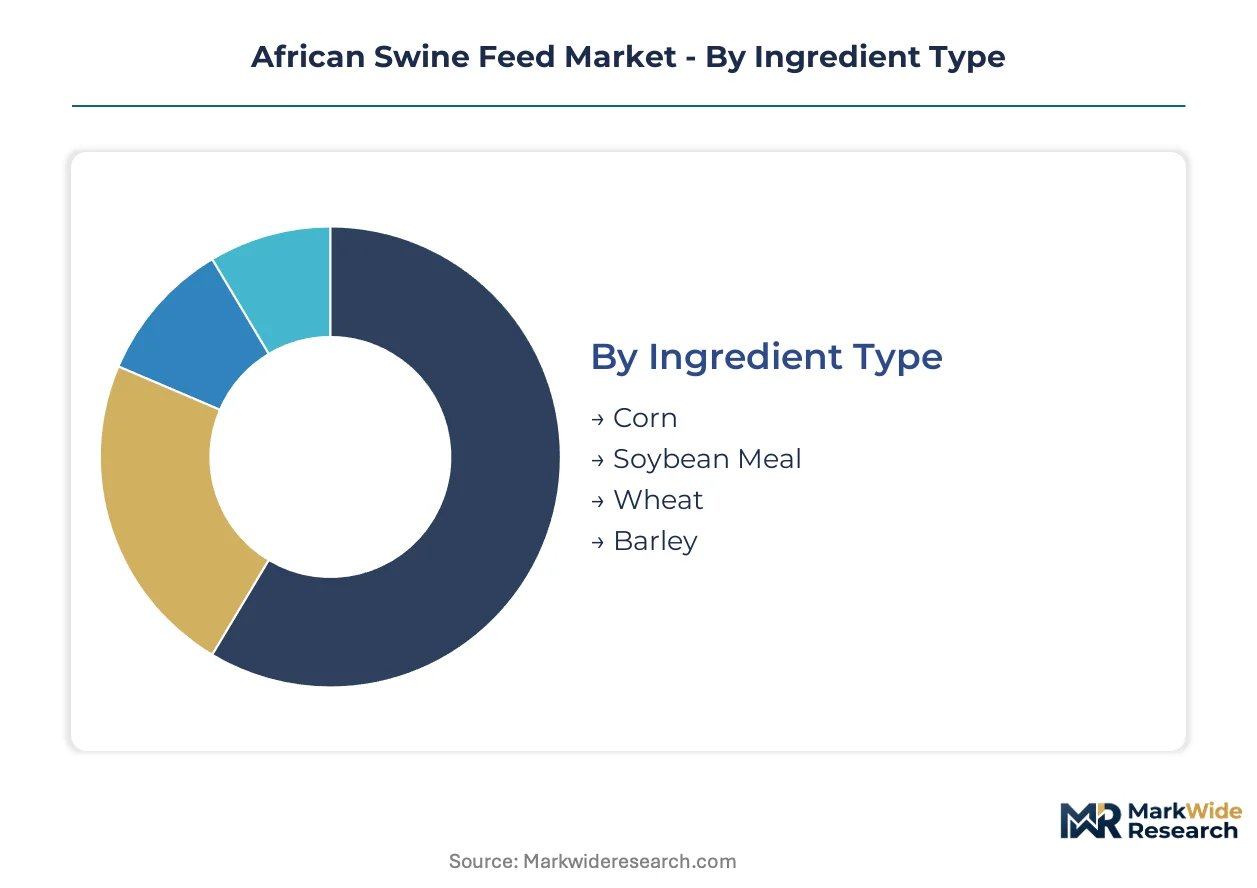
Ingredient sourcing decisions dominate feed procurement economics across Sub-Saharan Africa, where regional grain availability and protein concentrate localization determine formulation feasibility. Commercial integrators segment their supplier base by nutritional density, digestibility coefficients, and mycotoxin risk profiles rather than commodity price alone.
Ingredient Type:
Cost tier structures procurement priorities, with energy density and protein availability commanding premium allocations in commercial rations.
- Corn:Delivers 3,200-3,400 kcal ME per kilogram with 8-10% crude protein, forming the basal energy matrix for Nigerian and Kenyan intensive operations. Demand concentrates in southwestern Nigeria's 5,000+ head farms, where feed conversion ratio targets below 2.8:1 require consistent starch digestibility.
- Soybean Meal:Supplies 44-48% crude protein with balanced lysine-methionine profiles for grower-finisher phases. South African oilseed crushing expansion is localizing supply for Zambia's emerging commercial sector, displacing imported Argentine meal.
- Wheat:Offers intermediate energy density with higher non-starch polysaccharide content, requiring xylanase supplementation in Ethiopian pilot programs.
- Barley:Provides lower energy value but superior fiber handling in gestation diets, sourced primarily from Moroccan trade flows into West African markets.
Volume sits with corn; growth tilts toward soybean meal as regional crushing capacity expands.
Additive Type:
Application specificity drives additive selection, with growth stage nutrition and climate stress management dicting inclusion rates.
- Enzymes:Phytase and xylanase cocktails unlock phosphorus availability and fiber digestion in sorghum-millet substitutions. Nigerian integrators piloting 15-20% coarse grain inclusion report cost compression against corn-based formulations without sacrificing feed conversion targets.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex premixes prevent deficiency syndromes in tropical heat stress conditions. Import dependency from European suppliers exposes compounders to currency fluctuation and shipping disruptions.
- Minerals:Trace element precision in calcium-phosphorus ratios supports bone development in high-lean-gain genetic lines.
- Probiotics:Yeast-based and bacterial cultures address gut health challenges where antibiotic growth promoter phase-out timelines are tightening.
Procurement prioritizes enzymes for cost reduction; regulatory pressure accelerates probiotic substitution fastest.
Formulation Type:
Customer scale determines formulation complexity, with integration depth dicting whether farms blend on-site or purchase finished rations.
- Complete Feed:Nutritionally balanced rations delivered ready-to-feed, capturing 14-18% crude protein and 0.8-1.0% lysine specifications. Nigeria's southwestern intensive zones drive demand as non-technical operators avoid on-farm mixing errors.
- Premix:Micro-dosed mineral and vitamin concentrates requiring dilution, delivering disproportionate margin pools through technical expertise concentration. South African and Nigerian nutritionist scarcity limits penetration in secondary markets.
- Concentrate:Protein-energy bases requiring grain dilution, popular among Ghanaian cooperatives with localized maize sourcing.
- Supplementary Feed:Targeted nutrient top-dressing for specific production phases or recovery protocols.
Revenue concentrates in complete feed; premix expansion depends on mobile distribution network buildout.
Distribution Channel:
Supply chain configuration determines reach economics, with farm scale and geographic isolation fragmenting channel preference.
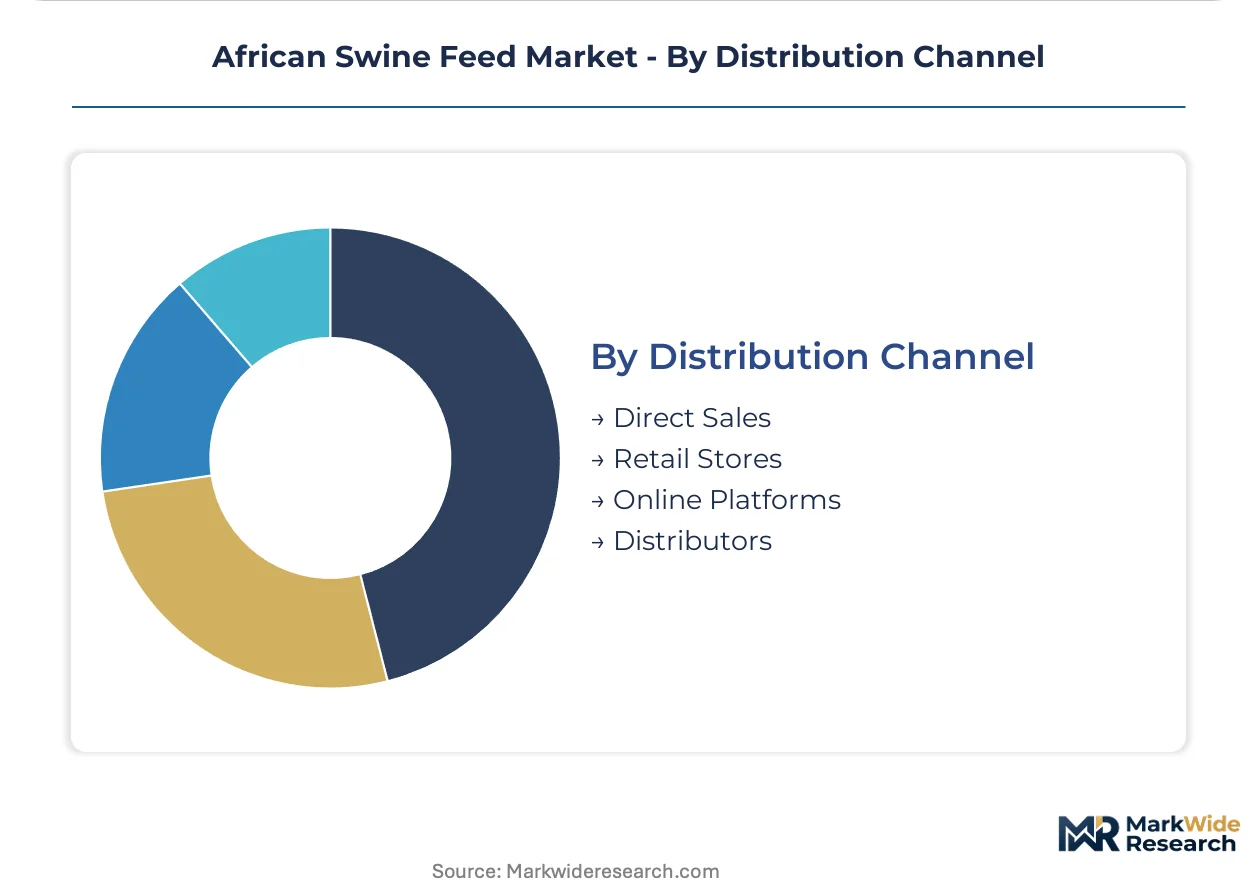
- Distributors:Aggregator networks with veterinary-supervised handling infrastructure, dominating Nigerian and Kenyan formal sector procurement. Biosecurity-aligned feed handling investments are redirecting capital toward traceable supply chains.
- Direct Sales:Mill-to-farm contracts locking volume commitments for operations exceeding 5,000 head, squeezing independent compounders dependent on fragmented smallholder demand.
- Retail Stores:Agro-dealer networks serving sub-commercial producers with bagged product in peri-urban zones.
- Online Platforms:Emerging order consolidation tools for premix and additive procurement, bypassing traditional markups in Ghana and Côte d'Ivoire.
Margin pools concentrate with distributors; online platforms are gaining share fastest among tech-enabled cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn surplus zones in Nigeria's southwestern belt anchor feed formulation economics across West Africa, with regional crushing capacity in South Africa and Zambia reshaping protein concentrate availability.
Nigeria
Intensive operations exceeding 5,000 head in Ogun and Oyo states drive compound feed procurement as commercial farms seek feed conversion ratios below 2.8:1. NAFDAC enforces EU-aligned mycotoxin thresholds that disqualify substantial local grain harvests from export-oriented production. Lagos-Ibadan corridor feed mills are consolidating purchasing power through contracted supply arrangements that lock volume commitments.
South Africa
Regional oilseed crushing expansion in industrial development zones is localizing soybean meal supply for domestic integrators and neighboring export markets. The Department of Agriculture, Land Reform and Rural Development mandates veterinary drug residue monitoring protocols for European market access. Gauteng and Mpumalanga feed manufacturers are segregating production lines to satisfy third-party certified premix sourcing requirements.
Kenya
FAO/OIE harmonized disease surveillance protocols are accelerating formal sector biosecurity investments among Rift Valley commercial pig farms. National veterinary authorities supervise feed handling standards that align with African swine fever containment frameworks. Nairobi peri-urban zones concentrate distributor networks with veterinary-supervised infrastructure for traceable procurement.
Ethiopia
Orthodox dietary restrictions have historically constrained formal pork production, yet urban consumption diversification is creating first-mover positioning for feed suppliers. The country's national veterinary regulator is developing import permitting frameworks for premix and additive categories. Addis Ababa and surrounding highland areas host pilot programs testing xylanase-supplemented wheat formulations for gestation diets.
Ghana
Mobile premix distribution networks are bypassing traditional distributor markups by delivering micro-dosed mineral packs directly to smallholder cooperatives. National food and drug administration protocols govern product registration for imported vitamin concentrates. Accra-Tema metropolitan feed channels are fragmenting between tech-enabled online platforms and legacy agro-dealer networks serving sub-commercial producers.
African Swine Feed Market Competitive Environment
Global majors compete with regional champions across formulation expertise and grain origination networks, producing a tiered structure where multinational compounders hold premium positions while local millers capture volume through price accessibility. Three archetypes dominate: integrated grain traders with crushing assets, premix specialists concentrating technical nutrition capabilities, and additive innovators targeting tropical climate gut health challenges. Capacity expansion in regional oilseed processing and strategic partnerships for enzyme licensing represent the primary competitive moves reshaping positioning.
Within the premix specialization tier, Nutreco NV and Kemin Industries Inc exemplify technical expertise concentration that commands disproportionate margin pools through trace mineral precision. Cargill Incorporated anchors the integrated grain trader archetype with continental origination networks. Among additive innovators, Alltech Inc occupies a position representing yeast-based portfolio development for digestibility optimization in coarse grain formulations.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Nutreco NV |
| Alltech Inc |
| Novus International |
| Kemin Industries Inc |
| Serfco Feeds |
| Elanc |
| Novafeeds |
| Elanco |
| Others |
Value Chain & Pricing Dynamics
Backward integration into soybean crushing anchors supply positioning for South African and Zambian compounders, simultaneously securing protein concentrate supply and compressing formulation costs against import-dependent competitors. This upstream control over lysine-rich inputs translates directly into pricing power when negotiating with Nigerian and Kenyan integrators facing volatile corn markets.
Pricing Analysis
Technical service bundling separates premium premix suppliers from commodity compounders, with Nutreco NV and Kemin Industries embedding nutritionist advisory hours into contracted rates while independent millers strip out support to hit spot-market price points. Price differentiation hinges on mycotoxin certification grade and volume scale commitments above 500 metric tons annually. Cost compression in economy-tier complete feeds is intensifying because coarse grain substitution with enzyme supplementation erodes the digestibility premium historically commanded by corn-based formulations. Smallholder cooperatives in Ghana and Côte d'Ivoire exhibit highest price sensitivity, while Nigerian integrators exceeding 5,000 head prioritize feed conversion ratio performance over per-kilogram cost.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian vitamin premix exporters, exposing African compounders to currency fluctuation and shipping disruptions when sourcing fat-soluble and B-complex concentrates. Geographic supply concentration centers on South Africa for oilseed crushing, Zambia for emerging protein processing, and Nigeria for basal grain origination. Raw material dependencies rest on corn, soybean meal, and sorghum-millet blends as climate-adaptive substitutes. Supply chain risk manifests as commodity price volatility transmitted through weather-induced harvest shocks in the Sahel and East African highlands. Distribution runs through veterinary-supervised aggregator networks in Nigeria and Kenya, with direct mill-to-farm contracts displacing spot procurement among large-scale integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-supplemented coarse grain formulations are displacing corn-centric legacy rations as Nigerian and Kenyan integrators pilot sorghum-millet inclusions at commercial scale. This technology transition rewards suppliers with localized ingredient sourcing capabilities and technical formulation expertise.
For Market Incumbents: Cement regional crushing capacity advantages in South African industrial development zones before Zambian competitors scale protein concentrate supply. Lock in multi-year offtake agreements with Nigerian integrators exceeding 5,000 head to defend against mobile premix distributors bypassing traditional channels. Prioritize third-party mycotoxin certification investments to maintain European market access as NAFDAC tightens residue monitoring protocols.
For New Entrants and Emerging Players: The premium-to-economy price gap in Ethiopian feed supply offers first-mover positioning as Orthodox dietary restrictions erode and urban consumption diversifies. Target mobile premix distribution to Ghanaian and Ivorian smallholder cooperatives, bypassing legacy agro-dealer markups through agent networks delivering micro-dosed mineral packs. Anchor go-to-market strategy on enzyme licensing partnerships that unlock coarse grain digestibility without captive R&D investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated grain-trader-acquirer archetypes seeking crushing assets and origination networks across Sub-Saharan Africa. Long-term viability favors compounders with backward integration into regional oilseed processing and biosecurity-aligned feed handling infrastructure. Watch FAO/OIE harmonization progress as the inflection signal—accelerated disease surveillance protocol adoption will consolidate formal sector procurement and displace fragmented smallholder supply channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Oilseed Crushing Expansion | South African industrial development zones offer tax relief that localizes protein concentrate supply for Nigerian integrators. |
| Enzyme Licensing Partnership | Phytase and xylanase technology access enables coarse grain substitution without compromising feed conversion targets. |
| Mobile Premix Distribution Network | Agent models delivering micro-dosed mineral packs bypass traditional distributor markups in Ghana and Côte d'Ivoire. |
| Third-Party Mycotoxin Certification | EU-aligned testing protocols under NAFDAC preserve European market access for export-oriented Nigerian pork producers. |
| Contracted Supply Arrangements | Volume commitments with millers lock in price hedging for Kenyan and Nigerian operations exceeding 5,000 head. |
Study Parameters
FAO/OIE surveillance reports, national veterinary authority filings, and oilseed trade statistics formed the secondary backbone for this analysis. Primary interviews with feed mill operations managers, commercial farm procurement leads, and premix distribution agents were combined with secondary validation from customs records and crushing capacity databases. Bottom-up and top-down triangulation cross-checked regional formulation demand against ingredient supply flows.
Bottom-up volume modeling aggregated farm-level feed consumption by integration scale, while top-down analysis tracked oilseed crushing capacity expansion and enzyme adoption rates across the projection horizon. Segmentation dimensions included ingredient type, additive category, formulation complexity, and distribution channel structure. CAGRs were derived from trend extrapolation of formal sector consolidation and coarse grain substitution elasticities, with Nigerian and South African regulatory trajectory serving as key forecast inputs.
Inputs from national veterinary authorities and regional oilseed processors were available through the study window; gaps in smallholder cooperative consumption data introduce uncertainty bands around informal sector estimates. Forecasts reflect assumptions regarding FAO/OIE protocol adoption speed and crushing capacity commissioning timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Italy Compound Feed Market