
 Asia-Pacific Poultry Meat Market | 2026-2036
Asia-Pacific Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Poultry Meat Market Outlook
Contract grower financing and feed-cost hedging services is pivoting how poultry volumes move from farm to processor across the Asia-Pacific region. Charoen Pokphand Foods Public Co. Ltd anchors Thailand's vertically integrated broiler supply through captive hatchery and feed mill networks. Wen's Food Group Co. Ltd dominates southern China's live-bird and chilled-meat channels with province-level slaughterhouse density. Suguna Foods Private Limited leverages India's smallholder contract farming model to sustain broiler output across Tamil Nadu and Karnataka.
Asia-Pacific poultry meat encompasses avian muscle tissue harvested from broilers, turkeys, and ducks, typically processed to carcass, cut, or mechanically separated forms with moisture content between 65% and 75% and protein density near 20% by weight; it serves as a primary animal protein input for retail, foodservice, and further-processed manufacturing. Broilers occupy the volume core across every major Asia-Pacific market, while vacuum-packed retail formats capture expanding margin pools in Japan and South Korea as freshness signaling intensifies. Food processors represent the fastest-growing end-user channel, driven by nugget, sausage, and ready-meal outsourcing from quick-service brands.
China's SAMR enforces GB standards for veterinary drug residues and labeling compliance, while Japan's MAFF and PMDA jointly administer import sanitary requirements and domestic processing audits; Australia's FSANZ and New Zealand's MPI operate parallel trans-Tasman standards that shape access for Thai and Brazilian exporters. India's FSSAI has tightened cold-chain licensing for interstate poultry movement, compressing informal slaughter operations. Stakeholders must monitor divergence between national antibiotic thresholds and packaging disclosure rules when configuring multi-country supply strategies.
Market Dynamics
Chilled poultry distribution networks across Southeast Asia are consolidating as cold chain infrastructure investments compress spoilage windows and extend shelf-stable radius from processing plants to urban retail endpoints.
Growth Catalysts
- Quick-service restaurant procurement:Indonesia's QSR sector is scaling centralized poultry sourcing through dedicated supplier agreements with integrated processors.
- SAMR food safety standards:China's revised GB veterinary residue limits are forcing facility upgrades that favor capitalized producers over informal slaughter operations.
- Feed mill technology:Precision formulation systems are reducing FCR variance across Thai contract grower networks.
Market Restraints
- Soybean meal price volatility:Feed input costs swing with Brazilian export timing, compressing grower margins in Vietnam and the Philippines.
- Import concentration:Grandparent stock genetics flow through three global suppliers, creating biosecurity vulnerability for Asia-Pacific hatcheries.
- Antibiotic residue thresholds:Japan's PMDA monitoring protocols reject shipments exceeding domestic MRLs, forcing dual-standard processing lines.
Strategic Opportunities
- Vietnam urban retail:Modern trade penetration in Ho Chi Minh City and Hanoi remains below Thai levels, creating vacuum-packed chilled meat expansion room.
- Mechanically separated poultry:Further-processed manufacturing demand from nugget and sausage exporters is outpacing dedicated MSC supply.
- India FSSAI cold-chain licensing:Interstate movement rules favor licensed operators, consolidating share toward organized players in Tamil Nadu and Karnataka.
Industry Challenges
- Veterinary talent scarcity:Regional shortage of poultry health specialists delays disease response in Indonesian contract farming zones.
- Slaughterhouse capex cycles:Automated evisceration and air-chilling systems require 7-10 year payback periods that strain mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Poultry Meat Market |
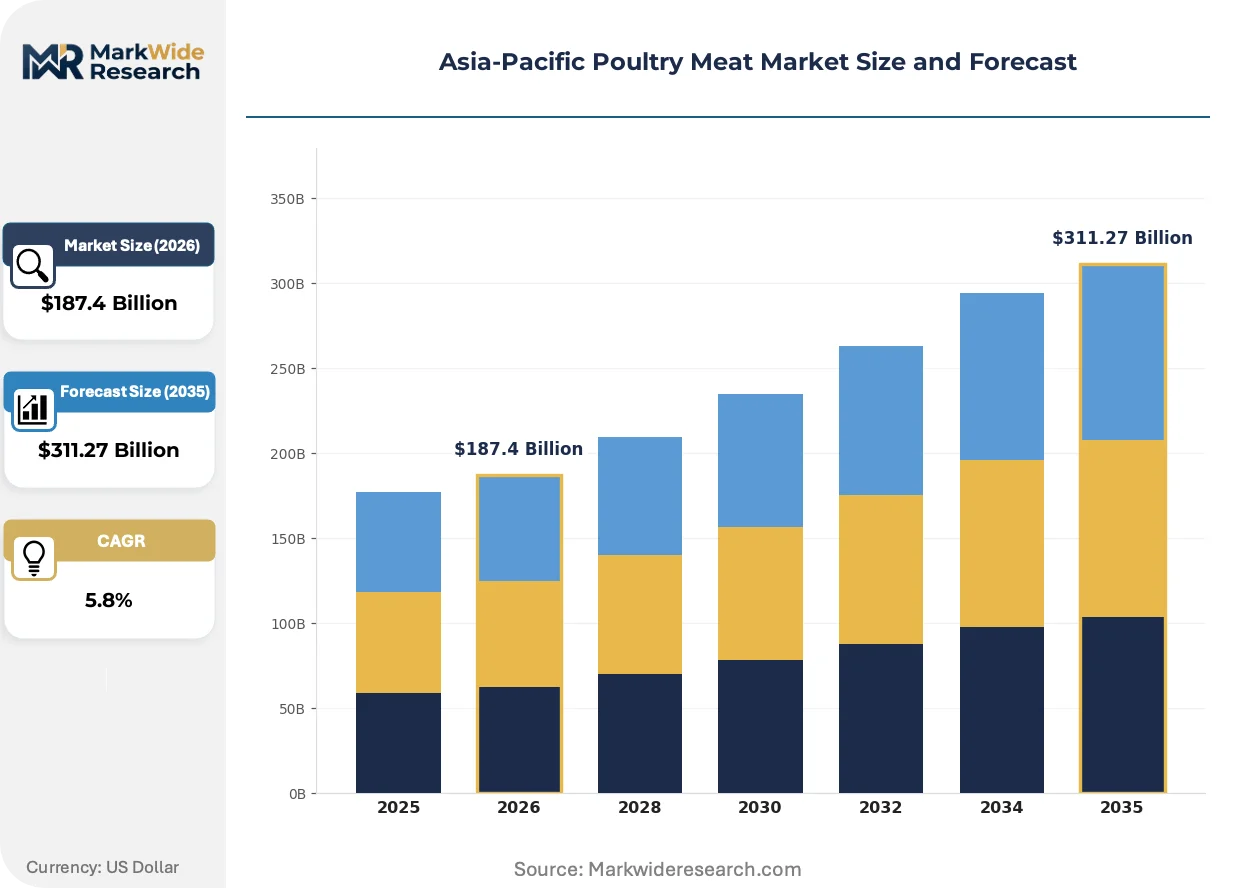
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Turkeys, Ducks, Other Distribution Channel: Supermarkets, Online, Wholesale, Butcher Shops Packaging Type: Plastic Trays, Vacuum Packs, Cans, Bags End User: Restaurants, Retailers, Food Processors, Households |
| Companies Covered | Suguna Foods Private Limited, Wen's Food Group Co. Ltd, Charoen Pokphand Foods Public Co. Ltd, Fujian Sunner Development Co. Ltd, NH Foods Ltd, New Hope Liuhe Co. Ltd, Tyson Foods Inc., BRF S.A., Cargill Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Poultry Meat Market Strategic Shifts
Processing automation and regulatory disclosure requirements are compressing traditional batch-based operations toward continuous-flow systems with real-time traceability.
Computer vision grading systems are automating carcass quality assessment at line speeds exceeding 140 birds per minute. Thai and Malaysian processors are retrofitting existing plants with these systems to reduce manual inspection headcount. The technology is automating defect detection that previously required skilled operatives, shifting labor toward maintenance and calibration roles.
Japan's MAFF import sanitary requirements now mandate country-of-origin labeling down to the hatchery level for chilled poultry entering foodservice channels. This industrial consequence forces exporters to segment supply chains by certification grade rather than pooling volumes. Australian and New Zealand processors are responding by establishing dedicated Japan-compliant production lines with segregated cold storage.
Central kitchen consolidation among Southeast Asian QSR chains is displacing traditional wet-market sourcing for raw poultry inputs. Franchise operators in Jakarta and Manila now require pre-portioned, vacuum-sealed cuts delivered direct to commissary facilities. Vietnam's urban retail channels exhibit the fastest behavioral transition, with modern trade share of chilled poultry climbing fastest in Hanoi and Ho Chi Minh City convenience store networks.
Asia-Pacific Poultry Meat Market Segmentation
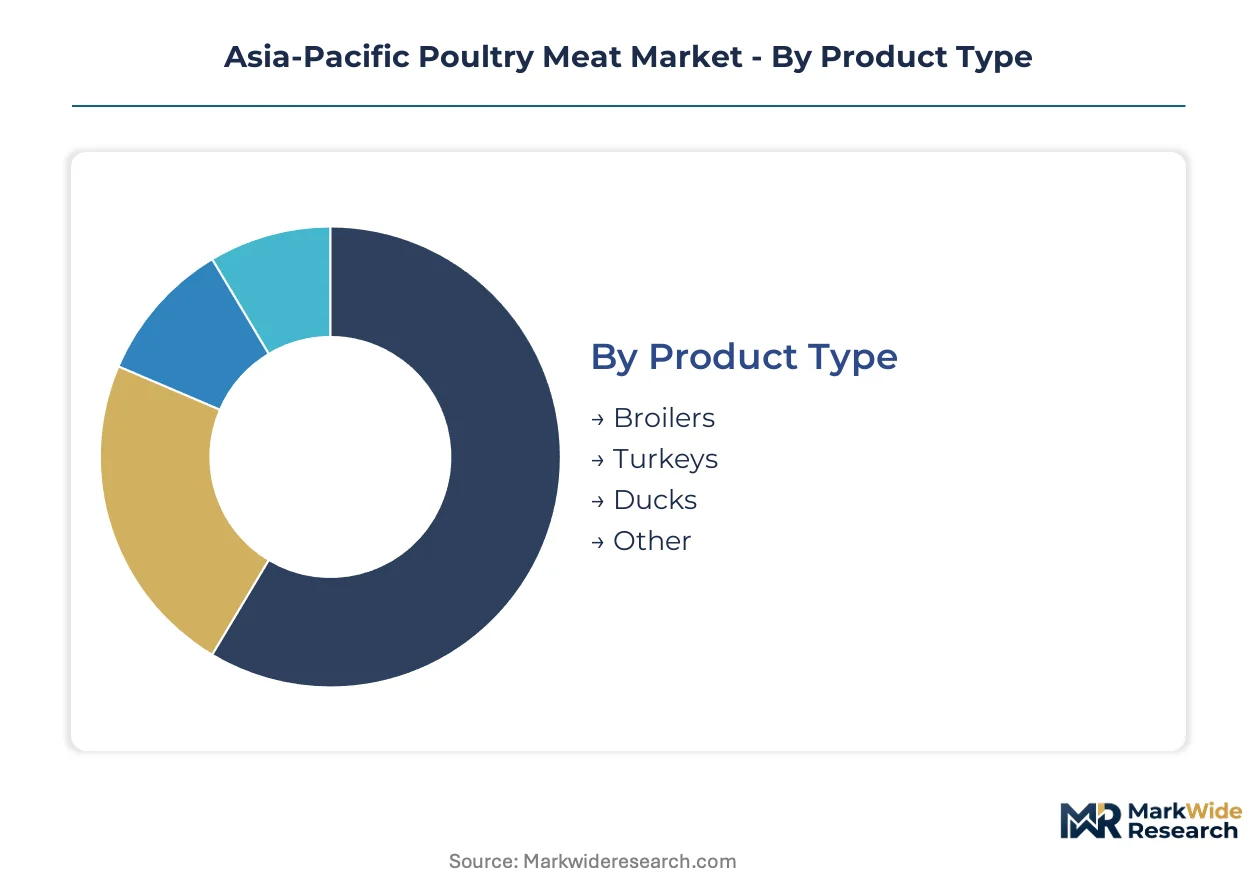
Asia-Pacific poultry meat segmentation reveals how product form, channel access, and packaging technology determine margin capture across fragmented national markets. Distinct consumption patterns in Japan's precision retail versus Indonesia's foodservice procurement create divergent segment priorities for processors configuring regional portfolios.
Product Type:
Broilers operate as standalone commodity volume drivers, while turkeys and ducks embed into specialized processing channels and ethnic cuisine supply chains.
- Broilers:Young chickens harvested at 35-42 days yield tender muscle tissue with protein density near 20% by weight and moisture content between 65% and 75%. Indonesian quick-service restaurants and Vietnamese urban retail channels concentrate procurement for whole carcass and cut formats.
- Turkeys:Heavier avian species processed to breast and thigh cuts serve premium deli and further-processed manufacturing segments in Japan and South Korea. Demand clusters around year-end consumption peaks and hotel catering contracts.
- Ducks:Waterfowl meat with higher fat deposition suits roasting and confit applications across southern China and Hong Kong foodservice.
- Other:Goose, quail, and specialty avian proteins occupy niche ceremonial and medicinal markets in Taiwan and mainland China.
Broilers lead volumes today; vacuum-packed chilled broiler cuts are gaining share fastest in Southeast Asian modern trade expansion.
Distribution Channel:
Channel selection maps directly to cold chain maturity, with ambient-capable wholesale networks dominating where refrigeration infrastructure remains underdeveloped.
- Supermarkets:Temperature-controlled retail formats with dedicated meat counters and self-service chilled cabinets capture margin premiums in Tokyo, Seoul, and Singapore. Japanese retailers enforce vacuum-packaging standards that extend shelf life and reduce markdown frequency.
- Online:E-commerce platforms with last-mile cold delivery infrastructure are expanding fastest in Shanghai, Jakarta, and Bangkok metropolitan zones. Quick-commerce operators promise 30-minute chilled poultry delivery to urban households.
- Wholesale:Wet-market intermediaries and foodservice distributors move bulk carcass and cut volumes through ambient or basic chilled logistics across Philippines and rural Indonesia.
- Butcher Shops:Independent fresh-meat counters with live-bird or same-day slaughter service retain loyalty among older consumers and traditional cuisine practitioners in Vietnam and India.
Supermarkets anchor value capture in developed Northeast Asian markets; online channels are expanding most quickly across Southeast Asian megacities.
Packaging Type:
Packaging technology stratifies along freshness signaling intensity, with premium formats commanding shelf placement in Japan and South Korea while basic configurations dominate price-sensitive segments.
- Vacuum Packs:Modified-atmosphere packaging with oxygen barrier films extends chilled shelf life to 14-21 days and enables centralized processing for distant retail endpoints. Japanese MAFF import requirements mandate hatchery-level traceability labeling on vacuum-packed chilled poultry entering foodservice.
- Plastic Trays:Overwrapped foam or PET containers with permeable film dominate Southeast Asian supermarket self-service cases where turnover velocity reduces spoilage risk.
- Bags:Polyethylene or nylon pouches for frozen whole birds and bulk cuts serve institutional procurement and rural retail stocking.
- Cans:Retort-processed poultry products occupy emergency preparedness and military supply niches with minimal fresh-market penetration.
Vacuum packs command premium positioning in Japan and South Korea; plastic trays retain volume dominance across Southeast Asian modern trade.
End User:
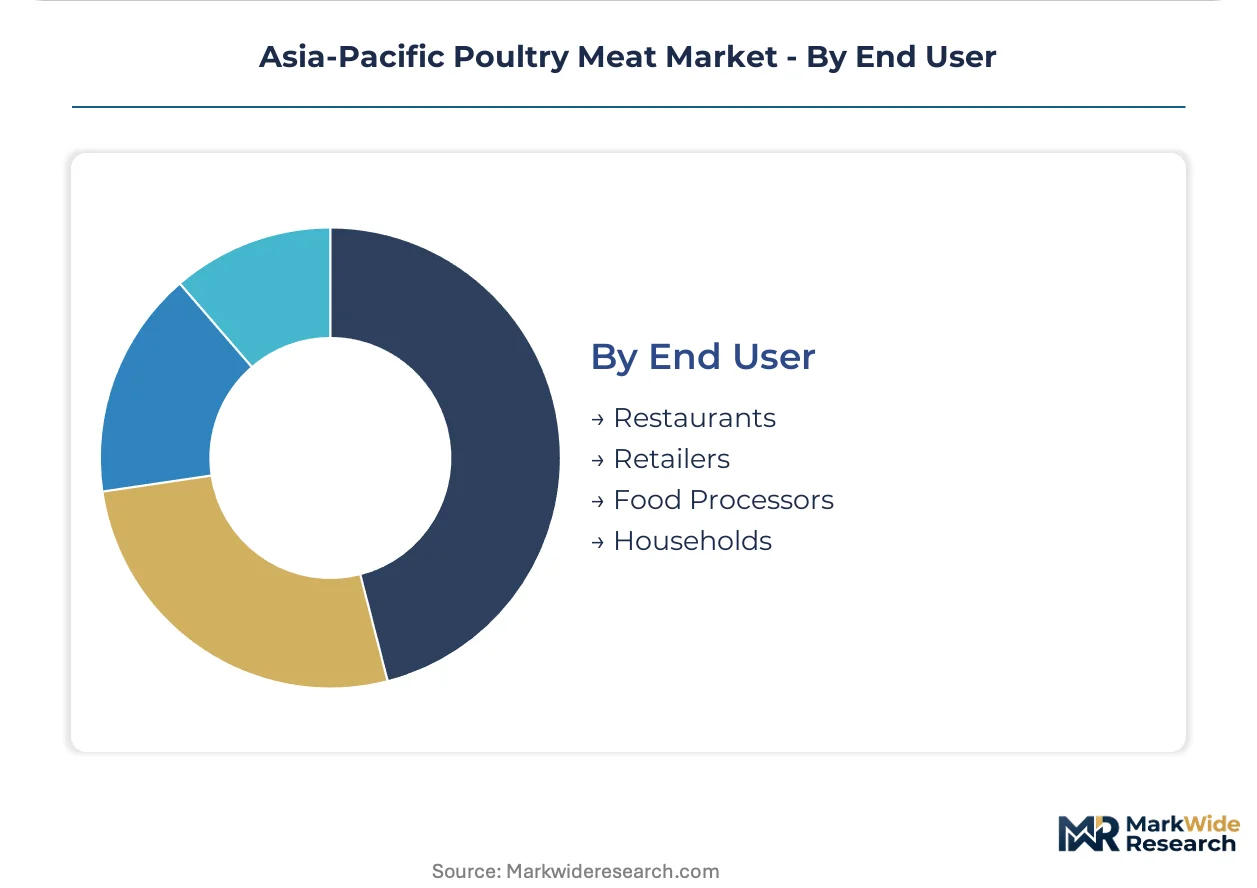
End-user segmentation tracks the shift from household cooking toward prepared-food outsourcing, with food processors capturing expanding share from quick-service brand consolidation.
- Food Processors:Dedicated nugget, sausage, and ready-meal manufacturers source mechanically separated poultry and pre-portioned cuts through contracted supply agreements. Central kitchen consolidation among Indonesian and Philippine QSR chains is displacing traditional wet-market sourcing.
- Restaurants:Full-service and quick-service operators in Jakarta, Manila, and Ho Chi Minh City now require pre-portioned, vacuum-sealed cuts delivered direct to commissary facilities.
- Retailers:Supermarket and convenience store chains in Vietnam's urban corridors exhibit the fastest behavioral transition, with modern trade share of chilled poultry climbing fastest in Hanoi and Ho Chi Minh City networks.
- Households:Direct consumer purchase through wet markets and traditional butcher counters persists in India and rural Indonesia where cold chain penetration remains limited.
Food processors are expanding most quickly through QSR supply chain consolidation; households retain volume leadership in South Asian markets with fragmented retail infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing poultry processing capacity across Asia-Pacific as compliance cost gaps between national regimes widen. Producers migrate toward jurisdictions with streamlined veterinary licensing while maintaining export access to premium markets through dedicated certification lines.
China
Urban retail modernization and quick-service restaurant expansion drive chilled broiler demand in Shanghai and Guangzhou corridors. SAMR's revised GB standards for veterinary drug residues force facility upgrades that disadvantage small-scale slaughter operations. Wen's Food Group anchors southern China's live-bird and chilled-meat channels through province-level slaughterhouse density in Guangdong and Fujian.
Japan
Hotel catering contracts and year-end consumption peaks sustain premium turkey breast and thigh cut demand. MAFF and PMDA jointly administer import sanitary requirements with hatchery-level traceability mandates for chilled poultry entering foodservice. Australian and New Zealand processors operate dedicated Japan-compliant production lines with segregated cold storage at export facilities.
Thailand
Contract grower networks supply integrated processors serving both domestic retail and export manufacturing channels. Charoen Pokphand Foods anchors vertically integrated broiler supply through captive hatchery and feed mill infrastructure. Bangkok-based processors retrofit plants with computer vision grading systems automating carcass quality assessment at line speeds exceeding 140 birds per minute.
Indonesia
Quick-service restaurant procurement scales through centralized sourcing agreements with integrated processors in Jakarta and Surabaya. Central kitchen consolidation among franchise operators displaces traditional wet-market sourcing for raw poultry inputs. Veterinary talent scarcity delays disease response in contract farming zones across Java and Sumatra.
Vietnam
Modern trade penetration in Ho Chi Minh City and Hanoi creates vacuum-packed chilled meat expansion opportunities below Thai saturation levels. Urban retail channels exhibit the fastest behavioral transition toward pre-portioned, vacuum-sealed cuts delivered direct to commissary facilities. Interstate cold-chain licensing under evolving regulatory frameworks favors organized operators over informal slaughter networks.
Asia-Pacific Poultry Meat Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated processors capturing foodservice procurement while independent growers supply fragmented wet-market channels. The market structure concentrates around three to five vertically integrated conglomerates controlling genetics, feed, and processing infrastructure. Strategic archetypes span captive hatchery-feed mill combinations, province-level slaughterhouse density operators, and smallholder contract farming coordinators. Dominant competitive moves include automated processing line retrofits and segregated cold storage investments for certification-grade export compliance.
Among Asia-Pacific-based integrated processors, Charoen Pokphand Foods Public Co. Ltd, Wen's Food Group Co. Ltd, and Suguna Foods Private Limited occupy distinct archetype positions. The Thai conglomerate represents captive supply chain control through hatchery and feed mill networks. The Chinese operator exemplifies province-level slaughterhouse density strategies in southern live-bird and chilled-meat channels. The Indian specialist anchors smallholder contract farming coordination across Tamil Nadu and Karnataka. These three structures illustrate how national market conditions shape viable competitive configurations.
| Leading Market Players |
|---|
| Suguna Foods Private Limited |
| Wen's Food Group Co. Ltd |
| Charoen Pokphand Foods Public Co. Ltd |
| Fujian Sunner Development Co. Ltd |
| NH Foods Ltd |
| New Hope Liuhe Co. Ltd |
| Tyson Foods Inc. |
| BRF S.A. |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors across Vietnam and Indonesia anchor supply discipline through informal credit networks that buffer feed cost spikes while limiting price transparency in contract negotiations. This ownership pattern concentrates pricing power with integrated Thai conglomerates that operate captive genetics and feed mill infrastructure, forcing smaller competitors to accept thinner margins or exit to cold-chain licensing requirements.
Pricing Analysis
Capacity additions in Thailand are reshaping price floors for chilled broiler exports across Southeast Asian modern trade channels. Three-tier pricing structure across premium, standard, and economy levels separates Japan-compliant vacuum-packed cuts from domestic supermarket trays and wet-market bulk sales. Price differentiation hinges on certification grade and cold-chain integrity, with SAMR-compliant lines commanding premiums over informal slaughter output. Cost compression in economy tiers is intensifying because Brazilian soybean meal timing swings feed input costs unpredictably. Quick-service restaurant procurement teams exhibit highest price sensitivity, while Japanese foodservice distributors prioritize traceability documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Bangkok, Ho Chi Minh City, and Jakarta operate hub-and-spoke patterns that extend shelf-stable radius as cold chain infrastructure matures. Geographic supply concentrates in Thailand, China, and Brazil, with grandparent stock genetics flowing through three global suppliers that create single-source vulnerability for Asia-Pacific hatcheries. Raw material dependencies rest on Brazilian soybean meal, Argentine corn, and domestic cassava alternatives. Distribution runs through integrated processor networks for QSR commissaries, while wet-market intermediaries retain ambient-capable wholesale channels in rural Philippines and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Japanese and South Korean buyers shift procurement toward hatchery-traceable chilled cuts that command sustained premiums over frozen commodity volumes.
For Market Incumbents: Acquire automated evisceration and air-chilling assets to compress payback periods below seven years and defend against Brazilian exporters establishing dedicated Japan-compliant production lines. Consolidate contract grower networks through feed-cost hedging services that lock in volume commitments before SAMR facility upgrades disqualify informal competitors. Channel control through central kitchen direct delivery agreements with Jakarta and Manila QSR chains limits wet-market displacement risk. For New Entrants and Emerging Players: Independent central kitchen operators in Vietnam's secondary cities represent the most penetrable buyer archetype as modern trade penetration lags Thai saturation levels. Target vacuum-packed chilled meat supply gaps in Hanoi convenience store networks where pre-portioned cut demand outpaces organized processor capacity. Go-to-market leverage rests on FSSAI cold-chain licensing compliance that barriers informal slaughter networks from interstate movement. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian smallholder contract farming coordinators with unconsolidated Tamil Nadu and Karnataka processing footprints. Long-term viability over the projection horizon favors operators with backward integration into captive hatchery and feed mill infrastructure that buffers input cost volatility. Watch Japan's PMDA antibiotic residue threshold enforcement as the inflection signal that accelerates dual-standard processing line investments across Thai export facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Line Retrofit | Computer vision grading systems at Thai plants reduce manual inspection headcount below 140 birds per minute thresholds. |
| Segregated Cold Storage Investment | Australian and New Zealand processors establish Japan-compliant production lines with dedicated hatchery-traceable inventory tracking. |
| Contract Grower Financing Expansion | Feed-cost hedging services through Charoen Pokphand Foods lock volume commitments across Thai broiler networks. |
| Central Kitchen Direct Partnership | Indonesian QSR chains in Jakarta displace wet-market sourcing through pre-portioned vacuum-sealed cut agreements. |
| FSSAI Cold-Chain Licensing Compliance | Interstate poultry movement rules in India consolidate share toward organized operators in Tamil Nadu and Karnataka. |
Study Parameters
Bottom-up food processor and QSR procurement modeling reconciled against top-down feed mill and hatchery capacity tracking forms the analytical core of this study. Primary interviews with contract farming coordinators, central kitchen procurement heads, cold-chain logistics operators, and veterinary compliance officers were validated against secondary sources including SAMR GB standard filings, Japan MAFF import sanitary requirement updates, FSSAI licensing registries, and Thai customs chilled poultry export records. Triangulation across these channels ensures volume estimates align with facility throughput capacities and regulatory compliance boundaries.
Input-output matrices map broiler live weight through processing yield coefficients, cold-chain loss rates, and channel-specific margin structures across the projection horizon. Segmentation dimensions include product form, packaging technology, distribution channel maturity, and end-user procurement consolidation patterns. CAGRs were derived from fitted growth curves against urban retail modernization indices and QSR outlet expansion trajectories. Industry-specific forecast inputs incorporate Brazilian soybean meal price volatility bands and grandparent stock import timing assumptions.
Inputs from regulatory filing databases and processor association disclosures were available through the study window; gaps in informal slaughter sector throughput data introduce uncertainty bands around India and Indonesia volume estimates. Forecasts reflect documented assumptions regarding cold chain infrastructure buildout rates and antibiotic residue threshold enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Chaga Mushroom Market