
 Cashew Market | 2026-2036
Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Cashew Market Intelligence
Automated steam-shelling technology is reshaping cashew processing economics by cutting labor dependency and kernel damage rates. Olam International Limited leverages integrated origination networks across West Africa to sustain supply security for its processing hubs. John B. Sanfilippo & Son Inc. anchors its competitive position through direct retail and private-label channel control in North America. Haldiram Foods International Private Limited dominates India's branded snack segment with roasted and flavored cashew portfolios.
Cashews are kidney-shaped seeds of Anacardium occidentale, typically containing 18% protein and 44% fat by weight, with shells requiring heat or steam treatment to release the edible kernel. The seed serves as a premium ingredient in confectionery, bakery, and plant-based dairy alternatives due to its creamy texture and neutral flavor profile. Whole Cashew commands premium pricing in gift and retail channels while Cashew Butter captures growth from clean-label spread demand in health food stores. Snack Producers represent the fastest-expanding end-user category as roasted and seasoned formats displace traditional nut mixes in convenience retail.
FDA food safety modernization rules and FSSAI labeling mandates shape processor compliance costs and export eligibility for Indian and Vietnamese suppliers. EU REACH chemical standards and EFSA mycotoxin limits determine European market access thresholds for raw kernel shipments. Stakeholders must monitor climate volatility in West African growing belts and processing automation ROI timelines to calibrate sourcing and capital deployment decisions.
Market Dynamics
Automated steam-shelling technology is compressing labor costs and kernel damage rates across Vietnamese and Indian processing clusters, while FSSAI fortification mandates redirect capital toward nutrient-enhanced product lines.
Growth Catalysts
- Plant-Based Protein Pivot:Snack producers are expanding roasted and flavored cashew portfolios as consumers substitute animal proteins with tree nuts in convenience retail formats.
- FSSAI Fortification Guidelines:India's food safety regulator mandates micronutrient enhancement, pushing processors to develop iron and zinc-fortified kernel offerings for domestic and export markets.
- Mechanized Shelling Diffusion:Vietnamese processors in Binh Phuoc province deploy automated steam-shelling lines that cut labor dependency and raise export-grade kernel recovery rates.
Market Restraints
- Raw Nut Price Volatility:West African supply interruptions from irregular rainfall patterns in Guinea-Bissau and Ivory Coast swing farmgate prices and squeeze processor margins.
- Processing Concentration Risk:Over sixty percent of shelled kernel output flows through Vietnam's Binh Phuoc cluster, creating single-point vulnerability to energy cost spikes or labor disruptions.
- EU Mycotoxin Thresholds:EFSA aflatoxin limits for raw kernel shipments impose testing burdens that disqualify smaller Indian and African exporters from European market access.
Strategic Opportunities
- Clean-Label Spread Formats:Cashew butter captures shelf space in North American health food channels as consumers reject palm oil and hydrogenated fat alternatives.
- West African Origin Branding:Direct-from-farm traceability programs in Ghana and Senegal allow premium positioning for single-origin kernels in European gift retail.
- PLI Scheme Alignment:India's production-linked incentive scheme for food processing subsidizes capital expenditure on automated grading and packaging lines.
Industry Challenges
- Shelling Technician Scarcity:Traditional hand-shelling expertise is disappearing faster than automated line operators can be trained, creating workforce transition friction in Indian processing hubs.
- FDA Compliance Timelines:Foreign Supplier Verification Program documentation requirements delay new supplier onboarding by four to six months for US-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cashew Market |
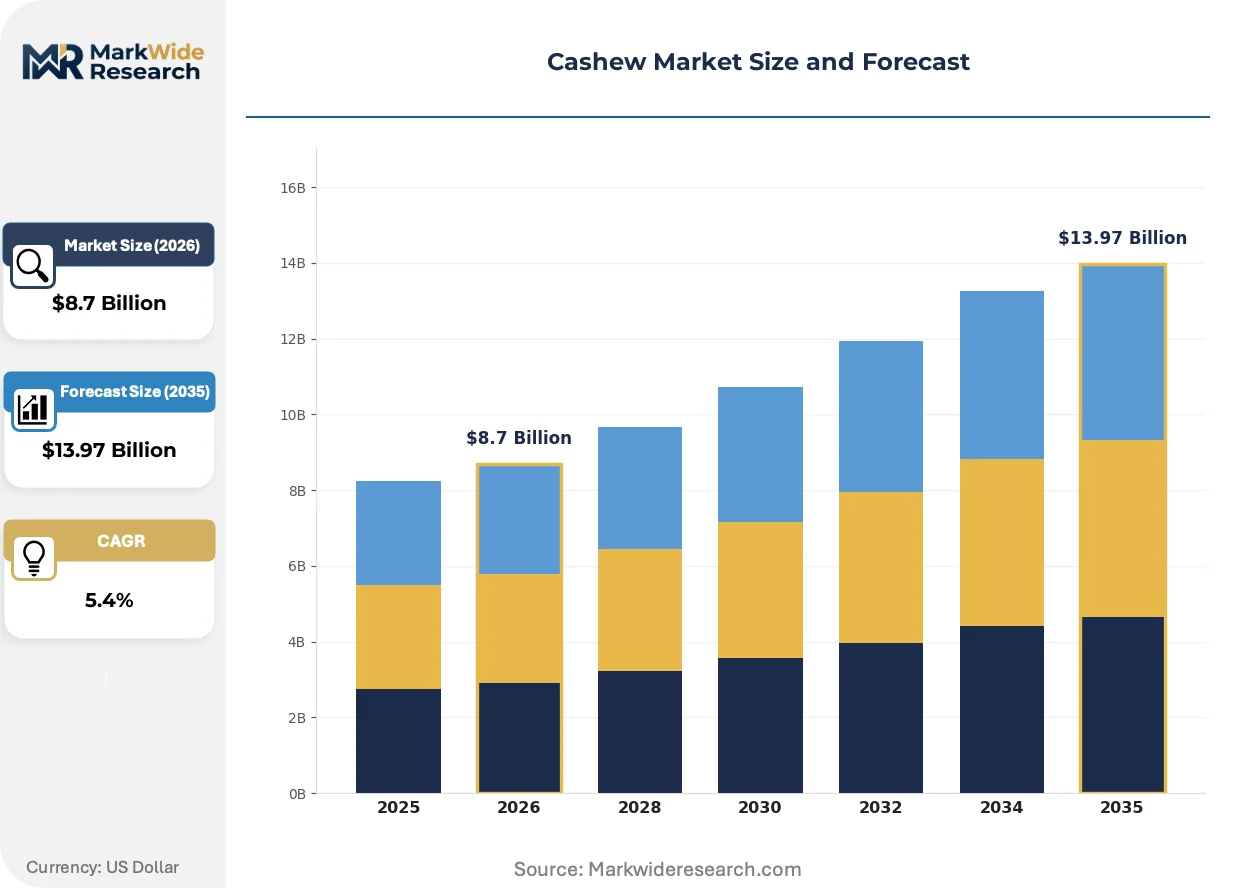
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Cashew, Cashew Pieces, Cashew Butter, Cashew Flour End User: Retail Consumers, Food Services, Food Manufacturers, Snack Producers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Application: Baking, Cooking, Confectionery, Nutraceuticals |
| Companies Covered | The Kraft Heinz Company, Vietnam Cashew Corporation (VINACAS), Nestlé S.A., John B. Sanfilippo & Son Inc., Haldiram Foods International Private Limited, Archer Daniels Midland Company, Olam International Limited, Shivam Cashew Industry, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cashew Market Strategic Shifts & Innovations
Processing automation and regulatory fortification mandates are converging to reshape competitive economics, while clean-label positioning opens new channel access for value-added formats.
Computer vision grading systems are digitizing kernel quality assessment at Vietnamese processing lines. Mid-scale processors in Binh Phuoc province adopt these systems to replace manual color-sorting teams. The technology is digitizing quality control workflows and compressing the time between shelling and export packing.
India's FSSAI fortification guidelines mandate iron, folic acid, and zinc enrichment in packaged nuts sold through retail channels. Processors must reformulate roasting protocols and labeling to comply, raising compliance costs but creating product differentiation in domestic supermarkets. Snack producers with existing fortified portfolios capture preferential placement in government school feeding programs.
Clean-label procurement criteria now dominate buyer negotiations in North American natural food channels. Retailers require single-ingredient roasted kernels or oil-free dry-roasted formats, displacing traditional oil-fried and seasoned mixes. This specification compression is most visible in Whole Foods and Sprouts Farmers Market private-label sourcing decisions.
Cashew Market Segmentation
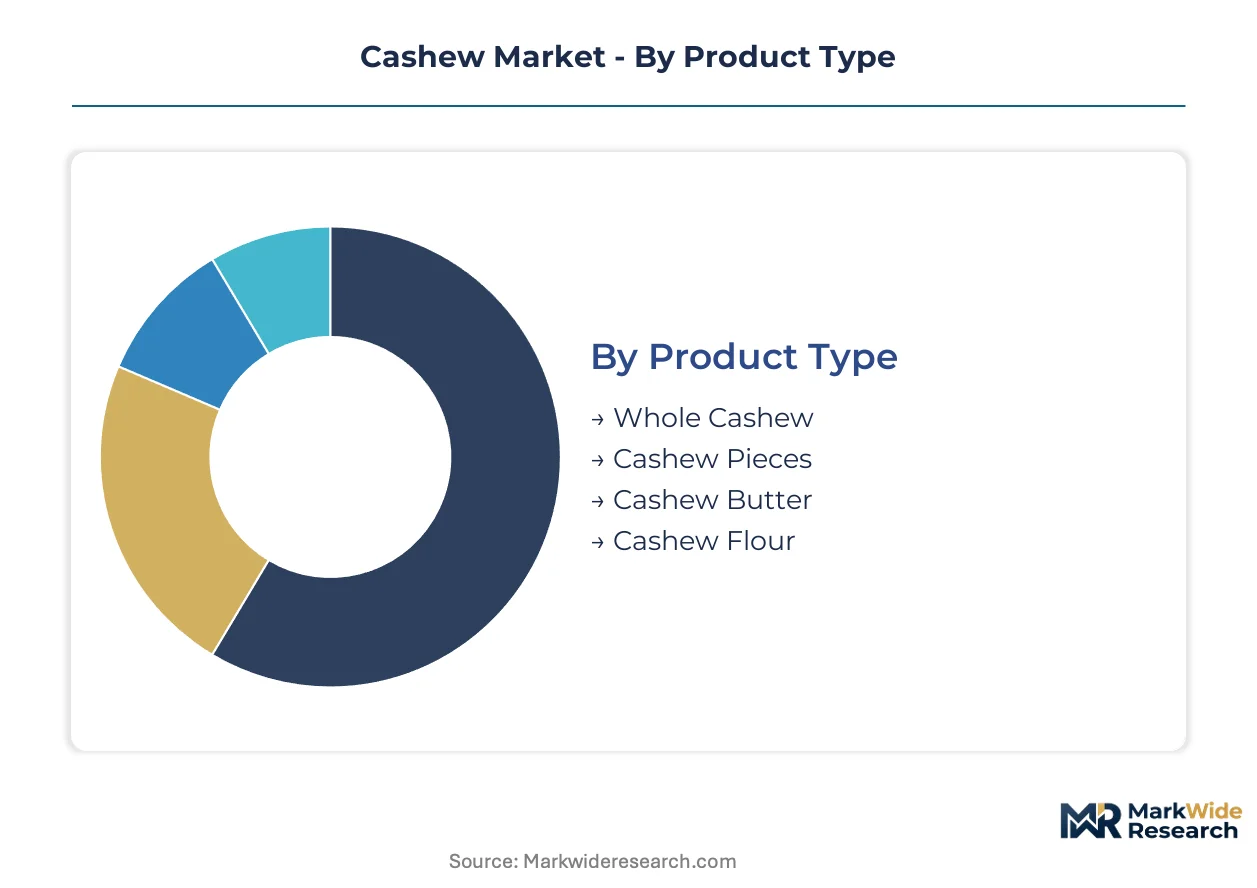
Cashew market segmentation reveals divergent margin profiles across product formats and channel access. Understanding these divisions helps processors allocate shelling capacity and roasting line investments toward the highest-return applications.
Product Type:
Use-case spectrum spans gift-grade whole kernels to industrial ingredient inputs, with value capture concentrated at opposite ends of the processing intensity curve.
- Whole Cashew:Intact kernels graded by size (W180 through W320) and color standards determine export premiums. Gift retail channels in Vietnam and India's urban centers absorb the highest-margin output, particularly during festival seasons when packaging costs justify price multiples over bulk commodity rates.
- Cashew Butter:Ground paste format with 95%+ kernel content serves clean-label spread demand in North American natural food channels. Single-ingredient positioning without palm oil or hydrogenated fats commands shelf space at Sprouts Farmers Market and Whole Foods private-label programs.
- Cashew Pieces:Broken kernel fragments from mechanical shelling operations supply industrial baking and confectionery bulk buyers at discounted rates versus whole grades.
- Cashew Flour:Finely milled defatted powder targets gluten-free bakery formulations and paleo diet specialty producers seeking neutral-flavor nut alternatives.
Established volume favors Whole Cashew; emerging adoption favors Cashew Butter.
End User:
Customer type determines roasting protocol specifications and fortification compliance burdens across the value chain.
- Snack Producers:Roasted and flavored format specialists drive fastest expansion as convenience retail displaces traditional nut mixes. FSSAI fortification mandates for iron and zinc enrichment apply directly to packaged snack shipments, creating compliance differentiation for early adopters in government school feeding programs.
- Food Manufacturers:Industrial buyers of paste, pieces, and flour for confectionery and plant-based dairy alternatives prioritize consistent fat content and aflatoxin certification over aesthetic kernel grades.
- Retail Consumers:Direct purchasers of raw or dry-roasted kernels for home consumption show price sensitivity and seasonal demand spikes tied to holiday gifting.
- Food Services:Restaurant and catering procurement of bulk roasted kernels focuses on cost-per-serving metrics with minimal brand loyalty.
Snack Producers are climbing the fastest; Food Manufacturers anchor baseline volume.
Distribution Channel:
Channel selection dictates packaging format, shelf-life requirements, and margin retention for processors.
- Supermarkets:Mass retail placement demands fortified labeling compliance and multi-layer barrier packaging for extended shelf stability in ambient storage conditions.
- Online Retail:Direct-to-consumer shipments require crush-resistant secondary packaging and shorter lead times from Binh Phuoc processing hubs to fulfillment centers.
- Health Food Stores:Clean-label procurement criteria enforce oil-free dry-roasted specifications and single-ingredient declarations without artificial flavoring.
- Wholesale:Bulk institutional sales of raw or minimally processed kernels operate on volume contracts with price volatility pass-through clauses.
Supermarkets retain the deepest volume footprint; Online Retail shows the steepest expansion trajectory.
Application:
End-use application segments separate commodity ingredient demand from premium functional positioning.
- Confectionery:Whole and piece grades supply chocolate enrobing and praline filling operations where fat migration control determines shelf appeal.
- Nutraceuticals:Protein isolate and micronutrient-fortified formats target supplement manufacturers leveraging FSSAI fortification guidelines for health claim eligibility.
- Baking:Flour and piece applications in gluten-free and paleo product formulations require consistent particle size distribution for dough handling.
- Cooking:Raw kernel demand from restaurant and home kitchen segments concentrates in ethnic cuisine channels with established cashew curry and dessert traditions.
Confectionery holds established processing volume; Nutraceuticals gain share fastest on functional positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major cashew economies, with processing concentration in Vietnam and India offsetting raw nut deficits through West African sourcing networks. Trade flows reflect deep specialization: origin countries ship in-shell harvests to Asian processing clusters, which re-export shelled kernels to consumer markets in Europe and North America.
Vietnam
Binh Phuoc province hosts the world's densest cashew processing cluster, where automated steam-shelling lines supply over half of globally traded shelled kernels. The Ministry of Industry and Trade administers export licensing and quality certification protocols that determine eligibility for EU and US shipments. Ho Chi Minh City's port infrastructure channels processed output through Cat Lai terminals to European confectionery buyers.
India
Kerala and Maharashtra processing hubs absorb raw nut imports from Guinea-Bissau and Ivory Coast to feed domestic snack consumption and re-export markets. FSSAI fortification mandates for iron and zinc enrichment apply to all retail-packaged kernel sales, reshaping roasting line investments in Kollam and Palasa clusters. The PLI scheme for food processing subsidizes automated grading equipment that accelerates export packing timelines.
United States
California and Texas distribution centers handle bulk kernel imports for private-label roasting and retail repackaging operations. FDA Foreign Supplier Verification Program documentation requirements extend supplier onboarding timelines for Vietnamese and Indian exporters. Chicago and Los Angeles metropolitan areas concentrate import brokerage and aflatoxin testing laboratories that gate European-sourced shipments.
Germany
Hamburg and Rotterdam-adjacent logistics corridors serve as entry points for EU-bound kernel shipments from Vietnamese processors. EFSA aflatoxin limits and REACH chemical standards determine customs clearance eligibility at German border inspection posts. Cologne and Frankfurt retail distribution networks channel organic and conventional grades into Central European supermarket chains.
Brazil
Ceará and Rio Grande do Norte growing belts supply both domestic processing and raw nut exports to Vietnam and India. The national agricultural regulator enforces phytosanitary certification for in-shell shipments that determines access to Asian processing markets. Fortaleza's port infrastructure handles the majority of Northeast Brazil's cashew export volume.
Cashew Market Key Industry Players
On the supply side, the industry is bifurcated between integrated origin-processor networks and regional roasting specialists. Tier-one operators control West African farmgate sourcing and Asian shelling capacity simultaneously. Three strategic archetypes dominate: vertically integrated traders, domestic snack brand owners, and industrial ingredient suppliers. Competitive moves concentrate on backward integration into raw nut origination and automation of shelling lines to compress labor costs.
Within the integrated trading tier, Olam International Limited and Archer Daniels Midland Company represent the archetype of origin-to-processor network control, while John B. Sanfilippo & Son Inc. occupies a position among North American roasting and private-label specialists. Haldiram Foods International Private Limited anchors the domestic Indian snack brand segment. These three exemplify how geographic scope and channel focus differentiate competitive positioning.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Vietnam Cashew Corporation (VINACAS) |
| Nestlé S.A. |
| John B. Sanfilippo & Son Inc. |
| Haldiram Foods International Private Limited |
| Archer Daniels Midland Company |
| Olam International Limited |
| Shivam Cashew Industry |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Vietnam's Binh Phuoc processing cluster determines both pricing tier spreads and supply chain shape, as energy cost spikes or labor disruptions in this hub cascade through export-grade kernel premiums and force buyers toward secondary sourcing networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the cashew trade. Price differentiation separates W180 gift-grade whole kernels from W320 standard grades and broken-piece economy tiers based on size certification and color standards. Pricing pressure stems from West African raw nut volatility as irregular rainfall in Guinea-Bissau and Ivory Coast squeezes processor margins. Snack producers show highest price sensitivity due to FSSAI fortification compliance costs, while confectionery buyers absorb premiums for fat-migration-controlled grades.
Supply Chain Analysis
EU REACH chemical standards and EFSA mycotoxin limits restrict kernel flows into European markets, creating regulatory chokepoints at German border inspection posts. Geographic supply concentrates in Vietnam, India, and Brazil, with raw material dependencies on West African in-shell harvests, automated steam-shelling equipment, and aflatoxin-certified storage infrastructure. Single-source vulnerability runs through Binh Phuoc's sixty-percent share of global shelled output. Distribution runs through Ho Chi Minh City's Cat Lai terminals and Kollam's export packing hubs to Hamburg and Rotterdam-adjacent logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated shelling technology diffusion is transforming cashew processing into a platform ecosystem where interoperable grading and packaging systems determine processor competitiveness and buyer switching costs.
For Market Incumbents: Build captive supply moats through backward integration into West African farmgate sourcing networks. Olam International's origination model demonstrates how Guinea-Bissau and Ivory Coast direct contracts buffer against raw nut volatility. Invest in FSSAI-compliant fortification roasting lines to secure preferential placement in India's government school feeding programs before compliance deadlines harden. For New Entrants and Emerging Players: Establish a beachhead in North American clean-label cashew butter segments where Whole Foods and Sprouts Farmers Market procurement criteria favor single-ingredient positioning over established oil-fried mixes. Target health food store channels with oil-free dry-roasted formats that bypass supermarket fortification compliance burdens. Leverage direct-to-consumer online retail to compress lead times from Binh Phuoc processing hubs. For Investors and Strategic Acquirers: FSSAI fortification mandate implementation reshapes the acquisition landscape toward processors with existing iron and zinc enrichment capabilities. Mid-term viability centers on automated grading equipment subsidized under India's PLI scheme for food processing. Monitor computer vision grading adoption rates at Vietnamese processing lines as inflection indicator for labor-cost compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Origination | Direct farmgate contracts in Guinea-Bissau and Ivory Coast secure raw nut supply against climate volatility. |
| Automated Steam-Shelling Line Deployment | Binh Phuoc processors cut labor dependency and raise export-grade kernel recovery rates through mechanization. |
| FSSAI Fortification Compliance Investment | Iron and zinc enrichment capabilities unlock preferential placement in India's government school feeding programs. |
| Clean-Label Product Line Extension | Single-ingredient cashew butter formats capture shelf space at Sprouts Farmers Market and Whole Foods private-label programs. |
| Computer Vision Grading System Adoption | Mid-scale Vietnamese processors replace manual color-sorting teams to compress shelling-to-export packing timelines. |
Research Approach
Desk research of customs and trade data, FSSAI regulatory filings, and SEC processor disclosures preceded structured interviews with cashew processing plant managers, export trading desk heads, and retail category buyers at North American natural food chains. Primary fieldwork with Binh Phuoc shelling line operators and Kollam roasting facility supervisors validated secondary estimates. Bottom-up volume triangulation against top-down trade flow analysis anchored market size calibration.
Baseline conditions held Vietnamese processing concentration and West African rainfall patterns fixed across the projection horizon, while FSSAI fortification compliance timelines and FDA Foreign Supplier Verification Program documentation requirements were varied as scenario inputs. Segmentation modeling spanned product type, end-user category, distribution channel, and application dimensions. CAGRs derived from trade volume trajectories and processor capacity expansion announcements, with automated shelling technology diffusion curves and clean-label procurement penetration rates as industry-specific forecast inputs.
Stress conditions across raw nut price volatility bands, energy cost spikes in Vietnamese processing clusters, and EFSA mycotoxin threshold enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about mechanization adoption timelines and regulatory compliance cost pass-through. Material shifts in West African climate patterns or EU chemical standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Rape Seed Meal Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Russia Compound Feed Market