
 Slippery Elm Market | 2026-2036
Slippery Elm Market Size, Share, and Industry Trends Forecast 2026-2036
Slippery Elm Market Analytics
Appalachian wildcrafter networks is hardening as the dominant upstream source for raw slippery elm bark. Nature's Way Products leverages long-term harvester contracts to secure consistent supply of certified organic material. NOW Foods anchors its position through vertical control over testing and encapsulation facilities in the United States. Mountain Rose Herbs differentiates by specializing in small-batch, sustainably harvested botanicals with full chain-of-custody documentation.
Slippery elm refers to the inner bark of Ulmus rubra, a deciduous tree native to eastern North America, containing mucilage polysaccharides that swell in water to form a protective gel with demulcent and emollient properties. The bark requires careful stripping, drying, and milling to preserve bioactive content for use in gastrointestinal soothing applications, topical preparations, and respiratory support formulations. Supplements and powders command the deepest margin pools due to higher per-unit value and repeat purchase patterns among chronic condition users. Digestive health applications lead volume consumption, while skin care represents the fastest-expanding addressable segment as cosmetic formulators incorporate mucilage extracts into barrier-repair products.
FDA dietary supplement regulations under DSHEA govern manufacturing practices and structure-function claims for slippery elm products sold in the United States. USDA organic certification and AHPA botanical authenticity standards further constrain supply by limiting acceptable harvesting methods and geographic sourcing zones. Stakeholders must monitor wild population sustainability assessments and potential CITES listing developments that could restrict bark commerce.
Market Dynamics
Wild population sustainability pressures are compressing harvestable supply of Ulmus rubra bark while FDA dietary supplement labeling requirements under DSHEA intensify documentation burdens on extractors and finished goods manufacturers.
Growth Catalysts
- DSHEA structure-function claims framework:Clear regulatory pathways for digestive health positioning enable supplement manufacturers to market mucilage-based formulations with reduced compliance friction.
- Barrier-repair cosmeceuticals:Cosmetic formulators in skin care applications are incorporating slippery elm extracts into protective gel matrices for atopic dermatitis and sensitive skin protocols.
- Appalachian harvester cooperatives:Consolidated wildcrafting networks in eastern North America are securing volume commitments through multi-year procurement contracts with domestic extractors.
Market Restraints
- Input cost volatility:Drought stress and oak wilt disease pressure are reducing viable Ulmus rubra stands in core harvesting zones, elevating raw bark premiums.
- Supply concentration risk:Dependence on wild-harvested material from discrete Appalachian watersheds creates single-source vulnerability without cultivated alternatives at scale.
- Substitution threat:Marshmallow root (Althaea officinalis) and Irish moss extracts offer comparable mucilage functionality at lower input costs for formulators.
Strategic Opportunities
- Underpenetrated Pacific Northwest cultivation:Oregon and Washington State extension services are evaluating Ulmus rubra agroforestry protocols for domesticated bark production.
- USDA organic certification tailwind:Premium pricing for certified organic material incentivizes harvesters to adopt documented sustainable stripping practices.
- Direct-to-practitioner channel innovation:Herbalists and naturopathic clinics are bypassing retail markup through bulk cooperative purchasing arrangements with regional herb suppliers.
Industry Challenges
- Botanical authentication skill gap:Fewer qualified taxonomists can distinguish Ulmus rubra from Ulmus americana in dried bark form, elevating adulteration risk.
- AHPA certification timeline compression:Third-party authenticity verification for wild-harvested material extends batch release cycles by four to six weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slippery Elm Market |
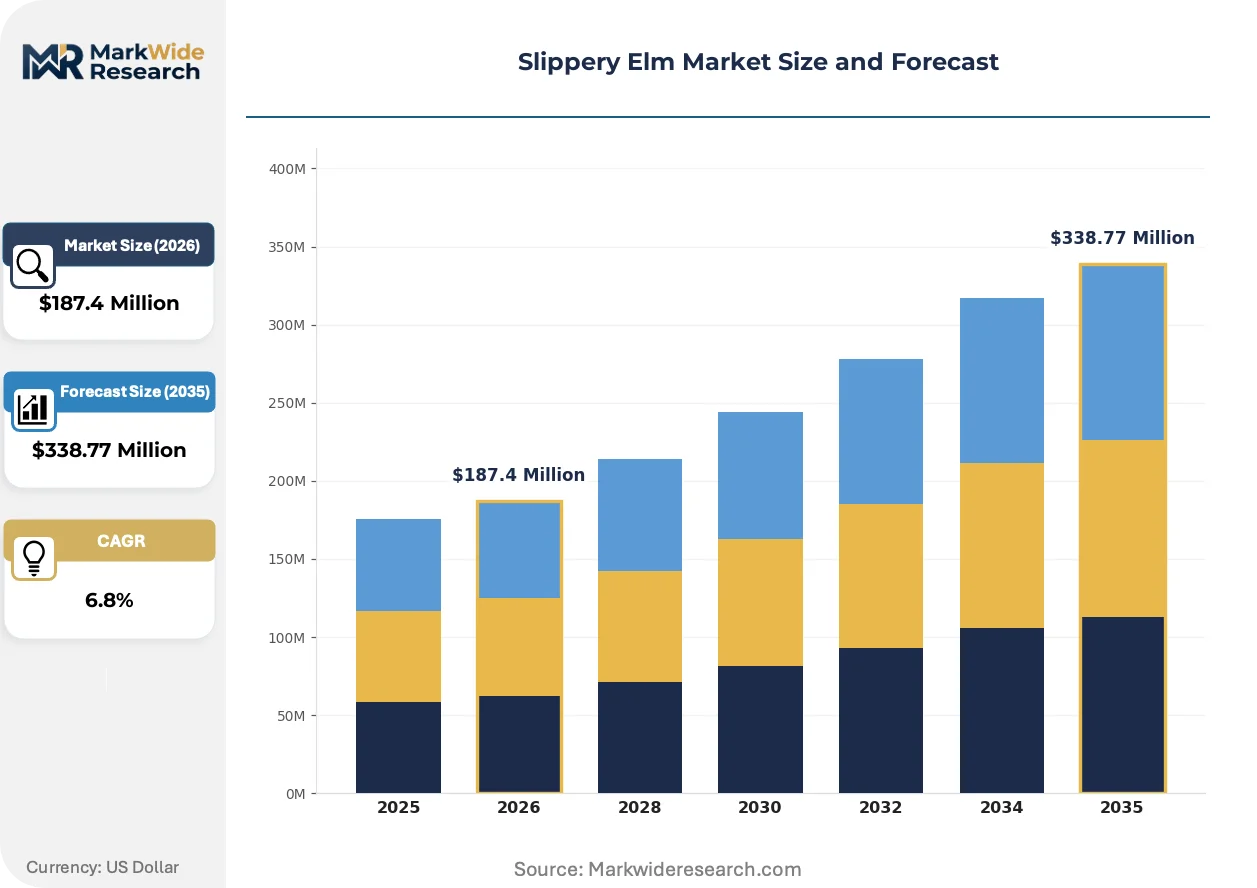
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laxatives, Herbal Teas, Supplements, Powders Application: Digestive Health, Skin Care, Immune Support, Weight Management Form: Capsules, Tablets, Liquid, Granules Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Nature's Way Products, NOW Foods, Mountain Rose Herbs, Gaia Herbs, Starwest Botanicals, Frontier Natural Products Co-op, Herb Pharm, Oregon's Wild Harvest, Solaray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slippery Elm Market Evolving Landscape
Processing technology and supply chain transparency tools are reshaping how mucilage polysaccharides move from forest to finished formulation.
Low-temperature vacuum drying technology is decentralizing extraction capacity away from centralized Midwest facilities toward smaller Appalachian processing cooperatives. Regional herb associations are adopting these systems to preserve bioactive content in high-tannin bark material. This geographic redistribution is compressing transport distances from harvest site to encapsulation.
USDA blockchain traceability pilots for botanical supply chains are tightening chain-of-custody documentation requirements for wild-harvested material. DSHEA adverse event reporting obligations now intersect with these verification systems, elevating compliance costs for smaller extractors. Dietary supplement manufacturers with in-house testing laboratories are absorbing this burden more efficiently than contract manufacturers.
Practitioner-channel bulk purchasing is displacing traditional retail stocking agreements among chronic condition users seeking gastrointestinal support. Naturopathic clinics and herbal apothecaries in the United States are consolidating demand through cooperative buying groups that negotiate directly with harvester networks. This channel shift is most visible in the Mountain West and Pacific Coast regions where integrative medicine penetration exceeds national averages.
Slippery Elm Market Segmentation
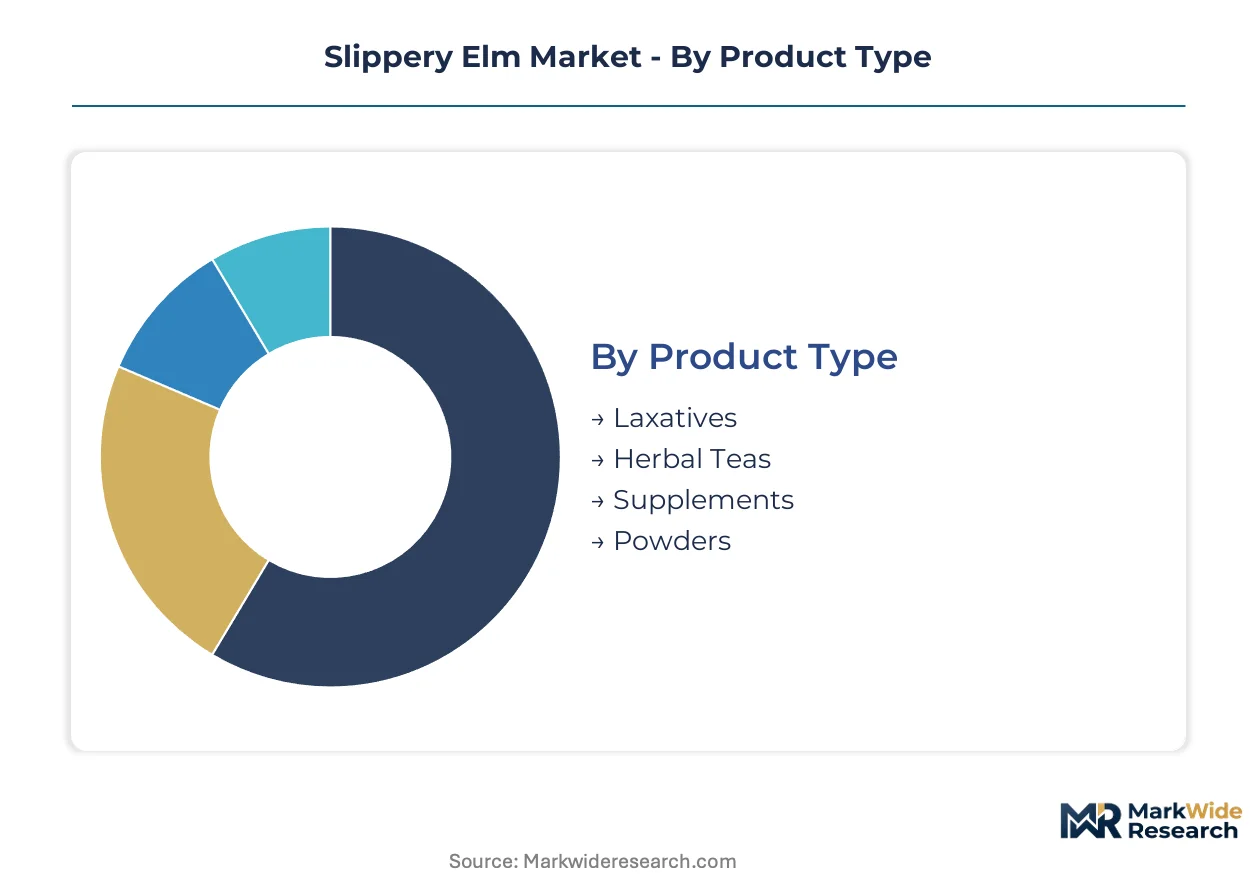
Slippery elm's mucilage polysaccharide content varies substantially across processing methods and finished formats, creating distinct margin profiles that reward manufacturers who match product specifications to end-use requirements. Segmentation clarity enables procurement teams to isolate which form factors command sustainable premiums versus commodity-adjacent positioning.
Product Type:
Upgrade cycles in digestive health applications are shortening as chronic condition users experiment with higher-potency formulations after initial trial purchases.
- Laxatives:Formulations combining slippery elm with senna or cascara sagrada dominate pharmacy shelf placement for acute constipation relief. Demand concentrates in United States drugstore chains where FDA monograph compliance enables direct symptom claims without pre-market approval.
- Herbal Teas:Whole bark pieces and cut-and-sifted material packaged in unbleached sachets appeal to traditional medicine practitioners seeking ritual preparation methods. Volume placements concentrate in natural foods cooperatives and apothecary channels across the Mountain West.
- Supplements:Standardized extracts delivering defined mucilage percentages support structure-function claims under DSHEA guidelines for gastrointestinal soothing. NOW Foods and Nature's Way Products anchor this segment through vertical control over encapsulation and testing protocols.
- Powders:Bulk material for compounding pharmacies and DIY formulation commands the deepest margin pools due to minimal processing overhead and direct practitioner relationships.
Volume placements concentrate in Supplements; the faster expansion belongs to Powders.
Application:
Cost-tier differentiation separates premium cosmeceutical positioning from mass-market digestive relief, with formulation complexity determining acceptable input grades.
- Digestive Health:Irritable bowel syndrome and gastroesophageal reflux protocols drive repeat purchase patterns among United States consumers seeking alternatives to proton pump inhibitors. Volume concentrates in direct-to-consumer subscription models bypassing retail markup.
- Skin Care:Barrier-repair formulations for atopic dermatitis incorporate mucilage extracts into protective gel matrices, with cosmetic formulators in California and New York driving specification requirements. This application gains share fastest as clean beauty positioning elevates botanical credentials.
- Immune Support:Throat-soothing lozenges and respiratory syrups leverage demulcent properties for seasonal wellness positioning, particularly in Appalachian regions with strong wildcrafting heritage.
- Weight Management:Satiety-promoting powders mixed into meal replacement shakes occupy a niche position dependent on influencer marketing rather than clinical positioning.
Digestive Health captures the largest absolute volume; Skin Care exhibits the steepest expansion trajectory.
Form:
Customer-type segmentation separates chronic condition users demanding precise dosing from wellness explorers prioritizing convenience and taste masking.
- Capsules:Two-piece gelatin or vegetable cellulose shells encapsulate standardized powder for precise unit dosing, dominating practitioner-channel bulk purchasing arrangements. Mountain Rose Herbs and comparable suppliers emphasize small-batch encapsulation with full chain-of-custody documentation.
- Tablets:Compressed formulations with added binders enable higher-density packaging and reduced shipping costs for retail distribution, though heat exposure during tableting risks mucilage degradation.
- Liquid:Glycerin-based extracts and alcohol tinctures appeal to pediatric and geriatric populations with swallowing difficulties, with compounding pharmacies in integrative medicine hubs driving specification.
- Granules:Instant-dissolving formats for hot beverage preparation occupy a transitional position between traditional tea preparation and modern convenience expectations.
Capsules dominate practitioner-directed volume; Liquid formats expand most quickly in pediatric and geriatric applications.
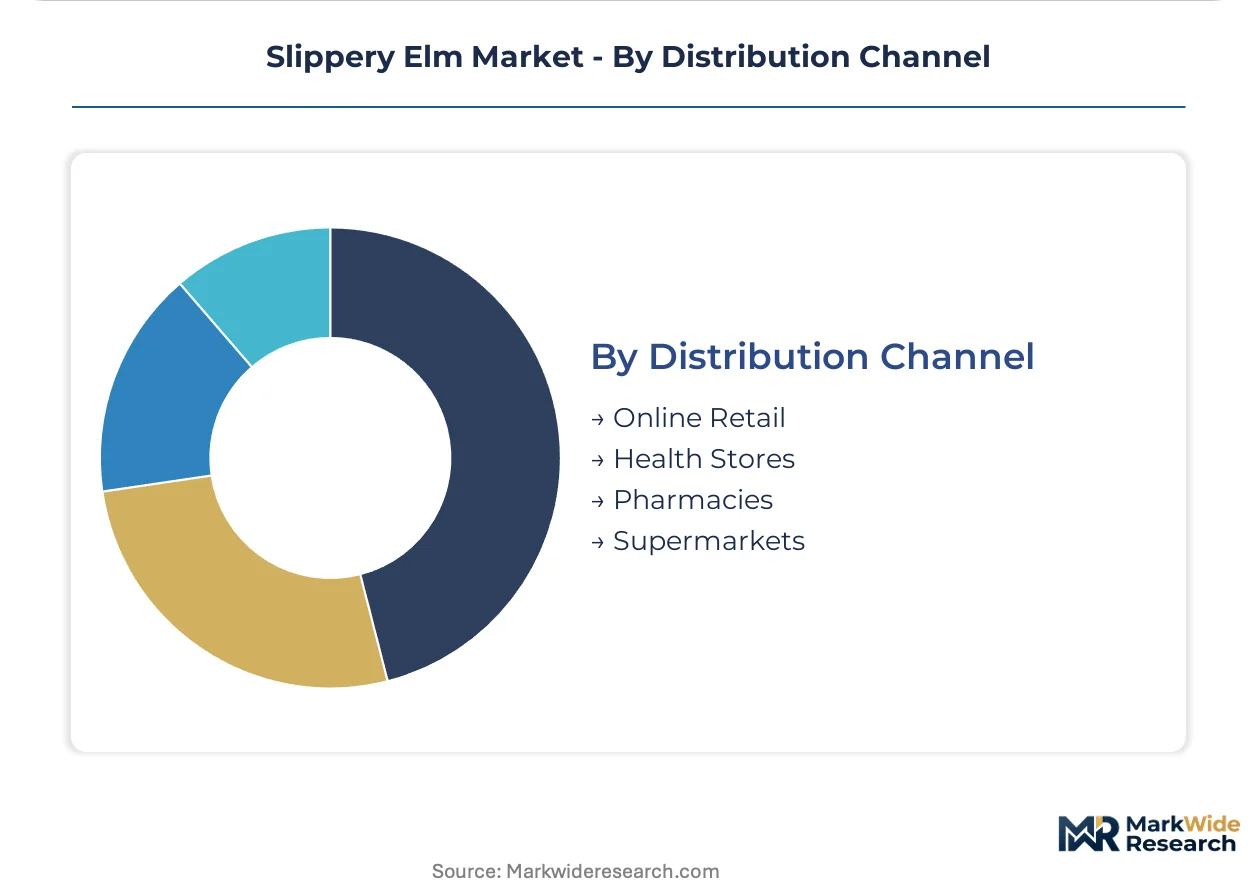
Distribution Channel:
Supply concentration in Appalachian harvester networks shapes channel economics, with proximity to processing infrastructure determining viable retail partnerships.
- Online Retail:Direct-to-consumer platforms enable subscription models for chronic users, with Amazon and specialized botanical sites capturing share from traditional health food stores. DSHEA compliance documentation displayed in digital storefronts reduces purchase friction for structure-function claims.
- Health Stores:Independent natural foods cooperatives and regional chains maintain curated botanical selections with staff-trained consultation, particularly strong in Pacific Coast markets with elevated integrative medicine penetration.
- Pharmacies:CVS, Walgreens, and Rite Aid shelf placement requires FDA OTC monograph alignment or supplement facts panel compliance, filtering out non-standardized material.
- Supermarkets:Mass-market grocery placement demands price-competitive positioning that compresses margins for wild-harvested supply, favoring lower-cost marshmallow root substitutions.
Volume concentrates in Online Retail; Health Stores maintain the most durable pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian watersheds in the eastern United States supply the dominant share of wild-harvested Ulmus rubra bark. Harvester cooperatives in West Virginia, Kentucky, and Tennessee anchor upstream procurement networks serving domestic extractors.
United States
Digestive health supplement demand and barrier-repair cosmeceutical formulations drive procurement from Appalachian wildcrafter networks. FDA DSHEA structure-function claim regulations govern finished product labeling and adverse event reporting obligations. Extractors in North Carolina and Virginia operate low-temperature vacuum drying cooperatives that shorten transport distances from harvest sites.
Canada
Health Canada Natural and Non-prescription Health Products Directorate oversees slippery elm licensing for throat lozenges and digestive aids. Practitioner-channel bulk purchasing through naturopathic clinics in British Columbia and Ontario concentrates demand in integrative medicine corridors. Wild-harvested material enters primarily through cross-border procurement arrangements with U.S. Appalachian suppliers.
Germany
EMA herbal monograph standards for Ulmus rubra extracts constrain import specifications for mucilage content and heavy metal limits. Traditional medicine pharmacies in Bavaria and Baden-Württemberg stock demulcent preparations for gastrointestinal and respiratory applications. Botanical wholesalers in Hamburg and Frankfurt coordinate EU distribution of certified organic material from North American sources.
United Kingdom
MHRA borderline product classification determines whether slippery elm formulations register as medicines or food supplements. Herbal apothecaries in London and Bristol maintain demand for whole bark pieces among traditional medicine practitioners. Brexit-related import documentation requirements have extended batch release timelines for wild-harvested botanicals from Appalachian suppliers.
Australia
TGA Listed Medicine approval pathways enable structure-function claims for digestive soothing and throat demulcent applications. Complementary medicine manufacturers in New South Wales and Victoria formulate slippery elm into practitioner-only dispensing lines. Import reliance on certified organic North American material intensifies during southern hemisphere winter months when seasonal wellness demand peaks.
Slippery Elm Market Competitive Landscape
Global majors compete with regional champions across supply chain control and certification depth. The vendor base stratifies between vertically integrated encapsulators, specialist wildcrafting intermediaries, and commodity botanical traders. Three archetypes dominate: harvester-contract holders securing Appalachian supply, in-house testing laboratories absorbing compliance burdens, and small-batch sustainability documenters serving practitioner channels. Competitive moves concentrate on backward integration into drying cooperatives and multi-year procurement contracting.
Within the harvester-contract tier, Nature's Way Products and NOW Foods occupy positions exemplifying volume-scale supply security through Appalachian cooperative relationships. Mountain Rose Herbs represents the documentation-intensive archetype, specializing in chain-of-custody transparency for practitioner-channel purchasers. These three anchors illustrate the market's bifurcation between mass-market encapsulation efficiency and premium-tier sustainability verification.
| Leading Market Players |
|---|
| Nature's Way Products |
| NOW Foods |
| Mountain Rose Herbs |
| Gaia Herbs |
| Starwest Botanicals |
| Frontier Natural Products Co-op |
| Herb Pharm |
| Oregon's Wild Harvest |
| Solaray |
| Others |
Value Network & Pricing Analysis
Backward integration into Appalachian drying cooperatives anchors both supply security and margin capture for domestic extractors. Nature's Way Products and NOW Foods leverage captive processing capacity to buffer wild bark premium volatility while commanding tiered pricing premiums through USDA organic certification.
Pricing Analysis
Certification bundling separates organic chain-of-custody documentation from commodity-grade material, with AHPA-verified wild-harvested bark commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across certified organic, conventional wild-harvested, and substitute-grade tiers reflects documentation burden and authentication risk. Pricing pressure stems from drought-stressed Ulmus rubra population decline in core Appalachian watersheds. Chronic condition users in practitioner channels show lowest price sensitivity; mass-market supermarket buyers exhibit highest substitution elasticity toward marshmallow root alternatives.
Supply Chain Analysis
Fuel and freight costs from remote Appalachian harvest sites to Midwest encapsulation facilities compress margins for non-integrated extractors. Raw material supply concentrates in West Virginia, Kentucky, and Tennessee wildcrafter networks. Processing depends on low-temperature vacuum drying equipment, AHPA-certified testing laboratories, and FDA-compliant labeling infrastructure. Single-source vulnerability from wild-harvested Appalachian material without cultivated alternatives at scale creates structural supply risk. Distribution runs through direct-to-practitioner cooperatives, online retail platforms, and pharmacy chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA DSHEA structure-function claim documentation creates a barrier-to-entry moat favoring incumbents with in-house testing laboratories.
For Market Incumbents: To counter substitution threat from Althaea officinalis and Irish moss extracts, deepen harvester cooperative contracting in underpenetrated Pacific Northwest cultivation zones and accelerate USDA organic certification timelines to tighten supply access for non-compliant competitors. Multi-year procurement commitments with West Virginia and Kentucky wildcrafter networks secure volume priority ahead of potential CITES listing developments. For New Entrants and Emerging Players: FDA DSHEA structure-function claim clarity in the United States opens a window for practitioner-channel bulk purchasing arrangements bypassing retail markup concentration. Target naturopathic clinic cooperatives in the Mountain West and Pacific Coast regions with compounding-grade powder formats and full chain-of-custody documentation. Direct-to-practitioner go-to-market positioning avoids pharmacy shelf placement compliance burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated dietary supplement majors seeking Appalachian supply security. Long-term viability hinges on wild population sustainability assessments and potential domestication breakthroughs in Oregon and Washington State agroforestry protocols. Monitor TGA Listed Medicine approval trends in Australia as early indicator of international regulatory acceptance trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Harvester Cooperative Long-Term Contracting | Multi-year procurement commitments with West Virginia and Kentucky wildcrafters lock in supply priority ahead of competitors. |
| USDA Organic Certification Investment | Documented sustainable stripping practices unlock premium pricing tiers and restrict competitor supply access. |
| Low-Temperature Vacuum Drying Capacity Expansion | Regional Appalachian processing cooperatives reduce transport distances and preserve mucilage bioactive content. |
| Direct-to-Practitioner Channel Development | Bulk purchasing arrangements with naturopathic clinics bypass retail markup and build recurring revenue. |
| Pacific Northwest Cultivation Pilot Funding | Oregon and Washington State agroforestry protocols address single-source wild-harvest vulnerability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with wildcrafter cooperative managers, dietary supplement regulatory affairs leads, naturopathic clinic procurement officers, and botanical testing laboratory directors combined with AHPA harvest guidelines, FDA DSHEA enforcement records, and USDA organic certification databases. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing.
Segment-level granularity modeled product type, application, form, and distribution channel dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for wild population sustainability constraints and regulatory documentation burden evolution. Forecast inputs incorporated Appalachian harvest yield estimates, domestication trial progress in Pacific Northwest extension services, and practitioner-channel penetration rates in integrative medicine corridors.
The model assumes a particular technology adoption path; alternative pathways for low-temperature vacuum drying decentralization would alter the outlook. Forecasts reflect assumptions regarding CITES listing developments, oak wilt disease progression, and substitution elasticity in mass-market channels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
South America Poultry Feed Market