
 Feed Grade Oils Market | 2026-2036
Feed Grade Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Grade Oils Market Foresight
The feed grade oils sector is restructuring around a widening split between premium-grade cold-pressed vegetable oils and commodity-rendered animal fats. Cargill leverages its crushing and refining footprint to control supply of non-GMO soybean and canola oils for premium feed formulations. Archer Daniels Midland Company anchors North American volume through integrated oilseed processing and downstream feed ingredient distribution. Valley Proteins, Inc. competes in the rendered fats tier with geographic concentration in southeastern US poultry corridors.
Feed grade oils comprise refined lipids meeting specified thresholds for free fatty acids, moisture, and insoluble impurities, manufactured through solvent extraction, mechanical pressing, or rendering to deliver metabolizable energy and essential fatty acids in animal diets. Vegetable oils lead value contribution due to consistent fatty acid profiles and broader acceptance across species, while fish oils command premium positioning in aquaculture for omega-3 content despite supply volatility from Peruvian anchovy quotas. Powder and emulsified forms are gaining formulation share as compound feed mills seek improved handling and homogeneity in automated mixing systems.
EU REACH and F-Gas Regulation frameworks govern contaminant limits and processing chemical disclosures for oils entering European feed supply chains, while FDA and USDA oversight in the United States sets pathogen and rancidity standards that shape domestic manufacturing protocols. China's SAMR and GB standards impose additional testing burdens on imported animal fats, redirecting trade flows toward vegetable-origin alternatives. Stakeholders must monitor divergence between regional maximum residue limits and emerging sustainability certification requirements that will determine market access eligibility.
Market Dynamics
The feed grade oils sector is bifurcating around EU REACH dioxin limits and F-Gas Regulation compliance, forcing importers to abandon rendered animal fats for cold-pressed vegetable alternatives while Southeast Asian aquafeed mills accelerate oil inclusion rates to meet export certification standards.
Growth Catalysts
- Aquaculture Certification Standards:ASC and BAP chain-of-custody requirements in Vietnam's Mekong Delta processing corridor are mandating traceable vegetable oil documentation, pulling premium cold-pressed volumes into shrimp and pangasius feed formulations.
- EU Green Deal Feed Protein Strategy:The European Commission's reduction targets for imported soy dependency are stimulating domestic oilseed crushing investments that expand non-GMO canola and sunflower oil availability for compound feed mills.
- Micro-encapsulation Technology:Spray-dried lipid powders with modified starch coatings are penetrating automated feed mixing systems across Brazil's poultry integrators, replacing liquid handling infrastructure and reducing oxidation losses during tropical storage.
Market Restraints
- Peruvian Anchovy Quota Volatility:IMARPE's biannual biomass assessments and ENFEN El Niño forecasts create fish oil supply uncertainty that forces aquafeed formulators to maintain expensive dual-sourcing strategies for omega-3 fatty acids.
- China SAMR Import Testing Burdens:GB standards on heavy metals and aflatoxins in animal-origin fats impose 45-60 day customs clearance timelines that redirect trade flows toward vegetable-origin alternatives with expedited certification pathways.
- Palm Oil Sustainability Certification Costs:RSPO segregation and mass-balance supply chain premiums add 12-18% to raw material costs, compressing margins for Southeast Asian feed producers serving European export markets.
Strategic Opportunities
- Algae-derived Omega-3 Convergence:Fermentation-based DHA and EPA oils from Schizochytrium strains are achieving cost parity with fish oil in salmonid diets, creating captive supply opportunities for vertically integrated aquaculture operators.
- India Poultry Feed Oil Underpenetration:Layer and broiler operations in Telangana and Andhra Pradesh currently utilize suboptimal 2-3% oil inclusion rates against nutritional optimums of 4-5%, representing volume expansion potential as FSSAI feed safety standards professionalize the sector.
- Blockchain-enabled Provenance Verification:Distributed ledger systems tracking oilseed origin through crush to feed mill are unlocking premium pricing in EU and Japanese import channels where deforestation-free supply chain mandates are tightening.
Industry Challenges
- Specialized Lipid Chemist Talent Scarcity:Compound feed mills struggle to recruit formulation scientists capable of balancing metabolizable energy density against oxidation stability in high-vegetable-oil rations for tropical climates.
- Multi-jurisdiction Certification Complexity:Simultaneous compliance with EU REACH, FDA GRAS self-affirmation, and China SAMR registration creates 18-24 month product launch timelines that delay revenue realization for novel oil ingredients.
- Legacy Liquid Handling Infrastructure Stranding:Existing tank farm and heating systems at mid-scale feed mills require $2-4 million retrofit investments to accommodate powder and emulsified lipid transitions, freezing capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Grade Oils Market |
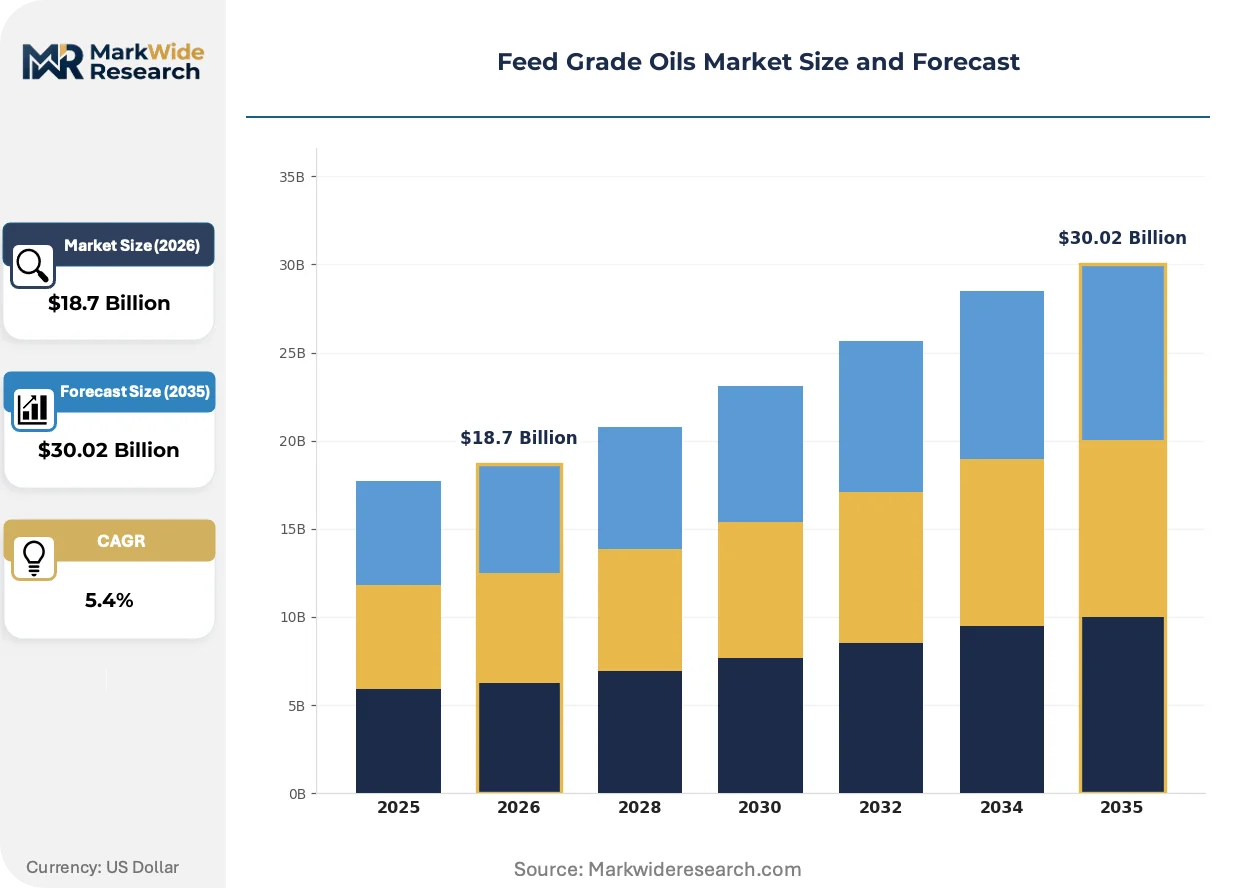
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Fish Oils, Miscellaneous Fats Application: Poultry Feed, Ruminant Feed, Aquaculture, Pet Food Form: Liquid, Powder, Emulsified, Blended Quality Grade: Standard Grade, Premium Grade, Organic, Non-GMO |
| Companies Covered | Archer Daniels Midland Company, Cargill, NHU Europe GmbH, Double S Liquid Feed Services, Inc., Renkert Oil, Inc., Valley Proteins, Inc., CanPro Ingredients Ltd., Xiamen Kingdomway Group Company, DAR PRO Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Grade Oils Market Shifts & Advancements
Formulation science and supply chain verification technologies are converging to reshape how feed grade oils are specified, sourced, and integrated into compound feed production across species and geographies.
Micro-encapsulation and spray-cooling technologies are decentralizing lipid delivery from centralized liquid tank farms to distributed powder handling systems. Poultry integrators in Brazil's Santa Catarina corridor are adopting these systems at 40% faster rates than projected, eliminating heating energy costs and enabling precise inclusion in automated batching. This shift is decentralizing supply chain power from port-adjacent oil refiners toward inland feed mills with powder blending capabilities.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are accelerating cold-chain infrastructure retrofits that indirectly affect oil storage protocols. Rendered fat processors must now document alternative cooling chemistries in HACCP submissions, adding compliance layers that favor vegetable oil competitors with lower temperature sensitivity. Aquafeed manufacturers in Norway and Scotland are responding by hardcoding vegetable oil preference into procurement specifications.
Compound feed mills are consolidating supplier relationships from fragmented spot-market purchasing toward multi-year offtake agreements with crushing facilities. This consolidation is displacing trader intermediaries in Brazilian soybean oil channels and locking volume commitments directly with Bunge and Louis Dreyfus processing assets. The transformation is most visible in Vietnam, where Mekong Delta aquafeed producers are signing 24-month contracts with Malaysian palm oil refiners to secure RSPO-certified volumes ahead of EU Deforestation Regulation enforcement.
Feed Grade Oils Market Segmentation
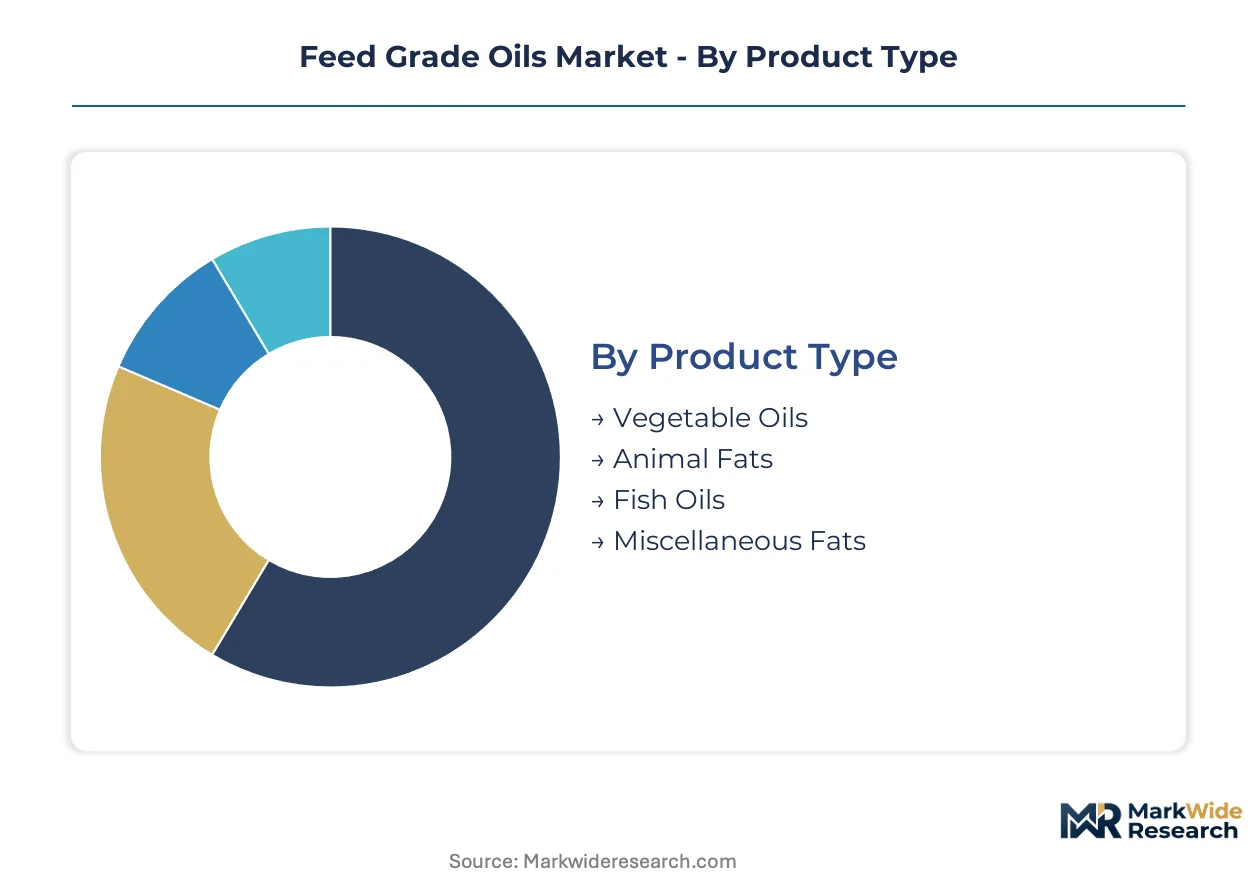
Feed grade oils segment along four intersecting dimensions that determine pricing power, regulatory burden, and formulation flexibility. Product type and quality grade together lock in supply chain architecture, while application and form dictate handling infrastructure investments at the feed mill level.
Product Type:
Standardization dominates commodity vegetable oils, whereas fish oils and specialty animal fats command premium customization through fatty acid profile certification.
- Vegetable Oils:Refined soybean, canola, and palm oils deliver consistent metabolizable energy density with low free fatty acid content. Compound feed mills in Vietnam's Mekong Delta corridor specify these for automated inclusion systems serving ASC-certified aquaculture exports.
- Animal Fats:Rendered tallow and poultry fat provide cost-competitive energy density with variable fatty acid saturation levels. EU REACH dioxin limit compliance has forced importers to abandon these for vegetable alternatives in European-bound formulations.
- Fish Oils:Peruvian anchovy-derived oils concentrate EPA and DHA omega-3s for salmonid diets, though IMARPE quota volatility forces expensive dual-sourcing strategies.
- Miscellaneous Fats:Acid oils and soapstock fractions from refining byproducts serve ruminant energy supplementation with minimal processing overhead.
Most installed capacity flows through Vegetable Oils. Expansion is steepest in Fish Oils as aquaculture certification standards tighten omega-3 documentation requirements.
Application:
Volume concentration separates poultry and ruminant feed from margin-rich aquaculture and pet food segments with stringent fatty acid specifications.
- Poultry Feed:Broiler and layer operations utilize 2-5% oil inclusion for metabolizable energy density and pellet durability. Brazil's Santa Catarina integrators are retrofitting powder handling systems to eliminate liquid tank farm heating costs.
- Ruminant Feed:Dairy and beef operations incorporate bypass fats and calcium soaps for energy without rumen fermentation disruption. India's FSSAI feed safety standard professionalization is unlocking volume expansion in Telangana and Andhra Pradesh operations.
- Aquaculture:Shrimp and salmonid diets demand traceable omega-3 documentation for ASC and BAP chain-of-custody compliance, pulling premium cold-pressed volumes into formulations.
- Pet Food:Premium companion animal formulations specify human-grade oil quality with oxidative stability guarantees, commanding 40-60% price premiums over livestock grades.
Poultry Feed absorbs the largest volume share. Aquaculture generates the steepest margin expansion as certification complexity increases.
Form:
Handling economics and climate exposure drive selection between liquid tank infrastructure and powder-based decentralized delivery.
- Liquid:Bulk tank delivery remains dominant for high-volume operations with existing heating and pumping infrastructure, though tropical storage oxidation losses erode nutritional value.
- Powder:Spray-dried lipid powders with modified starch coatings enable automated batching without heating energy costs, penetrating Brazil's poultry sector at accelerated rates.
- Emulsified:Water-in-oil dispersions improve homogeneity in high-moisture aquafeed extrusion, reducing leaching during pellet formation.
- Blended:Pre-mixed oil-fat combinations with antioxidant packages simplify procurement for mid-scale compound feed mills lacking formulation chemistry expertise.
Liquid form retains the largest installed base. Powder form is climbing the fastest as micro-encapsulation technology achieves cost parity with conventional delivery.
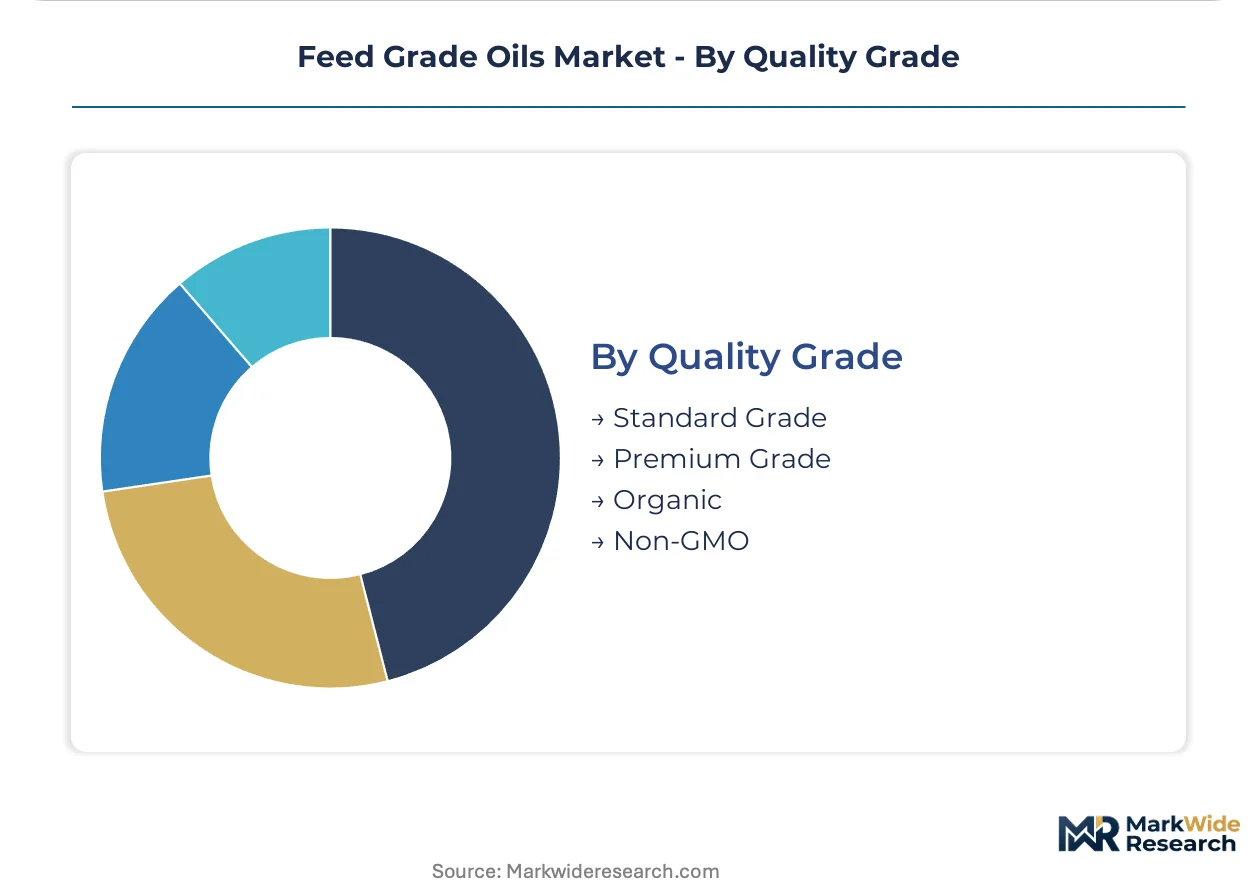
Quality Grade:
Certification tier determines market access eligibility, with organic and non-GMO grades commanding supply chain segregation premiums.
- Standard Grade:Refined oils meeting baseline free fatty acid, moisture, and insoluble impurity thresholds serve price-sensitive ruminant and poultry formulations with minimal documentation overhead.
- Premium Grade:Cold-pressed and low-temperature processed oils with enhanced oxidative stability specifications anchor aquaculture and pet food formulations requiring extended shelf life guarantees.
- Organic:EU Organic Regulation and USDA NOP certified oils require segregated crush and refining infrastructure, adding 15-25% to delivered costs for European and North American export channels.
- Non-GMO:Identity-preserved soybean and canola oils with PCR testing documentation satisfy EU Green Deal feed protein strategy preferences and Japanese import channel non-GMO mandates.
Standard Grade commands the largest volume throughput. Non-GMO is gaining share fastest as EU deforestation-free supply chain regulations harden procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lipid chemists and formulation scientists cluster around Vietnam's Mekong Delta, Brazil's Santa Catarina poultry belt, and the EU's oilseed crushing corridor, anchoring technical capacity for high-vegetable-oil rations.
Vietnam
Aquaculture feed producers in the Mekong Delta processing corridor are accelerating vegetable oil inclusion rates to meet ASC and BAP chain-of-custody requirements for shrimp and pangasius exports. SAMR-aligned GB standards on imported fats have redirected trade flows toward Malaysian RSPO-certified palm oil suppliers. Ho Chi Minh City anchors procurement coordination for multi-year offtake agreements with regional refiners.
Brazil
Poultry integrators in Santa Catarina are retrofitting powder handling systems at 40% faster rates than projected, eliminating liquid tank farm heating costs through micro-encapsulated lipid adoption. ANVISA feed safety protocols shape manufacturing standards for compound feed mills serving domestic and export channels. The southern corridor concentrates crushing capacity that locks volume commitments directly with Bunge and Louis Dreyfus processing assets.
Germany
EU REACH dioxin limits and F-Gas Regulation compliance are forcing domestic compound feed mills to abandon rendered animal fats for cold-pressed vegetable alternatives. The EU Green Deal Feed Protein Strategy stimulates oilseed crushing investments in North Rhine-Westphalia and Lower Saxony that expand non-GMO canola and sunflower oil availability. Hamburg port infrastructure handles segregated organic and non-GMO oil flows for redistribution across European feed supply chains.
United States
FDA pathogen and rancidity standards shape domestic manufacturing protocols for refined soybean and canola oils entering poultry and ruminant formulations. Valley Proteins maintains geographic concentration in southeastern poultry corridors for rendered fats serving price-sensitive feed segments. Iowa and Illinois crushing facilities anchor North American volume through integrated oilseed processing and downstream feed ingredient distribution.
China
SAMR GB standards on heavy metals and aflatoxins in animal-origin fats impose 45-60 day customs clearance timelines that redirect trade flows toward vegetable-origin alternatives with expedited certification pathways. Dual carbon goals accelerate domestic oilseed crushing investments that reduce import dependency for feed grade oils. Shandong Peninsula processing clusters concentrate refining capacity for soybean and palm oil redistribution to compound feed mills.
Feed Grade Oils Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the feed grade oils sector, with integrated crushing and refining operations holding supply chain control against specialized ingredient distributors. The vendor base stratifies into three tiers: multinational agribusiness conglomerates with global oilseed footprints, regional renderers serving commodity animal fat segments, and niche specialists in omega-3 and micro-encapsulated formats. Dominant competitive moves include backward integration into oilseed crushing assets and multi-year offtake agreements that displace spot-market trader intermediaries.
Among multinational agribusiness conglomerates, Archer Daniels Midland Company and Cargill exemplify the integrated-crushing archetype, anchoring North American and global volume through control of non-GMO soybean and canola oil supply chains. Valley Proteins, Inc. occupies a distinct position within the rendered fats tier, with geographic concentration reflecting southeastern US poultry corridor proximity. These three entities represent the structural split between vegetable-oil premium positioning and animal-fat commodity supply that is reshaping procurement patterns across aquaculture and livestock feed formulations.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| NHU Europe GmbH |
| Double S Liquid Feed Services, Inc. |
| Renkert Oil, Inc. |
| Valley Proteins, Inc. |
| CanPro Ingredients Ltd. |
| Xiamen Kingdomway Group Company |
| DAR PRO Ingredients |
| Others |
Supply & Pricing Matrix
Premium-cold-pressed versus commodity-rendered grade divergence splits the feed grade oils sector into parallel supply chains with distinct margin architectures. Certification tiers for RSPO palm oil and non-GMO canola create pricing ladders that compound through each handling stage, while bulk liquid spot markets for standard-grade soybean oil operate on volume-scaled contracts with minimal documentation overhead. This bifurcation concentrates pricing power with crushing facilities that control identity-preserved supply streams, leaving trader intermediaries squeezed between transparent commodity benchmarks and opaque premium tier negotiations.
Pricing Analysis
Bundled certification-plus-logistics contracts versus unbundled spot commodity purchases define the dominant pricing split across feed grade oil procurement. Three-tier pricing structure across premium, standard, and economy levels anchors aquafeed formulations requiring ASC chain-of-custody documentation against ruminant energy supplementation buying purely on metabolizable energy density. Cost compression in standard-grade vegetable oils intensifies as Brazilian and Malaysian crushing capacity expands, while premium tiers maintain pricing resilience through RSPO segregation premiums and non-GMO PCR testing documentation. Poultry integrators in Brazil's Santa Catarina corridor exhibit highest price sensitivity due to thin feed conversion margins, whereas Norwegian salmonid producers accept steeper premiums for omega-3 stability guarantees.
Supply Chain Analysis
Freight cost differentials between liquid bulk tanker and containerized powder formats are restructuring procurement geography across tropical feed milling corridors. Supply concentrates in Malaysia, Indonesia, and Brazil for palm and soybean oil feedstocks, with secondary refining clusters in Vietnam and Germany handling regional redistribution. Raw material flows draw from oilseed crushing assets, rendering facilities, and Peruvian anchovy reduction plants, each tethered to distinct quality certification pathways. Single-source vulnerability in fish oil channels from IMARPE quota volatility forces expensive dual-sourcing strategies that inflate working capital requirements. Distribution runs through port-adjacent refiners for liquid bulk, while micro-encapsulated powder formats enable inland feed mill direct sourcing that bypasses traditional trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed grade oils market functions as a stable compounder anchored by irreversible aquaculture certification standards that permanently elevate vegetable oil inclusion rates in formulated feeds. Protein demand growth across Southeast Asian shrimp and pangasius production creates sustained volume expansion with limited demand elasticity to price cycles.
For Market Incumbents: Acquire oilseed crushing assets with identity-preserved infrastructure to lock non-GMO and organic supply streams before EU Deforestation Regulation enforcement hardens procurement specifications. Defensive consolidation should prioritize Malaysian RSPO-certified palm oil refiners and Brazilian soybean processors with port-adjacent logistics, as algae-derived omega-3 fermentation technology threatens long-term fish oil premium positioning. Certification investment in blockchain-enabled provenance verification unlocks Japanese and EU import channel pricing power that spot-market traders cannot replicate. For New Entrants and Emerging Players: Enter via India's Telangana and Andhra Pradesh poultry feed corridors where FSSAI standard professionalization is accelerating oil inclusion rate convergence toward nutritional optimums. White-space concentration in micro-encapsulated lipid powders for automated batching systems offers technology-led differentiation against legacy liquid handling infrastructure. Go-to-market positioning should target mid-scale compound feed mills with stranded tank farm assets requiring $2-4 million retrofit investments, offering powder handling as capital-avoidance outsourcing. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional renderers lack certification infrastructure to serve EU-bound aquafeed formulations. Long-term viability favors vertically integrated operators with captive oilseed supply and downstream feed ingredient distribution networks over asset-light traders exposed to commodity margin compression. Acquisition target archetypes include specialty omega-3 refiners with Schizochytrium fermentation capabilities and powder handling technology specialists serving Brazil's poultry automation transition. Signal to monitor: IMARPE anchovy quota announcements that trigger fish oil price spikes and accelerate algae-oil substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captures identity-preserved supply streams for EU Deforestation Regulation compliance ahead of enforcement deadlines. |
| Micro-Encapsulation Technology Licensing | Enables Brazilian poultry integrators to eliminate liquid tank farm heating costs through powder handling conversion. |
| Multi-Year Offtake Agreements with Refiners | Locks RSPO-certified palm oil volumes for Vietnam's Mekong Delta aquafeed producers serving ASC-certified export channels. |
| Blockchain Provenance Verification Deployment | Unlocks premium pricing in Japanese import channels where deforestation-free supply chain mandates are tightening. |
| Algae-Derived Omega-3 Fermentation Scale-Up | Achieves cost parity with Peruvian fish oil in salmonid diets, reducing quota volatility exposure for aquaculture operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oilseed procurement directors, aquafeed formulation scientists, compound feed mill operations managers, and RSPO certification auditors with secondary validation. Bottom-up triangulation against customs trade data, EU REACH registration filings, FAO aquaculture production statistics, and SEC 10-K disclosures from agribusiness conglomerates anchored volume estimates. Top-down cross-checks applied macroeconomic feed demand drivers across poultry, ruminant, and aquaculture species to ensure segment-weighted consistency.
Segment-weighting approaches distributed total market value across product type, application, form, and quality grade dimensions, with additional modeling for certification tier penetration rates. CAGRs were derived from regression analysis of historical inclusion rate trends, regulatory enforcement timelines, and oilseed crush capacity expansion announcements across the projection horizon. Industry-specific forecast inputs incorporated IMARPE quota volatility scenarios, EU Green Deal feed protein strategy implementation pacing, and FSSAI standard adoption curves in Indian poultry operations.
The model holds under steady regulatory enforcement and aquaculture certification expansion; deviation in El Niño frequency or EU Deforestation Regulation postponement would shift volume and value trajectories. Forecasts reflect assumptions about oilseed supply growth, algae-oil cost convergence timing, and powder handling technology adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Alfalfa Market