
 Elaeis Guineensis Kernel Oil Market | 2026-2036
Elaeis Guineensis Kernel Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Elaeis Guineensis Kernel Oil Market Foresight
Personal care brands is rebalancing demand toward higher-lauric refined fractions as sulfate-free surfactant formulations gain shelf space. Wilmar International leverages integrated plantation assets across Indonesia and Malaysia to secure feedstock consistency. Sime Darby Plantation anchors its position through MSPO-certified estate coverage that satisfies European personal care brand audit requirements. Golden Agri-Resources competes on scale, operating some of the largest palm kernel crushing facilities in Southeast Asia.
Elaeis guineensis kernel oil is the fixed oil extracted from the endosperm of oil palm seeds, containing roughly 50% lauric acid by weight and yielding C12-C14 fatty acid fractions through high-pressure splitting and fractional distillation. The oil serves as the dominant feedstock for oleochemical surfactants, specialty fats, and medium-chain triglyceride production across food and personal care industries. Refined oil commands the largest value share among product types due to its direct use in cosmetics and pharmaceutical-grade formulations, while crude oil flows predominantly to integrated refiners with captive oleochemical capacity. Cosmetics and personal care applications represent the fastest-growing demand segment, driven by natural-label positioning and lauric acid-derived mild surfactant chemistry.
Indonesia's ISPO and Malaysia's MSPO certification frameworks mandate traceability and deforestation-free sourcing, reshaping procurement criteria for European and North American buyers. REACH registration requirements in Europe and FDA food-contact substance notifications in the United States further filter market access to processors with documented supply chain governance. Stakeholders must monitor evolving EU Deforestation Regulation implementation timelines and assess whether backward integration into certified kernel crushing assets will become a prerequisite for contract eligibility with multinational personal care and food manufacturers.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing kernel oil processors to reconfigure supply chain documentation systems and certify every plantation source, compressing margins for non-integrated traders while rewarding estate-backed refiners with captive crushing capacity.
Growth Catalysts
- Sulfate-free surfactant chemistry:Personal care formulators are substituting lauric acid-derived mild surfactants for traditional sulfates, pulling additional C12-C14 fraction volumes through Southeast Asian splitting facilities.
- Indonesia's ISPO certification expansion:Mandatory sustainability standards for large plantations are standardizing traceability infrastructure that downstream European buyers now require as a baseline procurement condition.
- Medium-chain triglyceride demand:Nutraceutical manufacturers are absorbing rising volumes of refined kernel oil fractions for ketogenic and sports nutrition applications, diversifying demand beyond traditional oleochemical channels.
Market Restraints
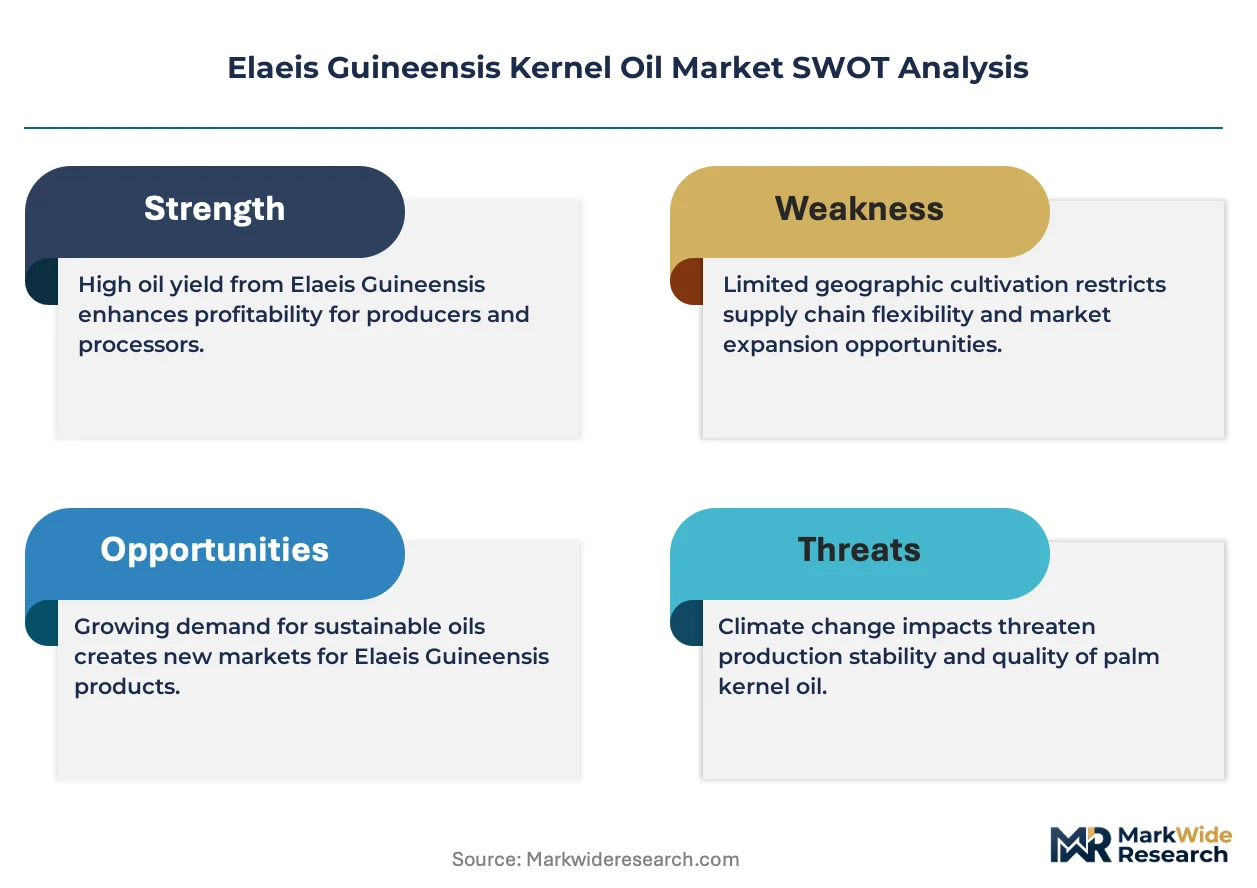
- Input cost volatility:Crude palm kernel oil prices fluctuate with fresh fruit bunch harvest cycles and El Niño weather patterns, compressing splitter margins during low-yield quarters.
- Supply concentration risk:Over 80% of global kernel crushing capacity sits within Indonesia and Malaysia, exposing buyers to simultaneous regulatory or logistics disruptions across both origins.
- Substitution threat from coconut oil:Philippine and Sri Lankan coconut oil processors compete for identical lauric acid market segments, with price arbitrage periodically displacing kernel oil in surfactant formulations.
Strategic Opportunities
- Underpenetrated African processing:Nigeria and Ghana possess expanding oil palm estates but minimal kernel fractionation infrastructure, creating first-mover openings for integrated plantation-to-refinery investments.
- Emerging pharmaceutical-grade applications:Injectable emulsion and infant nutrition manufacturers are qualifying refined kernel oil fractions for drug master file submissions, opening premium pricing tiers.
- EU Green Deal bio-based mandate:Renewable carbon content requirements for surfactants and lubricants are creating preferential offtake terms for certified-sustainable kernel-derived oleochemicals.
Industry Challenges
- Certification timeline compression:MSPO and ISPO audit backlogs are extending certification cycles to 18-24 months, delaying contract eligibility with multinational personal care brands.
- Fractionation technology capex intensity:High-pressure splitting and molecular distillation units require 40-60 million dollar investments per facility, limiting market entry to capitalized plantation groups.
- Legacy traceability system integration:Smallholder cooperative databases must interface with blockchain-enabled European buyer platforms, creating data standardization friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elaeis Guineensis Kernel Oil Market |
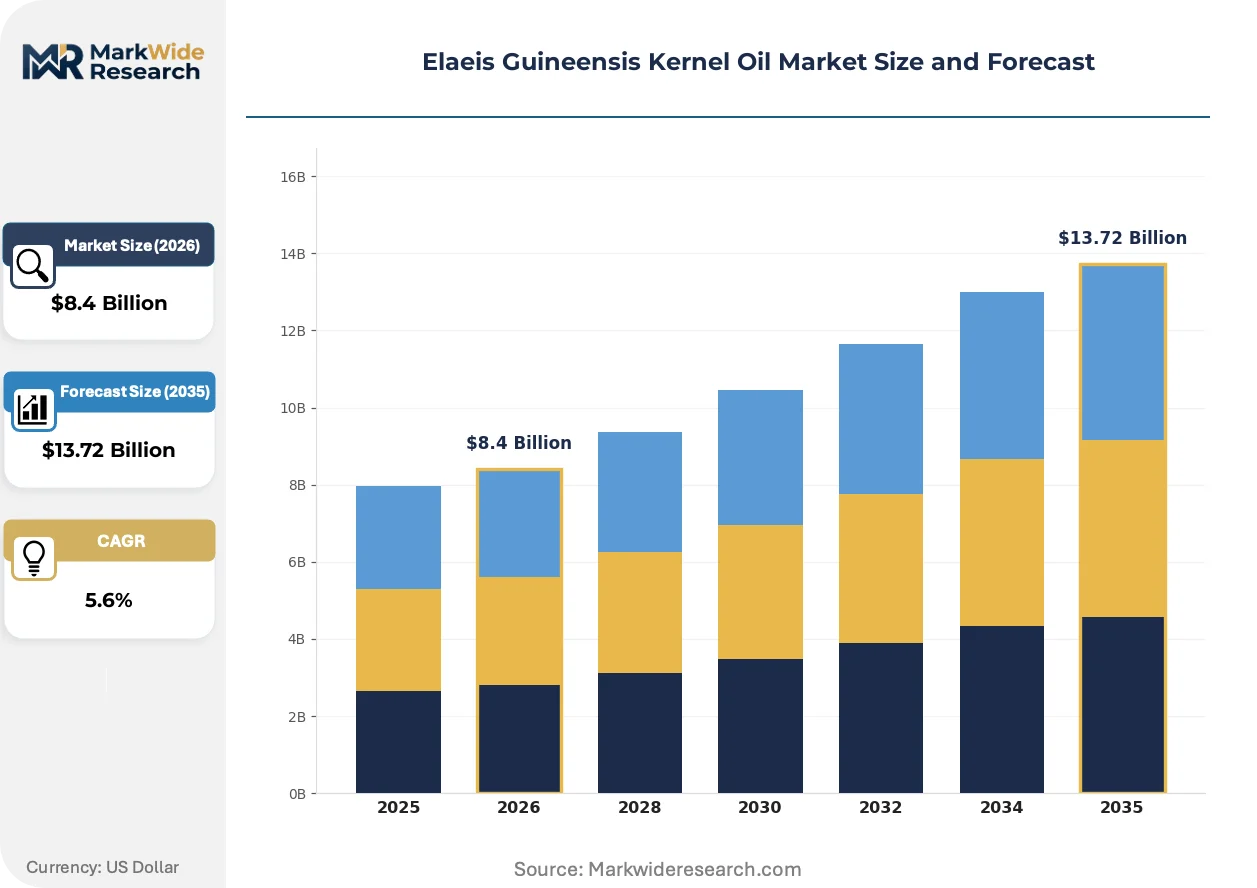
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Virgin Oil, Palm Kernel Cake Application: Cosmetics, Food Industry, Biofuels, Pharmaceuticals End User: Manufacturers, Retailers, Food Processors, Personal Care Brands Packaging Type: Bottled, Bulk, Tetra Packs, Jerry Cans |
| Companies Covered | Wilmar International, Sime Darby Plantation, IOI Corporation, Kuala Lumpur Kepong Berhad, Cargill, Golden Agri-Resources, Musim Mas Holdings, Bunge Limited, AAK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elaeis Guineensis Kernel Oil Market Shifts & Advancements
Digital traceability infrastructure and precision fractionation technologies are converging to transform how kernel oil moves from plantation to formulated end-product, with sustainability verification becoming inseparable from quality assurance.
Supercritical CO2 fractionation is integrating into select Malaysian refineries to extract pharmaceutical-grade medium-chain triglycerides without thermal degradation. European nutraceutical contract manufacturers are qualifying these outputs for infant formula applications at accelerated pace. This technology is integrating premium positioning into previously commodity-grade supply chains, compressing price spreads between food and pharmaceutical grades.
REACH registration requirements are tightening documentation burdens for kernel oil importers into the European Union, with ECHA now demanding full substance identity profiles for every C12-C14 derivative category. Downstream surfactant blenders are consolidating supplier lists to processors with complete dossier compliance. Personal care brands with European manufacturing footprints are most affected, shifting procurement toward MSPO-certified Malaysian estates with pre-filed technical packages.
Direct estate-to-brand contracting is displacing traditional trader-mediated spot purchases as personal care multinationals seek deforestation-risk insulation. Long-term offtake agreements now specify plantation GPS coordinates and audit frequencies rather than standard quality specifications. This pattern is most visible in Northern European markets, where REACh compliance officers hold veto power over supplier onboarding decisions.
Elaeis Guineensis Kernel Oil Market Segmentation
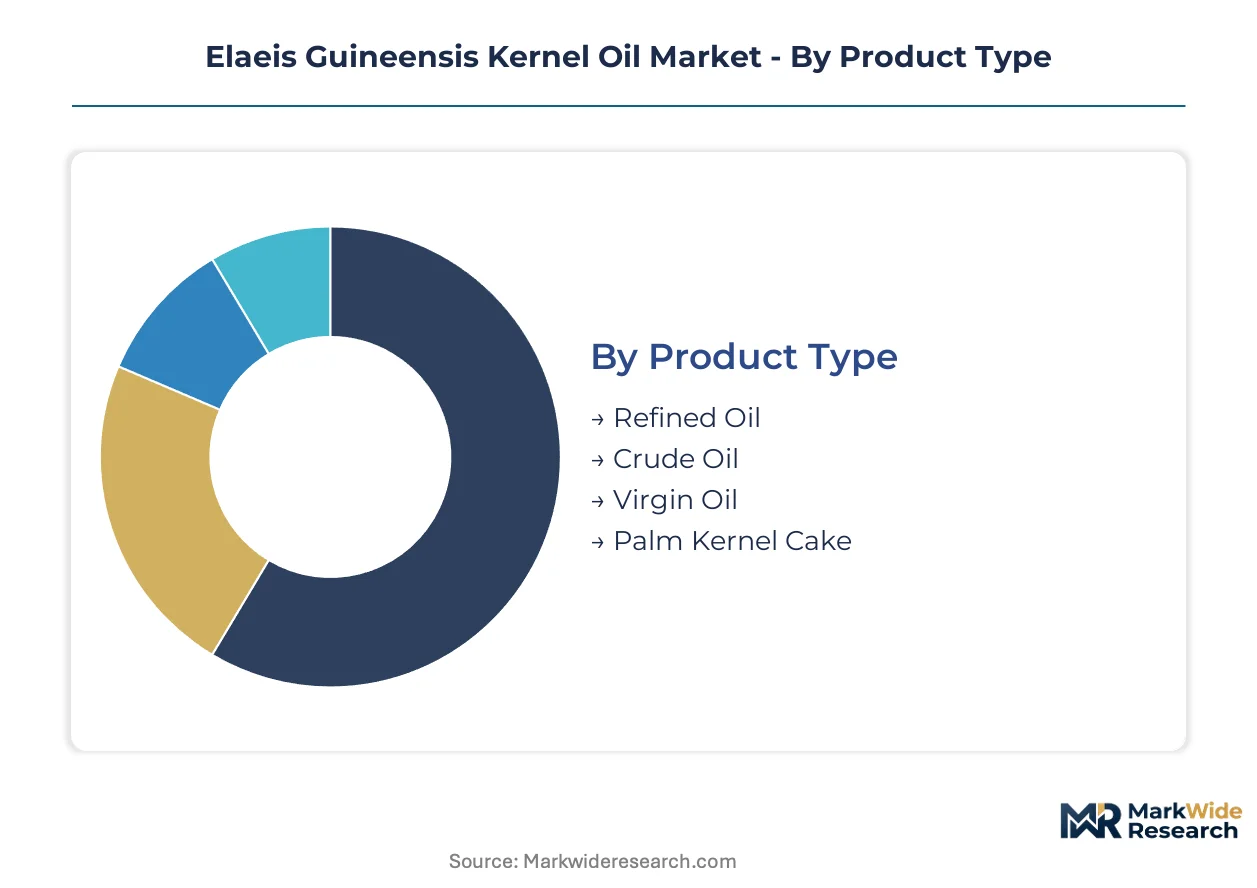
Kernel oil segmentation reflects divergent processing intensities and certification thresholds. Refined grades command premium positioning in pharmaceutical and personal care channels, while crude streams flow to integrated refiners with captive oleochemical capacity.
Product Type:
Refined oil sits at the apex of value capture, serving direct formulation in cosmetics and infant nutrition. Virgin and crude grades operate in embedded supply chains, feeding downstream fractionation rather than reaching end markets independently.
- Refined Oil:High-pressure splitting and molecular distillation yield pharmaceutical-grade C12-C14 fractions with complete contaminant removal. European nutraceutical contract manufacturers absorb expanding volumes for infant formula emulsions, driven by ECHA REACH dossier requirements that filter out uncertified processors.
- Crude Oil:Unfractionated kernel oil with 40-50% lauric acid content flows predominantly to integrated plantation-to-refinery complexes in Indonesia and Malaysia. Captive crushing capacity insures processors against El Niño-driven fresh fruit bunch yield volatility.
- Virgin Oil:Cold-pressed extraction preserves native tocopherol profiles for boutique cosmetic applications.
- Palm Kernel Cake:Solid residue from mechanical pressing supplies protein feedstock for livestock nutrition in Southeast Asian markets.
Volume placements concentrate in Crude Oil; the faster expansion belongs to Refined Oil.
Application:
Cosmetics and pharmaceuticals extract maximum margin through lauric acid-derived surfactant chemistry, while food and biofuel applications compete on scale economies rather than specification premiums.
- Cosmetics:Sulfate-free surfactant formulations are displacing traditional sodium lauryl sulfate in European and North American personal care products. Mild cleansing chemistry derived from C12-C14 fractions commands formulation priority in premium shampoo and facial cleanser lines.
- Pharmaceuticals:Injectable emulsion and parenteral nutrition manufacturers are qualifying refined kernel oil for drug master file submissions. Supercritical CO2 fractionation outputs from Malaysian refineries meet infant formula safety thresholds without thermal degradation.
- Food Industry:Medium-chain triglyceride incorporation into ketogenic and sports nutrition products diversifies demand beyond traditional confectionery fat applications.
- Biofuels:Fatty acid methyl ester production from lower-grade fractions supplies renewable diesel blendstock in EU Green Deal-compliant markets.
Cosmetics captures the dominant revenue share; pharmaceuticals is climbing the fastest.
End User:
Personal care brands and food processors exercise divergent procurement logics — the former prioritizing traceability documentation, the latter optimizing delivered cost through volume aggregation.
- Personal Care Brands:Northern European multinationals now specify plantation GPS coordinates and MSPO audit frequencies in long-term offtake agreements. Direct estate-to-brand contracting displaces trader-mediated spot purchases as deforestation-risk insulation becomes non-negotiable.
- Food Processors:Integrated plantation groups with captive kernel crushing capacity capture margin pools that fragment among independent traders.
- Manufacturers:Oleochemical splitters and fatty alcohol producers absorb the majority of crude kernel oil flows.
- Retailers:Private-label bottlers serve emerging market consumers through jerry can and bulk packaging formats.
Procurement scale concentrates with Manufacturers; specification premiums accrue to Personal Care Brands.
Packaging Type:
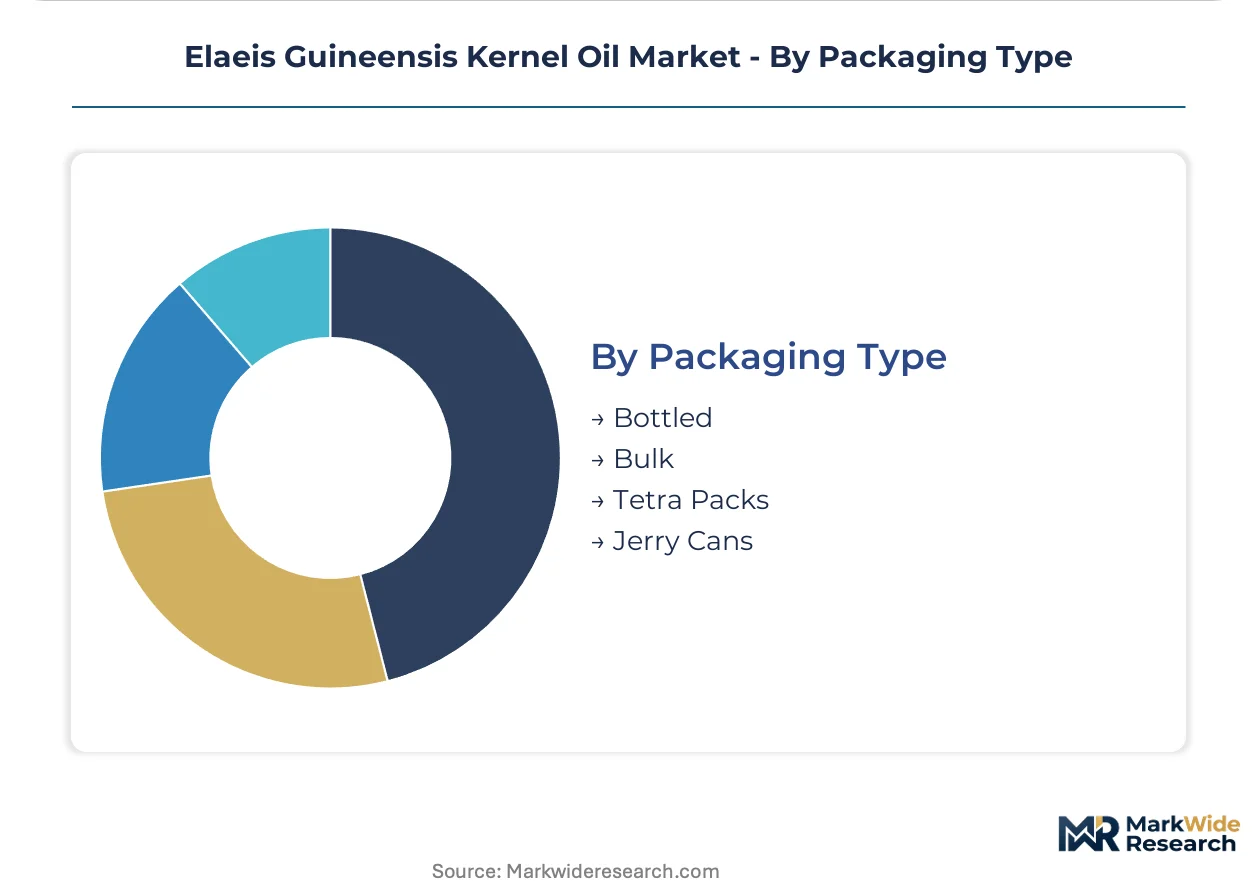
Bulk and jerry can formats dominate commercial flows, while bottled and tetra pack configurations serve retail channel differentiation in urban Southeast Asian markets.
- Bulk:ISO tank and flexitank shipments move refined fractions from Port Klang and Belawan to European and Chinese oleochemical hubs.
- Jerry Cans:20-liter polyethylene containers serve smallholder cooperative aggregation and regional food processor procurement in Indonesia.
- Bottled:Glass and PET formats target premium cosmetic and pharmaceutical shelf positioning.
- Tetra Packs:Aseptic cartons preserve virgin oil quality for health-food retail channels.
Shipment volumes cluster in Bulk; value per liter peaks in Bottled.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Kendal Industrial Park and Malaysia's Port Klang Free Zone concentrate integrated plantation-to-refinery complexes, drawing foreign direct investment through tax holidays and duty exemptions on oleochemical exports.
Indonesia
ISPO certification mandates for large estates are standardizing traceability infrastructure that European personal care brands now require. The Ministry of Agriculture enforces deforestation-free sourcing protocols through satellite monitoring of concession boundaries. Riau and North Sumatra host the densest kernel crushing clusters, where Wilmar International and Golden Agri-Resources operate captive fractionation facilities.
Malaysia
MSPO-certified estates supply pharmaceutical-grade refined fractions to Northern European nutraceutical contract manufacturers. The Malaysian Palm Oil Board administers sustainability audit protocols that compress certification cycles for integrated plantation groups. Johor and Sabah concentrate supercritical CO2 fractionation investments, with Port Klang serving as the primary export hub for C12-C14 derivative shipments.
Philippines
Coconut oil processors compete directly with palm kernel oil for identical lauric acid market segments in surfactant formulations. The Philippine Coconut Authority regulates quality standards for competing vegetable oil feedstocks. Davao Region and Quezon Province anchor coconut crushing capacity that periodically displaces kernel oil through price arbitrage.
Thailand
Medium-chain triglyceride demand from sports nutrition manufacturers is absorbing rising refined kernel oil volumes. The Thai Industrial Standards Institute mandates contaminant thresholds for food-grade oleochemical imports. Eastern Economic Corridor provinces host expanding oleochemical splitter investments targeting Chinese and Japanese offtake agreements.
Nigeria
Underdeveloped kernel fractionation infrastructure creates first-mover openings for integrated plantation-to-refinery investments. The National Agency for Food and Drug Administration and Control regulates edible oil safety standards that will extend to oleochemical derivatives. Edo and Ondo States possess expanding oil palm estates with minimal downstream processing capacity.
Elaeis Guineensis Kernel Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated plantation groups capturing margin pools that fragment among independent traders. The vendor base organizes around three strategic archetypes: estate-backed refiners with captive crushing capacity, merchant traders dependent on spot procurement, and oleochemical specialists with molecular distillation expertise. Dominant competitive moves include backward integration into certified kernel crushing assets and long-term offtake agreements specifying plantation GPS coordinates.
Among Southeast Asian plantation conglomerates, Wilmar International, Sime Darby Plantation, and Golden Agri-Resources exemplify the estate-backed refiner archetype. Wilmar International anchors Indonesian and Malaysian processing capacity through integrated assets. Sime Darby Plantation occupies a position defined by MSPO-certified estate coverage satisfying European audit requirements. Golden Agri-Resources represents scale-driven competitive positioning through large palm kernel crushing facilities.
| Leading Market Players |
|---|
| Wilmar International |
| Sime Darby Plantation |
| IOI Corporation |
| Kuala Lumpur Kepong Berhad |
| Cargill |
| Golden Agri-Resources |
| Musim Mas Holdings |
| Bunge Limited |
| AAK |
| Others |
Supply & Pricing Matrix
Skilled splitter operators in Riau and North Sumatra command wage premiums that widen spreads between pharmaceutical-grade and commodity-grade kernel oil fractions. Labor-cost differentials between Indonesian estate complexes and Malaysian supercritical CO2 facilities translate into tiered pricing bands that European nutraceutical buyers navigate through long-term offtake structures.
Pricing Analysis
Short lead-time premiums attach to MSPO-certified Malaysian estates with pre-filed REACH dossiers, while spot crude oil from independent traders trades at discounts reflecting documentation uncertainty. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels stratifies by certification completeness and splitting technology intensity. Pricing pressure stems from El Niño-driven fresh fruit bunch yield compression that tightens splitter feedstock availability. Personal care multinationals exhibit least price sensitivity due to deforestation-risk audit requirements, while regional food processors absorb maximum cost volatility.
Supply Chain Analysis
Freight cost differentials between Port Klang and Belawan shape procurement routing for European oleochemical hubs versus Chinese splitting facilities. Supply concentrates in Indonesia, Malaysia, and Thailand, with over four-fifths of global kernel crushing capacity anchored in the first two origins. The chain draws from fresh fruit bunch harvests, high-pressure splitting units, and molecular distillation columns. Single-source vulnerability runs through simultaneous regulatory disruptions across Indonesian ISPO and Malaysian MSPO audit cycles. Distribution runs through integrated plantation-to-refinery complexes that bypass trader-mediated spot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kernel oil supply is tightening around certified fractionation capacity, with supercritical CO2 facility investments creating a bottleneck that props pharmaceutical-grade pricing premiums.
For Market Incumbents: To counter coconut oil substitution from Philippine processors, secure backward integration into ISPO-certified kernel crushing assets in Riau and North Sumatra while expanding MSPO audit frequency specifications in European personal care contracts. Channel control through direct estate-to-brand GPS-coordinate contracting insulates against trader margin erosion. For New Entrants and Emerging Players: Specialty chemical distributors in Northern Europe represent the most accessible channel partners for pharmaceutical-grade qualification pathways. White-space targets include Nigerian estate-to-refinery complexes in Edo and Ondo States and infant nutrition emulsion applications requiring drug master file submissions. A certification-first go-to-market approach accelerates contract eligibility with multinational personal care brands. For Investors and Strategic Acquirers: The window for entry favors integrated plantation groups with captive crushing capacity and pre-established sustainability audit infrastructure. Long-term viability hinges on exposure to EU Green Deal bio-based surfactant mandates and nutraceutical MCT demand expansion. Watch for EU Deforestation Regulation implementation timelines as the inflection signal for contract eligibility restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Crushing | Captive ISPO and MSPO-certified feedstock secures contract eligibility with European personal care multinationals. |
| Supercritical CO2 Fractionation Investment | Non-thermal extraction technology qualifies output for infant formula drug master file submissions. |
| Long-term Offtake Agreement Structuring | Plantation GPS coordinate specifications satisfy EU Deforestation Regulation traceability mandates. |
| Pharmaceutical-grade Quality Certification | ECHA REACH dossier completion filters supplier lists for European nutraceutical contract manufacturers. |
| African Processing Capacity Buildout | First-mover positioning in Nigerian estate-to-refinery complexes captures underpenetrated West African supply. |
Research Methodology
Document review covered customs and trade flow databases, Malaysian Palm Oil Board sustainability reports, and ECHA REACH registration filings, complemented by interviews with plantation operations directors, oleochemical procurement leads at European personal care brands, splitter facility engineers, and Indonesian Ministry of Agriculture certification officers. Secondary validation drew from FDA food-contact substance notifications, EU Deforestation Regulation implementation guidance, and SEC filings of integrated plantation groups. Bottom-up volume modeling triangulated against top-down value estimates across product grade and application segments.
Output projections span crude, refined, and virgin oil grades across cosmetics, pharmaceuticals, food, and biofuel applications, incorporating oleochemical splitter capacity utilization rates and certification audit cycle durations throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves for lauric acid-derived surfactants and medium-chain triglyceride nutraceutical absorption. Model inputs included El Niño frequency patterns affecting fresh fruit bunch yields and EU Green Deal bio-based mandate compliance timelines.
Several conditions sit outside the modeled scope, including abrupt ISPO or MSPO regulatory revisions, trade policy shifts affecting Indonesian or Malaysian export tariffs, and breakthrough coconut oil processing technologies that alter lauric acid feedstock economics. Forecasts reflect assumptions about sustained European personal care brand deforestation-risk audit intensity and stable nutraceutical MCT demand growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
United Kingdom Animal Protein Market