
 Ginseng Market | 2026-2036
Ginseng Market Size, Share, and Industry Trends Forecast 2026-2036
Ginseng Market Analysis
Wild-simulated and certified-organic tier ginseng is reorganizing procurement priorities across nutraceutical supply chains. Korea Ginseng Corp leverages its vertical integration from cultivation to finished extract, sustaining price stability for red ginseng concentrates. Jilin Zixin Pharmaceutical Industrial anchors the Chinese supply base through its Changbai Mountain growing operations. Nature's Way Products LLC differentiates via stringent USP-verified capsule formulations that command retail shelf placement.
Ginseng comprises slow-growing perennial roots from Panax species, principally Panax ginseng and Panax quinquefolius, valued for ginsenoside triterpene saponins that typically range from two to eight percent by dry weight in commercial grades; these bioactive compounds serve as standardized inputs for adaptogenic supplements, functional beverages, and dermal cosmetic formulations. Red ginseng concentrates capture the dominant value pool due to labor-intensive steaming and drying protocols that concentrate bioactive fractions, while pharmaceutical company demand for extract-grade material is expanding fastest as drug-adjacent research into ginsenoside Rg1 and Rb1 mechanisms advances through clinical pipelines. Capsule and extract forms dominate finished-product margins, whereas raw root trading remains fragmented with price volatility tied to harvest cycles.
The FDA's dietary supplement Current Good Manufacturing Practice enforcement shapes US market access through identity-testing mandates, while South Korea's Ministry of Food and Drug Safety governs red ginseng grading under national standards that restrict geographic-origin labeling. China's National Medical Products Administration aligns ginseng-derived pharmaceutical raw materials with pharmacopoeial monographs that dictate export eligibility. Stakeholders must monitor evolving extraction-technology patents and shifting organic-certification reciprocity agreements between major producing jurisdictions.
Market Dynamics
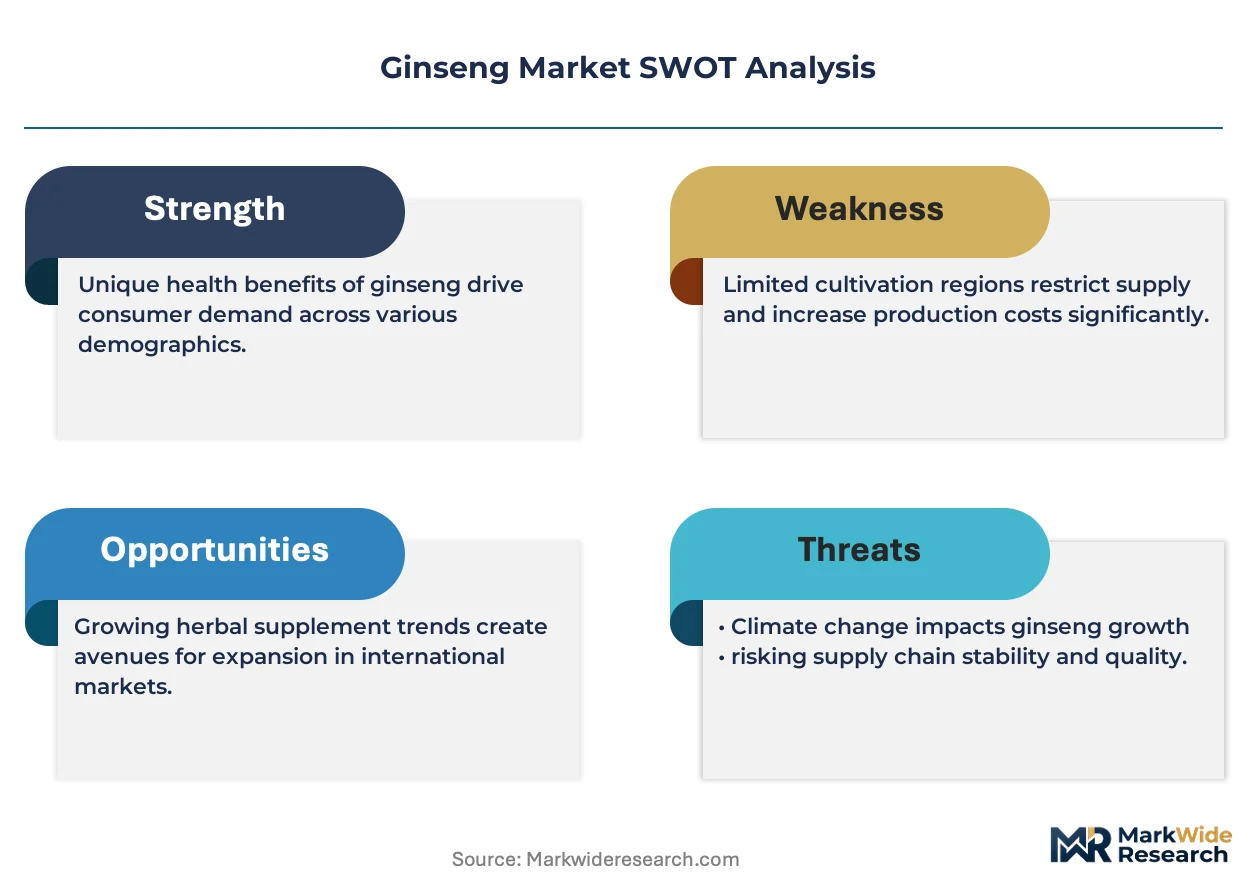
The Ginseng Market is undergoing structural reorganization as pharmaceutical procurement standards diverge from nutraceutical sourcing norms, with extraction-grade specifications tightening faster than finished-product formulations can absorb.
Growth Catalysts
- Pharmaceutical Pipeline Expansion:Drug-adjacent research into ginsenoside Rg1 and Rb1 mechanisms is accelerating clinical validation, pulling premium extract-grade material into formal therapeutic development channels.
- MFDS Red Ginseng Grading:South Korea's Ministry of Food and Drug Safety national standards restrict geographic-origin labeling, creating certified scarcity premiums that concentrate value in authenticated Geumsan supply.
- Steam-Processing Innovation:Labor-intensive red ginseng steaming and drying protocols now incorporate precision temperature controls that standardize bioactive fraction concentration across harvest cycles.
Market Restraints
- Input Cost Volatility:Six-year root maturation requirements for Panax ginseng create fixed supply inelasticity against demand surges, amplifying price swings during poor harvest seasons.
- Geographic Supply Concentration:Over seventy percent of certified-organic wild-simulated root originates from China's Changbai Mountain corridor, exposing buyers to single-region climate and policy risks.
- FDA NDI Notification Friction:The New Dietary Ingredient pathway imposes identity-testing mandates that extend time-to-market for novel extract formulations by twelve to eighteen months.
Strategic Opportunities
- Underpenetrated US Functional Beverage Channel:Adaptogenic drink formulations remain formulation-constrained rather than demand-constrained, with ginsenoside stability in liquid matrices representing solvable technical white space.
- EU Organic Certification Reciprocity:Evolving mutual recognition agreements between Korean and European organic standards bodies are reducing dual-certification costs for export-oriented cultivators.
- Dermal Cosmetic Convergence:Ginsenoside incorporation into topical delivery systems is crossing from traditional medicine positioning into dermatological active ingredient status.
Industry Challenges
- Ginsenoside Analytical Talent Scarcity:Standardized HPLC quantification of complex saponin profiles requires specialized phytochemistry expertise that outpaces academic program output.
- Legacy Raw Root Trading Infrastructure:Fragmented auction and broker networks for unprocessed material resist price transparency mechanisms that extract-grade buyers now demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ginseng Market |
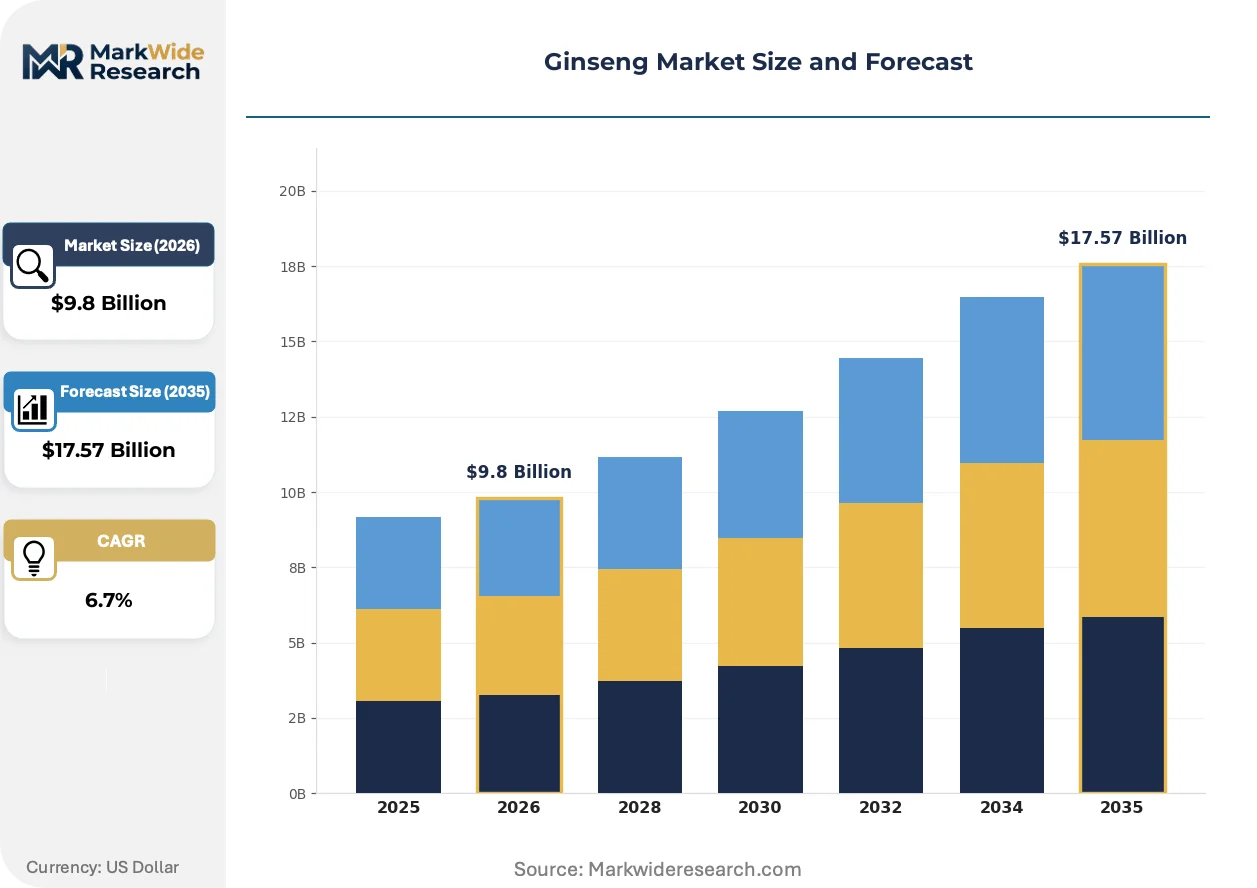
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Ginseng, White Ginseng, American Ginseng, Powder End User: Retail Consumers, Health Stores, Pharmaceutical Companies, Food & Beverage Industry Form: Capsules, Extracts, Teas, Raw Root Application: Health Supplements, Cosmetic Products, Nutritional Enhancers, Traditional Medicine |
| Companies Covered | Nature's Way Products LLC, Hain Celestial, Korea Ginseng Corp, The Boots Company, Jilin Zixin Pharmaceutical Industrial, Amway, Glanbia, Clariant AG, Herbalife Nutrition Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ginseng Market Emerging Trajectories
Extraction technology patents and cultivation automation are redistributing value capture between root growers and finished-product formulators, with intellectual property positioning overtaking acreage control as the primary competitive lever.
Supercritical CO2 extraction systems are fragmenting the ginsenoside recovery market by enabling selective fractionation that solvent-based methods cannot replicate. Pharmaceutical contract manufacturers are adopting these units at pilot scale to secure R&D-grade material with documented batch consistency. The technology is fragmenting premium extract supply chains into equipment-haves and equipment-have-nots, compressing margins for conventional ethanol processors.
China's NMPA alignment of ginseng-derived pharmaceutical raw materials with pharmacopoeial monographs is hardening export eligibility criteria for extract-grade shipments. Domestic processors must now maintain dual documentation streams for pharmaceutical versus nutraceutical channels. Korean red ginseng concentrate exporters are responding by pre-qualifying facilities under both NMPA and MFDS protocols to preserve cross-border flexibility.
Direct-procurement relationships between finished-product brands and certified-organic cultivators are displacing traditional broker-mediated spot markets for premium tier root. Contract structures now specify ginsenoside minimums and harvest-window exclusivity rather than weight-based pricing. This pattern is most visible in South Korea's Geumsan region, where vertical brand-cultivator partnerships are capturing margin that previously accrued to trading intermediaries.
Ginseng Market Segmentation
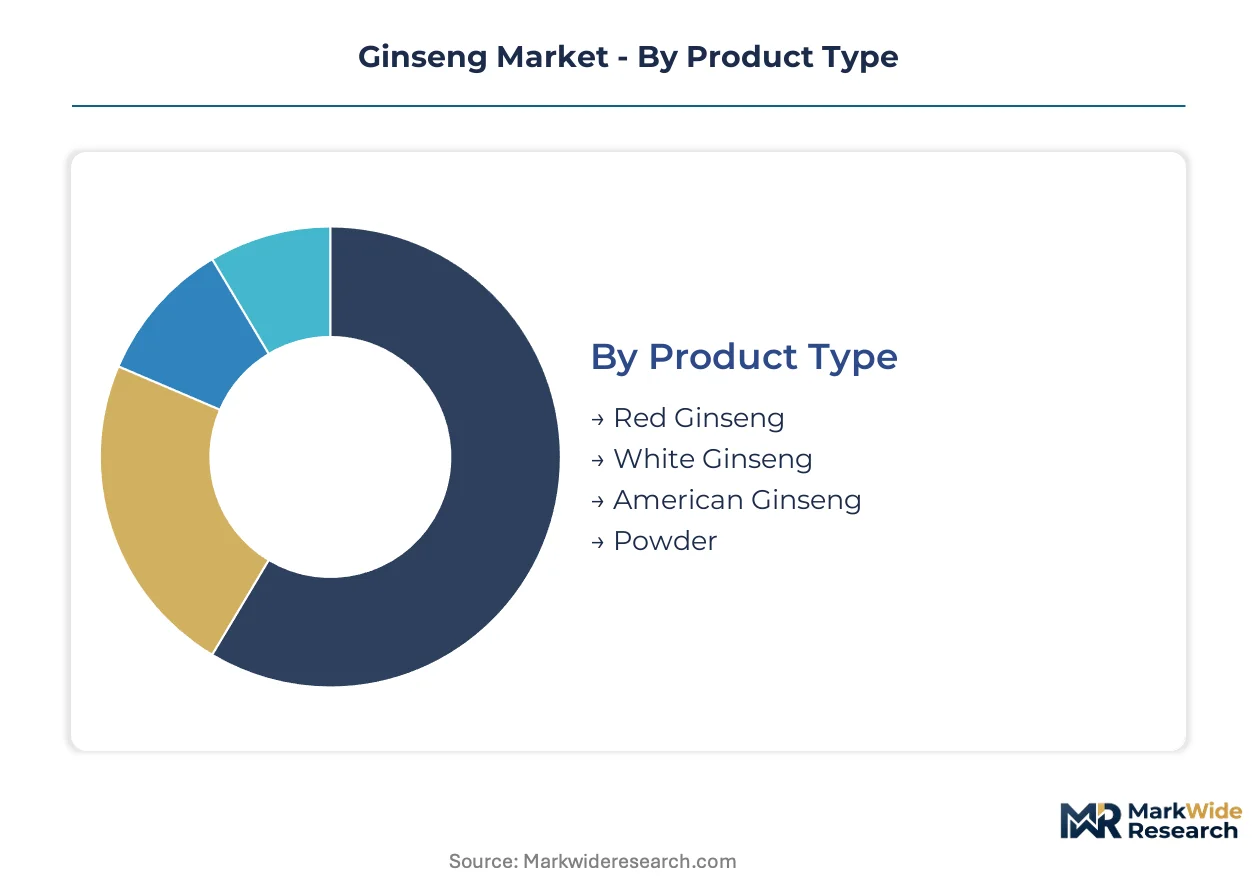
Ginseng procurement strategies diverge sharply across product tiers and end-use specifications. Pharmaceutical extract-grade requirements impose purity benchmarks that nutraceutical channels cannot absorb, fragmenting supplier qualification pathways.
Product Type:
MFDS red ginseng grading protocols and FDA identity-testing mandates create divergent compliance burdens across processing categories.
- Red Ginseng:Steam-processed Panax ginseng roots undergo labor-intensive six-year maturation cycles that concentrate ginsenoside Rg1 and Rb1 fractions. South Korea's Geumsan region dominates authenticated supply chains, with MFDS geographic-origin labeling restricting certified scarcity premiums to pre-qualified cultivators.
- White Ginseng:Air-dried roots retain native saponin profiles without thermal modification, serving traditional medicine practitioners who prioritize unaltered phytochemical signatures. China's Changbai Mountain corridor anchors wild-simulated organic production, though climate volatility amplifies harvest-cycle price swings.
- American Ginseng:Panax quinquefolius cultivation concentrates in Wisconsin and Ontario growing regions, with distinct ginsenoside ratios favoring calming rather than stimulating applications.
- Powder:Milled root material commands commodity pricing in bulk supplement formulations, with particle-size specifications varying by encapsulation equipment requirements.
Red ginseng handles the majority of throughput; American ginseng is gaining share fastest in North American functional beverage channels.
End User:
Procurement scale and specification rigor separate institutional buyers from retail-channel distributors.
- Retail Consumers:Direct-to-purchaser brands emphasize USP-verified capsule formulations and organic certification badges that command shelf placement premiums in pharmacy chains.
- Health Stores:Independent supplement retailers stock mid-tier extract products with ginsenoside percentage claims on primary packaging, sourcing through regional distributors rather than direct cultivator relationships.
- Pharmaceutical Companies:Drug-adjacent R&D pipelines demand batch-documented extract-grade material with HPLC-quantified saponin profiles, pulling premium supply into formal therapeutic development channels.
- Food & Beverage Industry:Adaptogenic drink manufacturers face ginsenoside stability challenges in liquid matrices, constraining formulation options despite expanding consumer interest.
Pharmaceutical companies drive specification tightening; food and beverage represents the steepest expansion trajectory as technical barriers erode.
Form:
Finished-product margins concentrate in processed formats while raw root trading retains auction-market fragmentation.
- Capsules:Encapsulated powder and standardized extracts dominate retail shelf space, with USP verification programs differentiating premium positioning from commodity alternatives.
- Extracts:Concentrated liquid and powdered preparations capture value-added margins through supercritical CO2 fractionation that conventional solvent methods cannot replicate.
- Teas:Whole-root and cut-and-sift preparations serve traditional consumption patterns in East Asian markets, with convenience formats expanding in Western channels.
- Raw Root:Unprocessed material trades through broker-mediated spot markets that resist price transparency mechanisms, exposing buyers to harvest-cycle volatility.
Capsules handle the majority of finished-product volume; extracts are climbing the fastest on margin capture.
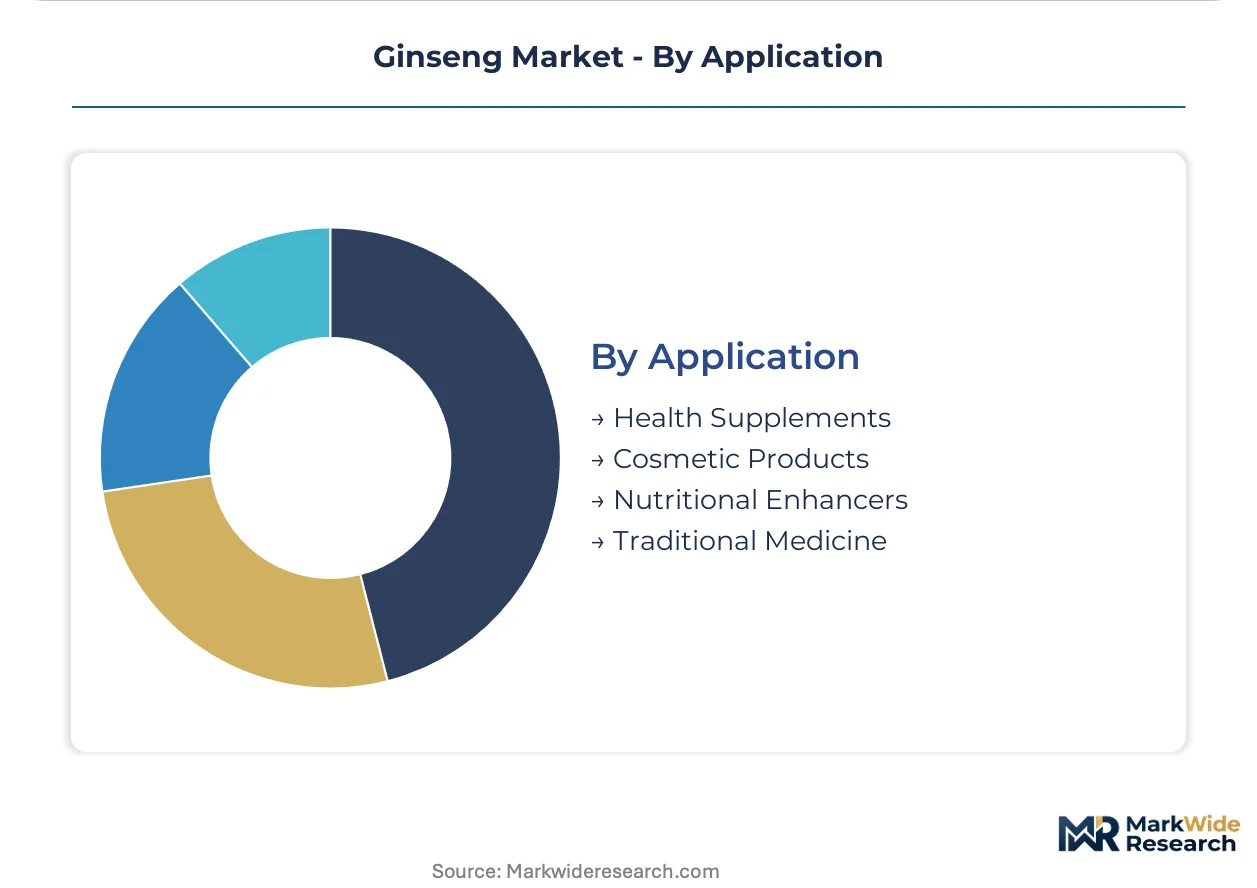
Application:
Regulatory jurisdiction determines permissible health claims and distribution channel access.
- Health Supplements:Dietary supplement positioning requires FDA NDI notification for novel extract formulations, extending time-to-market by twelve to eighteen months for innovative delivery systems.
- Cosmetic Products:Topical ginsenoside applications are crossing from traditional medicine positioning into dermatological active ingredient status, with Korean and French formulators leading clinical validation.
- Nutritional Enhancers:Functional food fortification faces stability and taste-mask challenges that constrain incorporation rates despite technical solvability.
- Traditional Medicine:Practitioners of Korean and Chinese medicine systems prioritize whole-root authenticity and provenance documentation over standardized potency metrics.
Health supplements handle the majority of commercial volume; cosmetic products are expanding most quickly as dermatological validation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seventy percent of certified-organic wild-simulated ginseng root originates from China's Changbai Mountain corridor, exposing procurement networks to single-region climate and policy risks. South Korea's Geumsan region and Wisconsin's Marathon County anchor authenticated red ginseng and American ginseng supply respectively. The analysis tracks five countries where cultivation concentration, regulatory frameworks, and processing infrastructure intersect.
China
Changbai Mountain corridor cultivators supply the majority of wild-simulated organic root to global nutraceutical channels. NMPA pharmacopoeial monographs now govern ginseng-derived pharmaceutical raw materials, hardening export eligibility for extract-grade shipments. Jilin Province processors maintain dual documentation streams to preserve cross-border flexibility into both pharmaceutical and nutraceutical channels.
South Korea
Geumsan region cultivators command scarcity premiums through MFDS geographic-origin labeling restrictions. Steam-processing facilities incorporate precision temperature controls that standardize bioactive fraction concentration. Vertical brand-cultivator partnerships in Geumsan are capturing margin previously accrued to trading intermediaries through contract structures specifying ginsenoside minimums.
United States
Wisconsin's Marathon County and Ontario growing regions concentrate Panax quinquefolius cultivation for calming-application formulations. FDA dietary supplement Current Good Manufacturing Practice enforcement shapes market access through identity-testing mandates. Nature's Way Products LLC anchors US retail positioning through USP-verified capsule formulations commanding pharmacy chain shelf placement.
Canada
Ontario growers supply distinct ginsenoside ratios favoring North American functional beverage channels. Health Canada maintains Natural Health Product Directorate oversight of ginseng extract licensing and label claims. Niagara Peninsula processing facilities face ginsenoside stability challenges in liquid matrices that constrain adaptogenic drink formulation options.
Germany
Specialty pharmaceutical importers demand batch-documented extract-grade material with HPLC-quantified saponin profiles for drug-adjacent R&D pipelines. EMA herbal medicinal product frameworks influence quality benchmarks that ripple through EU procurement specifications. Frankfurt-Rhine-Main distribution hubs consolidate extract shipments from Korean and Chinese origin points for European pharmaceutical contract manufacturers.
Ginseng Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the ginseng value chain. Supercritical CO2 extraction capabilities fragment premium extract supply into equipment-haves and equipment-have-nots, compressing margins for conventional ethanol processors. Three archetypes dominate: vertically integrated cultivator-processors with authenticated origin control, USP-verified finished-product formulators with retail shelf access, and pharmaceutical-grade extract specialists with batch-documentation protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure six-year root supply commitments against maturation-cycle inelasticity.
Among Korean integrated cultivator-processors, Korea Ginseng Corp exemplifies vertical control from Geumsan cultivation through finished extract production. Within Chinese pharmaceutical supply, Jilin Zixin Pharmaceutical Industrial occupies a position anchored to Changbai Mountain growing operations. At the US retail-formulation tier, Nature's Way Products LLC represents USP-verified positioning that differentiates shelf placement in pharmacy channels. These three players illustrate how geographic origin authentication, regulatory compliance depth, and finished-product brand equity constitute separable competitive dimensions.
| Leading Market Players |
|---|
| Nature's Way Products LLC |
| Hain Celestial |
| Korea Ginseng Corp |
| The Boots Company |
| Jilin Zixin Pharmaceutical Industrial |
| Amway |
| Glanbia |
| Clariant AG |
| Herbalife Nutrition Ltd |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction systems replacing solvent-based methods are redrawing procurement geography toward equipment-capable processors while compressing ethanol-processor margins. This substitution simultaneously concentrates value capture in Korean and Chinese facilities with capital access and fragments pricing power across conventional extraction tiers.
Pricing Analysis
MFDS geographic-origin labeling dictates the pricing tier structure for red ginseng concentrates, separating authenticated Geumsan supply from unverified alternatives. Three-tier pricing structure across premium certified-origin, standard extract-grade, and economy bulk-powder levels reflects ginsenoside minimum guarantees and harvest-window exclusivity. Cost compression in standard extract-grade material is intensifying because pharmaceutical buyers now demand batch-documented HPLC profiles that conventional processors cannot supply. Health stores and independent supplement retailers exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb premium tier pricing without volume elasticity.
Supply Chain Analysis
Container availability fluctuations on Busan-Rotterdam and Shanghai-Hamburg lanes are extending lead times for extract-grade shipments into European pharmaceutical contract manufacturers. Geographic supply concentrates in South Korea's Geumsan region, China's Changbai Mountain corridor, and Wisconsin's Marathon County. Raw material sourcing draws from six-year maturation root stock, supercritical CO2 extraction equipment, and USP-grade encapsulation inputs. Single-source vulnerability runs through the Changbai Mountain corridor's wild-simulated organic production. Distribution runs through direct brand-cultivator partnerships displacing traditional broker networks for premium tier root.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical pipeline expansion into ginsenoside Rg1 and Rb1 mechanisms is fragmenting demand into specification-divergent niches that reward specialized positioning over broad coverage.
For Market Incumbents: Compound authentication advantages by locking multi-year Geumsan cultivation contracts and pre-qualifying facilities under both NMPA and MFDS protocols. Incumbent processors face margin pressure from supercritical CO2 equipment-haves capturing pharmaceutical-grade premiums; backward integration into precision temperature-controlled steaming infrastructure preserves red ginseng concentrate margins against this threat. For New Entrants and Emerging Players: MFDS fast-track certification for geographic-origin labeling offers a regulatory entry wedge into scarcity-premium red ginseng positioning. The underpenetrated US functional beverage channel presents the most penetrable white space, with ginsenoside stability in liquid matrices representing solvable technical barriers that incumbent extract specialists have neglected. A direct-procurement contract structure specifying ginsenoside minimums rather than weight-based pricing secures cultivator relationships without broker intermediation. For Investors and Strategic Acquirers: The market sits at a specification-divergence phase that favors pharmaceutical-grade extract specialists with batch-documentation protocols over commodity root traders. Long-term viability across the projection horizon rests on intellectual property positioning in extraction technology patents rather than acreage control. Supercritical CO2 equipment adoption rates among Korean and Chinese processors signal inflection toward equipment-have margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Geumsan region partnerships secure six-year root supply commitments against maturation-cycle inelasticity. |
| Dual Regulatory Pre-Qualification | NMPA and MFDS protocol alignment preserves cross-border flexibility for pharmaceutical extract shipments. |
| Supercritical CO2 Equipment Deployment | Pharmaceutical contract manufacturers adopt pilot-scale units to secure R&D-grade material with documented batch consistency. |
| Direct Brand-Cultivator Partnerships | Contract structures specifying ginsenoside minimums capture margin previously accrued to trading intermediaries. |
| Functional Beverage Formulation Investment | Ginsenoside stability in liquid matrices represents solvable technical white space in underpenetrated US channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with red ginseng processors, pharmaceutical contract manufacturers, nutraceutical brand formulators, and MFDS regulatory affairs specialists. Secondary validation drew from FDA NDI notification filings, MFDS geographic-origin labeling standards, NMPA pharmacopoeial monographs, and USP verification program documentation. Bottom-up volume triangulation across cultivation acreage, extraction capacity, and finished-product shipments was cross-checked against top-down value estimates from import-export customs data and channel inventory audits.
Across the analysis window, the forecasting framework modeled product type segmentation by processing category, end-user procurement scale, finished-product form, and application regulatory jurisdiction. CAGRs were derived from elasticity-adjusted demand projections tied to pharmaceutical pipeline advancement rates and functional beverage technical barrier erosion. Industry-specific inputs included six-year root maturation cycle constraints, supercritical CO2 equipment adoption curves, and evolving organic-certification reciprocity agreement coverage.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical R&D investment and stable climate conditions in the Changbai Mountain corridor; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market