
 Global Industrial Hemp Market | 2026-2036
Global Industrial Hemp Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Hemp Market Analysis
The premium organic hemp segment is rebalancing away from commodity bulk fiber as certified regenerative cultivation commands contract premiums and traceability requirements harden. Manitoba Harvest Hemp Foods leverages its vertical supply chain from Canadian prairie farms to packaged goods shelves. Ecofibre Limited anchors its position through proprietary low-THC seed genetics and controlled Australian growing regions. HempFlax Group B.V. dominates European bast fiber processing with specialized decortication equipment and long-term automotive supply contracts.
Industrial hemp comprises Cannabis sativa L. cultivars containing less than 0.3% delta-9 THC by dry weight, valued for cellulose-rich bast fibers, oil-bearing seeds, and cannabinoid extracts. The plant requires no herbicides, sequesters carbon at high rates per hectare, and produces fibers with tensile strength comparable to glass fiber in composite applications. CBD extract commands the fastest value expansion as pharmaceutical and wellness formulators build validated supply chains, while raw fiber maintains volume leadership in automotive biocomposites and construction matting. Textiles application is maturing in denim and technical apparel blends, though margin pools concentrate in specialty stores and direct-to-brand distribution channels that capture full traceability premiums.
The USDA oversees U.S. hemp cultivation licensing through the Domestic Hemp Production Program, while the EU Green Deal and REACH framework shape European fiber and extract standards. China's NMPA and GB standards govern cannabinoid content thresholds and food-grade processing certifications, creating divergent compliance pathways for exporters. Stakeholders must monitor THC testing protocol harmonization between jurisdictions, as measurement method inconsistencies currently fragment cross-border seed and fiber trade.
Market Dynamics
THC threshold harmonization between jurisdictions is fragmenting cross-border seed trade and forcing processors to maintain parallel compliance systems for fiber, seed, and extract streams.
Growth Catalysts
- EU Green Deal biocomposite mandates:Automotive OEMs in Germany and France now specify hemp-reinforced thermoplastics in interior panel procurement contracts, pulling bast fiber demand from technical textile applications.
- CBD pharmaceutical pipeline validation:FDA IND approvals for cannabinoid therapeutics are hardening quality standards that propagate back to cultivation protocols and extraction facility investments.
- China's dual carbon goals:Provincial processors in Heilongjiang and Yunnan are expanding decortication capacity to supply domestic construction matting and export-oriented textile mills.
Market Restraints
- Input cost volatility in certified organic acreage:Regenerative cultivation protocols require multi-year rotation cycles that lock land out of higher-margin commodity crops, compressing farmer participation rates.
- Supply concentration in specialized decortication equipment:European and Canadian machinery builders control 90% of high-throughput bast fiber processing installations, creating bottleneck risk for new market entrants.
- Substitution threat from flax and jute fibers:Established textile supply chains for alternative cellulose sources maintain price advantages and shorter lead times in automotive and construction applications.
Strategic Opportunities
- Underpenetrated United States processing infrastructure:Post-2018 Farm Act cultivation expansion has outpaced domestic decortication and cannabinoid extraction capacity, creating import substitution potential for equipment suppliers and toll processors.
- Technology convergence of AI-driven spectral THC testing:Portable measurement devices combining near-infrared spectroscopy with machine learning classification are enabling real-time compliance verification at field and intake points.
- Regulatory tailwind from REACH bio-based material incentives:ECHA guidance on sustainable polymer feedstocks is opening procurement pathways for hemp fiber in EU automotive and packaging sectors previously reserved for petrochemical derivatives.
Industry Challenges
- Skill gap in cannabinoid extraction chemistry:Pharmaceutical-grade CBD isolation requires chromatography expertise scarce in legacy agricultural processing regions, forcing wage premiums and training program investments.
- Certification timeline compression for organic and regenerative claims:Third-party auditors face backlogs extending 18-24 months for new cultivation operations, delaying contract eligibility for premium supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Hemp Market |
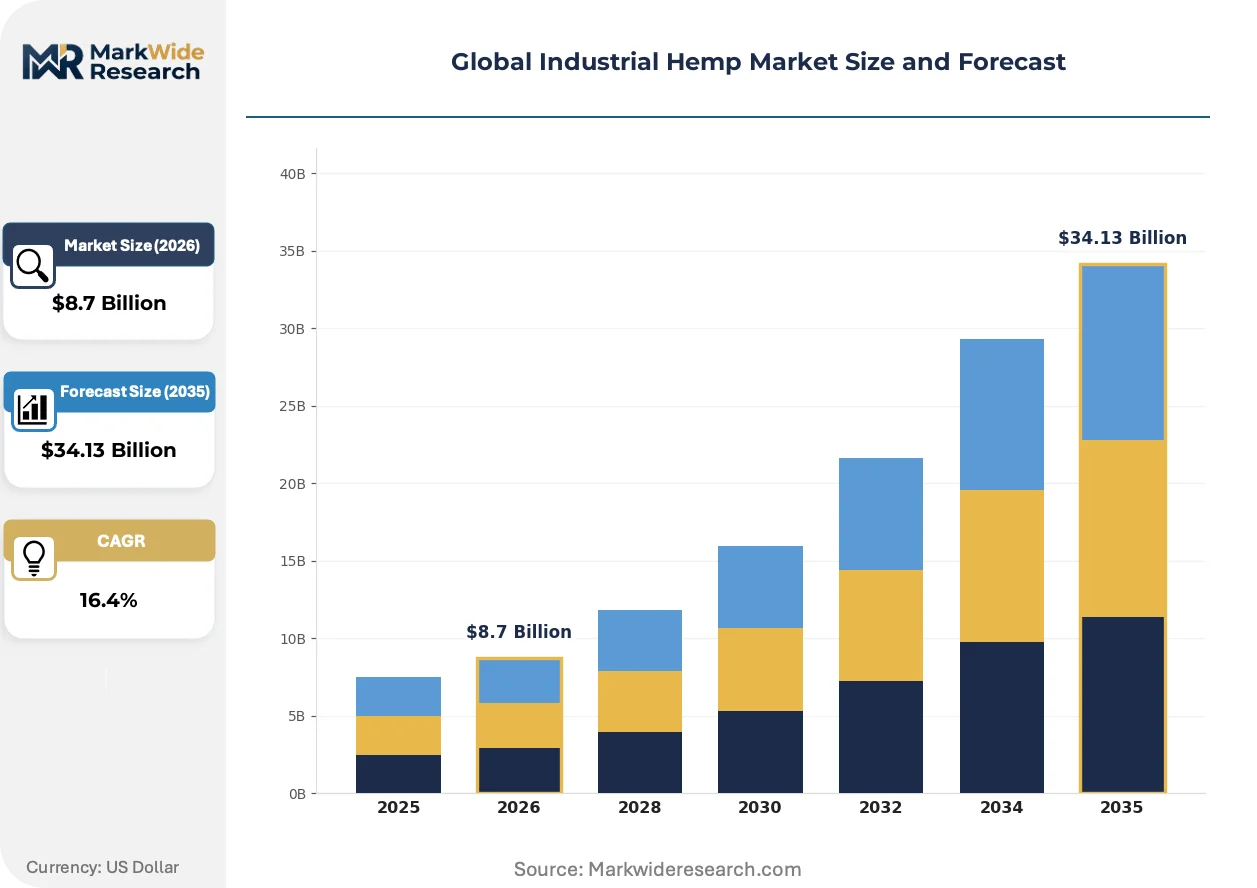
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Fiber, Seed, Oil, CBD Extract Application: Textiles, Construction, Food & Beverages, Personal Care End User: Manufacturers, Retailers, Agriculturalists, Researchers Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Manitoba Harvest Hemp Foods, Aurora Cannabis Inc., Parkland Industrial Hemp Growers Cooperative Ltd., Panda Biotech LLC, Charlotte's Web, Inc., HempFlax Group B.V., Canopy Growth Corporation, Curaleaf Holdings, Inc., Ecofibre Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Hemp Market Emerging Trajectories
Processing technology maturation and regulatory measurement standardization are compressing the gap between raw agricultural output and industrial-grade material specifications across fiber, seed, and extract categories.
Water-retting replacement by enzymatic bast fiber separation is overtaking traditional field decomposition in European and North American operations. Specialized cellulase formulations from Novozymes and DuPont are cutting retting duration from weeks to hours while improving fiber consistency. Automotive composite suppliers in Germany and tier-one textile mills in China are specifying enzymatically processed hemp to meet tighter tensile strength tolerances.
REACH framework updates on bio-based polymer feedstock traceability are forcing fiber processors to implement chain-of-custody documentation from farm to final compounder. ECHA guidance published in 2023 requires mass-balance accounting for hemp-derived cellulose used in automotive and construction applications. Dutch and Belgian decortication facilities are investing in blockchain-verified tracking systems to maintain EU market access.
Direct-to-brand contracting is displacing commodity spot markets for premium textile fiber. Denim manufacturers in Los Angeles and Amsterdam are signing multi-year offtake agreements with specific Canadian and Romanian farms, bypassing traditional merchant intermediaries. This procurement compression is most visible in technical apparel segments where regenerative certification commands measurable price premiums over conventional organic grades.
Global Industrial Hemp Market Segmentation
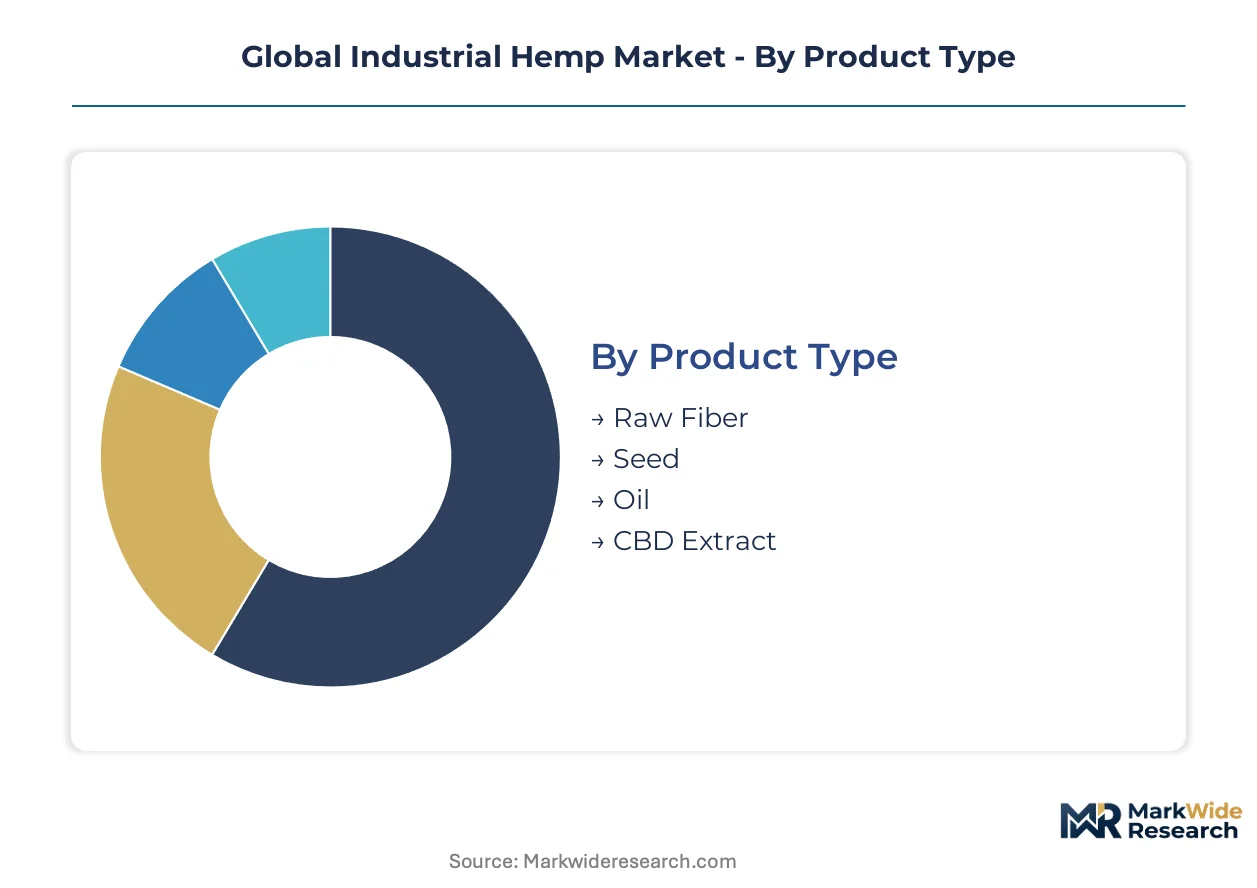
Industrial hemp's four-category segmentation reflects divergent processing requirements and regulatory pathways. Each category carries distinct margin profiles and compliance burdens that reshape procurement strategies across fiber, food, and pharmaceutical applications.
Product Type:
Supply concentration in bast fiber processing equipment tilts commercial gravity toward raw material streams with lower capital barriers to entry.
- Raw Fiber:Cellulose-rich bast fibers from hemp stalks deliver tensile strength comparable to glass fiber in composite applications. German automotive OEMs and Chinese construction matting producers absorb the majority of high-quality decorticated output, though European machinery bottlenecks constrain new supplier entry.
- CBD Extract:Cannabinoid isolation from hemp biomass requires chromatography expertise and pharmaceutical-grade facility certifications. FDA IND approvals for cannabinoid therapeutics are hardening quality standards that propagate back to cultivation protocols and extraction investments in Colorado and Oregon.
- Seed:Oil-bearing grain varieties from Canadian prairie farms supply protein powder and shelled hemp heart markets through vertical supply chains.
- Oil:Cold-pressed seed oil serves cosmetics formulators and food-grade applications under divergent NMPA and USDA certification pathways.
Raw fiber absorbs the bulk of installed capacity; CBD extract is expanding most quickly.
Application:
Cost tier differentiation separates commodity construction matting from premium textile blends commanding regenerative certification premiums.
- Textiles:Technical apparel and denim manufacturers in Los Angeles and Amsterdam source enzymatically processed hemp to meet tighter tensile strength tolerances. Direct-to-brand contracting is displacing commodity spot markets as regenerative certification commands measurable price premiums over conventional organic grades.
- Construction:Hempcrete and insulation batts sequester carbon at high rates per hectare of cultivated input. China's dual carbon goals are pulling Heilongjiang and Yunnan provincial processors into expanded decortication capacity for domestic building material supply.
- Food & Beverages:Protein powders and dairy alternatives from Canadian and Australian operations compete on organic certification timelines.
- Personal Care:Seed oil and CBD topicals face REACH and FDA cosmetic ingredient disclosure requirements.
Construction applications anchor volume demand; textiles capture the steepest margin expansion trajectory.
End User:
Customer type determines specification stringency, with pharmaceutical formulators imposing traceability requirements far exceeding agricultural commodity standards.
- Manufacturers:Automotive composite suppliers and textile mills specify hemp-reinforced thermoplastics and technical fiber blends. EU Green Deal biocomposite mandates now require mass-balance accounting from farm to final compounder, forcing blockchain-verified tracking system investments.
- Researchers:Agricultural universities and cannabinoid pharmacology programs drive seed genetics development and low-THC cultivar validation.
- Retailers:Specialty grocers and natural product chains curate certified organic hemp food portfolios.
- Agriculturalists:Prairie and alpine farmers rotate hemp into regenerative cultivation cycles requiring multi-year land commitments.
Manufacturers concentrate procurement volume; researchers are gaining influence fastest over seed genetics development.
Distribution Channel:
Geography of end-use shapes channel selection, with EU automotive supply chains demanding direct contractual relationships bypassing merchant intermediaries.
- Direct Sales:Multi-year offtake agreements between Romanian and Canadian farms and tier-one denim manufacturers eliminate spot market exposure. This procurement compression captures full traceability premiums in technical apparel segments.
- Specialty Stores:Natural product retailers and hemp-focused boutiques curate premium CBD and food-grade assortments with organic certification display requirements.
- Online:E-commerce platforms aggregate smaller CBD extract and personal care purchases from fragmented wellness consumers.
- Supermarkets:Mass-market grocers in Germany and the United States stock shelled hemp hearts and protein powders under private label arrangements.
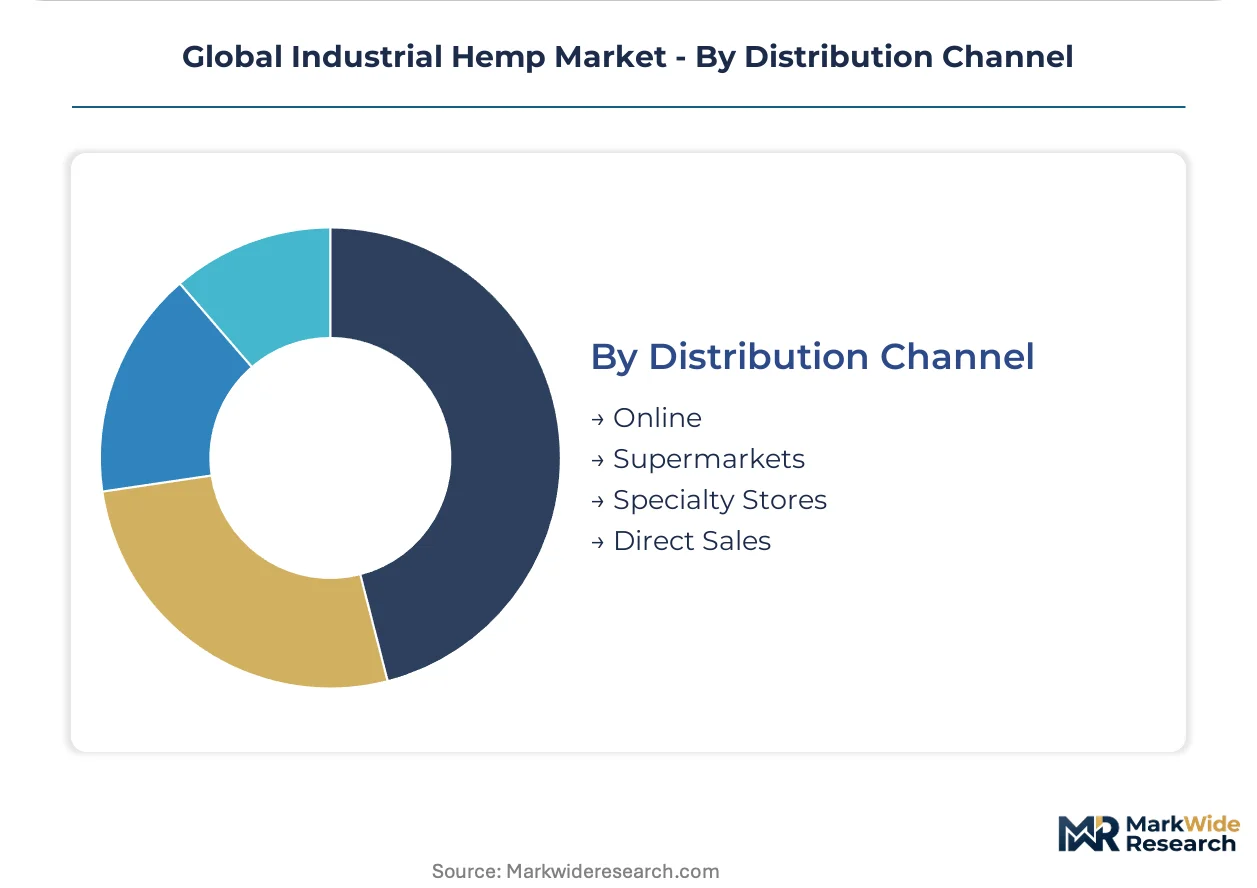
Direct sales command the highest value per ton; specialty stores are expanding shelf space fastest for certified organic grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heilongjiang province anchors China's industrial hemp processing expansion, with decortication clusters in Harbin and Mudanjiang supplying domestic construction matting and export-oriented textile mills. The province's dual carbon policy alignment is pulling provincial processors into expanded bast fiber capacity.
United States
Colorado and Oregon extraction facilities absorb the bulk of pharmaceutical-grade CBD isolation demand as FDA IND approvals harden quality standards. The USDA Domestic Hemp Production Program governs interstate cultivation licensing, though THC testing protocol fragmentation complicates cross-border seed trade. Post-2018 Farm Act cultivation expansion in Kentucky and Montana has outpaced domestic decortication capacity, creating toll processing bottlenecks.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify hemp-reinforced thermoplastics in interior panel procurement contracts under EU Green Deal biocomposite mandates. ECHA REACH framework updates require mass-balance accounting for hemp-derived cellulose, forcing blockchain-verified tracking investments at Dutch and Belgian border facilities. Bast fiber processing concentrates in Lower Saxony decortication corridors.
Canada
Prairie farms in Manitoba and Saskatchewan supply vertical supply chains from cultivation to packaged hemp hearts and protein powders. Health Canada oversees low-THC cultivar licensing while provincial organic certification backlogs extend 18-24 months for new operations. Winnipeg-based processors capture premium contract eligibility through established regenerative cultivation protocols.
Australia
Ecofibre Limited anchors controlled growing regions with proprietary genetics validation under TGA therapeutic goods oversight. New South Wales and Queensland processors face divergent state-level THC thresholds that fragment interstate seed commerce. Sydney and Melbourne extraction facilities serve Asia-Pacific wellness formulators building validated pharmaceutical supply chains.
Global Industrial Hemp Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across fiber, seed, and extract value streams. The market structures around three tiers: integrated agribusiness conglomerates controlling prairie-to-shelf supply chains, specialized decortication equipment operators dominating European bast fiber output, and pharmaceutical-grade extraction specialists concentrated in Colorado and Oregon. Consolidation pressures concentrate in processing infrastructure where machinery bottlenecks protect incumbent positions. Geographic expansion and backward integration into captive seed genetics represent the dominant competitive vectors.
Among North American integrated operators, Manitoba Harvest Hemp Foods exemplifies vertical supply chain control from prairie cultivation to retail shelf placement. HempFlax Group B.V. occupies the European machinery-dependent tier through Dutch decortication specialization. Ecofibre Limited represents the proprietary genetics archetype with Australian-controlled growing regions and low-THC cultivar development. These three anchors illustrate how competitive positioning stratifies across capital intensity, regulatory navigation, and intellectual property control rather than scale alone.
| Leading Market Players |
|---|
| Manitoba Harvest Hemp Foods |
| Aurora Cannabis Inc. |
| Parkland Industrial Hemp Growers Cooperative Ltd. |
| Panda Biotech LLC |
| Charlotte's Web, Inc. |
| HempFlax Group B.V. |
| Canopy Growth Corporation |
| Curaleaf Holdings, Inc. |
| Ecofibre Limited |
| Others |
Supply Flow & Price Mechanics
Bast fiber spot indices in European trading hubs cascade through three distinct pricing tiers as regenerative certification premiums separate contract-grade supply from commodity bulk. Canadian prairie processors capture upstream value through in-house decortication, while toll-dependent operators in Kentucky absorb margin compression from machinery bottlenecks and cross-border THC testing inconsistencies.
Pricing Analysis
Yield-based contract structures anchor premium tiers to fiber tensile performance in automotive composite specifications. Price differentiation separates enzymatically processed bast fiber meeting German OEM tolerances from field-retted grades sold into construction matting. Cost compression in standard-grade fiber runs through substitution threats from flax and jute supply chains. Construction material buyers exhibit highest price sensitivity; pharmaceutical CBD formulators show lowest sensitivity due to traceability requirements.
Supply Chain Analysis
Transatlantic freight cost volatility from Rotterdam to Charleston directly shapes margin allocation between European decortication specialists and U.S. toll processors. Supply concentrates in the Netherlands, Canada, and China for high-throughput bast fiber equipment. Raw material flows draw from Heilongjiang stalk supply, Manitoba seed genetics, and Oregon biomass for extraction. Single-source vulnerability in European machinery builders creates bottleneck risk. Distribution runs through direct multi-year offtake agreements for premium textile grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in industrial hemp is accelerating into a vertical-integration race as players pursue captive seed genetics to secure low-THC cultivar supply and bypass regulatory fragmentation.
For Market Incumbents: Lock in multi-year offtake agreements with specific Romanian and Canadian farms before direct-to-brand contracting displaces merchant intermediaries entirely. Invest in enzymatic processing capacity to meet German automotive tensile tolerances and defend against substitution from flax fiber supply chains. Priority lever: backward integration into proprietary seed genetics to control THC compliance at cultivation origin. For New Entrants and Emerging Players: Enter via underpenetrated U.S. decortication infrastructure in Kentucky and Montana where post-2018 Farm Act cultivation expansion has outpaced domestic processing capacity. Target toll processing services for hempcrete and construction matting producers facing equipment bottlenecks. Go-to-market angle: AI-driven spectral THC testing devices enabling real-time compliance verification at field intake points. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized decortication equipment operators in the Netherlands and Belgium with established EU Green Deal supply relationships and blockchain-verified tracking systems already deployed. Long-term viability centers on REACH bio-based material incentive alignment and automotive procurement contract renewal cycles. Signal to watch: FDA IND approval acceleration for cannabinoid therapeutics driving pharmaceutical-grade extraction facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Proprietary low-THC cultivar development at Ecofibre and Manitoba Harvest reduces regulatory compliance risk across jurisdictions. |
| Enzymatic Processing Capacity Expansion | Novozymes cellulase partnerships enable German automotive suppliers to meet tightened tensile strength specifications for interior panels. |
| Blockchain-Verified Tracking Implementation | Dutch decortication facilities satisfy ECHA REACH mass-balance accounting requirements for EU automotive market access. |
| Direct-to-Brand Contracting | Los Angeles denim manufacturers bypass merchant intermediaries to capture full regenerative certification premiums from Canadian farms. |
| AI-Driven Spectral THC Testing Deployment | Portable near-infrared devices with machine learning classification enable real-time compliance verification at U.S. field intake points. |
Methodological Framework
USDA Domestic Hemp Production Program filings, ECHA REACH guidance documents, and NMPA GB standards formed the secondary backbone for regulatory pathway mapping. Primary interviews with decortication equipment operators, automotive composite procurement managers, and CBD extraction facility chemists combined with secondary validation from customs trade data and provincial processing capacity disclosures. Bottom-up acreage and yield estimates triangulated against top-down end-use demand projections from automotive OEMs and pharmaceutical formulators.
Historical trendline analysis across cultivation licensing trajectories, decortication capacity installations, and CBD extraction facility investments established baseline growth patterns. The analytical framework segmented volume and value across raw fiber, CBD extract, seed, and oil categories by application in textiles, construction, food, and personal care. CAGRs derived from regression analysis against EU Green Deal biocomposite mandate implementation schedules and China's dual carbon policy alignment. Key inputs included provincial processor expansion announcements in Heilongjiang and Yunnan, and FDA IND approval pipelines for cannabinoid therapeutics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under THC threshold harmonization failures between jurisdictions and enzymatic processing technology adoption delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Animal Feed Ingredients Market