
 US Fungicide Market | 2026-2036
US Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
US Fungicide Market Insights
Pre-mix bundling of strobilurin-triazole combinations is restructuring how row-crop buyers evaluate cost per acre. BASF SE leverages its formulation expertise to sustain premium positioning in soybean rust protection. Bayer AG anchors its portfolio through in-house production of proprietary active ingredients. Syngenta Group competes on resistance-management stewardship programs that lock in multi-season contracts.
A fungicide is a crop protection agent formulated with specific active ingredients—azoles, strobilurins, or biological organisms—designed to inhibit fungal spore germination, mycelial growth, or cell division in plants. Triazoles dominate volume sales due to their systemic mobility and broad-spectrum control of rusts and mildews, though margin pools are thinning from generic competition. Biologicals represent the fastest-expanding category as EPA registration pathways for microbials shorten and farmers seek MRL-compliant export options. Liquid formulations lead application share, yet granule demand rises where precision agriculture equipment reduces drift exposure.
EPA registration requirements under FIFRA shape product development timelines and label restrictions, while USDA NRCS conservation programs direct cost-share funds toward reduced-risk fungicide selections. State-level 24(c) registrations in Iowa and Illinois create localized market access for novel actives ahead of federal approval. Stakeholders must monitor pending EPA Endangered Species Act consultations, as species-impact findings could trigger buffer-zone mandates that reshape field-application economics and product choice.
Market Dynamics
Resistance management protocols under EPA FIFRA guidelines are forcing specialty crop growers in California and Florida to expand preventive fungicide rotations, restructuring procurement patterns toward bundled active ingredient programs.
Growth Catalysts
- USDA EQIP conservation incentives:Cost-share funds direct Midwest corn-soy belt operators toward reduced-risk biological fungicide selections, accelerating regenerative agriculture adoption.
- Specialty crop export compliance:Maximum residue limit requirements from importing jurisdictions drive California vineyard and Florida citrus operators toward biological alternatives.
- Precision agriculture hardware penetration:Granule-compatible application equipment in Iowa and Illinois reduces drift exposure and expands formulation flexibility.
Market Restraints
- Active ingredient supply concentration:Triazole technical production concentrates among Chinese and Indian API manufacturers, exposing formulators to import tariff volatility.
- Generic strobilurin price compression:Patent-expired azoxystrobin and pyraclostrobin flood commodity row-crop channels, collapsing margin pools for systemic fungicide portfolios.
- EPA endangered species consultations:Pending ESA findings for listed species in agricultural watersheds threaten buffer-zone mandates that would restrict field-application windows.
Strategic Opportunities
- 24(c) special local need registrations:Iowa and Illinois state-level approvals create early market access pathways for novel actives ahead of federal EPA registration.
- Biological-microbiome convergence:Seed-treatment integration of Trichoderma and Bacillus strains with synthetic chemistries opens differentiated positioning in soybean rust protection.
- Direct-to-grower digital channels:Agronomic data platforms bypass traditional distribution tiers, capturing margin and locking in multi-season resistance-management contracts.
Industry Challenges
- Formulation chemist scarcity:Expertise in biological-synthetic compatibility and shelf-life stabilization concentrates among retiring specialists at legacy agricultural chemistry programs.
- Resistance monitoring infrastructure:Pathogen population surveillance networks require sustained capital commitment from registrants without guaranteed regulatory reciprocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fungicide Market |
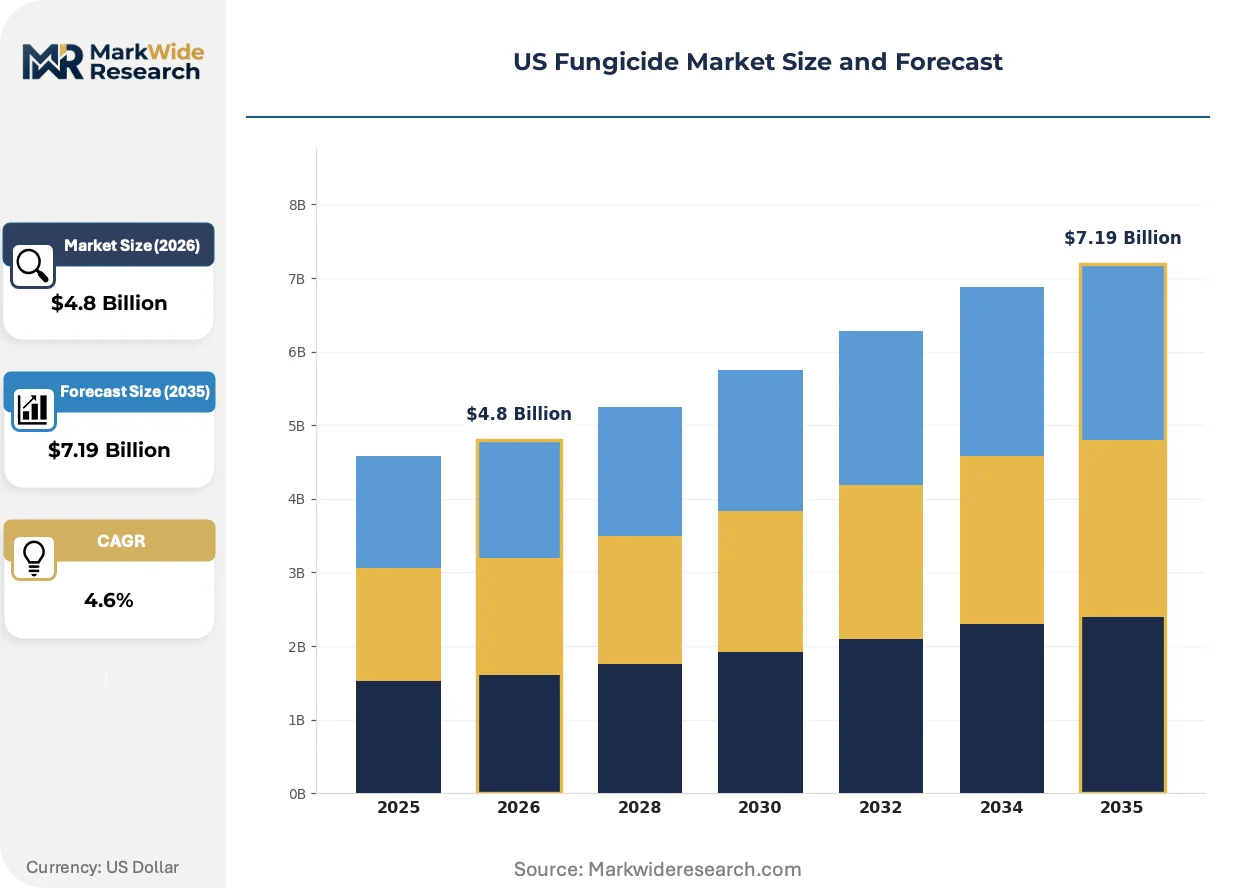
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triazoles, Strobilurins, Chloronitriles, Biologicals Application: Agricultural, Turf & Ornamental, Home & Garden, Commercial Formulation: Liquid, Granule, Powder, Emulsifiable Concentrate End User: Farmers, Lawn Care Providers, Gardeners, Agricultural Cooperatives |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, UPL Limited, FMC Corporation, American Vanguard Corporation, Sumitomo Chemical Co., Ltd, Nufarm Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fungicide Market Trends and Innovations
Formulation science and regulatory compliance frameworks are converging to redefine how fungicide value is measured, moving beyond cost-per-acre toward resistance lifecycle economics and export certification security.
RNA interference fungicides are unifying targeted pathogen suppression with reduced non-target organism exposure. Specialty vegetable operators in California's Salinas Valley pilot spray programs combining dsRNA actives with conventional triazoles. The technology is unifying biological precision with synthetic efficacy benchmarks, compressing the historical trade-off between spectrum and selectivity.
EPA's revised endangered species consultation procedures under FIFRA Section 7 are extending registration timelines for new chemical actives. The agency's 2024 biological evaluation requirements for listed species trigger additional field-study obligations for registrants. Soybean rust protection products face the most acute timeline pressure, with several novel strobilurin-triazole combinations awaiting clearance in Louisiana and Mississippi watersheds.
Buyer concentration among agricultural retailers is compressing manufacturer negotiating leverage. Three national distributors now control the majority of Midwest corn-soy belt fungicide volume, extracting slotting fees and exclusive formulation terms. This consolidation is most visible in Iowa and Illinois, where cooperative buying groups have fragmented and volume has migrated to integrated agronomy service platforms bundling seed, crop protection, and fertility.
US Fungicide Market Segmentation
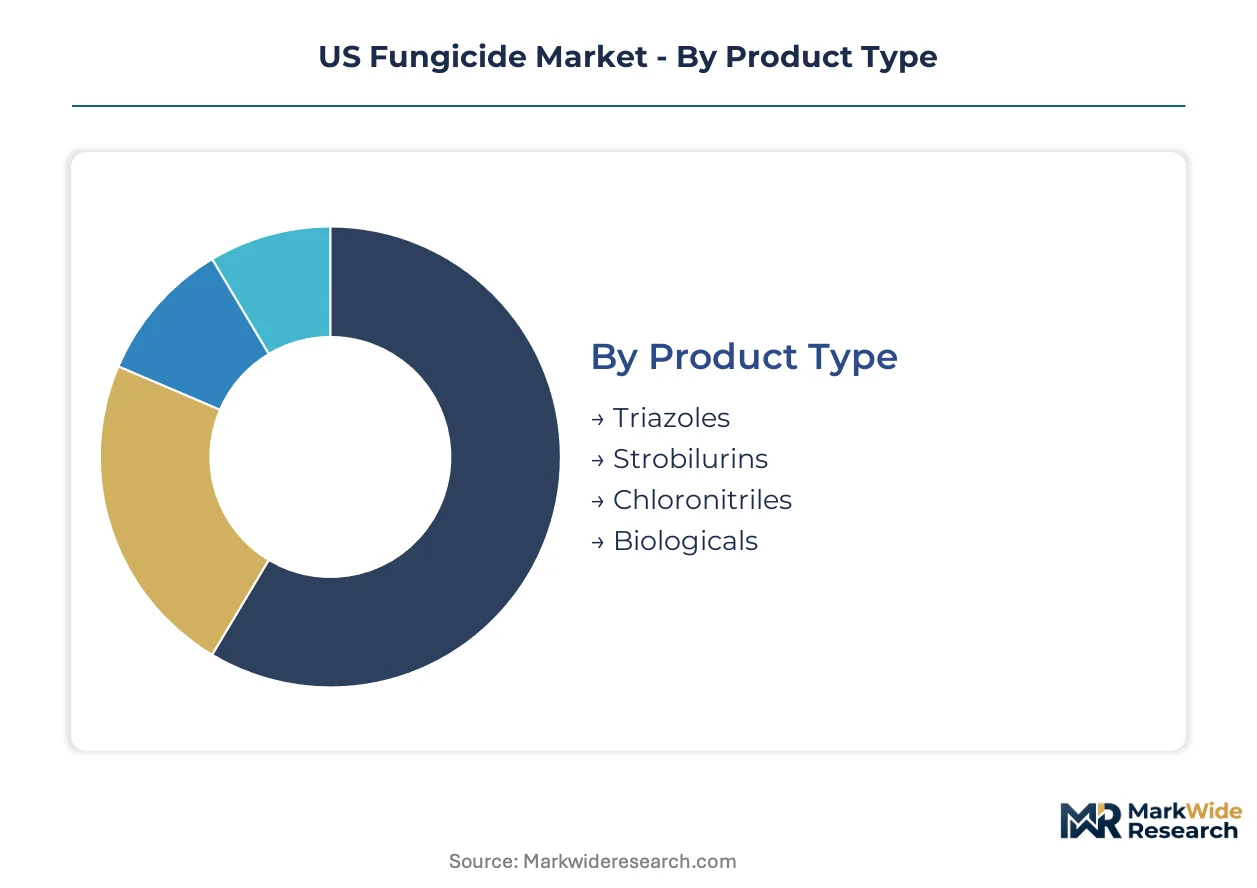
Segmentation in the US fungicide market reveals how procurement priorities diverge between export-facing specialty growers and domestic commodity operators. Understanding these fault lines exposes where formulation investment and distribution resources generate differential returns.
Product Type:
Buyers differentiate by resistance management requirements and residue limit compliance rather than upfront cost alone.
- Triazoles:Systemic azole chemistry delivers broad-spectrum control of rusts and mildews through translaminar mobility. Volume concentrates in Iowa and Illinois corn-soy rotations where generic competition has collapsed price points and thinned margins.
- Strobilurins:Mitochondrial respiration inhibitors provide preventive protection with extended residual activity. California vineyard operators and Florida citrus growers anchor demand as EPA resistance protocols mandate rotation partners.
- Chloronitriles:Contact-acting protectants serve as resistance-breaking tank-mix partners in high-value vegetable systems.
- Biologicals:Microbial and biochemical actives from Trichoderma and Bacillus strains gain traction where USDA EQIP cost-share funds offset premium pricing.
Volume sits with Triazoles; growth tilts toward Biologicals.
Application:
End-use concentration determines formulation specifications and regulatory exposure profiles.
- Agricultural:Row-crop and specialty crop production consumes the majority of active ingredient volume. Midwest corn-soy belt procurement clusters around pre-mix bundles, while California and Florida operations prioritize resistance stewardship programs.
- Turf & Ornamental:Golf course superintendents and landscape contractors drive demand for fast-acting contact fungicides with minimal re-entry intervals.
- Home & Garden:Retail channel distribution emphasizes ready-to-use formulations and consumer-friendly application instructions.
- Commercial:Industrial vegetation management and nursery operations require bulk procurement with specialized handling protocols.
Revenue concentrates in Agricultural; margin expansion favors Turf & Ornamental.
Formulation:
Application equipment compatibility and drift mitigation requirements reshape buyer preferences across geographies.
- Liquid:Suspension concentrates and soluble liquids dominate commercial agriculture through aerial and ground rig compatibility. Iowa and Illinois operators favor liquid systems for speed of loading and tank-mix flexibility.
- Granule:Precision agriculture equipment penetration in the corn-soy belt reduces drift exposure and enables banded application. Demand climbs where buffer-zone constraints tighten under pending EPA endangered species consultations.
- Powder:Wettable powders persist in specialty markets requiring long-term storage stability.
- Emulsifiable Concentrate:Oil-based carriers enhance cuticular penetration in high-rainfall environments.
Application share belongs to Liquid; equipment-driven substitution favors Granule.
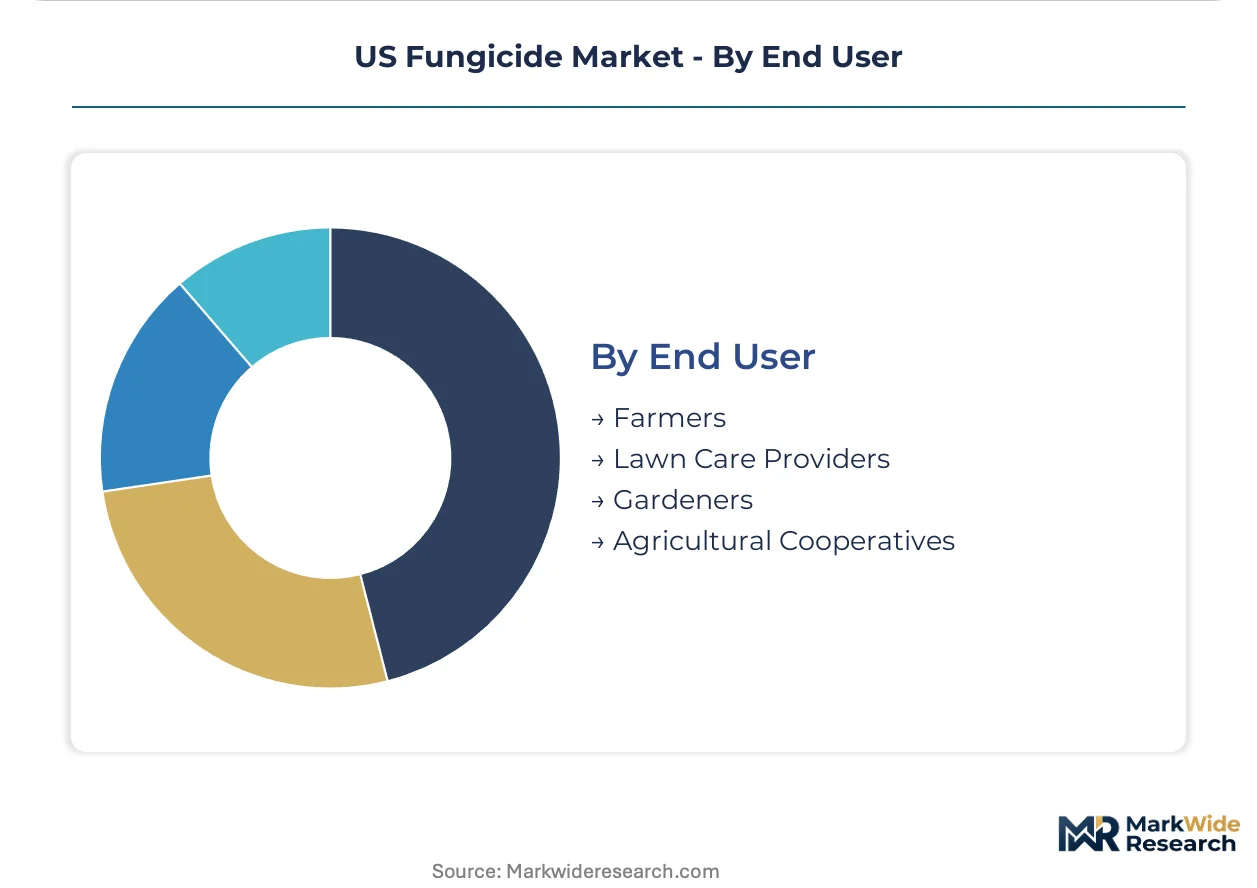
End User:
Scale and technical sophistication determine whether buyers access products through retail, cooperative, or direct channels.
- Farmers:Individual operators in the Midwest corn-soy belt and specialty crop regions of California and Florida represent the core volume base. Procurement shifts toward bundled agronomy platforms integrating seed, fertility, and crop protection.
- Lawn Care Providers:Professional applicators demand consistent efficacy and rapid re-entry intervals to maintain service schedules.
- Gardeners:Consumer segment prioritizes convenience and safety signaling over cost optimization.
- Agricultural Cooperatives:Consolidated buying power in Iowa and Illinois extracts slotting fees and exclusive formulation terms from manufacturers.
Volume aggregates with Farmers; cooperative consolidation elevates Agricultural Cooperatives as gatekeepers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US produces limited fungicide active ingredient technicals domestically, relying instead on imported azole and strobilurin precursors from Asian manufacturers. Consumption concentrates in coastal specialty crop zones and Midwest commodity belts, creating divergent procurement patterns across state lines.
California
Vineyard operators in Napa and Sonoma counties anchor demand for resistance-compliant strobilurin rotations under EPA FIFRA guidelines. The state's Department of Pesticide Regulation enforces stricter buffer-zone requirements than federal baselines, pushing Salinas Valley vegetable growers toward precision granule applications. Fresno County almond orchards represent the largest single-county fungicide expenditure in specialty agriculture.
Florida
Citrus greening management protocols drive preventive fungicide adoption in Polk and Hendry counties, with growers rotating between strobilurins and biological alternatives. The Florida Department of Agriculture and Consumer Services coordinates with EPA on 24(c) special local need registrations for novel actives targeting postbloom fruit drop. Miami-Dade County's winter vegetable operations demand MRL-compliant biologicals for European export markets.
Iowa
Corn-soy belt operators in Story and Marshall counties prioritize cost-per-acre optimization through pre-mix bundled procurement. USDA EQIP cost-share funds direct reduced-risk selections toward biological seed treatments. Des Moines-based cooperative buying groups have consolidated into integrated agronomy platforms bundling crop protection with fertility and seed.
Illinois
Soybean rust pressure in McLean and Champaign counties sustains demand for systemic triazoles despite generic price compression. The Illinois Department of Agriculture processes 24(c) registrations ahead of federal EPA timelines, creating early access windows for novel formulations. Peoria's precision agriculture equipment penetration accelerates granule-compatible application adoption.
Texas
High Plains cotton producers in Lubbock and Hockley counties deploy contact fungicides against seedling disease complexes. The Texas Department of Agriculture administers state-level resistance monitoring programs for Fusarium and Rhizoctonia populations. Rio Grande Valley specialty vegetable operations mirror California's export compliance requirements, driving biological fungicide uptake.
US Fungicide Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a tiered structure where scale-driven players anchor volume segments and boutique operators capture premium niches. The market consolidates around three archetypes: integrated agrochemical conglomerates with captive active ingredient production, formulation specialists leveraging external technical supply, and biological technology developers targeting regenerative agriculture incentives. M&A activity concentrates on microbiome platform acquisitions, while capacity expansion focuses on liquid formulation facilities in Midwest logistics corridors.
Among integrated conglomerates, BASF SE and Bayer AG exemplify the backward-integrated archetype through in-house production of proprietary active ingredients. Syngenta Group occupies a stewardship-focused position, competing on resistance-management programs that lock in multi-season contracts with specialty crop operators. These three European-anchored players represent the dominant competitive force, with their combined formulation expertise shaping premium positioning in soybean rust protection and vineyard disease management.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| UPL Limited |
| FMC Corporation |
| American Vanguard Corporation |
| Sumitomo Chemical Co., Ltd |
| Nufarm Ltd |
| Others |
Pricing and Supply Chain Analysis
EPA endangered species consultation requirements under FIFRA Section 7 gate qualified supply access for novel active ingredients while compressing premium-tier pricing power among registrants awaiting clearance in Louisiana and Mississippi watersheds.
Pricing Analysis
Price erosion across commodity triazole tiers traces to patent-expired azoxystrobin and pyraclostrobin flooding Iowa and Illinois row-crop channels. Pricing stratifies across premium resistance-stewardship bundles, standard pre-mix combinations, and economy generic formulations. California vineyard operators show least price sensitivity where MRL compliance mandates biological premiums, while Midwest corn-soy belt cooperative buying groups extract maximum slotting concessions.
Supply Chain Analysis
Direct-to-grower digital channels bypass traditional distribution tiers for multi-season contract capture, though three national distributors still control majority Midwest volume. Active ingredient technical production concentrates in China and India for azole and strobilurin precursors, with formulation finishing at domestic liquid facilities in Midwest logistics corridors. Supply chain risk centers on import tariff exposure for API shipments, while biological actives from Trichoderma and Bacillus strains draw from domestic fermentation capacity.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic price compression and distributor consolidation are forcing sub-scale formulators toward exit or acquisition, rewarding players with captive technical production and stewardship-locked customer relationships.
For Market Incumbents: Extend resistance-management stewardship programs into multi-season digital platforms that lock in California and Florida specialty crop operators against biological disruptors. Deepen backward integration into proprietary active ingredient production to defend margin pools against Chinese and Indian API tariff volatility. For New Entrants and Emerging Players: Capture USDA EQIP cost-share flows in the Midwest corn-soy belt by positioning biological seed-treatment formulations with Trichoderma-Bacillus combinations as reduced-risk alternatives. Target Iowa and Illinois state-level 24(c) registration pathways ahead of federal EPA timelines for early market access. For Investors and Strategic Acquirers: Pending EPA Endangered Species Act consultation outcomes for listed species in agricultural watersheds are the leading indicator that buffer-zone mandate severity will reshape field-application economics and consolidate manufacturing among registrants with formulation flexibility. Acquisition focus should center on microbiome platform developers with EPA-registered microbials and shelf-life stabilization expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Biological-Synthetic Formulation Integration | Seed-treatment convergence with Trichoderma and Bacillus strains opens differentiated soybean rust protection positioning. |
| 24(c) Special Local Need Registration | Iowa and Illinois state-level approvals create federal EPA clearance runway for novel active ingredient launches. |
| Direct-to-Grower Digital Channel Buildout | Agronomic data platforms capture margin and lock multi-season resistance-management contracts outside distributor tiers. |
| Backward Integration into API Production | In-house azole and strobilurin technical manufacturing insulates against Chinese and Indian import tariff exposure. |
| Precision Agriculture Equipment Partnership | Granule-compatible application systems reduce drift exposure and expand formulation flexibility under pending EPA buffer constraints. |
Research Methodology
Independent corroboration across EPA registration databases, USDA NRCS conservation program disbursement records, and state-level 24(c) approval filings underwrites the qualitative findings. Primary interviews with fungicide formulation chemists, agricultural cooperative procurement managers, specialty crop growers in California and Florida, and EPA regulatory affairs specialists combined with secondary validation from FIFRA registration timelines, customs import data for API shipments, and SEC 10-K disclosures from agrochemical registrants. Bottom-up volume estimates from county-level expenditure patterns triangulate against top-down market sizing from active ingredient production capacity.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects. Segmentation dimensions modeled include product type chemistry class, application end-use concentration, formulation physical state, and regional regulatory cluster intensity. CAGRs derive from fitted growth curves against historical adoption patterns, with specific inputs from precision agriculture equipment penetration rates and USDA EQIP enrollment trajectories in the corn-soy belt.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA Endangered Species Act consultation timelines, Chinese API tariff policy shifts, and biological registration pathway duration compression. Forecasts reflect documented assumptions regarding resistance management protocol adherence and distributor consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
CBD Plant Nutrients Market