
 Bell Palsy Treatment Market | 2026-2036
Bell Palsy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bell Palsy Treatment Market Analytics
North American pharmaceutical manufacturing capacity for corticosteroid APIs is realigning after supply chain disruptions during the pandemic period. Pfizer Inc. leverages its integrated steroid production network to secure raw material access for Bell palsy indications. Sanofi SA anchors its position through long-standing relationships with hospital formularies across France and neighboring markets. AbbVie Inc. competes on the strength of its specialty care distribution infrastructure in the United States.
Bell palsy treatment addresses acute idiopathic facial nerve paralysis through pharmacological and rehabilitative interventions, with corticosteroids representing the first-line pharmacotherapy based on randomized evidence showing improved facial nerve recovery outcomes when administered within 72 hours of symptom onset. The primary commercial purpose centers on preventing permanent synkinesis and facial asymmetry through timely medical intervention combined with structured physical therapy protocols. Corticosteroids dominate current prescription volumes due to established efficacy data and broad formulary inclusion, while physical therapy represents the fastest-growing segment as rehabilitation protocols gain standardized reimbursement codes in multiple healthcare systems. Oral delivery mode occupies the largest share of administered doses, though intravenous formulations capture premium pricing in acute hospital settings where rapid bioavailability proves clinically critical.
FDA oversight of corticosteroid labeling and risk evaluation shapes product development priorities for manufacturers serving the United States market, while EMA pharmacovigilance requirements for neurological indications influence European clinical trial designs and post-market surveillance obligations. The WHO inclusion of corticosteroids in its essential medicines list supports access programs in lower-income settings, though procurement volumes remain constrained by diagnostic capacity limitations. Stakeholders must monitor evolving physical therapy reimbursement frameworks and antiviral combination study outcomes to anticipate shifts in standard-of-care protocols.
Market Dynamics
Neurology clinics are consolidating acute facial paralysis protocols around corticosteroid-first pathways, compressing decision windows to 72 hours and forcing manufacturers to align supply chains with emergency department dispensing patterns rather than traditional pharmacy fulfillment.
Growth Catalysts
- EMA pharmacovigilance frameworks:Standardized post-market surveillance for neurological corticosteroid use is building prescriber confidence in European markets and expanding eligible patient pools for acute intervention.
- Physical therapy reimbursement codes:Structured rehabilitation protocols are gaining formal recognition across German, Japanese, and United States healthcare systems, shifting treatment from episodic to continuous care models.
- Aging demographics in Japan:Elevated incidence rates of idiopathic facial nerve paralysis among patients over 60 are sustaining treatment volumes and justifying dedicated clinic infrastructure investments.
Market Restraints
- API supply concentration:Corticosteroid active pharmaceutical ingredient production clusters in specific manufacturing regions, exposing finished dose formulators to single-source disruption risks.
- FDA labeling requirements:Evolving risk evaluation mandates for neurological indications are extending product development timelines and elevating post-approval compliance costs for United States market entrants.
- Antiviral substitution pressure:Combination therapy studies examining acyclovir-valacyclovir protocols threaten to fragment first-line prescribing away from corticosteroid monotherapy in academic medical centers.
Strategic Opportunities
- Underpenetrated diagnostic capacity:Rural United States markets and secondary Japanese cities present expansion potential for telemedicine-enabled acute facial paralysis triage systems.
- Intravenous formulation development:Premium-priced hospital-grade corticosteroid delivery is capturing share in acute settings where rapid bioavailability determines functional recovery outcomes.
- Physical therapy protocol standardization:WHO essential medicines list inclusion for corticosteroids is creating pathway opportunities for bundled rehabilitation services in lower-income healthcare systems.
Industry Challenges
- Specialized rehabilitation workforce scarcity:Facial nerve-specific physical therapists require extended certification timelines, constraining clinic expansion capacity in high-demand metropolitan markets.
- Legacy EHR integration friction:Neurology department information systems require costly customization to accommodate 72-hour treatment window alerts and automated corticosteroid dispensing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bell Palsy Treatment Market |
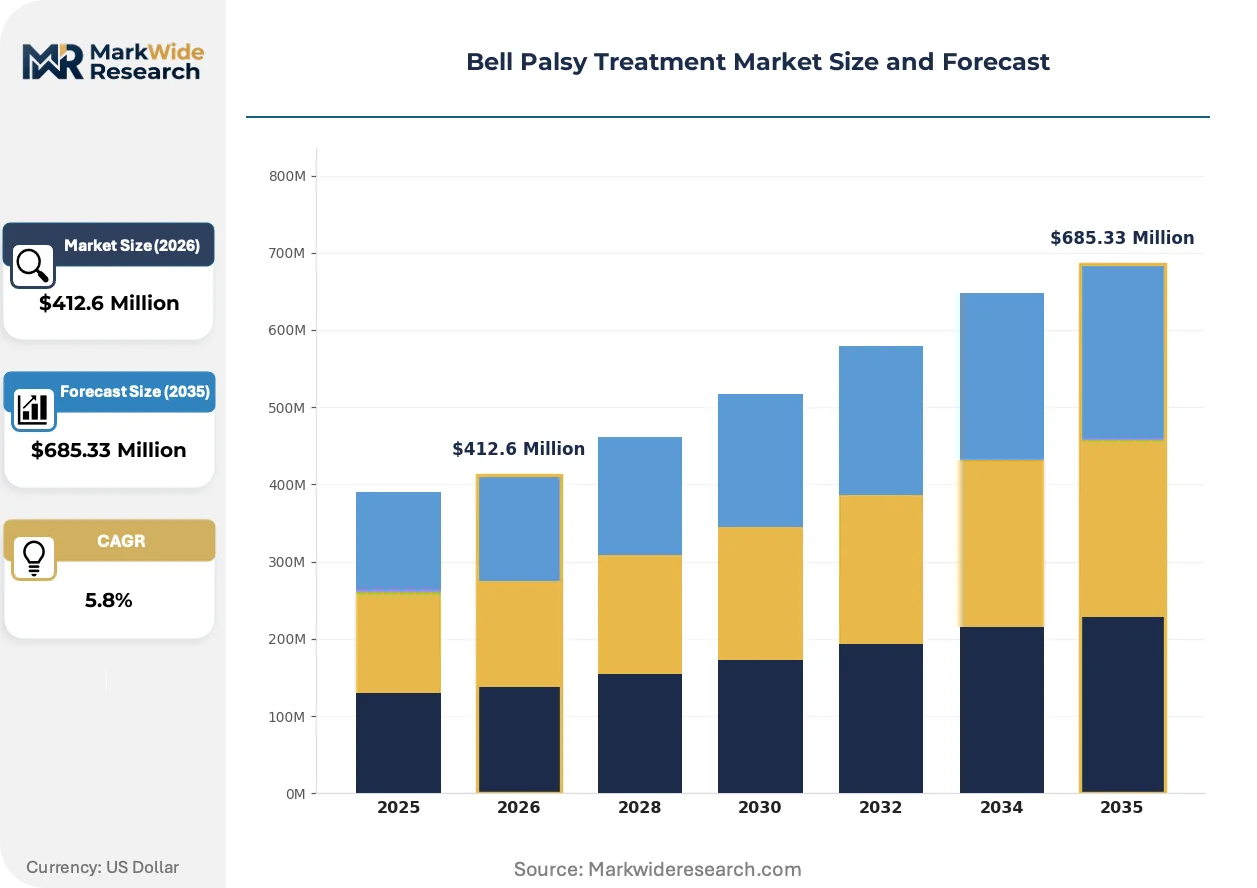
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Physical Therapy, Antivirals, Analgesics Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Patient Type: Adults, Children, Elderly, Post-Surgery |
| Companies Covered | AbbVie Inc., Sanofi SA, Pfizer Inc., AstraZeneca, Bristol-Myers Squibb and Company, Johnson & Johnson, Bayer AG, Novartis AG, Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bell Palsy Treatment Market Evolving Landscape
Digital health infrastructure is compressing acute facial paralysis diagnosis-to-treatment intervals while regulatory bodies on both sides of the Atlantic tighten pharmacovigilance expectations for neurological corticosteroid applications.
Telemedicine triage platforms is modularizing access to specialist neurology consultation for patients presenting with acute facial asymmetry. Rural health systems and urgent care networks are adopting these systems at accelerating rates. This technology is compressing geographic barriers to 72-hour corticosteroid initiation and redistributing treatment volumes from academic centers to community settings.
EMA pharmacovigilance requirements for neurological indications are mandating enhanced post-market surveillance protocols for corticosteroid products. Manufacturers serving European markets must now maintain active facial nerve recovery outcome registries. Hospital formularies in Germany and France are responding by consolidating purchases with suppliers demonstrating robust surveillance infrastructure.
Physical therapy service unbundling is separating facial rehabilitation from general neurological rehabilitation contracts. United States outpatient clinics and Japanese day-care centers are purchasing standalone facial nerve exercise protocols rather than bundled neurorehabilitation packages. This pattern is most visible in markets where reimbursement codes explicitly distinguish idiopathic facial paralysis from stroke-related facial weakness.
Bell Palsy Treatment Market Segmentation
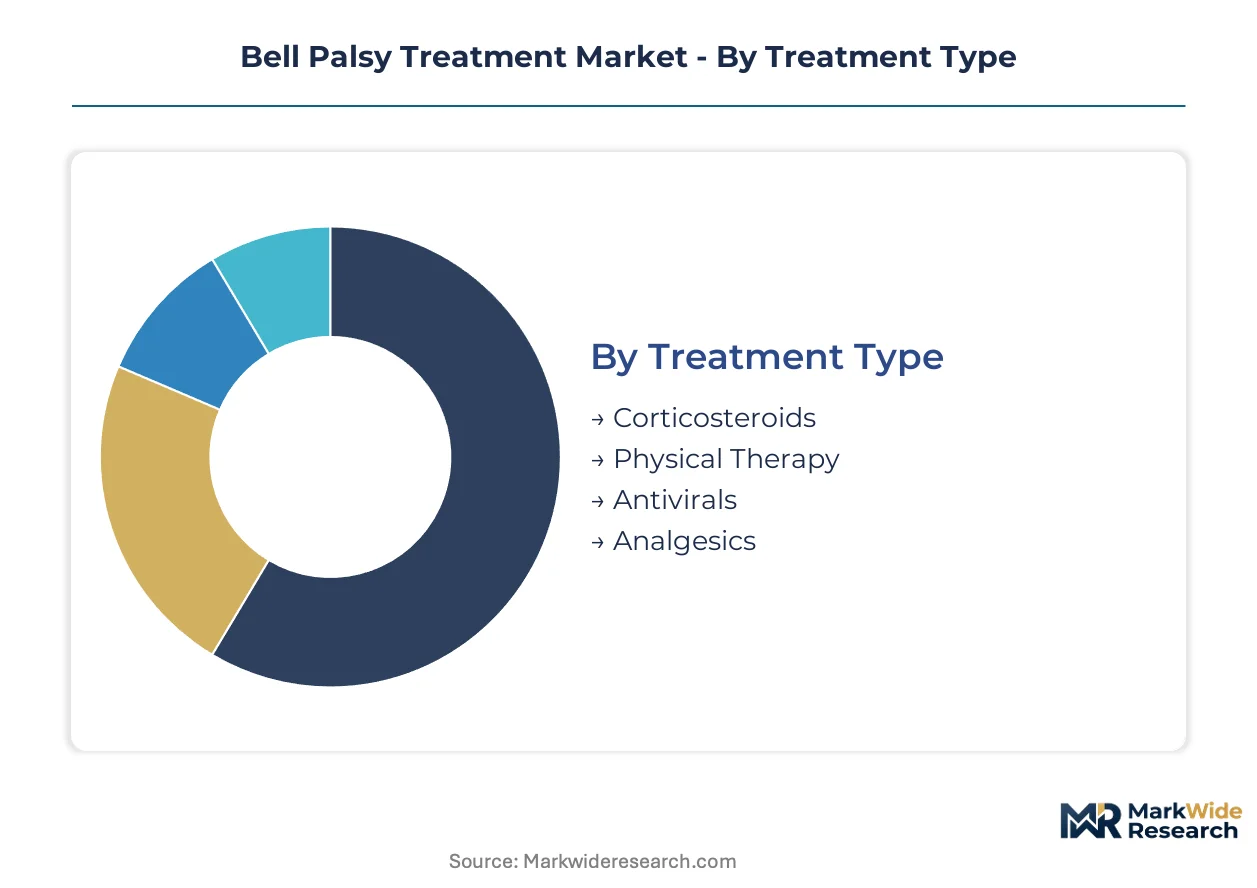
Treatment pathways for acute facial nerve paralysis fragment across pharmacological and rehabilitative modalities, with reimbursement codes and bioavailability requirements determining where value concentrates. Manufacturers must align formulation strategies with the 72-hour intervention window that defines clinical outcomes.
Treatment Type:
Volume dominance sits with corticosteroid prescriptions, while premium pricing attaches to emerging combination protocols and specialized rehabilitation services.
- Corticosteroids:Synthetic glucocorticoid formulations, primarily prednisolone and methylprednisolone, reduce facial nerve inflammation through immunosuppressive action. Hospital formularies in the United States and Germany prioritize these agents for emergency department dispensing within the critical 72-hour onset period.
- Physical Therapy:Facial neuromuscular retraining protocols target synkinesis prevention through structured exercise regimens. Japanese day-care centers and United States outpatient clinics are purchasing standalone protocols as reimbursement codes separate idiopathic facial paralysis from stroke rehabilitation.
- Antivirals:Acyclovir and valacyclovir target suspected viral etiology in combination regimens.
- Analgesics:Pain management adjuncts address secondary discomfort during acute presentation phases.
Today's leader: Corticosteroids. Tomorrow's challenger: Physical Therapy.
Delivery Mode:
Route selection tracks clinical urgency, with hospital-acquired infections and bioavailability timelines shaping prescriber preferences across care settings.
- Oral:Tablet and liquid formulations enable community-based initiation within the treatment window. Primary care networks in rural United States markets rely on oral prednisolone for same-day dispensing.
- Intravenous:Hospital-grade methylprednisolone sodium succinate achieves peak plasma concentration within minutes. Academic medical centers in Germany and Japan specify IV protocols for severe complete paralysis presentations.
- Injectable:Intramuscular depot formulations extend release profiles for patient compliance.
- Topical:Transdermal delivery remains investigational for facial nerve applications.
Oral administration commands prescription volume. Intravenous delivery captures margin expansion in acute tertiary settings.
End User:
Care setting fragmentation reflects triage pathway evolution, with telemedicine platforms redistributing treatment initiation from traditional hospital gateways.
- Hospitals:Emergency departments anchor acute protocol initiation with integrated corticosteroid dispensing workflows. EHR customization requirements in United States academic centers are compressing diagnosis-to-treatment intervals.
- Rehabilitation Centers:Dedicated facial nerve clinics provide protocolized neuromuscular retraining. Workforce certification scarcity constrains expansion in high-demand Japanese and German metropolitan markets.
- Clinics:Community neurology practices manage stable post-acute cases.
- Home Care:Telemedicine-enabled monitoring extends protocol adherence beyond facility walls.
Hospitals retain acute case volume. Rehabilitation centers are climbing the fastest as continuous care models displace episodic intervention.
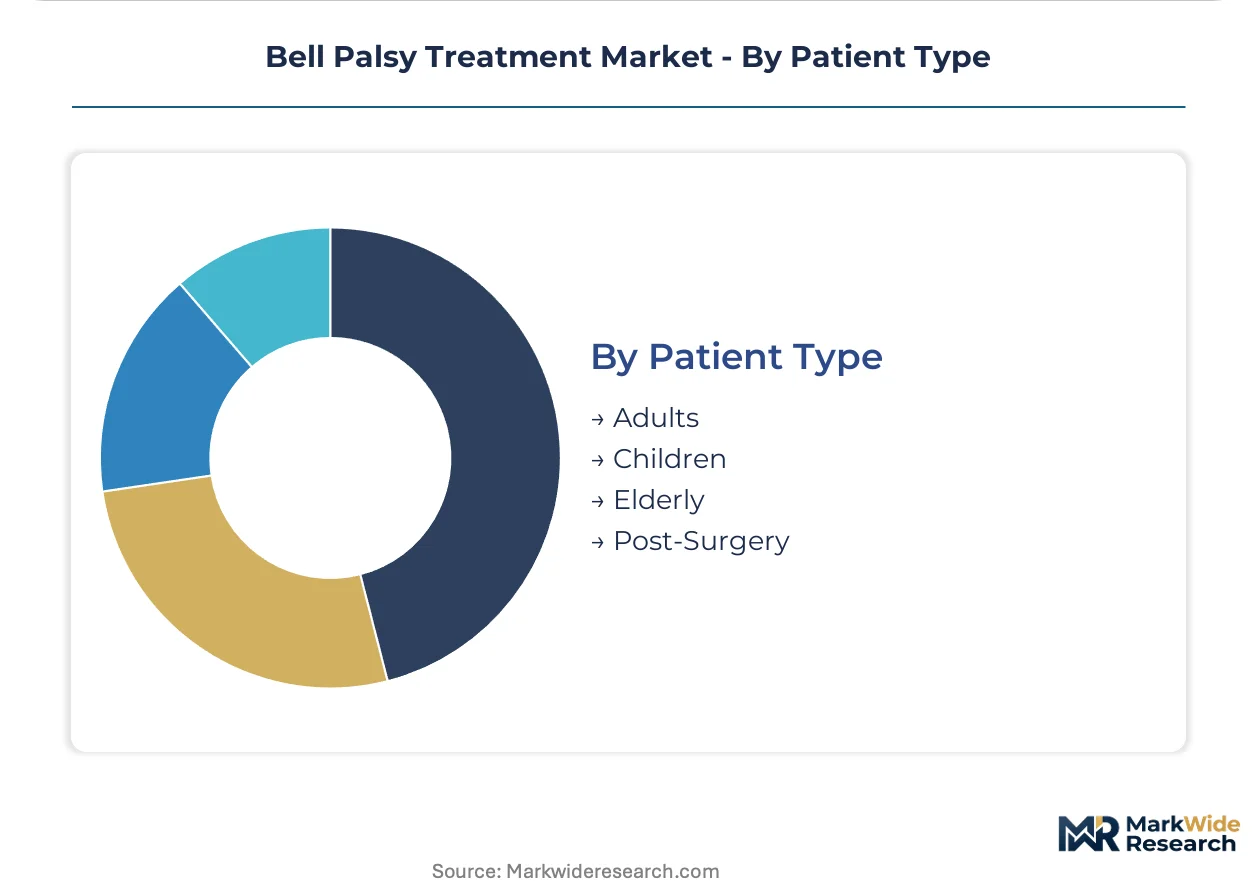
Patient Type:
Age-stratified incidence patterns concentrate commercial investment toward demographics with elevated idiopathic facial nerve paralysis risk and reimbursement accessibility.
- Elderly:Patients over 60 exhibit elevated incidence of spontaneous facial nerve dysfunction. Japan's aging demographic sustains dedicated clinic infrastructure investments and justifies premium protocol development.
- Adults:Working-age patients drive volume through occupational urgency for functional recovery. United States disability insurance timelines create pressure for rapid return-to-work outcomes.
- Children:Pediatric presentations require modified dosing and specialized diagnostic workup.
- Post-Surgery:Iatrogenic facial nerve injury represents a distinct rehabilitation pathway.
Elderly patients anchor sustained treatment volumes. Adult working-age segments demand efficiency-focused service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping corticosteroid API sourcing as manufacturers relocate production to jurisdictions with streamlined neurological drug approval pathways. Cost-of-compliance gaps between FDA and EMA frameworks are accelerating facility investments in select European markets while United States producers absorb elevated pharmacovigilance overhead.
United States
Emergency department corticosteroid dispensing volumes concentrate in academic medical centers with customized EHR alert systems. FDA labeling requirements for neurological indications extend development timelines but consolidate purchasing power among hospital systems with integrated formulary management. The Boston-Cambridge corridor anchors specialty care distribution infrastructure serving tertiary referral networks.
Germany
Hospital formularies in Bavaria and North Rhine-Westphalia prioritize suppliers with active facial nerve recovery outcome registries. EMA pharmacovigilance mandates for neurological corticosteroid use are standardizing post-market surveillance across German healthcare regions. The Frankfurt-Rhine-Main cluster hosts contract manufacturing organizations serving European acute care markets.
Japan
Aging demographics in the Kanto and Kansai regions sustain dedicated facial nerve clinic infrastructure investments. PMDA streamlined review pathways for reformulated corticosteroids are accelerating product lifecycle management for domestic manufacturers. Tokyo metropolitan area day-care centers are purchasing standalone facial rehabilitation protocols under separated reimbursement codes.
United Kingdom
Telemedicine-enabled acute facial paralysis triage systems are penetrating rural health networks in Scotland and Northern England. MHRA alignment with EMA pharmacovigilance standards is reducing regulatory friction for corticosteroid imports from European manufacturing sites. The Oxford-Cambridge arc concentrates neurology department information system vendors customizing 72-hour treatment window workflows.
India
CDSCO manufacturing facility inspections are tightening API export quality standards for corticosteroid active pharmaceutical ingredients. Domestic diagnostic capacity limitations constrain procurement volumes despite WHO essential medicines list inclusion. The Hyderabad-Visakhapatnam pharmaceutical corridor is expanding corticosteroid API production for finished dose formulators serving lower-income healthcare systems.
Bell Palsy Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue physical therapy protocol standardization and telemedicine-enabled service delivery. The vendor base stratifies across integrated pharmaceutical manufacturers, specialty care distributors, and standalone rehabilitation service providers. Three archetypes dominate: steroid API producers with captive finished-dose capacity, hospital formulary incumbents with long-standing procurement relationships, and digital health platforms compressing diagnosis-to-treatment intervals. Competitive moves concentrate on M&A targeting facial nerve-specific physical therapy certification programs and strategic partnerships bundling pharmacological and rehabilitative interventions.
Among United States-based pharmaceutical incumbents, Pfizer Inc. and AbbVie Inc. exemplify integrated steroid production network strategies securing raw material access. Sanofi SA occupies a position within the European hospital formulary anchor tier through established relationships across France and neighboring markets. These three entities represent distinct competitive positioning vectors: upstream API control, specialty care distribution infrastructure, and continental European procurement consolidation.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Sanofi SA |
| Pfizer Inc. |
| AstraZeneca |
| Bristol-Myers Squibb and Company |
| Johnson & Johnson |
| Bayer AG |
| Novartis AG |
| Merck & Co. Inc. |
| Others |
Value Network & Pricing Analysis
EMA pharmacovigilance mandates for neurological corticosteroid applications gate qualified supply access and premium-tier pricing power, as hospital formularies in Germany and France consolidate purchasing with manufacturers demonstrating active facial nerve recovery outcome registries and robust post-market surveillance infrastructure.
Pricing Analysis
Hospital formulary rebates and GPO contract tiers shape corticosteroid pricing dynamics across acute care settings. Three-tier pricing structure across premium intravenous formulations, standard oral tablets, and economy generic prednisolone separates value capture by bioavailability urgency and certification grade. Pricing pressure stems from antiviral combination therapy studies threatening to fragment first-line prescribing in academic medical centers. Price-sensitive community clinics in rural United States markets drive volume through oral generic substitution, while tertiary hospitals absorb premium IV methylprednisolone sodium succinate pricing for severe complete paralysis presentations.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive corticosteroid APIs is elevating landed cost differentials between Indian and Chinese manufacturing hubs and European formulation sites. API production concentrates in India, China, and the United States, with the Hyderabad-Visakhapatnam corridor expanding synthetic glucocorticoid output for finished dose formulators. Raw material dependencies include prednisolone base compounds, methylprednisolone intermediates, and specialized parenteral packaging materials. Single-source vulnerability in corticosteroid API synthesis exposes formulators to disruption risks from CDSCO inspection backlogs. Distribution runs through hospital procurement systems with integrated emergency department dispensing workflows in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bell Palsy Treatment Market compounds steadily as aging demographics in Japan and reimbursement code expansion for physical therapy protocols sustain treatment volumes across neurologic care settings.
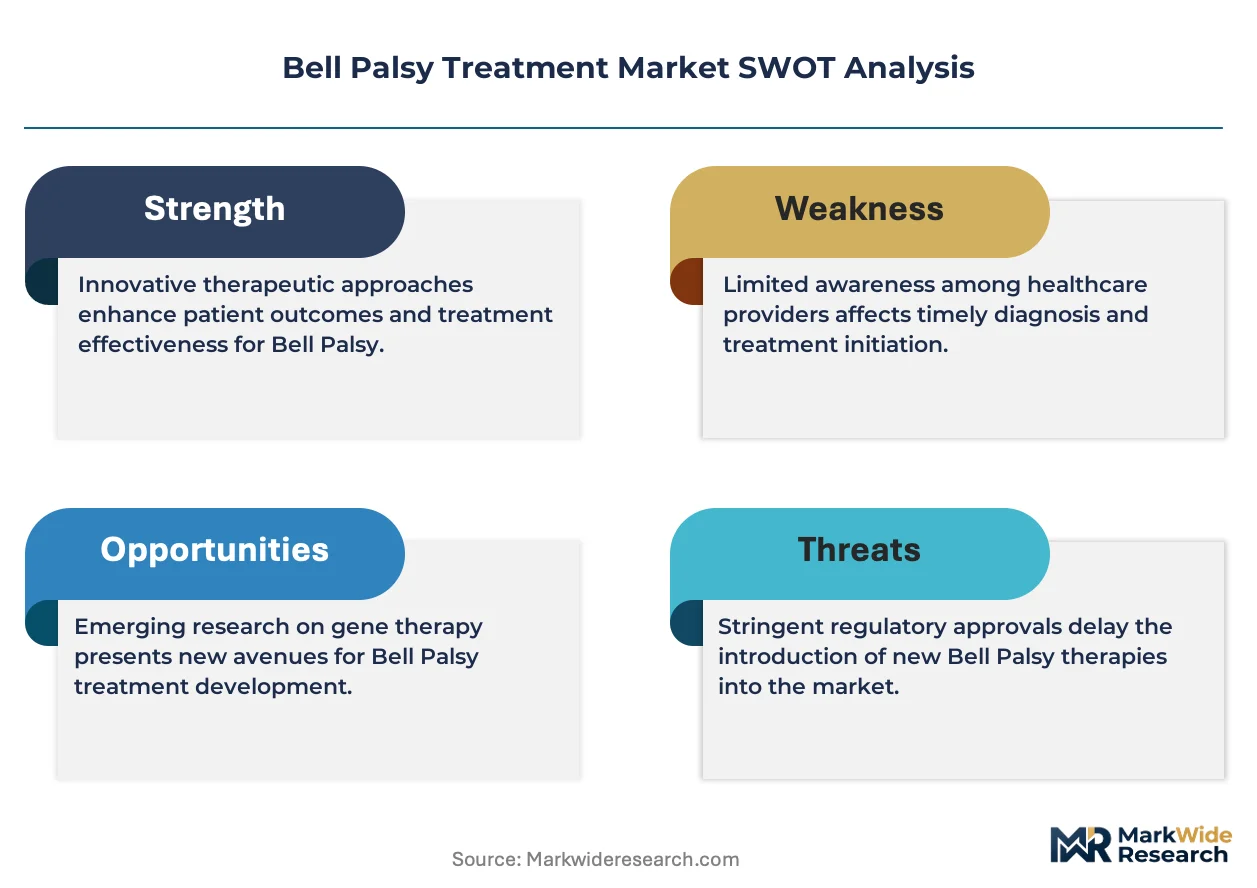
For Market Incumbents: Anchor formulary position through backward integration into corticosteroid API production and certification investment in facial nerve-specific physical therapy protocols. Defend against antiviral substitution pressure by funding combination therapy head-to-head trials and securing long-term GPO contracts with 72-hour dispensing guarantee clauses. Prioritize EHR alert system integration to compress diagnosis-to-treatment intervals and lock in emergency department volume. For New Entrants and Emerging Players: Telemedicine-enabled triage platforms offer the lowest-friction entry vector for acute facial paralysis diagnosis-to-treatment compression. Target rural United States health systems and secondary Japanese cities with underpenetrated specialist neurology access. Pursue standalone physical therapy protocol licensing to rehabilitation centers separating facial nerve rehabilitation from bundled neurorehabilitation contracts. For Investors and Strategic Acquirers: Roll-up economics work for facial nerve-specific physical therapy certification programs because workforce scarcity constrains clinic expansion capacity in high-demand metropolitan markets. Five-to-ten year viability hinges on reimbursement code durability and telemedicine infrastructure penetration. Acquisition targets include digital health platforms with 72-hour treatment window alert capabilities and standalone rehabilitation service providers with Japanese or German clinic networks. Watch antiviral combination trial readouts as the critical inflection signal for corticosteroid monotherapy share erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Physical Therapy Protocol Standardization | WHO essential medicines list inclusion for corticosteroids creates bundled rehabilitation pathway opportunities in lower-income healthcare systems. |
| Intravenous Formulation Development | Premium-priced hospital-grade methylprednisolone captures acute settings where rapid bioavailability determines functional recovery outcomes. |
| Telemedicine Triage Platform Deployment | Rural United States health systems adopt modular specialist neurology consultation for acute facial asymmetry at accelerating rates. |
| EMA Pharmacovigilance Infrastructure Investment | Active facial nerve recovery outcome registries satisfy German and French hospital formulary consolidation toward surveillance-demonstrating suppliers. |
| Rehabilitation Workforce Certification Expansion | Extended facial nerve-specific physical therapist training timelines constrain clinic capacity in high-demand Japanese and German metropolitan markets. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation through triangulation. Primary interviews engaged neurology department heads, hospital formulary directors, physical therapy certification program administrators, and corticosteroid API procurement managers. Secondary sources included FDA labeling databases, EMA pharmacovigilance registries, ClinicalTrials.gov intervention studies, and national reimbursement code filings. Bottom-up patient volume estimates and top-down pharmaceutical expenditure data were cross-referenced for convergence.
Granularity-level modeling tracked treatment type, delivery mode, end-user setting, and patient age demographic across the projection horizon. Segmentation dimensions included corticosteroid versus physical therapy versus antiviral modality, oral versus intravenous versus injectable route, hospital versus rehabilitation center versus clinic site, and elderly versus adult versus pediatric population. CAGRs were derived from patient incidence trend extrapolation, reimbursement code adoption curves, and corticosteroid prescription volume elasticity to 72-hour window alert system penetration. Forecast inputs incorporated PMDA streamlined review pathway utilization rates and telemedicine platform deployment trajectories.
Antiviral combination trial outcomes, EMA pharmacovigilance mandate enforcement intensity, and physical therapy reimbursement code expansion delays are the dominant revision risks. Forecasts reflect assumptions about corticosteroid first-line protocol persistence and diagnostic capacity growth in underpenetrated markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
3D Neuroscience Market
Neurology
Chiari Malformation Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Arachnoiditis Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Optic Neuritis Treatment Market
Neurology
North America Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Spain Neurology Devices Market
Neurology
South Korea Neurology Devices Market
Neurology
Chile Neurology Devices Market
Neurology
Tourette Syndrome Market
Neurology
Moyamoya Disease Market