
 South America MRI Market | 2026-2036
South America MRI Market Size, Share, and Industry Trends Forecast 2026-2036
South America MRI Market Analytics
Outpatient clinics is collapsing the historical hospital-centric procurement model across South America. Siemens Healthineers AG leverages its established service infrastructure to sustain long-term contracts with large public hospital networks. GE Healthcare competes aggressively on financing structures that lower capital barriers for mid-tier diagnostic centers. Koninklijke Philips NV differentiates through AI-integrated workflow platforms that reduce scan-to-diagnosis time.
Magnetic resonance imaging (MRI) employs superconducting magnets generating field strengths from 0.2 to 7.0 Tesla to produce detailed tomographic images of soft tissues without ionizing radiation; these systems require cryogenic cooling with liquid helium and specialized radiofrequency coils tuned to hydrogen proton resonance frequencies. Closed MRI systems dominate installed base volumes due to superior signal-to-noise ratios and faster acquisition protocols, though open MRI configurations command premium positioning for bariatric and claustrophobic patient segments. High-Field MRI technology leads replacement cycles as facilities seek faster throughput and enhanced resolution for neurological and oncological diagnostics.
ANVISA governs medical device registration and post-market surveillance in Brazil, while Argentina's national pharmaceutical regulator oversees import licensing and clinical validation requirements for imaging equipment. ANVISA's streamlined risk-based classification for MRI systems is reshaping how manufacturers structure local technical documentation and in-country representation. Stakeholders must monitor how Mercosur harmonization efforts affect cross-border equipment certification and service liability frameworks.
Market Dynamics
Outpatient diagnostic centers across Brazil are collapsing the historical hospital-centric procurement model, forcing equipment vendors to restructure service contracts and financing terms for decentralized buyers.
Growth Catalysts
- ANVISA Risk-Based Reclassification:Brazil's streamlined technical documentation requirements for MRI systems are compressing approval timelines for imported high-field equipment, accelerating fleet replacement cycles.
- Referral Network Density:São Paulo's concentration of tertiary care hospitals generates patient flows that justify dedicated imaging capacity in surrounding diagnostic centers.
- Helium Conservation Technologies:Closed-loop cryogenic cooling systems are reducing operational dependency on liquid helium supply volatility, lowering total cost of ownership for mid-tier facilities.
Market Restraints
- Liquid Helium Supply Concentration:Regional dependence on US and Qatari helium exports creates input cost volatility that distorts operating budgets for superconducting MRI systems.
- Import Licensing Friction:Argentina's national pharmaceutical regulator imposes extended clinical validation timelines that delay equipment commissioning by 8-14 months versus Brazilian pathways.
- Technical Specialist Scarcity:Certified MRI physicists and maintenance engineers concentrate in São Paulo and Buenos Aires, leaving secondary cities underserved for complex system support.
Strategic Opportunities
- Mercosur Harmonization:Pending cross-border equipment certification frameworks would enable single regulatory approval for sales across Brazil, Argentina, Paraguay, and Uruguay.
- AI-Integrated Workflow Platforms:Automated scan prescription and reconstruction algorithms are compressing examination times, allowing diagnostic centers to increase daily throughput without additional magnet capacity.
- Bariatric Patient Segments:Open MRI configurations command premium positioning for obese and claustrophobic populations underserved by conventional closed-bore systems.
Industry Challenges
- Field Service Engineer Pipeline:Magnet quench recovery and cryogenic system maintenance require specialized training that regional technical institutes do not currently supply at scale.
- Legacy System Integration:PACS and radiology information systems in public hospital networks operate on outdated protocols that complicate connectivity with modern MRI consoles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America MRI Market |
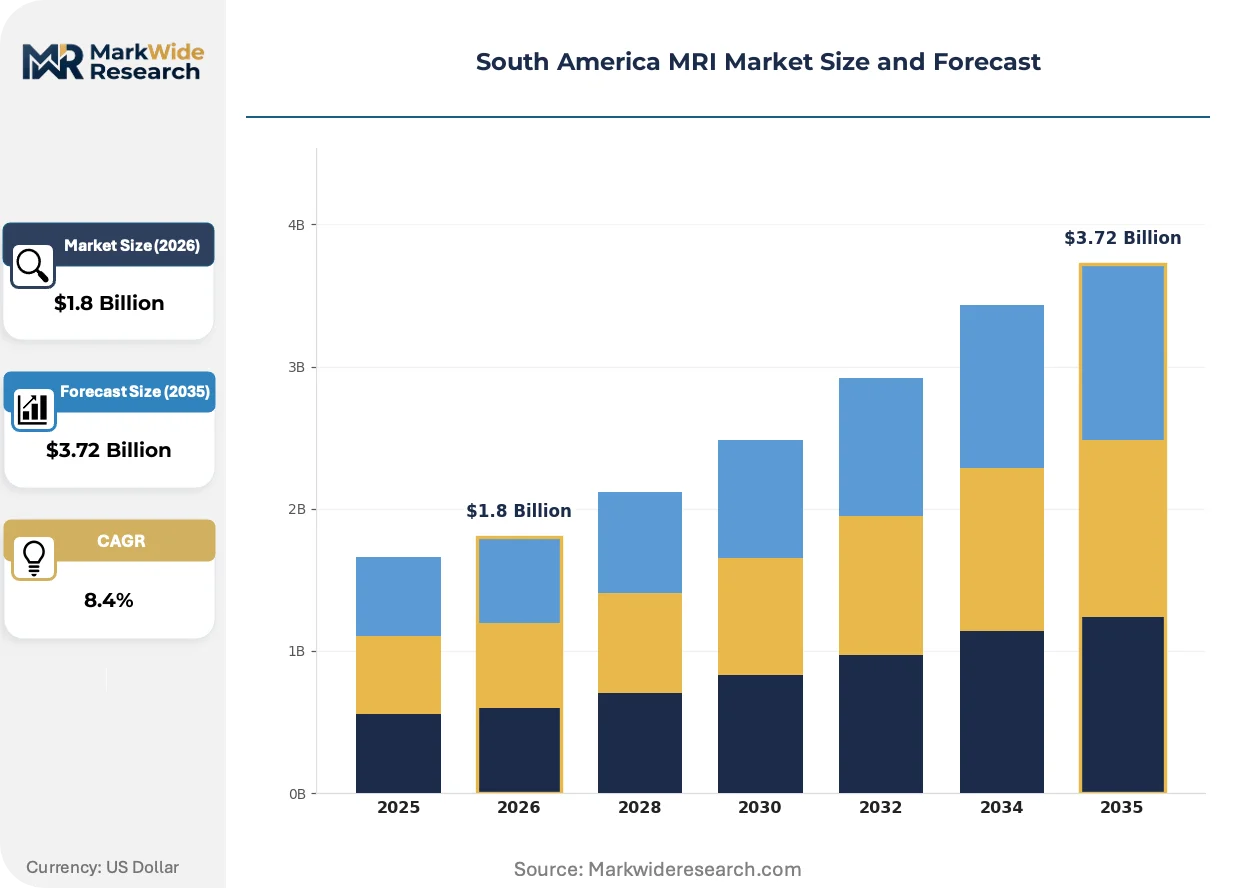
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Application: Neurology, Orthopedics, Oncology, Cardiovascular Technology: High-Field MRI, Low-Field MRI, Ultra-High-Field MRI, Hybrid MRI |
| Companies Covered | Siemens Healthineers AG, Koninklijke Philips NV, GE Healthcare, Canon Medical Systems Corporation, FUJIFILM Corporation, Bracco Diagnostic Inc, ESAOTE SPA, Hologic Inc, Hitachi Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America MRI Market Evolving Landscape
Artificial intelligence integration and decentralized care delivery are restructuring how MRI capacity is deployed and monetized across South American healthcare networks.
Compressed sensing reconstruction algorithms are fragmenting the traditional trade-off between scan duration and image quality. Diagnostic centers in Brazil's Southeast region are adopting these techniques to double daily examination volumes without magnet upgrades. The technology is fragmenting service-level expectations, as patients accustomed to same-day scheduling at outpatient clinics now demand equivalent access from hospital-based radiology departments.
ANVISA's updated post-market surveillance requirements for Class IV medical devices are mandating real-time adverse event reporting through digital platforms. Manufacturers must now maintain localized technical documentation and in-country representation for surveillance compliance. High-field MRI systems face the steepest compliance burden, with importers restructuring Brazilian subsidiaries to absorb regulatory liability directly.
Diagnostic centers are unbundling equipment procurement from long-term service contracts, forcing vendors to compete on discrete maintenance pricing. São Paulo's largest outpatient imaging chains now tender magnet coverage separately from coil replacement and software upgrades. This behavior is most visible in Brazil's private insurance market, where reimbursement pressure on imaging fees drives facilities to minimize fixed cost commitments.
South America MRI Market Segmentation
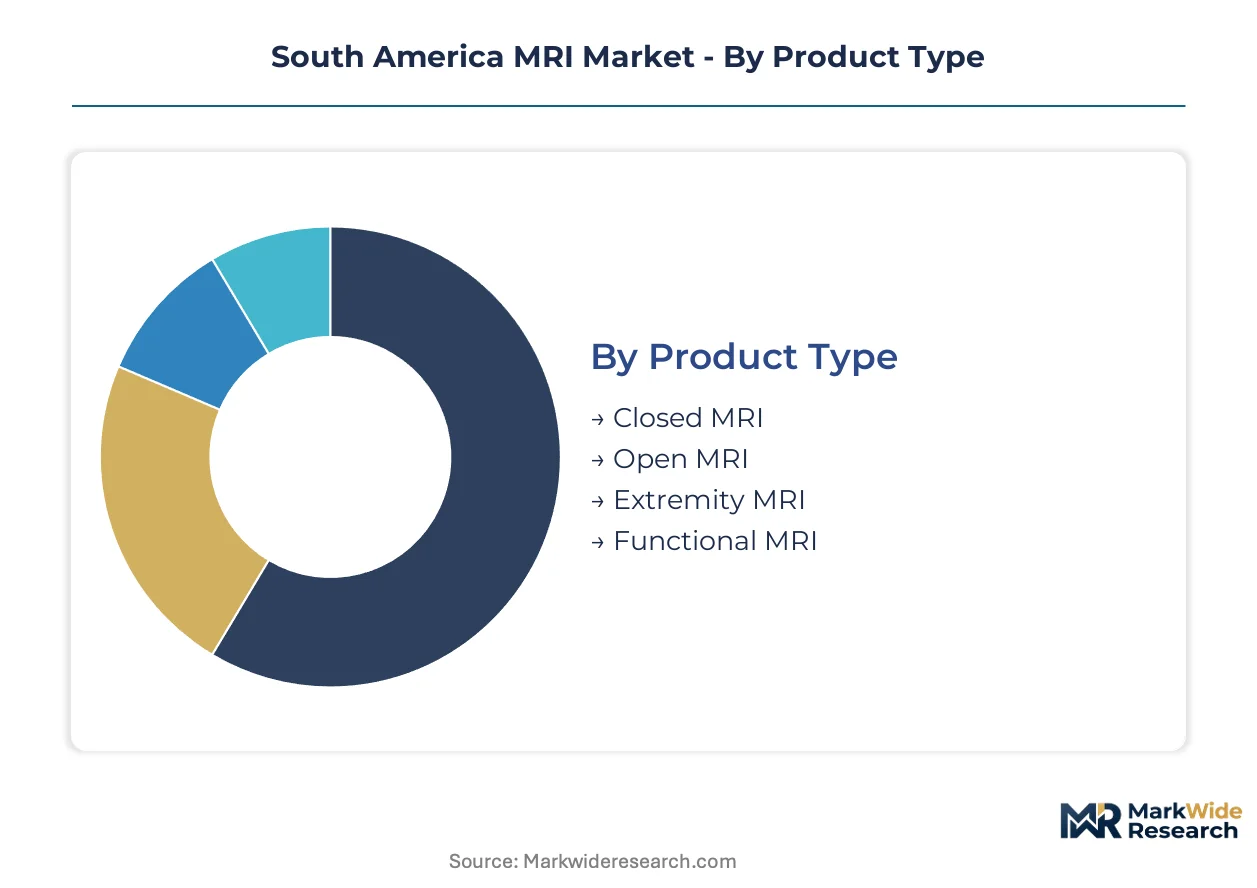
South American MRI procurement patterns diverge sharply across product configurations, end-user settings, and clinical applications. Understanding these segment boundaries reveals where vendors must restructure pricing and service models to capture replacement cycles and new capacity installations.
Product Type:
Margin pools concentrate in high-field closed systems where service contracts and helium management generate recurring revenue streams, while open configurations command premium positioning for underserved patient populations.
- Closed MRI:Superconducting magnets operating at 1.5T and 3.0T field strengths deliver superior signal-to-noise ratios for neurological and oncological diagnostics. São Paulo's tertiary hospital networks anchor demand as referral density justifies dedicated high-throughput installations.
- Open MRI:Permanent magnet or resistive designs eliminate patient enclosure, addressing bariatric and claustrophobic populations excluded from conventional bore systems. Brazil's private diagnostic chains in Rio de Janeiro and Belo Horizonte are expanding open configurations to differentiate against hospital-based competitors.
- Extremity MRI:Dedicated limb-scanning systems with compact footprints serve orthopedic-focused outpatient clinics.
- Functional MRI:Blood-oxygen-level-dependent imaging enables pre-surgical brain mapping for neurosurgical planning.
The dominant share belongs to Closed MRI, while Open MRI is closing the gap fastest.
End User:
Procurement authority is fragmenting as diagnostic centers and outpatient clinics displace traditional hospital-centric purchasing.
- Diagnostic Centers:Brazil's independent imaging chains are unbundling equipment procurement from long-term service contracts, forcing vendors to compete on discrete maintenance pricing. ANVISA's streamlined registration pathways enable faster fleet expansion than hospital bureaucracy permits.
- Outpatient Clinics:Same-day scheduling capabilities and direct patient access are driving capital allocation toward decentralized MRI capacity. São Paulo's largest outpatient imaging chains now tender magnet coverage separately from software upgrades.
- Hospitals:Public hospital networks in Brazil and Argentina face legacy PACS integration challenges that complicate connectivity with modern MRI consoles.
- Research Institutions:Academic medical centers in Buenos Aires and São Paulo anchor demand for advanced functional imaging protocols.
Diagnostic Centers hold the dominant installed base position, though Outpatient Clinics are expanding most quickly.
Application:
Clinical throughput economics vary dramatically by specialty, with neurology and oncology justifying premium field strengths while orthopedics tolerates lower-cost configurations.
- Neurology:High-resolution brain imaging for stroke, multiple sclerosis, and tumor detection demands 3.0T field strengths and specialized head coils. Brazil's Southeast region concentrates neurologist referral networks that sustain dedicated capacity.
- Oncology:Whole-body staging and treatment response monitoring drives continuous scan volume at tertiary centers. Compressed sensing reconstruction algorithms are doubling daily examination volumes without magnet upgrades.
- Orthopedics:Joint and spine imaging represents the highest-volume indication across mid-tier diagnostic centers.
- Cardiovascular:Cardiac MRI remains underpenetrated due to technologist training gaps and longer examination protocols.
Neurology commands the dominant procedure volume, with Oncology climbing the fastest as cancer screening programs expand.
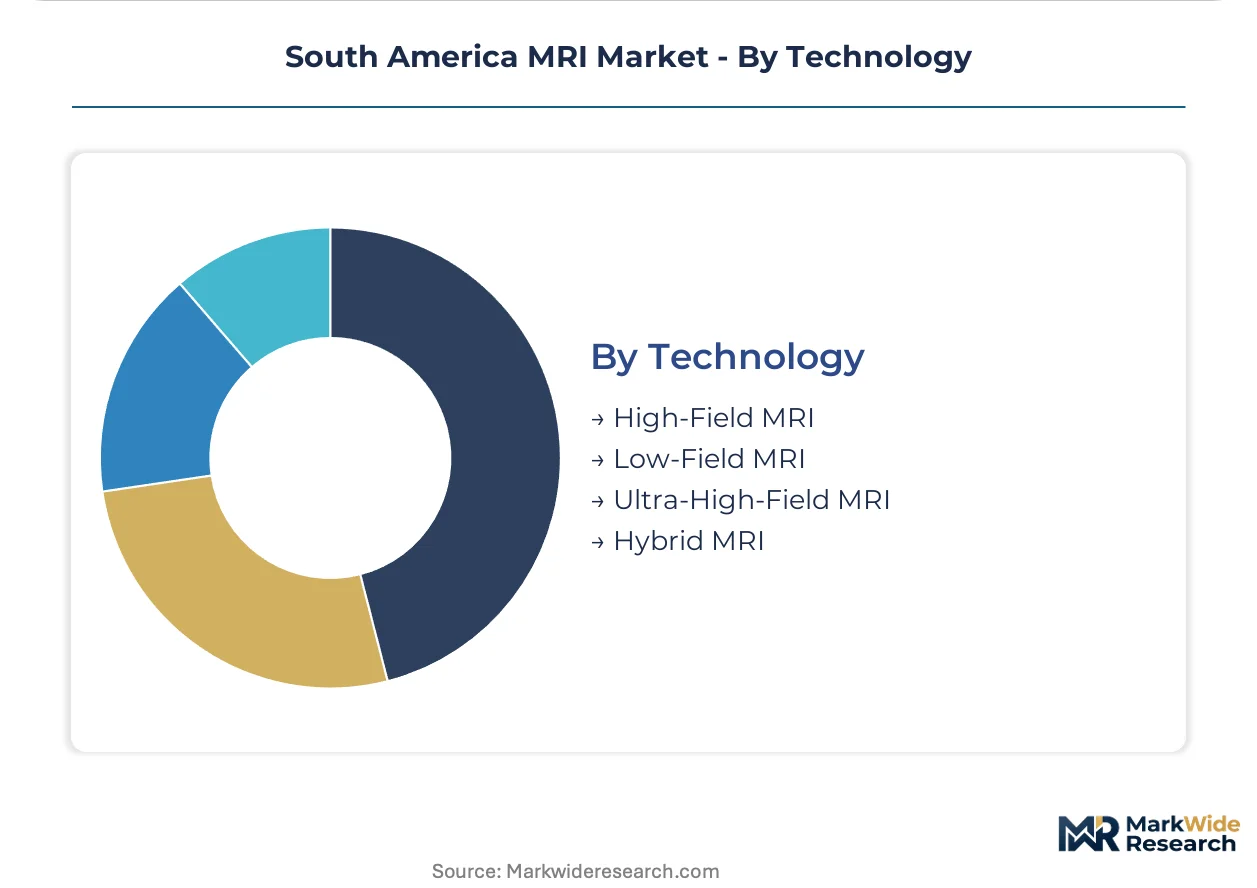
Technology:
Field strength stratification determines capital intensity, operational costs, and clinical capability boundaries across the installed base.
- High-Field MRI:1.5T and 3.0T superconducting systems dominate replacement cycles as facilities seek faster throughput. Helium conservation technologies with closed-loop cryogenic cooling are reducing operational dependency on volatile liquid helium supply chains.
- Ultra-High-Field MRI:7.0T research systems enable sub-millimeter resolution for neurodegenerative disease studies. Brazil's academic medical centers anchor regional demand as research funding concentrates in São Paulo and Rio de Janeiro.
- Low-Field MRI:Permanent magnet systems serve price-sensitive installations in secondary cities.
- Hybrid MRI:Combined PET-MR configurations enable simultaneous functional and anatomical imaging for oncology staging.
High-Field MRI maintains the dominant installed position, while Ultra-High-Field MRI is gaining share fastest among research-focused institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic center chains and outpatient clinic networks concentrate procurement authority across South America, displacing traditional hospital-centric purchasing patterns and reshaping equipment distribution geography.
Brazil
São Paulo's referral hospital networks generate patient flows justifying dedicated MRI capacity in surrounding diagnostic centers. ANVISA's risk-based reclassification for Class IV medical devices compresses approval timelines for imported high-field systems. The Southeast region anchors national demand, with Rio de Janeiro and Belo Horizonte expanding independent imaging chains.
Argentina
Buenos Aires concentrates certified MRI physicists and maintenance engineers, leaving secondary cities underserved for complex system support. The national pharmaceutical regulator imposes extended clinical validation timelines delaying equipment commissioning. Córdoba and Rosario are emerging as satellite hubs for mid-tier diagnostic investments.
Chile
Santiago's private insurance market drives reimbursement-sensitive procurement favoring operational cost optimization. The national medical device regulator maintains alignment with international standards for streamlined import licensing. Northern mining regions generate occupational health imaging demand distinct from clinical diagnostics.
Colombia
Bogotá's tertiary care concentration supports high-throughput neurological and oncological imaging installations. The national health technology assessment body evaluates MRI acquisitions for public hospital networks. Medellín's medical tourism infrastructure attracts capital for premium diagnostic configurations.
Peru
Lima's fragmented diagnostic landscape presents consolidation opportunities for imaging chain operators. The national pharmaceutical regulator oversees import licensing with variable timeline predictability. Arequipa and Trujillo represent secondary city expansion targets for standardized mid-field installations.
South America MRI Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established service infrastructures. Siemens Healthineers AG, Koninklijke Philips NV, and GE Healthcare occupy dominant positions through long-term hospital network contracts. Strategic archetypes include integrated diagnostics platforms, financing-structured equipment vendors, and AI-workflow specialists. Competitive moves concentrate on restructuring service contracts for decentralized buyers and compressing scan-to-diagnosis times through software integration.
Within the integrated diagnostics tier, Siemens Healthineers AG represents the archetype of service infrastructure leverage sustaining public hospital relationships. GE Healthcare exemplifies financing-structured competition lowering capital barriers for mid-tier diagnostic centers. Koninklijke Philips NV occupies a position as workflow platform specialist differentiating through AI-integrated scan optimization. These three anchors demonstrate how vendor strategy diverges across procurement authority fragmentation.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| GE Healthcare |
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| Bracco Diagnostic Inc |
| ESAOTE SPA |
| Hologic Inc |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
ANVISA's risk-based classification for Class IV medical devices gates both supplier qualification and price differentiation simultaneously, as manufacturers must maintain localized technical documentation and in-country representation to access Brazil's diagnostic center procurement channels. This regulatory threshold fragments the market into tiers where vendors with established Brazilian subsidiaries command premium positioning over importers still navigating approval timelines.
Pricing Analysis
Cost-plus service contracts with helium price indexation dominate vendor-facility relationships across Brazil's Southeast region. Pricing stratifies across premium, standard, and economy tiers based on field strength certification and bundled maintenance coverage. Cost compression in mid-tier diagnostic centers is intensifying because independent imaging chains now tender magnet coverage separately from software upgrades. Public hospital networks exhibit the highest price sensitivity due to fixed budget allocations, while private outpatient chains in São Paulo prioritize throughput optimization over capital outlay minimization.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Rotterdam ports to Santos container terminals have elevated landed costs for superconducting magnet systems. Manufacturing concentrates in Germany, the Netherlands, and the United States for high-field MRI platforms, while China anchors production of permanent magnet components for open configurations. The regional installed base draws from liquid helium supply chains tethered to US and Qatari export terminals. Single-source vulnerability characterizes cryogenic cooling system procurement, as closed-loop technologies remain concentrated among three specialized vendors. Distribution runs through authorized dealer networks that maintain field service engineer pools for magnet quench recovery and coil replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified MRI physicist scarcity constrains system utilization rates across secondary Brazilian cities, creating a structural bottleneck that limits revenue capture for installed capacity. This capability gap shapes competitive dynamics more acutely than equipment availability or financing terms.
For Market Incumbents: Shield installed base positions by embedding field service engineers within São Paulo's largest diagnostic center chains through exclusive multi-year maintenance agreements. Deepen backward integration into helium conservation technology to offset supply volatility exposure. Counter emerging AI-workflow specialists by acquiring scan optimization software capabilities that compress examination times without magnet replacement. For New Entrants and Emerging Players: Remote technical support gaps in Argentina's secondary cities present white-space opportunities where incumbents under-serve maintenance response timelines. Target Córdoba and Rosario diagnostic centers with standardized mid-field installations and training-partnership go-to-market structures. Differentiate through subscription-based software upgrades that unbundle from traditional magnet coverage contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian diagnostic center chains seeking exit liquidity after consolidation phases. Long-term viability hinges on AI-integrated workflow adoption rates that determine throughput economics across the projection horizon. Monitor ANVISA post-market surveillance compliance costs as the inflection indicator for vendor margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Conservation Technology Licensing | Reduces operational dependency on volatile US and Qatari liquid helium supply chains for Brazilian facilities. |
| AI-Integrated Workflow Platform Development | Compresses scan-to-diagnosis time for São Paulo outpatient chains competing on same-day scheduling capabilities. |
| Diagnostic Center Chain Partnership | Secures long-term service contract revenue from Brazil's independent imaging networks unbundling procurement. |
| ANVISA Regulatory Compliance Investment | Accelerates approval timelines for imported high-field systems through localized technical documentation. |
| Remote Technical Support Infrastructure | Addresses certified MRI physicist scarcity in Argentina's secondary cities through centralized monitoring capabilities. |
Research Methodology
A standing panel of hospital biomedical engineers, diagnostic center procurement directors, ANVISA regulatory consultants, and GPO contracts managers provided ongoing calibration throughout the study period. Primary interviews with field service engineers and helium supply specialists were cross-validated against ANVISA device registration databases, Mercosur trade flow records, and hospital procurement disclosures. Bottom-up installed base enumeration was triangulated with top-down healthcare expenditure modeling across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, end user, clinical application, and field strength technology dimensions. CAGRs were derived from replacement cycle timing, fleet expansion patterns, and reimbursement trajectory assumptions. Forecast inputs incorporated ANVISA approval timeline compression, compressed sensing algorithm adoption curves, and diagnostic center chain consolidation rates.
Forecasts assume regulatory continuity in ANVISA's risk-based classification and Argentina's national pharmaceutical oversight; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market