
 Medical Imaging Management Market | 2026-2036
Medical Imaging Management Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Management Market Outlook
North American enterprise software vendors is decoupling from legacy on-premise hardware dependencies as health systems seek scalable cloud architectures. GE Healthcare leverages its Edison platform to anchor AI-native imaging workflows across hospital networks. Siemens Healthineers sustains R&D intensity in digital twin simulations for MRI protocol optimization. Philips competes through hybrid delivery models that bridge on-premise security with cloud elasticity.
Medical imaging management encompasses software systems that acquire, store, distribute, and analyze diagnostic images with DICOM compliance and sub-second retrieval latency for clinical decision support. Picture Archiving and Communication Systems dominate installed base value but face margin compression from commoditized storage, while Imaging Analytics commands premium pricing through FDA-cleared AI algorithms for lesion detection and quantification. Workflow Management Solutions represent the fastest-expanding segment as labor shortages drive automation of technologist scheduling, exam protocoling, and radiologist worklist prioritization.
FDA software-as-a-medical-device regulations, HIPAA security rule amendments, and IEC 62304 medical device software lifecycle standards collectively elevate compliance costs while creating barriers for unvalidated entrants. The EU AI Act and MDR convergence in Europe imposes additional conformity requirements on algorithmic diagnostic tools. Stakeholders must monitor evolving reimbursement pathways for AI-augmented reads and decide whether to build, partner, or acquire imaging analytics capabilities before regulatory clarity solidifies competitive positions.
Market Dynamics
Cloud-native architectures are displacing legacy on-premise PACS installations as hospital networks consolidate multi-site imaging infrastructure, forcing vendors to decouple software from proprietary hardware stacks.
Growth Catalysts
- AI-augmented diagnostic workflows:FDA software-as-a-medical-device clearances accelerate algorithmic lesion detection deployment across radiology departments.
- Enterprise imaging consolidation:Integrated delivery networks unify cardiology and radiology PACS under single-vendor contracts to reduce interoperability friction.
- Labor automation imperatives:Persistent technologist shortages drive demand for automated exam protocoling and intelligent worklist prioritization systems.
Market Restraints
- Compliance cost escalation:IEC 62304 software lifecycle standards and HIPAA security rule amendments impose validation burdens that favor incumbent vendors.
- Cloud migration latency:Hospital IT departments face 18-36 month procurement cycles for infrastructure overhauls, slowing subscription revenue conversion.
- Storage commoditization:Hyperscale cloud providers compress margins on archival tiers, eroding traditional PACS profitability.
Strategic Opportunities
- AI reimbursement pathways:CMS and private payor coverage determinations for algorithm-assisted reads create new revenue streams for imaging analytics vendors.
- Hybrid deployment models:Edge-computing architectures that process sensitive data on-premise while leveraging cloud elasticity address security-conscious buyers.
- Workflow orchestration:Cross-departmental scheduling platforms that integrate MRI, CT, and ultrasound bookings capture operational efficiency budgets.
Industry Challenges
- Interoperability standardization:DICOMweb and FHIR implementation inconsistencies force costly custom integration work for multi-vendor environments.
- Cybersecurity certification timelines:SOC 2 Type II and HITRUST assessments extend sales cycles by 6-12 months for cloud-native entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Management Market |
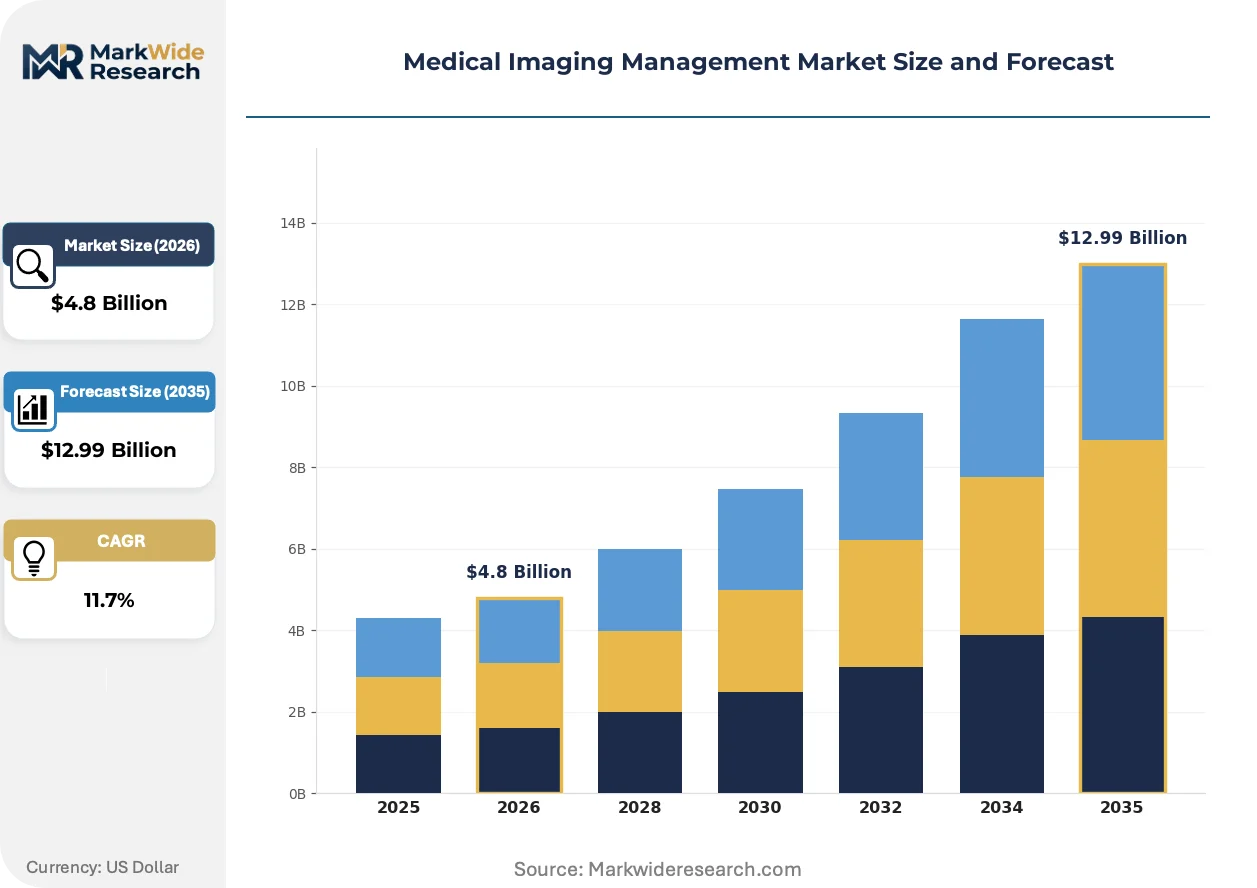
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiology Information Systems, Picture Archiving and Communication Systems, Imaging Analytics, Workflow Management Solutions End User: Hospitals, Diagnostic Laboratories, Research Institutions, Imaging Centers Delivery Mode: On-Premise, Cloud-Based, Hybrid, Software as a Service Technology: X-Ray, MRI, CT, Ultrasound |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Holdings Corporation, McKesson Corporation, Agfa-Gevaert Group, Carestream Health, Canon Medical Systems, Merge Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Management Market Strategic Shifts
Containerized microservices architectures are fragmenting monolithic PACS codebases, enabling point-solution vendors to attack specific workflow pain points without full-platform displacement.
Vendor-neutral archive technology is modularizing image storage from viewing and analytics layers, allowing hospitals to unbundle procurement decisions. Radiology departments at academic medical centers are piloting best-of-breed viewers while retaining legacy archives. This decomposition is compressing switching costs and opening entry points for specialized workflow vendors.
The EU AI Act convergence with MDR requirements imposes additional conformity assessments on algorithmic diagnostic tools marketed in Europe. Manufacturers must now document training data provenance and performance monitoring protocols before CE marking. European radiology groups are delaying procurement decisions pending regulatory clarity, favoring established vendors with compliance infrastructure.
Subscription pricing for imaging software is displacing perpetual license models as hospital capital budgets tighten. Chief financial officers prefer operational expenditure treatment for IT investments, forcing vendors to restructure revenue recognition. United States-based health systems with private equity ownership are leading this transition, demanding usage-based billing aligned with exam volumes.
Medical Imaging Management Market Segmentation
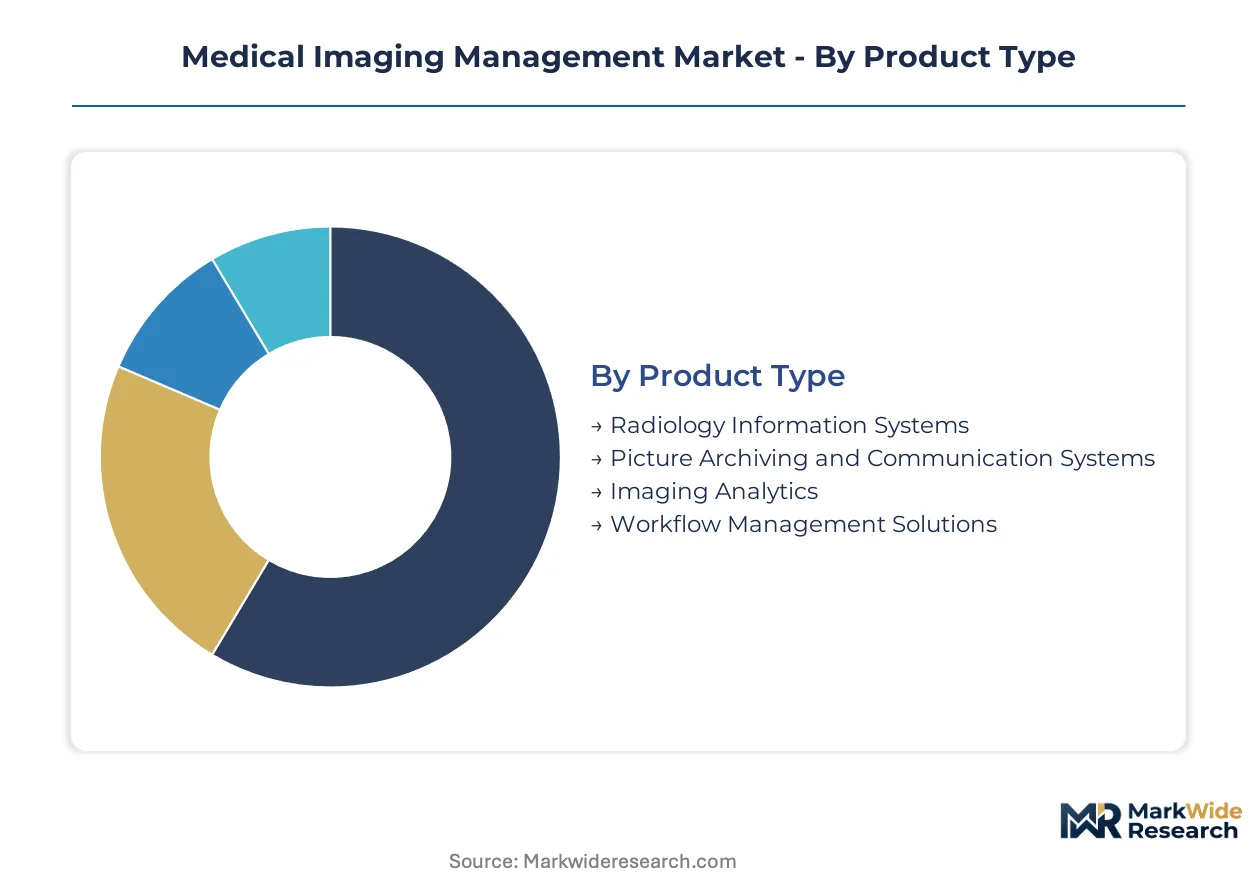
Medical imaging management segmentation reveals distinct procurement patterns across infrastructure layers. Product architecture, deployment topology, and clinical application each command separate budget cycles and vendor evaluation criteria within hospital networks.
Product Type:
Supply concentration clusters around platforms with FDA software-as-a-medical-device clearances, creating tiered vendor ecosystems.
- Picture Archiving and Communication Systems:DICOM-compliant repositories with sub-second retrieval latency anchor hospital IT infrastructure. United States integrated delivery networks consolidate multi-site PACS under single-vendor contracts to reduce interoperability friction.
- Imaging Analytics:Algorithmic lesion detection and quantification modules command premium pricing through FDA-cleared AI workflows. Academic medical centers in the United States pilot best-of-breed analytics while retaining legacy archives.
- Radiology Information Systems:Scheduling, reporting, and billing modules interface with PACS layers.
- Workflow Management Solutions:Automated exam protocoling and intelligent worklist prioritization address technologist shortages.
Picture Archiving and Communication Systems absorb the bulk of installed capacity; Workflow Management Solutions is expanding most quickly.
End User:
Procurement authority varies sharply across buyer categories, with capital budget treatment dictating vendor engagement models.
- Hospitals:Enterprise imaging deployments unify cardiology and radiology workflows under centralized governance. United States hospital networks expanding multi-site infrastructure drive demand for scalable cloud architectures.
- Imaging Centers:Independent operators prioritize subscription pricing to align IT expenditure with exam volume fluctuations.
- Diagnostic Laboratories:High-throughput environments require seamless integration with laboratory information systems.
- Research Institutions:Academic medical centers pilot vendor-neutral archives and best-of-breed viewers.
Hospitals absorb the bulk of installed capacity; Imaging Centers is climbing the fastest.
Delivery Mode:
Revenue recognition restructuring accelerates as chief financial officers favor operational expenditure treatment.
- Cloud-Based:Hyperscale elasticity supports multi-site consolidation without proprietary hardware dependencies. United States health systems with private equity ownership lead subscription transitions.
- Hybrid:Edge-computing architectures process sensitive data on-premise while leveraging cloud scalability for archival tiers.
- On-Premise:Legacy installations persist where data sovereignty requirements block external hosting.
- Software as a Service:Usage-based billing aligns vendor revenue with actual exam volumes.
On-Premise retains the bulk of installed capacity; Cloud-Based is gaining share fastest.
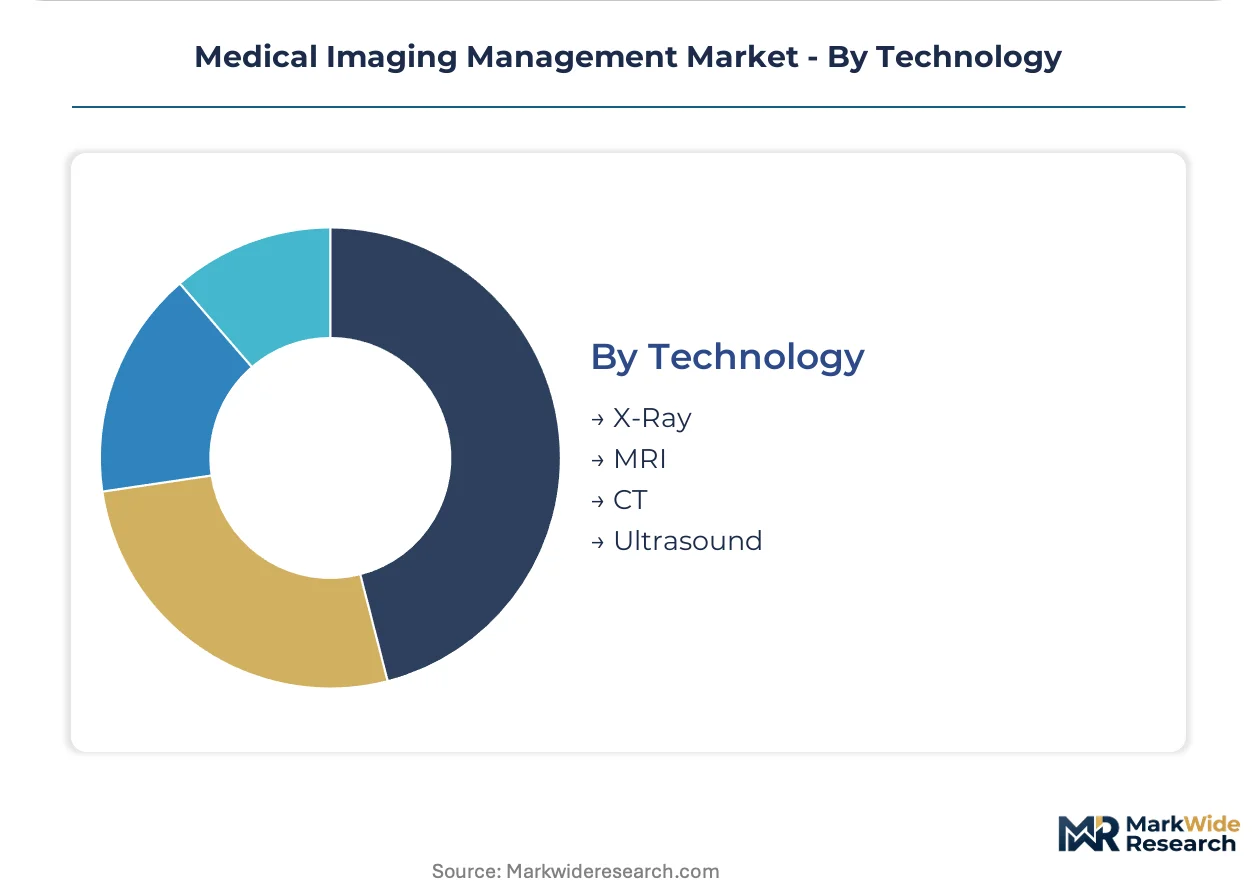
Technology:
Modality-specific workflow requirements fragment procurement decisions across radiology sub-specialties.
- MRI:Digital twin simulations optimize protocol selection and reduce scan times. Siemens Healthineers sustains R&D intensity in this segment.
- CT:High-volume throughput demands intelligent worklist prioritization and automated dose monitoring.
- X-Ray:Highest exam volumes drive commoditization pressure on basic archiving and viewing.
- Ultrasound:Point-of-care expansion requires mobile-optimized workflow tools and distributed image capture.
X-Ray absorbs the bulk of installed capacity; MRI is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley software engineering talent anchors North American innovation in cloud-native imaging architectures, while German precision manufacturing underpins European hardware-software integration capabilities.
United States
Integrated delivery networks in Texas and Florida consolidate multi-site PACS infrastructure under single-vendor contracts. FDA software-as-a-medical-device clearances accelerate algorithmic deployment across academic medical centers. Mayo Clinic and Cleveland Clinic anchor enterprise imaging pilot programs in Rochester and Cleveland.
Germany
Baden-Württemberg manufacturing clusters sustain R&D intensity in MRI digital twin simulations for protocol optimization. EU AI Act convergence with MDR imposes additional conformity assessments on algorithmic diagnostic tools. Siemens Healthineers anchors medical technology development in Erlangen.
Japan
Aging demographics in Kanto drive demand for automated workflow management to address radiologist shortages. PMDA regulatory frameworks govern AI-augmented diagnostic software approvals. Tokyo academic medical centers pilot vendor-neutral archive technologies.
United Kingdom
NHS England procurement frameworks favor subscription pricing models for imaging software to align IT expenditure with operational budgets. MHRA post-Brexit regulatory autonomy shapes software-as-a-medical-device approval pathways. London teaching hospitals lead cloud migration initiatives.
India
Diagnostic laboratory chains in Maharashtra and Karnataka expand high-throughput imaging infrastructure requiring seamless LIS integration. CDSCO medical device regulations govern software lifecycle standards. Hyderabad and Bangalore health technology clusters attract venture capital for imaging analytics startups.
Medical Imaging Management Market Competitive Environment
Global majors compete with regional champions across cloud infrastructure and AI algorithm development, producing a tiered vendor ecosystem where scale-driven platforms coexist with specialized workflow vendors. Consolidation pressures favor incumbents with compliance infrastructure. Three archetypes dominate: diversified conglomerates with Edison-type platforms, pure-play imaging specialists, and cloud-native entrants. M&A activity targets AI analytics capabilities, while strategic partnerships bridge hardware-software gaps.
Among diversified health technology conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions exemplifying platform-centric competition. These companies represent archetypes of hardware-software integration, medical device manufacturing heritage, and hybrid delivery model innovation respectively. Their collective presence anchors competitive dynamics around enterprise imaging consolidation and cloud-native architecture transitions.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| McKesson Corporation |
| Agfa-Gevaert Group |
| Carestream Health |
| Canon Medical Systems |
| Merge Healthcare |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud storage index movements cascade through medical imaging software supply chains, compressing archival-tier margins while elevating premiums for AI-augmented diagnostic modules. Hospital procurement committees unbundle vendor-neutral archives from viewing layers, forcing price competition at the infrastructure base while protecting algorithmic workflow premiums.
Pricing Analysis
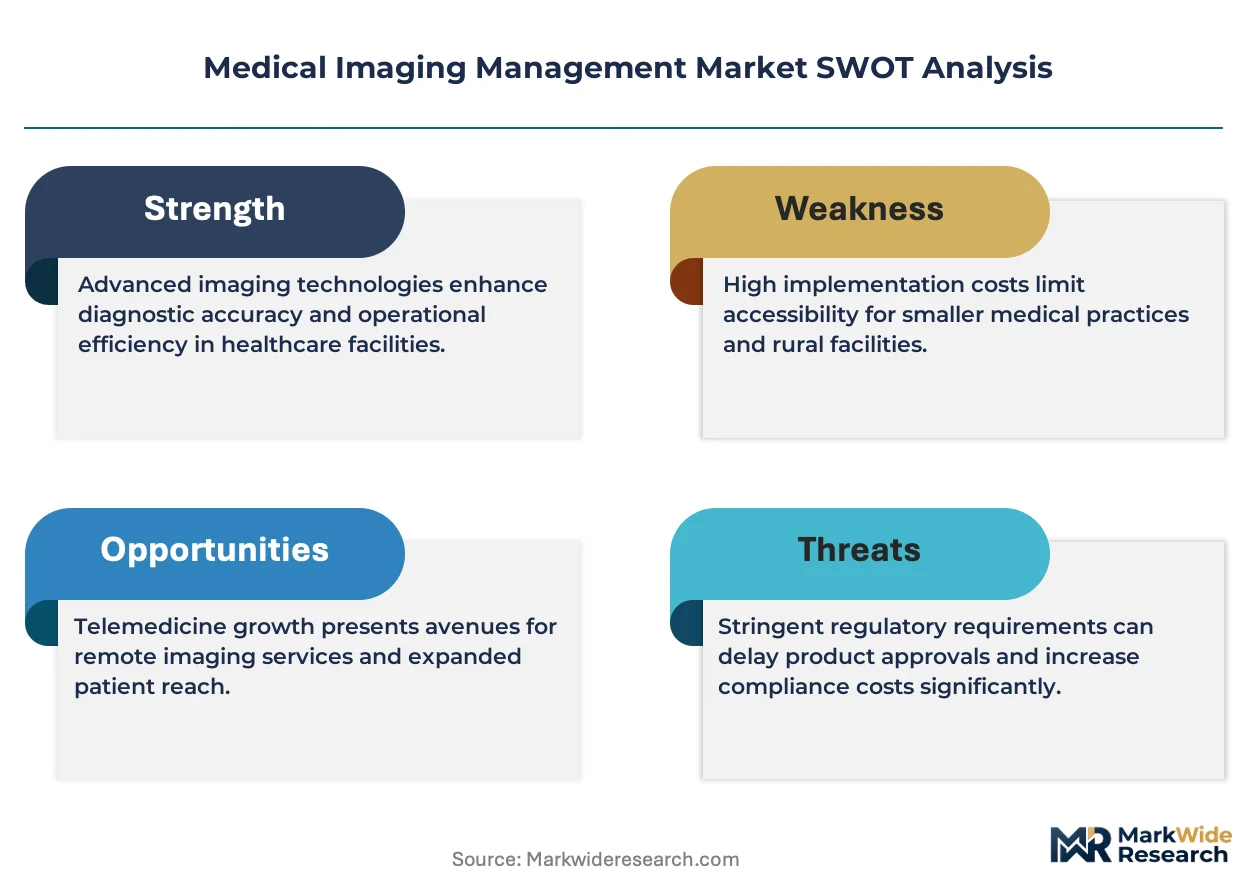
Warranty and implementation service bundling separates enterprise PACS contracts from stripped-down SaaS tiers targeting independent imaging centers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA software-as-a-medical-device clearance status, with validated AI algorithms commanding substantial premiums over uncertified workflow tools. Pricing pressure stems from hyperscale cloud providers entering archival storage tiers, eroding legacy vendor profitability. Independent imaging centers exhibit highest price sensitivity, while academic medical centers prioritize clinical validation over cost minimization.
Supply Chain Analysis
Freight and customs logistics for specialized medical hardware components concentrate supply chain leverage among established manufacturing clusters. Component sourcing draws from Germany for precision MRI subsystems, Japan for sensor arrays, and the United States for FDA-cleared software modules. Raw material dependencies include rare-earth magnets for imaging equipment, semiconductor chips for processing units, and specialized glass for detector assemblies. Single-source vulnerability persists in cryogenic cooling systems for MRI platforms. Distribution runs through hospital GPO contracts and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical imaging management sits at a technology-transition inflection where cloud-native architectures systematically displace legacy on-premise PACS installations. Containerized microservices and vendor-neutral archives are dismantling monolithic software stacks that dominated procurement for two decades.
For Market Incumbents: To counter cloud-native entrants attacking workflow orchestration segments, GE Healthcare and Siemens Healthineers must accelerate Edison-platform and digital-twin R&D investments while securing multi-site hospital network contracts that raise switching costs. Backward integration into AI training data pipelines protects algorithmic differentiation. Certification investment in FDA software-as-a-medical-device pathways maintains regulatory moats against unvalidated competitors. For New Entrants and Emerging Players: Direct-to-cloud deployment channels offer the most penetrable route for specialized workflow vendors targeting mid-tier hospital networks in Texas and Florida. Best-of-breed analytics modules for specific modalities—particularly MRI protocol optimization and CT dose monitoring—present white-space opportunities beneath full-platform incumbents. Partnership with vendor-neutral archive providers enables market entry without storage infrastructure investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI analytics specialists with FDA-cleared algorithms in the United States, where reimbursement pathway clarity is crystallizing faster than in European markets constrained by EU AI Act uncertainty. Long-term viability hinges on software-as-a-medical-device compliance infrastructure rather than hardware manufacturing scale. Watch CMS coverage determinations for algorithm-assisted reads as the critical inflection signal for imaging analytics valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | FDA 510(k) clearance for lesion detection algorithms unlocks hospital procurement at academic medical centers. |
| Hospital System Partnership | Multi-site IDN contracts in Texas and Florida consolidate cardiology-radiology workflows under single-vendor governance. |
| Cloud-Native Platform Migration | Containerized microservices displace monolithic PACS codebases, enabling point-solution vendor entry. |
| AI Companion Development | FDA-cleared diagnostic algorithms command premium pricing through automated worklist prioritization. |
| Reimbursement Strategy | CMS coverage pathways for algorithm-assisted reads create sustainable revenue streams beyond software licensing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this medical imaging management analysis. Primary interviews with hospital CIOs, radiology department chairs, biomedical engineers, and GPO contracts managers cross-validated procurement trend signals. Secondary sources included FDA 510(k) clearance databases, CMS reimbursement determinations, hospital procurement records, and SEC filings from publicly traded health technology conglomerates. Bottom-up site-level deployment tracking reconciled against top-down vendor revenue disclosures.
Data-stream reconciliation across multiple information channels informed the analytical framework. Segmentation modeling spanned product architecture, deployment topology, end-user category, and modality-specific technology requirements across the projection horizon. CAGRs derived from curve-fitting historical adoption patterns against regulatory milestone timing and cloud infrastructure investment cycles. Forecast inputs weighted FDA software-as-a-medical-device clearance velocity and hospital capital-to-operating-expenditure transition rates.
The model holds under stable regulatory clarity conditions; deviation in FDA enforcement posture or EU AI Act implementation timelines would shift vendor competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
C-Arms Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Preclinical Brain Imaging Market