
 Finland Pharmaceutical Market | 2026-2036
Finland Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Pharmaceutical Market Foresight
Aftermarket service revenue from biologics cold-chain logistics is narrowing as Orion Oyj extends its domestic distribution infrastructure and Novartis Finland anchors its Helsinki-area specialty pharmacy network. MSD Finland leverages long-standing institutional relationships with university hospitals, while Roche differentiates through companion diagnostics bundled with targeted oncology therapies.
Finland pharmaceuticals encompass chemically synthesized small molecules, recombinant biologics, and sterile injectables manufactured under EU GMP Annex 1 aseptic processing standards, primarily serving therapeutic intervention and disease prevention across Nordic healthcare systems. Prescription drugs dominate value pools given Kela's centralized reimbursement authority, while biosimilars compete aggressively on tender pricing in hospital formularies. Oncology commands the fastest therapy-area expansion as academic medical centers in Helsinki and Tampere deepen participation in pan-European clinical trial networks.
Fimea, the Finnish Medicines Agency, enforces EU MDR-aligned pharmacovigilance and clinical trial transparency requirements that elevate compliance costs for market entrants, while EMA centralized procedures streamline multinational portfolio introductions. Kela's annual reimbursement list revisions directly reshape prescribing volumes and manufacturer revenue visibility. Stakeholders must track Helsinki's biotech incubator pipeline and anticipate which early-stage platforms will graduate into Fimea-regulated commercialization pathways.
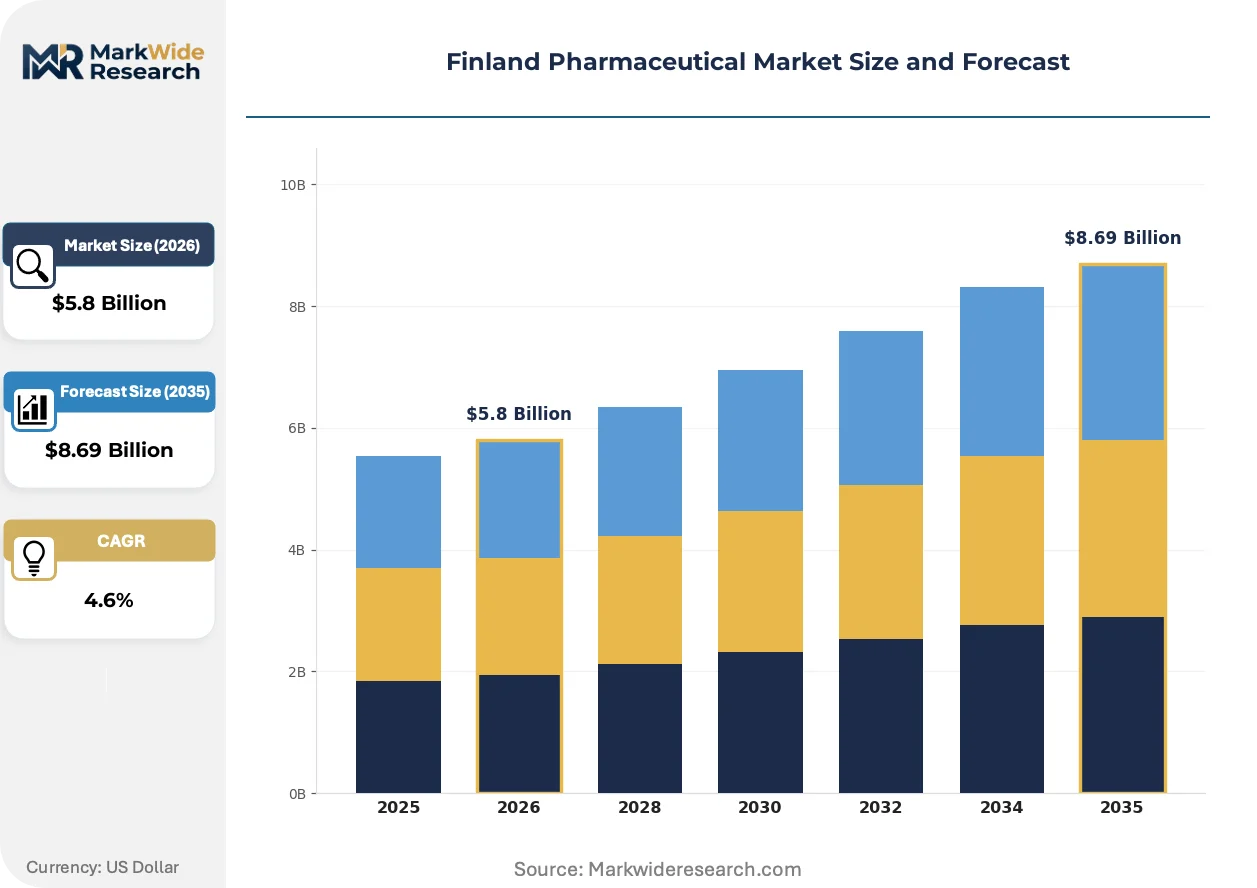
Market Dynamics
Kela's transition toward outcome-based reimbursement protocols is compressing traditional volume-based prescribing and forcing manufacturers to demonstrate real-world evidence before securing formulary placement.
Growth Catalysts
- EU MDR-aligned pharmacovigilance:Fimea's enforcement of enhanced clinical trial transparency requirements elevates standards for market entrants, rewarding early compliance investments with accelerated pathway access.
- Oncology biologics demand:Academic medical centers in Helsinki and Tampere are deepening participation in pan-European clinical trial networks, attracting multinational sponsors seeking Nordic patient cohorts.
- Specialty pharmacy infrastructure:Domestic cold-chain distribution networks are expanding capacity to handle temperature-sensitive biologics, reducing reliance on cross-border logistics.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of complex biologics depends on imported starting materials from concentrated Asian manufacturing basins, exposing Finnish formulators to supply interruption risk.
- Kela reimbursement list volatility:Annual revisions to the centralized reimbursement catalog create revenue visibility constraints for manufacturers dependent on public formulary placement.
- Biosimilar tender compression:Hospital procurement of off-patent biologics faces aggressive price competition through competitive tendering, eroding margin pools for originator products.
Strategic Opportunities
- Companion diagnostics bundling:Integration of biomarker testing with targeted oncology therapies creates differentiated positioning against pure pharmaceutical competitors.
- Helsinki biotech incubator pipeline:Early-stage platforms graduating from capital-region accelerators offer acquisition targets with pre-validated Fimea regulatory familiarity.
- Outcome-based contracting models:Kela's evolving protocols reward manufacturers willing to assume performance risk through indication-specific reimbursement agreements.
Industry Challenges
- Aseptic processing certification timelines:EU GMP Annex 1 compliance for sterile injectables requires extended facility validation periods that delay commercialization.
- Cross-functional talent scarcity:Regulatory affairs professionals with simultaneous Fimea and EMA procedure expertise command premium compensation in a constrained labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Pharmaceutical Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biosimilars, Vaccines Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases End User: Pharmacies, Hospitals, Clinics, Home Care Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | AbbVie Inc., AstraZeneca plc, Bayer AG, C.H. Boehringer Sohn AG & Ko. KG, GlaxoSmithKline plc, Orion Oyj, Novartis Finland, MSD Finland, Roche, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Pharmaceutical Market Shifts & Advancements
Digital infrastructure is penetrating pharmaceutical operations from manufacturing floor to patient adherence monitoring, compressing traditional workflow timelines and enabling predictive intervention models.
Real-world evidence platforms are digitizing post-market surveillance by integrating electronic health record data from Helsinki University Hospital and Tampere University Hospital into continuous safety monitoring. Oncology and neurology therapeutic developers are adopting these systems fastest, using live outcome feeds to support Kela reimbursement negotiations and accelerate label expansion submissions.
Fimea's alignment with EU MDR pharmacovigilance requirements is elevating compliance architecture across the domestic industry. Manufacturers must now maintain transparent adverse event reporting systems that interface directly with European Medicines Agency databases. Small molecule and biologic segments face equivalent documentation burdens, driving consolidation of regulatory affairs functions among mid-scale domestic players.
Hospital procurement committees are consolidating vendor relationships around integrated supply partners capable of delivering cold-chain logistics, inventory management, and clinical educator support through single contracts. This concentration displaces fragmented distributor networks that previously handled discrete logistics functions. University hospitals in the capital region and Pirkanmaa are furthest advanced in this transition, using multi-year agreements to lock in capacity for expanding biologics portfolios.
Finland Pharmaceutical Market Segmentation
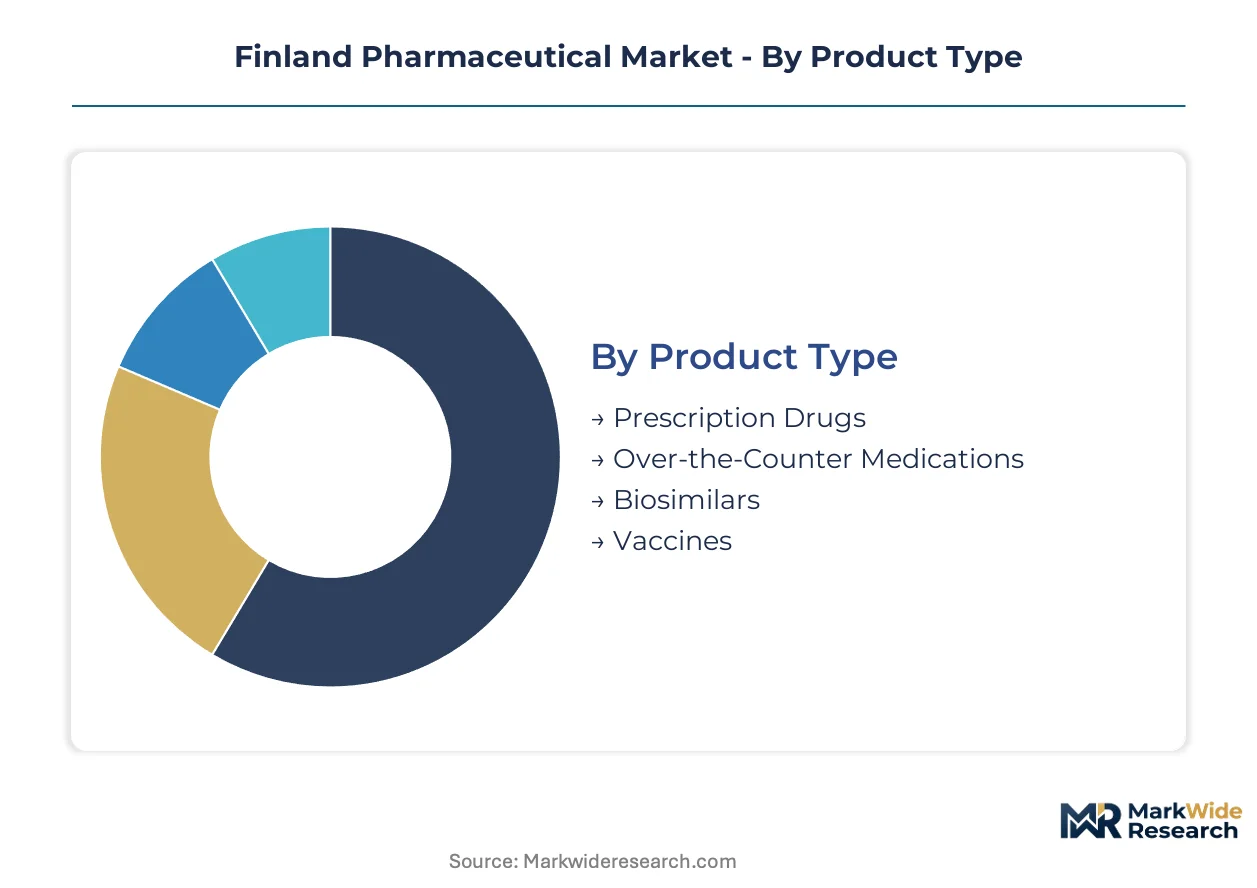
Finland's pharmaceutical segmentation reflects Kela's centralized procurement authority and the concentration of specialty care in Helsinki and Tampere academic medical centers. Distinct service intensity requirements across product categories shape manufacturer go-to-market economics.
Product Type:
After-sales service intensity varies sharply across product categories, with biologics requiring cold-chain maintenance and patient support programs that small molecules rarely demand.
- Prescription Drugs:Small-molecule formulations dominate Kela reimbursement volumes, with cardiovascular and metabolic therapies absorbing the largest share of outpatient pharmacy dispensing. Helsinki University Hospital's specialty clinics drive concentrated demand for novel oncology and neurology prescriptions.
- Biosimilars:Recombinant protein alternatives to originator biologics compete through aggressive hospital tender pricing. Pirkanmaa Hospital District's procurement consolidation has accelerated biosimilar penetration in rheumatology and oncology formularies.
- Over-the-Counter Medications:Self-care products face margin pressure from pharmacy chain consolidation and cross-border e-commerce.
- Vaccines:Public immunization programs dominate procurement through THL national stockpiling contracts.
Prescription drugs hold the largest share; momentum sits with biosimilars.
Therapy Area:
Cost tier stratification separates high-investment specialty biologics from commoditized chronic disease management.
- Oncology:Targeted therapies and immuno-oncology biologics command premium pricing through companion diagnostic bundling. Tampere University Hospital's participation in pan-European trial networks accelerates patient access to investigational compounds.
- Neurology:Multiple sclerosis and Alzheimer's disease pipelines concentrate investment from multinational sponsors seeking Nordic real-world evidence cohorts.
- Cardiovascular:Genericized small-molecule portfolios face reimbursement compression under Kela's annual list revisions.
- Infectious Diseases:Antimicrobial stewardship programs restrict hospital formulary placement for novel antibiotics.
Cardiovascular maintains volume leadership; oncology represents the steepest expansion trajectory.
End User:
Customer type determines regulatory touchpoint density and distribution infrastructure requirements.
- Hospitals:Academic medical centers in the capital region and Pirkanmaa absorb disproportionate shares of high-cost biologics through centralized procurement committees.
- Pharmacies:Retail dispensing networks handle chronic disease maintenance therapies under Kela's reimbursement protocols.
- Clinics:Specialist outpatient facilities in Helsinki coordinate with hospital networks for infusion therapy administration.
- Home Care:Self-administered injectables and oral therapies reduce institutional bed-day costs.
Hospitals capture the highest value per patient; home care is expanding most quickly.
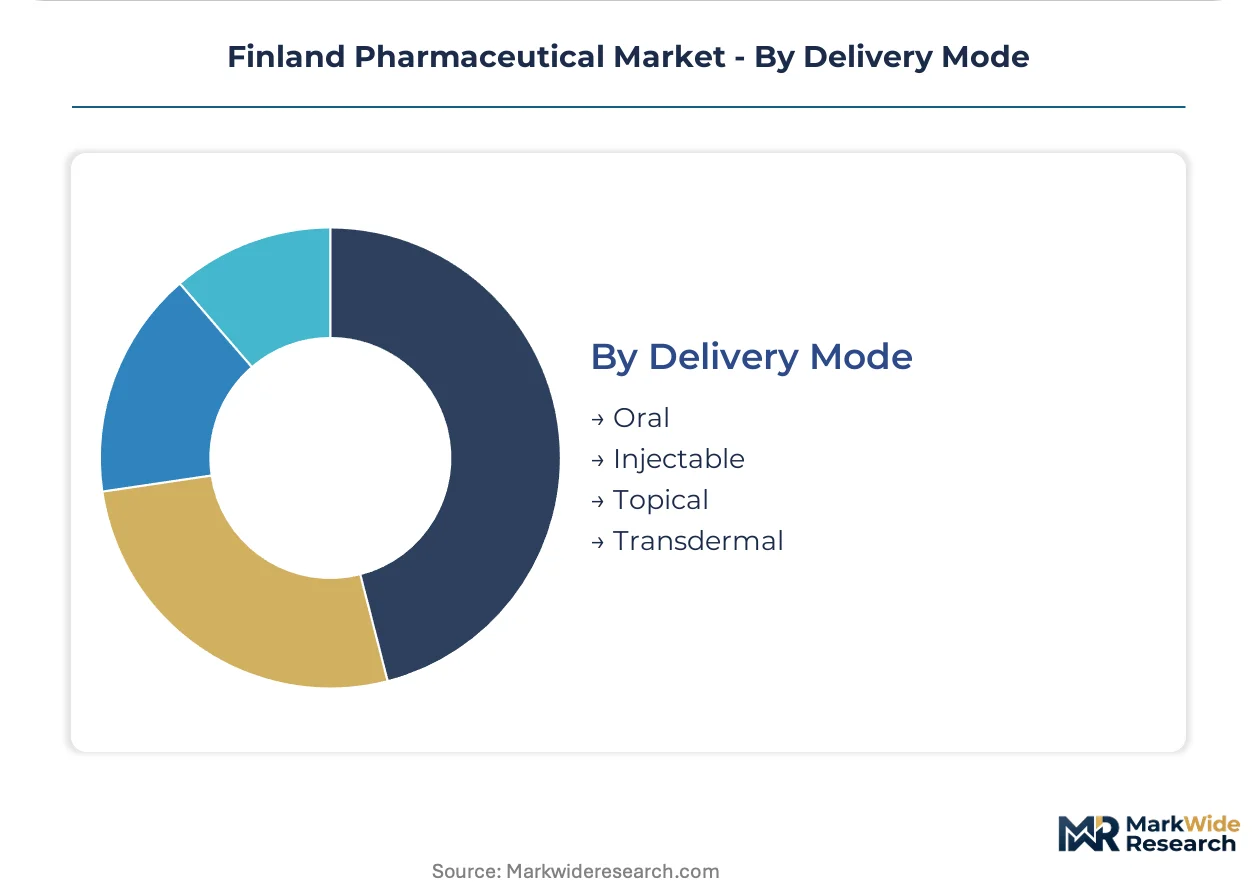
Delivery Mode:
Supply concentration in aseptic manufacturing capacity shapes commercialization timelines for sterile formats.
- Injectable:Biologics and sterile small molecules require EU GMP Annex 1 validated facilities. Orion Oyj's Espoo manufacturing campus anchors domestic fill-finish capacity.
- Oral:Solid dosage forms face intense price competition from Central European contract manufacturers.
- Topical:Dermatology and pain management formulations distribute through pharmacy retail with limited cold-chain requirements.
- Transdermal:Patch delivery systems for chronic pain and hormone replacement occupy niche positioning.
Oral delivery holds volume dominance; injectable formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across Nordic pharmaceutical markets varies sharply: Finland and Sweden show lower price sensitivity due to centralized reimbursement systems, while Denmark and Norway exhibit tighter formulary controls that compress margins faster.
Sweden
Oncology biologics and rare disease therapies drive disproportionate investment from multinational sponsors attracted by Stockholm's Karolinska Institute clinical trial infrastructure. The Dental and Pharmaceutical Benefits Agency (TLV) enforces mandatory health economic assessments that delay market access for therapies lacking cost-effectiveness documentation. Uppsala's regulatory science cluster anchors pharmacovigilance operations serving pan-Nordic safety monitoring requirements.
Norway
Specialty hospital procurement concentrates in Oslo University Hospital's centralized purchasing authority, which negotiates confidential net pricing for high-cost biologics. The Norwegian Medicines Agency (NoMA) aligns with EMA centralized procedures while maintaining national discretion on reimbursement timelines. Bergen's marine biotechnology research institutes supply novel active pharmaceutical ingredients for experimental immunotherapy platforms.
Denmark
Diabetes and obesity therapeutic demand absorbs substantial reimbursement capacity through Region H hospital formularies, reflecting elevated metabolic disease prevalence. The Danish Medicines Agency (DKMA) operates accelerated assessment pathways for therapies addressing unmet needs in oncology and neurology. Copenhagen's Medicon Valley biotech corridor hosts contract manufacturing organizations specializing in aseptic fill-finish capacity for sterile injectables.
Estonia
Cross-border parallel trade from Tallinn pharmacies into Finnish markets creates pricing arbitrage pressure on reimbursed outpatient medications. The State Agency of Medicines (SAM) maintains EU MDR-aligned device regulations that facilitate synchronized Nordic product launches. Tartu's university hospital network participates in Baltic-Nordic clinical trial consortia, expanding patient access to investigational oncology compounds.
Finland Pharmaceutical Market Competitive Landscape
Capability concentration sits with domestic manufacturers possessing integrated distribution infrastructure; scale advantage sits with multinational subsidiaries leveraging centralized R&D pipelines and pan-European procurement relationships. The market structures around three tiers: originator biologics suppliers commanding premium positioning, biosimilar competitors competing on tender pricing, and domestic formulators with localized manufacturing and regulatory familiarity. Dominant competitive moves include companion diagnostic bundling for oncology positioning and outcome-based contracting negotiations with Kela reimbursement authorities.
Among multinational pharmaceutical subsidiaries, AbbVie Inc., AstraZeneca plc, and Novartis Finland occupy positions representing the originator biologics tier, each anchoring distinct therapeutic specialization vectors within hospital formularies. Orion Oyj exemplifies the domestic integrated manufacturer archetype, combining API synthesis with finished dosage production and cold-chain distribution capabilities serving Nordic markets. MSD Finland and Roche sit within the precision medicine positioning cluster, leveraging companion diagnostic relationships and academic medical center affiliations to differentiate beyond pure pharmaceutical supply.
| Leading Market Players |
|---|
| AbbVie Inc. |
| AstraZeneca plc |
| Bayer AG |
| C.H. Boehringer Sohn AG & Ko. KG |
| GlaxoSmithKline plc |
| Orion Oyj |
| Novartis Finland |
| MSD Finland |
| Roche |
| Others |
Supply & Pricing Matrix
Helsinki-Vantaa logistics corridor freight dynamics compress margin structures for temperature-sensitive biologics while amplifying price spreads between domestic cold-chain specialists and cross-border distributors serving hospital procurement committees.
Pricing Analysis
After-sales service revenue from cold-chain maintenance contracts and patient support programs drives lifetime value capture for biologics manufacturers competing in Kela-reimbursed formularies. Three-tier pricing structure across premium originator biologics, mid-tier biosimilars, and economy generic small molecules reflects differentiation by clinical evidence depth and companion diagnostic bundling. Pricing pressure stems from competitive tendering for hospital formulary placement, particularly in oncology and rheumatology categories. Hospital procurement committees exhibit highest price sensitivity, while specialty clinics dependent on academic medical center affiliations prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Upstream active pharmaceutical ingredient feedstock for complex biologics draws from concentrated manufacturing basins in India, China, and South Korea, exposing Finnish formulators to single-source vulnerability for recombinant protein starting materials. Critical dependencies include sterile filtration media, cold-chain packaging components, and aseptic fill-finish equipment validated to EU GMP Annex 1 standards. Tariff exposure on imported starting materials compounds margin pressure for domestic manufacturers lacking backward integration into API synthesis. Distribution runs through Orion Oyj's Espoo campus and Novartis Finland's Helsinki-area specialty pharmacy network, consolidating previously fragmented logistics functions under integrated supply partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finland's pharmaceutical market demands substitution defense against biosimilar entrants eroding originator biologics margins through aggressive hospital tender pricing.
For Market Incumbents: Pre-empt biosimilar displacement by deepening companion diagnostic bundling in oncology and neurology portfolios, locking in academic medical center formulary preference through outcome-based contracting with Kela. Secure cold-chain distribution capacity through multi-year agreements with Helsinki-region logistics providers before competitor consolidation tightens access. Vertical integration into patient adherence monitoring technology creates switching costs that pure pharmaceutical suppliers cannot replicate. For New Entrants and Emerging Players: Build out regulatory affairs capabilities combining Fimea national procedure expertise with EMA centralized pathway navigation, addressing acute talent scarcity that delays market access for unprepared sponsors. Target Pirkanmaa Hospital District's procurement consolidation initiative as the most penetrable entry point, where biosimilar tender participation rules remain less entrenched than in Helsinki academic centers. Position through real-world evidence generation partnerships with Tampere University Hospital's clinical trial infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting mature small-molecule portfolios facing Kela reimbursement compression. Long-term viability centers on platforms demonstrating sustainable differentiation through biomarker-driven patient selection or rare disease orphan status insulating against tender pressure. Monitor Helsinki biotech incubator graduation rates as inflection signal for pre-revenue acquisition opportunities with validated regulatory familiarity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Integration with Helsinki University Hospital biomarker testing platforms differentiates oncology positioning against pure pharmaceutical competitors. |
| Outcome-Based Contracting | Kela reimbursement protocol evolution rewards manufacturers assuming performance risk through indication-specific agreements. |
| Cold-Chain Infrastructure Expansion | Domestic distribution capacity investments reduce reliance on cross-border logistics vulnerable to temperature excursion. |
| Regulatory Affairs Talent Acquisition | Dual Fimea-EMA expertise commands premium compensation in constrained labor pools, delaying unprepared entrants. |
| Real-World Evidence Platform Development | Electronic health record integration with Tampere University Hospital supports label expansion and reimbursement negotiations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through EMA centralized procedure filings, ClinicalTrials.gov protocol registrations, Finnish Medicines Agency adverse event databases, and Kela annual reimbursement list revisions. Bottom-up patient volume modeling by therapy area and dosage form triangulated against top-down pharmaceutical expenditure flows reported through national health accounts.
Forecast inputs considered treatment line stratification, administration route differentiation, regional regulatory cluster alignment, and patient population segmentation across the projection horizon. CAGRs were derived from compound growth trajectory analysis applied to base-year expenditure estimates, with oncology biologics expansion rates calibrated against academic medical center clinical trial participation trends and neurology pipeline advancement milestones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar specialists or outcome-based contracting pioneers would shift outcomes beyond modeled ranges. Cross-checking against THL national pharmaceutical expenditure benchmarks and EMA approval timeline databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market