
 Tapentadol Market | 2026-2036
Tapentadol Market Size, Share, and Industry Trends Forecast 2026-2036
Tapentadol Market Analysis
The FDA's Risk Evaluation and Mitigation Strategy is pivoting how manufacturers design abuse-deterrent formulations and physician training programs. Grünenthal GmbH leverages its European heritage in pain management to sustain research intensity around novel delivery mechanisms. Johnson & Johnson Services Inc. anchors its position through hospital-centric distribution networks that control institutional procurement channels. Teva Pharmaceutical Industries Ltd. competes on manufacturing scale, extending its generic infrastructure to capture cost-sensitive segments across multiple geographies.
Tapentadol is a centrally acting analgesic with dual mechanism of action, combining mu-opioid receptor agonism with norepinephrine reuptake inhibition in a single molecular structure, typically formulated as hydrochloride salt with defined purity specifications for pharmaceutical-grade production. Its primary purpose is to treat moderate to severe acute and chronic pain while offering a reduced gastrointestinal side-effect profile compared to conventional opioids. Extended-release formulations command the dominant share of product-type revenue due to patient compliance advantages and reimbursement alignment for chronic conditions, while immediate-release variants serve acute pain episodes in surgical settings. Within therapy areas, neuropathic pain applications represent the fastest-expanding segment as clinicians seek alternatives to gabapentinoids with better tolerability profiles.
The US FDA, the European Medicines Agency, and national health technology assessment bodies in Germany and France collectively shape market access through opioid-specific risk management frameworks and pricing negotiations that favor clinically differentiated products. These regulatory layers elevate barriers for new entrants without established pharmacovigilance infrastructure or demonstrated real-world evidence portfolios. Stakeholders must monitor evolving abuse-deterrent labeling standards and parallel import dynamics across European markets to anticipate margin compression or geographic arbitrage opportunities.
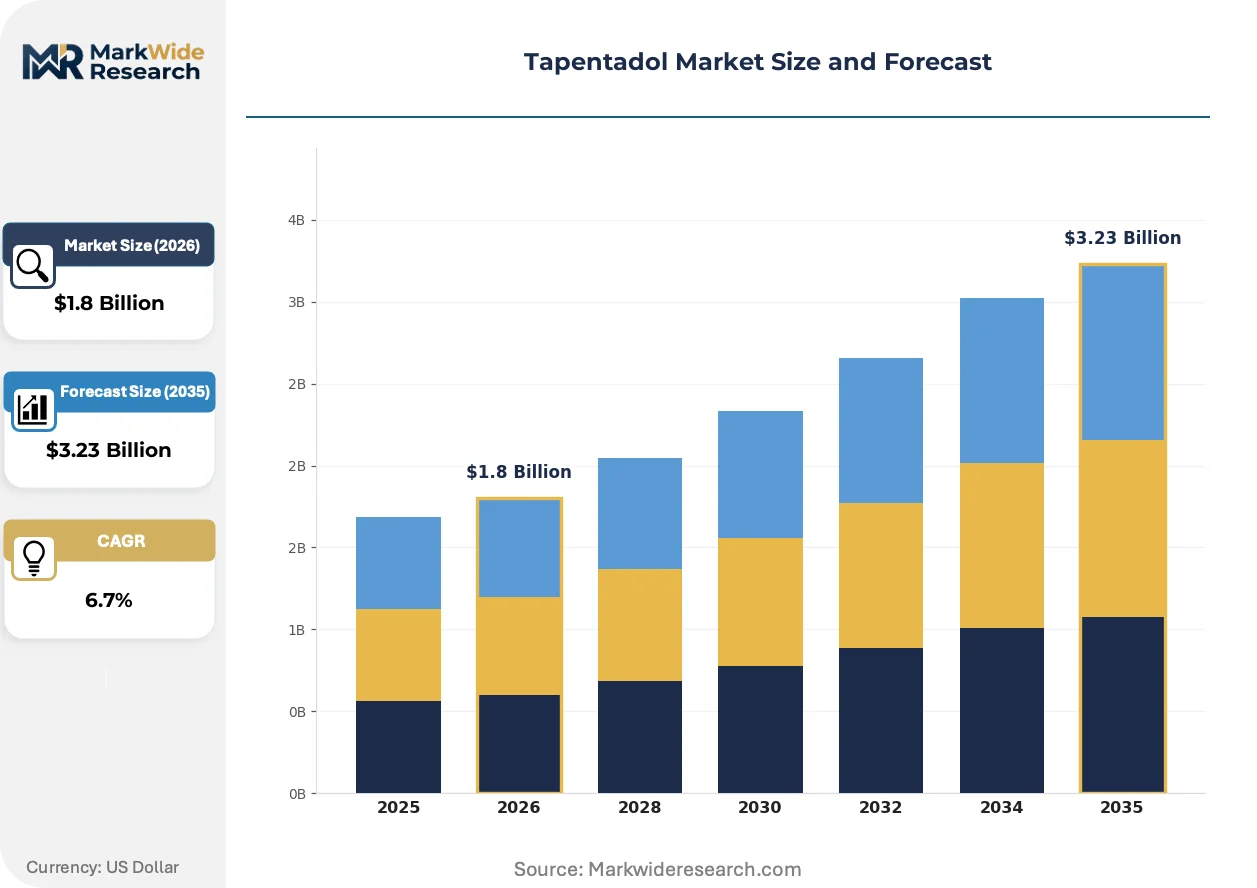
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy is forcing reformulation investments across the tapentadol landscape, as manufacturers redesign extended-release tablets with abuse-deterrent properties to retain hospital formulary placement amid tightening institutional protocols.
Growth Catalysts
- Neuropathic pain protocols:Pain clinics are expanding tapentadol prescribing for diabetic peripheral neuropathy as clinicians seek alternatives to gabapentinoids with superior gastrointestinal tolerability profiles.
- REACH compliance frameworks:European manufacturers gaining EMA-approved risk management plans are securing preferential reimbursement in Germany and France through health technology assessment pathways.
- Hospital consolidation:Integrated delivery networks in the United States are standardizing extended-release tapentadol on formulary to reduce opioid-related adverse event rates across surgical and chronic pain service lines.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India, creating vulnerability to export license delays and quality enforcement actions by CDSCO.
- Abuse-deterrent development costs:Polymer matrix and gel-forming technologies required for REMS-compliant formulations demand capital intensity that excludes mid-scale generic entrants.
- Buprenorphine substitution:Partial agonist alternatives with established abuse-deterrent platforms are capturing chronic pain volume in United States Veterans Health Administration facilities.
Strategic Opportunities
- Pediatric extension pathways:FDA priority review vouchers for pediatric pain indications offer regulatory acceleration for sponsors conducting trials in post-surgical adolescent populations.
- Japan's aging demographic:PMDA's streamlined approval for neuropathic pain in elderly patients is opening volume expansion as METI promotes chronic pain management in long-term care facilities.
- Digital therapeutics bundling:Prescription digital companions for pain self-management are creating channel innovation through pharmacy benefit manager formulary integration.
Industry Challenges
- Pharmacovigilance infrastructure:Sponsors must maintain REMS-compliant physician certification databases and adverse event reporting systems that strain regulatory affairs staffing.
- Cross-jurisdictional labeling:Divergent abuse-deterrent evidentiary standards between FDA and EMA are forcing dual development tracks that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapentadol Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extended Release, Immediate Release, Combination Therapy, Oral Solution Therapy Area: Chronic Pain, Neuropathic Pain, Postoperative Pain, Cancer Pain End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Specialty Clinics Delivery Mode: Oral, Intravenous, Transdermal, Inhalation |
| Companies Covered | Johnson & Johnson Services Inc., Grünenthal GmbH, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Lupin Limited, Cipla Ltd., Zydus Lifesciences Ltd., Aurobindo Pharma Ltd., Torrent Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapentadol Market Emerging Trajectories
Formulation science and regulatory science are converging to redefine competitive advantage in tapentadol, with manufacturers racing to align product attributes with evolving abuse-deterrent labeling standards while payers tighten prior authorization criteria.
Multilayered extended-release matrix technologies are consolidating manufacturing scale around platforms that combine immediate-release tapentadol cores with erosion-resistant outer barriers. Hospital systems adopting these formulations are reducing breakthrough-dose rescue medication orders by standardizing on single-entity products. The technology is consolidating procurement decisions within pharmacy and therapeutics committees that previously split volume across multiple opioid SKUs.
The FDA's updated guidance on in vitro alcohol extraction studies is mandating additional formulation robustness testing for all new opioid submissions. Manufacturers with existing extended-release platforms are conducting retrospective studies to defend current labeling against potential class-wide restrictions. United States sponsors with approved REMS programs are most affected, as FDA reviewers are demanding real-world abuse surveillance data as a condition of label maintenance.
Integrated delivery networks are centralizing pain medication decisions through specialty pharmacy carve-outs that bypass traditional retail channels. Hospital-owned specialty pharmacies are capturing chronic pain prescriptions through 90-day dispensing protocols that displace community pharmacy volume. This concentration is most visible in United States Medicare Advantage populations where payers are directing members to narrow network arrangements with demonstrated adherence monitoring capabilities.
Tapentadol Market Segmentation
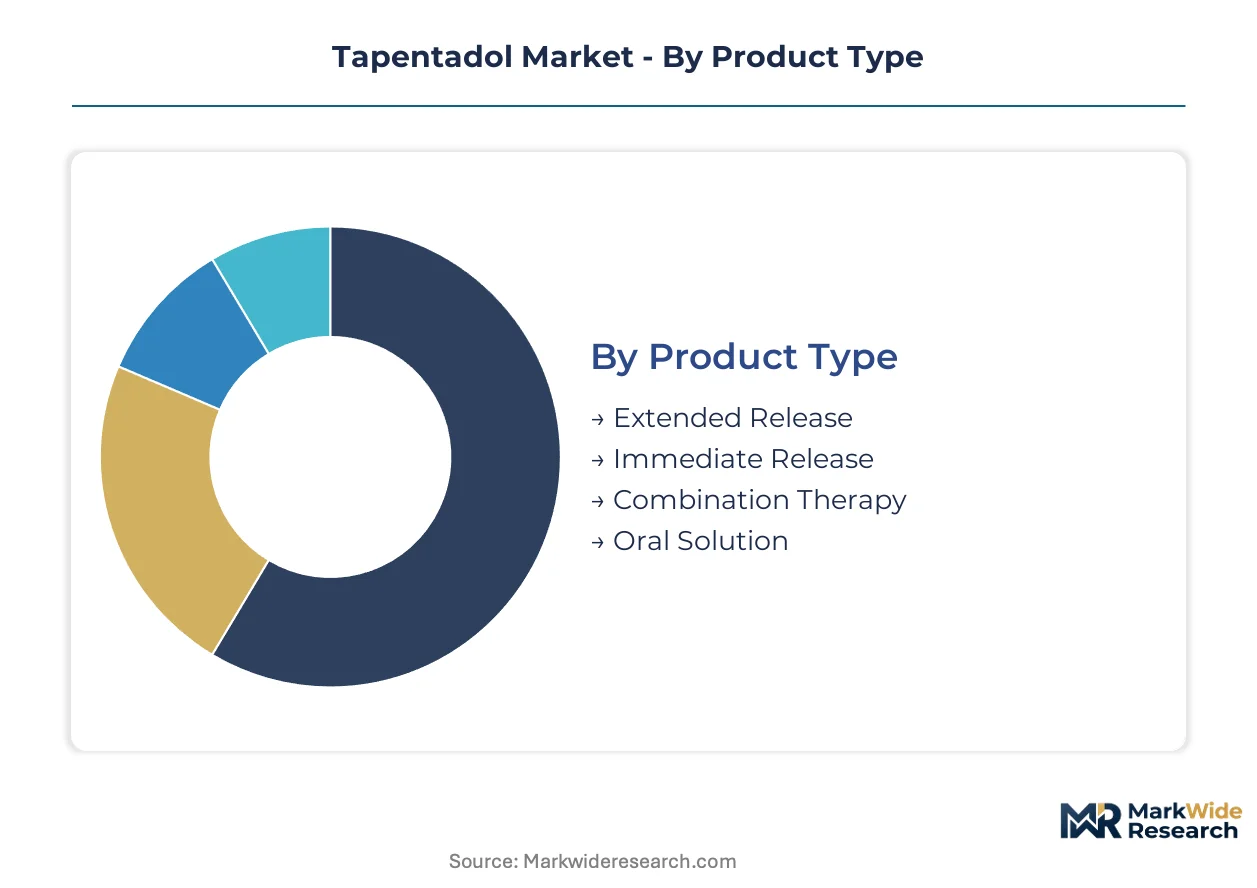
Tapentadol's dual mechanism creates distinct formulation requirements across acute and chronic pain pathways. Segmentation reveals how hospital procurement priorities diverge from retail pharmacy demand, with reimbursement protocols favoring extended-release platforms for maintenance therapy.
Product Type:
Extended-release formulations command premium positioning through compliance advantages, while immediate-release variants compete on per-dose cost in surgical settings.
- Extended Release:Matrix-based tablets with defined dissolution profiles deliver sustained plasma concentrations over 12-hour intervals. Hospital formularies in the United States prioritize these formulations for chronic pain service lines seeking to reduce breakthrough medication incidents and associated adverse event documentation.
- Immediate Release:Rapid-onset tablets with faster absorption kinetics serve acute pain episodes in perioperative protocols. Ambulatory surgical centers in Germany specify these for same-day discharge cases where duration of action must align with observation windows.
- Combination Therapy:Co-formulated products pairing tapentadol with adjunct analgesics for multimodal pain protocols.
- Oral Solution:Liquid formulations enabling dose titration in patients with swallowing difficulties or nasogastric tube requirements.
Today's leader: Extended Release. Tomorrow's challenger: Combination Therapy.
Therapy Area:
Neuropathic pain applications are climbing the fastest as clinicians seek alternatives to gabapentinoids with superior tolerability profiles.
- Neuropathic Pain:Diabetic peripheral neuropathy and post-herpetic neuralgia represent the steepest expansion trajectory. Pain clinics in France are expanding tapentadol prescribing as ANSM guidelines emphasize norepinephrine reuptake mechanisms for neuropathic mechanisms.
- Chronic Pain:Long-term management of non-cancer pain dominates prescription volume. Veterans Health Administration facilities in the United States are standardizing extended-release tapentadol for chronic musculoskeletal conditions amid opioid stewardship mandates.
- Postoperative Pain:Acute surgical recovery protocols favoring reduced opioid burden compared to traditional mu-agonists.
- Cancer Pain:Palliative care applications where dual mechanism addresses mixed nociceptive-neuropathic pain states.
Neuropathic Pain is capturing specialist attention fastest; Chronic Pain retains the volume base.
End User:
Hospital procurement consolidation is shifting volume toward integrated delivery networks with centralized pharmacy and therapeutics authority.
- Hospitals:Inpatient and outpatient departments with formulary control over opioid selection. IDNs in the United States are capturing 90-day dispensing through captive specialty pharmacies, displacing community pharmacy volume for chronic pain maintenance.
- Specialty Clinics:Dedicated pain management centers with prescriber certification under REMS protocols. These clinics in Japan are expanding tapentadol utilization as METI promotes chronic pain infrastructure in long-term care facilities.
- Ambulatory Surgical Centers:Same-day procedure settings with focused acute pain protocols.
- Home Care Settings:Long-term care and hospice environments with nursing-administered medication programs.
Hospitals control the procurement lever; Specialty Clinics are gaining prescriber influence.
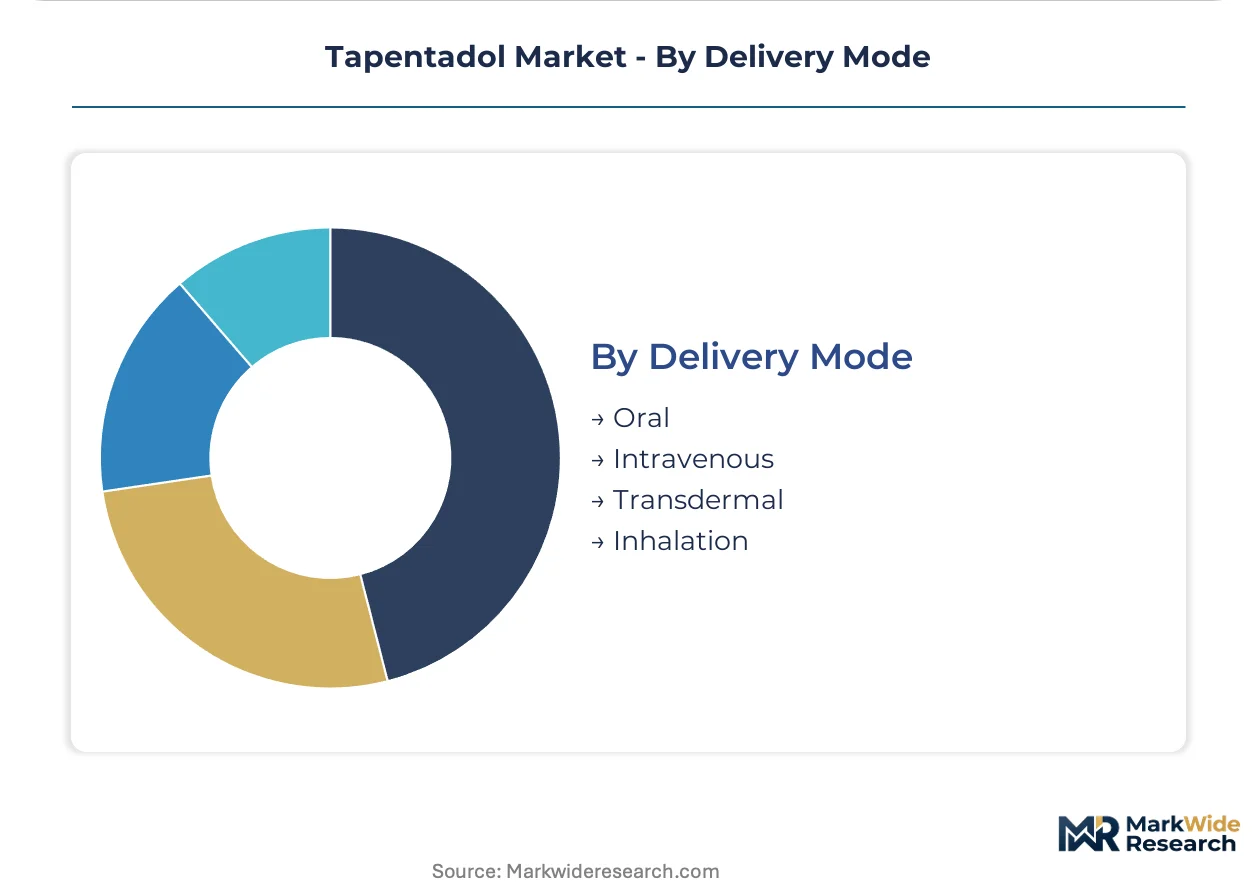
Delivery Mode:
Oral administration dominates through patient acceptance and manufacturing scale, while alternative routes serve specific clinical constraints.
- Oral:Tablets and solutions with established bioavailability profiles and patient self-administration capability. German hospital procurement frameworks prioritize oral extended-release formulations for discharge planning and adherence monitoring.
- Intravenous:Perioperative and emergency department applications where rapid titration is required. Surgical centers in the United States specify IV tapentadol for patients with contraindications to traditional IV opioids.
- Transdermal:Patch-based delivery systems under development for steady-state maintenance with reduced peak-trough variability.
- Inhalation:Investigational dry powder formulations targeting rapid onset for breakthrough pain episodes.
Oral delivery holds the installed base; Intravenous captures acute care premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pain management specialists cluster in urban medical centers across five countries where hospital procurement consolidation and regulatory frameworks for controlled substances create distinct market conditions.
United States
Integrated delivery networks in Texas and Florida are standardizing extended-release tapentadol through captive specialty pharmacies that displace retail volume. The FDA's Risk Evaluation and Mitigation Strategy mandates physician certification databases that elevate compliance costs for new entrants. Philadelphia's hospital corridor anchors institutional procurement decisions for the Mid-Atlantic region.
Germany
Health technology assessment bodies in Berlin and Munich prioritize EMA-approved risk management plans for reimbursement eligibility in chronic pain protocols. The country's statutory health insurance funds negotiate pricing through the G-BA assessment framework. Baden-Württemberg's pharmaceutical manufacturing belt supplies active pharmaceutical ingredients to formulation facilities across Europe.
Japan
Pain clinics in Tokyo and Osaka are expanding tapentadol utilization as METI promotes chronic pain infrastructure in long-term care facilities serving the aging population. PMDA's streamlined approval pathways for neuropathic pain indications accelerate market access for sponsors with pediatric extension data. Nagoya's medical device corridor supports combination therapy development with digital therapeutics.
India
Active pharmaceutical ingredient production concentrates in Hyderabad and Ahmedabad, creating supply vulnerability to CDSCO export license enforcement actions. Domestic manufacturers are extending formulation capabilities to capture cost-sensitive segments across Southeast Asian markets. Maharashtra's pharmaceutical cluster houses multiple finished-dose facilities serving regulated and emerging markets.
France
ANSM guidelines emphasizing norepinephrine reuptake mechanisms are expanding tapentadol prescribing in Paris and Lyon pain clinics for diabetic peripheral neuropathy. The country's health technology assessment body evaluates abuse-deterrent properties in pricing negotiations. Île-de-France's hospital networks centralize procurement through regional pharmacy and therapeutics committees.
Tapentadol Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established hospital distribution networks. Market access depends on REMS-compliant infrastructure and real-world evidence portfolios that justify formulary placement against partial agonist alternatives. Three archetypes dominate: originator companies with abuse-deterrent patent estates, generic manufacturers with API-to-finished-dose integration, and hospital-centric distributors controlling institutional procurement channels. Capacity expansion in extended-release matrix technologies and strategic partnerships with specialty pharmacy networks represent the dominant competitive moves.
Among diversified healthcare conglomerates, Johnson & Johnson Services Inc. occupies a position exemplifying hospital-centric distribution control, while Grünenthal GmbH represents European heritage in pain management research. Teva Pharmaceutical Industries Ltd. anchors the generic-scale archetype with manufacturing infrastructure spanning multiple geographies. These three entities collectively illustrate how regulatory compliance capabilities and procurement channel access determine competitive positioning in controlled-substance markets.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Grünenthal GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Lupin Limited |
| Cipla Ltd. |
| Zydus Lifesciences Ltd. |
| Aurobindo Pharma Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Others |
Supply Flow & Price Mechanics
EMA-approved risk management plans gate qualified supply access and premium-tier pricing eligibility across European markets, with hospital formulary placement contingent on demonstrated pharmacovigilance infrastructure that smaller manufacturers cannot replicate.
Pricing Analysis
Bundled REMS compliance services separate premium-tier suppliers from unbundled transactional competitors. Three-tier pricing structure across REMS-integrated, standard-formulary, and economy-generic levels reflects certification depth and physician training investment. Pricing pressure stems from buprenorphine partial agonist substitution in Veterans Health Administration facilities. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with captive specialty pharmacies demonstrate lowest sensitivity due to adherence-monitoring value capture.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients is reshaping sourcing patterns for domestic-content compliance. API production clusters in Hyderabad and Ahmedabad feed formulation facilities in Germany and the United States, with hydrochloride salt precursor supply anchored in Maharashtra's chemical corridor. Single-source vulnerability concentrates in CDSCO export license dependencies. Distribution runs through hospital-owned specialty pharmacies capturing chronic pain volume from retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in abuse-deterrent formulation premiums and API-to-finished-dose integration savings.
For Market Incumbents: Acquire pediatric trial data packages to secure FDA priority review vouchers before competitors complete adolescent post-surgical studies. Defend hospital formulary position by embedding real-world abuse surveillance databases that satisfy REMS maintenance requirements. Capacity expansion in extended-release matrix technologies at existing European manufacturing sites preserves EMA risk management plan alignment. For New Entrants and Emerging Players: Underserved pain clinics in Japan's long-term care facilities present white-space access as METI infrastructure investments outpace prescriber certification capacity. Target neuropathic pain protocols in French and German outpatient settings where gabapentinoid tolerability concerns drive therapeutic switching. Go-to-market through digital therapeutics bundling partnerships with pharmacy benefit managers seeking adherence monitoring differentiation. For Investors and Strategic Acquirers: Roll-up economics work for API-to-formulation integrated manufacturers because REMS compliance infrastructure creates scale advantages that fragment the generic tier. Five-to-ten year viability hinges on abuse-deterrent patent estate longevity and real-world evidence portfolio depth. Watch FDA guidance updates on in vitro alcohol extraction studies as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | Physician certification databases satisfy FDA maintenance requirements for extended-release labeling. |
| Pediatric Trial Advancement | Priority review vouchers accelerate market access for adolescent post-surgical pain indications. |
| API Backward Integration | In-house hydrochloride salt production reduces CDSCO export license exposure for Indian manufacturers. |
| Specialty Pharmacy Partnership | Hospital-owned dispensing channels capture 90-day chronic pain volume from retail pharmacies. |
| Abuse-Deterrent Reformulation | Polymer matrix technologies defend formulary placement against buprenorphine substitution trends. |
Methodological Framework
Direct dialogue with regulatory affairs leads, hospital procurement managers, formulary directors, and pain clinic prescribers grounded qualitative assessment in operational constraints. Secondary validation drew from FDA REMS program filings, EMA risk management plan submissions, ClinicalTrials.gov protocol registries, and hospital GPO contract databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across the analysis window.
Segment-level projections incorporated formulation type, therapy area mechanism, end-user procurement channel, and regional regulatory cluster as structural dimensions. CAGRs derived from weighted average of historical volume trends and policy-driven adoption curve assumptions. Forecast inputs included REMS enrollment trajectories, health technology assessment body pricing negotiations, and specialty pharmacy carve-out penetration rates.
Underlying measurement precision varies by segment; extended-release hospital procurement carries tighter precision than emerging transdermal development programs. Forecasts reflect documented assumptions on regulatory timeline stability and reimbursement policy continuity. Abuse-deterrent labeling standard revisions or CDSCO enforcement intensity shifts could materially revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Palonosetron Hydrochloride Market