
 Drug Designing Tools Market | 2026-2036
Drug Designing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Designing Tools Market Analysis
Structure-based design precision is unwinding legacy computational chemistry workflows across major pharmaceutical R&D budgets. Schrödinger, Inc. leverages proprietary physics-based simulation engines to anchor high-value partnerships with top-ten drug developers. IQVIA sustains dominance in real-world evidence integration, while Insilico Medicine competes through generative AI platforms that automate target identification pipelines.
Drug designing tools encompass software, platforms, and services that apply molecular modeling, computational chemistry, and fragment-based design algorithms to predict protein-ligand interactions and optimize lead compound affinity. These systems process crystallographic data, pharmacophore maps, and quantum mechanical parameters to reduce wet-laboratory iteration cycles in preclinical development. Software segments currently capture the largest revenue share due to recurring license models, though services are expanding fastest as biotechnology firms outsource specialized computational expertise. Structure-based design technology leads in commercial deployment maturity, while fragment-based design is displacing traditional high-throughput screening in early-stage target validation.
The FDA evaluates computational chemistry submissions through its emerging technology program, tightening validation standards for in-silico toxicity predictions. EMA's qualification opinion pathway for drug modeling and simulation tools shapes European vendor market access requirements. WHO prequalification guidelines for AI-assisted drug discovery are forcing platform developers to document algorithmic transparency and training data provenance. Stakeholders must monitor evolving regulator expectations around explainable AI before committing to multi-year enterprise licensing agreements.
Market Dynamics
Physics-based molecular simulation engines are compressing preclinical validation timelines, forcing pharmaceutical R&D budgets to reallocate from wet-laboratory screening toward computational chemistry infrastructure.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's emerging technology program for computational submissions reduces regulatory review cycles for in-silico toxicity predictions, pulling adoption forward among mid-cap biotechnology developers.
- Generative AI Platforms:Automated target identification pipelines trained on crystallographic databases compress lead optimization from months to weeks, displacing manual pharmacophore mapping in early-stage programs.
- Boston and San Francisco Biotech Clusters:Concentrated contract research organization spending on structure-based design software creates demand density that subsidizes platform development costs for specialized vendors.
Market Restraints
- Algorithmic Transparency Requirements:WHO prequalification guidelines for AI-assisted drug discovery mandate documented training data provenance, extending platform qualification timelines by 12-18 months for non-compliant systems.
- Specialized Talent Scarcity:The intersection of quantum chemistry and machine learning expertise concentrates among fewer than two hundred practitioners globally, inflating compensation costs for computational biology teams.
- Legacy Wet-Laboratory Infrastructure:Sunk capital in high-throughput screening facilities creates organizational resistance to fragment-based design adoption within established pharmaceutical R&D divisions.
Strategic Opportunities
- EMA Qualification Opinion Pathway:European Medicines Agency drug modeling and simulation tool standards create first-mover advantage for vendors achieving formal qualification before competitor entry.
- Fragment-Based Design Convergence:Integration of cryo-electron microscopy data with machine learning scoring functions opens white space in membrane protein target classes previously resistant to structure-based approaches.
- India CDMO Outsourcing:Contract development and manufacturing organizations in Hyderabad and Bangalore are building captive computational chemistry capabilities, creating services demand for platform licensing and training.
Industry Challenges
- Cross-Functional Integration Complexity:Computational chemistry platforms must interface with legacy electronic laboratory notebook systems and compound management databases, requiring expensive custom middleware development.
- Explainable AI Documentation Burden:Regulatory submissions now require interpretable model outputs for toxicity predictions, forcing vendors to abandon black-box neural architectures in favor of mechanistically transparent algorithms with reduced predictive accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Designing Tools Market |
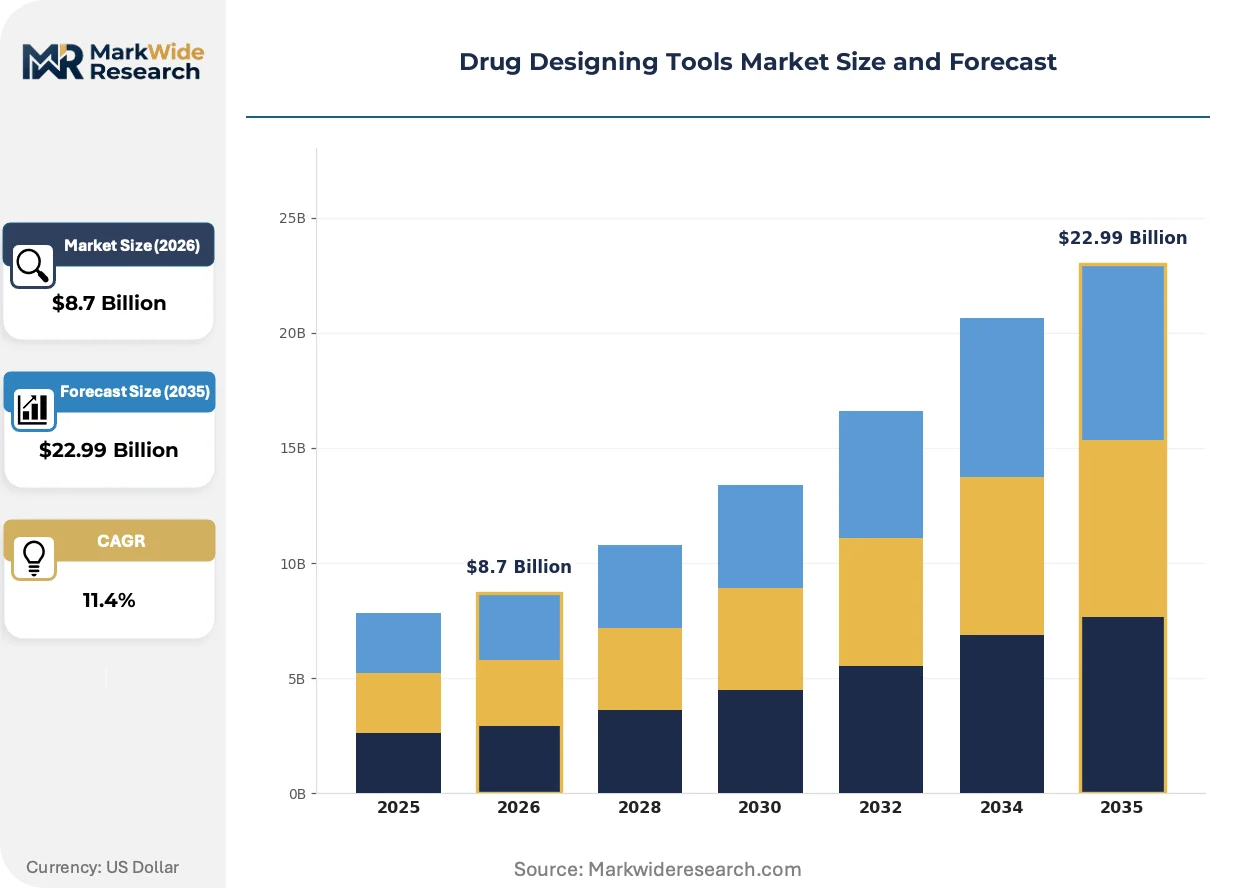
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platforms, Services, Databases Technology: Molecular Modeling, Structure-Based Design, Fragment-Based Design, Computational Chemistry End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research, Contract Research Organizations Application: Lead Discovery, Preclinical Development, Target Identification, Drug Repurposing |
| Companies Covered | Deep Intelligent Pharma, IQVIA, Schrödinger, Inc., Atomistic Insights, Cadence Design Systems, OpenEye Scientific Software, Evogene Ltd., BioSymetrics, Insilico Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Designing Tools Market Emerging Trajectories
Generative chemistry models and real-world evidence integration are rewiring how pharmaceutical developers prioritize molecular candidates, shifting investment from late-stage optimization toward target selection accuracy.
AlphaFold-derived protein structure predictions are fragmenting the competitive landscape for structure-based design platforms. Contract research organizations now access atomic-resolution models for previously intractable targets without proprietary crystallography infrastructure. This capability diffusion compresses the value capture window for specialized structural biology service providers.
The EU AI Act's risk classification system for medical device software is tightening validation standards for predictive toxicity models. EMA qualification opinions now require algorithmic change control protocols that document model drift and retraining triggers. European biotechnology firms are responding by consolidating vendor relationships around platforms with pre-established regulatory documentation packages.
Biotechnology procurement teams are unbundling software licenses from mandatory implementation services, favoring modular subscription tiers over enterprise-wide perpetual agreements. Mid-cap drug developers in Cambridge and South San Francisco are piloting usage-based pricing tied to molecules advanced to IND-enabling studies. This consumption model shift pressures incumbent vendors to restructure recurring revenue architectures.
Drug Designing Tools Market Segmentation
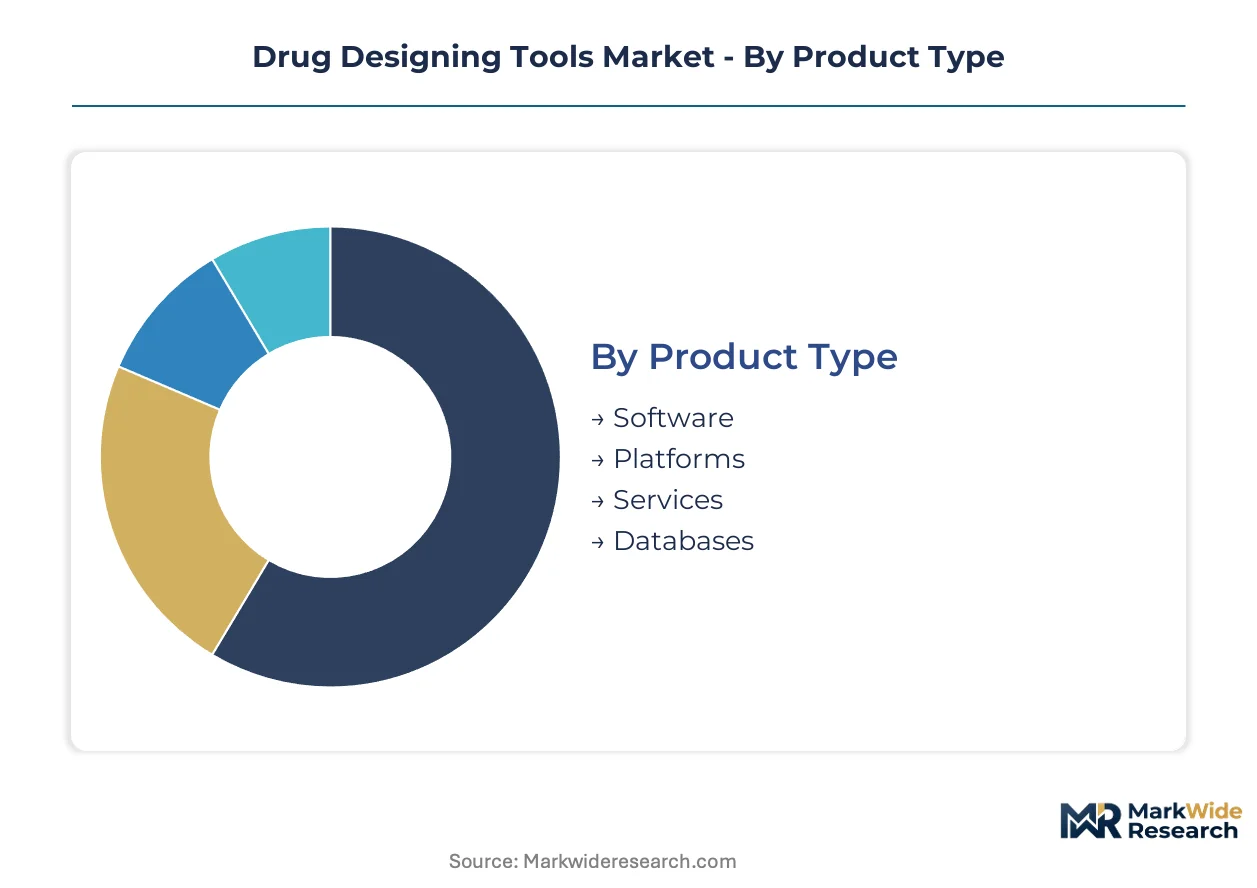
Segmentation in drug designing tools reveals how value migrates between software licensing and specialized services. Procurement patterns differ sharply between large pharmaceutical R&D budgets and mid-cap biotechnology outsourcing strategies.
Product Type:
Margin pools concentrate in recurring software licenses, though services are capturing expanding share through outsourced computational expertise.
- Software:Physics-based simulation engines and molecular visualization suites command premium pricing through perpetual and subscription licensing models. Pharmaceutical R&D budgets in the United States allocate heavily to structure-based design modules. Recurring revenue stability attracts vendor investment in algorithm refinement.
- Services:Contract computational chemistry teams provide fragment-based design and lead optimization on project-based engagement. Biotechnology firms in Boston and San Francisco clusters outsource specialized expertise rather than building captive capabilities. Talent scarcity at the quantum chemistry-machine learning intersection sustains pricing power.
- Platforms:Integrated end-to-end systems combining modeling, data management, and regulatory documentation tools.
- Databases:Crystallographic repositories, pharmacophore libraries, and curated toxicity datasets supporting in-silico screening workflows.
Software holds installed capacity. Services is rotating up the share rankings.
Technology:
Application intensity varies by therapeutic target class, with membrane proteins and intrinsically disordered regions demanding differentiated computational approaches.
- Structure-Based Design:Protein-ligand docking algorithms and binding affinity prediction models anchor commercial deployment maturity. Cryo-electron microscopy data integration is expanding addressable target space. FDA emerging technology program submissions increasingly feature structure-based toxicity predictions.
- Fragment-Based Design:Low molecular weight compound libraries and enthalpic optimization protocols displace high-throughput screening in early-stage validation. European Medicines Agency qualification opinion pathways favor fragment-based approaches for documented mechanistic transparency.
- Molecular Modeling:Quantum mechanical calculations and molecular dynamics simulations for conformational analysis and reaction pathway prediction.
- Computational Chemistry:Cheminformatics toolkits, QSAR modeling, and ADMET property prediction for lead compound prioritization.
Structure-based design dominates current procurement volumes. Fragment-based design is climbing the fastest among emerging technology categories.
End User:
Customer scale determines platform configuration, with enterprise licensing contrasting against modular, usage-based procurement.
- Pharmaceutical Companies:Top-ten drug developers deploy enterprise-wide computational chemistry infrastructure across therapeutic areas. Internal platform development competes against vendor licensing for physics engine customization. Schrödinger partnerships exemplify high-value, multi-year strategic relationships.
- Biotechnology Firms:Mid-cap developers in Cambridge and South San Francisco pilot consumption-based pricing tied to IND-enabling milestones. Modular subscription tiers replace mandatory implementation bundles. IQVIA real-world evidence integration addresses evidence generation requirements for accelerated approval pathways.
- Academic Research:University laboratories accessing discounted educational licenses and open-source alternatives for method development.
- Contract Research Organizations:Service providers building captive computational capabilities in Hyderabad and Bangalore for platform licensing and training delivery.
Pharmaceutical companies anchor enterprise spending. Biotechnology firms are expanding fastest in absolute terms.
Application:
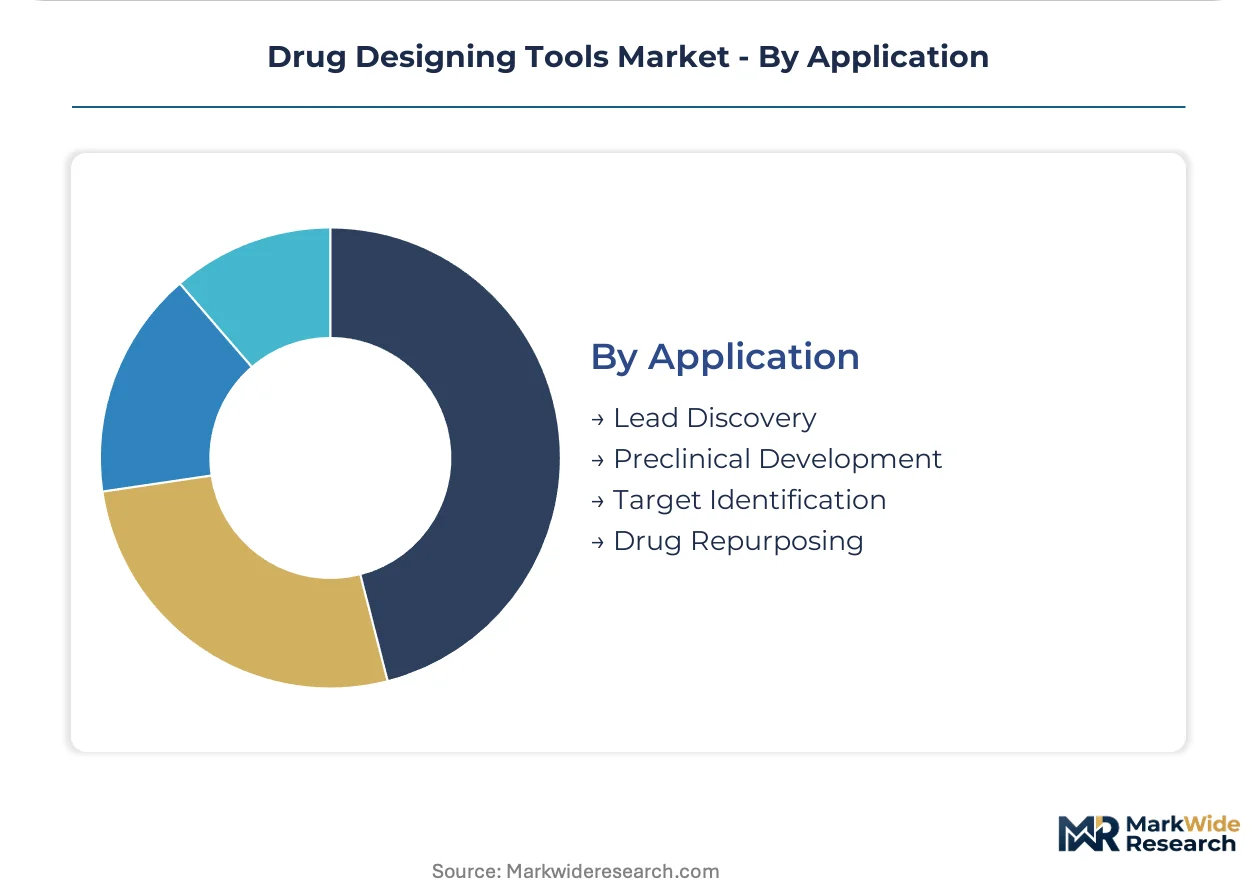
Workflow positioning determines tool selection, with upstream target selection gaining investment relative to downstream optimization.
- Lead Discovery:Virtual screening campaigns and hit-to-lead expansion protocols process millions of compounds through pharmacophore filtering. Generative AI platforms automate molecular generation, compressing timeline from months to weeks. Insilico Medicine competes through automated target identification pipeline integration.
- Preclinical Development:In-silico toxicity prediction and ADMET optimization reduce wet-laboratory iteration cycles. WHO prequalification guidelines for AI-assisted discovery mandate algorithmic transparency documentation. EMA qualification opinions require interpretable model outputs, favoring mechanistically transparent architectures.
- Target Identification:Disease mechanism elucidation and druggable genome prioritization through multi-omics integration.
- Drug Repurposing:Existing compound repositioning through network pharmacology and indication expansion modeling.
Lead discovery captures current procurement intensity. Preclinical development is gaining share fastest as regulatory validation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates where contract research organization spending density subsidizes specialized vendor economics. Computational chemistry infrastructure investment clusters around established pharmaceutical R&D hubs and emerging biotechnology manufacturing centers.
United States
FDA accelerated approval pathways for computational submissions pull adoption forward among mid-cap biotechnology developers. The emerging technology program reduces regulatory review cycles for in-silico toxicity predictions. Boston and San Francisco biotech clusters anchor contract research organization spending on structure-based design software.
Germany
EMA qualification opinion pathways for drug modeling and simulation tools create first-mover advantage for compliant vendors. Algorithmic change control protocols now document model drift and retraining triggers under EU AI Act risk classifications. Heidelberg and Munich pharmaceutical R&D centers drive enterprise licensing for integrated computational chemistry platforms.
Switzerland
Swissmedic regulatory documentation requirements favor platforms with pre-established qualification packages. Basel anchors Novartis and Roche computational infrastructure spending on physics-based simulation engines. Geneva biotechnology procurement teams pilot usage-based pricing tied to IND-enabling milestones.
India
CDSCO guidelines for AI-assisted drug discovery documentation extend platform qualification timelines for non-compliant systems. Hyderabad and Bangalore contract development and manufacturing organizations build captive computational chemistry capabilities. Platform licensing and training demand concentrates in these southern Indian biotechnology manufacturing corridors.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with FDA computational submission standards streamlines dual-market platform qualification. London and Cambridge biotechnology firms unbundle software licenses from mandatory implementation services. Modular subscription tiers replace enterprise-wide perpetual agreements among mid-cap developers.
Drug Designing Tools Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Physics-based simulation engine specialists command premium pricing through proprietary algorithmic differentiation. Generative AI platform providers compete on automated pipeline compression. Services-based computational chemistry providers capture share through outsourced expertise rather than licensed technology. Dominant competitive moves include strategic partnerships with top-ten drug developers and geographic expansion through India-based training and licensing operations.
Within the physics-based simulation tier, Schrödinger, Inc. and OpenEye Scientific Software occupy positions defined by proprietary engine architecture. IQVIA anchors the real-world evidence integration segment. Insilico Medicine exemplifies the generative AI platform archetype through automated target identification pipelines. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Deep Intelligent Pharma |
| IQVIA |
| Schrödinger, Inc. |
| Atomistic Insights |
| Cadence Design Systems |
| OpenEye Scientific Software |
| Evogene Ltd. |
| BioSymetrics |
| Insilico Medicine |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month platform qualification timelines for WHO-compliant systems compress vendor cash conversion cycles and concentrate pricing power among established documentation providers. This lead-time band forces mid-cap biotechnology developers toward modular subscription tiers rather than enterprise perpetual licenses, reshaping how computational chemistry infrastructure is procured across Boston and San Francisco clusters.
Pricing Analysis
FDA emerging technology program qualification dictates the pricing tier structure for in-silico toxicity prediction platforms. Three-tier pricing separates enterprise physics-engine licenses from modular SaaS subscriptions and project-based computational chemistry services. Price differentiation rests on algorithmic transparency documentation depth and EMA qualification opinion status. Cost compression in mid-tier subscriptions is intensifying because biotechnology procurement teams unbundle implementation services from core software licenses. Mid-cap developers in Cambridge and South San Francisco exhibit highest price sensitivity, while top-ten drug developers anchor premium tier stability.
Supply Chain Analysis
Specialized talent scarcity at the quantum chemistry-machine learning intersection creates a chokepoint that underwrites vendor pricing power and extends project delivery timelines. Platform development draws from United States, Germany, and Switzerland for physics-engine architecture, while services capacity concentrates in India through Hyderabad and Bangalore CDMO corridors. Raw material dependencies span crystallographic databases, pharmacophore libraries, and proprietary simulation algorithms. Single-source vulnerability runs through the fewer than two hundred practitioners globally who command both quantum chemistry and machine learning expertise. Distribution runs through direct enterprise licensing for pharmaceutical R&D budgets and channel partnerships for mid-cap biotechnology outsourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
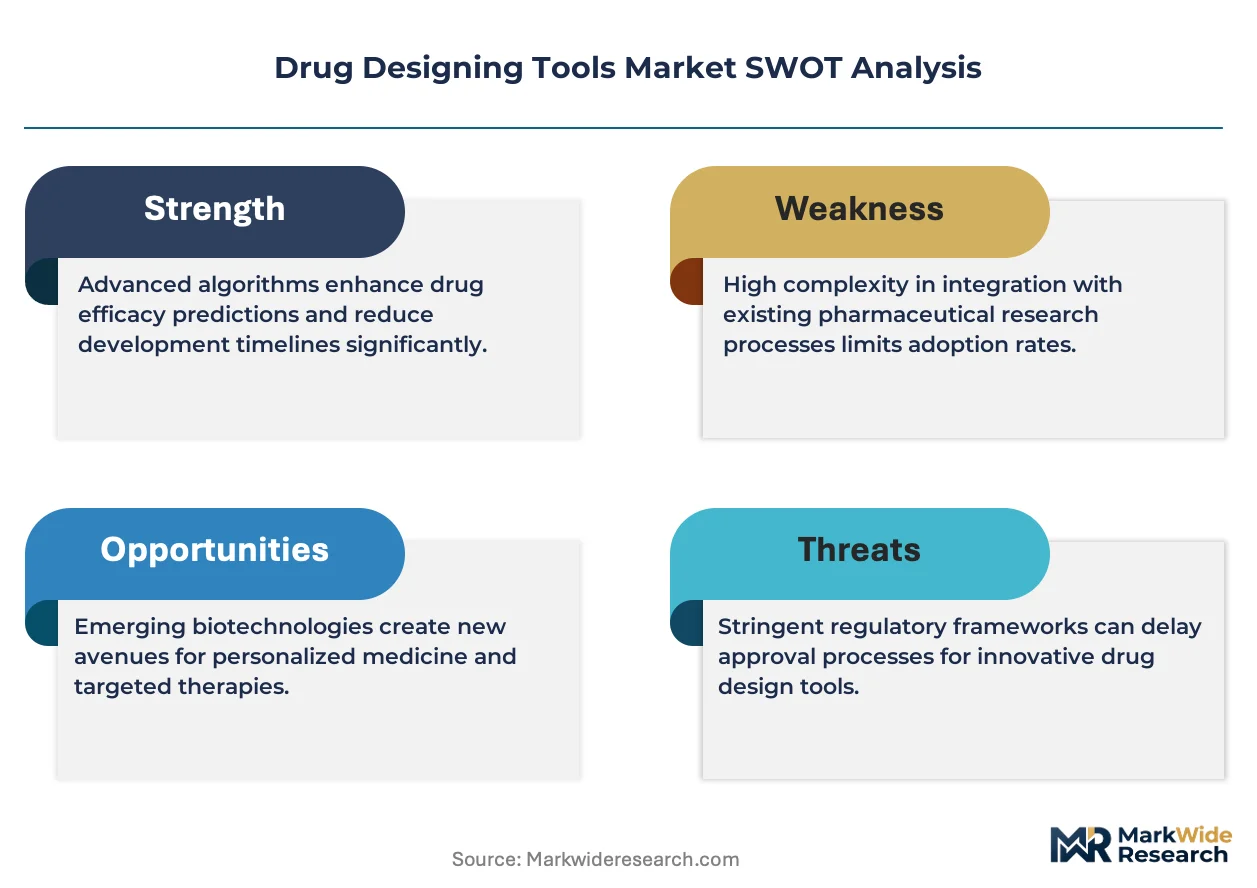
Computational drug design is crossing into platform economics as AlphaFold-derived structural predictions commoditize atomic-resolution modeling and force vendors toward interoperable, API-first architectures. This ecosystem shift rewards modular integration over monolithic enterprise suites.
For Market Incumbents: Secure EMA qualification opinion pathways before competitor entry to lock in European biotechnology procurement decisions. Deepen backward integration into proprietary crystallographic data pipelines to differentiate against open-source structure predictions. Fragment-based design convergence with cryo-electron microscopy data represents the primary substitution threat to legacy structure-based revenue streams. For New Entrants and Emerging Players: Lead with automated target identification pipelines for membrane protein classes previously resistant to structure-based approaches. India CDMO captive capability building offers the most penetrable geography for platform licensing and training services. Position through usage-based pricing tied to IND-enabling milestones rather than competing on perpetual license economics. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-documentation moat play because algorithmic transparency requirements and WHO prequalification standards are extending platform qualification timelines and consolidating vendor relationships around pre-established documentation packages. Target acquisition archetypes include specialized computational chemistry services providers with India-based delivery capacity. Watch FDA emerging technology program expansion as the signal indicating accelerated regulatory acceptance of in-silico submissions.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Opinion Pathway | First-mover certification under EU AI Act risk classifications locks in European biotechnology procurement decisions before competitor platforms achieve compliance. |
| Fragment-Based Design Platform Launch | Cryo-electron microscopy integration opens membrane protein targets previously inaccessible to structure-based approaches, expanding addressable market. |
| India CDMO Training and Licensing Expansion | Hyderabad and Bangalore captive capability building creates recurring services revenue from contract development and manufacturing organization computational chemistry outsourcing. |
| Algorithmic Transparency Documentation Investment | WHO prequalification compliance reduces platform qualification timeline risk and satisfies EMA interpretable model output requirements for toxicity predictions. |
| Usage-Based Pricing Model Introduction | Modular subscription tiers tied to IND-enabling milestones align vendor revenue with customer value realization and displace mandatory implementation bundles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA emerging technology program submissions, EMA qualification opinion documentation, and WHO prequalification guidelines for AI-assisted drug discovery. Primary interviews engaged drug development executives at top-ten pharmaceutical companies, regulatory affairs leads at mid-cap biotechnology firms, computational biology directors at Boston and San Francisco cluster organizations, and procurement managers at contract research organizations. Secondary validation drew from clinical trial databases, SEC filings of publicly traded platform vendors, and patent landscape analyses covering physics-based simulation engines and generative chemistry architectures. Bottom-up triangulation across software licensing transactions, services contract values, and platform subscription metrics was cross-checked against top-down pharmaceutical R&D budget allocation studies.
Segmentation dimensions modeled span product type, technology category, end-user scale, and application workflow positioning across the analysis window. Treatment line stratification separated lead discovery from preclinical development procurement intensity. Deployment architecture distinguished enterprise perpetual licenses from modular SaaS and project-based services. Regional regulatory clusters captured FDA, EMA, and CDSCO pathway differentiation. CAGRs were derived from trend extrapolation of licensing transaction volumes, qualified by platform qualification timeline assumptions and talent scarcity constraints on services capacity expansion.
The analysis sits within stated boundaries; outcomes outside sustained FDA emerging technology program expansion, stable EMA qualification opinion throughput, or contained talent cost inflation would require recalibration. Forecasts reflect documented assumptions around regulatory acceptance velocity and biotechnology outsourcing propensity. Practitioners should keep alternative scenarios live as WHO prequalification guideline enforcement and EU AI Act risk classification implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
India Nicotine Replacement Therapy Market