
 Middle East and Africa Laxative Market | 2026-2036
Middle East and Africa Laxative Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Laxative Market Foresight
Hospital procurement of laxatives is collapsing as homecare and retail pharmacy purchasing surges across the Middle East and Africa. Abbott Laboratories leverages its established gastrointestinal portfolio to dominate hospital formulary contracts in the Gulf Cooperation Council states. Sanofi competes through broad retail distribution, while Bayer AG anchors consumer trust with its heritage brand presence in Egyptian and Nigerian pharmacy networks.
Laxatives comprise pharmacological agents that induce bowel evacuation through osmotic water retention, neuromuscular stimulation, or stool bulk modification, with active ingredients ranging from senna glycosides to polyethylene glycol 3350. Their primary purpose spans constipation management, pre-surgical bowel preparation, and opioid-induced bowel dysfunction treatment. Osmotic laxatives lead value generation due to superior safety profiles in elderly polypharmacy patients, while tablet formulations capture the largest volume share through pharmacy shelf accessibility and patient compliance advantages. Homecare channels exhibit the fastest expansion trajectory as telehealth prescribing and direct-to-patient delivery models penetrate South African and Emirati urban markets.
Saudi Arabia's SFDA, South Africa's SAHPRA, and Egypt's national pharmaceutical regulator enforce varying OTC-to-prescription classification thresholds that directly determine product accessibility and labeling requirements across national markets. These divergent frameworks compel manufacturers to maintain multiple formulation dossiers and packaging specifications, elevating compliance costs for pan-regional suppliers. Stakeholders must monitor impending harmonization initiatives under the African Medicines Agency while calibrating country-specific registration investments against portfolio prioritization decisions.
Market Dynamics
The Middle East and Africa Laxative Market is reshaping around the migration of purchasing from institutional procurement to patient-directed retail channels, driven by telehealth expansion and self-medication authorization across Gulf health ministries.
Growth Catalysts
- SFDA Reclassification Protocols:Saudi Arabia's tightened OTC pathways for bulk-forming agents expand pharmacy shelf access while reducing prescription bottlenecks in chronic constipation management.
- Geriatric Facility Expansion:Nursing home construction across Dubai, Riyadh, and Cairo generates concentrated demand for polypharmacy-compatible osmotic formulations.
- Telehealth Prescribing:South Africa's direct-to-patient delivery platforms bypass traditional hospital formulary gatekeepers, accelerating homecare channel penetration.
Market Restraints
- Active Ingredient Import Dependency:Polyethylene glycol 3350 and senna glycosides concentrate in Indian and Chinese API suppliers, exposing formulators to shipping cost volatility and customs delays.
- Registration Dossier Multiplication:Divergent OTC thresholds between Egypt's pharmaceutical regulator, SAHPRA, and SFDA force manufacturers to maintain separate stability studies and labeling specifications for each national market.
- Herbal Remedy Substitution:Traditional Arabic and African botanical laxatives retain patient loyalty in rural Morocco, Nigeria, and Ethiopia, compressing branded pharmaceutical penetration.
Strategic Opportunities
- Underpenetrated East African Markets:Kenya and Ethiopia's pharmacy modernization programs create first-mover advantages for entrants establishing cold-chain distribution for liquid formulations.
- Pediatric Indication Expansion:SAHPRA's accelerated review pathway for childhood constipation therapeutics opens formulation development for polyethylene glycol 3350 sachets.
- Subscription Direct-to-Patient Models:Chronic opioid-induced constipation patients in South African urban centers demonstrate willingness to pay for automated replenishment services bypassing retail pharmacy visits.
Industry Challenges
- Formulation Scientist Scarcity:Gulf states lack sufficient pharmaceutical technologists trained in osmotic agent stability testing, forcing manufacturers to import quality control talent from India and Egypt.
- Multinational Packaging Harmonization:Pan-regional suppliers struggle to reconcile Saudi bilingual Arabic-English requirements with South Africa's 11-language labeling mandates without duplicating production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Laxative Market |
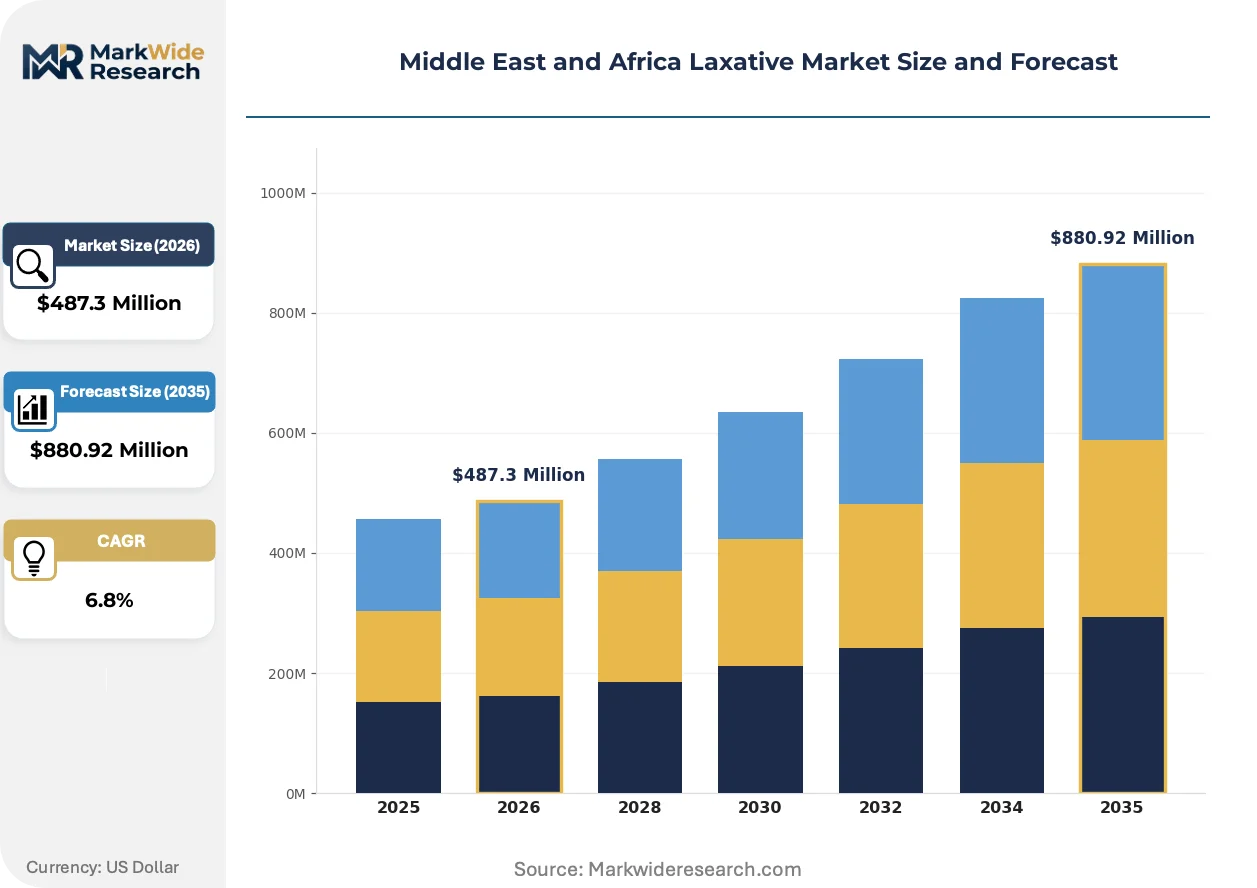
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulant Laxatives, Osmotic Laxatives, Bulk-forming Laxatives, Stool Softeners End User: Hospitals, Clinics, Pharmacies, Homecare Formulation: Tablets, Powders, Liquids, Suppositories Distribution Channel: Retail, Online, Wholesalers, Direct Sales |
| Companies Covered | Abbott Laboratories, Novartis AG, Sanofi, Dr. Reddy’s Laboratories Ltd., Johnson & Johnson, GlaxoSmithKline plc, Pfizer Inc., Boehringer Ingelheim International GmbH, Bayer AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Laxative Market Shifts & Advancements
Formulation science and distribution architecture are converging to redefine how laxatives reach patients across Middle Eastern and African markets, with regulatory digitization and channel disintermediation as dominant vectors.
Polyethylene glycol 3350 powder sachets is displacing traditional tablet and liquid presentations in institutional and homecare settings alike. Geriatric care facilities across the UAE and Qatar prefer the dosing flexibility and reduced aspiration risk of dissolvable powders. This shift compresses manufacturing line requirements for tablet compression while expanding contract packaging demand for unit-dose sachet filling.
SFDA's electronic submission gateway and Egypt's digital registration portal are compressing approval timelines for OTC laxative renewals. Manufacturers now submit stability data and labeling variations through centralized platforms rather than paper dossiers. Small and mid-sized pharmaceutical firms in Jordan and Lebanon leverage this digitization to compete with established Gulf formulary incumbents.
Self-medication authorization is fragmenting the traditional physician-prescription pathway across South African pharmacy chains. Pharmacists in Johannesburg and Cape Town retail networks now recommend osmotic agents directly for travel constipation and intermittent irregularity. This behavior concentrates volume in private pharmacy channels while eroding hospital outpatient dispensing share.
Middle East and Africa Laxative Market Segmentation
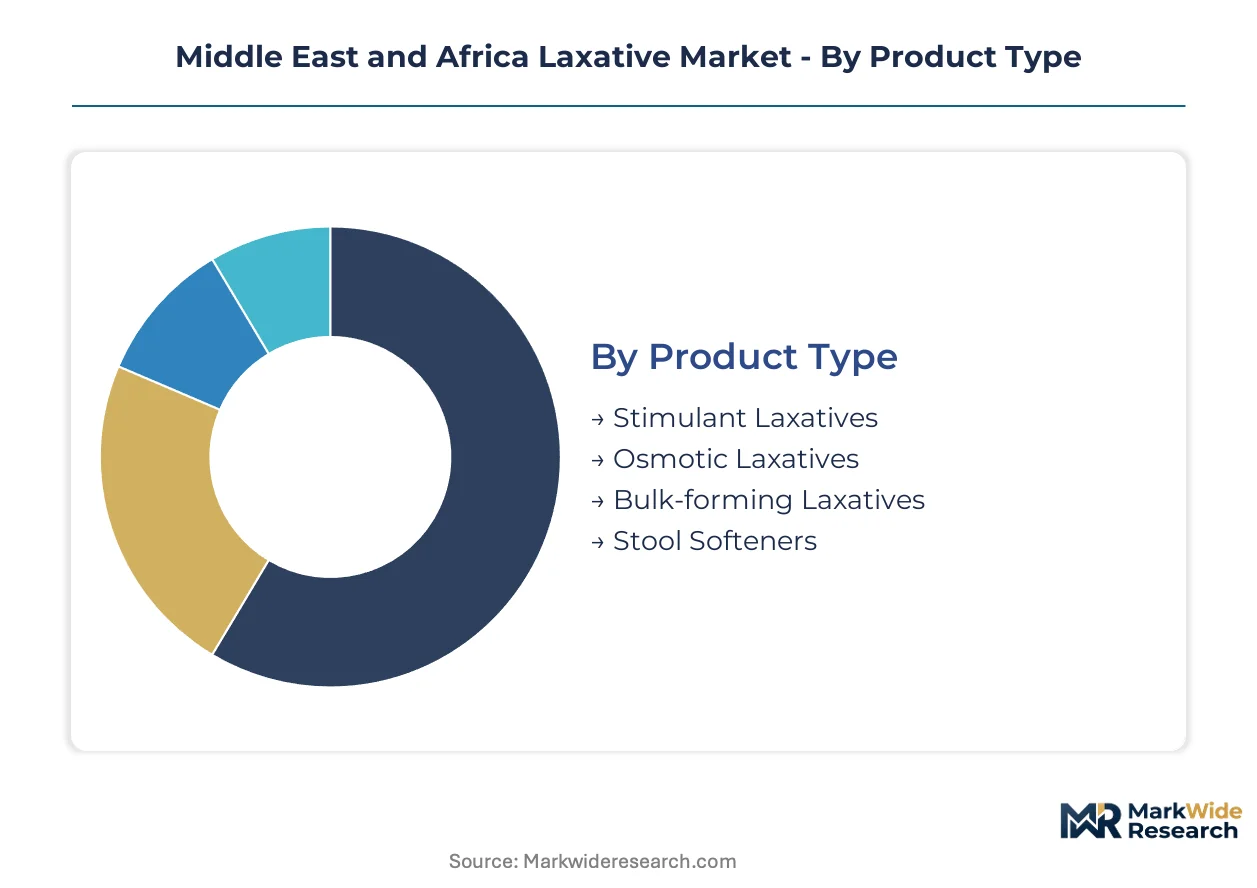
Laxative purchasing patterns across the Middle East and Africa fragment sharply by channel access, with regulatory classification determining whether patients obtain products through pharmacy shelves, institutional procurement, or direct-to-patient platforms. Understanding these segment boundaries clarifies where formulation investments and distribution partnerships generate returns.
Product Type:
Channel-mix dynamics favor osmotic and bulk-forming agents in retail pharmacy settings where Saudi SFDA and South African SAHPRA have expanded OTC pathways, while stimulant laxatives remain concentrated in hospital procurement due to stricter prescription requirements.
- Osmotic Laxatives:Polyethylene glycol 3350 formulations retain water in the intestinal lumen through osmotic pressure, producing predictable bowel evacuation without electrolyte disturbance. Demand concentrates in geriatric care facilities across Dubai, Riyadh, and Cairo where polypharmacy patients require agents compatible with cardiovascular and renal medications. SFDA's streamlined OTC registration for these agents accelerates pharmacy shelf placement.
- Stimulant Laxatives:Senna glycosides and bisacodyl trigger colonic neuromuscular contraction through direct mucosal irritation. Procurement clusters in hospital formularies across Gulf Cooperation Council states where SFDA maintains prescription-only classification for chronic use, limiting retail penetration despite faster onset of action.
- Bulk-forming Laxatives:Psyllium husk and methylcellulose increase stool mass to stimulate peristalsis; traditional Arabic botanical alternatives compete fiercely in rural Moroccan and Ethiopian markets.
- Stool Softeners:Docusate sodium reduces surface tension to permit water penetration into hardened stool; limited adoption outside post-surgical protocols in South African private hospitals.
By volume, bulk-forming laxatives lead through traditional remedy substitution. By growth pace, osmotic formulations are climbing the fastest as geriatric facility construction accelerates.
End User:
Cost-tier stratification separates premium-priced homecare subscriptions from commodity hospital contracts, with telehealth platforms capturing margin-rich chronic constipation patients in South African urban centers.
- Homecare:Direct-to-patient delivery models bypass retail pharmacy markups for chronic opioid-induced constipation patients in Johannesburg and Cape Town who prioritize convenience over immediate purchase. Automated replenishment subscriptions demonstrate willingness to pay premium pricing for privacy and adherence support.
- Pharmacies:Private pharmacy chains across South Africa and Emirates retail networks capture self-medication volume for travel constipation and intermittent irregularity; pharmacist recommendation protocols displace physician prescriptions for first-line osmotic agents.
- Hospitals:Pre-surgical bowel preparation and oncology protocols drive institutional procurement; formulary contracts concentrate in Abbott Laboratories and Sanofi portfolios across Gulf states.
- Clinics:Outpatient gastroenterology practices in Cairo and Lagos maintain limited dispensing for diagnostic preparation; regulatory fragmentation constrains pan-regional clinic chain standardization.
By patient touchpoints, pharmacies dominate. By margin expansion, homecare is gaining share fastest.
Formulation:
Application requirements dictate format selection, with geriatric aspiration risk driving powder adoption while tablet convenience sustains retail pharmacy volume.
- Powders:Polyethylene glycol 3350 sachets dissolve in beverage for flexible dosing; UAE and Qatar nursing homes prefer reduced aspiration risk versus liquid formulations. Unit-dose packaging expands contract manufacturing demand in Jordan and Lebanon.
- Tablets:Compressed bisacodyl and senna glycosides maximize pharmacy shelf stability and patient portability; South African retail chains prioritize blister-pack presentations for theft deterrence and inventory rotation.
- Liquids:Lactulose syrups serve pediatric and dysphagia populations; cold-chain requirements limit East African distribution penetration.
- Suppositories:Rectal bisacodyl addresses acute fecal impaction in hospital emergency departments; cultural resistance constrains home use across conservative Gulf markets.
By manufacturing throughput, tablets lead. By facility preference shift, powders are expanding most quickly.
Distribution Channel:
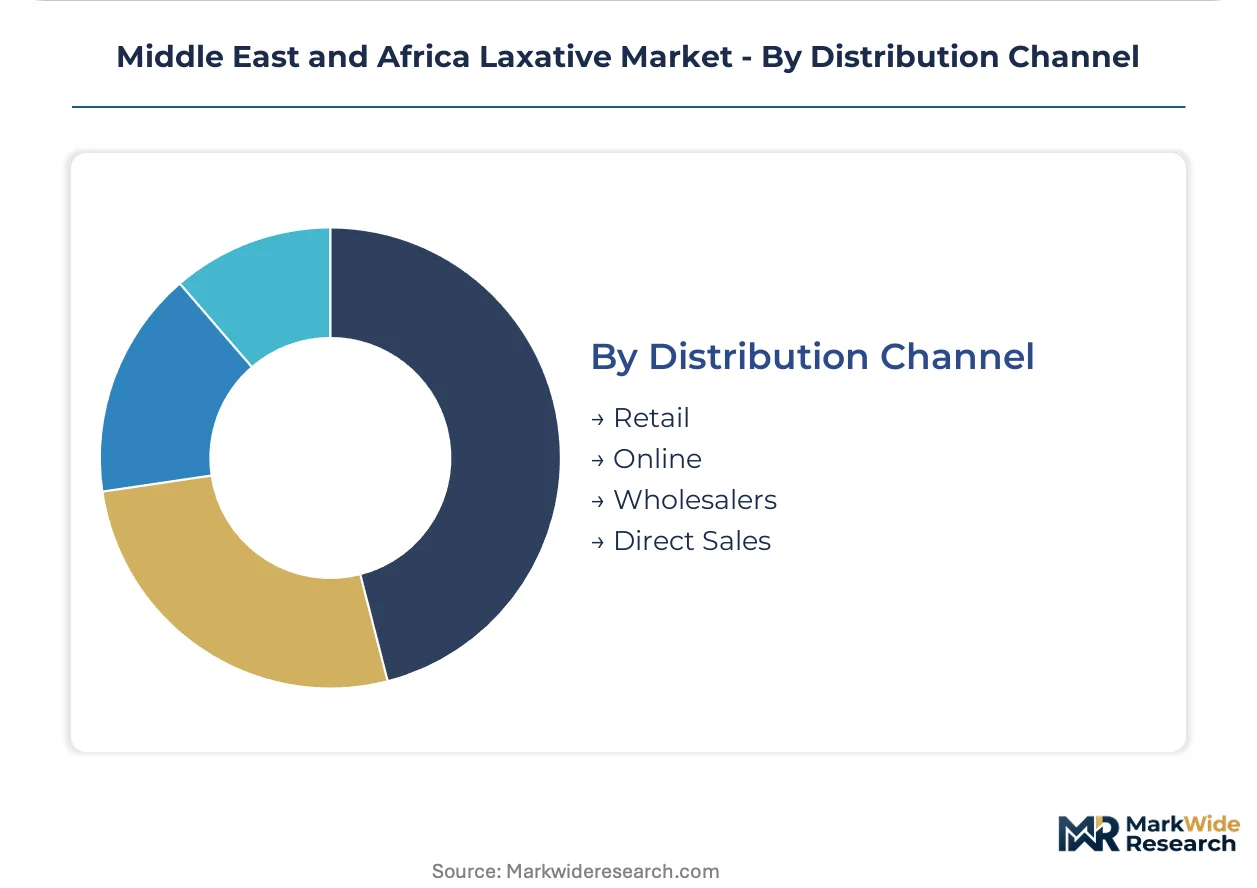
Volume concentration runs through wholesale networks serving fragmented pharmacy bases, while margin capture shifts toward disintermediated direct sales.
- Retail:Private pharmacy chains in South Africa and Emirates urban centers consolidate purchasing power; shelf-space competition between multinational heritage brands and local generics intensifies.
- Wholesalers:Regional distributors bridge multinational manufacturers to fragmented independent pharmacies across Nigeria, Egypt, and Morocco; inventory financing and credit terms determine supplier loyalty.
- Online:Telehealth-integrated platforms in South Africa bypass physical pharmacy visits for chronic patients; regulatory ambiguity around cross-border shipment constrains pan-regional scaling.
- Direct Sales:Subscription models target opioid-induced constipation patients in affluent Johannesburg suburbs; patient data capture enables adherence monitoring and formulary influence.
By transaction volume, wholesalers dominate. By channel innovation velocity, direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient import corridors concentrate through Indian and Chinese API suppliers, exposing formulators across the Middle East and Africa to shipping cost volatility and customs processing delays that reshape national market prioritization.
Saudi Arabia
Geriatric facility construction in Riyadh and Jeddah generates concentrated demand for polypharmacy-compatible osmotic formulations. SFDA tightened over-the-counter classification protocols for stimulant laxatives, forcing manufacturers to maintain separate prescription-track dossiers. The Eastern Province industrial cluster hosts contract packaging operations serving Gulf Cooperation Council distribution networks.
South Africa
Urbanization and rising self-medication awareness channel laxative volume through private pharmacy retail chains in Johannesburg and Cape Town. SAHPRA enforces accelerated review pathways for pediatric constipation therapeutics, opening formulation development opportunities. Telehealth-integrated direct-to-patient delivery platforms bypass traditional hospital formulary gatekeepers in affluent suburban markets.
Egypt
Heritage brand presence anchors consumer trust in Egyptian pharmacy networks serving chronic constipation patients. The national pharmaceutical regulator maintains distinct OTC-to-prescription classification thresholds that diverge from Gulf standards, elevating compliance costs for pan-regional suppliers. Cairo's outpatient gastroenterology practices maintain limited dispensing for diagnostic bowel preparation protocols.
United Arab Emirates
Nursing homes across Dubai and Abu Dhabi prefer polyethylene glycol 3350 powder sachets for reduced aspiration risk versus liquid formulations. MOHAP digitization initiatives compress approval timelines for OTC laxative renewals through electronic submission gateways. The Jebel Ali pharmaceutical free zone concentrates regional distribution hubs serving re-export markets.
Nigeria
Traditional botanical laxatives retain patient loyalty in rural northern and southwestern regions, compressing branded pharmaceutical penetration. The national medicines regulatory agency enforces import licensing requirements that delay product registration for multinational entrants. Lagos pharmacy modernization programs create first-mover advantages for entrants establishing wholesale distribution infrastructure.
Middle East and Africa Laxative Market Competitive Landscape
Concentration sits with multinational pharmaceutical conglomerates possessing established gastrointestinal portfolios and Gulf formulary contracts. Three structural tiers separate heritage brand owners with consumer trust from generic manufacturers competing on price and regional specialists leveraging regulatory digitization. Competitive moves center on portfolio diversification into pediatric indications and strategic partnerships with telehealth platforms for direct-to-patient channel access.
Among heritage-brand pharmaceutical conglomerates, Abbott Laboratories, Sanofi, and Bayer AG occupy positions reflecting distinct competitive archetypes. Abbott leverages its established gastrointestinal portfolio to dominate hospital formulary contracts across Gulf Cooperation Council states. Sanofi competes through broad retail distribution reach in private pharmacy networks. Bayer anchors consumer trust through heritage brand presence in Egyptian and Nigerian pharmacy channels. These three exemplify how multinational scale, regional regulatory expertise, and channel-specific positioning combine to structure competitive outcomes across Middle Eastern and African markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Novartis AG |
| Sanofi |
| Dr. Reddy's Laboratories Ltd. |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Contract packaging scale in Jordan and Lebanon determines regional price floors for polyethylene glycol 3350 sachets, as facility utilization rates below seventy percent force margin compression that cascades through Gulf wholesale networks and Egyptian pharmacy chains alike.
Pricing Analysis
Volume-discount tiering separates hospital formulary contracts from retail pharmacy procurement and direct-to-patient subscription models. Price differentiation rests on SFDA registration tier and cold-chain handling certification for liquid formulations. Cost compression in standard-grade tablets is intensifying because Indian API suppliers are consolidating shipping contracts. Hospital procurement managers in Riyadh demonstrate lowest price sensitivity; rural Moroccan independent pharmacies exhibit highest.
Supply Chain Analysis
Inbound logistics costs through Jebel Ali and Port of Durban fluctuate with Red Sea container availability and Indian Ocean shipping lane congestion. Active ingredient production concentrates in India and China, with secondary formulation capacity in Jordan and Egypt. Raw material dependencies include polyethylene glycol 3350, senna glycosides, and psyllium husk. Single-source vulnerability from Chinese API suppliers exposes formulators to customs processing delays. Distribution runs through regional wholesalers serving fragmented pharmacy bases across Nigeria and Morocco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against traditional Arabic and African botanical laxatives that retain patient loyalty in rural markets, eroding branded pharmaceutical volume through substitution effects that pricing alone cannot counter.
For Market Incumbents: Compound formulary lock-in across Gulf Cooperation Council hospital systems through polypharmacy compatibility data packages that generic entrants cannot replicate. Secure backward integration into polyethylene glycol 3350 sourcing to buffer Indian API supplier consolidation. Channel control through telehealth platform partnerships defends against direct-to-patient subscription erosion. For New Entrants and Emerging Players: Differentiate on pediatric indication development targeting SAHPRA's accelerated review pathway for childhood constipation therapeutics. Kenya and Ethiopia's pharmacy modernization programs represent the most penetrable geography. Cold-chain distribution partnerships for liquid formulations offer a defensible go-to-market angle against tablet-dominated incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with regulatory digitization capabilities and Jordanian contract packaging assets. Long-term viability hinges on African Medicines Agency harmonization progress rather than country-specific registration plays. Acquisition targets should demonstrate electronic submission gateway proficiency. The signal to watch is SFDA OTC reclassification momentum for bulk-forming agents.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | SAHPRA's accelerated review pathway opens formulation development for polyethylene glycol 3350 sachets. |
| Telehealth Platform Integration | Direct-to-patient delivery models in Johannesburg bypass retail pharmacy markups for chronic patients. |
| Backward Integration into API Sourcing | In-house production of polyethylene glycol 3350 reduces exposure to Indian supplier shipping volatility. |
| Regulatory Digitization Investment | SFDA electronic submission gateway proficiency compresses approval timelines against paper-dossier competitors. |
| East African Distribution Expansion | Kenya pharmacy modernization programs create first-mover advantages for liquid formulation cold-chain entrants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at Saudi SFDA, hospital procurement managers in Dubai and Riyadh, Egyptian pharmacy chain category buyers, and South African telehealth platform operators; and secondary validation through SFDA registration databases, SAHPRA approval records, Egyptian pharmaceutical regulator filings, and customs trade data on API imports. Bottom-up patient-volume modeling and top-down pharmaceutical spending triangulation anchored value estimates.
Across the analysis window, the analytical framework modeled segmentation by product type, end user, formulation, and distribution channel, with regional regulatory cluster as an additional dimension. CAGRs derived from patient demographic projections, facility construction pipelines, and channel migration rates. Forecast inputs included geriatric population growth in Gulf states and telehealth adoption curves in South African urban centers.
Decision-makers should treat outputs as directional under assumptions of continued SFDA OTC pathway expansion and stable Indian-Chinese API supply; material deviation would warrant model refresh. Specific risk factors include African Medicines Agency harmonization delays and Red Sea shipping disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Anticancer Drugs Market