
 Super Absorbent Dressings Market | 2026-2036
Super Absorbent Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Super Absorbent Dressings Market Intelligence
Project finance and leasing arrangements for advanced wound care manufacturing lines is rewriting competitive entry barriers in the super absorbent dressings sector. Smith & Nephew leverages captive polymer sourcing to sustain margin stability across European hospital networks. Molnlycke Health Care AB anchors its position through vertically controlled hydrocolloid production in Scandinavia. Coloplast Corp. differentiates via specialized stoma and wound care channel control in North American homecare segments.
Super absorbent dressings are multilayer wound interface products engineered with polyurethane foam matrices or sodium alginate fibers to manage exudate volumes exceeding ten milliliters per square centimeter daily; their primary commercial purpose is to maintain moist wound healing environments while preventing periwound maceration in chronic and acute lesions. Foam dressings occupy the largest revenue pool given their versatility across surgical sites and pressure ulcers, while alginate segments are capturing accelerated demand in burn treatment centers where hemostatic performance commands premium positioning. Hospital end users still dominate procurement volumes, though homecare channels are expanding fastest as post-acute discharge protocols shorten inpatient stays.
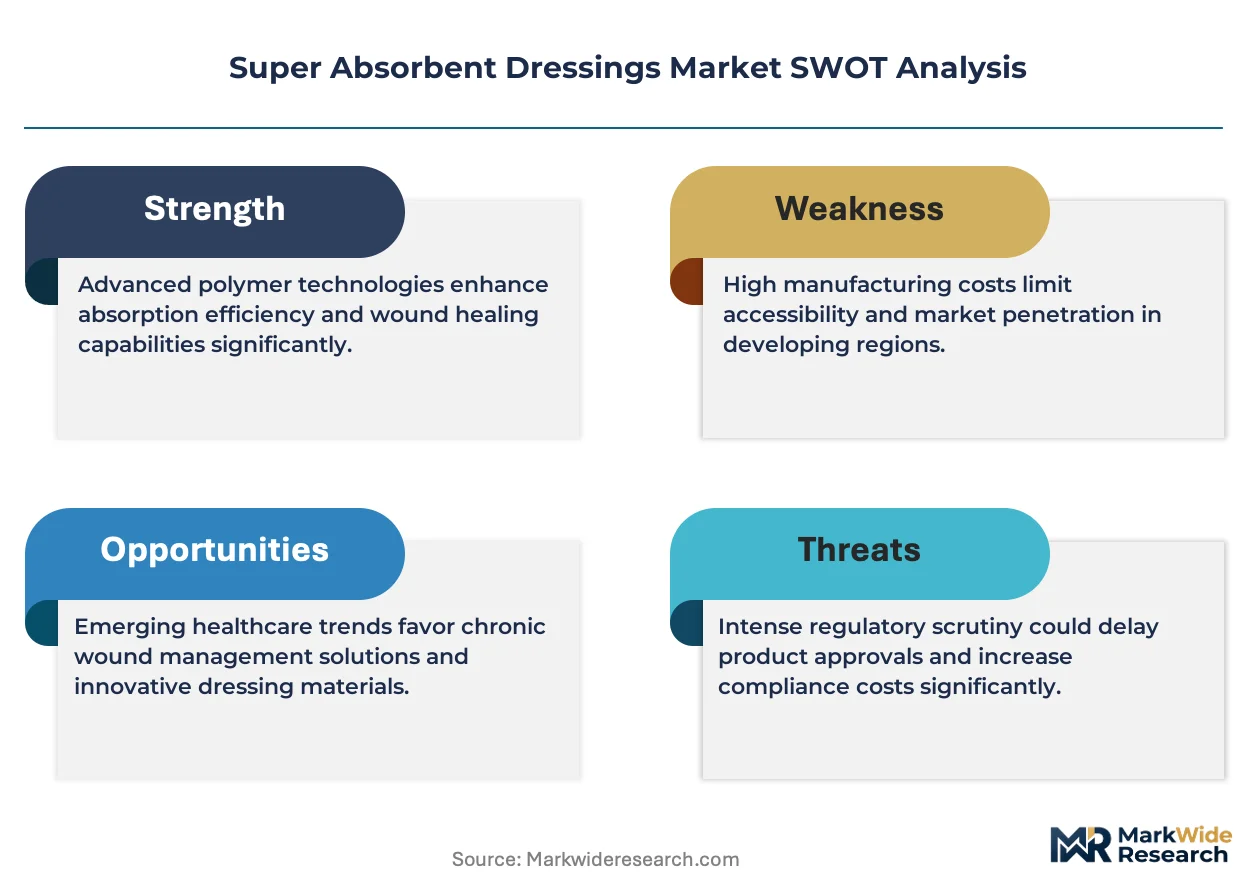
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) are tightening biocompatibility documentation requirements for polymer-based dressings, directly elevating R&D compliance costs for market entrants. Health Canada and Japan's PMDA maintain aligned but distinct cytotoxicity testing standards that fragment approval timelines for multi-region product launches. Stakeholders must monitor how CMS bundled payment reforms and EU Green Deal sustainability mandates will reshape material sourcing decisions for synthetic polymer substrates.
Market Dynamics
CMS bundled payment reforms are compressing hospital reimbursement windows and forcing procurement officers to prioritize super absorbent dressings that reduce dressing change frequency and nursing labor hours. This reimbursement pressure is restructuring competitive advantage around clinical outcome documentation rather than unit cost alone.
Growth Catalysts
- EU Medical Device Regulation (MDR):Biocompatibility documentation requirements are elevating barriers for low-quality imports, creating protected market space for compliant manufacturers in European hospital networks.
- Homecare infrastructure:Post-acute discharge protocols in Germany and Japan are pulling dressing volumes into outpatient channels where patient self-administration expands addressable demand.
- Sodium alginate fiber technology:Hemostatic performance in burn treatment centers commands premium positioning and accelerates category migration from traditional gauze.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam matrices depend on propylene oxide and toluene diisocyanate pricing, exposing margin stability to energy market swings.
- Single-region polymer concentration:Captive sourcing advantages cluster with integrated manufacturers, fragmenting supply security for non-vertically controlled competitors.
- Silver ion substitution:Antimicrobial foam dressings face displacement pressure from ionic silver alternatives in infected wound protocols.
Strategic Opportunities
- Brazil's SUS expansion:Universal health coverage growth in Northeast and North regions creates underpenetrated demand for cost-optimized alginate variants.
- Wearable biosensor convergence:Integration of moisture detection electronics with foam substrates enables remote exudate monitoring for homecare patients.
- EU Green Deal mandates:Sustainability requirements for synthetic polymer substrates are opening preferential procurement pathways for bio-based alternatives.
Industry Challenges
- MDR technical documentation:Clinical evaluation report preparation for polymer-based dressings consumes 18-24 month certification timelines, delaying product launches.
- Polymer science talent scarcity:Formulation chemists with hydrocolloid and superabsorbent polymer expertise command premium compensation, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Absorbent Dressings Market |
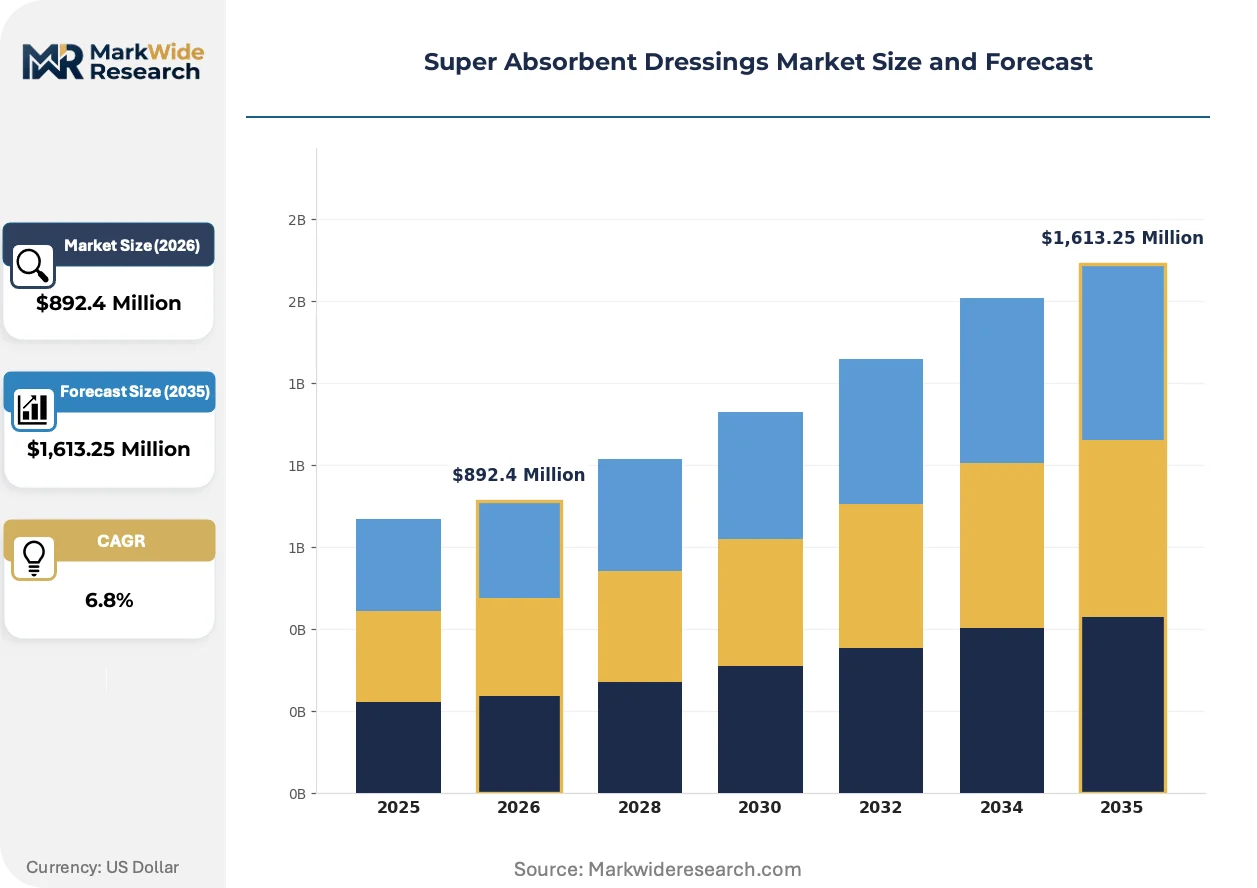
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Dressings, Hydrocolloid Dressings, Alginate Dressings, Composite Dressings End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Application: Wound Care, Surgical Sites, Burn Treatment, Pressure Ulcers Material: Polyurethane, Hydrogel, Cotton, Synthetic Polymers |
| Companies Covered | 3M, Smith & Nephew, Coloplast Corp., Molnlycke Health Care AB, Hartmann USA, Inc., Medline Industries, Integra LifeSciences, Cardinal Health, ConvaTec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Absorbent Dressings Market Strategic Shifts & Innovations
Digital wound assessment tools are virtualizing traditional clinical workflows and creating data dependencies that reshape how dressing performance is validated and purchased. This technological infusion is compressing the gap between product innovation and reimbursement evidence requirements.
Smart dressing substrates embedded with printed electronic sensors are virtualizing exudate monitoring by transmitting moisture and temperature data to centralized nursing stations. Burn centers in the United States are piloting these systems to reduce unscheduled dressing inspections. The technology is virtualizing labor-intensive visual assessment protocols into automated alert systems that trigger intervention only when thresholds breach.
Japan's PMDA has aligned cytotoxicity testing standards with ISO 10993-5 updates, creating documentation harmonization that accelerates multi-region product launches for compliant manufacturers. This regulatory convergence reduces redundant biocompatibility studies and compresses approval timelines. Alginate segments with existing ISO certification are capturing first-mover advantage in Japanese homecare channels where PMDA alignment is accelerating market access.
Hospital procurement committees are consolidating vendor rosters and demanding outcome guarantees that bundle dressing performance with nursing labor cost reductions. This buying-pattern shift is displacing spot-purchase contracts with multi-year agreements that lock in volume commitments. German hospital networks are most advanced in this transition, where purchasing cooperatives negotiate performance-based terms that penalize periwound maceration incidents.
Super Absorbent Dressings Market Segmentation
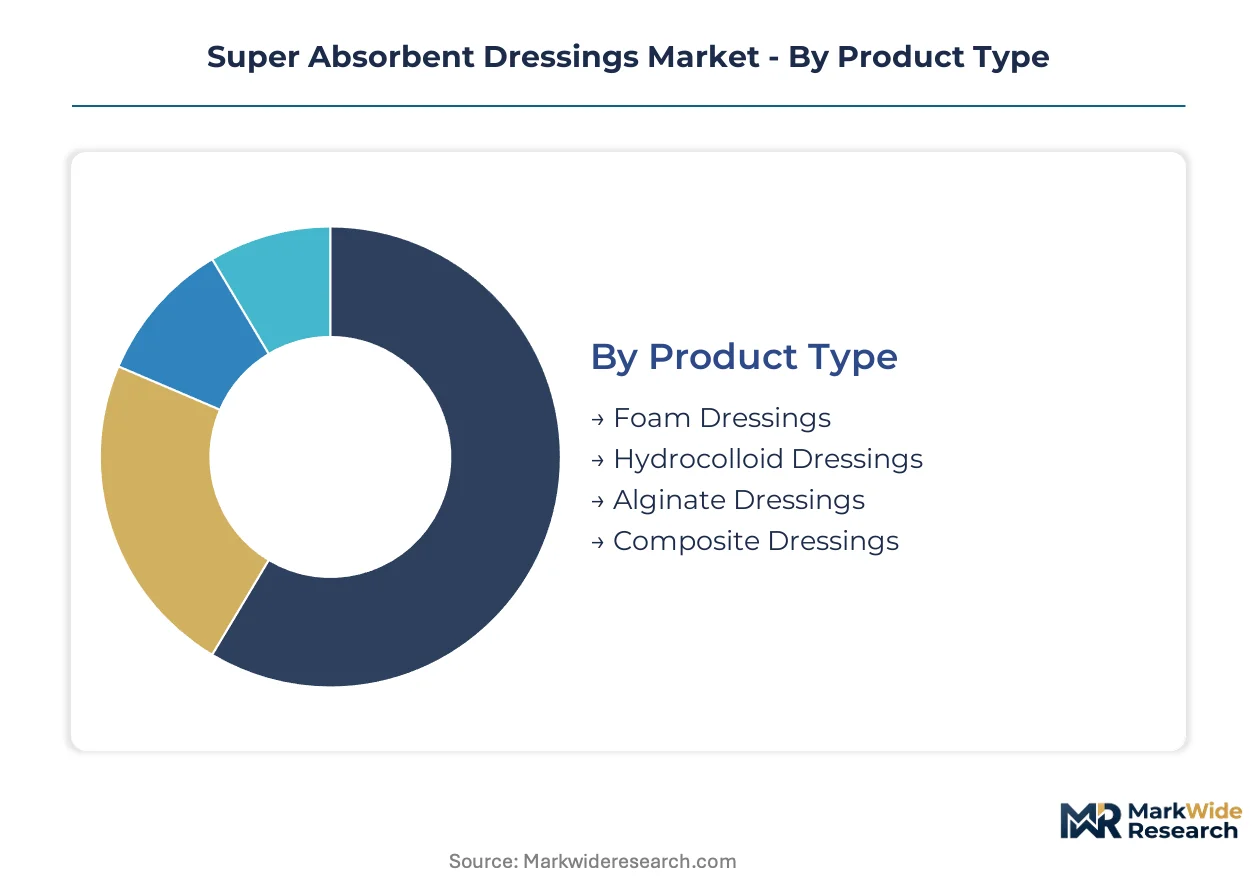
Super absorbent dressing manufacturers configure production lines around distinct technical specifications and clinical use cases. Segment-level demand volatility creates working capital pressures that favor flexible polymer sourcing strategies over dedicated single-product facilities.
Product Type:
Foam dressings turn inventory fastest in acute care settings where surgical discharge volumes drive weekly replenishment cycles, while alginate variants sit longer in burn center supply chains due to lower utilization frequency.
- Foam Dressings:Polyurethane matrices with open-cell architecture absorb exudate through capillary action while maintaining tensile integrity during removal. German hospital networks concentrate procurement of these variants as CMS bundled payment reforms in the United States compress reimbursement windows and force dressing change frequency reductions. Margin stability depends on captive propylene oxide sourcing.
- Alginate Dressings:Sodium alginate fibers extracted from brown seaweed form gel matrices upon contact with wound fluid, delivering hemostatic performance that commands premium positioning. Burn treatment centers in Japan and the United States anchor demand concentration as PMDA and FDA pathways align on cytotoxicity documentation standards. Hemostatic protocols displace traditional gauze in these specialized settings.
- Hydrocolloid Dressings:Carboxymethylcellulose and gelatin composites create occlusive environments for low-to-moderate exudate wounds.
- Composite Dressings:Multi-layer constructions combine absorbent cores with adhesive borders and moisture barriers.
Foam dressings anchor the volume base while alginate dressings gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich hospital systems from budget-constrained homecare channels where patient self-administration drives unit economics toward simplified packaging formats.
- Hospitals:Centralized procurement committees negotiate multi-year performance contracts that bundle dressing efficacy with nursing labor cost documentation. German purchasing cooperatives penalize periwound maceration incidents through outcome-based terms. CMS reimbursement compression forces consolidation onto vendor rosters with outcome guarantees.
- Homecare:Post-acute discharge protocols in Japan and Germany pull dressing volumes into outpatient channels where patient self-administration expands addressable demand. Brazil's SUS expansion in Northeast and North regions creates underpenetrated demand for cost-optimized variants with simplified application instructions.
- Clinics:Outpatient wound care centers balance inventory breadth against procedure volume variability.
- Long-term Care Facilities:Pressure ulcer prevention protocols drive scheduled dressing rotation programs with limited clinical oversight.
Hospitals dominate current procurement volumes while homecare channels expand most quickly as length-of-stay protocols shorten.
Application:
Volume concentration varies sharply across wound etiology, with surgical site management generating predictable demand patterns against the irregular intake cycles of burn trauma centers.
- Wound Care:Chronic lesion management spans diabetic foot ulcers, venous stasis wounds, and traumatic injuries with divergent exudate profiles. Foam substrates predominate in moist wound healing protocols across United States hospital networks where value-based care models reward reduced healing times.
- Surgical Sites:Post-operative incision protection demands consistent absorbency without adhesion trauma upon removal. German and Japanese hospital procurement prioritizes these variants in orthopedic and general surgery departments where discharge timing depends on dressing performance documentation.
- Burn Treatment:Hemostatic and antimicrobial requirements in thermal and chemical injury protocols.
- Pressure Ulcers:Long-term care and geriatric hospital settings with staged prevention protocols.
Wound care anchors the volume base while burn treatment gains share at the steepest rate.
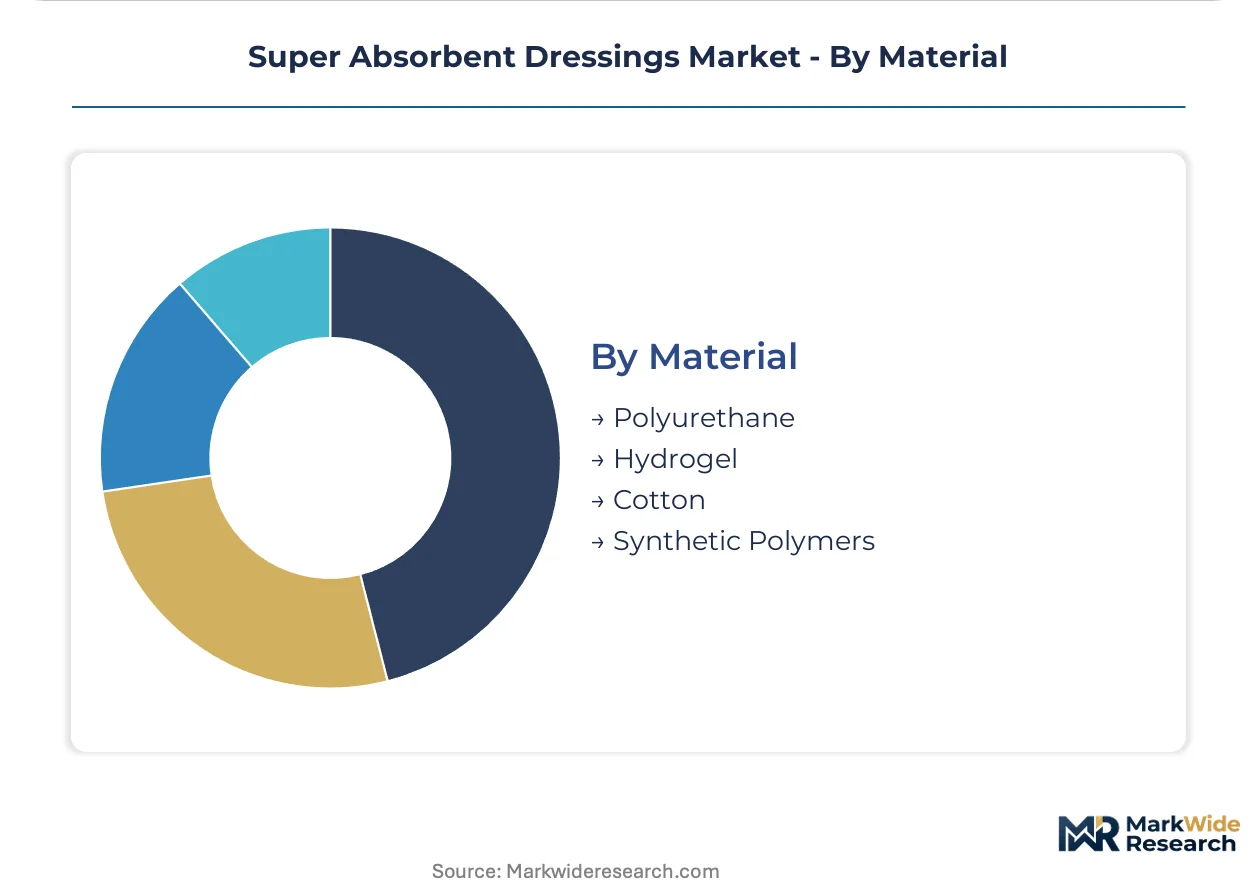
Material:
Supply concentration for petrochemical feedstocks creates margin volatility that bio-based alternatives are beginning to exploit under EU Green Deal procurement preferences.
- Polyurethane:Toluene diisocyanate and polyether polyol formulations deliver tunable absorbency and mechanical strength for foam dressings. Energy market swings in propylene oxide pricing expose non-integrated manufacturers to margin compression.
- Synthetic Polymers:Superabsorbent polyacrylate granules and fiber technologies enable exudate retention exceeding ten milliliters per square centimeter. Smith & Nephew and Molnlycke Health Care AB maintain captive production in European and Scandinavian facilities respectively.
- Hydrogel:Cross-linked polymer networks that donate moisture to dry wound environments.
- Cotton:Natural fiber substrates with limited absorbency but established cost positioning in emerging markets.
Polyurethane anchors the volume base while synthetic polymers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS bundled payment reforms in the United States are compressing hospital reimbursement windows and forcing procurement officers to prioritize dressing change frequency reductions. Germany's purchasing cooperatives negotiate outcome-based terms that penalize periwound maceration incidents. Japan's PMDA alignment with ISO 10993-5 updates accelerates multi-region product launches for compliant manufacturers.
United States
Hospital procurement committees consolidate vendor rosters around outcome guarantees that bundle dressing performance with nursing labor cost reductions. FDA 510(k) clearance pathways tighten biocompatibility documentation requirements for polymer-based dressings. Burn centers in Texas and California pilot smart dressing substrates with embedded moisture detection electronics.
Germany
Aging demographics and expanding homecare infrastructure pull super absorbent dressing volumes into outpatient channels where patient self-administration expands addressable demand. EU Medical Device Regulation biocompatibility documentation elevates barriers for low-quality imports. Purchasing cooperatives in Bavaria and North Rhine-Westphalia negotiate performance-based terms penalizing clinical complications.
Japan
Post-acute discharge protocols shorten inpatient stays and pull dressing volumes into homecare channels. PMDA maintains aligned but distinct cytotoxicity testing standards that fragment approval timelines for multi-region launches. Alginate segments with existing ISO certification capture first-mover advantage in Tokyo and Osaka homecare markets.
Brazil
Universal health coverage expansion through SUS creates underpenetrated demand for cost-optimized alginate variants in Northeast and North regions. ANVISA regulatory pathways for imported medical devices shape competitive entry dynamics. São Paulo anchors manufacturing and distribution infrastructure serving hospital networks across Southeast states.
Super Absorbent Dressings Market Key Industry Players
On the supply side, the industry is moderately consolidated around vertically integrated polymer producers and specialized wound care manufacturers with captive sourcing advantages. Three strategic archetypes dominate: integrated healthcare conglomerates with backward polymer control, mid-cap specialists with regional channel depth, and diversified medical device players leveraging existing hospital contracts. Competitive moves center on M&A for polymer science capabilities and strategic partnerships for biosensor integration.
Within the integrated tier, Smith & Nephew and Molnlycke Health Care AB occupy positions sustained by captive production infrastructure in European and Scandinavian facilities respectively. Coloplast Corp. exemplifies the specialized channel control archetype through focused stoma and wound care positioning in North American homecare segments.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Coloplast Corp. |
| Molnlycke Health Care AB |
| Hartmann USA, Inc. |
| Medline Industries |
| Integra LifeSciences |
| Cardinal Health |
| ConvaTec Group |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility in propylene oxide and toluene diisocyanate markets determines both pricing tier spreads and supply chain shape across super absorbent dressing manufacturing. Energy market swings compress margins for non-integrated manufacturers while rewarding backward polymer control with pricing power in hospital procurement negotiations.
Pricing Analysis
Certification level (ISO 10993-5/CE/FDA-grade) creates the primary spread between premium alginate variants and economy foam alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors contract negotiations, with MDR-compliant documentation commanding 15-20 point spreads over import alternatives. Price erosion runs through standard-tier foam dressings as CMS bundled payment reforms force cost compression. Homecare channels exhibit highest price sensitivity due to patient out-of-pocket exposure, while German purchasing cooperatives prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Molnlycke's Scandinavian facilities, Smith & Nephew's European polymer operations, and Coloplast's North American stoma care infrastructure. Germany, Japan, and the United States anchor geographic supply concentration for finished dressing production. Raw material dependencies center on Saudi Arabian propylene oxide, Scandinavian sodium alginate harvests, and German polyurethane chemical processing. Single-source vulnerability in petrochemical feedstocks exposes margin stability to energy market discontinuities. Distribution runs through hospital GPO contracts in the United States, purchasing cooperatives in Germany, and SUS regional warehouses in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart dressing convergence with remote patient monitoring platforms creates platform-economics inflection, with moisture biosensor integration rewriting how dressing performance is validated and reimbursed across homecare channels.
For Market Incumbents: Build regulatory documentation moats through MDR technical file depth and ISO 10993-5 certification currency that emerging competitors cannot replicate within 18-24 month windows. Smith & Nephew and Molnlycke should deepen backward polymer control to defend margin position against propylene oxide volatility. Hospital GPO contract consolidation demands outcome-based performance guarantees that penalize periwound maceration incidents. For New Entrants and Emerging Players: Build out white-space positions in Brazil's SUS Northeast and North regions where universal health coverage expansion outruns established distribution infrastructure. Alginate variants with simplified Portuguese-language application instructions capture underpenetrated demand where ANVISA pathways favor cost-optimized documentation. Partner with São Paulo-based distributors for hospital network access rather than direct sales buildout. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating compliant manufacturers above import-dependent competitors facing 18-24 month certification delays. Target mid-cap specialists with existing ISO 10993-5 documentation and regional channel depth in German homecare or Japanese post-acute discharge markets. Watch PMDA-ISO alignment acceleration as signal for multi-region product launch feasibility and valuation inflection in alginate segments.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Creates 18-24 month competitive moat against low-quality imports in EU hospital networks. |
| Biosensor Integration Partnership | Enables remote exudate monitoring for Japanese and German homecare reimbursement pathways. |
| Brazil SUS Distribution Buildout | Captures universal coverage expansion in Northeast and North regions ahead of incumbent response. |
| Captive Polymer Sourcing Expansion | Insulates margin stability from propylene oxide volatility in German and US hospital contracts. |
| Alginate Hemostatic Performance Positioning | Commands premium placement in Texas and California burn centers displacing traditional gauze. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across wound care clinicians, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and homecare distribution specialists. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement data, and ANVISA import registration records. Bottom-up demand modeling triangulated against top-down polymer consumption estimates across the analysis window.
Calibration anchored volume projections to observed hospital discharge protocol shifts and homecare infrastructure buildout rates in Germany and Japan. Segmentation dimensions spanned product type (foam/alginate/hydrocolloid/composite), end user (hospital/homecare/clinic/long-term care), application (wound care/surgical site/burn treatment/pressure ulcer), and material substrate (polyurethane/synthetic polymer/hydrogel/cotton). CAGRs derived from elasticity-adjusted pricing trajectories and exudate management protocol adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated polymer producers or biosensor platform entrants would shift outcomes beyond modeled ranges. Quarterly review of MDR certification timelines, PMDA-ISO alignment progress, and CMS bundled payment reform implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Filter Needles Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Cryotubes Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Global Needles Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Plasma Expanders Market