
 Nonwoven Surgical Drapes Market | 2026-2036
Nonwoven Surgical Drapes Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Surgical Drapes Market Intelligence
The shift toward procedure-specific, pre-packaged surgical kits is rewriting the logistics and product configuration of nonwoven drapes. This approach reduces operating room setup time and minimizes waste. Medline Industries leverages its extensive distribution network to supply these custom kits to large hospital systems. Mölnlycke Health Care differentiates through its focus on patented adhesive technologies for secure drape placement, while Cardinal Health competes by offering integrated supply chain solutions.
Nonwoven surgical drapes are single-use textiles engineered to create and maintain a sterile field around a surgical site. Constructed from materials like multi-layer polypropylene SMS composites, they provide a critical barrier against fluid and microbial contamination during invasive procedures. While standard drapes for general surgery command the largest volume, the custom drapes segment for specialized applications like orthopedic and cardiac surgery represents the fastest-growing category. Hospitals remain the dominant end user, though ambulatory surgical centers show rapid uptake.
Market access is governed by stringent regulations, including the FDA's requirements for medical devices in the United States and the EU's Medical Device Regulation (MDR). Compliance with the ISO 13485 standard for quality management systems is a baseline for manufacturers seeking to compete across developed markets. Navigating the evolving standards for material sustainability and end-of-life disposal will define future competitive advantages for suppliers.
Market Dynamics
The structural shift toward procedure-specific surgical kits is the central force reconfiguring the nonwoven surgical drapes market. This model, which bundles drapes with other necessary single-use items, alters supply chain logistics, inventory management for hospitals, and the competitive basis from individual product features to system-wide efficiency.
Growth Catalysts
- Ambulatory Surgical Centers:The rapid expansion of ambulatory surgical centers, which prioritize high patient throughput and strict infection control, is driving demand for standardized, single-use draping systems that ensure procedural efficiency and sterility.
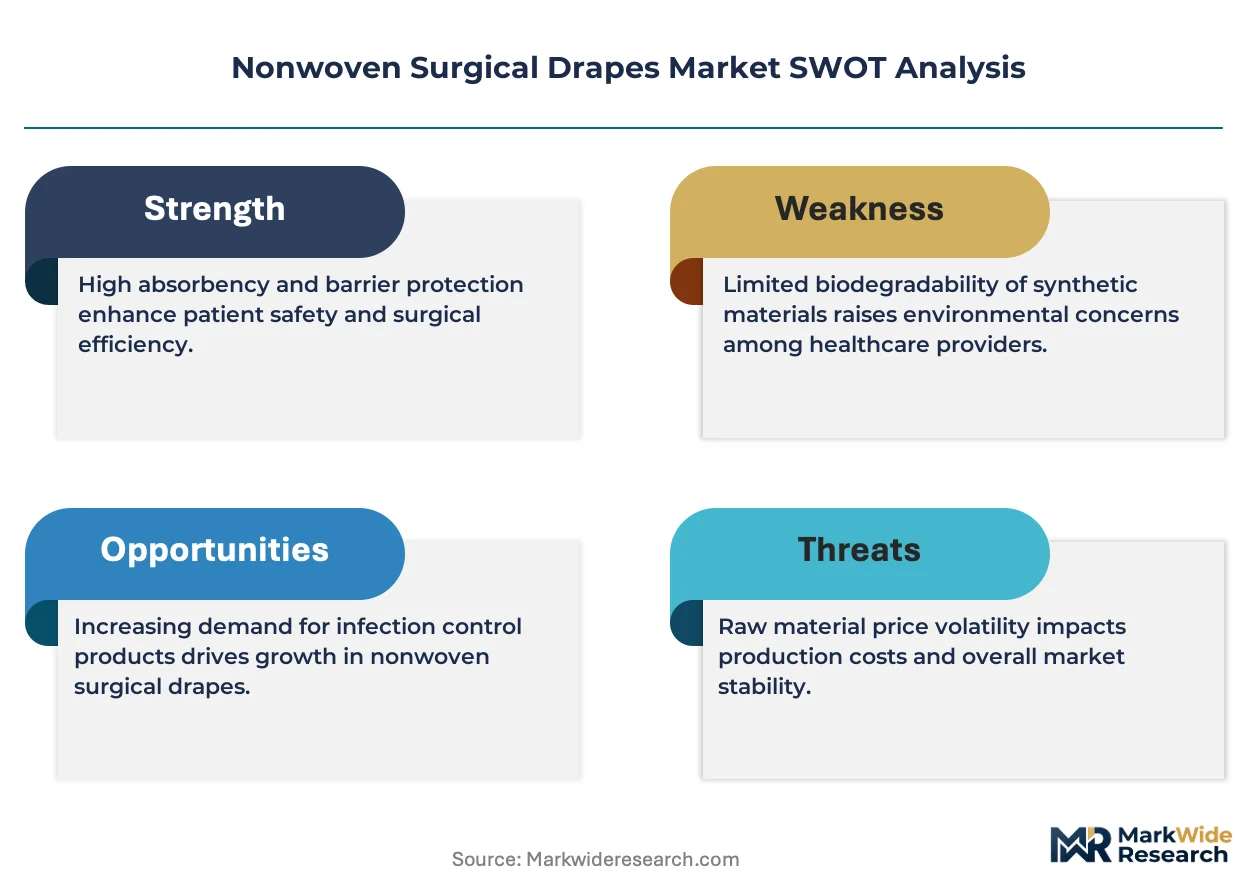
- Advanced Composite Materials:Development of multi-layer SMS (spunbond-meltblown-spunbond) composites with enhanced fluid barrier properties directly addresses clinical needs for preventing strikethrough and reducing surgical site infection risks during complex, fluid-intensive procedures.
- Stringent Healthcare Standards:High surgical volumes in countries like Germany, coupled with rigorous national healthcare standards for infection prevention, create concentrated demand for high-performance drapes that meet demanding clinical and regulatory benchmarks.
Market Restraints
- Raw Material Volatility:The market is exposed to price fluctuations in polypropylene, the primary petroleum-derived raw material for SMS nonwovens, creating cost instability for manufacturers and pricing pressure for end users.
- Medical Waste Generation:Growing environmental scrutiny from hospital administrators and regulators over the significant volume of plastic waste generated by single-use drapes creates pressure for more sustainable materials or disposal solutions.
- Regulatory Compliance Burden:Stringent regulations, such as the EU's Medical Device Regulation (MDR), increase the cost, complexity, and timeline for product development and market access, creating a significant barrier for smaller manufacturers.
Strategic Opportunities
- Robotic Surgery Drapes:The increasing adoption of robotic surgical systems creates a distinct opportunity for highly specialized, custom-fit drapes designed to cover complex equipment geometries while maintaining a sterile field.
- Emerging Market Penetration:Expanding healthcare infrastructure and rising surgical volumes in large developing economies, such as Brazil and India, represent significant growth opportunities for introducing standardized draping solutions to improve infection control.
- Smart Drape Technology:Integrating sensor technology into drapes to detect sterile field breaches or monitor fluid accumulation offers a path for product differentiation and added clinical value in high-risk surgeries.
Industry Challenges
- Logistical Complexity:The shift to customized surgical kits requires sophisticated supply chain capabilities to manage the assembly, sterilization, and just-in-time delivery of thousands of unique configurations to diverse hospital systems.
- Sustainability Reporting:Adapting manufacturing processes and supply chains to meet evolving standards for material traceability and end-of-life disposal, such as those related to the EU's CSRD, presents a major operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Surgical Drapes Market |
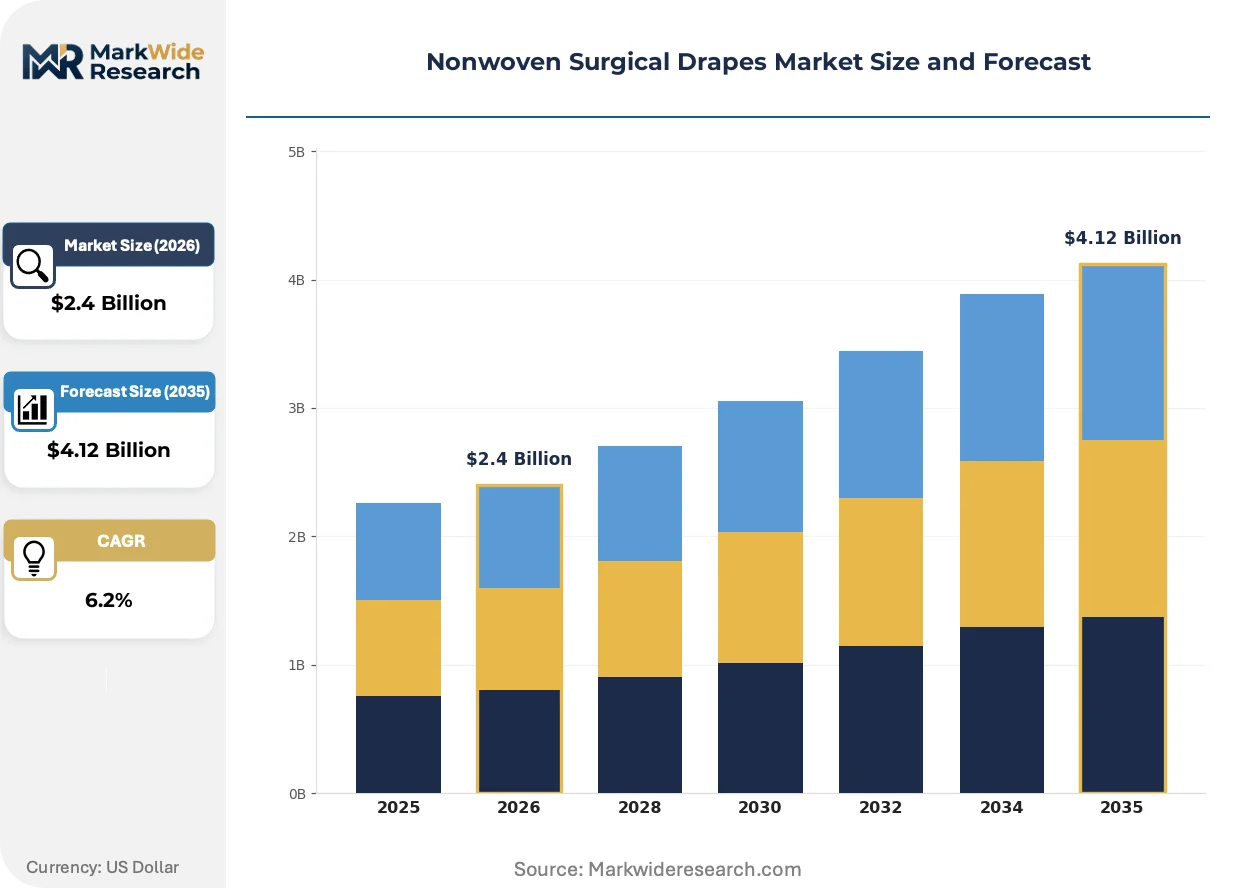
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drapes, Sterile Drapes, Custom Drapes, Disposable Drapes Material: Polypropylene, Polyester, Rayon, SMS End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Application: Cardiac Surgery, Orthopedic Surgery, General Surgery, Surgical Procedures |
| Companies Covered | Medline Industries, Cardinal Health, 3M, Owens & Minor, Mölnlycke Health Care, McKesson Corporation, PAUL HARTMANN AG, Standard Textile, Halyard Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Surgical Drapes Market Strategic Shifts & Innovations
Product development is increasingly focused on the dual objectives of elevating clinical performance in the operating room and addressing the environmental impact of single-use medical products. This balance drives innovation in materials, regulatory strategy, and healthcare purchasing models across the industry.
Antimicrobial-impregnated fabrics represent a significant evolution in drape technology, designed to actively reduce microbial colonization on the drape surface. High-risk surgical specialties, including orthopedics and cardiac surgery, are the primary adopters, seeking to lower surgical site infection rates. The market focus is migrating from passive barrier protection toward active, material-based contributions to infection prevention protocols.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on all medical textiles. This regulation enforces stricter requirements for clinical evidence, risk management, and post-market surveillance. Manufacturers serving the European market are most impacted, investing heavily to update technical documentation and quality management systems to maintain their CE marking and market access.
Consolidated purchasing through Group Purchasing Organizations (GPOs) and large Integrated Delivery Networks (IDNs) is altering buyer behavior. This trend favors suppliers capable of providing broad product portfolios and demonstrating value through supply chain efficiencies, often at the expense of smaller, specialized vendors. This shift in procurement is most pronounced within the United States healthcare system, where GPOs wield substantial influence.
Nonwoven Surgical Drapes Market Segmentation
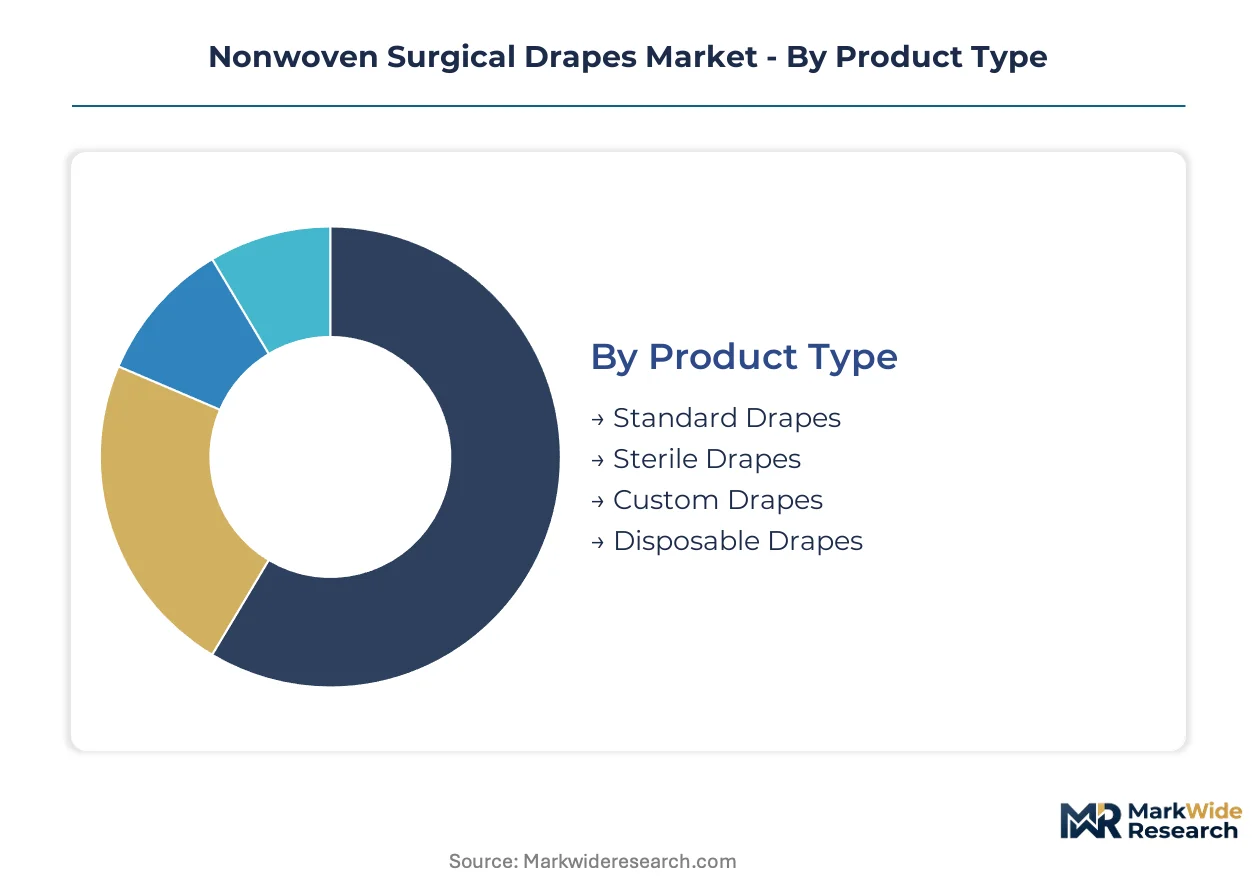
The nonwoven surgical drapes market is intricately segmented, reflecting the diverse clinical demands and operational requirements across healthcare settings. Understanding these distinct segments illuminates varying purchasing patterns and the influence of material innovation on product adoption.
Product Type:
The nonwoven surgical drapes market addresses a diverse use-case spectrum, requiring tailored product types for varying procedural needs and sterility requirements. These distinctions influence material composition and design for optimal barrier protection.
- Custom Drapes:Engineered for specific surgical procedures or robotic systems, these drapes integrate unique cutouts, fenestrations, and adhesive zones. Demand concentrates in specialized surgical centers for complex orthopedic and cardiac interventions, driven by efficiency and precise sterile field maintenance.
- Sterile Drapes:These pre-sterilized products are ready for immediate use in the operating room, eliminating on-site processing steps. Hospitals and ambulatory surgical centers prioritize sterile drapes to meet stringent infection control protocols and reduce turnaround times for procedures.
- Standard Drapes:General-purpose drapes provide a basic sterile barrier for a wide range of common surgical procedures.
- Disposable Drapes:Single-use drapes emphasize convenience and infection control, preventing cross-contamination between patients.
The dominant share belongs to Standard Drapes, while Custom Drapes are expanding most quickly.
Material:
Material selection for nonwoven surgical drapes is driven by the specific application requirements, balancing fluid resistance, breathability, and cost-effectiveness.
- SMS:Spunbond-Meltblown-Spunbond composites offer superior fluid resistance and bacterial barrier properties through multiple layers. High-risk, fluid-intensive procedures in large hospital systems increasingly adopt SMS drapes to minimize surgical site infections.
- Polypropylene:This thermoplastic polymer forms the base for many nonwoven drapes, providing strength and barrier characteristics. Its cost-effectiveness and versatility make it a primary material for general-purpose drapes across various healthcare settings.
- Polyester:Polyester-based drapes offer durability and absorbency, sometimes blended with other fibers for specific performance.
- Rayon:Rayon provides absorbency and softness, often used in drapes where patient comfort is a consideration.
SMS composites are gaining significant traction due to their enhanced performance, while polypropylene remains the foundational material for volume production.
End User:
The volume of nonwoven surgical drape consumption varies significantly across different end-user segments, reflecting distinct operational models and procedural throughput.
- Hospitals:These large healthcare facilities represent the largest end-user segment, conducting a broad spectrum of complex and routine surgical procedures. Their demand for drapes spans all types, from standard to highly specialized custom kits, driven by high patient volumes.
- Ambulatory Surgical Centers:ASCs are rapidly expanding, focusing on outpatient procedures and efficient patient throughput. They show rapid uptake of standardized, single-use draping systems to maintain sterility and optimize procedural workflows.
- Clinics:Smaller clinics utilize drapes for minor surgical interventions and sterile procedures, often prioritizing cost-effective solutions.
- Research Institutions:These entities use surgical drapes for animal studies and experimental procedures requiring sterile environments.
Hospitals continue to drive the majority of demand, but Ambulatory Surgical Centers are demonstrating the steepest expansion trajectory.
Application:
Customer requirements for surgical drapes are highly differentiated by the specific surgical application, necessitating specialized designs for optimal patient outcomes.
- General Surgery:This segment accounts for the largest volume of nonwoven drapes, covering a wide array of common surgical interventions. Standardized, efficient draping solutions are crucial for maintaining sterile fields in high-throughput general operating rooms.
- Orthopedic Surgery:Procedures like joint replacements and spinal surgeries require specialized drapes with enhanced fluid control and robust barrier properties. These drapes often feature integrated pouches and secure adhesive zones to manage blood and irrigation fluids effectively.
- Cardiac Surgery:Highly complex cardiac procedures demand specific drapes designed for chest and vascular access, often with integrated instrument holders.
- Surgical Procedures:This broad category encompasses all interventions requiring a sterile field, driving consistent demand across diverse medical specialties.
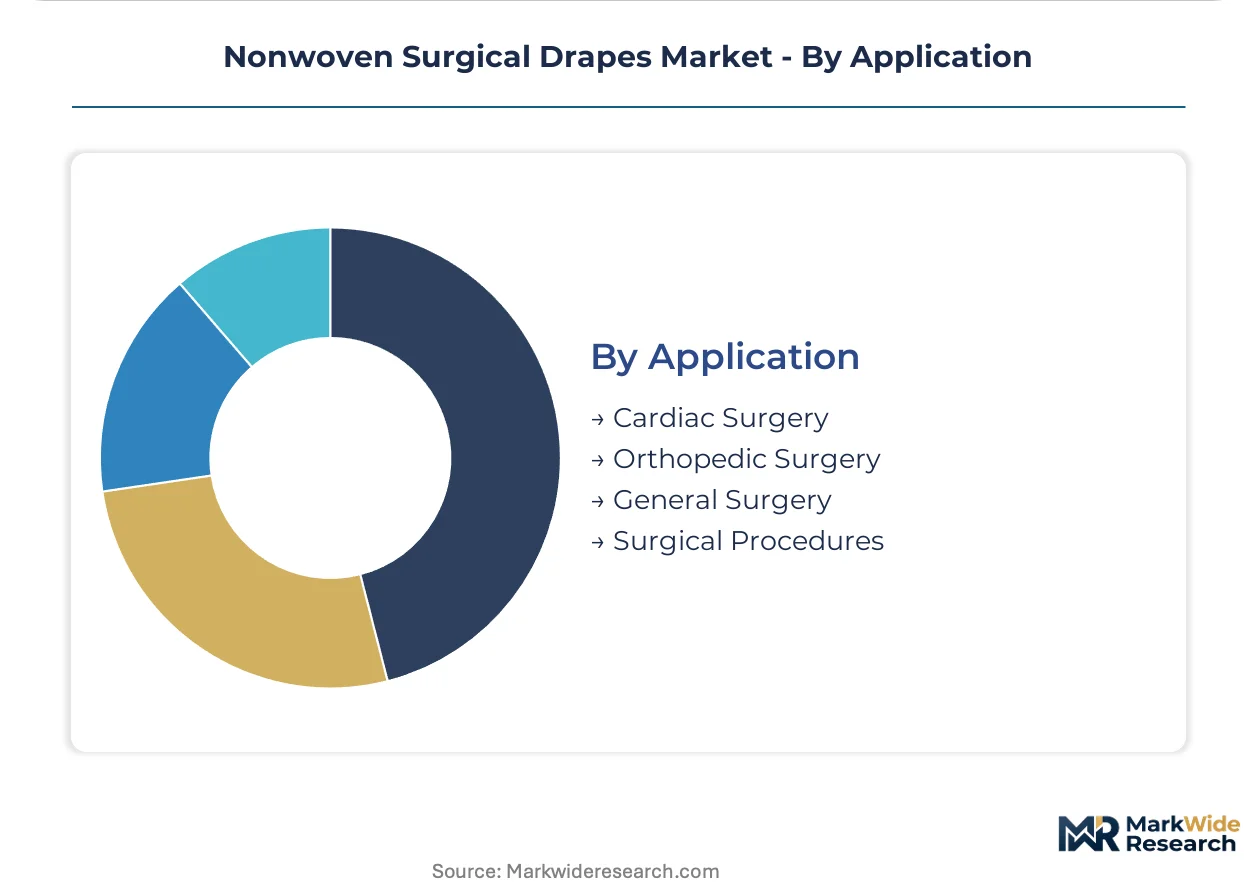
General Surgery represents the largest application volume, while specialized areas like Orthopedic Surgery are increasingly adopting custom solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for nonwoven surgical drapes exhibits concentrated demand from large hospital systems and rapidly expanding ambulatory surgical centers. These key buyer archetypes prioritize both infection prevention and procedural efficiency across diverse geographies. Stringent national healthcare standards further influence product adoption and market growth.
Germany
Germany's robust healthcare system drives significant demand for high-performance nonwoven surgical drapes, particularly for complex procedures. The EU's Medical Device Regulation (MDR) enforces strict quality and safety benchmarks for medical textiles. Manufacturers in the Munich and Berlin healthcare clusters focus on advanced drape solutions to meet these demanding clinical and regulatory requirements.
United States
The United States market sees substantial demand from large integrated delivery networks and expanding ambulatory surgical centers. FDA regulations govern the approval and marketing of all medical devices, including nonwoven drapes. Major medical device clusters in Boston and Texas are centers for innovation in sterile barrier solutions and supply chain optimization.
India
India's rapidly expanding healthcare infrastructure and increasing surgical volumes fuel demand for standardized nonwoven drapes. The CDSCO regulates medical devices, ensuring product quality and safety for the Indian market. Medical device manufacturing hubs in Delhi-NCR and Mumbai are scaling up production to address growing domestic and regional needs.
Brazil
Brazil's growing surgical sector, particularly in private healthcare, generates consistent demand for single-use nonwoven drapes. ANVISA, the national health surveillance agency, sets strict standards for medical device registration and quality control. Healthcare technology companies in São Paulo and Rio de Janeiro are developing localized supply chains for essential surgical consumables.
Japan
Japan's advanced healthcare system and high volume of complex surgical procedures drive demand for premium nonwoven drapes. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous evaluation and approval for medical products. Research and development centers in Tokyo and Osaka focus on integrating advanced materials and smart technologies into surgical textiles.
Nonwoven Surgical Drapes Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in nonwoven surgical drapes. The market exhibits a tiered structure, with large diversified medical supply companies operating alongside niche manufacturers focused on specialized drape solutions. Strategic archetypes include integrated supply chain providers, material innovation leaders, and procedure-specific kit assemblers. Companies pursue strategic partnerships and portfolio diversification to enhance market reach and product offerings.
Among diversified medical supply companies, Medline Industries represents a significant force through its extensive distribution network for custom kits. Cardinal Health exemplifies integrated supply chain solutions, serving large hospital systems with broad product portfolios. Mölnlycke Health Care occupies a position as a specialist in patented adhesive technologies, differentiating its drape offerings through secure placement. These entities anchor various segments of the market, from high-volume general drapes to specialized procedure-specific kits. Their competitive strategies often involve leveraging existing customer relationships and optimizing logistical capabilities.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| 3M |
| Owens & Minor |
| Mölnlycke Health Care |
| McKesson Corporation |
| PAUL HARTMANN AG |
| Standard Textile |
| Halyard Health |
| Others |
Cost & Logistics Intelligence
Polypropylene, the foundational petroleum-derived raw material, significantly influences pricing power downstream. Its cost fluctuations directly impact manufacturer margins and end-user pricing across the nonwoven surgical drapes market.
Pricing Analysis
Long-term cost-plus contracts for nonwoven surgical drapes often feature polypropylene price indexation. Pricing stratifies across standard drapes for clinics and highly customized solutions for specialized surgical centers. Customization level and stringent regulatory compliance, such as FDA and EU MDR standards, drive price differentiation. Pricing softness reflects the negotiating power of Group Purchasing Organizations in the US, while smaller clinics remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms are common within the nonwoven surgical drapes supply chain, particularly for large hospital systems. Supply concentration for advanced materials draws from specialized manufacturers in China, the United States, and Germany. The market relies heavily on polypropylene and specialized adhesive technologies as key inputs. Commodity price volatility for polypropylene represents a significant structural risk. Distribution runs through extensive networks operated by integrated supply chain providers and Group Purchasing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven surgical drapes market is poised for a cyclical recovery, driven by the normalization of elective surgical volumes post-pandemic. Sustained expansion of ambulatory surgical centers further reinforces this positive trajectory.
For Market Incumbents:Entrench existing hospital system relationships through custom kit bundling and integrated supply chain solutions. Invest in advanced composite materials and sustainability initiatives to counter environmental scrutiny and raw material volatility. Strategic partnerships with GPOs can secure long-term contracts against competition from niche manufacturers. Optimizing logistical capabilities provides a key lever for maintaining market share.
For New Entrants and Emerging Players:Establish a beachhead in the rapidly expanding ambulatory surgical center segment with standardized, efficient draping systems. Focus on specialized applications like robotic surgery drapes, designing custom-fit solutions for complex equipment geometries. Penetration opportunities exist in emerging markets, such as India and Brazil, by introducing standardized infection control solutions. A go-to-market strategy emphasizing material innovation and procedural efficiency resonates with these buyers.
For Investors and Strategic Acquirers:Capital is best deployed toward companies specializing in advanced composite materials or integrated supply chain solutions for custom kits. The market for nonwoven surgical drapes demonstrates long-term viability as an essential medical consumable, driven by increasing global surgical volumes. Acquisition targets should include niche manufacturers with patented adhesive technologies or robust sustainability reporting capabilities. The signal to watch is the increasing market penetration of antimicrobial-impregnated fabrics in high-risk surgical specialties.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Sustainable Materials | Addresses environmental scrutiny and evolving EU CSRD standards for manufacturers. |
| Expand Custom Kit Assembly Capabilities | Meets hospital demand for procedural efficiency and Medline Industries' distribution model. |
| Develop Robotic Surgery Drapes | Captures new demand from increasing adoption of robotic surgical systems. |
| Strengthen GPO Partnerships | Secures market access and volume commitments within the US healthcare system. |
| Integrate Smart Drape Technology | Offers product differentiation and added clinical value in high-risk surgeries. |
Research Approach
A standing panel of hospital procurement managers, biomedical engineers, and surgical specialists provided ongoing calibration for market insights. Primary interviews with these industry stakeholders were rigorously validated against secondary sources including FDA filings, EU MDR documentation, and ISO 13485 certifications. This approach combined bottom-up data collection with top-down market sizing, ensuring robust triangulation.
Scenario-bracketing across various economic growth trajectories informed the forecast model's sensitivity analysis. The analytical framework projected market dynamics over the projection horizon, modeling segmentation by product type, material, end user, application, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical growth patterns and projected adoption rates for advanced drapes. Key forecast inputs included surgical procedure volumes and raw material price forecasts.
Stress conditions across raw material price volatility and surgical volume fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope of this study. Forecasts inherently reflect assumptions about market conditions and regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Menthol Patches Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Compression Socks Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Healthcare Adhesive Tapes Market