
 UAE Hospital Supplies Market | 2026-2036
UAE Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Hospital Supplies Market Outlook
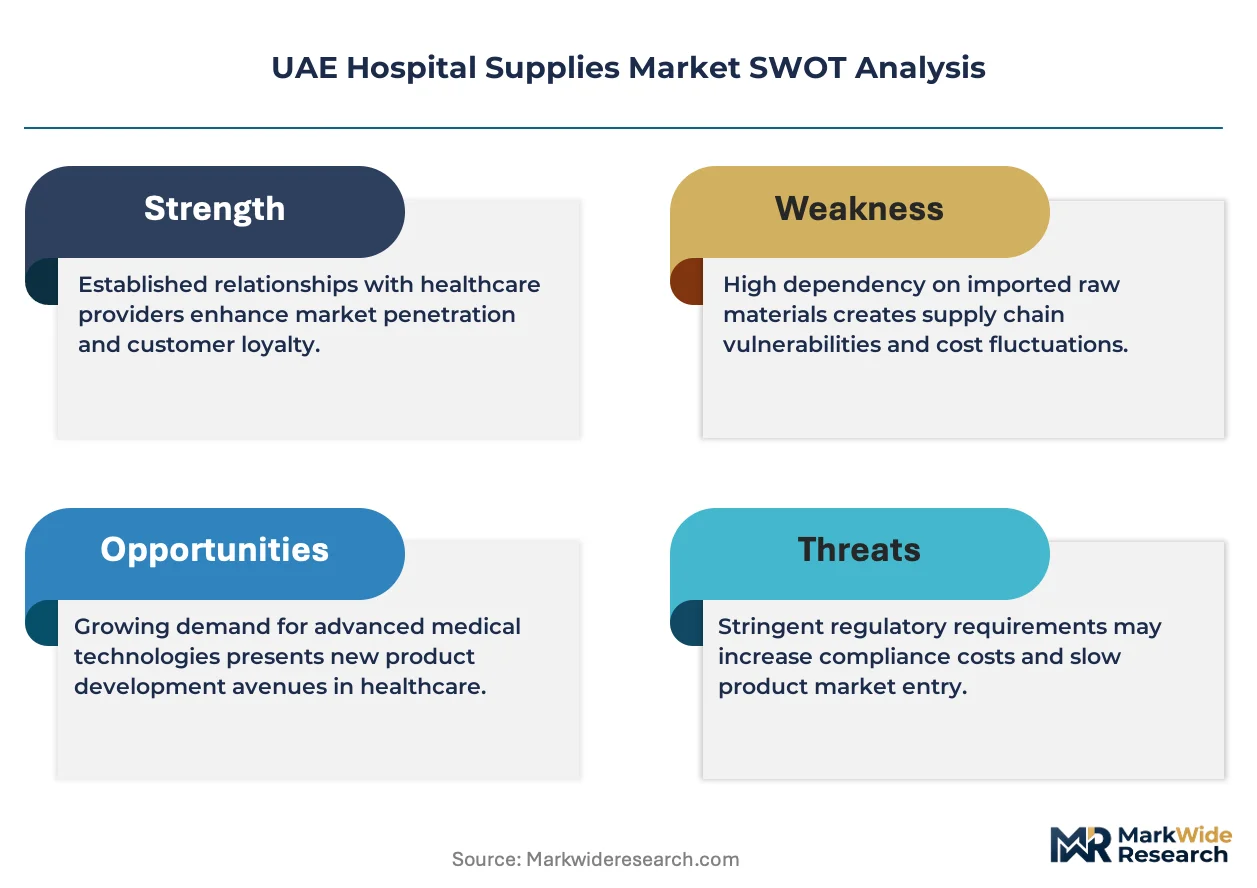
Private hospital expansion across Dubai and Abu Dhabi is realigning procurement priorities toward premium consumables and specialized surgical instruments. Siemens Healthineers leverages its imaging-integrated supply chain to dominate radiology-aligned hospital equipment tenders. B. Braun SE anchors its position through sterile processing systems that private operators favor for infection control compliance. Medtronic plc competes aggressively in interventional consumables where cardiac centers in Dubai Healthcare City concentrate demand.
Hospital supplies encompass the full spectrum of consumable materials, durable medical equipment, furnishings, and precision instruments required for patient diagnosis, treatment, and facility operations, with sterilization-grade polymers and ISO-compliant manufacturing processes ensuring biocompatibility and infection prevention. Consumables capture recurring revenue streams through high-velocity restocking cycles tied to surgical volumes and inpatient census. Equipment segments require substantial capital deployment but yield long-term service contracts and upgrade pathways. Surgical instruments represent a margin-dense category where single-use disposable formats displace traditional reprocessing in premium facilities.
MOHAP enforces device registration and quality certification protocols that filter non-compliant imports from entering UAE hospital supply chains. The UAE's alignment with GCC standardization requirements adds a secondary compliance layer for cross-border distributors. Stakeholders must monitor how MOHAP's evolving digital tracking mandates for high-risk device categories reshape supplier qualification timelines and inventory transparency obligations.
Market Dynamics
MOHAP's mandatory quality certification protocols are compressing supplier qualification timelines and forcing procurement departments to rebuild vendor rosters around ISO-compliant manufacturing footprints, fundamentally restructuring how hospital supplies enter UAE distribution channels.
Growth Catalysts
- Cardiac center concentration:Interventional consumables demand concentrates in Dubai Healthcare City facilities performing complex catheterization procedures, pulling advanced guidewires and stent delivery systems into the emirate.
- MOHAP device registration mandates:The regulator's digital tracking requirements for high-risk categories are accelerating inventory transparency investments across hospital supply chains.
- Sterile processing automation:Private operators in Abu Dhabi favor automated sterile processing systems to meet infection control compliance standards and reduce reprocessing labor costs.
Market Restraints
- Polymer feedstock volatility:Sterilization-grade polymer prices fluctuate with petrochemical input costs, squeezing margins on single-use surgical consumables.
- European supplier concentration:Premium surgical instrument sourcing clusters with German and Swiss manufacturers, exposing UAE buyers to euro-denominated pricing and extended lead times.
- Reprocessing capability gaps:Limited local capacity for ISO-validated instrument reprocessing forces reliance on imported sterile disposable formats at premium price points.
Strategic Opportunities
- Northern emirate hospital buildouts:Ras Al Khaimah and Fujairah healthcare infrastructure expansion creates first-mover advantage for distributors establishing cold-chain logistics outside Dubai-Abu Dhabi corridors.
- GCC cross-border standardization:Alignment with Gulf Cooperation Council technical regulations opens consolidated procurement pathways into Saudi and Qatari markets.
- Imaging-integrated supply contracts:Radiology-aligned equipment tenders increasingly bundle contrast media, injectors, and maintenance services, favoring suppliers with full modality portfolios.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital supply chains lack sufficient locally trained specialists to validate complex device installations and manage vendor qualification documentation.
- Certification timeline compression:MOHAP's evolving documentation requirements for novel device categories extend product registration cycles beyond commercial planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Hospital Supplies Market |
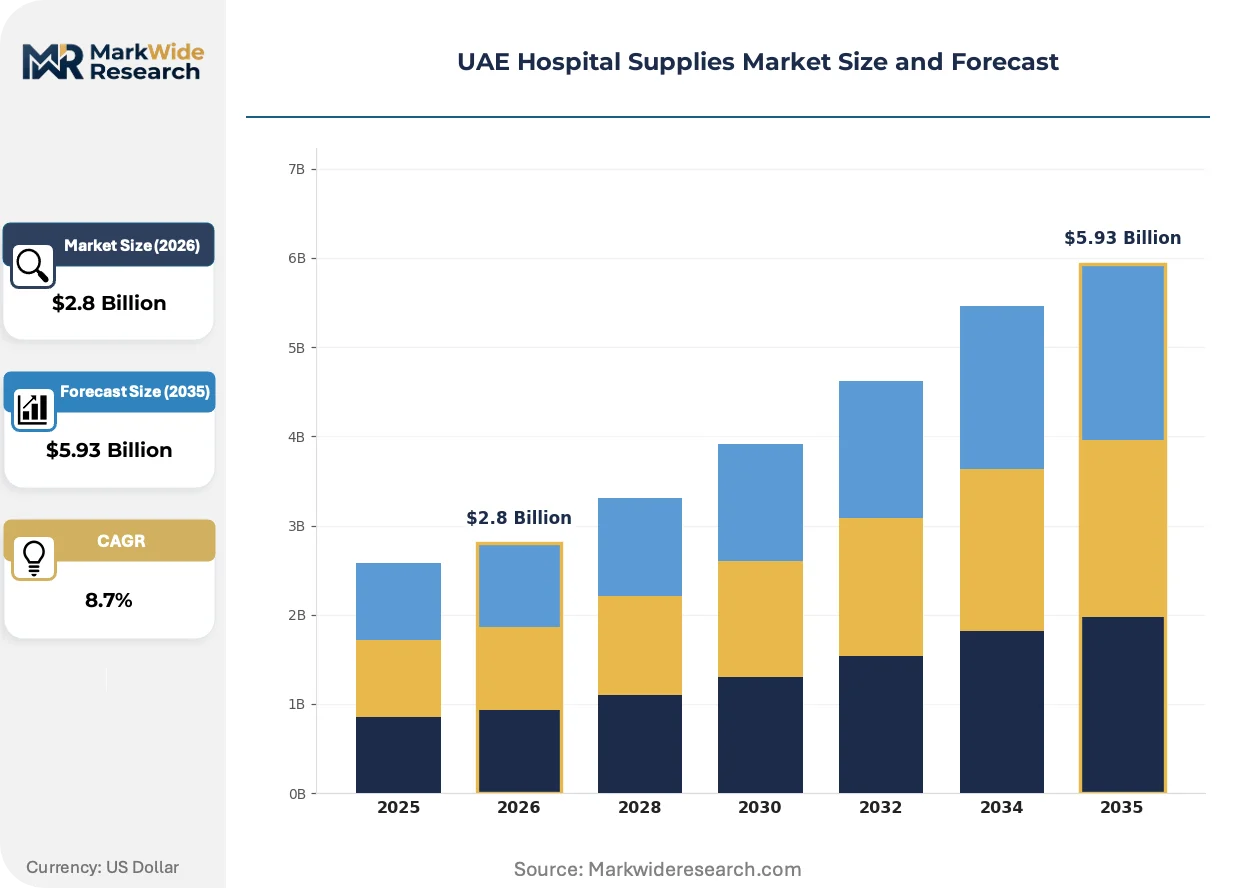
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Equipment, Furniture, Surgical Instruments End User: Public Hospitals, Private Hospitals, Specialty Clinics, Rehabilitation Centers Supply Channel: Direct Sales, Distributors, Online Retail, Medical Supply Stores Application: Inpatient Care, Outpatient Care, Surgical Procedures, Emergency Services |
| Companies Covered | Johnson & Johnson, Siemens Healthineers, B. Braun SE, Philips Healthcare, GE Healthcare, Baxter International Inc., Boston Scientific Corporation, Stryker Corporation, Medtronic plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Hospital Supplies Market Strategic Shifts
Single-use disposable formats are displacing traditional reprocessing workflows across premium UAE facilities, while regulatory digitization and procurement centralization reshape how suppliers access hospital buyers.
Smart packaging embedded with temperature and sterilization indicators is overtaking conventional labeling in high-value consumables. Dubai's private cardiac and orthopedic centers adopt these formats fastest, demanding real-time chain-of-custody documentation. The technology is compressing liability exposure for distributors while raising baseline packaging costs.
MOHAP's phased implementation of unique device identification tracking mirrors FDA UDI requirements and pressures importers to upgrade serialization infrastructure. Manufacturers serving both US and UAE markets leverage common labeling platforms, but local distributors face capital outlays for scanning and database integration. High-risk implantable categories face the earliest compliance deadlines.
Hospital group purchasing organizations in Abu Dhabi and Dubai consolidate procurement authority previously held by individual facility materials managers. Centralized tenders favor suppliers offering multi-year service bundles over transactional consumables vendors. The shift is most visible among the three largest private chains, which now control a disproportionate share of surgical volume.
UAE Hospital Supplies Market Segmentation
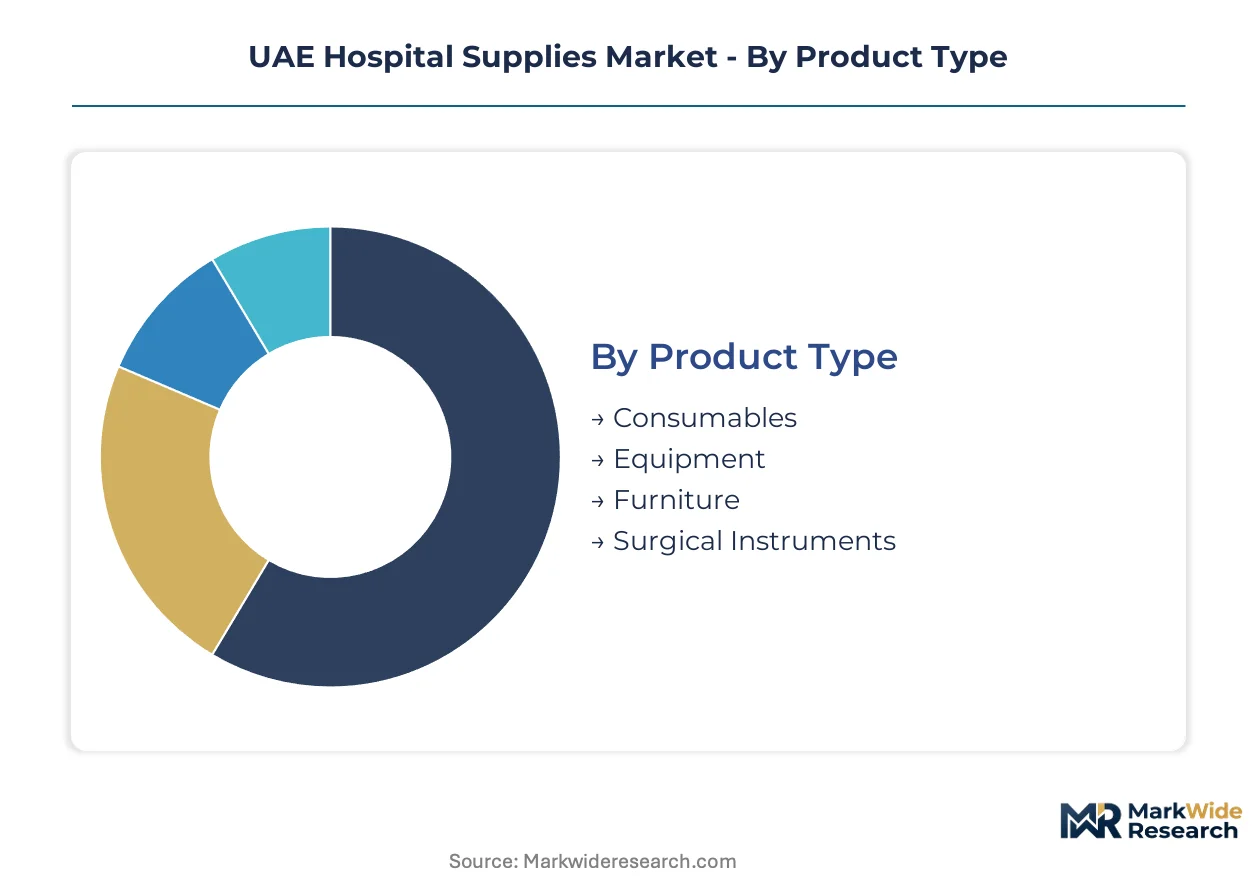
Segmentation reveals how procurement capital, regulatory compliance, and clinical workflow requirements diverge across the UAE hospital supplies landscape. Capital-intensive equipment segments demand long financing cycles and MOHAP certification rigor, while consumables generate recurring revenue through high-velocity restocking tied to surgical volumes.
Product Type:
Equipment segments absorb the heaviest upfront capital deployment, with imaging systems and sterile processing infrastructure requiring multi-year financing structures that reshape hospital balance sheets.
- Consumables:Single-use sterile polymers, wound dressings, and diagnostic reagents dominate procurement velocity. Dubai Healthcare City cardiac centers pull advanced guidewires and stent delivery systems into concentrated demand clusters, with MOHAP's digital tracking mandates accelerating inventory transparency investments.
- Equipment:Capital goods span imaging modalities, patient monitoring systems, and sterilization infrastructure. Abu Dhabi's private hospital chains favor automated sterile processing systems to meet infection control compliance and compress reprocessing labor costs.
- Furniture:Patient beds, surgical tables, and facility furnishings carry lower technical specification burdens but require GCC standardization alignment for cross-border procurement consolidation.
- Surgical Instruments:Precision-manufactured reusable and disposable formats serve interventional procedures. Single-use disposable formats displace traditional reprocessing in premium Dubai and Abu Dhabi facilities, compressing liability exposure while raising per-procedure supply costs.
Most installed capacity flows through Consumables. Expansion is steepest in Equipment as private hospital chains modernize infrastructure.
End User:
Customer-type concentration determines pricing power, with consolidated private chains extracting volume discounts that fragment procurement economics for standalone facilities.
- Public Hospitals:Government-funded facilities operate under centralized MOHAP procurement frameworks with extended tender cycles and stringent local content requirements. Budget constraints favor standard-grade consumables over premium single-use formats.
- Private Hospitals:Dubai and Abu Dhabi chains control disproportionate surgical volume and consolidate purchasing authority through group purchasing organizations. These entities favor multi-year service bundles and automated sterile processing systems.
- Specialty Clinics:Concentrated in Dubai Healthcare City, these facilities drive demand for interventional consumables and imaging-integrated supply contracts that bundle contrast media with maintenance services.
- Rehabilitation Centers:Post-acute facilities require durable medical equipment and mobility aids, with procurement patterns tied to patient discharge flows from acute care settings.
Private Hospitals command the largest procurement budgets. Specialty Clinics are climbing the fastest as Dubai Healthcare City expands interventional capacity.
Supply Channel:
Channel selection reflects product complexity, with capital equipment demanding direct manufacturer relationships while consumables flow through distributor networks optimized for cold-chain logistics.
- Direct Sales:Imaging systems and sterile processing infrastructure move through manufacturer-direct contracts that bundle installation, training, and long-term service agreements. Siemens Healthineers leverages this channel for radiology-aligned tenders.
- Distributors:Regional logistics networks dominate consumables and surgical instruments, with Northern emirate expansion creating first-mover opportunities outside Dubai-Abu Dhabi corridors.
- Online Retail:Digital procurement platforms gain traction for standardized consumables and non-critical furnishings, though high-risk implantables remain excluded from e-commerce channels under MOHAP guidelines.
- Medical Supply Stores:Local retail points serve smaller clinics and outpatient facilities with immediate-need consumables, carrying limited inventory depth for specialized surgical formats.
Distributors handle the majority of transaction volume. Direct Sales is expanding most quickly as private chains consolidate capital equipment procurement.
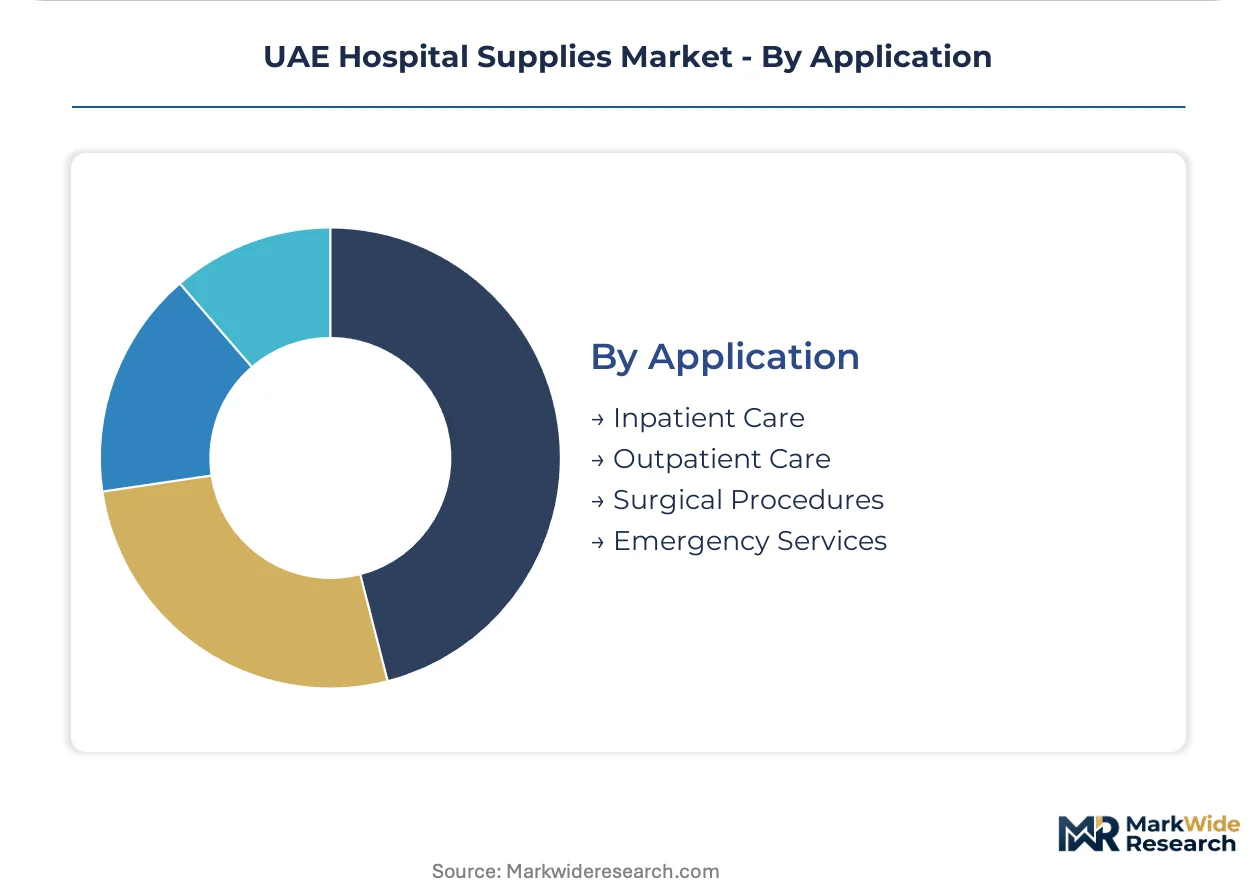
Application:
Application-based demand correlates with reimbursement structures and clinical throughput, with surgical procedures generating the highest per-case supply intensity.
- Inpatient Care:Extended-stay facilities consume wound care products, patient monitoring consumables, and durable equipment. Census fluctuations drive restocking velocity across Dubai and Abu Dhabi hospital networks.
- Outpatient Care:Diagnostic and minor procedure settings favor rapid-turn consumables with lower sterilization requirements. Volume concentrates in specialty clinic clusters with streamlined supply chains.
- Surgical Procedures:Operating rooms generate peak supply intensity through sterile drapes, sutures, and interventional consumables. Cardiac and orthopedic centers in Dubai Healthcare City pull premium single-use instruments into concentrated demand.
- Emergency Services:Trauma and acute response settings require immediate-availability consumables and portable equipment, with supply redundancy mandates raising inventory carrying costs.
Surgical Procedures absorb the highest supply expenditure per encounter. Outpatient Care is gaining share fastest as same-day procedures expand across private networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Healthcare City anchors procurement intensity for interventional consumables and imaging-integrated supply chains. Abu Dhabi's private hospital chains consolidate purchasing authority through group purchasing organizations. Northern emirates present first-mover opportunities for distributors establishing cold-chain logistics outside traditional corridors.
Dubai
Cardiac and orthopedic centers in Dubai Healthcare City pull premium single-use instruments into concentrated demand clusters. MOHAP's digital tracking mandates for high-risk device categories accelerate inventory transparency investments across private hospital supply chains. The Dubai Science Park corridor hosts medical device distributors optimizing serialization infrastructure for unique device identification compliance.
Abu Dhabi
Private hospital chains favor automated sterile processing systems to meet infection control compliance standards and compress reprocessing labor costs. The emirate's health authority enforces stringent local content requirements in centralized procurement frameworks. Yas Island medical clusters attract capital equipment tenders bundling installation, training, and long-term service agreements.
Sharjah
Mid-tier private hospitals and specialty clinics drive demand for standardized consumables and diagnostic reagents. The emirate's healthcare regulator aligns with MOHAP certification protocols while maintaining distinct tender documentation requirements. Industrial zones near Sharjah International Airport support regional logistics hubs serving Northern Emirates distribution networks.
Northern Emirates
Ras Al Khaimah and Fujairah healthcare infrastructure expansion creates first-mover advantage for distributors establishing cold-chain logistics. Government-funded hospital buildouts operate under extended tender cycles with stringent budget constraints favoring standard-grade consumables. New medical cities in development phases present long-term equipment procurement pipelines for imaging modalities and patient monitoring systems.
UAE Hospital Supplies Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek to bundle equipment, consumables, and maintenance services into multi-year contracts. The vendor base organizes around three tiers: multinational conglomerates with full modality portfolios, regional distributors with cold-chain logistics specialization, and niche specialists in sterile processing or interventional consumables. Portfolio diversification and geographic expansion represent the dominant competitive moves as players seek to capture Northern Emirates buildouts and GCC cross-border procurement consolidation.
Within the multinational conglomerate tier, Siemens Healthineers, B. Braun SE, and Medtronic plc exemplify divergent strategic positions. Siemens Healthineers occupies a position anchored in imaging-integrated supply chains, representing the archetype of modality-driven tender participation. B. Braun SE exemplifies the sterile processing systems specialization that private operators favor for infection control compliance. Medtronic plc sits within the interventional consumables vector where cardiac center concentration in Dubai Healthcare City generates disproportionate demand pull.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Siemens Healthineers |
| B. Braun SE |
| Philips Healthcare |
| GE Healthcare |
| Baxter International Inc. |
| Boston Scientific Corporation |
| Stryker Corporation |
| Medtronic plc |
| Others |
Value Chain & Pricing Dynamics
Sterilization-grade polymer feedstock costs cascade through distributor markups into hospital procurement tiers, with petrochemical price volatility compressing margins on single-use surgical consumables before reaching Abu Dhabi and Dubai purchasing committees.
Pricing Analysis
Distributor margins absorb the steepest compression as MOHAP certification costs and euro-denominated supplier invoices squeeze middle-tier logistics providers. Three-tier pricing structure across premium, standard, and economy levels separates ISO-validated sterile disposables from reprocessed instruments and basic consumables. Pricing pressure stems from polymer feedstock volatility and European supplier concentration, with public hospitals exhibiting highest price sensitivity while private cardiac centers in Dubai Healthcare City prioritize compliance over unit cost.
Supply Chain Analysis
Air freight costs from Germany and Switzerland dominate landed pricing for precision surgical instruments, with Dubai International Airport serving as the primary customs clearance node. Supply concentrates in German, Swiss, and US manufacturing hubs for high-value interventional consumables, drawing from sterilization-grade polymer resins, medical-grade stainless steel, and specialized coating chemistries. Single-source vulnerability runs through European instrument reprocessing equipment, while distribution flows through regional logistics networks with cold-chain specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's phased unique device identification mandates function as a regulatory compounder, accelerating inventory transparency investments and favoring suppliers with pre-built serialization infrastructure.
For Market Incumbents: Acquire UAE-based distributor networks with established MOHAP compliance documentation to defend against emerging regional cold-chain specialists. Consolidate sterile processing system installations across Abu Dhabi private chains before certification timeline compression eliminates late entrants. Backward integration into polymer compounding hedges feedstock volatility exposure. For New Entrants and Emerging Players: Launch via direct hospital system partnerships in Ras Al Khaimah and Fujairah, where government-funded buildouts lack entrenched supplier relationships. Target standardized consumables segments where public hospital budget constraints favor cost-efficient alternatives. Penetrate through imaging-integrated service bundling that mimics Siemens Healthineers' radiology-aligned tender participation. For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical engineering talent scarcity extends vendor qualification timelines beyond commercial planning horizons. Five-to-ten year viability favors distributors with Northern Emirates logistics footprints and GCC cross-border standardization alignment. Monitor MOHAP digital tracking mandate implementation velocity as inflection indicator for serialization infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Certification Investment | Accelerates market access timelines for high-risk device categories against non-compliant imports. |
| Imaging-Integrated Supply Contracting | Bundles contrast media, injectors, and maintenance services into multi-year hospital system agreements. |
| Northern Emirates Logistics Buildout | Captures first-mover advantage in Ras Al Khaimah and Fujairah healthcare infrastructure expansion. |
| Sterile Processing Automation Partnership | Addresses Abu Dhabi private hospital infection control compliance and labor cost reduction priorities. |
| GCC Cross-Border Standardization Alignment | Opens consolidated procurement pathways into Saudi and Qatari markets under unified technical regulations. |
Study Parameters
Coverage spans Dubai, Abu Dhabi, Sharjah, and Northern Emirates, with primary inputs from each emirate's hospital procurement landscape. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committees, and MOHAP regulatory affairs specialists combined with secondary validation from hospital procurement databases, GPO contract filings, customs import records, and MOHAP device registration disclosures. Bottom-up facility-level demand modeling triangulated against top-down market sizing.
Granularity-level modeling captured product type, end user, supply channel, and application dimensions at the emirate level, with surgical procedure intensity and inpatient census driving consumables velocity assumptions. CAGRs derived from surgical volume projections, private hospital expansion pipelines, and regulatory compliance cost trajectories. Forecast inputs incorporated MOHAP digital tracking mandate implementation schedules and polymer feedstock price sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended MOHAP certification delays or accelerated GCC standardization harmonization. Forecasts reflect documented assumptions regarding surgical volume growth, private hospital capex cycles, and regulatory implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Bags Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Global Lancets Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Safety Needles Market
Medical Supplies
Drosophila Bottles Market