
 Push-In Plug Vials Market | 2026-2036
Push-In Plug Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Push-In Plug Vials Market Analytics
A capital-intensity divergence between automated high-throughput molders and manual specialty producers is unwinding legacy competitive boundaries in vial manufacturing. Thermo Fisher Scientific leverages integrated life sciences distribution to bundle vial sales with analytical instruments. Gerresheimer AG anchors European pharmaceutical packaging through captive borosilicate glassworks and dedicated sterile filling partnerships. Schott AG differentiates via FIOLAX glass chemistry expertise and pre-sterilized ready-to-use vial formats.
Push-in plug vials are cylindrical primary containers sealed with elastomeric or plastic closures that snap into place without crimping, typically manufactured from Type I borosilicate glass or cyclic olefin polymers to minimize ionic leaching and maintain headspace integrity for parenteral and diagnostic applications. Glass vials dominate biologic drug containment due to chemical inertness and regulatory familiarity, while plastic vials gain traction in point-of-care diagnostic kits where breakage resistance and reduced shipping mass matter. Research laboratories represent a concentrated end-user segment where small-lot flexibility and rapid format switching override unit cost minimization.
The FDA enforces container closure integrity standards under USP <1207>, while the EU MDR and EMA guidelines mandate extractables profiling for elastomeric plug materials in drug-contact applications. These frameworks elevate testing documentation burdens for vial-plug combinations, favoring suppliers with pre-validated component kits and Drug Master File submissions. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters to anticipate specification convergence or divergence that reshapes qualification costs and regional sourcing strategies.
Market Dynamics
Container closure integrity testing under USP 1207 and EU MDR extractables mandates are forcing manufacturers to consolidate validation documentation, compressing qualification timelines and elevating barriers for unbundled component suppliers.
Growth Catalysts
- Biologic drug containment demand:Monoclonal antibody and cell therapy pipelines require borosilicate vials with elastomeric plug compatibility, driving procurement of pre-validated Drug Master File kits.
- EU MDR implementation:The Medical Device Regulation's tightened leachables testing requirements favor suppliers with captive glassworks and in-house polymer chemistry capabilities.
- Diagnostic kit decentralization:Point-of-care testing expansion creates pull for cyclic olefin polymer vials with snap-fit closures that withstand temperature excursions during field deployment.
Market Restraints
- Raw material concentration:Specialized borosilicate glass feedstock production clusters in Germany and limited qualified elastomer compounders create single-source vulnerability for sterile vial manufacturers.
- Energy-intensive forming:Continuous melting furnaces for Type I glass consume natural gas volumes that expose margins to European energy price volatility.
- Regulatory documentation burden:FDA container closure guidance and EMA extractables protocols require 18-24 month qualification cycles that freeze supplier switching.
Strategic Opportunities
- Pre-sterilized ready-to-use formats:Fill-finish contractors seek terminally sterilized nested vial-plug combinations that eliminate in-house washing and depyrogenation capital expenditure.
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q3D elemental impurity guidelines creates opening for suppliers offering pre-validated vial systems to domestic injectable producers.
- Digital supply chain integration:Serialization mandates under EU Falsified Medicines Directive and US DSCSA drive demand for vial suppliers with integrated track-and-trace data infrastructure.
Industry Challenges
- Cleanroom manufacturing scale-up:ISO 14644 Class 7 filling environments require capital deployment that strains mid-tier producers seeking sterile vial market entry.
- Pharmacopeial harmonization gaps:Divergent USP, EP, and JP extractables testing protocols force redundant analytical work that extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Push-In Plug Vials Market |
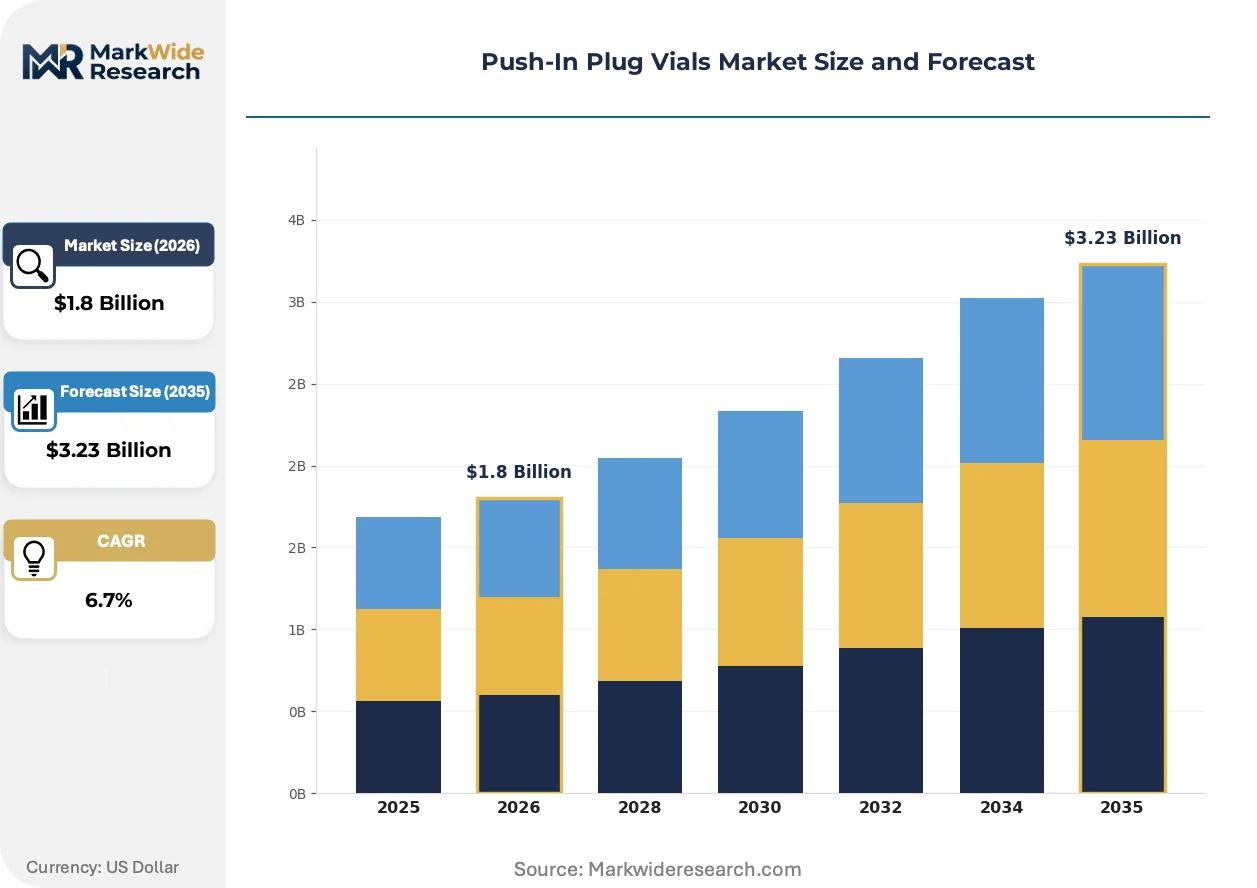
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Vials, Glass Vials, Sterile Vials, Non-Sterile Vials End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Application: Vaccines, Injectable Drugs, Diagnostic Reagents, Laboratory Samples Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Thermo Fisher Scientific, International Scientific Supplies, Gerresheimer AG, Schott AG, West Pharmaceutical Services, Nipro Corporation, Chromatography Research Supplies, Scientific Glass Laboratories, ProSciTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Push-In Plug Vials Market Evolving Landscape
Material substitution and regulatory convergence are compressing traditional competitive boundaries between glass and polymer vial formats while reshaping qualification workflows across pharmaceutical and diagnostic end-uses.
Cyclic olefin polymer vials with integrated snap-fit closures are supplanting borosilicate formats in temperature-sensitive diagnostic shipments. Point-of-care testing manufacturers adopt these polymer systems to reduce breakage losses and cut shipping mass by 60 percent. The shift is compressing glass vial demand in non-parenteral applications while opening polymer supply chain bottlenecks.
EMA's updated guidelines on elemental impurities in pharmaceutical packaging mandate ICP-MS screening for glass and elastomer components. Manufacturers must now submit comprehensive migration data across accelerated aging protocols. Small-scale vial molders without captive analytical laboratories face outsourcing costs that erode margin on low-volume specialty formats.
Consolidated procurement of pre-validated vial-plug combinations is displacing component-level sourcing at major biopharma fill-finish operations. Contract manufacturing organizations now specify nested, terminally sterilized systems that arrive ready for aseptic processing. This preference shift concentrates purchasing power with integrated packaging suppliers in Germany and Switzerland.
Push-In Plug Vials Market Segmentation
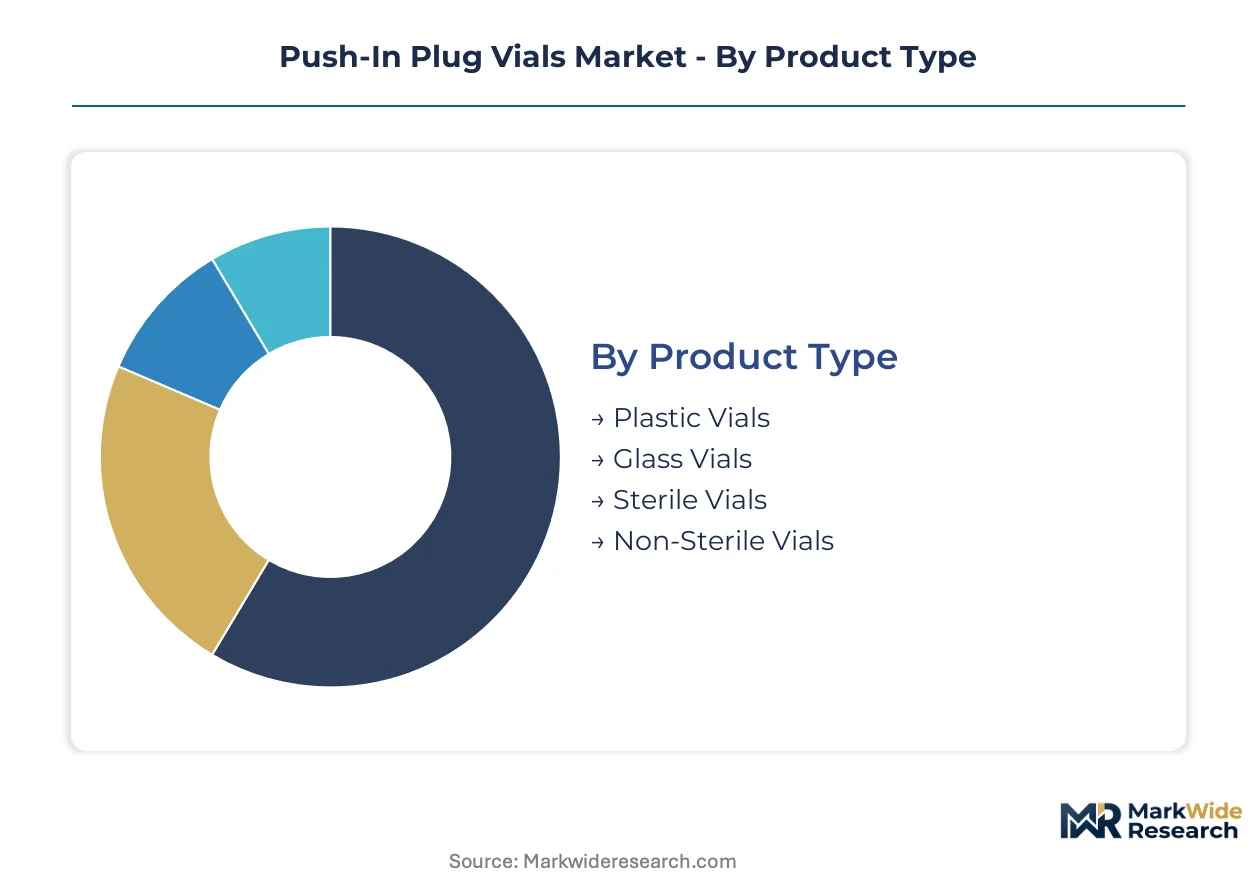
Segmentation in push-in plug vials reveals how material chemistry, sterility grade, and end-use specifications fragment procurement patterns across pharmaceutical and diagnostic supply chains. Understanding these divisions exposes where validation burdens concentrate and where format flexibility commands premium positioning.
Product Type:
Domestic production clusters in Germany and Switzerland anchor glass vial supply, while plastic vial sourcing increasingly draws from Asian polymer compounders serving export markets.
- Plastic Vials:Cyclic olefin polymer and polypropylene formats withstand temperature excursions during field deployment. Diagnostic kit manufacturers in the United States and point-of-care developers in India drive procurement for breakage-resistant alternatives to glass.
- Glass Vials:Type I borosilicate compositions from Gerresheimer and Schott facilities in Germany dominate biologic drug containment. FDA USP Type I standards and EMA extractables mandates cement borosilicate's position in parenteral applications despite energy-intensive forming costs.
- Sterile Vials:Terminally sterilized, ready-to-use formats eliminate in-house washing and depyrogenation at fill-finish contractors.
- Non-Sterile Vials:Research and compounding pharmacies accept bulk formats requiring downstream processing, trading convenience for unit cost reduction.
Glass vials hold the largest share; momentum sits with sterile-ready formats that compress qualification timelines.
End User:
Procurement scale varies dramatically: pharmaceutical companies negotiate multi-year Drug Master File contracts while research laboratories prioritize small-lot flexibility over unit economics.
- Pharmaceutical Companies:Fill-finish operations at Merck KGaA, Pfizer, and Roche facilities specify pre-validated vial-plug combinations with complete extractables documentation. CDSCO alignment with ICH Q3D in India and FDA container closure guidance in the US extend qualification cycles to 18-24 months.
- Biotechnology Firms:Cell therapy and monoclonal antibody developers require borosilicate compatibility with elastomeric closures for sensitive biologics. Cambridge, Massachusetts and Basel, Switzerland clusters concentrate demand for nested, terminally sterilized systems.
- Research Laboratories:Academic and CRO facilities order non-sterile formats in variable lot sizes with rapid format switching.
- Hospitals:Compounding pharmacies and clinical trial sites source smaller volumes with less stringent documentation requirements.
Pharmaceutical companies command volume concentration; biotechnology firms are expanding most quickly as cell therapy pipelines mature.
Application:
Regulatory stringency stratifies sharply: parenteral drug applications face USP 1207 container closure integrity mandates while diagnostic reagents operate under less burdensome quality frameworks.
- Vaccines:Temperature-stable borosilicate vials with elastomeric closures protect mRNA and viral vector formulations through cold chain distribution. UNICEF and Gavi procurement specifications drive demand for pre-qualified, multi-dose formats in low-resource settings.
- Injectable Drugs:Biologics and small-molecule parenterals require Type I glass or validated polymer alternatives with documented leachables profiles. EMA's updated elemental impurities guidelines now mandate ICP-MS screening across accelerated aging protocols.
- Diagnostic Reagents:Point-of-care and laboratory assays favor cyclic olefin polymer vials for reduced shipping mass and breakage resistance.
- Laboratory Samples:Research and clinical trial specimen collection accepts non-sterile, non-validated formats where cost minimization overrides regulatory documentation.
Injectable drugs hold the largest share; diagnostic reagents are climbing the fastest as decentralized testing expands.
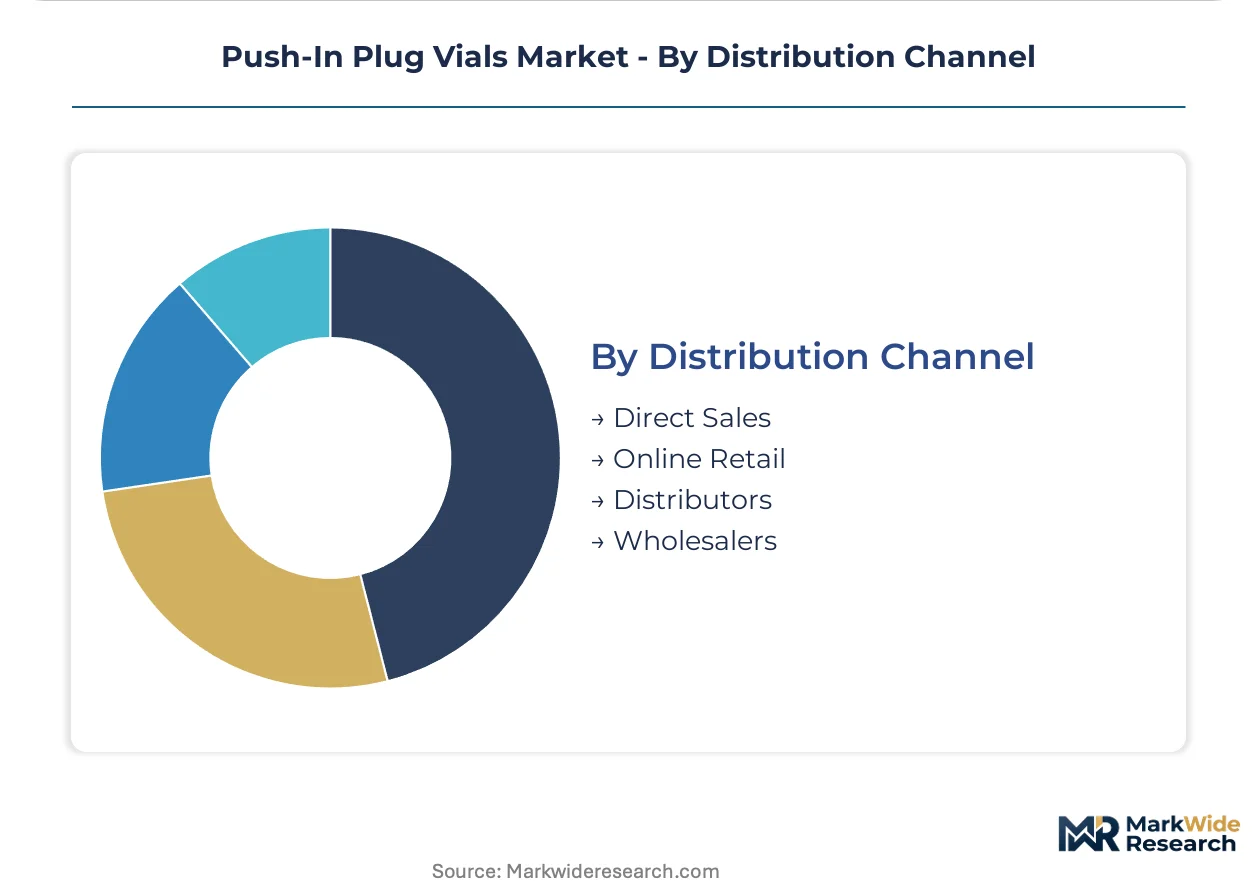
Distribution Channel:
Channel selection tracks customer scale and technical complexity: direct relationships dominate validated pharmaceutical supply while distributors serve fragmented research demand.
- Direct Sales:Integrated packaging suppliers like Gerresheimer and Schott negotiate multi-year contracts with fill-finish contractors for nested vial-plug systems. Technical service teams co-develop validation protocols with pharmaceutical quality departments.
- Distributors:VWR, Thermo Fisher Scientific, and regional laboratory supply houses aggregate fragmented research laboratory demand across North America and Europe.
- Online Retail:E-commerce platforms serve small-scale compounding pharmacies and independent researchers with standard catalog formats.
- Wholesalers:Regional pharmaceutical wholesalers handle generic injectable manufacturers with less specialized packaging requirements.
Direct sales capture the largest share; distributors are gaining share fastest as research laboratory procurement consolidates through integrated supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes push-in plug vials predominantly for sterile biologic containment, while the United States and India diverge toward diagnostic and research applications where breakage resistance and cost flexibility override validation documentation.
Germany
Gerresheimer and Schott anchor specialized borosilicate production clusters in Mainz and Mitterteich, supplying pre-validated Drug Master File kits to European fill-finish contractors. The EU MDR's tightened leachables testing requirements favor domestic suppliers with captive glassworks and in-house polymer chemistry capabilities. Bavaria's pharmaceutical packaging corridor concentrates sterile vial output for monoclonal antibody and cell therapy pipelines.
United States
Point-of-care diagnostic manufacturers in Massachusetts and California drive procurement of cyclic olefin polymer vials with snap-fit closures for temperature-stable field deployment. FDA container closure guidance under USP 1207 extends qualification cycles to 18-24 months, freezing supplier relationships with integrated packaging vendors. Cambridge's biotechnology cluster concentrates demand for nested, terminally sterilized systems from fill-finish contractors.
India
Domestic injectable producers in Maharashtra and Gujarat seek pre-validated vial systems as CDSCO aligns with ICH Q3D elemental impurity guidelines. The country's pharmaceutical manufacturing expansion creates openings for suppliers offering Drug Master File submissions to contract manufacturing organizations. Hyderabad's vaccine production hub generates concentrated demand for multi-dose borosilicate formats with elastomeric plug compatibility.
Switzerland
Swissmedic's stringent packaging regulations reinforce Basel's position as a validation-intensive procurement center for biologics containment. Roche and Novartis fill-finish operations specify nested vial-plug combinations with complete extractables documentation across accelerated aging protocols. The country's pharmaceutical packaging suppliers leverage proximity to German borosilicate feedstock while maintaining distinct regulatory compliance frameworks.
Japan
PMDA's harmonization with ICH quality guidelines drives pharmaceutical companies toward pre-validated component kits with documented container closure integrity. The Kanto region's biotechnology corridor concentrates demand for sterile-ready formats that compress qualification timelines for monoclonal antibody developers. Osaka's diagnostic manufacturers increasingly source cyclic olefin polymer alternatives for decentralized testing applications.
Push-In Plug Vials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding pre-validated Drug Master File relationships and the lower tier competing on small-lot flexibility for research applications. German glassworks operators and diversified life sciences distributors occupy distinct strategic positions, while mid-tier molders face margin compression from energy-intensive forming costs and outsourced analytical testing burdens. Consolidation pressures favor suppliers with captive borosilicate production and in-house sterilization capabilities. Strategic partnerships between vial manufacturers and fill-finish contractors are displacing component-level sourcing.
Among diversified life sciences conglomerates, Thermo Fisher Scientific exemplifies the integrated distribution archetype, bundling vial procurement with analytical instruments and laboratory supply contracts. German glass specialists Gerresheimer AG and Schott AG anchor the premium-tier vector, representing the captive-manufacturing archetype through specialized borosilicate chemistry expertise and dedicated sterile filling partnerships. These three occupy positions that reflect divergent competitive strategies: broad portfolio leverage versus deep vertical control over material feedstock and forming processes.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| International Scientific Supplies |
| Gerresheimer AG |
| Schott AG |
| West Pharmaceutical Services |
| Nipro Corporation |
| Chromatography Research Supplies |
| Scientific Glass Laboratories |
| ProSciTech |
| Others |
Value Network & Pricing Analysis
Eighteen-month Drug Master File qualification cycles concentrate purchasing power with German and Swiss suppliers, compressing spot-market liquidity and amplifying contract-premium capture for validated vial-plug combinations. Buyers trading speed for documentation face steep switching costs that insulate incumbent pricing.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical procurement, with fill-finish contractors locking multi-year contracts for nested sterile systems. Price differentiation rests on USP Type I certification tier and captive borosilicate glassworks ownership. Cost compression in standard-grade formats intensifies as Asian polymer compounders expand cyclic olefin polymer capacity. Research laboratories exhibit highest price sensitivity, while biotechnology firms prioritize validation speed over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among fill-finish contractors seeking to minimize working capital tied to sterilized nested components, though strategic stockpiling of borosilicate feedstock persists at German glassworks. Supply concentrates in Germany, Switzerland, and the United States. Production draws from specialized sand deposits, pharmaceutical-grade elastomer compounds, and energy-intensive continuous melting furnaces. Single-source vulnerability in qualified elastomer compounders creates exposure. Distribution runs through direct technical sales teams for pharmaceutical accounts and laboratory distributors for fragmented research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic drug pipeline expansion positions this market for cyclical recovery as monoclonal antibody and cell therapy investments translate into fill-finish capacity deployment.
For Market Incumbents: Secure captive borosilicate supply through backward integration into German glassworks or exclusive feedstock agreements. Lock fill-finish contractors into extended Drug Master File contracts before EMA extractables mandates widen compliance gaps. Energy price volatility threatens margin stability; in-house sterilization capabilities defend against mid-tier molders seeking sterile market entry. For New Entrants and Emerging Players: CDSCO certification fast-track for ICH Q3D-aligned vial systems opens Maharashtra and Gujarat injectable producers. Target Indian contract manufacturing organizations with pre-validated component kits. Research laboratories in North America offer penetrable white-space through distributor partnerships emphasizing small-lot flexibility and rapid format switching. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because qualification documentation burdens favor integrated suppliers with captive analytical laboratories and sterilization infrastructure. Acquisition targets include mid-tier molders with polymer chemistry expertise but lacking sterile processing capabilities. Watch EMA-USP pharmacopeial harmonization progress as inflection indicator for qualification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Consolidation | Pre-validated vial-plug kits compress 18-month FDA qualification timelines for biologics developers. |
| Cyclic Olefin Polymer Capacity Expansion | Asian compounders target diagnostic kit manufacturers seeking 60% shipping mass reduction. |
| Captive Borosilicate Integration | German glassworks operators secure feedstock control against energy price volatility exposure. |
| Ready-to-Use Sterile Format Launch | Nested systems eliminate capital expenditure for in-house washing and depyrogenation. |
| Digital Supply Chain Integration | Serialization infrastructure aligns with EU Falsified Medicines Directive track-and-trace mandates. |
Research Methodology
Cross-validation between primary interviews with fill-finish operations managers, regulatory affairs directors, and laboratory procurement officers and secondary sources including FDA container closure guidance documents, EMA extractables protocols, and USP pharmacopeial chapters anchors the qualitative findings. Bottom-up demand modeling from pharmaceutical and diagnostic end-use segments triangulates against top-down industry capacity assessments.
Sensitivity analysis across material substitution scenarios and regulatory timeline variations shapes the projection framework. Segmentation dimensions include product chemistry, sterility grade, end-user procurement scale, and application regulatory stringency. CAGRs derive from elasticity-adjusted demand curves incorporating biologic pipeline maturation and diagnostic decentralization trends. Forecast inputs include energy cost trajectories for glass forming and polymer compounder capacity expansion schedules.
Decision-makers should treat outputs as directional under assumptions of sustained biologic drug investment and stable pharmacopeial divergence; material deviation would warrant model refresh. Revision becomes warranted when EMA-USP harmonization crosses implementation thresholds or when energy price volatility disrupts borosilicate production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Blood Preparation Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Global Non-PVC IV Bags Market