
 Global Surgical Pledgets Market | 2026-2036
Global Surgical Pledgets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Pledgets Market Foresight
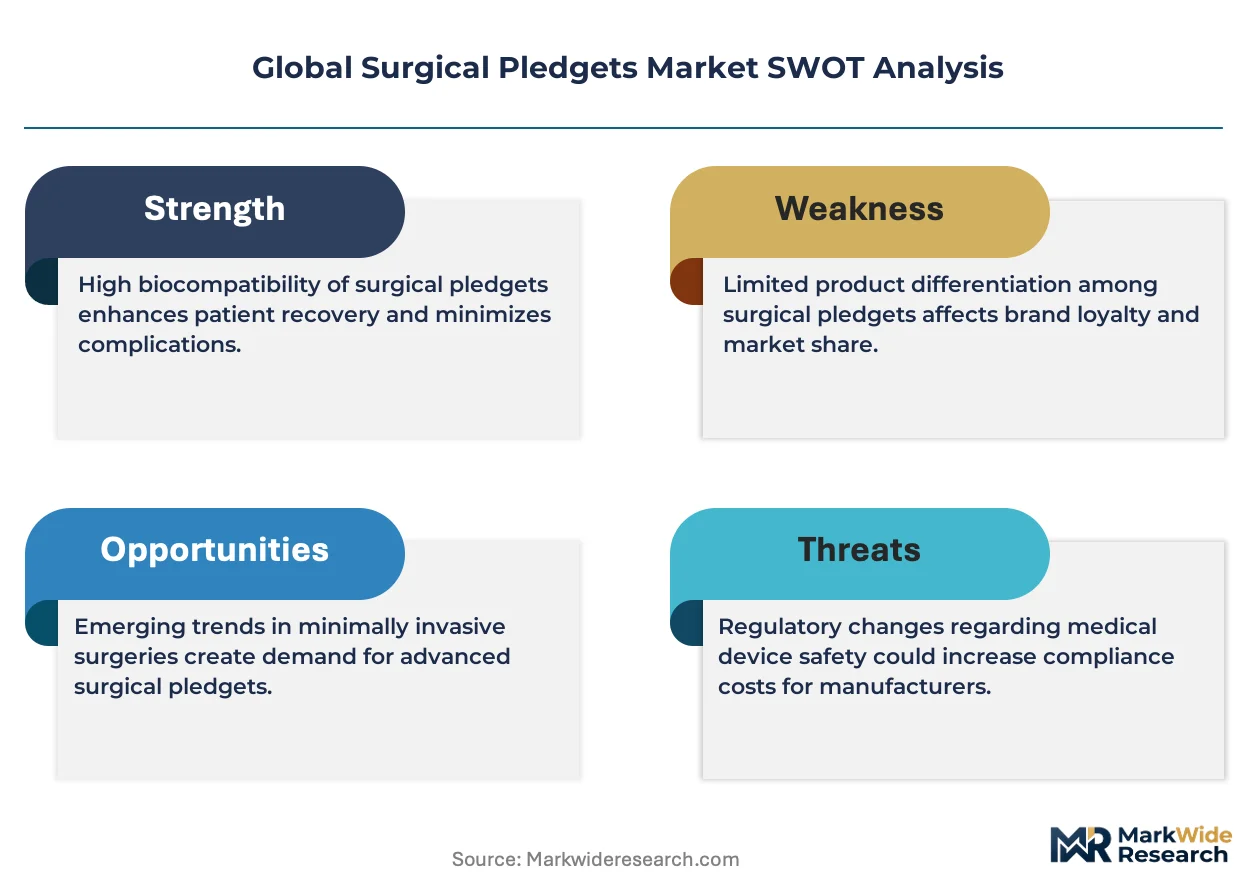
Specialized textile engineering talent is bifurcating the competitive landscape, as manufacturers with in-house weaving capabilities pull away from converters dependent on external fabric sources. Medtronic leverages backward integration into non-woven felt production to control pledget thickness tolerances for cardiac applications. B. Braun Melsungen AG anchors its European position through proprietary needle-pledget combination designs. Johnson & Johnson competes on suture-pledget kit bundling that reduces operative setup time in catheterization labs.
Surgical pledgets are small, flat pads of woven or compressed textile—typically collagen, polyester, or polyglactin—placed under sutures to distribute tension and prevent tissue tearing during wound closure. Most absorbable variants degrade through hydrolysis within 60–90 days, eliminating foreign-body retention in vascular anastomoses. Absorbable pledgets command the largest revenue share due to routine deployment in median sternotomy closures, while coated variants represent the fastest-expanding category as antimicrobial impregnation reduces surgical site infections in orthopedic settings. Composite pledgets combining synthetic mesh with biologic sealants are capturing margin pools in neurosurgical dural repair where leakage prevention commands premium pricing.
The FDA enforces 510(k) clearance pathways for pledgets marketed as accessories to predicate suture devices, while the EU Medical Device Regulation requires notified-body certification under Class IIa or IIb rules depending on implantation duration. ISO 10993 biocompatibility testing governs cytotoxicity and sensitization profiles across both jurisdictions, effectively raising barriers for Asian suppliers lacking accredited laboratory partnerships. Stakeholders must monitor evolving FDA guidance on absorbable synthetic polymers, as reclassification could trigger premarket approval requirements for long-resorption products currently cleared through abbreviated pathways.
Market Dynamics
Integrated delivery networks in the United States are consolidating surgical pledget procurement across multi-hospital systems, compressing vendor margins while elevating technical specifications for suture-line reinforcement products.
Growth Catalysts
- EU Medical Device Regulation:Tightened biocompatibility documentation requirements for implantable accessories are accelerating manufacturer investment in ISO 10993 testing infrastructure, raising quality floors across the supply base.
- Cardiovascular surgery expansion:Tertiary hospital programs are scaling pledget utilization for median sternotomy closures and vascular anastomoses, embedding absorbable variants into standard surgical protocols.
- Antimicrobial coating chemistry:Silver-ion and triclosan-impregnated pledgets are capturing orthopedic demand for surgical site infection reduction in implant-heavy procedures.
Market Restraints
- Polyester fiber price volatility:Petroleum-derived raw material costs swing with energy markets, compressing converter margins for non-integrated manufacturers lacking captive polymer supply.
- Asian supplier accreditation gaps:Manufacturers in India and Southeast Asia face structural exclusion from EU and US hospital contracts without ISO 17025 laboratory partnerships for cytotoxicity validation.
- Long-resorption polymer reclassification risk:FDA guidance evolution on absorbable synthetic polymers threatens to shift some products from 510(k) clearance to premarket approval pathways, extending time-to-market.
Strategic Opportunities
- Brazilian cardiac surgery growth:ANVISA regulatory harmonization with MDR standards creates entry pathways for certified manufacturers as private hospital chains expand cardiovascular service lines.
- Neurosurgical composite pledgets:Biologic-synthetic hybrids combining collagen felt with fibrin sealant coatings command premium positioning in dural repair where cerebrospinal fluid leakage prevention drives purchasing decisions.
- Direct-to-hospital digital procurement:Specialized surgical distributors are launching e-procurement platforms that bypass traditional medical-surgical wholesalers, capturing margin through disintermediation.
Industry Challenges
- Textile engineering talent scarcity:In-house weaving capability requires specialized non-woven felt engineers whose expertise concentrates at legacy medical textile manufacturers, constraining new entrant scale-up.
- Needle-pledget combination sterilization validation:Complex combination product filings with FDA demand extended shelf-life studies and packaging integrity testing that delay commercialization timelines.
- Biocompatibility testing backlog:Accredited laboratories face capacity constraints for ISO 10993 cytotoxicity and sensitization studies, stretching product development cycles for reformulated materials.
Report Scope
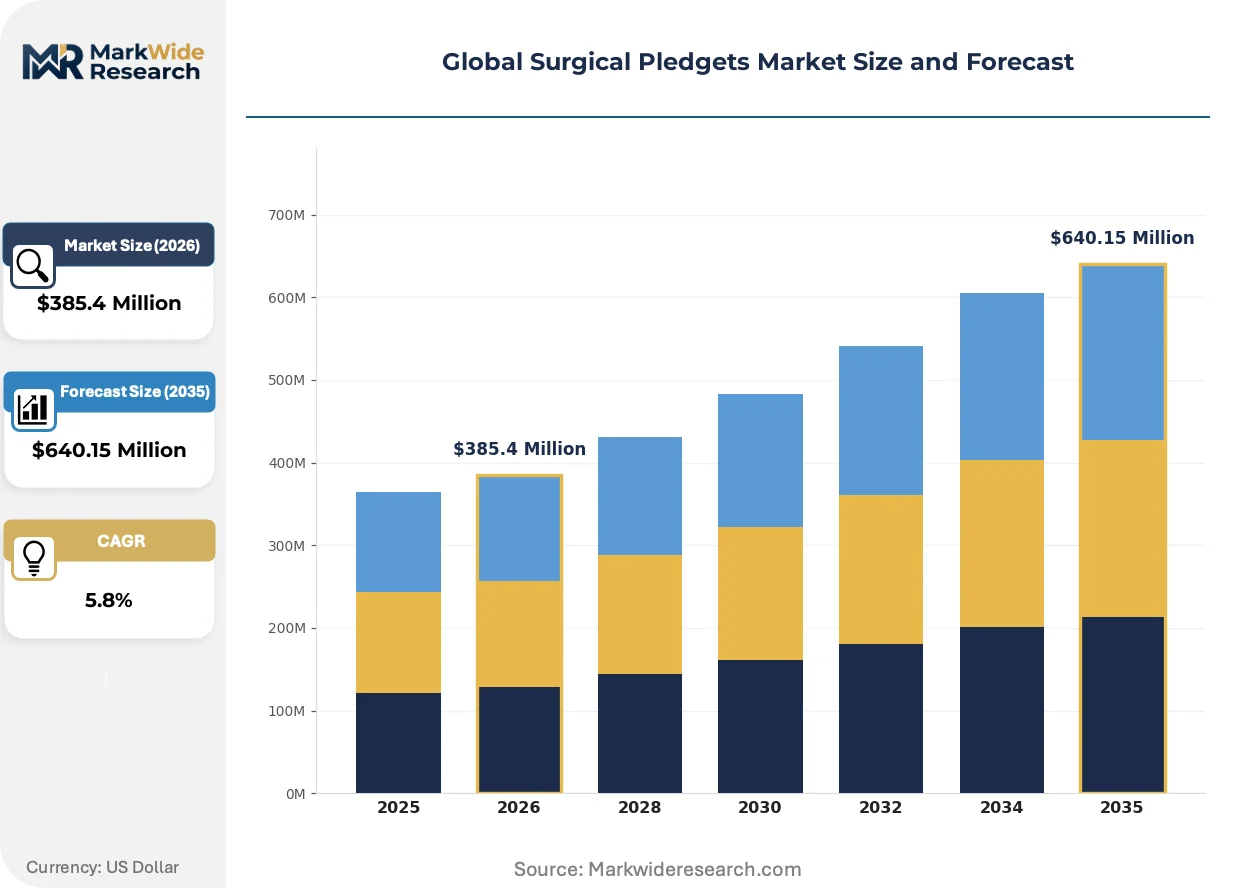
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Pledgets Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-Absorbable, Coated, Composite Therapy Area: Cardiovascular, Orthopedic, Neurosurgical, Plastic Surgery, Gynecological End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Distribution Channel: Direct Sales, Distributors, Online Platforms, Medical Supply Wholesalers |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Johnson & Johnson, Teleflex Incorporated, Medline Industries, Péters Surgical, Dolphin Sutures, DeRoyal Industries, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Pledgets Market Shifts & Advancements
Specialized textile engineering and antimicrobial material science are converging to redefine product differentiation in surgical pledget manufacturing, with in-house production capabilities becoming the decisive competitive variable.
Antimicrobial-impregnated pledgets are displacing standard uncoated variants in orthopedic and spinal fusion applications. Hospital infection control committees are mandating silver-ion or chlorhexidine-coated options for implant-adjacent procedures. This displacement is compressing commodity pledget pricing while expanding margin pools for manufacturers with validated coating deposition processes.
The EU Medical Device Regulation's Class IIb implantation-duration rules are forcing structural investment in notified-body relationships. Manufacturers must maintain technical documentation for absorption kinetic profiles across product families. Cardiac surgery applications face the steepest compliance burden given extended implantation timelines in vascular anastomoses.
Integrated delivery networks are unbundling suture-pledget kits from traditional surgical pack contracts. Procurement teams at systems like Kaiser Permanente and HCA Healthcare are negotiating direct pledget supply agreements that displace distributor-assembled kits. This behavioral shift concentrates volume with manufacturers offering sterile-ready, individually packaged units compatible with robotic surgery setups.
Global Surgical Pledgets Market Segmentation
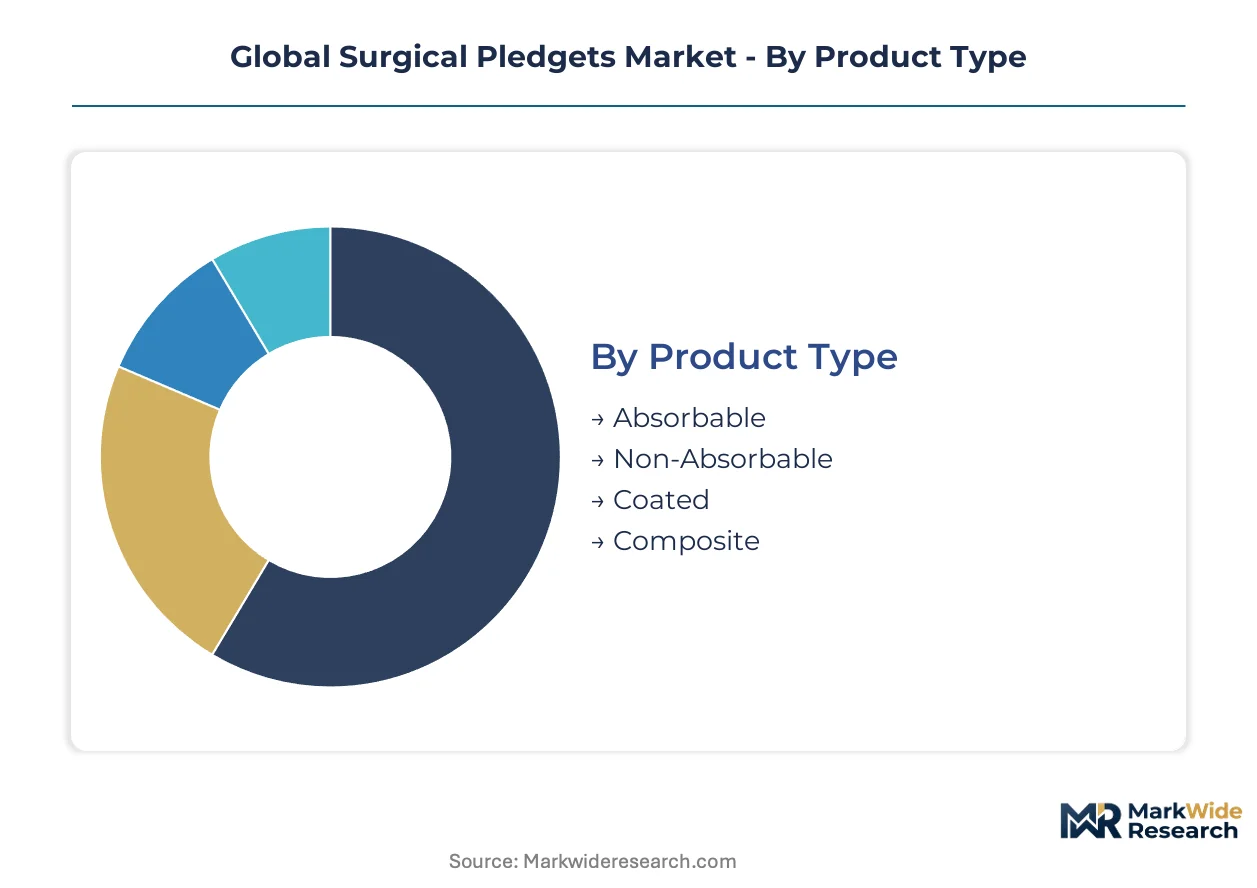
Segmentation in surgical pledgets reveals how regulatory pathways, clinical workflows, and procurement economics split demand across distinct technical specifications. Product absorbability profiles determine FDA clearance routes, while therapy area specialization dictates sterilization standards and packaging formats.
Product Type:
FDA 510(k) pathways diverge sharply based on resorption kinetics, with absorbable synthetics clearing through abbreviated routes while long-duration implants face Class IIb scrutiny under EU MDR implantation-duration rules.
- Absorbable:Hydrolytic degradation within 60–90 days eliminates foreign-body retention in vascular anastomoses. Tertiary cardiovascular programs in the United States embed these into median sternotomy closure protocols, driving standardized procurement across integrated delivery networks.
- Coated:Silver-ion and chlorhexidine impregnation creates antimicrobial barriers for implant-adjacent orthopedic procedures. Hospital infection control committees in Germany and France are mandating coated variants for spinal fusion cases, compressing uncoated commodity pricing.
- Non-Absorbable:Polyester and PTFE constructs provide permanent reinforcement for high-tension wound closures.
- Composite:Biologic-synthetic hybrids combine collagen felt with fibrin sealants for neurosurgical dural repair.
Absorbable pledgets handle the majority of throughput; coated variants are gaining share fastest on antimicrobial mandates.
Therapy Area:
Procedure volume and reimbursement intensity create divergent margin structures, with cardiac surgery sustaining premium pricing for suture-line reinforcement while orthopedic utilization scales on infection reduction economics.
- Cardiovascular:Median sternotomy closures and vascular anastomoses demand precise thickness tolerances for hemostasis. Private hospital chains in Brazil are expanding cardiac service lines as ANVISA harmonizes with MDR standards, creating certified manufacturer entry pathways.
- Orthopedic:Implant-heavy spine and joint procedures drive antimicrobial-coated pledget adoption. CMS bundled payment models in the United States tie reimbursement to surgical site infection rates, elevating coated variant specification in procurement tenders.
- Neurosurgical:Cerebrospinal fluid leakage prevention commands premium pricing for composite constructs.
- Plastic Surgery:Aesthetic and reconstructive applications prioritize cosmetic scarring outcomes.
- Gynecological:Pelvic floor repair utilizes absorbable variants for tension-free vaginal tape procedures.
Cardiovascular applications anchor revenue concentration; neurosurgical composites show the steepest expansion trajectory on leakage prevention premiums.
End User:
Capital intensity and sterilization infrastructure determine customer access, with robotic surgery compatibility becoming a non-negotiable specification for high-volume purchasers.
- Hospitals:Integrated delivery networks like Kaiser Permanente and HCA Healthcare are unbundling pledgets from surgical packs, negotiating direct supply agreements for sterile-ready individually packaged units. Robotic surgery setup compatibility now gates vendor qualification.
- Ambulatory Surgical Centers:Cost compression and limited storage capacity favor pre-sterilized disposable formats.
- Specialty Clinics:Concentrated procedure volumes in cardiac and orthopedic subspecialties sustain direct manufacturer relationships.
- Research Institutes:Preclinical and biomechanical studies drive small-batch custom specifications.
Hospitals command the dominant procurement volume; ambulatory surgical centers are expanding most quickly on outpatient migration.
Distribution Channel:
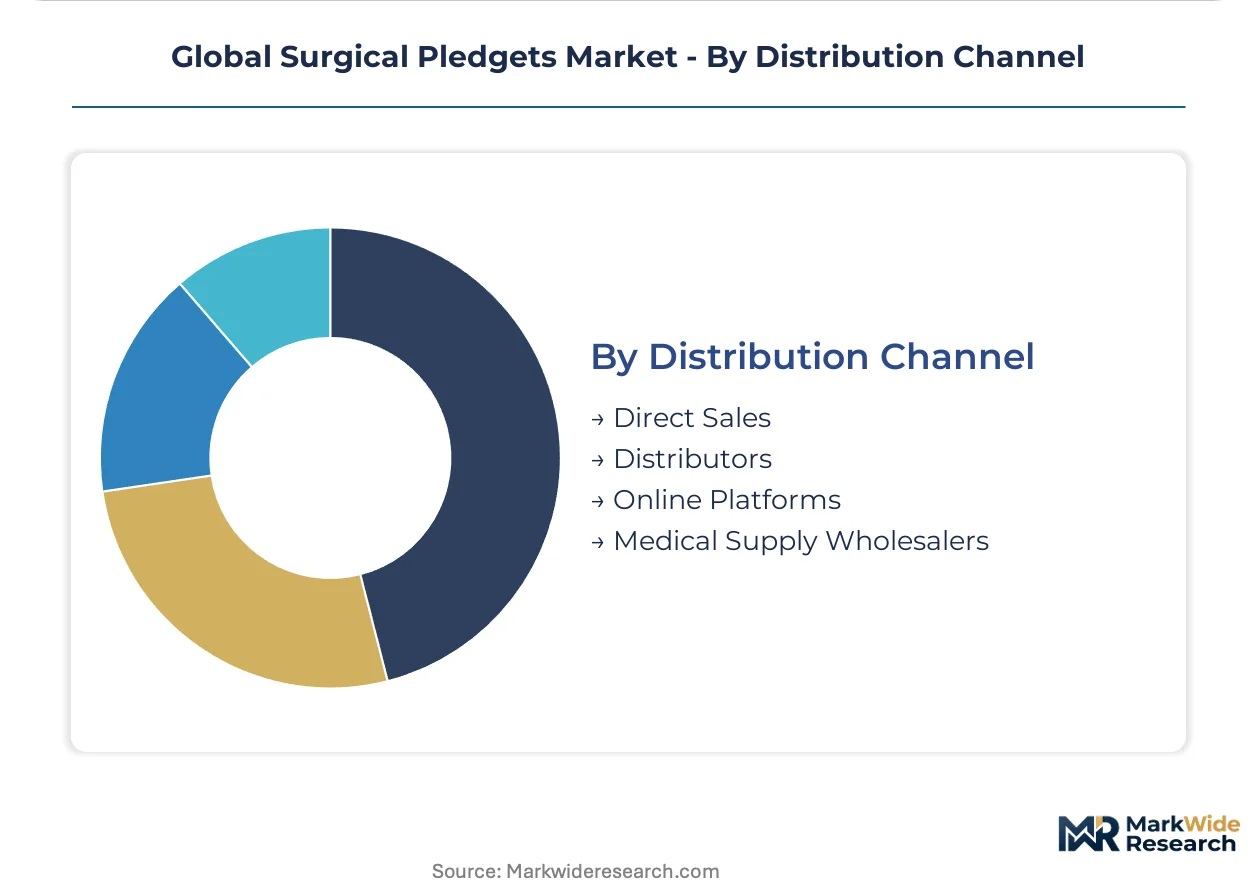
Margin capture and customer intimacy trade off across channel structures, with digital platforms disintermediating traditional medical-surgical wholesalers in specific customer segments.
- Direct Sales:Manufacturer field forces maintain technical specification relationships with IDN procurement teams and cardiac surgery department heads. Direct contracts capture margin otherwise lost to distributor markups.
- Distributors:Regional surgical supply houses provide same-day fulfillment for urgent replacement orders.
- Online Platforms:Specialized e-procurement portals bypass traditional wholesalers for standardized SKUs.
- Medical Supply Wholesalers:Broad-line distributors serve smaller hospitals lacking dedicated surgical procurement staff.
Direct sales channels manage the largest contract value; online platforms are climbing the fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States hospitals prioritizing sterile-ready individual packaging for robotic surgery compatibility while German procurement teams enforce antimicrobial coating mandates through infection control committee specifications.
United States
Integrated delivery networks at Kaiser Permanente and HCA Healthcare unbundle pledgets from surgical packs, negotiating direct supply agreements that displace distributor-assembled kits. FDA 510(k) clearance pathways govern absorbable synthetic variants, with evolving guidance on long-resorption polymers threatening reclassification. The Cleveland Clinic and Mayo Clinic cardiac surgery centers drive specification for precise thickness tolerances in median sternotomy closures.
Germany
Hospital infection control committees in Berlin and Munich mandate silver-ion and chlorhexidine-coated pledgets for spinal fusion procedures, compressing uncoated commodity pricing. EU MDR Class IIb rules apply to extended implantation products, forcing structural investment in notified-body relationships. The Rhine-Ruhr medical technology cluster concentrates textile engineering talent for non-woven felt production.
Japan
PMDA marketing authorization pathways align with ISO 10993 biocompatibility testing requirements, elevating barriers for suppliers lacking accredited laboratory partnerships. Tokyo and Osaka tertiary hospitals expand cardiovascular surgery programs, embedding absorbable pledgets into standard protocols. METI industrial policy supports domestic medical textile manufacturing capability.
Brazil
ANVISA regulatory harmonization with EU MDR standards creates certified manufacturer entry pathways as private hospital chains in São Paulo and Rio de Janeiro expand cardiac service lines. Absorbable variant demand scales with median sternotomy volume growth. The Southeast region concentrates surgical device distribution infrastructure.
China
NMPA registration requirements for implantable accessories intensify documentation burdens for absorption kinetic profiles. Shanghai and Beijing tertiary hospitals standardize procurement across multi-hospital systems, compressing vendor margins while elevating technical specifications. Yangtze River Delta medical device clusters develop domestic non-woven felt weaving capability.
Global Surgical Pledgets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with in-house weaving capability becoming the decisive competitive variable. The upper tier controls thickness tolerances through captive non-woven felt production, while converters dependent on external fabric sources face margin compression from petroleum-derived raw material volatility. Three archetypes dominate: backward-integrated textile engineers, proprietary combination-product designers, and suture-pledget kit bundlers. Competitive moves concentrate on M&A for laboratory accreditation assets and capacity expansion into antimicrobial coating deposition processes.
Among the integrated leaders, Medtronic plc exemplifies backward integration into non-woven felt production for cardiac application tolerance control. B. Braun Melsungen AG occupies a position within the proprietary combination-product tier through needle-pledget integration expertise. Johnson & Johnson represents the kit-bundling archetype, reducing operative setup time through suture-pledget package configurations. These three anchors illustrate how technical specialization and supply chain control separate competitive tiers.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Teleflex Incorporated |
| Medline Industries |
| Péters Surgical |
| Dolphin Sutures |
| DeRoyal Industries |
| Henry Schein |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day absorption kinetic validation cycles compress procurement flexibility for hospital buyers, concentrating pricing power with manufacturers holding captive non-woven felt production and ISO 17025 laboratory accreditation. This lead-time structure reinforces margin premiums for backward-integrated suppliers while squeezing converter margins dependent on external textile sourcing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated delivery networks and tier-one manufacturers, locking in volume commitments against polyester fiber price volatility. Price differentiation hinges on ISO 10993 biocompatibility certification tier and antimicrobial coating deposition capability, with silver-ion variants commanding premiums over uncoated commodity pledgets. Cost compression in standard absorbable tiers intensifies as IDNs consolidate procurement across multi-hospital systems. Ambulatory surgical centers exhibit the highest price sensitivity due to limited storage capacity and cash-flow constraints, while tertiary cardiovascular programs prioritize thickness tolerance precision over unit cost.
Supply Chain Analysis
Strategic stockpile preferences concentrate among German and Japanese manufacturers buffering against biocompatibility testing laboratory backlogs, while United States buyers favor just-in-time replenishment through distributor-assembled surgical packs. Raw material sourcing draws from United States collagen suppliers, German polyester fiber producers, and Chinese non-woven felt weavers. Petroleum-derived polymer costs tether converter margins to energy market swings. Single-source vulnerability concentrates in specialized textile engineering talent pools within the Rhine-Ruhr and Yangtze River Delta clusters. Distribution runs through regional surgical supply houses for urgent fulfillment and direct manufacturer contracts for standardized IDN procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical pledget penetration remains early-cycle in neurosurgical composite applications and Brazilian private hospital chains, with ANVISA regulatory harmonization accelerating certified manufacturer entry into Latin American cardiovascular service lines.
For Market Incumbents: Compound technical specification advantages by deepening antimicrobial coating deposition capacity and securing notified-body relationships under EU MDR Class IIb implantation-duration rules. Expand sterile-ready individual packaging lines to capture IDN unbundling of surgical pack contracts. Defend against Asian supplier accreditation gaps by accelerating ISO 17025 laboratory partnership acquisitions. For New Entrants and Emerging Players: E-procurement platform underinvestment by legacy distributors creates white-space for specialized surgical distributors launching direct-to-hospital digital channels. Target neurosurgical composite pledgets in dural repair applications where cerebrospinal fluid leakage prevention commands premium positioning and incumbent concentration remains lowest. Pursue ANVISA certification pathways as Brazilian private hospital chains expand cardiac surgery volumes. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical textile parents lacking dedicated surgical pledget commercial infrastructure or antimicrobial coating validation assets. Five-to-ten-year viability favors manufacturers with captive non-woven felt weaving and established GPO contracts at Kaiser Permanente or HCA Healthcare. Monitor FDA guidance evolution on long-resorption polymer reclassification as inflection signal for premarket approval pathway shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Deposition Scale-Up | Silver-ion and chlorhexidine validation captures orthopedic procurement mandates from German infection control committees. |
| ISO 17025 Laboratory Partnership Acquisition | Accredited cytotoxicity testing capacity eliminates biocompatibility backlog delays for reformulated material launches. |
| Notified-Body Relationship Structuring | EU MDR Class IIb technical documentation capabilities secure extended implantation product market access. |
| Direct-to-Hospital E-Procurement Platform Launch | Disintermediation of traditional medical-surgical wholesalers captures margin through IDN digital procurement adoption. |
| ANVISA Certification Pathway Investment | Regulatory harmonization with MDR standards enables entry into São Paulo and Rio de Janeiro cardiac service line expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac surgeons, hospital procurement committee members, biomedical engineers, GPO contracts managers, and non-woven felt textile engineers. Secondary validation drew from FDA 510(k) filings, EU MDR notified-body certification databases, ANVISA regulatory harmonization documentation, hospital procurement tender records, and ISO 10993 biocompatibility testing protocols. Bottom-up volume modeling triangulated against top-down market sizing across absorbable, coated, non-absorbable, and composite product categories.
Across the analysis window, projections integrated procedure volume trajectories in cardiovascular, orthopedic, and neurosurgical therapy areas with pricing dynamics from IDN contract structures and antimicrobial coating premiums. Segmentation dimensions spanned product absorbability profiles, therapy area specialization, end-user capital intensity, and distribution channel digitization. CAGRs derived from elasticity-adjusted adoption curves for composite pledgets in dural repair and coated variants in infection-control-mandated orthopedic procedures.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR Class IIa/IIb implantation-duration rules; material policy shifts toward premarket approval requirements would require re-modeling. Revision becomes warranted when polyester fiber cost volatility exceeds historical bands or biocompatibility testing laboratory capacity constraints extend product development cycles beyond absorption kinetic validation windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Medical Bags Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Global IV Bags Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Abdominal Compression Garments Market