
 US Cloud Robotics Market | 2026-2036
US Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
US Cloud Robotics Market Insights
The NIST Cybersecurity Framework is restructuring capital deployment timelines for cloud robotics vendors serving US defense and critical infrastructure contracts. Amazon Robotics leverages its captive fulfillment network to dominate domestic last-mile automation deployments. NVIDIA Corporation anchors high-performance edge-to-cloud inference pipelines for industrial robot swarms. Boston Dynamics specializes in locomotion platforms that integrate with private cloud orchestration stacks for hazardous environment inspection.
Cloud robotics denotes networked robotic systems that offload computation, data storage, and machine learning model training to remote server infrastructure while retaining time-critical control loops at the edge, typically operating with sub-50ms latency requirements for motion planning and safety interlocks. Its primary commercial purpose centers on enabling fleets of robots to share learned behaviors, coordinate tasks dynamically, and reduce onboard hardware costs through centralized processing power. Public cloud deployments currently lead in pilot-phase adoption due to elastic scaling economics, though hybrid cloud configurations are capturing margin pools in manufacturing settings where data sovereignty concerns restrict full offloading. Robotics as a Service is expanding fastest among mid-sized logistics operators seeking to convert capital expenditures into operational expenditures without maintaining internal DevOps teams for robot fleet management.
FAA regulations governing beyond-visual-line-of-sight drone operations intersect with OSHA workplace safety standards for collaborative robots to create a dual-compliance burden for vendors targeting aerial and ground-based automation simultaneously. The Securities and Exchange Commission's emerging climate disclosure rules are pressuring publicly traded manufacturers to document carbon impacts from cloud compute dependencies in their robotics programs. Stakeholders must monitor how NIST's forthcoming AI risk management framework applies to autonomous decision-making in multi-robot coordination systems before committing to long-term platform architectures.
Market Dynamics
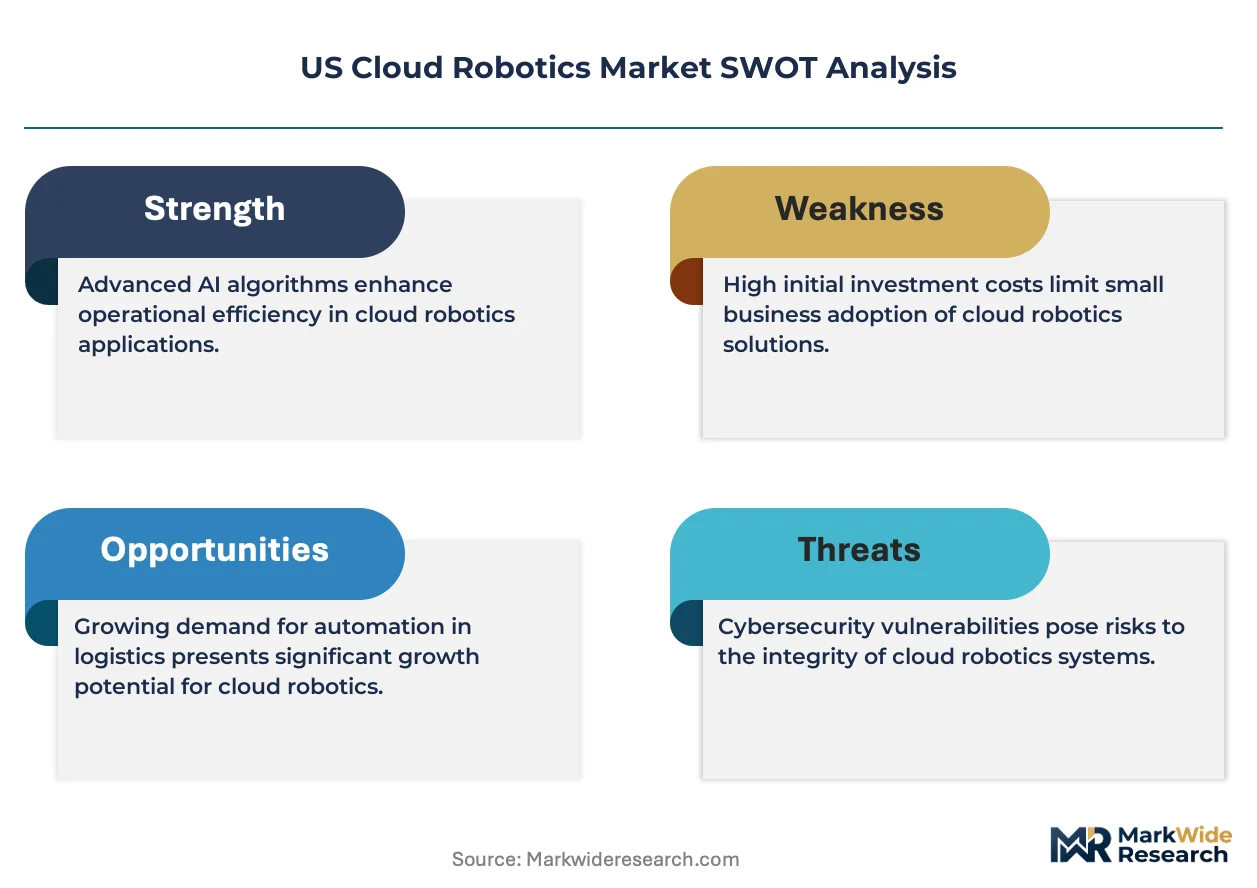
NIST's cybersecurity framework for autonomous systems is forcing cloud robotics vendors to restructure compliance architectures before bidding on federal contracts, compressing product development timelines and elevating vendor qualification costs.
Growth Catalysts
- FAA Beyond-Visual-Line-of-Sight Rulemaking:Expanding commercial drone corridors across Michigan's automotive testing grounds and California's Central Valley logistics hubs is accelerating aerial robotics deployment for inventory monitoring.
- Midwest Manufacturing Density:Michigan's automotive corridor demand for cloud-coordinated welding and assembly robots is pulling edge-to-cloud orchestration platforms into heavy industrial settings.
- Robotics as a Service Model Maturation:Mid-sized Southeast fulfillment operators are converting capital expenditures to operational expenditures through third-party fleet management, bypassing internal DevOps requirements.
Market Restraints
- Semiconductor Supply Concentration:GPU and specialized inference chip dependencies on Taiwan-based foundries create vulnerability for edge-compute hardware procurement cycles.
- Dual-Compliance Burden:Vendors targeting simultaneous aerial and ground automation must satisfy both FAA flight standards and OSHA collaborative robot safety protocols, doubling certification timelines.
- Data Sovereignty Technical Limitations:Manufacturing settings with restricted offloading requirements force hybrid cloud architectures that sacrifice elastic scaling economics for compliance.
Strategic Opportunities
- Southeast Logistics Corridor Expansion:Georgia and Tennessee distribution hub construction is outpacing local automation vendor presence, creating whitespace for cloud-native fleet operators.
- SEC Climate Disclosure Pressure:Publicly traded manufacturers must document cloud compute carbon impacts, favoring vendors with transparent emissions tracking and renewable-powered data center partnerships.
- 5G-Private Network Convergence:Sub-10ms latency from carrier-deployed private 5G networks is enabling new motion planning applications previously restricted to on-premise edge servers.
Industry Challenges
- Multi-Robot Coordination Talent Scarcity:Shortage of engineers proficient in distributed systems, safety-critical control loops, and cloud-native orchestration is constraining fleet deployment velocity.
- Legacy Warehouse Management System Integration:Decades-old WMS platforms in established logistics networks resist API-native connectivity, forcing expensive middleware development for cloud robotics compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cloud Robotics Market |
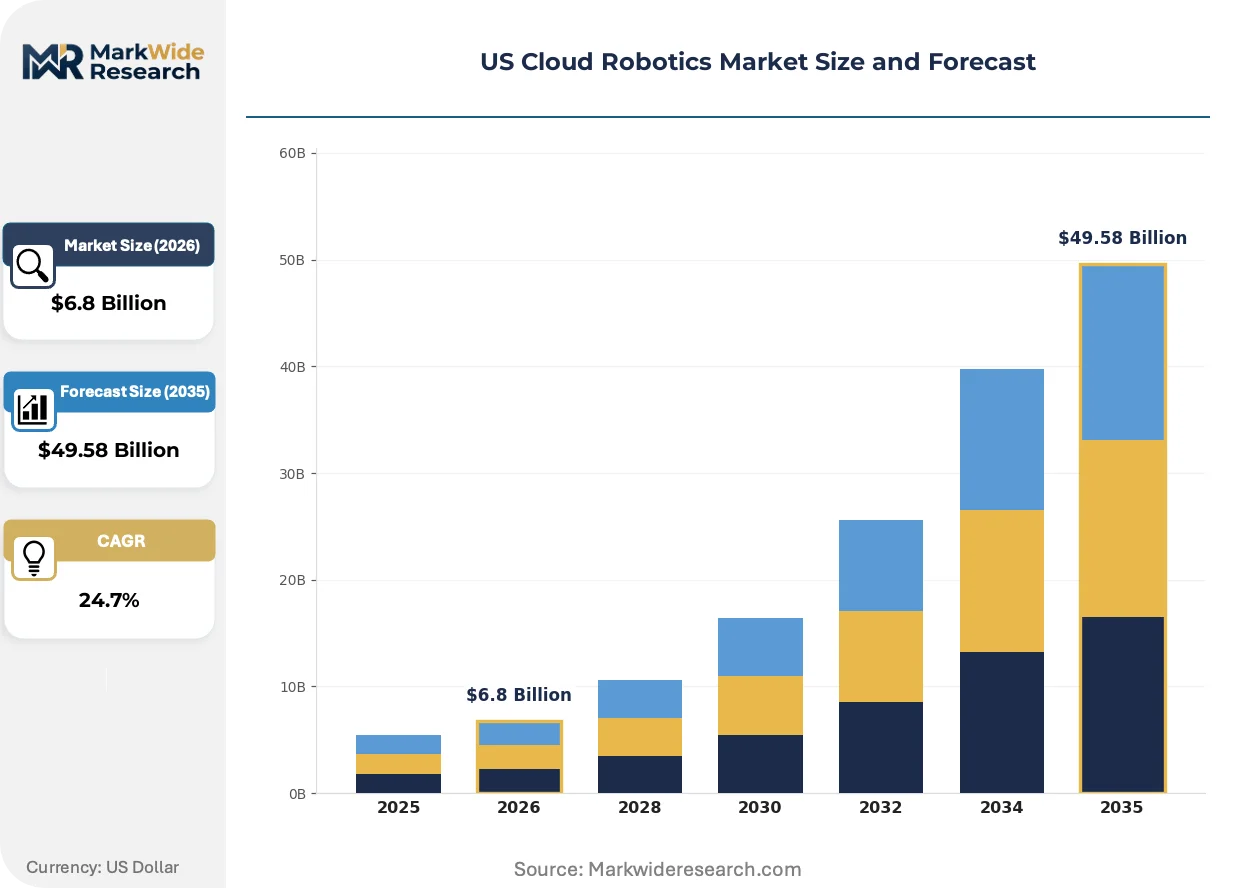
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Robotics as a Service End User: Manufacturing, Healthcare, Logistics, Retail Technology: Machine Learning, Artificial Intelligence, Computer Vision, Natural Language Processing |
| Companies Covered | Amazon Robotics, Google LLC, Microsoft Corporation, IBM Corporation, Boston Dynamics, NVIDIA Corporation, Rockwell Automation Inc., Formant, Locus Robotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cloud Robotics Market Trends and Innovations
Latency-critical control architectures are fragmenting as private 5G networks and edge inference chips compete with centralized cloud processing, reshaping vendor technology roadmaps and customer deployment preferences.
Digital twin simulation environments are rewriting how cloud robotics vendors validate fleet coordination algorithms before physical deployment. Automotive manufacturers in Michigan are adopting these virtual testing platforms most aggressively, compressing safety certification timelines from months to weeks while reducing hardware damage costs during algorithm iteration.
OSHA's pending updates to collaborative robot safety standards are forcing vendors to redesign force-limiting and speed-restricting control systems. The proposed rules would mandate enhanced sensor redundancy for human-robot interaction zones, most heavily affecting ground-based logistics automation in California's high-volume fulfillment centers where robot density exceeds national averages.
Mid-market logistics operators are unbundling after-sales service from hardware procurement, preferring third-party managed service providers for fleet optimization and predictive maintenance. This behavioral shift is most visible across Southeast distribution hubs where capital-constrained buyers prioritize uptime guarantees over vendor-direct support relationships.
US Cloud Robotics Market Segmentation
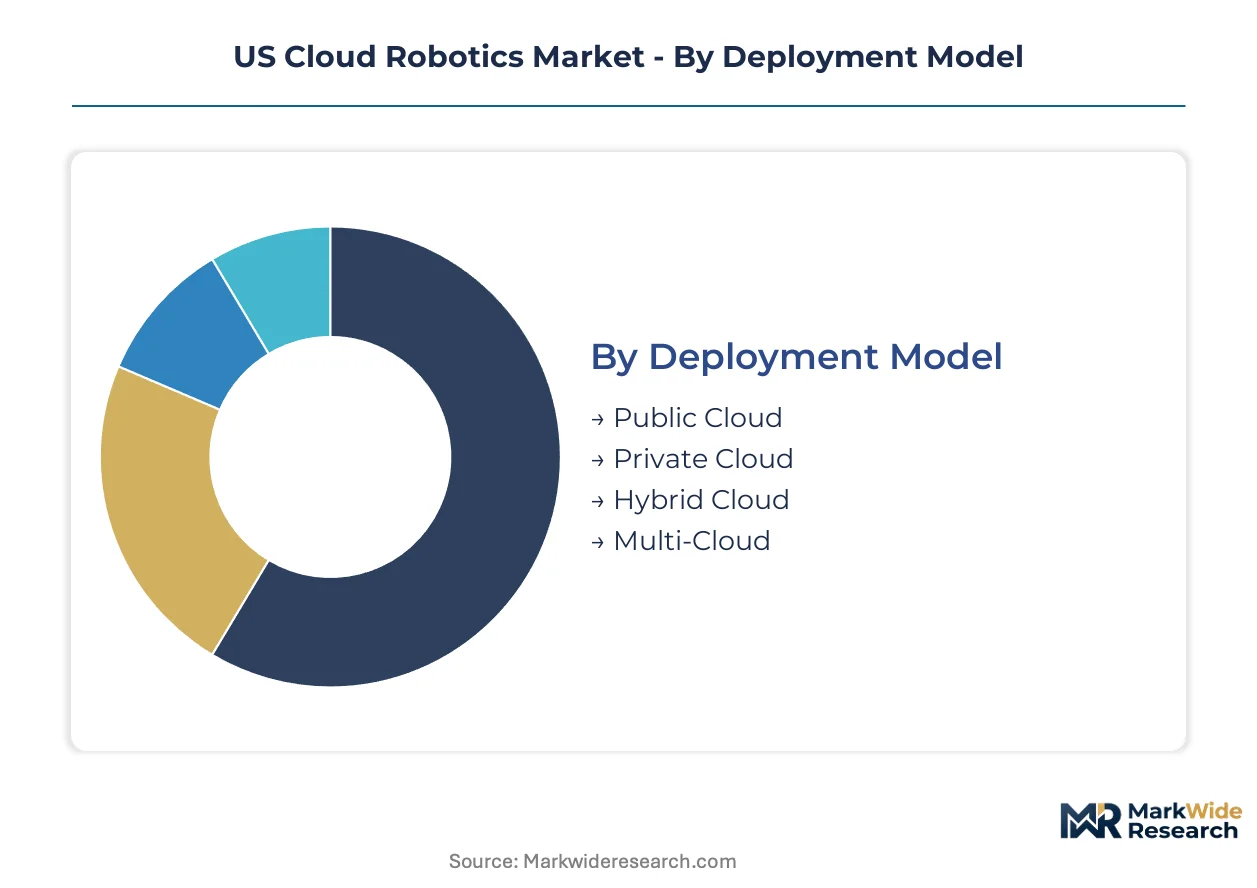
Cloud robotics architectures fragment across deployment models, service tiers, and underlying technologies that determine latency budgets, compliance postures, and capital intensity. Understanding how these segments intersect with end-use applications reveals where vendor margins concentrate and where procurement patterns are shifting.
Deployment Model:
Cost sensitivity and data sovereignty requirements separate buyers choosing centralized versus distributed compute architectures.
- Public Cloud:Elastic scaling economics dominate pilot-phase robotics programs where compute loads spike unpredictably during fleet learning cycles. Michigan automotive manufacturers favor this model for non-proprietary simulation workloads.
- Private Cloud:Dedicated infrastructure satisfies defense contractors and critical infrastructure operators under NIST cybersecurity framework mandates. Compliance-driven procurement elevates total cost of ownership but eliminates multi-tenant data exposure risks.
- Hybrid Cloud:Time-critical control loops remain at the edge while model training offloads to centralized servers. California logistics hubs deploy this architecture to balance sub-50ms latency requirements with elastic compute economics.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud mitigates vendor lock-in for large-scale fleet operators. Southeast fulfillment networks increasingly demand this flexibility during contract negotiations.
Public Cloud leads volumes today; Hybrid Cloud is gaining share fastest.
Service Type:
Internal DevOps capabilities determine whether buyers self-manage infrastructure or outsource fleet orchestration entirely.
- Infrastructure as a Service:Bare-metal compute and GPU clusters provisioned on demand support robotics workloads with spiky resource requirements. Mid-sized operators lacking data center expertise consume this layer most heavily.
- Platform as a Service:Managed Kubernetes and container orchestration abstracts away infrastructure complexity for application developers. Healthcare robotics vendors leverage this tier to accelerate FDA-compliant software deployment pipelines.
- Software as a Service:Pre-built fleet management dashboards and predictive maintenance tools eliminate custom development. Retail robotics adopters with limited engineering headcount gravitate toward this consumption model.
- Robotics as a Service:Complete hardware-plus-software subscriptions convert capital expenditures to operational expenditures. Georgia and Tennessee distribution operators are expanding fastest in this segment as warehouse construction outpaces automation talent availability.
Infrastructure as a Service anchors current spending; Robotics as a Service exhibits the steepest expansion trajectory.
End User:
Regulatory complexity and robot density requirements create divergent procurement timelines across vertical applications.
- Manufacturing:Cloud-coordinated welding and assembly robots in Michigan's automotive corridor demand millisecond-precision motion planning. OSHA collaborative robot standards and NIST cybersecurity frameworks impose dual compliance burdens on vendors.
- Healthcare:Surgical assistance and hospital logistics robots face FDA device regulations alongside HIPAA data privacy requirements. Edge-to-cloud inference pipelines support real-time decision support while preserving patient data sovereignty.
- Logistics:California fulfillment centers operate the densest ground-based robot fleets in domestic commerce. FAA beyond-visual-line-of-sight rulemaking is simultaneously expanding aerial robotics deployment for inventory monitoring.
- Retail:Shelf-scanning and customer service robots prioritize computer vision accuracy over motion complexity. Smaller store footprints and lower robot counts reduce the economic case for full cloud orchestration compared to warehouse scale.
Manufacturing commands the largest installed base; Logistics is climbing the fastest as e-commerce fulfillment networks expand.
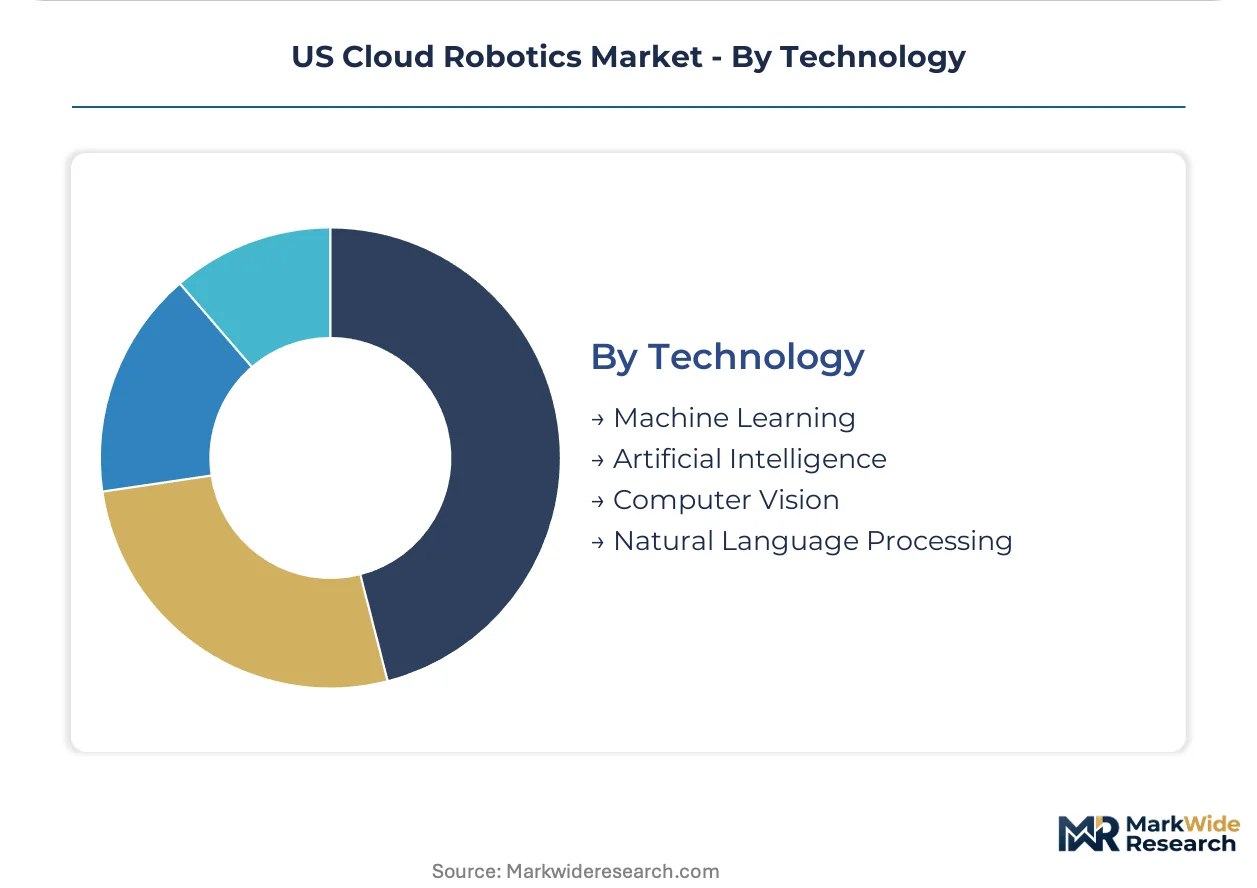
Technology:
Computational requirements and data pipeline architectures distinguish how each enabling technology integrates with cloud robotics stacks.
- Machine Learning:Distributed training across robot fleets enables collective learning where edge devices contribute data and receive updated models. Centralized model versioning and A/B testing accelerate algorithm iteration cycles.
- Artificial Intelligence:Autonomous decision-making in multi-robot coordination systems faces emerging scrutiny under NIST's forthcoming AI risk management framework. Vendors are restructuring governance architectures before long-term platform commitments solidify.
- Computer Vision:Object detection and semantic segmentation pipelines offload inference to cloud GPUs for non-time-critical analysis. Manufacturing quality inspection and retail shelf monitoring represent high-volume applications.
- Natural Language Processing:Voice-enabled human-robot interaction supports collaborative workflows in healthcare and retail settings. Lower computational intensity permits lighter edge hardware compared to vision workloads.
Computer Vision dominates current processing loads; Artificial Intelligence is expanding most quickly as autonomous coordination requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud robotics infrastructure first achieved commercial scale in California's logistics corridors during the mid-2010s, with Amazon Robotics pioneering warehouse fleet coordination at scale. The technology has since diffused across domestic manufacturing belts and emerging distribution hubs.
California
Los Angeles and Central Valley logistics clusters operate the densest ground-based robot fleets in domestic commerce. FAA beyond-visual-line-of-sight rulemaking is expanding aerial robotics deployment for inventory monitoring across Bakersfield distribution centers. The state's data privacy regulations shape hybrid cloud architectures that retain sensitive edge processing locally.
Michigan
Detroit-Warren automotive corridors generate concentrated demand for cloud-coordinated welding and assembly robots with millisecond-precision motion planning. NIST cybersecurity framework compliance requirements elevate vendor qualification costs for federal defense contracts. Cloud-native simulation platforms compress safety certification timelines at Dearborn and Lansing manufacturing facilities.
Georgia
Atlanta distribution hub construction outpaces local automation vendor presence, creating whitespace for cloud-native fleet operators. State economic development incentives for warehouse automation accelerate Robotics as a Service adoption among capital-constrained mid-market logistics buyers. Savannah port automation projects integrate edge-to-cloud orchestration for container handling.
Tennessee
Memphis and Nashville logistics networks expand robot fleet density to match e-commerce fulfillment growth. Regional 5G private network deployments enable sub-10ms latency for motion planning applications previously restricted to on-premise edge servers. Chattanooga manufacturing automation clusters adopt hybrid cloud architectures balancing compliance with elastic compute economics.
Texas
Dallas-Fort Worth distribution corridors attract cloud robotics vendors seeking geographic diversification beyond saturated coastal markets. State energy sector automation creates dual-use opportunities for hazardous environment inspection platforms. Houston industrial robotics adoption concentrates in petrochemical facility maintenance applications.
US Cloud Robotics Market Competitive Landscape
The competitive structure tilts toward technology conglomerates with captive cloud infrastructure and specialized robotics pure-plays with locomotion expertise. Market concentration is pronounced at the infrastructure layer where hyperscale cloud providers control essential compute and storage resources. Two strategic archetypes dominate: vertically integrated fulfillment operators leveraging internal demand to subsidize platform development, and component suppliers anchoring edge-to-cloud inference pipelines for third-party robot manufacturers. Dominant competitive moves include strategic partnerships between cloud providers and industrial automation vendors, plus portfolio diversification into adjacent autonomous systems categories.
Among hyperscale cloud providers, Amazon Robotics, Microsoft Corporation, and Google LLC exemplify contrasting market positions. Amazon Robotics represents the captive-demand archetype, converting internal fulfillment network requirements into externally facing platform capabilities. Microsoft Corporation and Google LLC occupy infrastructure-provider positions, supplying orchestration tools and machine learning frameworks to third-party robot fleet operators without direct hardware manufacturing exposure. This tripartite structure shapes procurement negotiations for mid-sized logistics operators seeking to avoid single-vendor dependency.
| Leading Market Players |
|---|
| Amazon Robotics |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Boston Dynamics |
| NVIDIA Corporation |
| Rockwell Automation Inc. |
| Formant |
| Locus Robotics |
| Others |
Pricing and Supply Chain Analysis
NVIDIA GPU spot pricing indices cascade through cloud robotics supply chains, compressing margins for edge-compute hardware vendors while elevating subscription premiums for managed fleet services that absorb procurement volatility.
Pricing Analysis
Robotics-as-a-Service subscription tiers dominate customer contracts, separating premium SLAs with sub-20ms latency guarantees from standard tiers with shared cloud infrastructure and economy tiers for pilot-phase deployments. Price differentiation hinges on NIST cybersecurity certification level and edge hardware redundancy specifications. Cost compression in economy tiers is intensifying because mid-sized logistics operators demand pay-per-pick pricing models. Southeast fulfillment buyers exhibit highest price sensitivity, while Michigan automotive manufacturers prioritize millisecond-precision guarantees over per-unit cost.
Supply Chain Analysis
Dual-sourcing mandates from defense contractors and critical infrastructure operators force cloud robotics vendors to qualify GPU suppliers across Taiwan, South Korea, and domestic foundries. Specialized inference chips and high-bandwidth memory modules anchor bill-of-materials costs. Single-source vulnerability concentrates in advanced packaging nodes. Distribution runs through direct OEM relationships for large fleet operators and regional systems integrators for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US cloud robotics has shifted into a late-cycle quality phase where NIST-compliant orchestration platforms command sustained pricing power against commodity hardware alternatives.
For Market Incumbents: Acquire edge-AI software stacks to fortify against NVIDIA's inference pipeline dominance. AWS and Azure partnerships with industrial automation vendors compress independent platform margins. Certification investment in FAA beyond-visual-line-of-sight compliance creates defensible positioning for aerial-ground hybrid fleets. For New Entrants and Emerging Players: Capital-constrained mid-market logistics operators in Georgia and Tennessee represent the most penetrable buyer archetype. Robotics-as-a-Service unbundling creates whitespace for third-party fleet optimization specialists. Channel partnerships with regional 5G private network deployers accelerate customer acquisition without captive sales infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid cloud orchestration vendors serving manufacturing settings with data sovereignty requirements. Long-term viability favors platforms with renewable-powered data center partnerships as SEC climate disclosure rules harden. Watch NIST AI risk management framework publication timing as inflection indicator for autonomous coordination system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FAA-compliant orchestration stacks attract defense contractor procurement committees. |
| Acquisition of Specialist Firm | Edge-AI inference vendors fill latency-critical control gaps in hybrid architectures. |
| Strategic Partnership | Private 5G carrier alliances enable sub-10ms motion planning for manufacturing clients. |
| Geographic Expansion | Southeast logistics corridor presence captures warehouse construction outpacing automation supply. |
| Product Launch | NIST-certified cybersecurity modules unlock federal contract bidding eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud robotics platform engineers, fleet operations directors at logistics operators, automotive manufacturing automation leads, and hyperscaler solution architects with secondary validation against SEC filings, FAA regulatory dockets, and NIST framework documentation. Bottom-up deployment counts and top-down infrastructure spending estimates were triangulated.
Comparable historical periods anchored the projection horizon, with modeled segmentation spanning deployment architecture, service tier, end-use vertical, and enabling technology. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G private network rollout timelines and OSHA collaborative robot standard evolution.
Underlying measurement precision varies by segment; public cloud deployment volumes carry tighter precision than emerging multi-cloud configurations. Forecasts reflect assumptions around semiconductor supply normalization and regulatory clarity timelines. Deviation in NIST AI risk management framework stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Restaurant Delivery Robot Market